
 Targeted Liposomes Drug Delivery Market | 2026-2036
Targeted Liposomes Drug Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Targeted Liposomes Drug Delivery Market Analysis
CE marking under the EU Medical Device Regulation is collapsing the set of qualified suppliers for liposomal drug-device combination products. Gilead Sciences dominates liposomal formulation development through its established nanotechnology platforms. Johnson and Johnson leverages its pharmaceutical manufacturing scale to sustain commercial production of complex liposomal therapies. Novartis anchors European market access through specialized oncology distribution networks.
Targeted liposomes drug delivery employs phospholipid bilayer vesicles engineered with surface ligands, polyethylene glycol coatings, or charge modifications to achieve tissue-specific drug release and reduced systemic toxicity. These systems primarily serve to improve therapeutic indices of cytotoxic agents by concentrating drug payload at disease sites while sparing healthy tissue. PEGylated liposomes command premium positioning due to extended circulation half-life and reduced reticuloendothelial clearance. Immunoliposomes represent the fastest-expanding category as antibody-directed targeting enables receptor-mediated uptake in solid tumors. Conventional liposomes occupy mature, cost-sensitive segments where generic competition has compressed margins.
FDA's Office of Biotechnology Products and EMA's Committee for Medicinal Products for Human Use enforce stringent characterization requirements for liposomal critical quality attributes including particle size distribution, lamellarity, and drug encapsulation efficiency. The country's national pharmaceutical regulator in Japan, PMDA, has issued specific guidance on liposomal drug bioequivalence that shapes generic entry strategies. WHO prequalification programs for antiretroviral liposomal formulations influence procurement decisions in low-income markets. Stakeholders must monitor evolving pharmacopeial standards for liposomal characterization methods to anticipate compliance investments.
Market Dynamics
FDA's accelerated approval pathways for nanomedicine products are compressing development timelines while simultaneously tightening characterization requirements for critical quality attributes. This regulatory velocity is creating asymmetric advantages for firms with pre-validated manufacturing platforms.
Growth Catalysts
- Immunoliposome engineering:Antibody-directed targeting enables receptor-mediated uptake in solid tumors, expanding addressable oncology indications beyond conventional chemotherapy limitations.
- Japan's PMDA bioequivalence guidance:Specific regulatory frameworks for liposomal drug equivalence are clarifying generic entry pathways and stimulating formulation innovation.
- Academic medical center expansion:Oncology departments are scaling liposomal doxorubicin and paclitaxel adoption through integrated cancer center networks.
Market Restraints
- Phospholipid supply concentration:Raw material sourcing depends on a limited supplier base concentrated in European and Asian chemical manufacturing clusters.
- CE marking collapse under EU MDR:Stricter conformity assessment procedures for drug-device combinations are disqualifying legacy suppliers from European market access.
- Complex manufacturing scale-up:Aseptic processing requirements and particle size distribution control create technical barriers between pilot and commercial production.
Strategic Opportunities
- Antiretroviral liposomal prequalification:WHO procurement programs for low-income markets create volume opportunities outside premium oncology segments.
- Personalized medicine convergence:Patient-specific immunoliposome formulations combining genomic profiling with targeted delivery represent unpenetrated white space.
- US National Cancer Institute funding:Federal clinical trial infrastructure supports investigator-initiated studies that de-risk novel liposomal payloads.
Industry Challenges
- Pharmacopeial standard evolution:Shifting compendial methods for lamellarity and encapsulation efficiency assessment force continuous analytical method redevelopment.
- Specialized talent scarcity:Lipid chemistry and nanoscale characterization expertise remains concentrated among a narrow cohort of academic and industrial researchers.
- Legacy system integration:Conventional pharmaceutical manufacturing IT infrastructure requires costly adaptation for real-time liposomal process analytical technology deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Targeted Liposomes Drug Delivery Market |
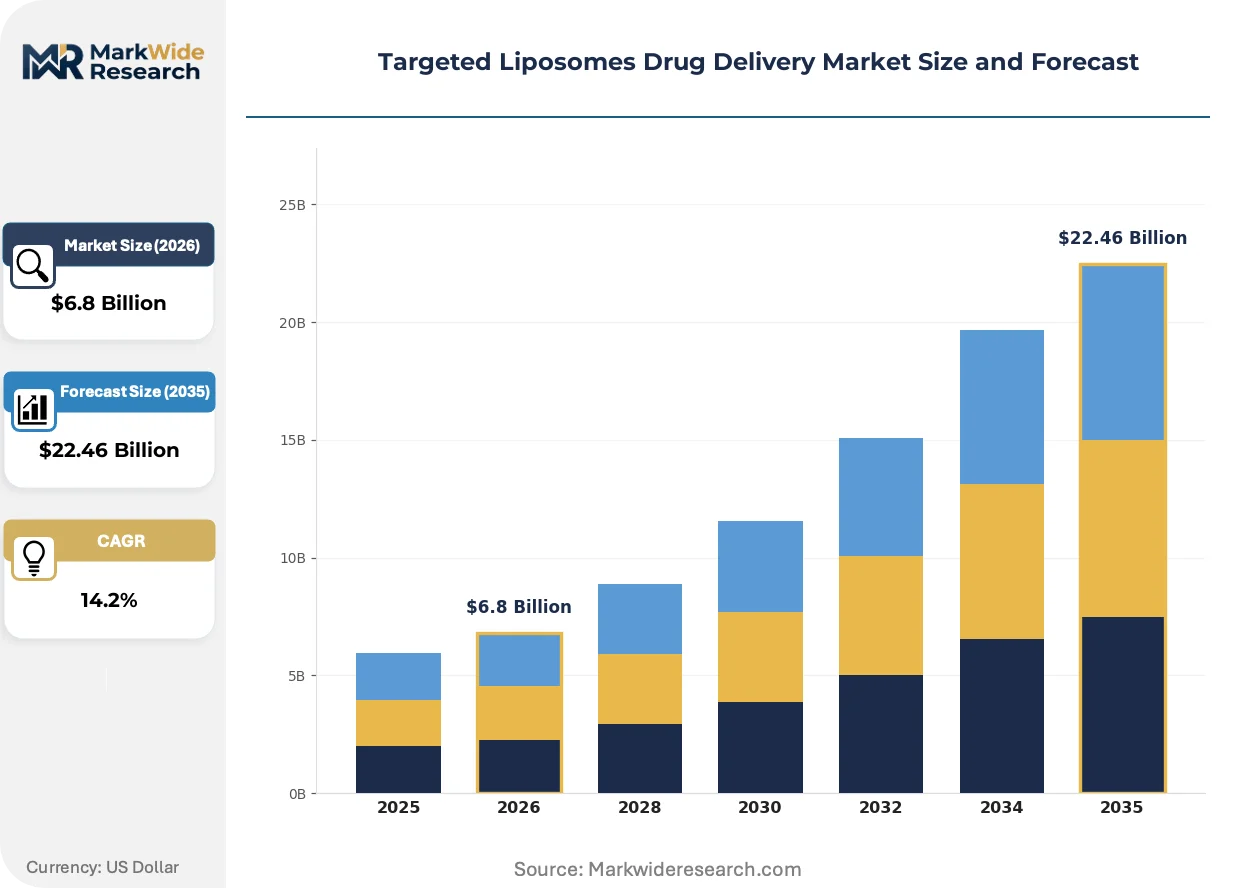
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Liposomes, PEGylated Liposomes, Immunoliposomes, Cationic Liposomes Therapy Area: AIDS, Cancer, Cardiovascular Disorders, Neurological Disorders End User: Hospitals, Research Laboratories, Pharmaceutical Companies, Specialty Clinics Administration Route: Intravenous, Subcutaneous, Oral, Intramuscular |
| Companies Covered | Johnson and Johnson, Spectrum Pharmaceuticals, Inc., Gilead Sciences, Inc., Celsion Corporation, Novartis AG, Pacira BioSciences, Inc., Ipsen Pharma, Catalent, Luye Pharma Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Targeted Liposomes Drug Delivery Market Emerging Trajectories
Surface engineering of phospholipid bilayers is enabling programmable drug release kinetics that match disease-specific pharmacological requirements. These advances are redefining competitive differentiation beyond payload capacity toward targeting precision and tissue penetration depth.
Multifunctional liposome architectures incorporating stimuli-responsive elements are displacing passive accumulation models in oncology applications. Leading cancer centers are adopting pH-sensitive and enzyme-triggered release systems for tumor microenvironment activation. This displacement is compressing market share for conventional PEGylated formulations lacking active targeting mechanisms.
EMA's Committee for Medicinal Products for Human Use has tightened requirements for liposomal critical quality attribute documentation in marketing authorization applications. Manufacturers must now submit extended stability data and in-vitro release method validation packages. European oncology-focused CDMOs are responding by investing in dedicated nanomedicine analytical capabilities ahead of formal guidance finalization.
Hospital procurement committees are consolidating liposomal therapy purchasing through centralized pharmacy and therapeutics committees. Academic medical centers are displacing individual physician preference with formulary-driven standardization for high-cost oncology infusions. This concentration is most visible in United States NCI-designated cancer centers where value-based care metrics influence therapeutic selection.
Targeted Liposomes Drug Delivery Market Segmentation
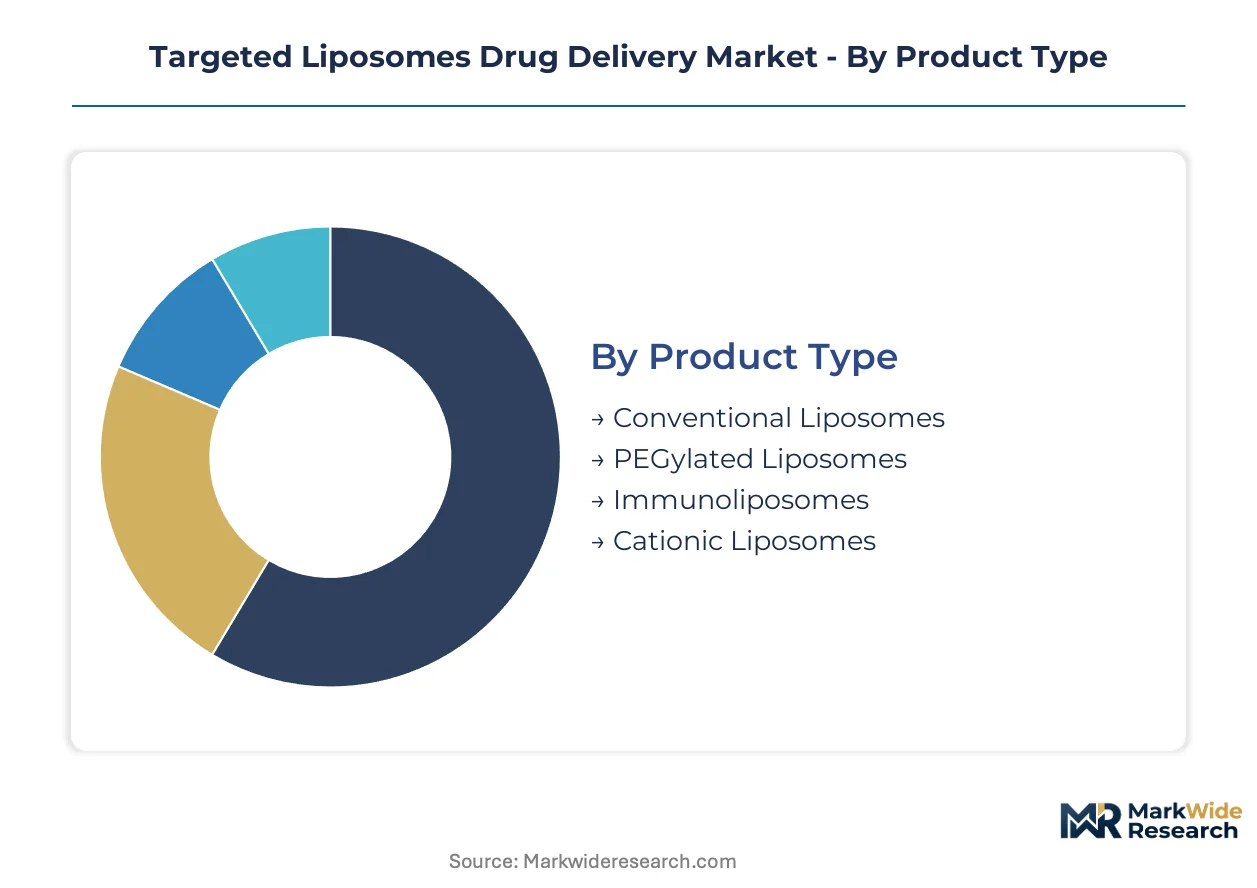
Segmentation in targeted liposomes drug delivery reveals distinct technology maturity curves and geographic demand patterns. Each dimension exposes different competitive pressures, from manufacturing scale requirements in product types to regulatory complexity across administration routes.
Product Type:
PEGylated liposomes and immunoliposomes drive export-oriented revenue, while conventional formulations serve cost-sensitive domestic markets with compressed margins.
- PEGylated Liposomes:Polyethylene glycol surface coatings extend circulation half-life by reducing reticuloendothelial system clearance. Demand concentrates in United States academic medical centers where extended-release oncology protocols command premium reimbursement. FDA accelerated approval pathways favor these established formulations.
- Immunoliposomes:Antibody-conjugated surface ligands enable receptor-mediated uptake in solid tumors through active targeting mechanisms. Japanese and European oncology departments are scaling adoption fastest as EMA and PMDA clarify characterization requirements for these complex biologics.
- Conventional Liposomes:First-generation phospholipid vesicles without surface modification dominate generic substitution markets in India and Brazil.
- Cationic Liposomes:Positively charged bilayer compositions optimize nucleic acid encapsulation for gene therapy applications.
Conventional liposomes command the established base. The steepest expansion runs through immunoliposomes.
Therapy Area:
Cancer applications absorb the highest per-patient therapy costs, while cardiovascular and neurological indications remain underpenetrated due to blood-brain barrier engineering challenges.
- Cancer:Liposomal doxorubicin and paclitaxel formulations reduce cardiotoxicity and neuropathy compared to free drug administration. United States NCI-designated cancer centers drive volume through integrated infusion networks.
- AIDS:Antiretroviral liposomal prequalification through WHO programs creates procurement concentration in Sub-Saharan African and Southeast Asian public health systems.
- Neurological Disorders:Blood-brain barrier penetration remains the critical technical barrier limiting commercial penetration.
- Cardiovascular Disorders:Localized drug delivery to atherosclerotic plaques requires targeted ligand engineering still in clinical validation.
Cancer applications command the established base. The steepest expansion runs through AIDS as WHO procurement volumes scale.
End User:
Hospital procurement committees are consolidating purchasing power, while research laboratories and pharmaceutical companies represent pre-commercial development demand with different investment timelines.
- Hospitals:Centralized pharmacy and therapeutics committees now standardize high-cost oncology infusions through formulary-driven protocols. United States academic medical centers are displacing individual physician preference with value-based care metrics.
- Pharmaceutical Companies:Internal nanomedicine platforms at Gilead Sciences and Johnson and Johnson sustain captive demand for liposomal manufacturing scale-up expertise.
- Research Laboratories:Investigator-initiated studies funded through National Cancer Institute infrastructure de-risk novel payload development.
- Specialty Clinics:Outpatient infusion centers compete on convenience metrics but lack negotiating leverage against hospital systems.
Hospitals command the established base. The steepest expansion runs through pharmaceutical companies building internal nanotechnology capabilities.
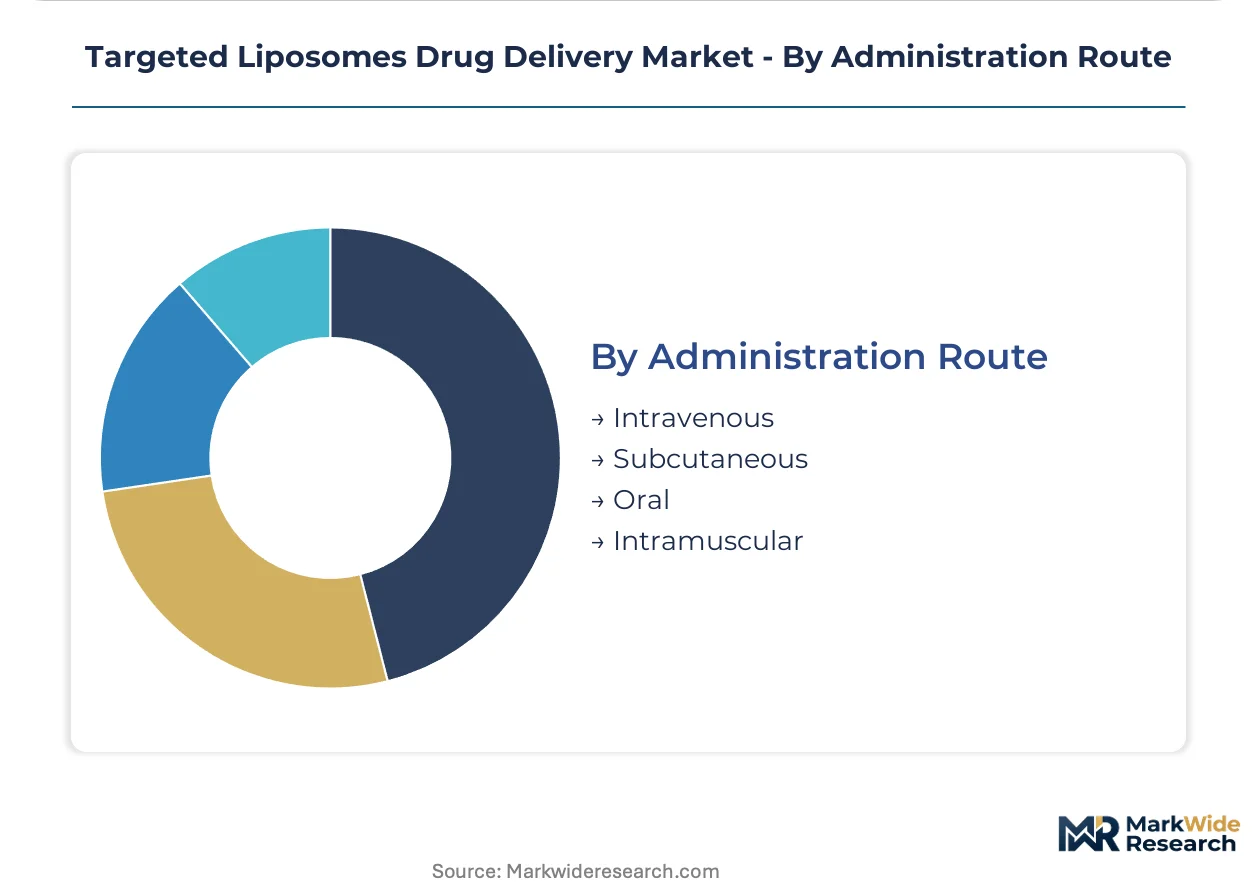
Administration Route:
Intravenous delivery dominates current commercial production, while oral and subcutaneous routes represent formulation innovation frontiers with distinct regulatory validation requirements.
- Intravenous:Direct bloodstream infusion enables precise dosing control for cytotoxic payloads. Manufacturing infrastructure concentrates in United States and European CDMOs with aseptic processing certification.
- Subcutaneous:Depot formulations extend dosing intervals for chronic disease management. PMDA in Japan has issued specific bioequivalence guidance shaping generic entry strategies for these modified-release systems.
- Oral:Gastrointestinal stability and mucosal absorption barriers limit current commercial viability despite patient compliance advantages.
- Intramuscular:Sustained-release depots for vaccine adjuvants and hormonal therapies occupy niche therapeutic categories.
Intravenous administration commands the established base. The steepest expansion runs through subcutaneous routes as patient-centric dosing protocols gain regulatory traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and specialized oncology hospitals concentrate purchasing power across major pharmaceutical markets. Procurement committees in these institutions drive formulary standardization for high-cost liposomal infusions. Regulatory velocity varies significantly by jurisdiction, creating asymmetric competitive advantages.
United States
NCI-designated cancer centers in Boston, Houston, and New York Metro scale liposomal doxorubicin adoption through integrated infusion networks. FDA accelerated approval pathways compress development timelines for nanomedicine products while tightening characterization requirements. Manufacturing infrastructure clusters around Philadelphia and San Francisco Bay Area CDMOs with aseptic processing certification.
Germany
EMA Committee for Medicinal Products for Human Use enforcement of extended stability data requirements shapes marketing authorization strategies. CE marking collapse under EU Medical Device Regulation disqualifies legacy suppliers from drug-device combination markets. Heidelberg and Munich oncology centers anchor European demand for immunoliposome clinical trials.
Japan
PMDA bioequivalence guidance for liposomal drugs clarifies generic entry pathways and stimulates formulation innovation. Tokyo and Osaka academic hospitals drive adoption of antibody-directed targeting systems. Domestic pharmaceutical manufacturers invest in nanoscale characterization capabilities ahead of formal guidance finalization.
India
CDSCO regulatory frameworks for complex generics create pathways for conventional liposome manufacturing at scale. Mumbai and Hyderabad pharmaceutical clusters expand contract development capabilities for export-oriented PEGylated formulations. WHO prequalification programs for antiretroviral liposomes influence procurement decisions in African and Southeast Asian markets.
Switzerland
Swissmedic oversight of critical quality attributes attracts nanomedicine development from multinational pharmaceutical operations. Basel and Zurich regions concentrate lipid chemistry expertise and specialized analytical method development. European distribution networks for premium oncology therapies anchor through Swiss logistics infrastructure.
Targeted Liposomes Drug Delivery Market Vendor Landscape
Player mix skews toward integrated pharmaceutical conglomerates with validated nanotechnology platforms. Market structure concentrates around firms with pre-established manufacturing scale and regulatory submission experience. Three archetypes dominate: platform technology developers, commercial-scale manufacturers, and specialized oncology-focused developers. Competitive moves center on strategic partnerships for lipid supply security and capacity expansion for aseptic processing capabilities.
Within the integrated pharmaceutical tier, Johnson and Johnson, Gilead Sciences, and Novartis occupy positions that exemplify scale-driven competitive advantages. Johnson and Johnson represents the commercial manufacturing archetype with pharmaceutical production infrastructure. Gilead Sciences anchors the platform technology segment through established nanotechnology capabilities. Novartis sits within the European market access specialization, leveraging distribution networks for oncology therapeutics. These three entities collectively demonstrate how regulatory velocity and manufacturing scale create defensive positioning in liposomal drug delivery.
| Leading Market Players |
|---|
| Johnson and Johnson |
| Spectrum Pharmaceuticals, Inc. |
| Gilead Sciences, Inc. |
| Celsion Corporation |
| Novartis AG |
| Pacira BioSciences, Inc. |
| Ipsen Pharma |
| Catalent |
| Luye Pharma Group |
| Others |
Supply Flow & Price Mechanics
Ninety-day phospholipid inventory buffers in European chemical manufacturing clusters concentrate pricing power among legacy suppliers while compressing margins for formulation developers lacking backward integration into lipid chemistry capabilities.
Pricing Analysis
Cost-plus contracts indexed to egg yolk phospholipid commodity benchmarks dominate raw material procurement. Three-tier pricing structure across PEGylated premium formulations, immunoliposome specialty tiers, and conventional generic equivalents reflects encapsulation efficiency differentials. Pricing pressure stems from hospital formulary standardization consolidating purchasing leverage. Academic medical centers exhibit lowest price sensitivity; Indian CDSCO-registered generic manufacturers face acute margin compression.
Supply Chain Analysis
Kourou spaceport-adjacent lipid extraction facilities in French Guiana represent a latent chokepoint for high-purity phospholipid feedstock. Manufacturing gravity centers on Germany, Japan, and the United States for aseptic processing infrastructure. Raw material dependencies encompass hydrogenated soy phosphatidylcholine, synthetic cholesterol, and PEGylation reagents. Single-source vulnerability concentrates in hydrogenated lipid precursors. Distribution runs through Swiss oncology logistics hubs serving European hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics as FDA accelerated approval pathways compress development timelines and restock depleted clinical pipeline inventories.
For Market Incumbents: Fortify lipid supply security through captive production of hydrogenated phosphatidylcholine or long-term offtake agreements with European chemical manufacturers. Expand aseptic processing capacity in United States CDMO clusters to capture immunoliposome formulation demand. EMA extended stability requirements threaten legacy analytical capabilities.
For New Entrants and Emerging Players: Lead with antiretroviral liposomal prequalification pathways under WHO procurement programs as the most penetrable volume segment. Target Sub-Saharan African public health systems with cost-engineered conventional formulations. Pursue technology licensing from academic medical center spinouts to bypass internal R&D scale requirements.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational pharmaceutical conglomerates divesting non-core nanomedicine platforms. Five-to-ten-year viability hinges on regulatory submission experience and validated manufacturing scale. Monitor PMDA bioequivalence guidance finalization as inflection signal for generic entry velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Aseptic processing certification unlocks commercial supply contracts with NCI-designated cancer centers. |
| Regulatory Approval Pathway | FDA accelerated approval compresses development timelines for novel immunoliposome payloads. |
| Backward Integration | Captive phospholipid production insulates margins from European chemical supplier concentration. |
| Hospital System Partnership | Formulary placement agreements with academic medical centers secure volume commitments. |
| Pipeline Diversification | Gene therapy cationic liposome expansion reduces oncology indication concentration risk. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with regulatory affairs leads, hospital procurement managers, and nanomedicine manufacturing executives; and secondary validation against FDA filings, EMA marketing authorization submissions, ClinicalTrials.gov protocols, and WHO prequalification records. Bottom-up formulation demand modeling triangulated against top-down pharmaceutical R&D expenditure tracking.
Across the projection horizon, analytical frameworks segmented demand by product type, therapy area, administration route, and regional regulatory cluster. CAGRs derived from patent expiry modeling, biosimilar entry velocity, and academic medical center formulary adoption curves. Forecast inputs incorporated PMDA guidance evolution timelines and CE marking transition compliance costs.
The analysis sits within stated boundaries; outcomes outside sustained NCI funding levels or phospholipid supply stability would require recalibration. Practitioners should keep alternative scenarios live as EMA critical quality attribute requirements and hospital value-based care metrics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Secondary Myelofibrosis Therapeutics Market
Pharmaceuticals
India Plasma Fractionation Market
Pharmaceuticals
Global Hepatitis B Vaccines Market
Pharmaceuticals
Global Vero Cell Rabies Vaccine Market
Pharmaceuticals
Peptide and Anticoagulant Drugs Market
Pharmaceuticals
Bendamustin Market
Pharmaceuticals
Bispecific Antibody Therapeutics Contract Manufacturing Market
Pharmaceuticals
Meperidine Drugs Market
Pharmaceuticals
Global Prophylactic HIV Drugs Market
Pharmaceuticals
Inhaled Nitric Oxide Market
Pharmaceuticals
Powder-Filled Hard Gelatin Capsules Market
Pharmaceuticals
France Diabetes Drugs Market
Pharmaceuticals
Netherlands Pharmaceutical Market
Pharmaceuticals
Cough Suppressant Drugs Market
Pharmaceuticals
Global Travel Vaccines Market
Pharmaceuticals
Complement-Targeted Therapeutics Market