
 Asia-Pacific Cancer Vaccines Market | 2026-2036
Asia-Pacific Cancer Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cancer Vaccines Market Outlook
mRNA lipid nanoparticle formulations are realigning cost structures away from traditional peptide-based manufacturing in the Asia-Pacific cancer vaccines sector. GlaxoSmithKline leverages its adjuvant technology heritage to sustain competitive positioning across Southeast Asian markets. Bristol-Myers Squibb anchors its regional presence through immuno-oncology combinations with therapeutic vaccine candidates. Serum Institute of India dominates bulk manufacturing economics for accessible preventive and therapeutic doses.
Cancer vaccines are biologic preparations designed to stimulate antigen-specific immune responses against malignant cells, typically comprising tumor-associated antigens, neoantigens, or autologous tumor lysates delivered via viral vectors, nucleic acid platforms, or protein subunits, with specifications requiring cold-chain stability between 2°C and 8°C for protein-based formats and ultralow -70°C storage for mRNA formulations; their primary purpose is to prevent virus-induced carcinogenesis or to treat established tumors by breaking immune tolerance. Therapeutic vaccines command the deepest margin pools as personalized neoantigen platforms expand, while RNA Technology attracts the fastest development velocity across the region's clinical pipelines. Hospitals remain the dominant end-user channel for administered doses, though oncology clinics capture growing volumes for outpatient immuno-oncology protocols.
Japan's PMDA operates a pioneering regenerative medicine and cellular therapy review framework that compresses approval timelines for cancer vaccines, while India's CDSCO implements accelerated pathways under the New Drugs and Clinical Trials Rules to stimulate domestic biopharma innovation. Australia's TGA aligns its biologicals licensing with ICH quality standards, creating harmonized manufacturing benchmarks for regional exporters. Stakeholders must monitor how China's NMPA balances data localization requirements against multinational trial participation rules, as this tension will determine which platforms achieve scalable market access across the Asia-Pacific.
Market Dynamics
mRNA lipid nanoparticle platforms are compressing manufacturing timelines and reshaping competitive economics across the Asia-Pacific cancer vaccines sector, forcing peptide-based incumbents to reconfigure cost structures or exit therapeutic segments entirely.
Growth Catalysts
- Japan's PMDA regenerative medicine framework:Compressed approval timelines for personalized neoantigen vaccines accelerate clinical-to-commercial transitions for domestic biotech firms.
- Oncology clinic expansion:Outpatient immuno-oncology protocols in Australia and South Korea shift administration volumes away from hospital inpatient settings.
- CDSCO accelerated pathways:India's New Drugs and Clinical Trials Rules stimulate domestic innovation for gastric and liver malignancy vaccines targeting regional disease burdens.
Market Restraints
- Ultralow cold-chain infrastructure:mRNA formulations requiring -70°C storage strain distribution networks in Southeast Asian markets with unreliable electricity grids.
- Input concentration risk:Lipid nanoparticle manufacturing depends on a narrow supplier base concentrated in North American and European chemical producers.
- Technical limitation in neoantigen prediction:Computational pipelines for personalized vaccine design remain computationally intensive and clinically unvalidated for solid tumor heterogeneity.
Strategic Opportunities
- Vietnam and Indonesia penetration:Underdeveloped therapeutic vaccine access in these Southeast Asian markets creates first-mover positioning for viral vector platforms with ambient-stable profiles.
- Technology convergence:Combination of therapeutic vaccines with checkpoint inhibitors opens new protocol categories in oncology clinics across Australia.
- China's NMPA data localization requirements:Domestic trial participation mandates create captive market access for biotech firms establishing local manufacturing partnerships.
Industry Challenges
- Bioinformatics talent scarcity:Shortage of computational biologists specializing in neoantigen prediction pipelines constrains personalized vaccine program scaling.
- Good Manufacturing Practice certification timelines:CDSCO and TGA facility approvals extend 18-24 months, delaying regional supply ramp for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cancer Vaccines Market |
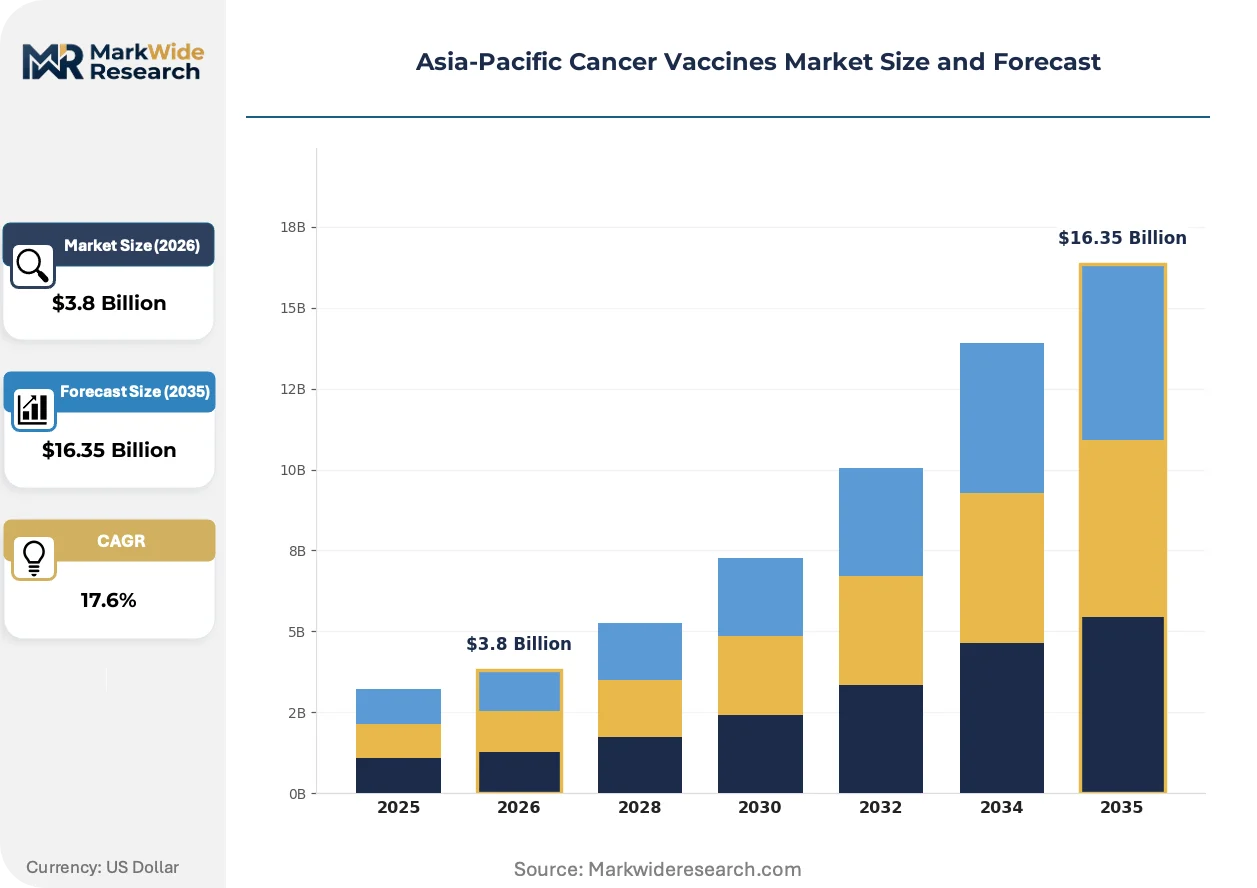
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.35 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preventive Vaccines, Therapeutic Vaccines, Proto-oncogene Vaccines, Tumor Antigen Vaccines Delivery Mode: Intramuscular Injection, Intravenous Injection, Subcutaneous Injection, Dermal Application End User: Hospitals, Research Institutions, Oncology Clinics, Diagnostic Centers Technology: DNA Technology, RNA Technology, Viral Vector Technology, Protein-based Technology |
| Companies Covered | GlaxoSmithKline, AstraZeneca, Bristol-Myers Squibb, Pfizer, Sanofi, Eli Lilly and Company, Merck & Co., Serum Institute of India, Daiichi Sankyo Company Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cancer Vaccines Market Strategic Shifts
Platform biology and regulatory science are converging to redefine how cancer vaccines advance from discovery to regional market access, with nucleic acid delivery systems and adaptive licensing frameworks commanding disproportionate investment attention.
mRNA lipid nanoparticle technology functions as a programmable antigen delivery system enabling rapid pivot between tumor-associated and neoantigen targets. Oncology clinics in Japan and Australia are adopting these platforms at accelerating velocity for outpatient administration. This flexibility is integrating therapeutic vaccine development with real-time genomic profiling, compressing the traditional antigen selection-to-manufacturing cycle from months to weeks.
Japan's PMDA operates a pioneering regenerative medicine and cellular therapy review framework that compresses approval timelines for personalized cancer immunotherapies. This regulatory architecture accelerates commercial entry for first-in-class platforms while establishing precedent for adaptive licensing across the Asia-Pacific. Domestic Japanese biotech firms and multinational subsidiaries are restructuring clinical trial designs to align with this pathway, prioritizing single-arm studies with surrogate endpoints.
Hospital procurement departments are unbundling vaccine administration from bundled oncology service contracts, creating standalone reimbursement categories for outpatient therapeutic protocols. Oncology clinics in South Korea and Australia capture growing volumes through this channel fragmentation, displacing traditional inpatient infusion centers. This shift is most visible in Australia's private healthcare network, where clinic chains negotiate direct platform supply agreements bypassing hospital pharmacy intermediaries.
Asia-Pacific Cancer Vaccines Market Segmentation
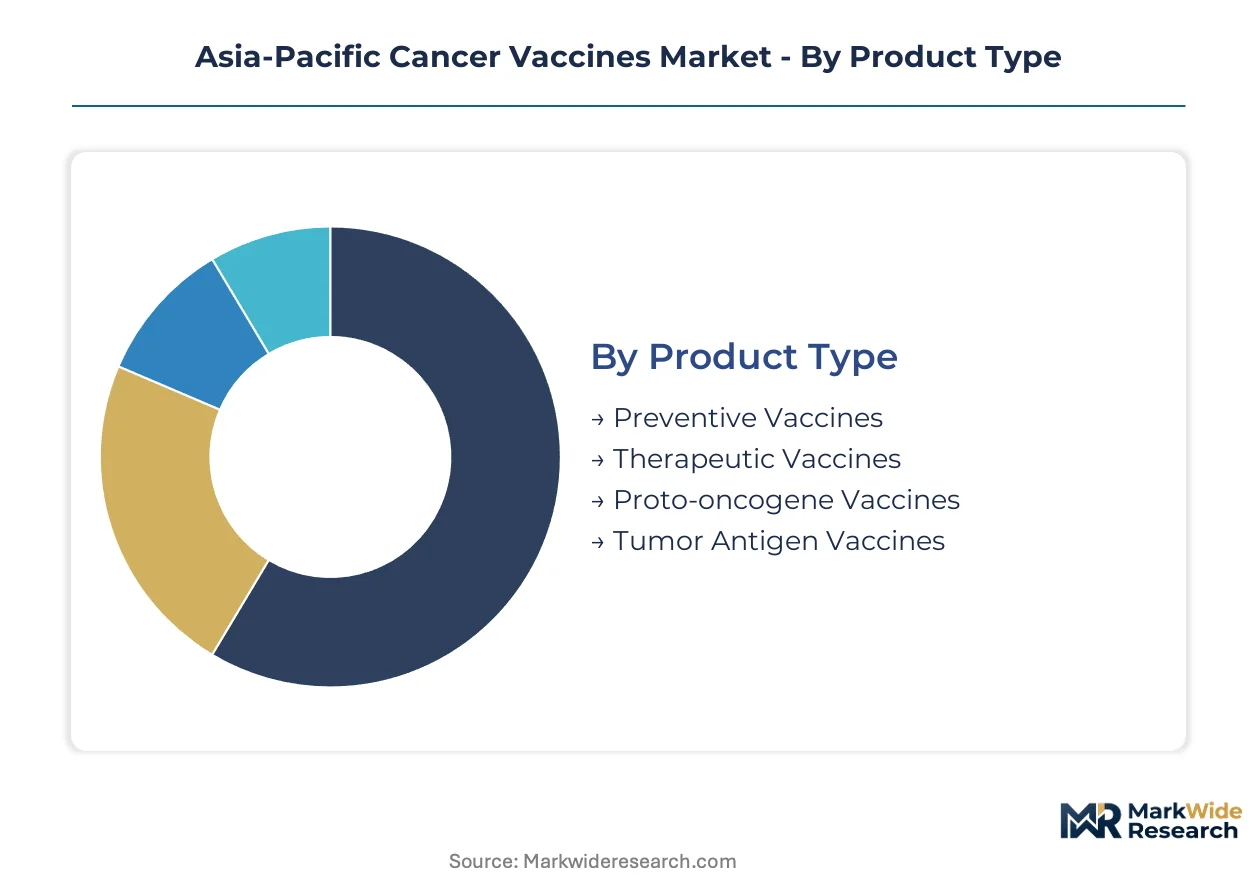
Cancer vaccines segment across multiple technical and commercial dimensions that determine manufacturing scale, distribution infrastructure, and reimbursement pathways. Understanding how product formats, administration routes, and technology platforms diverge reveals where margin pools concentrate and where supply constraints emerge.
Product Type:
Buyers differentiate primarily by clinical intent — prevention versus treatment — which dictates regulatory pathway complexity and pricing power.
- Therapeutic Vaccines:These biologics target established malignancies using tumor-associated antigens or patient-specific neoantigens to break immune tolerance. Oncology clinics across Japan and Australia are expanding outpatient administration of these platforms as PMDA compressed timelines accelerate commercial entry for personalized formats.
- Preventive Vaccines:Designed to intercept virus-induced carcinogenesis, these products target human papillomavirus and hepatitis B antecedents. India's CDSCO accelerated pathways under New Drugs and Clinical Trials Rules are stimulating domestic manufacturing for accessible preventive doses targeting regional disease burdens.
- Tumor Antigen Vaccines:Off-the-shelf formulations targeting shared tumor-associated antigens reduce manufacturing complexity compared to personalized alternatives.
- Proto-oncogene Vaccines:Emerging platforms directed against mutated oncogene products remain in early clinical development across Asia-Pacific academic centers.
Therapeutic vaccines lead volumes today; RNA-enabled therapeutic formats are gaining share fastest.
Delivery Mode:
Route selection hinges on immune response kinetics and cold-chain feasibility across diverse Asia-Pacific healthcare infrastructure.
- Intramuscular Injection:The standard administration route for protein-based and mRNA lipid nanoparticle formulations, enabling depot formation and sustained antigen presentation. Southeast Asian markets with unreliable electricity grids favor this modality for formulations stable at standard refrigeration.
- Intravenous Injection:Required for certain viral vector platforms and cell-based vaccines, demanding hospital-grade infusion capabilities. Australian oncology clinics are capturing growing volumes through outpatient IV protocols that displace traditional inpatient settings.
- Subcutaneous Injection:Simplified administration suitable for peptide-based vaccines and some nucleic acid platforms.
- Dermal Application:Microneedle and patch-based delivery systems in development for thermostable viral vector formats.
Intramuscular administration dominates dose volumes; subcutaneous routes are climbing the fastest as outpatient protocols expand.
End User:
Channel selection reflects reimbursement unbundling and the shift from inpatient to outpatient immuno-oncology care.
- Oncology Clinics:Specialized outpatient facilities capturing growing therapeutic vaccine volumes as hospital procurement departments unbundle administration from bundled oncology contracts. South Korean clinic chains are negotiating direct platform supply agreements that bypass hospital pharmacy intermediaries.
- Hospitals:Retain dominance for complex IV-administered formats and inpatient protocols, particularly in China's tier-one cities where integrated cancer centers concentrate.
- Research Institutions:Academic medical centers in Japan and Australia conduct early-phase trials under PMDA and TGA frameworks.
- Diagnostic Centers:Emerging sites for companion diagnostic-linked vaccine selection in China's biotech corridors.
Hospitals retain the largest patient throughput; oncology clinics show the steepest expansion trajectory.
Technology:
Platform selection determines manufacturing capital intensity, regulatory validation burden, and speed of antigen pivot.
- RNA Technology:mRNA lipid nanoparticle systems enable rapid reprogramming between tumor-associated and neoantigen targets, compressing antigen selection-to-manufacturing cycles from months to weeks. China's NMPA data localization requirements are creating captive market access for firms establishing local manufacturing partnerships for these platforms.
- Viral Vector Technology:Adenovirus and lentivirus delivery systems offer durable antigen expression with ambient-stable profiles suited to Southeast Asian distribution constraints. Vietnam and Indonesia's underdeveloped cold-chain infrastructure creates first-mover positioning for these formats.
- DNA Technology:Plasmid-based vaccines with simplified manufacturing economics but lower immunogenicity requiring electroporation enhancement.
- Protein-based Technology:Traditional peptide and recombinant protein formats facing margin pressure from nucleic acid platform competition.
Protein-based platforms retain installed manufacturing base; RNA technology is expanding most quickly across regional clinical pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's biotech corridors in Shanghai and Suzhou anchor therapeutic vaccine development across the Asia-Pacific, with domestic firms and multinationals co-developing mRNA and viral vector platforms for gastric and liver malignancies prevalent in East Asian populations.
China
Demand concentrates in Shanghai and Suzhou biotech clusters for personalized neoantigen platforms targeting gastric cancer. NMPA data localization requirements create captive market access for firms establishing local manufacturing partnerships. Yangtze River Delta facilities are expanding GMP capacity for mRNA lipid nanoparticle production.
Japan
Oncology clinics in Tokyo and Osaka are expanding outpatient therapeutic vaccine adoption for melanoma and lung cancer indications. PMDA's regenerative medicine framework compresses approval timelines for personalized immunotherapies. Kansai region academic medical centers are restructuring trial designs to align with single-arm adaptive licensing pathways.
India
Domestic manufacturing for accessible preventive doses targets HPV and hepatitis B antecedents in regional disease burdens. CDSCO accelerated pathways under New Drugs and Clinical Trials Rules stimulate biopharma innovation. Pune and Hyderabad bulk manufacturing facilities are scaling output for export markets across Southeast Asia.
Australia
Private healthcare networks in Sydney and Melbourne are unbundling vaccine administration from bundled oncology contracts. TGA biologicals licensing aligns with ICH quality standards for regional exporters. Victoria's oncology clinic chains negotiate direct platform supply agreements that bypass hospital pharmacy intermediaries.
South Korea
Seoul Capital Area clinics capture growing therapeutic vaccine volumes through outpatient immuno-oncology protocols. MFDS streamlines review pathways for combination therapies with checkpoint inhibitors. Busan-Ulsan manufacturing hubs are adding viral vector capacity for ambient-stable formulations targeting Southeast Asian distribution.
Asia-Pacific Cancer Vaccines Market Competitive Environment
Global majors compete with regional champions across technology platform differentiation, with multinational pharmaceutical conglomerates holding established adjuvant and immuno-oncology portfolios while domestic biotech firms capture localized manufacturing economics. The vendor base stratifies into three tiers: integrated conglomerates with broad oncology pipelines, specialized vaccine manufacturers with bulk production scale, and emerging biotech platforms focused on nucleic acid delivery systems. Dominant competitive moves include strategic partnerships for local manufacturing rights and technology licensing agreements to secure NMPA data compliance pathways.
Within the integrated conglomerate tier, GlaxoSmithKline and Bristol-Myers Squibb exemplify archetypes leveraging adjuvant heritage and immuno-oncology combination strategies respectively. Among regional manufacturing specialists, Serum Institute of India occupies a position representing bulk production economics for accessible dose supply across price-sensitive markets. These three anchors illustrate how competitive positioning diverges between technology-led premium platforms and scale-driven accessible supply models.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| AstraZeneca |
| Bristol-Myers Squibb |
| Pfizer |
| Sanofi |
| Eli Lilly and Company |
| Merck & Co. |
| Serum Institute of India |
| Daiichi Sankyo Company Limited |
| Others |
Value Chain & Pricing Dynamics
Lipid nanoparticle input costs cascade through three pricing tiers for cancer vaccines across Asia-Pacific markets, with ionizable lipid sourcing from North American chemical producers feeding premium mRNA formulations while peptide-based alternatives compete on manufacturing scale in standard and economy segments.
Pricing Analysis
Input-cost pass-through from lipid nanoparticle chemistry anchors premium pricing for mRNA platforms, while manufacturing scale drives differentiation between personalized neoantigen formats and off-the-shelf tumor antigen vaccines. Price differentiation rests on cold-chain complexity and regulatory certification tier, with PMDA-accelerated pathways commanding premiums over standard CDSCO review timelines. Pricing pressure intensifies in Southeast Asian markets as ambient-stable viral vector alternatives erode mRNA margins. Hospital procurement departments exhibit highest price sensitivity, while oncology clinics in Japan and Australia accept premium positioning for outpatient administration convenience.
Supply Chain Analysis
Direct-to-hospital channels handle complex IV-administered formats in China's tier-one cities, while specialized distributors serve oncology clinic networks across Australia and South Korea with outpatient-compatible intramuscular products. Manufacturing concentrates in China, India, and South Korea, with Yangtze River Delta facilities expanding GMP capacity for mRNA production and Pune-Hyderabad hubs scaling bulk preventive vaccine output. Raw material dependencies center on ionizable lipids, synthetic nucleotides, and viral vector plasmid banks sourced primarily from North American and European suppliers. Single-source vulnerability in lipid nanoparticle chemistry creates supply chain risk for regional mRNA programs. Distribution runs through cold-chain logistics providers with -70°C capabilities for nucleic acid platforms and standard refrigeration networks for protein-based alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific cancer vaccines function as a regulatory compounder where PMDA's regenerative medicine framework and CDSCO's accelerated pathways continuously expand addressable demand through compressed approval timelines.
For Market Incumbents: Anchor competitive position through backward integration into lipid nanoparticle manufacturing or captive supply agreements with North American chemical producers. Defend against emerging biotech platforms by securing exclusive oncology clinic distribution contracts in Australia's unbundled procurement environment. Prioritize GMP certification investment in India and Japan to maintain supply priority under CDSCO and PMDA frameworks.
For New Entrants and Emerging Players: Begin with viral vector platforms targeting Vietnam and Indonesia's underdeveloped therapeutic vaccine access, where ambient-stable profiles bypass -70°C infrastructure constraints. Capture first-mover positioning in China's NMPA data localization compliance pathway through local manufacturing partnerships. Pursue direct supply agreements with South Korean clinic chains as the most penetrable channel for outpatient immuno-oncology protocols.
For Investors and Strategic Acquirers: Consolidation pressure builds where bioinformatics talent scarcity constrains personalized vaccine program scaling across the region. Long-term viability favors platforms with demonstrated PMDA or CDSCO approval momentum and established cold-chain distribution partnerships. Target acquisition archetypes include computational biology specialists with validated neoantigen prediction pipelines. Watch for inflection signals in MFDS combination therapy approvals linking therapeutic vaccines with checkpoint inhibitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | PMDA's regenerative medicine framework compresses timelines for personalized immunotherapies entering Japanese oncology clinics. |
| Manufacturing Scale-Up | Yangtze River Delta GMP expansion addresses NMPA data localization requirements for mRNA platform market access. |
| Licensing Agreement | Technology partnerships with North American lipid suppliers secure input cost stability for regional mRNA production. |
| Clinical Trial Advancement | Single-arm adaptive designs align with PMDA precedent, accelerating commercial entry for first-in-class platforms. |
| Pipeline Diversification | Viral vector development for ambient-stable formats targets Southeast Asian markets with unreliable cold-chain infrastructure. |
Study Parameters
Coverage spans China, Japan, India, Australia, and South Korea, with primary inputs from each market combining interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors with secondary validation from PMDA filings, CDSCO submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient population modeling and top-down market sizing triangulate volume and value estimates across the analysis window.
Rate-of-change decomposition separates volume growth from pricing dynamics across product type, technology platform, administration route, and regional regulatory cluster segments. CAGRs derive from patient incidence projections, treatment penetration assumptions, and dose pricing trajectories throughout the forecast period. Industry-specific inputs include PMDA approval pathway utilization rates and CDSCO accelerated review application volumes.
Several conditions sit outside the modeled scope, including regulatory rejection scenarios, manufacturing facility contamination events, and competitor pipeline failures that could revise commercialization timelines. Forecasts reflect assumptions about continued regulatory framework stability and cold-chain infrastructure investment across Southeast Asian markets. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Human Vaccines Market
Pharmaceuticals
Contraceptive Drugs Market
Pharmaceuticals
Global Loperamide Hcl Market
Pharmaceuticals
Human Combination Vaccines Market
Pharmaceuticals
Generic Pharmaceuticals Contract Manufacturing Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Inhibitors Market
Pharmaceuticals
Amlodipine Besylate Market
Pharmaceuticals
Asia-Pacific Adenomyosis Drugs Market
Pharmaceuticals
Tinea Versicolor Treatment Market
Pharmaceuticals
Synthetic Drugs Market
Pharmaceuticals
Veterinary Insulin Drugs Market
Pharmaceuticals
US Pharmaceutical CMO Market
Pharmaceuticals
Mucosolvan (Ambroxol) Market
Pharmaceuticals
Digital Pharmaceutical Supply Chain Management Market
Pharmaceuticals
Traumatic Brain Injury Drugs Market
Pharmaceuticals
Soft Capsules Drugs Market