
 Basic Methacrylate Copolymer Market | 2026-2036
Basic Methacrylate Copolymer Market Size, Share, and Industry Trends Forecast 2026-2036
Basic Methacrylate Copolymer Market Analysis
The capability gap between integrated resin producers and formulation-only suppliers is collapsing as raw material volatility squeezes margins. BASF SE leverages its captive methacrylate monomer supply to sustain cost advantages across pharmaceutical-grade copolymer lines. Evonik Industries anchors its position through specialized medical device polymers that meet stringent biocompatibility protocols. Arkema Group competes by controlling downstream coating formulations in European automotive supply chains.
Basic methacrylate copolymers comprise methyl methacrylate units copolymerized with functional monomers such as butyl methacrylate or dimethylaminoethyl methacrylate, yielding glass transition temperatures tunable between 20°C and 105°C for targeted film-forming performance. These materials serve primarily as binders, enteric coatings, and controlled-release matrices in pharmaceutical and industrial applications. Copolymer A variants dominate current revenue pools due to established use in moisture-protective tablet coatings, while medical device applications represent the fastest-expanding segment driven by implantable drug-eluting platforms. Poly(methyl methacrylate) grades retain mature, high-volume positions in dental and orthopedic cement formulations where decades of clinical validation protect incumbent supply relationships.
EMA's excipient master file requirements and FDA's Inactive Ingredient Database standards govern pharmaceutical-grade copolymer qualification, creating barriers for unqualified suppliers and concentrating procurement among pre-audited vendors. REACH registration obligations and evolving EU MDR traceability mandates further shape competitive access across European medical device supply chains. Stakeholders must monitor regulatory divergence between FDA quality-by-design expectations and EMA's evolving polymer impurity thresholds to anticipate reformulation investments and qualification timelines.
Market Dynamics
Pharmaceutical manufacturers are consolidating procurement around pre-qualified copolymer suppliers as EMA impurity thresholds and FDA quality-by-design protocols tighten material traceability requirements. This regulatory compression favors integrated producers with captive monomer supply and documented batch histories over formulation-only vendors.
Growth Catalysts
- Controlled-release drug delivery:Tablet manufacturers seek methacrylate matrices enabling zero-order release kinetics for narrow-therapeutic-index compounds. EUDRAGIT polymer families command preference for gastric-resistance applications.
- REACH polymer registration:Completed registrations for methacrylate copolymers reduce regulatory friction for European pharmaceutical formulators, accelerating qualification timelines for new excipient grades.
- Implantable medical devices:Drug-eluting stent and orthopedic coating applications expand addressable volume for biocompatible copolymer grades with tunable degradation profiles.
Market Restraints
- Methyl methacrylate feedstock volatility:Acetone cyanohydrin route dependence exposes margins to acetone and hydrogen cyanide price swings, compressing returns for non-integrated compounders.
- Specialty polymer supply concentration:Pharmaceutical-grade copolymer production clusters in Germany and Switzerland, creating geographic single-source risk for qualified material.
- Cellulosic substitute competition:Hydroxypropyl methylcellulose acetate succinate offers comparable enteric performance at lower excipient cost for cost-sensitive generic formulations.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO excipient guidelines alignment with IPEC standards creates opening for qualified suppliers to penetrate formulation outsourcing hubs near Hyderabad and Ahmedabad.
- 3D-printed personalized dosing:Fused deposition modeling of methacrylate-based filaments enables on-demand tablet production with patient-specific release profiles.
- EU MDR traceability mandates:Unique Device Identification requirements for implantable polymers reward suppliers with blockchain-enabled batch documentation systems.
Industry Challenges
- Polymer characterization expertise:Advanced gel permeation chromatography and thermal analysis capabilities required for molecular weight distribution documentation are scarce among mid-tier compounders.
- DMF compilation timelines:FDA Type IV Drug Master File preparation for novel copolymer compositions demands 18-24 month investment before commercial supply authorization.
- Legacy coating equipment retrofit:Aqueous dispersion grades require spray system modifications incompatible with solvent-based infrastructure at established tablet facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Basic Methacrylate Copolymer Market |
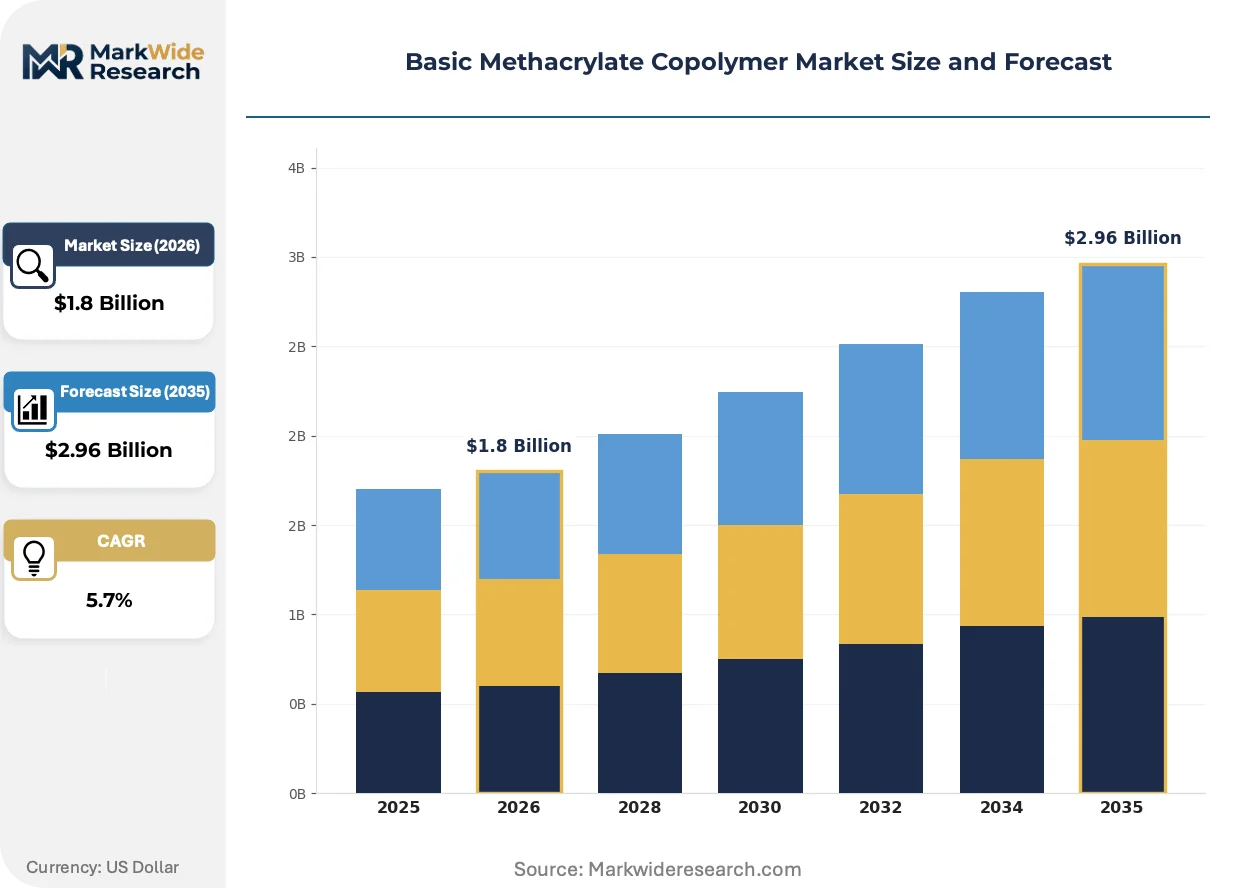
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poly(methyl methacrylate), Copolymer A, Copolymer B, Copolymer C Application: Coatings, Adhesives, Sealants, Medical Devices End User: Automotive, Construction, Healthcare, Electronics Distribution Channel: Direct Sales, Wholesale, Online Retail, Others |
| Companies Covered | Croda Inc., Corel Pharma Chem., The Dow Chemical Company, Arkema Group, Akzo Nobel N.V., BASF SE, Sigma-Aldrich Co. LLC, Vikram Thermo, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Basic Methacrylate Copolymer Market Emerging Trajectories
Functionalization chemistry and process analytical technology are redefining how methacrylate copolymers qualify for pharmaceutical use. Manufacturers now compete on molecular precision rather than commodity scale.
Reactive extrusion with in-line near-infrared monitoring is displacing batch solution polymerization for pharmaceutical-grade copolymers. Continuous processing equipment suppliers report accelerated adoption among CDMOs serving North American generic drug sponsors. This shift compresses batch-to-batch variability while reducing solvent recovery burdens.
EMA's revised guideline on plasticizers and impurities in polymer excipients is forcing reformulation of legacy coating dispersions. Manufacturers must demonstrate absence of specified nitrosamines and residual monomers below tightened thresholds. European tablet producers are prioritizing suppliers with validated purge protocols and dedicated pharmaceutical production lines.
Long-term supply agreements with pharmaceutical sponsors now specify copolymer molecular weight distribution parameters rather than broad pharmacopeial compliance. Procurement teams at major generics houses embed polymer scientists in supplier qualification audits. This specification tightening is most visible among German and Swiss formulation facilities serving EU institutional tender markets.
Basic Methacrylate Copolymer Market Segmentation
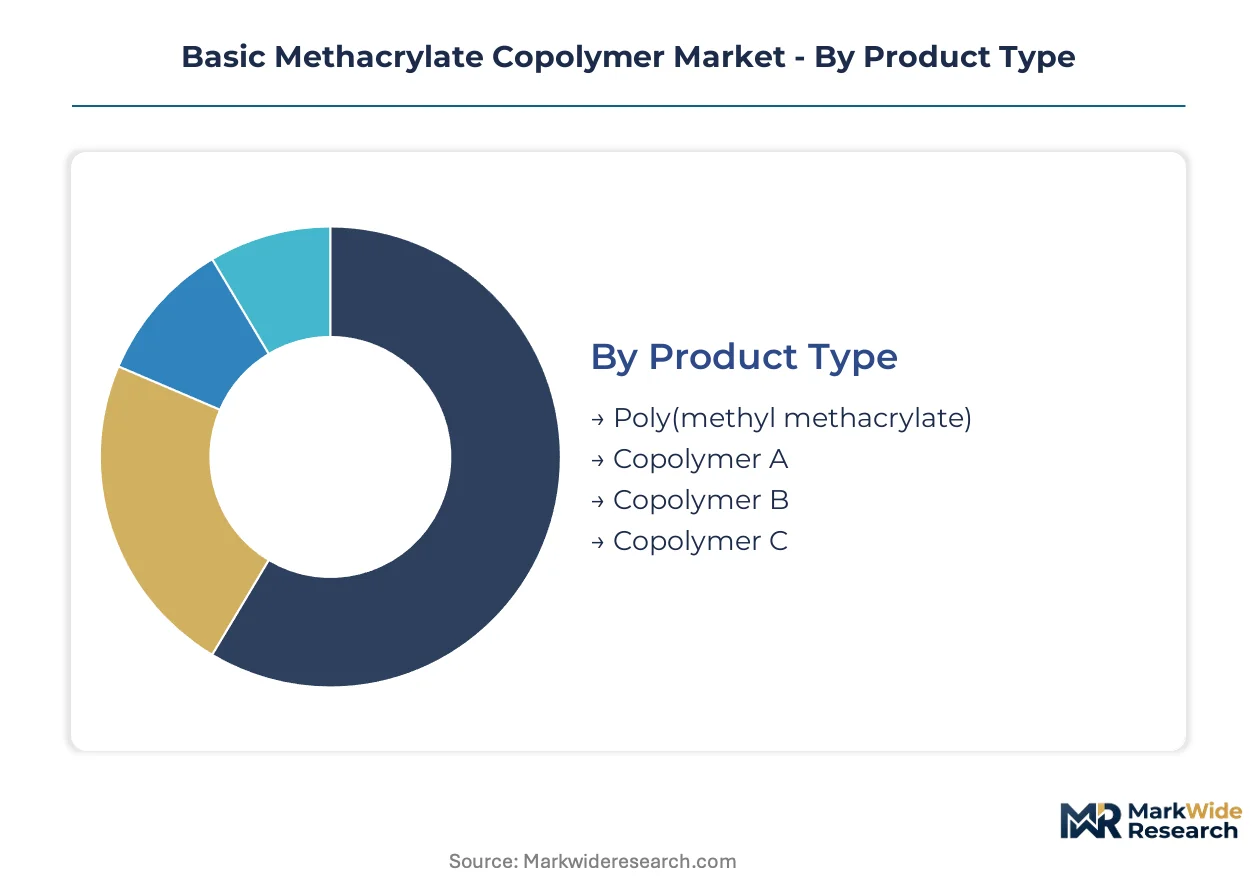
Segmentation in basic methacrylate copolymers reveals how margin capture diverges between commodity resin grades and qualification-intensive pharmaceutical lines. Manufacturers optimize production assets differently depending on whether they serve industrial coating formulators or FDA-audited drug sponsors.
Product Type:
Margin pools concentrate in copolymer variants with documented pharmaceutical master files, while commodity PMMA competes on scale economies.
- Copolymer A:Methyl methacrylate copolymerized with butyl methacrylate yields glass transition temperatures of 60-80°C optimized for moisture-protective tablet coatings. German pharmaceutical formulators in the Rhine-Main cluster consume the majority of qualified production for gastric-resistant film applications. EMA impurity thresholds and FDA Type IV DMF requirements protect incumbent suppliers from price-based competition.
- Poly(methyl methacrylate):Homopolymer grades with molecular weights of 300,000-1,000,000 g/mol dominate dental and orthopedic cement formulations where decades of clinical validation create switching costs. Swiss orthopedic device manufacturers and German dental suppliers anchor demand for medical-grade PMMA with residual monomer specifications below 0.1%.
- Copolymer B:Dimethylaminoethyl methacrylate-functionalized variants provide cationic charge density for controlled-release matrices in narrow-therapeutic-index compounds.
- Copolymer C:Specialty grades with tunable degradation profiles serve implantable drug-eluting stent platforms requiring biocompatibility certification under EU MDR.
Copolymer A holds installed capacity. Copolymer C is rotating up the share rankings.
Application:
Application-driven segmentation shows pharmaceutical coatings commanding price premiums over industrial adhesives by a factor of three to five.
- Coatings:Enteric and moisture-protective film formulations for oral solid dosage forms require aqueous dispersion grades with particle sizes of 10-50 microns. Hyderabad and Ahmedabad formulation outsourcing hubs in India are expanding procurement of EUDRAGIT-equivalent copolymers as CDSCO guidelines align with IPEC standards.
- Medical Devices:Drug-eluting stent coatings, orthopedic cement fixatives, and implantable matrices demand biocompatibility testing under ISO 10993 protocols. German medical device clusters around Tuttlingen and Swiss orthopedic manufacturers near Winterthur concentrate qualified supply relationships.
- Adhesives:Industrial bonding applications for automotive assembly and electronics manufacturing utilize solvent-borne copolymer solutions.
- Sealants:Construction-grade formulations emphasize UV stability and weathering resistance for exterior glazing applications.
Coatings dominate current revenue. Medical devices are climbing the fastest.
End User:
End-user segmentation tracks how regulatory intensity varies across automotive specification systems versus healthcare qualification protocols.
- Healthcare:Pharmaceutical manufacturers and medical device sponsors impose molecular weight distribution specifications, residual monomer limits, and batch documentation requirements that exclude non-integrated compounders. German generics houses and Swiss innovator firms embed polymer scientists in supplier audits for institutional tender markets.
- Automotive:OEM coating specifications for interior trim and exterior lighting assemblies emphasize scratch resistance and UV stability rather than biocompatibility certification.
- Construction:Sealant and glazing applications prioritize weathering performance and cost efficiency over pharmaceutical-grade purity.
- Electronics:Display and optical component manufacturers demand optical clarity and dimensional stability in thin-film coatings.
Healthcare commands premium pricing. Electronics is gaining volume share through display coating applications.
Distribution Channel:
Channel segmentation reflects the technical service intensity required for pharmaceutical qualification versus the transactional nature of industrial resin supply.
- Direct Sales:Integrated producers including BASF SE and Evonik Industries deploy technical service teams to support DMF compilation, regulatory correspondence, and batch documentation for pharmaceutical sponsors. Long-term supply agreements now specify molecular weight distribution parameters rather than broad pharmacopeial compliance.
- Wholesale:Industrial coating and adhesive formulators procure standard grades through regional distributors with inventory positioning near German chemical clusters.
- Online Retail:Small-volume research quantities and 3D printing filaments for personalized dosing applications move through specialized polymer suppliers.
- Others:Contract manufacturing organizations and toll compounders facilitate custom copolymer synthesis for niche applications.
Direct sales maintains relationship density. Wholesale is expanding through just-in-time inventory programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows reveal Germany and Switzerland as net exporters of pharmaceutical-grade copolymers, while India and China remain import-dependent for qualified excipient grades. The Rhine-Main and Basel clusters ship aqueous dispersions to formulation hubs in Hyderabad and Shanghai under long-term supply agreements.
Germany
Rhine-Main pharmaceutical formulators and Tuttlingen medical device manufacturers anchor European demand for EUDRAGIT-equivalent copolymers. REACH registration completions for methacrylate copolymers reduce regulatory friction for domestic compounders. The Ludwigshafen chemical corridor hosts integrated producers with captive monomer supply and dedicated pharmaceutical production lines.
United States
Generic drug sponsors in New Jersey and North Carolina drive procurement of Type IV DMF-qualified copolymers for controlled-release formulations. FDA quality-by-design protocols and Inactive Ingredient Database standards tighten material traceability requirements for excipient suppliers. The Boston-Cambridge biotech corridor expands demand for biocompatible grades in implantable drug-eluting platforms.
India
Hyderabad and Ahmedabad formulation outsourcing hubs scale procurement as CDSCO excipient guidelines align with IPEC standards. The country's national pharmaceutical regulator accelerates qualification timelines for pre-audited international suppliers. Gujarat's specialty chemical parks attract toll compounders serving domestic generic houses with imported methacrylate dispersions.
Switzerland
Winterthur orthopedic manufacturers and Basel pharmaceutical innovators concentrate demand for medical-grade PMMA with residual monomer specifications below 0.1%. Swissmedic biocompatibility protocols and EU MDR traceability mandates reward suppliers with documented batch histories. The Basel-Lörrach chemical corridor maintains qualified supply relationships for implantable polymer grades.
China
Shanghai and Jiangsu formulation facilities import pharmaceutical-grade copolymers pending domestic DMF-equivalent qualification pathways. NMPA excipient master file requirements evolve toward IPEC alignment, creating openings for pre-qualified international suppliers. The Yangtze River Delta pharmaceutical cluster trials methacrylate-based 3D printing filaments for personalized dosing applications.
Basic Methacrylate Copolymer Market Vendor Landscape
Concentration sits with integrated chemical conglomerates possessing captive methacrylate monomer supply and pharmaceutical-grade production assets. Three archetypes define competitive positioning: backward-integrated resin producers with documented batch histories, formulation-focused compounders serving industrial coatings, and specialized medical polymer suppliers with ISO 10993 biocompatibility certification. Dominant competitive moves include long-term supply agreements specifying molecular weight distribution parameters and reactive extrusion technology licensing to CDMOs.
Among Germany-based integrated producers, BASF SE and Evonik Industries exemplify the backward-integrated archetype with pharmaceutical-grade production lines. Arkema Group occupies a position bridging industrial coating formulations and specialized medical applications. These three anchors represent distinct strategic postures: monomer-captive scale, medical device specialization, and downstream coating control.
| Leading Market Players |
|---|
| Croda Inc. |
| Corel Pharma Chem. |
| The Dow Chemical Company |
| Arkema Group |
| Akzo Nobel N.V. |
| BASF SE |
| Sigma-Aldrich Co. LLC |
| Vikram Thermo |
| Evonik Industries |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at captive methacrylate monomer facilities in Germany's Ludwigshafen corridor shapes both supply concentration and price floors for pharmaceutical-grade copolymers. Integrated producers leverage backward control over acetone cyanohydrin feedstock to sustain margin buffers that formulation-only compounders cannot match, while EMA impurity thresholds and FDA Type IV DMF requirements erect qualification barriers that protect incumbent pricing power.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the basic methacrylate copolymer market. Price differentiation hinges on FDA Type IV DMF certification status and molecular weight distribution documentation precision, with pharmaceutical sponsors paying substantial premiums for qualified batches versus industrial coating formulators. Cost compression in commodity PMMA grades is intensifying because cellulosic substitutes erode share in cost-sensitive generic tablet applications. Industrial adhesive buyers exhibit highest price sensitivity, while implantable medical device sponsors prioritize batch documentation over unit cost.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp trade lanes elevates inbound logistics costs for methacrylate monomer feedstock moving into German production clusters. Supply concentrates in Germany, Switzerland, and the United States for pharmaceutical-grade copolymers, with raw material dependencies on acetone, hydrogen cyanide, and specialized methacrylate monomers. Single-source vulnerability concentrates around qualified aqueous dispersion production in the Rhine-Main corridor. Distribution runs through direct technical-service relationships for pharmaceutical sponsors and regional wholesale networks for industrial formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The basic methacrylate copolymer market is entering a cyclical recovery phase as pharmaceutical outsourcing normalizes post-pandemic and implantable device volumes rebound. Methyl methacrylate feedstock cost normalization is restoring margin headroom for integrated producers with captive supply.
For Market Incumbents: Consolidate position by securing long-term offtake agreements with Hyderabad and Ahmedabad formulation hubs before CDSCO qualification pathways mature for domestic competitors. Prioritize reactive extrusion technology licensing to CDMOs serving North American generic sponsors, as continuous processing adoption accelerates and threatens batch-compounder margins. Backward integration into pharmaceutical-grade aqueous dispersion capacity protects against formulation-only entrants gaining DMF status. For New Entrants and Emerging Players: Differentiate on EU MDR traceability compliance by deploying blockchain-enabled batch documentation systems for implantable polymer grades. Target the Indian pharmaceutical manufacturing white space where CDSCO-IPEC alignment creates qualification openings for pre-audited international suppliers. Pursue toll-compounding partnerships with Gujarat specialty chemical parks to establish domestic presence without full production asset commitment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated producers with documented pharmaceutical master files and long-term supply agreements specifying molecular weight distribution parameters. Five-to-ten year viability favors backward-integrated specialists with captive monomer supply and dedicated pharmaceutical production lines. Monitor EMA polymer impurity threshold revisions as the signal indicating reformulation investment cycles and qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Reactive Extrusion Technology Licensing | CDMOs serving FDA-audited sponsors adopt continuous processing to compress batch variability and solvent recovery burdens. |
| Blockchain-Enabled Batch Documentation | EU MDR traceability mandates reward suppliers with immutable polymer provenance records for implantable grades. |
| Long-Term Supply Agreement Restructuring | Procurement teams at German generics houses now embed molecular weight distribution specifications rather than broad pharmacopeial compliance. |
| Indian Market Qualification Investment | CDSCO excipient guideline alignment with IPEC standards accelerates penetration timelines for pre-audited international suppliers. |
| Biocompatibility Certification Expansion | ISO 10993 protocol documentation opens implantable drug-eluting stent and orthopedic coating applications for qualified copolymer grades. |
Methodological Framework
Desk research of EMA excipient guidelines, FDA Inactive Ingredient Database standards, and REACH polymer registration records preceded structured interviews with pharmaceutical procurement managers, CDMO technical directors, and medical device regulatory affairs leads. Primary fieldwork captured qualification timeline dynamics, batch documentation requirements, and supplier audit protocols across German, Swiss, and Indian formulation clusters. Secondary validation drew from customs trade data, SEC filings of integrated chemical producers, and IPEC excipient certification databases. Bottom-up copolymer grade volume estimates and top-down pharmaceutical excipient market sizing were triangulated to reconcile segmentation outputs.
Analytical variance decomposes across product type, application intensity, and regional regulatory cluster to isolate growth contribution by segment. Modeled dimensions span copolymer variant classification, end-use industry qualification tier, and distribution channel technical service intensity. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements by integrated producers. Key forecast inputs include methyl methacrylate feedstock cost trajectories and EMA impurity threshold evolution timelines.
Decision-makers should treat outputs as directional under assumptions of sustained pharmaceutical outsourcing growth and stable REACH registration status; material deviation in monomer feedstock volatility or regulatory divergence would warrant model refresh. Practitioners should keep alternative scenarios live as CDSCO qualification pathway maturity and 3D-printed personalized dosing adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Asia-Pacific Opaque Polymers Market
Polymers & Resins
Ethylene Copolymer Market
Polymers & Resins
Global Impregnating Resins Market
Polymers & Resins
Global Emulsion Polymer Market
Polymers & Resins
Global Bio Based Polyurethane Market
Polymers & Resins
Middle East Polyethylene Terephthalate (PET) Market
Polymers & Resins
Cathodic Acrylic Market
Polymers & Resins
Europe Geopolymer Market
Polymers & Resins
Global Specialty Polystyrene Resin Market
Polymers & Resins
Poly(P-Phenylene Ether) (PPE) Market
Polymers & Resins
Thermoplastic Polyester Engineering Resin (TPER) Market
Polymers & Resins
Global Polymer Chameleons Market
Polymers & Resins
Global Polyether Ether Ketone (PEEK) Market
Polymers & Resins
Phenoxy Resins Market
Polymers & Resins
Emulsion PVC Market
Polymers & Resins
Linear Low Density Polyethylene Lldpe Market