
 Bio-Based PU Market | 2026-2036
Bio-Based PU Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based PU Market Analytics
High-performance grade specifications are redrawing competitive boundaries in bio-based polyurethane supply. Covestro AG leverages its European pilot facilities to validate renewable feedstock consistency at industrial scale. BASF SE anchors global biopolyol distribution through backward integration into vegetable oil refining partnerships. Wanhua Chemical Group Co., Ltd. dominates Asia-Pacific volume by operating dedicated bio-PU reactor trains at its Ningbo complex.
Bio-based polyurethane denotes polymers synthesized from renewable polyols—typically derived from castor oil, soybean oil, or sugarcane—reacted with diisocyanates to yield elastomers, foams, or coatings with tunable hardness from Shore A 20 to D 80. These materials serve industries seeking petrochemical displacement without sacrificing compression set resistance or tensile strength. Flexible foam formulations command the widest end-use footprint, though coatings applications are pulling ahead on margin contribution as automotive OEMs specify low-VOC interior finishes. Rigid foam insulation segments compete on thermal conductivity metrics against conventional PU, with construction codes in several jurisdictions now mandating embodied carbon disclosure that favors bio-origin feedstocks.
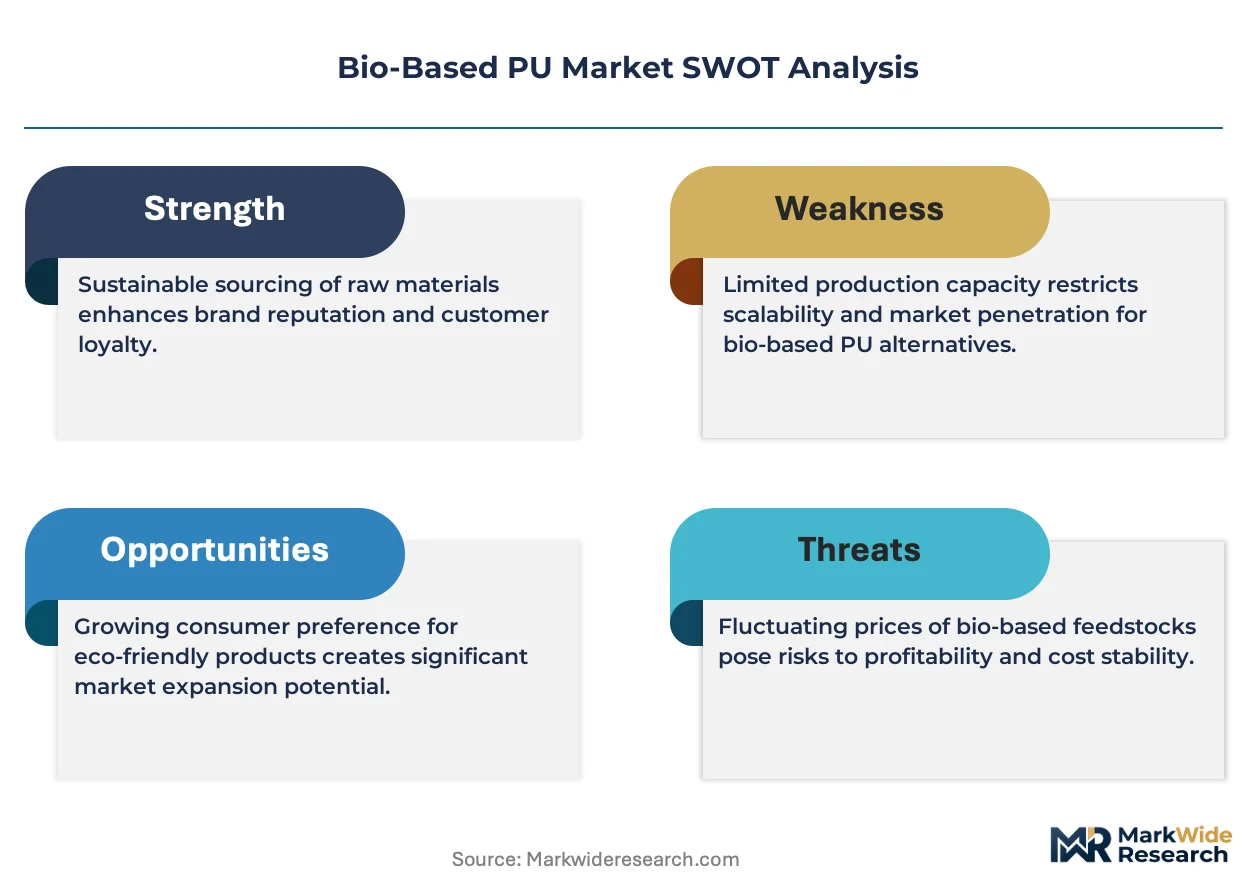
EPA bio-preferred procurement guidelines and REACH substance restrictions are tightening the aperture for petroleum-derived polyurethane entrants, while China's MEE dual carbon enforcement is accelerating domestic biopolyol capacity additions. ECHA authorization requirements for aromatic isocyanates are forcing reformulation timelines across European adhesive suppliers. Stakeholders must monitor feedstock crop yield volatility and isocyanate price spreads to calibrate bio-content claims against actual cost position.
Market Dynamics
REACH restrictions on petrochemical isocyanates are redirecting formulation investments toward bio-alternatives, compressing reformulation timelines and reshaping supplier qualification protocols across European adhesive and coating supply chains.
Growth Catalysts
- Castor-oil polyol procurement:Automotive seating programs in Germany and Japan are expanding specification of castor-oil-derived polyols for interior components, validating renewable feedstock performance at production scale.
- MEE dual carbon enforcement:China's Ministry of Ecology and Environment is accelerating domestic biopolyol capacity additions through emissions intensity benchmarks that favor bio-origin feedstocks over conventional petrochemical routes.
- Construction embodied carbon codes:Jurisdictions mandating embodied carbon disclosure in building materials are creating specification pull for rigid foam insulation with verified bio-content credentials.
Market Restraints
- Feedstock crop yield volatility:Castor bean harvest fluctuations in India and Brazil introduce polyol price instability that petrochemical alternatives do not face.
- Isocyanate supply concentration:Aromatic diisocyanate production concentrates in coastal China and the US Gulf Coast, exposing bio-PU formulators to geographic supply risk regardless of polyol origin.
- Technical performance gaps:Bio-based rigid foams still trail conventional PU on thermal conductivity metrics in sub-zero applications, limiting specification in cold-chain infrastructure.
Strategic Opportunities
- Underpenetrated footwear midsole segment:Running shoe brands in Vietnam and Indonesia are piloting bio-PU elastomers for energy-return midsoles, opening volume potential beyond established automotive and furniture markets.
- EPA bio-preferred procurement:Federal purchasing guidelines in the United States are creating mandated demand pools for bio-based coating systems in military and civilian fleet maintenance facilities.
- Digital formulation platforms:AI-assisted polyol blending is converging with rapid prototyping methods, compressing development cycles for custom bio-PU grades tailored to regional feedstock availability.
Industry Challenges
- Biopolyol certification timelines:ASTM D6866 and ISO 16620 testing protocols require 4-6 week turnaround, delaying customer qualification and contract execution.
- Reactor retrofit capex:Converting conventional PU trains to handle higher-moisture bio-polyols demands stainless steel vessel upgrades and nitrogen blanketing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based PU Market |
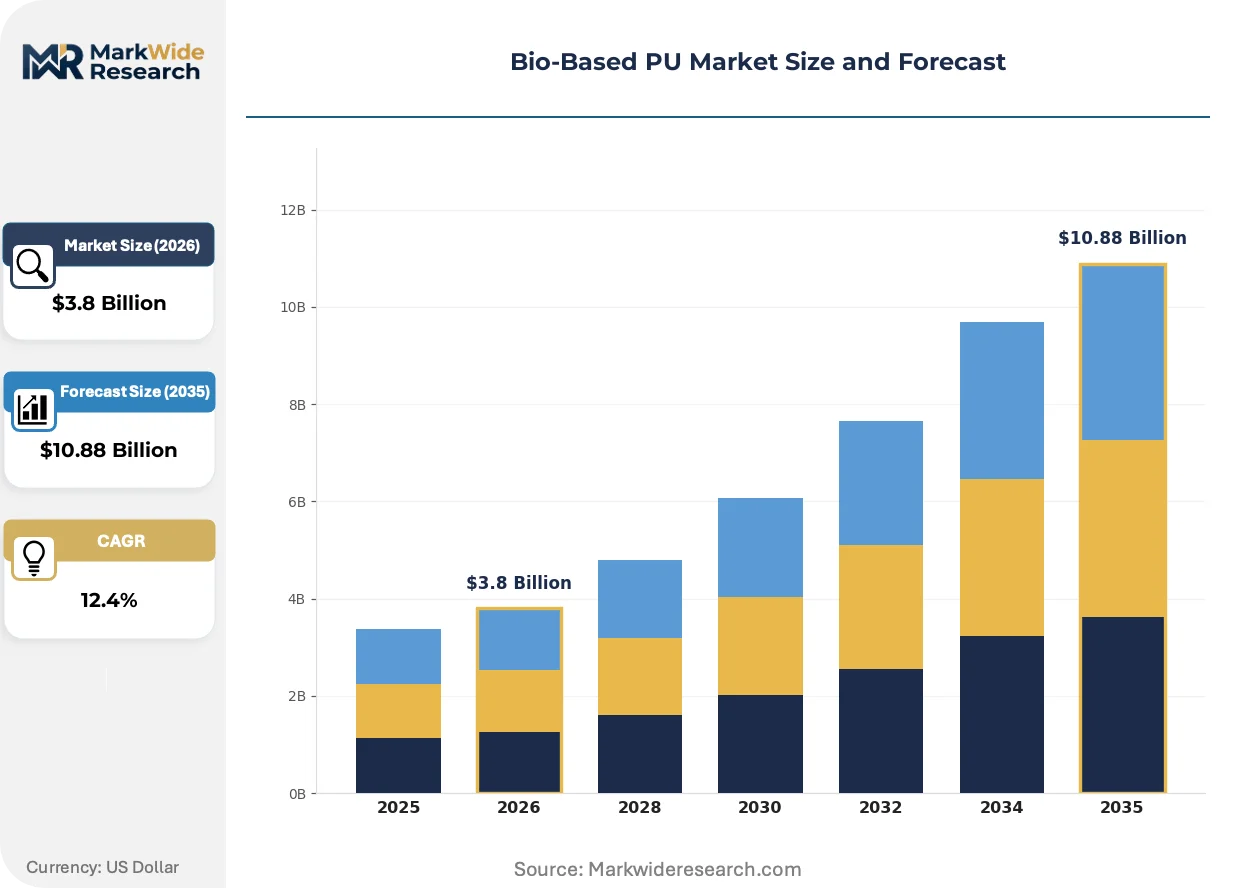
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.88 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Foam, Rigid Foam, Coatings, Adhesives End User: Construction, Automotive, Furniture, Footwear Application: Insulation, Upholstery, Sealants, Flooring Form: Liquid, Solid, Composite, Powder |
| Companies Covered | BASF SE, Covestro AG, Huntsman International LLC, The Dow Chemical Company, The Lubrizol Corporation, Mitsui Chemicals Inc., Wanhua Chemical Group Co., Ltd., Cargill, Incorporated, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based PU Market Evolving Landscape
Formulation science is compressing the performance gap between renewable and petrochemical polyurethanes through molecular architecture advances and process intensification methods.
Enzymatic polyol refinement is miniaturizing. This biotechnology strips free fatty acids from vegetable oil feedstocks with precision that thermal methods cannot match. Tier-1 automotive suppliers in Stuttgart and Toyota City are qualifying enzymatically refined grades for instrument panel skins. The technology is miniaturizing capital requirements for polyol production, enabling distributed refining facilities closer to castor and soybean growing regions.
REACH authorization requirements for aromatic isocyanates are forcing reformulation across European adhesive suppliers. ECHA's sunset date enforcement compresses transition timelines to 18-24 months for affected substances. Coatings formulators serving German automotive OEMs are accelerating aliphatic isocyanate trials and bio-polyol pairings to maintain supply continuity.
Specification-driven procurement is consolidating buying power among automotive OEMs and major furniture retailers. Long-term offtake agreements with volume commitments are displacing spot-market polyol purchases for tier-2 foam molders. This concentration is most visible in China's Yangtze River Delta, where integrated chemical parks enable direct supplier-mill relationships that bypass traditional distribution layers.
Bio-Based PU Market Segmentation
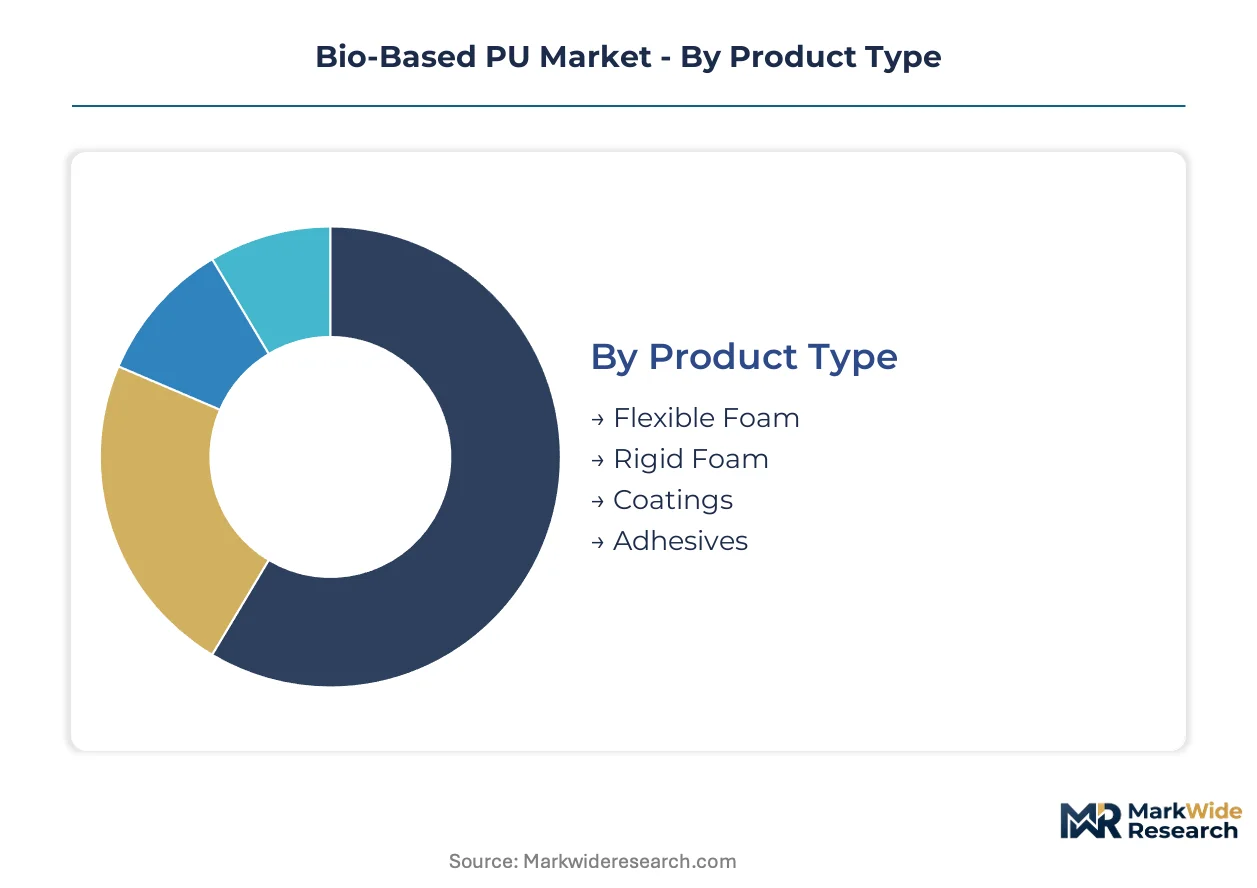
Bio-based polyurethane demand fragments across formulation chemistry, end-use durability requirements, and regional feedstock access. Segmentation reveals where castor-oil polyol specifications command premium positioning versus commodity substitution plays.
Product Type:
Flexible foam formulations dominate domestic consumption in furniture and automotive clusters, while rigid foam and coatings serve export-led construction and industrial markets.
- Flexible Foam:Open-cell structures derived from soybean and castor oil polyols deliver compression set resistance for seating and bedding applications. German automotive seating programs and Japanese OEM qualification protocols are validating renewable feedstock consistency at production scale.
- Rigid Foam:Closed-cell insulation boards compete on thermal conductivity metrics against conventional PU in building envelopes. China's Yangtze River Delta manufacturing cluster concentrates biopolyol production for rigid foam serving Southeast Asian construction exports.
- Coatings:Low-VOC interior finishes for automotive OEMs leverage aliphatic isocyanate pairings with bio-polyols.
- Adhesives:Structural bonding formulations face REACH authorization pressures on aromatic isocyanates across European supply chains.
Flexible foam commands the established base. The steepest expansion runs through coatings as automotive interior specifications tighten VOC thresholds.
End User:
Cost tier stratification separates specification-driven automotive and construction buyers from price-sensitive furniture and footwear procurement.
- Construction:Rigid foam insulation for commercial and residential building envelopes faces embodied carbon disclosure mandates in multiple jurisdictions. Jurisdictions mandating embodied carbon disclosure in building materials are pulling specification toward verified bio-content credentials.
- Automotive:Interior components including instrument panel skins and seating foams require Shore A 20-80 hardness tunability with renewable feedstock traceability.
- Furniture:Mattress and upholstery foam molders in China's integrated chemical parks source biopolyols through direct supplier-mill relationships.
- Footwear:Running shoe brands in Vietnam and Indonesia are piloting bio-PU elastomers for energy-return midsoles beyond established markets.
Construction absorbs volume at standard margins. Automotive and footwear segments are climbing the fastest on specification premiums.
Application:
Volume concentration in insulation and upholstery contrasts with emerging specification pull in sealants and specialty flooring systems.
- Insulation:Thermal barrier applications in cold-chain infrastructure and building envelopes. Bio-based rigid foams still trail conventional PU on thermal conductivity metrics in sub-zero applications, limiting specification scope.
- Upholstery:Soft-touch surfaces for furniture and automotive seating leverage castor-oil polyol hydrolytic stability.
- Sealants:Expansion joint and waterproofing formulations face ECHA sunset date enforcement on aromatic isocyanates.
- Flooring:Resilient surface coatings and underlayment foams for commercial installation.
Upholstery anchors current demand. Sealants are gaining share fastest as reformulation timelines compress across European adhesive suppliers.
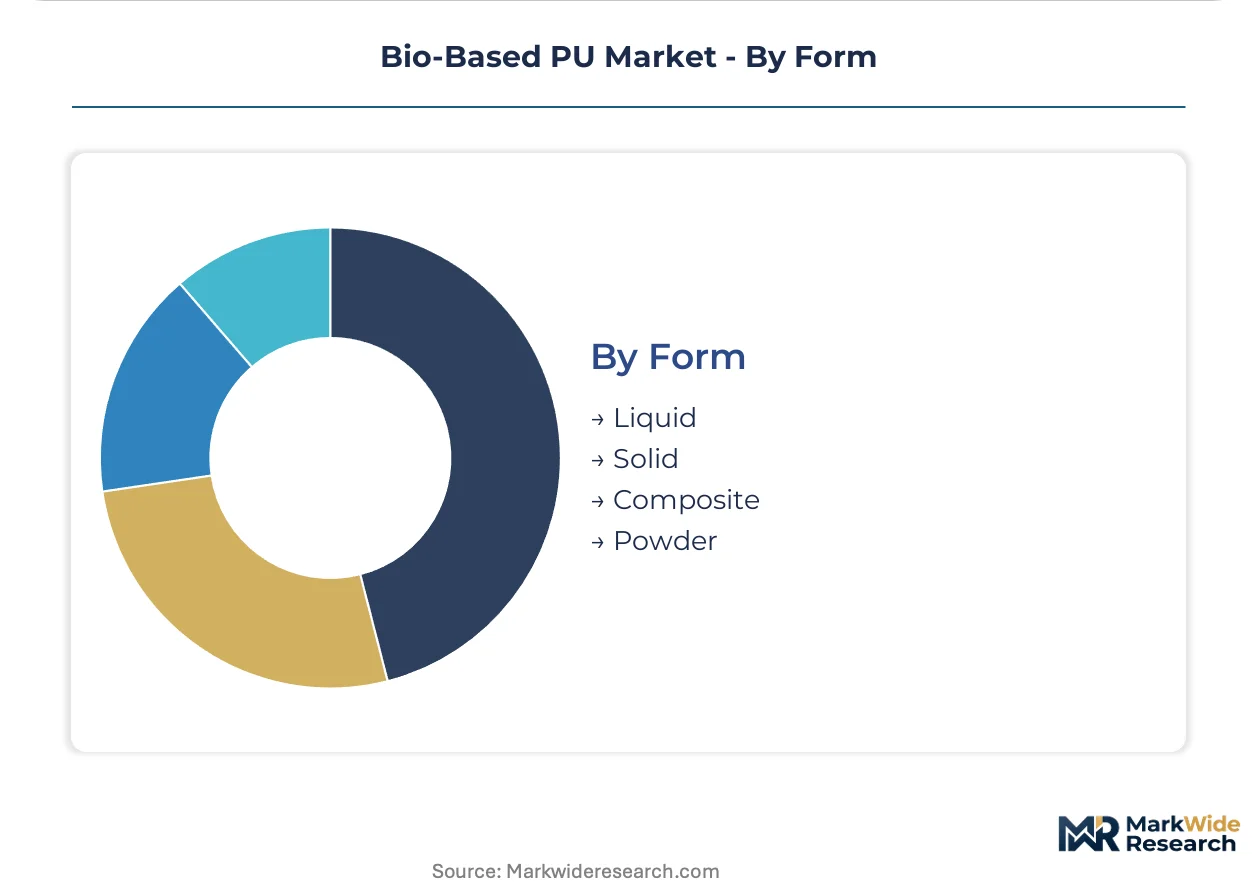
Form:
Supply chain configuration favors liquid systems for integrated chemical park production, while solid and powder forms serve distributed compounding and specialty manufacturing.
- Liquid:Pumpable two-component systems for continuous foam molding and spray application. Ningbo complex operations and Yangtze River Delta facilities run dedicated bio-PU reactor trains on liquid feedstocks.
- Solid:Prepolymer pellets and cast elastomer blocks for machining and compression molding.
- Composite:Fiber-reinforced panels and sandwich structures for transportation and construction.
- Powder:Thermoplastic polyurethane granules for rotational molding and powder coating.
Liquid systems dominate throughput economics. Powder forms are expanding most quickly in specialty coating applications requiring solvent-free processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive seating programs export castor-oil-derived polyol specifications to Japanese OEMs, establishing a trans-Eurasian trade corridor for bio-PU feedstock validation.
China
MEE dual carbon enforcement drives biopolyol capacity additions through emissions intensity benchmarks favoring bio-origin feedstocks. Wanhua Chemical Group Co., Ltd. operates dedicated bio-PU reactor trains at its Ningbo complex. The Yangtze River Delta manufacturing cluster concentrates integrated chemical parks enabling direct supplier-mill relationships.
Germany
Automotive OEMs in Stuttgart specify castor-oil polyols for instrument panel skins and seating components. ECHA REACH authorization requirements for aromatic isocyanates compress reformulation timelines to 18-24 months. Coatings formulators serving Bavarian automotive clusters accelerate aliphatic isocyanate trials with bio-polyol pairings.
United States
EPA bio-preferred procurement guidelines create mandated demand pools for bio-based coating systems in military and civilian fleet maintenance. Federal purchasing standards displace spot-market polyol procurement for tier-2 suppliers. Texas and Louisiana host aromatic diisocyanate production exposing bio-PU formulators to geographic supply risk.
Japan
Toyota City and Nagoya automotive clusters validate renewable feedstock performance at production scale for interior components. METI industrial standards support bio-based material qualification protocols. Kanto region chemical processors import German castor-oil polyol specifications for domestic foam molding operations.
India
Castor bean cultivation in Gujarat and Rajasthan supplies raw material for polyol refinement targeting European automotive buyers. BIS certification requirements align with ASTM D6866 testing protocols for bio-content verification. Mumbai-Pune industrial corridor hosts enzymatic polyol refinement pilots reducing capital requirements for distributed production.
Bio-Based PU Market Competitive Landscape
Listed leaders compete with private specialists across feedstock integration depth and regional market access. European chemical conglomerates anchor premium-tier positioning through backward integration into vegetable oil refining partnerships. Asian volume producers dominate cost-competitive segments via dedicated reactor trains at integrated chemical parks. Two dominant competitive moves define current positioning: capacity expansion in China's Yangtze River Delta manufacturing cluster and strategic partnerships linking castor-growing regions to automotive qualification hubs.
Within the listed-chemical-conglomerate tier, BASF SE anchors global biopolyol distribution networks through European pilot facilities validating renewable feedstock consistency. Covestro AG occupies a position exemplifying premium-grade specification leadership for automotive interior applications. Wanhua Chemical Group Co., Ltd. represents the scale-driven archetype with dedicated bio-PU reactor infrastructure at its Ningbo complex. These three entities collectively illustrate the geographic and strategic segmentation binding feedstock access to end-use qualification protocols.
| Leading Market Players |
|---|
| BASF SE |
| Covestro AG |
| Huntsman International LLC |
| The Dow Chemical Company |
| The Lubrizol Corporation |
| Mitsui Chemicals Inc. |
| Wanhua Chemical Group Co., Ltd. |
| Cargill, Incorporated |
| Arkema |
| Others |
Value Network & Pricing Analysis
Dedicated bio-PU reactor trains at China's Ningbo complex and Yangtze River Delta integrated chemical parks compress unit economics through captive polyol supply and nitrogen-blanketed processing infrastructure. Scale concentration in these facilities anchors price floors for enzymatically refined grades while exposing smaller formulators to margin compression from feedstock crop yield volatility and stainless steel retrofit capex.
Pricing Analysis
Next-generation enzymatically refined polyols command 15-25% premiums over thermal-processed equivalents, while first-generation soybean-oil formulations face commodity substitution pressure from petrochemical alternatives. Pricing stratifies across premium, standard, and economy tiers based on ASTM D6866 certification tier and castor-oil content percentage. Cost compression in standard-grade flexible foam is intensifying because REACH authorization timelines compress reformulation windows. Furniture molders in China's integrated chemical parks exhibit highest price sensitivity; German automotive OEMs show lowest sensitivity due to renewable feedstock traceability mandates.
Supply Chain Analysis
Strategic stockpile preferences dominate castor-oil procurement given monsoon-dependent harvest cycles in Gujarat and Rajasthan, while just-in-time norms govern aromatic diisocyanate flows from coastal China and the US Gulf Coast. Supply draws from India for castor beans, China for MDI/TDI isocyanates, and Germany for enzymatic refinement catalysts. Single-source vulnerability concentrates in aromatic diisocyanate production regardless of polyol origin. Distribution runs through direct supplier-mill relationships in Yangtze River Delta chemical parks, bypassing traditional distribution layers for volume automotive and construction buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bio-based polyurethane sits at a high-growth inflection as ECHA REACH authorization deadlines force 18-24 month reformulation cycles across European adhesive supply chains. The regulatory compression creates structural advantage for players with validated renewable feedstock pipelines and certification-ready product portfolios.
For Market Incumbents: Consolidate backward integration into vegetable oil refining partnerships to secure castor-oil supply continuity against Indian harvest volatility. Expand dedicated bio-PU reactor capacity in Yangtze River Delta chemical parks to capture MEE dual carbon enforcement-driven demand. Certification investment in ASTM D6866 and ISO 16620 protocols defends position against emerging enzymatic refinement specialists threatening premium-tier margins.
For New Entrants and Emerging Players: Anchor in Vietnam and Indonesia footwear midsole segments where running shoe brands pilot bio-PU elastomers without entrenched supplier relationships. Target EPA bio-preferred procurement pools for military and civilian fleet maintenance coatings, where mandated demand creates volume certainty absent in spot furniture markets. Go-to-market through digital formulation platforms offering AI-assisted polyol blending for regional feedstock adaptation.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enzymatic refinement technology licensors with automotive qualification protocols already validated. Long-term viability over the projection horizon hinges on feedstock crop yield hedging capabilities and isocyanate supply diversification. Acquisition target archetype: mid-cap enzymatic polyol specialists with Stuttgart or Toyota City automotive approvals. Signal to watch: compression in 4-6 week ASTM D6866 testing turnaround times indicating certification infrastructure scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Castor Oil Refining | Captures margin from Gujarat cultivation through European automotive qualification pipelines. |
| Enzymatic Refinement Capacity Expansion | Miniaturizes capital requirements for distributed production near soybean and castor growing regions. |
| Long-term Supply Agreement with Automotive OEMs | Displaces spot-market polyol purchases as German and Japanese seating programs consolidate procurement. |
| Joint Venture in Yangtze River Delta Chemical Park | Accesses MEE dual carbon enforcement benefits through integrated supplier-mill relationships. |
| Green Manufacturing Transition Certification | Aligns with REACH authorization timelines and EPA bio-preferred procurement mandates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs/trade data, ACC/Cefic chemical industry reports, SEC 10-K filings, and ECHA substance authorization databases. Primary interviews engaged plant managers at biopolyol production facilities, procurement leads at German and Japanese automotive OEMs, distribution channel partners in Yangtze River Delta chemical parks, and technical R&D directors specializing in enzymatic refinement. Bottom-up triangulation against top-down macroeconomic indicators validates volume and value estimates across the analysis window.
Segmentation dimensions modeled include product type (flexible foam, rigid foam, coatings, adhesives), end-use industry (automotive, construction, furniture, footwear), form (liquid, solid, powder, composite), and regional production hub concentration. CAGRs derive from elasticity-adjusted demand curves incorporating feedstock crop yield volatility and isocyanate price spread dynamics. Industry-specific forecast inputs encompass REACH authorization sunset dates and MEE dual carbon enforcement intensity benchmarks.
Decision-makers should treat outputs as directional under assumptions of sustained ECHA enforcement timelines and stable castor bean cultivation economics in India; material deviation in regulatory stringency or harvest yields would warrant model refresh. Practitioners should keep alternative scenarios live as EPA bio-preferred procurement scope and China MEE emissions intensity benchmarks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polymer Foam Market
Polymers & Resins
United States Polyols Market
Polymers & Resins
Polyimide Resin Market
Polymers & Resins
Global Solid Masterbatches Market
Polymers & Resins
Polyolefin Foam Market
Polymers & Resins
Global Chlorinated Polyethylene Market
Polymers & Resins
Soil Release Polymer Market
Polymers & Resins
Global Polymer Stabilizer Market
Polymers & Resins
Europe Polyamide Market
Polymers & Resins
Caprolactam (Nylon 6 Fiber and Nylon 6 Resin) Market
Polymers & Resins
Global One Component Polyurethane Foam Market
Polymers & Resins
Global Bio Based Polyurethane Market
Polymers & Resins
Fluoropolymers in Healthcare Market
Polymers & Resins
Global Polymer Market
Polymers & Resins
Middle East Polyethylene Market
Polymers & Resins
Global Amorphous Polyalphaolefin (APAO) for Hot Melt Market