
 Global Acrylic Polymer Market | 2026-2036
Global Acrylic Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acrylic Polymer Market Foresight
Southeast Asian petrochemical expansions is recalibrating feedstock availability for acrylic ester producers. BASF leverages integrated acrylic acid complexes across Ludwigshafen and Nanjing to sustain cost-advantaged methyl methacrylate output. Dow Chemical Company anchors North American supply through Freeport, Texas, operations while competing in waterborne architectural coatings. Arkema differentiates via specialty methacrylate derivatives for electronics and medical applications.
Acrylic polymers comprise synthetic resins derived from acrylic acid, methacrylic acid, or their esters, typically polymerized through free-radical emulsion or solution processes to achieve molecular weights between 10,000 and 1,000,000 g/mol, serving primarily as film-forming binders, adhesives, and rheology modifiers. Methyl methacrylate dominates commodity volume due to polymethyl methacrylate sheet and resin demand, while butyl acrylate leads growth in waterborne coatings and pressure-sensitive adhesives driven by solvent-reduction mandates. Emulsion forms command the largest share of coatings applications, whereas powder grades concentrate in construction adhesives and textile finishing where dry-blending efficiency matters.
EPA regulations on volatile organic compound emissions restrict solvent-borne acrylic formulations in US architectural and industrial maintenance coatings, pushing reformulation toward emulsion and latex systems. REACH registration requirements and the EU Green Deal's chemical sustainability criteria are tightening monomer traceability and recyclability standards across European value chains. ECHA evaluations of acrylic acid derivatives influence classification decisions that ripple through global hazard communication protocols. Stakeholders must monitor regulatory divergence between California's CARB standards and emerging GB standards from China's MEE as formulation decisions increasingly lock in regional supply configurations.
Market Dynamics
Waterborne formulation mandates across major industrial economies are compressing solvent-borne acrylic capacity while reallocating capital toward emulsion polymerization infrastructure. This regulatory compression is restructuring supplier economics and regional trade flows.
Growth Catalysts
- REACH compliance deadlines:European Green Deal chemical sustainability criteria are accelerating substitution of solvent-borne systems with low-VOC emulsion grades across architectural coatings value chains.
- Construction adhesives:China's Yangtze River Delta chemical clusters are absorbing expanded methyl methacrylate output for infrastructure bonding applications and prefabricated panel assembly.
- Pressure-sensitive adhesives:Butyl acrylate emulsion demand is concentrating in Gujarat's industrial corridor for tape and label manufacturing serving domestic packaging consumption.
Market Restraints
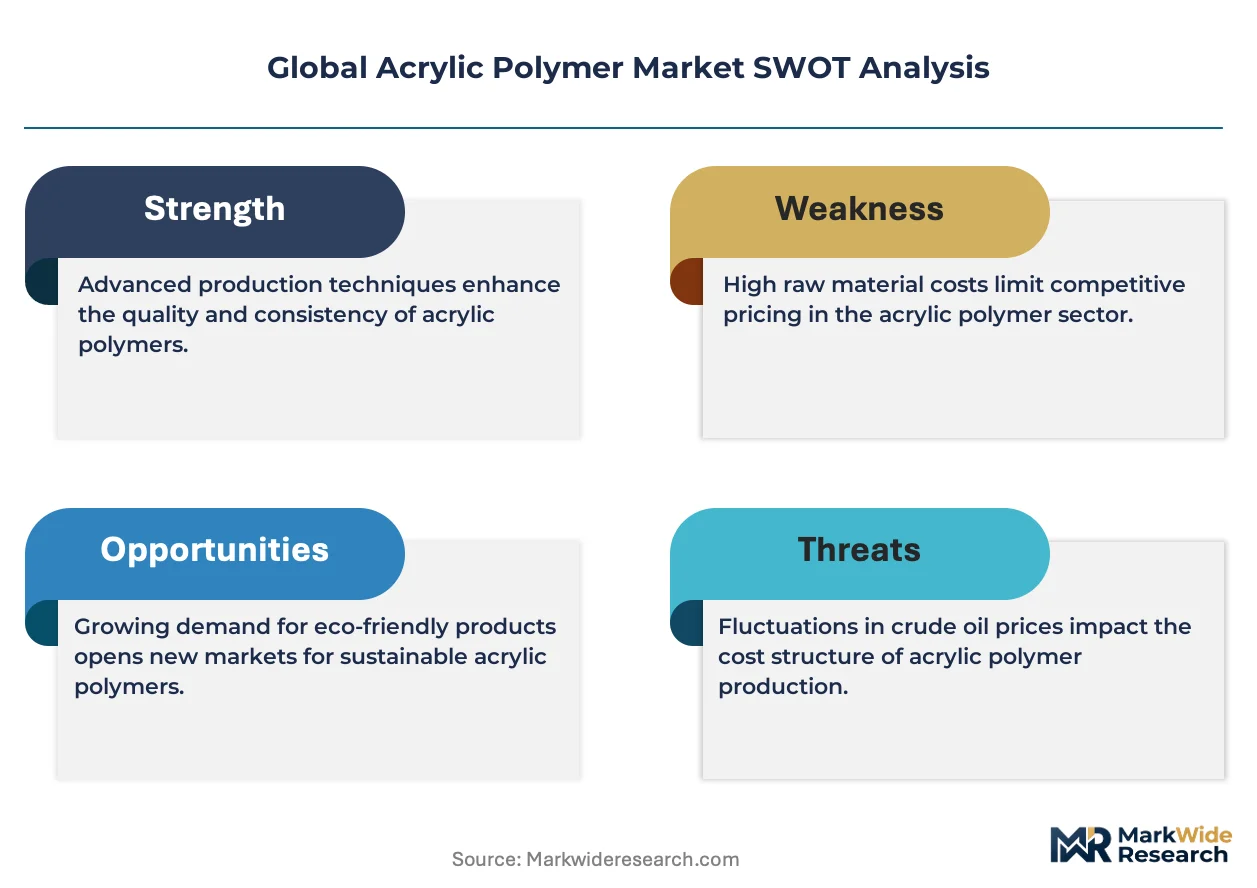
- Propylene feedstock volatility:Acrylic acid production costs track naphtha-cracker propylene yields, exposing margin compression during petrochemical cycle downturns.
- Specialty monomer supply concentration:Hydroxyethyl methacrylate and specialty acrylate esters depend on concentrated European and Japanese merchant suppliers.
- Epoxy and polyurethane substitution:High-performance coatings applications face displacement from hybrid epoxy-acrylic and two-component polyurethane systems in corrosion-protection segments.
Strategic Opportunities
- India's PLI scheme for chemicals:Production-linked incentives for specialty chemicals are attracting acrylic emulsion capacity investments targeting domestic coatings formulation.
- Medical device coatings:Antimicrobial methacrylate surface treatments are penetrating catheter and implantable device manufacturing with FDA 510(k) pathway requirements.
- Digital printing substrates:Ink-receptive acrylic coatings are expanding into packaging and textile printing equipment as water-based ink adoption accelerates.
Industry Challenges
- Emulsion polymerization engineering talent:Free-radical kinetics expertise and reactor scale-up competency scarcity constrains capacity expansion timelines.
- Legacy solvent-borne asset strandedness:EPA NESHAP compliance investments for existing coating lines face uncertain payback against accelerating emulsion substitution.
- Cross-border monomer registration:ECHA REACH data-sharing obligations and Korea REACH equivalency determinations create multi-jurisdiction compliance complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acrylic Polymer Market |
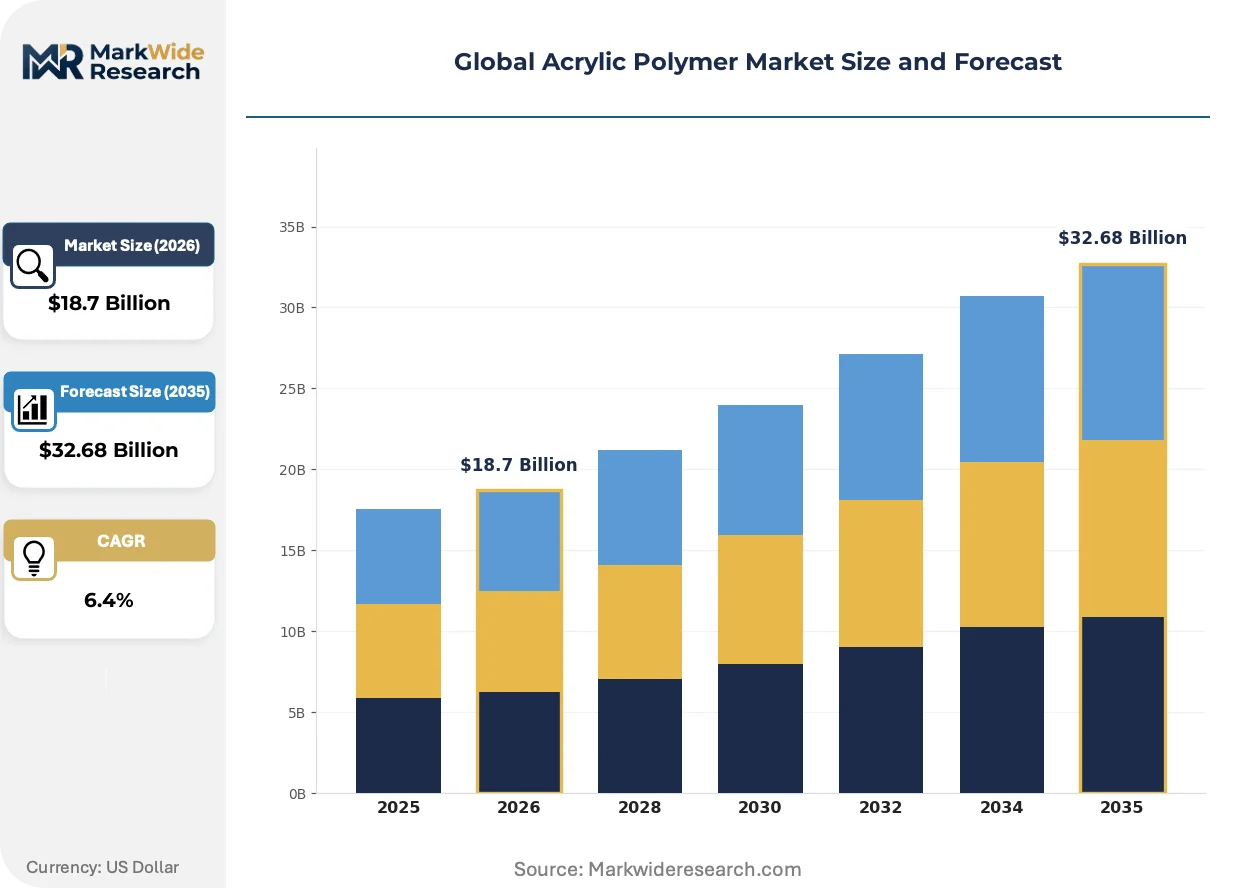
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
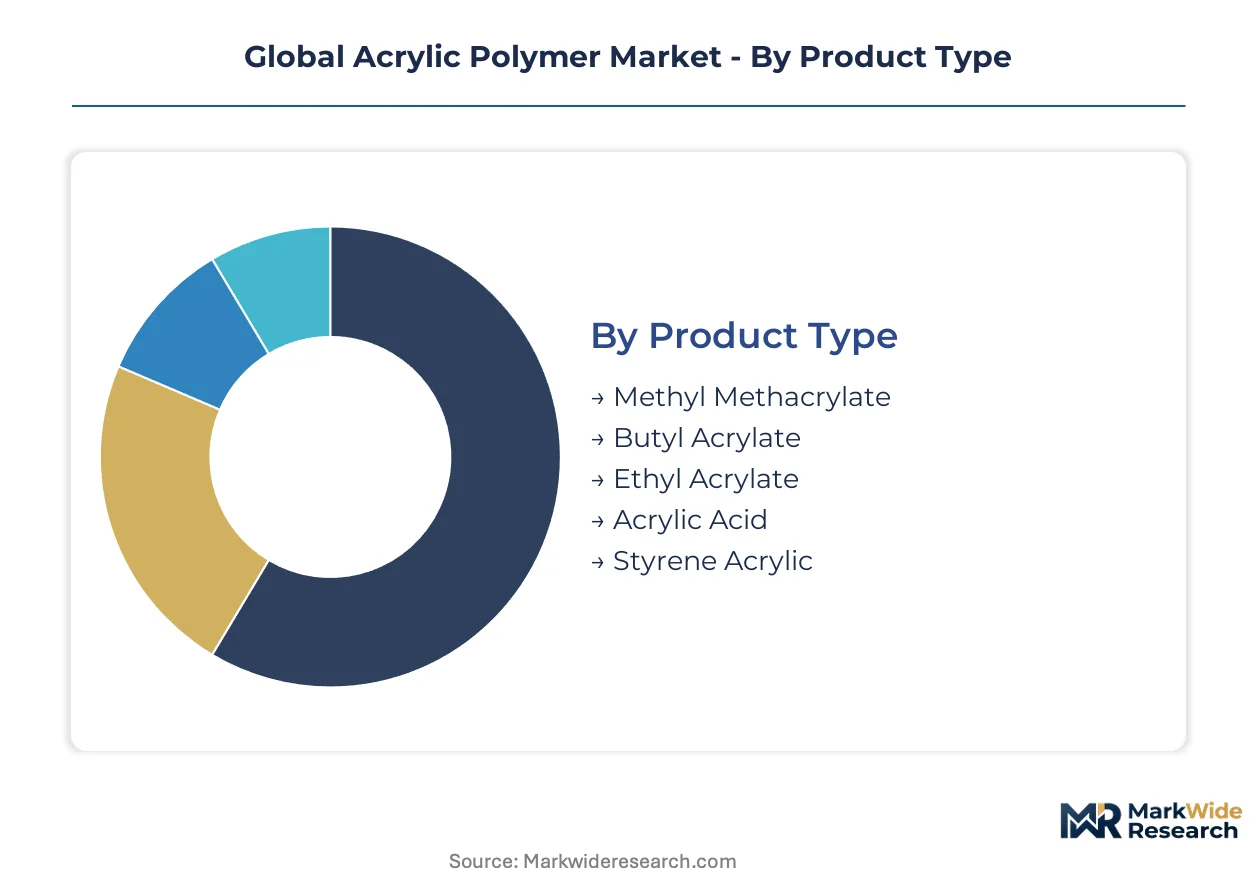
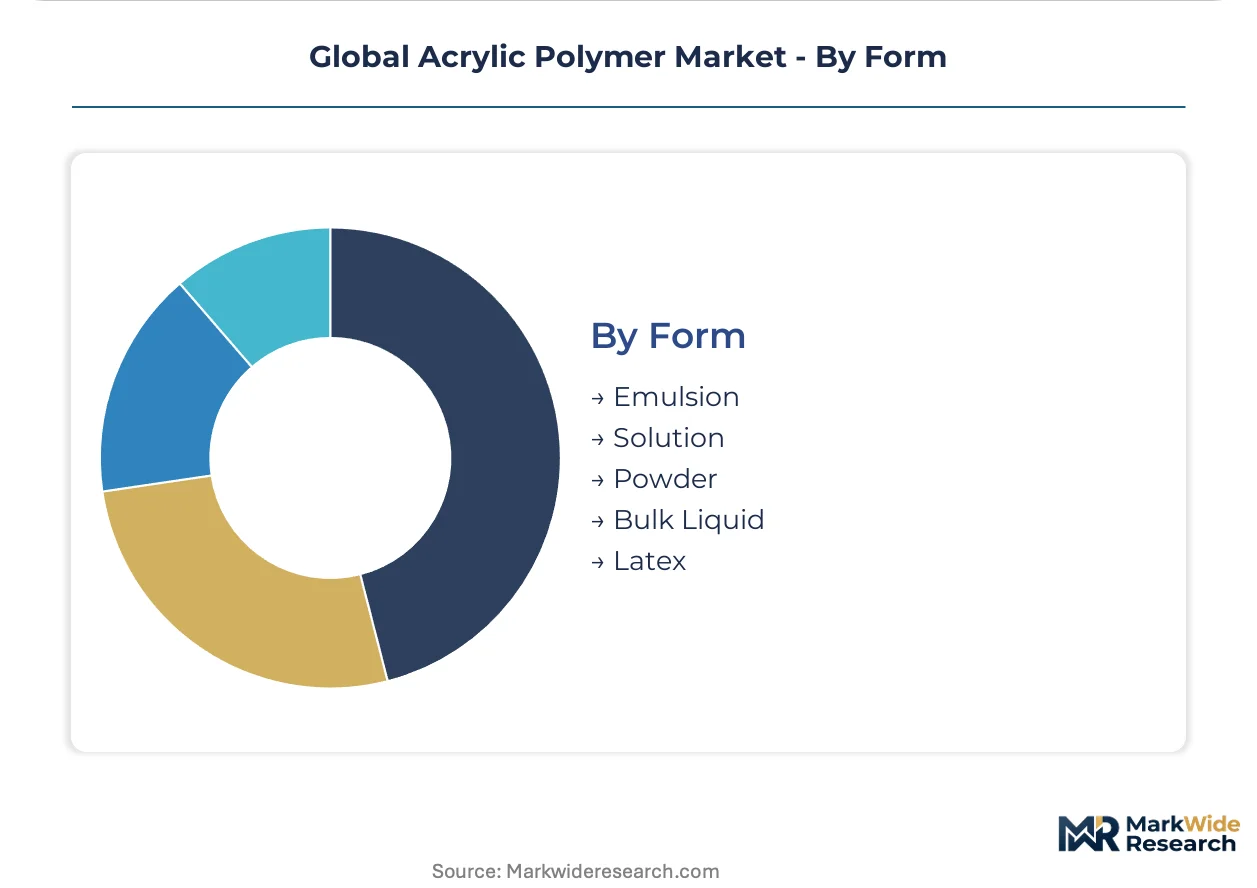
| Segmentation | Product Type: Methyl Methacrylate, Butyl Acrylate, Ethyl Acrylate, Acrylic Acid, Styrene Acrylic Application: Adhesives, Coatings, Elastomers, Textile Finishing, Paints, Sealants End User Industry: Construction, Personal Care, Packaging, Electronics, Adhesive Manufacturers, Textile Producers Form: Emulsion, Solution, Powder, Bulk Liquid, Latex |
| Companies Covered | BASF, Dow Chemical Company, Arkema, Celanese Corporation, Mitsubishi Chemical Corporation, DuPont, LG Chem, Sumitomo Chemical, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acrylic Polymer Market Shifts & Advancements
Acrylic polymer innovation is pivoting from commodity volume expansion toward functional performance differentiation and sustainability-aligned chemistry. Three concurrent developments are restructuring competitive advantage.
Bio-based acrylic acid routes are expanding into commercial-scale production through fermentation-derived 3-hydroxypropionic acid pathways. European coatings formulators are qualifying these materials for premium architectural segments where carbon footprint disclosure influences specification. This technology is expanding into supply contracts with multinational building materials distributors seeking scope 3 emissions reductions.
EPA NESHAP standards for hazardous air pollutants are tightening residual monomer limits in architectural coatings manufacturing. Facility-level compliance is forcing reformulation investments and process control upgrades across US production assets. Waterborne acrylic-alkyd hybrid systems are capturing share in industrial maintenance segments previously dominated by solvent-borne alkyds.
Specification-driven procurement is compressing supplier qualification cycles as coatings formulators consolidate vendor bases around integrated resin-additive-service providers. Regional distributors are losing specification influence to direct technical service relationships between polymer producers and large architectural coatings manufacturers. This pattern is most visible in North American and Western European markets where buyer concentration has accelerated.
Global Acrylic Polymer Market Segmentation
Acrylic polymer specifications diverge sharply across end-use requirements, with molecular weight distribution and glass transition temperature determining suitability for pressure-sensitive adhesives versus rigid sheet applications. Formulation chemists select monomer composition based on weatherability demands, adhesion substrate compatibility, and regulatory compliance obligations in target markets.
Product Type:
Upgrade cycles in automotive glazing and architectural fenestration are accelerating methyl methacrylate substitution for polycarbonate and glass, while waterborne coating mandates elevate butyl acrylate specification rates.
- Methyl Methacrylate:High-clarity thermoplastic resin with exceptional UV stability and impact resistance, polymerized to molecular weights exceeding 1,000,000 g/mol for cast sheet and extruded profiles. Demand concentrates in China's Yangtze River Delta for automotive light guide panels and noise barriers along high-speed rail corridors, driven by infrastructure investment schedules and domestic automotive production targets.
- Butyl Acrylate:Soft, tacky homopolymer and copolymer building block with Tg near -54°C, enabling pressure-sensitive adhesive formulation without plasticizer addition. Waterborne emulsion demand is climbing fastest in India's Gujarat industrial corridor for packaging tape and labelstock serving e-commerce logistics expansion, compelled by solvent-reduction mandates from India's Central Pollution Control Board.
- Ethyl Acrylate:Intermediate Tg monomer for coatings flexibility and adhesive tack balance, copolymerized in architectural latex systems.
- Acrylic Acid:Carboxylic acid functional monomer for crosslinkable coatings and superabsorbent polymer feedstock, supplied primarily as glacial and aqueous solutions.
- Styrene Acrylic:Cost-optimized copolymer combining styrene rigidity with acrylic durability for interior architectural coatings and paper coating binders.
Volume placements concentrate in Methyl Methacrylate; the faster expansion belongs to Butyl Acrylate.
Application:
Application selection tracks substrate compatibility requirements and cure chemistry constraints, with thermal sensitivity of end-use materials dictating waterborne versus solvent-borne system choice.
- Adhesives:Structural, pressure-sensitive, and hot-melt formulations exploiting acrylic tack, cohesion balance, and oxidative stability. Construction adhesives demand is absorbing expanded methyl methacrylate output in prefabricated concrete panel assembly and flooring installation systems across China's manufacturing hubs, responding to modular construction adoption and accelerated project timelines.
- Coatings:Film-forming binders for architectural, automotive, and industrial maintenance finishes requiring weatherability and gloss retention. Architectural coatings procurement is tilting toward emulsion grades in Germany's Rhine-Ruhr industrial region to satisfy EU Green Deal chemical sustainability criteria and ECHA REACH compliance deadlines for low-VOC formulations.
- Elastomers:Crosslinked acrylic rubber for automotive seals and gaskets demanding heat and oil resistance beyond nitrile capabilities.
- Textile Finishing:Soft hand modifiers and wrinkle-resistant treatments applied via pad-dry-cure processes to cotton and synthetic blends.
- Paints:Decorative and protective finishes distinguished from industrial coatings by distribution channel and specification authority.
- Sealants:Gap-filling and joint-sealing compounds requiring movement accommodation and substrate adhesion without primer.
Adhesives command the largest volume placement; Coatings are climbing the fastest.
End User Industry:
Customer procurement patterns separate specification-driven industries with technical service requirements from price-sensitive commodity buyers.
- Construction:Adhesives, sealants, coatings, and sheet applications for residential, commercial, and infrastructure projects. Infrastructure bonding applications in China's Yangtze River Delta chemical clusters are absorbing methyl methacrylate output for bridge deck waterproofing and tunnel lining systems, driven by national transportation network expansion targets and prefabrication adoption.
- Personal Care:Film-forming polymers for hair styling, sun care, and color cosmetics requiring skin compatibility and sensory performance. Specialty methacrylate derivative demand is expanding in South Korea's cosmetic formulation sector for long-wear color cosmetics and UV-filter encapsulation, responding to MFDS cosmetic safety assessment requirements and K-beauty export growth.
- Packaging:Pressure-sensitive adhesives for labels and tapes, plus coatings for barrier and print receptivity.
- Electronics:Photoresists, display films, and encapsulants requiring optical clarity and dielectric stability.
- Adhesive Manufacturers:Toll compounders and formulators converting raw emulsions and resins into finished adhesive systems.
- Textile Producers:Finishing houses and integrated mills applying functional treatments to fabric substrates.
Construction dominates volume placement; Personal Care is gaining share fastest.
Form:
Physical form selection determines handling infrastructure, shipping economics, and formulation integration methods for downstream processors.
- Emulsion:Aqueous dispersion of acrylic polymer particles stabilized by surfactant systems, typically 40-60% solids. Waterborne architectural coatings formulation is redirecting procurement toward emulsion grades in the US Gulf Coast region to satisfy EPA NESHAP hazardous air pollutant standards and residual monomer limits, compelling reformulation investments and process control upgrades.
- Solution:Polymer dissolved in organic solvent for high-gloss industrial coatings and specialty adhesive applications requiring clarity and film integrity.
- Powder:Spray-dried or precipitated solid for dry-blend construction adhesives, textile sizing, and powder coating applications.
- Bulk Liquid:Unpolymerized monomer or oligomeric syrup for in-house polymerization or reactive processing.
- Latex:Natural rubber-compatible terminology often applied interchangeably with synthetic acrylic emulsions in coatings discourse.
Emulsion captures the dominant volume placement; Powder is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Propylene feedstock availability from naphtha crackers anchors acrylic polymer production economics across manufacturing geographies. Regional demand patterns diverge sharply between construction-intensive Asian markets and sustainability-driven European specification requirements. Regulatory fragmentation around VOC limits and monomer registration is redirecting trade flows and localization strategies.
China
Methyl methacrylate demand from automotive light guide panels and high-speed rail noise barriers drives consumption in the Yangtze River Delta chemical clusters. MEE GB standards on industrial emissions and chemical facility siting restrict new acrylic acid capacity in densely populated zones. Nanjing's integrated petrochemical complexes are expanding waterborne emulsion output for domestic architectural coatings reformulation.
United States
Waterborne architectural coatings procurement is compressing solvent-borne acrylic demand along the Gulf Coast petrochemical corridor. EPA NESHAP hazardous air pollutant standards and residual monomer limits force reformulation investments at existing coating lines. Freeport, Texas operations anchor North American methyl methacrylate supply while competing in emulsion-grade production for pressure-sensitive adhesives.
Germany
EU Green Deal chemical sustainability criteria and ECHA REACH compliance deadlines accelerate low-VOC emulsion substitution in the Rhine-Ruhr industrial region. Ludwigshafen's integrated acrylic acid complexes sustain cost-advantaged methyl methacrylate output through backward integration into propylene feedstock. Coatings formulators in Bavaria are qualifying bio-based acrylic acid routes for premium architectural segments.
India
Production-linked incentives for specialty chemicals under the PLI scheme attract acrylic emulsion capacity investments targeting domestic coatings formulation. Central Pollution Control Board solvent-reduction mandates elevate butyl acrylate specification rates in Gujarat's industrial corridor. Ahmedabad and Vadodara chemical clusters absorb expanded output for packaging tape and labelstock serving e-commerce logistics expansion.
Japan
Specialty methacrylate derivative demand concentrates in Kansai and Kanto regions for electronics and medical device applications. METI chemical management policies and JIS standards influence monomer purity specifications for photoresist and display film manufacturing. Osaka-based formulators supply antimicrobial surface treatments for catheter and implantable device producers navigating FDA 510(k) pathway requirements.
Global Acrylic Polymer Market Competitive Landscape
Global majors compete with regional champions across integrated feedstock access and specialty derivative capabilities. The market structure tiers between propylene-integrated commodity producers and focused specialty monomer suppliers. Three archetypes dominate: petrochemical conglomerates with acrylic acid back-integration, European-Japanese specialty methacrylate houses, and Asian emulsion polymerization specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves, with localization strategies following regional regulatory divergence.
Within the integrated petrochemical tier, BASF and Dow Chemical Company exemplify scale-driven positioning through captive acrylic acid production. Arkema occupies a specialty-focused position among methacrylate derivative suppliers. These three anchors represent distinct strategic postures: European-based conglomerate verticality, North American Gulf Coast feedstock access, and French specialty chemical differentiation.
| Leading Market Players |
|---|
| BASF |
| Dow Chemical Company |
| Arkema |
| Celanese Corporation |
| Mitsubishi Chemical Corporation |
| DuPont |
| LG Chem |
| Sumitomo Chemical |
| SABIC |
| Others |
Supply & Pricing Matrix
Captive acrylic acid production at Ludwigshafen, Freeport, and Nanjing anchors supply positions for integrated majors while compressing margin capture for merchant monomer buyers. This backward integration into propylene feedstock simultaneously insulates cost structures from naphtha-cracker volatility and concentrates pricing power among producers with in-house acid capabilities.
Pricing Analysis
Technical service bundling separates premium emulsion grades from unbundled commodity resin transactions, with formulation support, regulatory documentation, and joint development programs commanding 15-25% markups over spot resin pricing. Price differentiation hinges on REACH registration completeness and ISO 14001 environmental certification tier, with ECHA-compliant specialty grades resisting erosion better than standard architectural emulsions. Cost compression in commodity butyl acrylate emulsions is intensifying because of Southeast Asian capacity additions and feedstock cost advantages. Small coatings formulators in India's Gujarat corridor exhibit highest price sensitivity, while medical device coating specialists in Japan's Kansai region prioritize regulatory security over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from automotive OEMs and multinational coatings houses force buyers to qualify multiple methyl methacrylate suppliers across Germany, China, and the United States, preventing single-source concentration despite integrated producers' scale advantages. Raw material flows draw from naphtha-cracker propylene in Northeast Asia, shale-gas-derived feedstock on the US Gulf Coast, and refinery streams in Northwest Europe. Single-source vulnerability concentrates in hydroxyethyl methacrylate and specialty acrylate esters, where European and Japanese merchant suppliers dominate. Distribution runs through direct technical service relationships for large architectural coatings manufacturers, bypassing traditional distributor influence in North American and Western European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where ECHA REACH registration deadlines and residual monomer limits under EPA NESHAP create regulatory moats that protect compliant incumbents while raising capital barriers for prospective entrants.
For Market Incumbents: Acquire stranded solvent-borne coating assets in North America to convert toward waterborne emulsion capacity, capturing EPA NESHAP compliance-driven demand redirection while eliminating competitor feedstock access. Consolidate regional emulsion polymerization engineering talent through targeted hiring in Germany's Rhine-Ruhr corridor, addressing the scarcity constraining expansion timelines for specialty methacrylate derivatives. For New Entrants and Emerging Players: Begin with bio-based acrylic acid qualification programs for premium European architectural segments, where carbon footprint disclosure requirements and EU Green Deal procurement criteria create specification entry points unavailable to commodity incumbents. Target India's PLI-supported specialty chemicals investments for acrylic emulsion capacity, leveraging domestic coatings formulation growth and Central Pollution Control Board solvent-reduction mandates to establish local supply relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty methacrylate derivative producers with FDA 510(k) cleared medical device coating portfolios, where antimicrobial surface treatment demand and regulatory qualification timelines create durable competitive positions. Long-term viability favors integrated producers with captive acrylic acid supply and established REACH registration portfolios. Watch ECHA classification evaluations for acrylic acid derivatives as the inflection signal that would reshape global hazard communication costs and reformulation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Feedstock | Ludwigshafen and Freeport complexes sustain cost-advantaged methyl methacrylate output against merchant acid buyers. |
| Green Manufacturing Transition | Fermentation-derived 3-hydroxypropionic acid pathways qualify European formulators for EU Green Deal procurement criteria. |
| Capacity Expansion in India | PLI scheme incentives attract acrylic emulsion investments targeting Gujarat's packaging tape and labelstock demand. |
| Long-term Supply Agreement | Direct technical service relationships with large architectural coatings manufacturers disintermediate regional distributors. |
| Joint Venture for Specialty Derivatives | Osaka-based antimicrobial methacrylate partnerships penetrate FDA 510(k) medical device coating pathways. |
Research Methodology
Trade databases, ECHA registration dossiers, and SEC 10-K filings formed the secondary backbone, cross-referenced with primary interviews involving plant managers at integrated acrylic acid complexes, procurement leads at downstream coatings manufacturers, distribution channel partners in architectural supply chains, and technical R&D directors specializing in emulsion polymerization. Bottom-up and top-down triangulation validated volume estimates against propylene feedstock consumption patterns and downstream formulation demand.
Bottom-up modeling anchored volume projections across the analysis window, with top-down macro checks against construction spending indices and automotive production schedules. Segmentation dimensions included monomer chemistry, physical form, end-use industry concentration, and regional regulatory compliance tier. CAGRs derived from historical propylene-to-acid conversion economics and emulsion polymerization capacity expansion timelines, with sensitivity to naphtha-cracker operating rates and waterborne formulation mandate implementation pace.
Underlying measurement precision varies by segment; commodity methyl methacrylate volume estimates carry tighter precision than specialty hydroxyethyl methacrylate derivatives where merchant supply concentration limits disclosure. Forecasts reflect assumptions around REACH registration completion schedules, EPA NESHAP enforcement intensity, and PLI scheme disbursement continuity. Deviation in ECHA classification decisions for acrylic acid derivatives would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polybutene Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Resins Market
Polymers & Resins
Africa Polyether Ether Ketone (PEEK) Market
Polymers & Resins
North America Polypropylene Copolymer Market
Polymers & Resins
Thailand Plastics Market
Polymers & Resins
Polystyrene (PS) and Expanded Polystyrene (EPS) Market
Polymers & Resins
South America Epoxy Resins Market
Polymers & Resins
Hair Styling Biopolymers Market
Polymers & Resins
Global Unsaturated Polyester Resins Market
Polymers & Resins
Synthetic Polymer Waxes Market
Polymers & Resins
Synthetic Latex Polymers Market
Polymers & Resins
Highly Reactive Polyisobutylene (HR-PIB) Market
Polymers & Resins
Global Epoxy Primer Market
Polymers & Resins
Global Emulsion Polymer Market
Polymers & Resins
Global High Temperature Resin Market
Polymers & Resins
Global Cyanate Ester Resins Market