
 Global Absorbable Tissue Spacer Market | 2026-2036
Global Absorbable Tissue Spacer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Absorbable Tissue Spacer Market Foresight
Oncology clinics are rotating toward minimally invasive spacer deployment as radiation hospitals scale back open surgical placement protocols. Boston Scientific leverages its interventional oncology portfolio to anchor North American distribution channels for injectable delivery systems. Palette Life Sciences competes through product specialization in hydrogel formulations designed for prostate-rectum separation during radiotherapy. Bioprotect Ltd. sustains technology leadership in bioresorbable foams with extended degradation profiles tailored to multi-week radiation cycles.
Absorbable tissue spacers comprise implantable, biodegradable materials—typically hydrogels, collagen matrices, or synthetic polymers—that temporarily create physical separation between organs or tissues to shield healthy structures from radiation exposure or surgical trauma. These devices undergo controlled hydrolysis or enzymatic degradation over predetermined intervals ranging from several weeks to months, eliminating the need for secondary retrieval procedures. Hydrogel spacers dominate current volume flows due to established reimbursement codes and physician familiarity with injection-based placement, while bioresorbable foams represent the fastest-expanding category as manufacturers refine porosity gradients to match tissue regeneration timelines. Collagen spacers occupy a mature niche in post-surgical healing applications where hemostatic properties add functional value beyond mechanical separation.
FDA 510(k) clearance requirements govern U.S. market entry for absorbable spacers, while the EMA's Medical Device Regulation imposes strengthened clinical evidence standards across European markets. The EU MDR's emphasis on post-market surveillance is forcing manufacturers to rebuild technical documentation for legacy products. Japan's PMDA maintains distinct biocompatibility testing protocols that create additional regulatory friction for Western suppliers. Stakeholders must monitor evolving reimbursement thresholds for spacer-assisted radiotherapy as health technology assessment bodies in Germany, France, and England recalibrate cost-effectiveness benchmarks for prostate cancer interventions.
Market Dynamics
Injectable hydrogel deployment protocols are compressing open surgical placement volumes as radiation oncology departments prioritize same-day outpatient procedures over operating room scheduling. This procedural shift is restructuring capital allocation across hospital systems and ambulatory surgical centers.
Growth Catalysts
- Prostate Radiotherapy Protocols:Major cancer centers in the United States, Germany, and Japan have established spacer-assisted radiotherapy as standard-of-care for localized prostate malignancies, creating institutional demand pull.
- FDA 510(k) Pathway:The premarket notification framework accelerates absorbable implant approvals compared with premarket authorization routes, shortening commercialization timelines for biodegradable hydrogel formulations.
- Reimbursement Code Expansion:Category III CPT codes for hydrogel spacer placement are converting to permanent status across multiple commercial payers, reducing prior authorization friction.
Market Restraints
- Polymer Raw Material Concentration:Medical-grade polyethylene glycol and crosslinking agents concentrate among three specialty chemical suppliers in Germany and Switzerland, exposing manufacturers to input cost volatility.
- EU MDR Technical Documentation:Legacy absorbable spacer products face forced re-registration under strengthened clinical evidence standards, creating compliance backlogs and market access delays.
- Permanent Implant Substitution:Non-absorbable silicone and PTFE spacers retain cost advantages for multi-year radiation fractionation schedules, limiting biodegradable penetration in specific protocols.
Strategic Opportunities
- Gynecologic Brachytherapy:Hydrogel separation between vaginal mucosa and rectum during cervical cancer treatment represents an underpenetrated application with minimal competitive saturation.
- Japanese PMDA Biocompatibility Harmonization:Emerging mutual recognition agreements between FDA and Japan's pharmaceutical regulator are reducing duplicate testing requirements for Western manufacturers.
- 3D-Printed Porosity Gradients:Converging additive manufacturing with controlled-release polymer science enables patient-specific degradation profiles matched to individual radiation schedules.
Industry Challenges
- Interventional Radiology Training Bottlenecks:Transperineal ultrasound-guided spacer injection requires specialized skills that radiation oncologists and urologists must acquire through proctored case volumes.
- Post-Market Surveillance Infrastructure:EU MDR mandates for implant registries and long-term biocompatibility tracking demand capital investment in pharmacovigilance systems that smaller manufacturers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Absorbable Tissue Spacer Market |
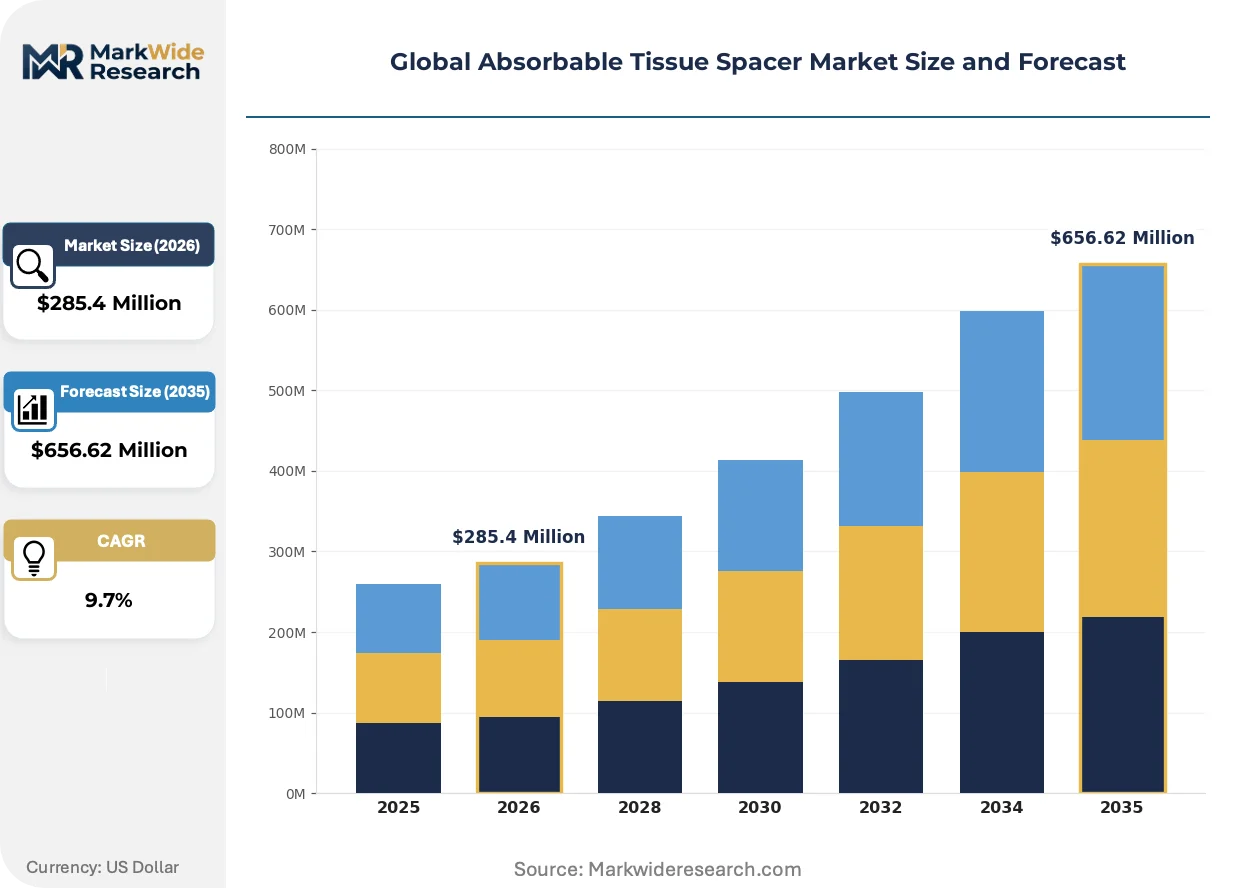
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $656.62 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogel Spacers, Polymer Films, Collagen Spacers, Silicone-Based Spacers, Bioresorbable Foams Application: Radiation Therapy, Post-Surgical Healing, Tissue Regeneration, Organ Protection, Scar Prevention End User: Oncology Clinics, Surgical Centers, Radiation Hospitals, Research Institutes, Ambulatory Surgery Centers Deployment: Intraoperative Use, Preoperative Placement, Injectable Delivery, Minimally Invasive Procedures, External Application |
| Companies Covered | Bioprotect Ltd., CR Bard, Boston Scientific, CIVCO Radiotherapy, Morita Corporation, Palette Life Sciences, Becton Dickinson and Company, IsoAid, Biocomposites, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Absorbable Tissue Spacer Market Shifts & Advancements
Bioresorbable foam chemistry and injection robotics are converging to enable precision placement with tunable degradation kinetics. These advances are compressing the gap between mechanical performance and biological integration timelines.
Bioresorbable polyurethane foams with interconnected pore architectures are supplanting first-generation hydrogels in multi-week radiation protocols. Major academic medical centers in the United States are adopting foam spacers for head-and-neck applications where structural rigidity prevents compression under tissue pressure. This material transition is enabling thinner separation distances with equivalent radiation dose reduction, expanding eligible patient populations.
Japan's PMDA has tightened biocompatibility testing protocols for absorbable implants, requiring extended subchronic toxicity studies that add months to registration timelines. Domestic Japanese manufacturers with established testing infrastructure are capturing incremental market share as Western suppliers rebuild dossiers. The regulatory friction is accelerating partnership strategies between foreign device makers and local contract research organizations.
Hospital purchasing committees are consolidating spacer procurement under centralized interventional oncology contracts rather than maintaining separate urology and radiation oncology vendor relationships. This committee-driven sourcing is displacing individual physician preference items with standardized formularies across health systems in Germany and England. The concentration is most visible within National Health Service trusts where value-based procurement frameworks dominate capital allocation decisions.
Global Absorbable Tissue Spacer Market Segmentation
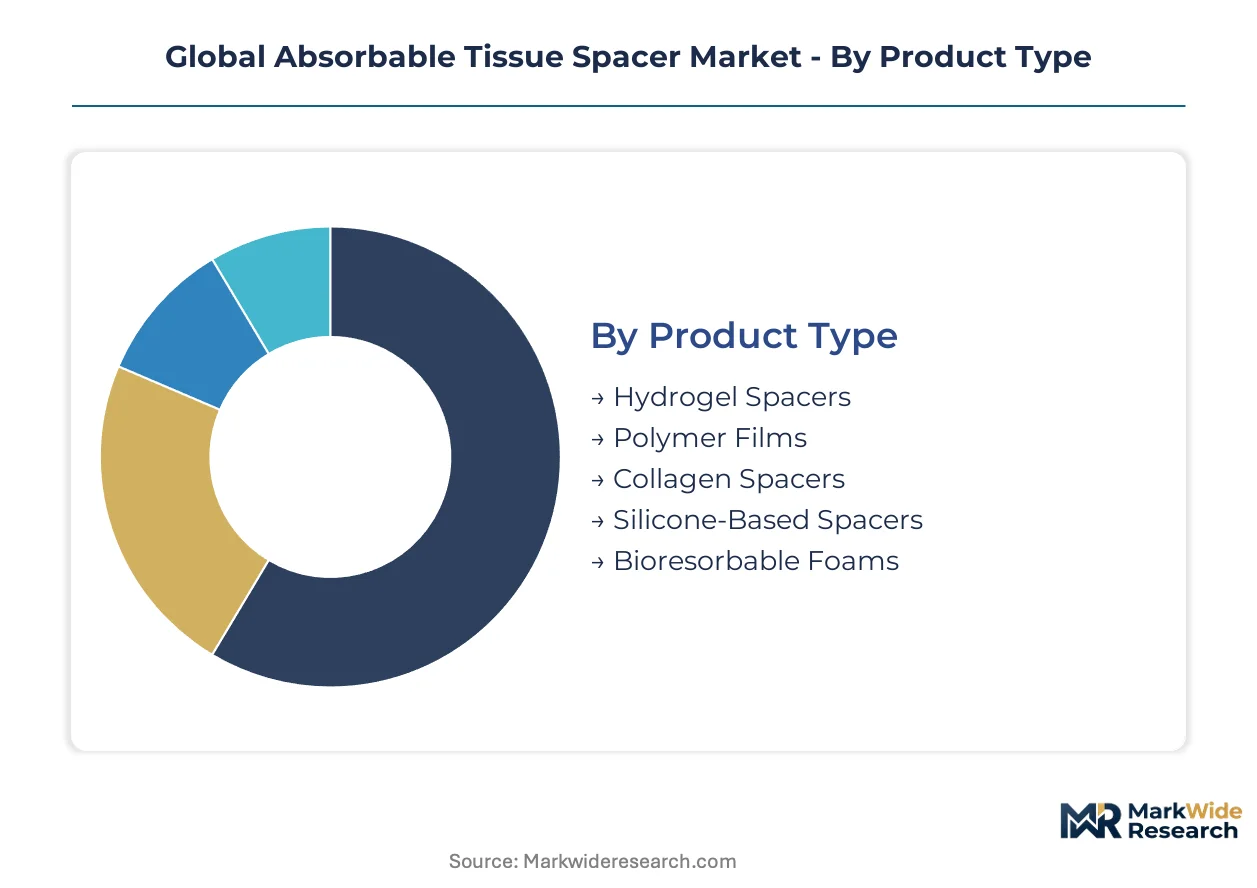
Segmentation in absorbable tissue spacers reflects divergent regulatory pathways, reimbursement structures, and clinical workflows across product categories. Each dimension carries distinct margin profiles and capital requirements that shape manufacturer portfolio decisions.
Product Type:
FDA 510(k) clearance timelines vary substantially across material chemistries, with hydrogel formulations benefiting from predicate device precedents while novel bioresorbable foams face extended biocompatibility scrutiny.
- Hydrogel Spacers:Crosslinked polyethylene glycol matrices dominate current procedural volumes due to established CPT reimbursement codes and physician familiarity with transperineal injection protocols. Major cancer centers in the United States have standardized hydrogel deployment for prostate-rectum separation during radiotherapy fractions.
- Bioresorbable Foams:Polyurethane and polylactic acid foams with tunable porosity gradients are displacing first-generation hydrogels in multi-week radiation schedules where structural rigidity prevents tissue compression. Academic medical centers in Germany and Japan are adopting foam spacers for head-and-neck applications requiring thinner separation distances.
- Collagen Spacers:Derived from bovine or porcine sources, these hemostatic matrices serve post-surgical healing niches where biological integration timelines match shorter regeneration cycles.
- Polymer Films:Thin synthetic barriers address organ protection scenarios requiring predictable degradation without volume displacement.
- Silicone-Based Spacers:Non-absorbable variants retain cost advantages for extended fractionation protocols, limiting biodegradable penetration in specific reimbursement environments.
Hydrogel spacers handle the majority of throughput; bioresorbable foams are gaining share fastest as porosity engineering advances.
Application:
Reimbursement intensity concentrates in radiation therapy applications where spacer-assisted dose escalation protocols command premium coding, while post-surgical indications face tighter cost-effectiveness thresholds.
- Radiation Therapy:Prostate, cervical, and head-and-neck malignancies drive institutional procurement decisions. Category III CPT codes for hydrogel spacer placement are converting to permanent status across commercial payers in the United States.
- Post-Surgical Healing:Cardiac and abdominal procedures utilize collagen matrices for adhesion prevention. Demand concentrates in surgical centers with bundled payment contracts.
- Tissue Regeneration:Orthopedic and dental applications employ resorbable scaffolds matched to bone remodeling timelines.
- Organ Protection:Shielding applications in pelvic and thoracic radiotherapy represent emerging volume pools with minimal competitive saturation.
- Scar Prevention:Dermatological and plastic surgery applications occupy a fragmented niche with limited reimbursement coverage.
Radiation therapy commands the dominant revenue share; organ protection is climbing fastest as gynecologic brachytherapy protocols expand.
End User:
Capital allocation patterns diverge between integrated health systems and independent facilities, with purchasing committee consolidation favoring standardized formularies over physician preference items.
- Oncology Clinics:Freestanding radiation oncology practices prioritize same-day outpatient spacer deployment over operating room scheduling. These facilities drive demand for injectable delivery systems with minimal infrastructure requirements.
- Radiation Hospitals:Academic medical centers with proton and brachytherapy capabilities specify advanced spacer formulations for complex fractionation regimens. Procurement decisions in Germany and England increasingly flow through centralized interventional oncology contracts.
- Surgical Centers:Ambulatory facilities with urology and gynecology service lines utilize spacers for post-operative healing applications.
- Ambulatory Surgery Centers:Medicare reimbursement changes for outpatient procedures are reshaping case volume distribution between hospital-based and freestanding settings.
- Research Institutes:Preclinical and clinical trial activities generate limited commercial volume but influence future standard-of-care protocols.
Oncology clinics process the highest procedure volumes; radiation hospitals are expanding fastest as academic centers adopt foam-based protocols.
Deployment:
Procedural economics favor minimally invasive techniques that eliminate operating room time, though intraoperative placement retains advantages for complex anatomical scenarios.
- Injectable Delivery:Ultrasound-guided transperineal injection dominates prostate applications. Training bottlenecks in interventional radiology skills constrain expansion rates.
- Minimally Invasive Procedures:Laparoscopic and robotic placement protocols are compressing open surgical volumes in gynecologic and abdominal applications.
- Intraoperative Use:Direct surgeon placement during open procedures persists in cardiac and thoracic scenarios requiring immediate structural support.
- Preoperative Placement:Staged deployment protocols allow tissue conditioning prior to radiation commencement.
- External Application:Topical and surface-based delivery occupies niche indications with limited current reimbursement.
Injectable delivery manages the bulk of current throughput; minimally invasive procedures are advancing most rapidly as robotics integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's pharmaceutical logistics hub channels German absorbable spacer exports across the European Union, while direct rail links from Basel to Frankfurt accelerate Swiss-German polymer supply chains for medical-grade raw materials.
United States
Category III CPT codes for hydrogel spacer placement are converting to permanent status across commercial payers, reducing prior authorization friction for prostate radiotherapy. The FDA's 510(k) premarket notification pathway accelerates absorbable implant approvals compared with premarket authorization routes. Major cancer centers in Houston and Boston have established spacer-assisted radiotherapy as standard-of-care for localized prostate malignancies.
Germany
Health technology assessment bodies recalibrate cost-effectiveness benchmarks for prostate cancer interventions, expanding reimbursement thresholds for spacer-assisted protocols. The EU MDR's strengthened clinical evidence standards force manufacturers to rebuild technical documentation for legacy products. The Rhine-Main cluster around Frankfurt concentrates polymer research institutes and specialty chemical suppliers serving medical device manufacturers.
Japan
PMDA biocompatibility testing protocols require extended subchronic toxicity studies that add months to registration timelines for absorbable implants. Emerging mutual recognition agreements between FDA and Japan's pharmaceutical regulator reduce duplicate testing requirements for Western manufacturers. Domestic manufacturers with established testing infrastructure in Osaka and Tokyo capture incremental market share as foreign suppliers rebuild dossiers.
United Kingdom
National Health Service trusts consolidate spacer procurement under centralized interventional oncology contracts, displacing individual physician preference items with standardized formularies. Value-based procurement frameworks dominate capital allocation decisions across England's regional health systems. The Cambridge-Oxford-London corridor anchors clinical trial activity for novel bioresorbable foam formulations.
Switzerland
Medical-grade polyethylene glycol and crosslinking agents concentrate among specialty chemical suppliers in Basel and Geneva, exposing manufacturers to input cost volatility. Swissmedic maintains distinct biocompatibility documentation requirements that create additional regulatory friction for EU-sourced products. The Basel pharmaceutical cluster integrates polymer science expertise with medical device commercialization infrastructure.
Global Absorbable Tissue Spacer Market Competitive Landscape
Listed leaders compete with private specialists across technology platforms and geographic reach, creating a tiered competitive structure where scale-driven multinationals anchor North American distribution while regional specialists dominate formulation innovation. The vendor base clusters around three strategic archetypes: interventional oncology platform companies leveraging existing hospital contracts, hydrogel formulation specialists with proprietary polymer chemistry, and bioresorbable foam pioneers engineering extended degradation profiles. Competitive dynamics center on M&A activity to secure injectable delivery capabilities and strategic partnerships to navigate Japan's PMDA registration requirements.
Within the interventional oncology tier, Boston Scientific and CR Bard exemplify platform companies that anchor North American distribution channels through existing hospital purchasing relationships. Palette Life Sciences occupies a position among formulation specialists focused on hydrogel matrices for prostate-rectum separation. Bioprotect Ltd. represents the bioresorbable foam archetype with technology leadership in tunable porosity gradients.
| Leading Market Players |
|---|
| Bioprotect Ltd. |
| CR Bard |
| Boston Scientific |
| CIVCO Radiotherapy |
| Morita Corporation |
| Palette Life Sciences |
| Becton Dickinson and Company |
| IsoAid |
| Biocomposites |
| Others |
Supply & Pricing Matrix
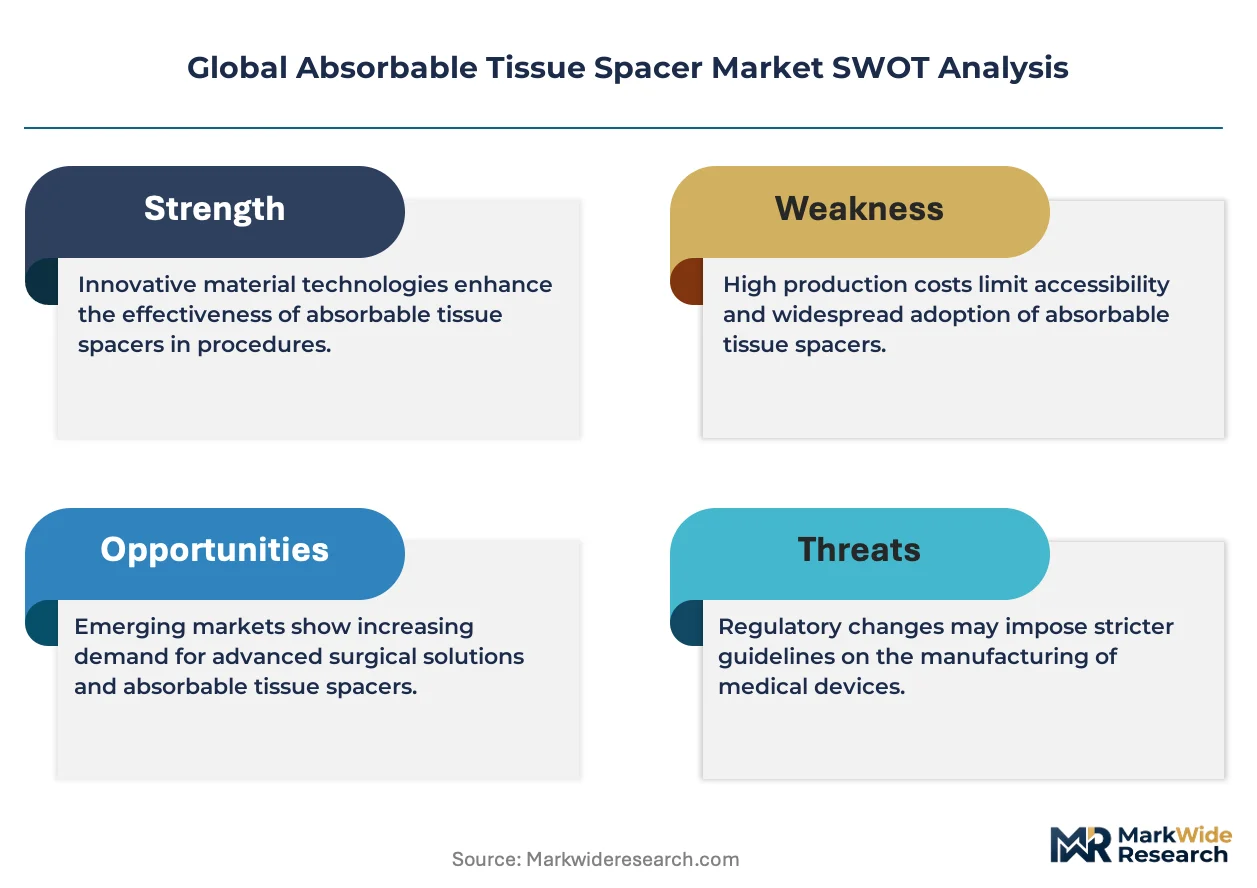
FDA 510(k) clearance tiers gate both supplier qualification and price differentiation simultaneously, with predicate device pathways enabling faster market entry for established formulations while novel bioresorbable foams command premium positioning due to extended biocompatibility scrutiny and specialized manufacturing requirements.
Pricing Analysis
Volume-discount tiering structures separate hospital system contracts from ambulatory surgical center procurement, with three-tier pricing stratification across premium foam formulations, standard hydrogel matrices, and economy-grade collagen products. Price differentiation rests on certification grade—FDA 510(k) versus CE marking pathways—and vertical integration depth among German and Swiss polymer suppliers. Pricing pressure stems from EU MDR compliance costs forcing margin compression in legacy product lines. Ambulatory surgery centers exhibit highest price sensitivity due to Medicare reimbursement rate constraints, while academic medical centers prioritize performance specifications over unit economics.
Supply Chain Analysis
Inventory lead times for medical-grade polyethylene glycol and crosslinking agents extend due to concentrated production among specialty chemical suppliers in Germany, Switzerland, and the United States. Raw material dependencies center on pharmaceutical-grade polymer precursors, sterilization packaging, and precision injection delivery systems. Supply chain risk concentrates in single-source vulnerability for crosslinking agents subject to Swissmedic export documentation requirements. Distribution runs through hospital purchasing committees and group purchasing organizations rather than direct manufacturer-to-physician channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The absorbable tissue spacer market represents high-growth disruption as bioresorbable foam chemistry converges with precision injection robotics, with FDA-PMDA mutual recognition agreements creating regulatory arbitrage opportunities for first movers in cross-border commercialization.
For Market Incumbents: Compound market position through backward integration into polymer precursor manufacturing and captive supply of medical-grade crosslinking agents. Bioresorbable foam specialists threaten hydrogel incumbents through superior structural rigidity in head-and-neck applications. Priority investment centers on 3D-printed porosity gradient capabilities matched to individualized radiation schedules.
For New Entrants and Emerging Players: Post-market surveillance infrastructure gaps among mid-tier manufacturers present service-layer opportunities in EU MDR compliance support and implant registry management. Gynecologic brachytherapy applications remain underpenetrated with minimal competitive saturation. Go-to-market execution should target partnership strategies with Japanese contract research organizations to navigate PMDA biocompatibility testing protocols.
For Investors and Strategic Acquirers: EU MDR forced re-registration reshapes the acquisition landscape toward targets with rebuilt technical documentation and established post-market surveillance systems. Five-to-ten year viability favors manufacturers with diversified material platforms spanning hydrogel, foam, and collagen chemistries. Signal to monitor: CPT code conversion timelines for organ protection applications beyond prostate cancer.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Optimization | Accelerated clearance timelines compress commercialization cycles for biodegradable hydrogel formulations. |
| Japanese PMDA Partnership Strategy | Local CRO relationships reduce duplicate testing requirements and registration friction for Western entrants. |
| 3D-Printed Porosity Gradient Development | Patient-specific degradation profiles match mechanical performance to individual radiation fractionation schedules. |
| Hospital System Contract Consolidation | Centralized interventional oncology procurement displaces physician preference items with standardized formularies. |
| Post-Market Surveillance Infrastructure Buildout | EU MDR implant registry compliance creates competitive moat against undercapitalized competitors. |
Research Methodology
Cross-validation between primary interviews with radiation oncologists, interventional radiologists, hospital purchasing committee members, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, EMA MDR technical documentation, Japanese PMDA submission records, and hospital procurement database extracts. Bottom-up procedure volume modeling triangulates with top-down market sizing across hydrogel, foam, and collagen product categories.
Sensitivity analysis frameworks test forecast robustness across reimbursement code conversion scenarios, EU MDR compliance cost assumptions, and polymer raw material price volatility inputs. Segmentation dimensions include material chemistry, application indication, end-user facility type, and deployment modality. CAGRs derive from procedure volume trajectories and average selling price evolution across the projection horizon, with specific weighting for proton therapy adoption rates and brachytherapy protocol expansion.
Forecasts assume regulatory continuity in FDA 510(k) pathways, EU MDR implementation timelines, and Japanese PMDA biocompatibility protocols; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Global Collagen Meniscus Implants Market
Biomaterials
Global Medical Grade Collagen Market
Biomaterials
Brazil Bone Graft and Substitutes Market
Biomaterials
Global Biomaterials Market
Biomaterials
Heparin Market
Biomaterials
Pulp Cells Market
Biomaterials
Hemostatic Gels Market
Biomaterials
Global Bioactive Materials Market
Biomaterials
Bioceramics and Hydroxyapatite Market
Biomaterials
Scaffold Materials Market
Biomaterials
Bone Substitutes Market
Biomaterials
Polysaccharide Hemostatic System Market
Biomaterials
Orthopedic Bone Defect Repair Materials Market
Biomaterials
Biomimetic Peptides Market
Biomaterials
South America Collagen Market
Biomaterials
Global Extracellular Matrix Patches Market