
 Africa Eubiotics Market | 2026-2036
Africa Eubiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Eubiotics Market Outlook
Market Dynamics
The capital-intensity divergence between fermentation-based probiotic manufacturers and blended organic acid formulators is reorganizing competitive tiers across the continent. Royal DSM leverages its strain development infrastructure to supply thermostable probiotic cultures for African climate conditions. Cargill Incorporated anchors its position through backward integration into organic acid production, controlling feed-grade citric acid supply from Brazilian source plants. BASF SE competes via precision-delivery essential oil encapsulation technologies that withstand pelleting temperatures.
Product Landscape
Eubiotics comprise live microbial cultures, fermentable fibers, short-chain organic acids, and botanical extracts formulated to modulate gastrointestinal microbiota and enhance nutrient assimilation in monogastric and ruminant species. The primary commercial purpose centers on replacing sub-therapeutic antibiotics in animal production systems while maintaining zootechnical performance metrics. Probiotics command the dominant revenue position due to higher unit economics and registration complexity that limits generic competition. Organic acids represent the fastest-expanding category as pelleting-stable acidulant blends penetrate West African broiler operations. Essential oils concentrate margin pools in aquaculture applications where palatability enhancement justifies premium pricing.
Regulatory Environment
South Africa's Department of Agriculture, Land Reform and Rural Development enforces Act 36 of 1947 registration requirements for veterinary feed additives, while the National Regulator for Compulsory Specifications administers import conformity assessments for probiotic strains. Nigeria's National Agency for Food and Drug Administration and Control coordinates with the Standards Organisation of Nigeria to establish maximum residue limits for antibiotic alternatives in exported poultry products. Kenya's Agriculture and Food Authority implements feed safety regulations under the Crops Act that mandate documentation of eubiotic active concentrations. Stakeholders must monitor harmonization progress under the African Continental Free Trade Area protocol, which could mutualize registration dossiers and reshape market access priorities.
Market Dynamics
The tightening of antibiotic residue limits across African livestock export corridors is compressing formulation timelines and forcing feed compounders to validate alternative growth promoters under accelerated commercial pressure.
Growth Catalysts
- Act 36 of 1947 enforcement:South Africa's veterinary feed additive registration mandate creates compliant product demand that filters into neighboring SADC markets through cross-border supply agreements.
- Integrated broiler operations:Nigeria's commercial poultry sector concentrates procurement volumes, enabling eubiotic suppliers to achieve batch-scale economies previously unavailable in fragmented backyard systems.
- Pelleting-stable acidulant blends:West African feed mills adopt heat-resistant organic acid formulations that survive extrusion temperatures, unlocking inclusion in complete feeds rather than top-dressing applications.
Market Restraints
- Strain thermostability limitations:Probiotic cultures from temperate-climate suppliers suffer viability loss during African storage and transport, constraining effective shelf life to eight weeks in ambient conditions.
- Citric acid supply concentration:Brazilian source plants control feed-grade organic acid feedstock, exposing formulators to Atlantic shipping disruptions and currency volatility in the Real-Dollar corridor.
- Registration dossier costs:Kenya's Agriculture and Food Authority mandates documentation of active concentrations that exceeds small-scale domestic manufacturers' analytical capabilities.
Strategic Opportunities
- Rwanda's emerging dairy cooperatives:Underpenetrated ruminant eubiotic demand in East African highland farming systems offers first-mover positioning before regional feed industrialization accelerates.
- African Continental Free Trade Area harmonization:Mutualized registration dossiers under AfCFTA protocols would collapse redundant national approval timelines and reshape market access priorities toward centralized manufacturing hubs.
- Aquaculture essential oil encapsulation:Ghana's tilapia cage farming sector presents premium pricing acceptance for palatability-enhancing botanical extracts that justify unit economics unavailable in terrestrial livestock.
Industry Challenges
- Microbiome analytical capacity gaps:Commercial laboratories capable of strain-specific enumeration remain concentrated in Johannesburg and Lagos, creating diagnostic bottlenecks for efficacy verification.
- Feed mill integration complexity:Legacy batching systems in established East African operations require retrofitting for precise micro-dosing of live cultures, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Eubiotics Market |
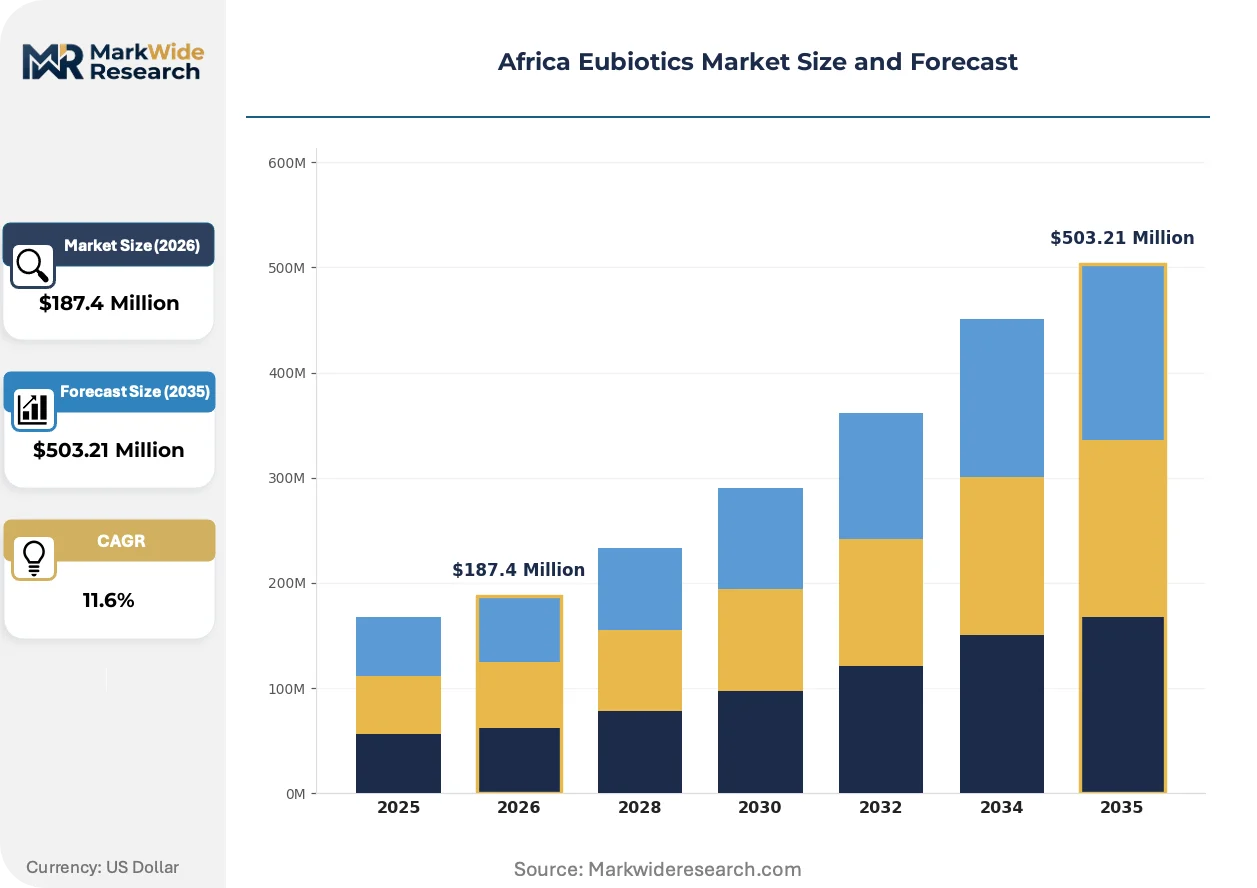
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prebiotics, Probiotics, Organic Acids, Essential Oils Application: Agriculture, Animal Feed, Aquaculture, Food & Beverage End User: Dairy Farms, Poultry Farms, Aquafeed Producers, Livestock Producers Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Royal DSM, Kemin Industries Inc., Cargill Incorporated, Addcon, Novus International Inc., BASF SE, Chr. Hansen AS, Behn Meyer Group, DuPont de Nemours Inc., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Eubiotics Market Strategic Shifts
Formulation science is converging with climate-adaptive strain development to produce eubiotic products that survive African supply chain conditions without cold chain dependency.
Encapsulation technologies for essential oils and organic acids are fragmenting the competitive map. Precision-delivery systems that withstand pelleting temperatures above 85°C enable inclusion in complete feeds rather than separate premixes. Nigerian integrated poultry operations are adopting these formulations fastest, compressing the premium that thermolabile probiotics previously commanded.
Kenya's Agriculture and Food Authority is extending Crops Act feed safety regulations to mandate traceability of eubiotic active concentrations from import through final feed manufacturing. This industrial consequence forces suppliers to establish local analytical partnerships or risk exclusion from government-sanctioned procurement channels. Commercial feed mills in Nairobi and Mombasa are responding by consolidating supplier lists to those with documented batch consistency.
Buyer concentration among integrated livestock operations is consolidating procurement decisions into centralized technical teams with veterinary nutrition expertise. Traditional distributor networks that served fragmented backyard producers are losing share to direct manufacturer relationships with scale buyers. This pattern is most visible in South Africa's Western Cape poultry corridor, where three processor groups control 60 percent of regional eubiotic volume.
Africa Eubiotics Market Segmentation
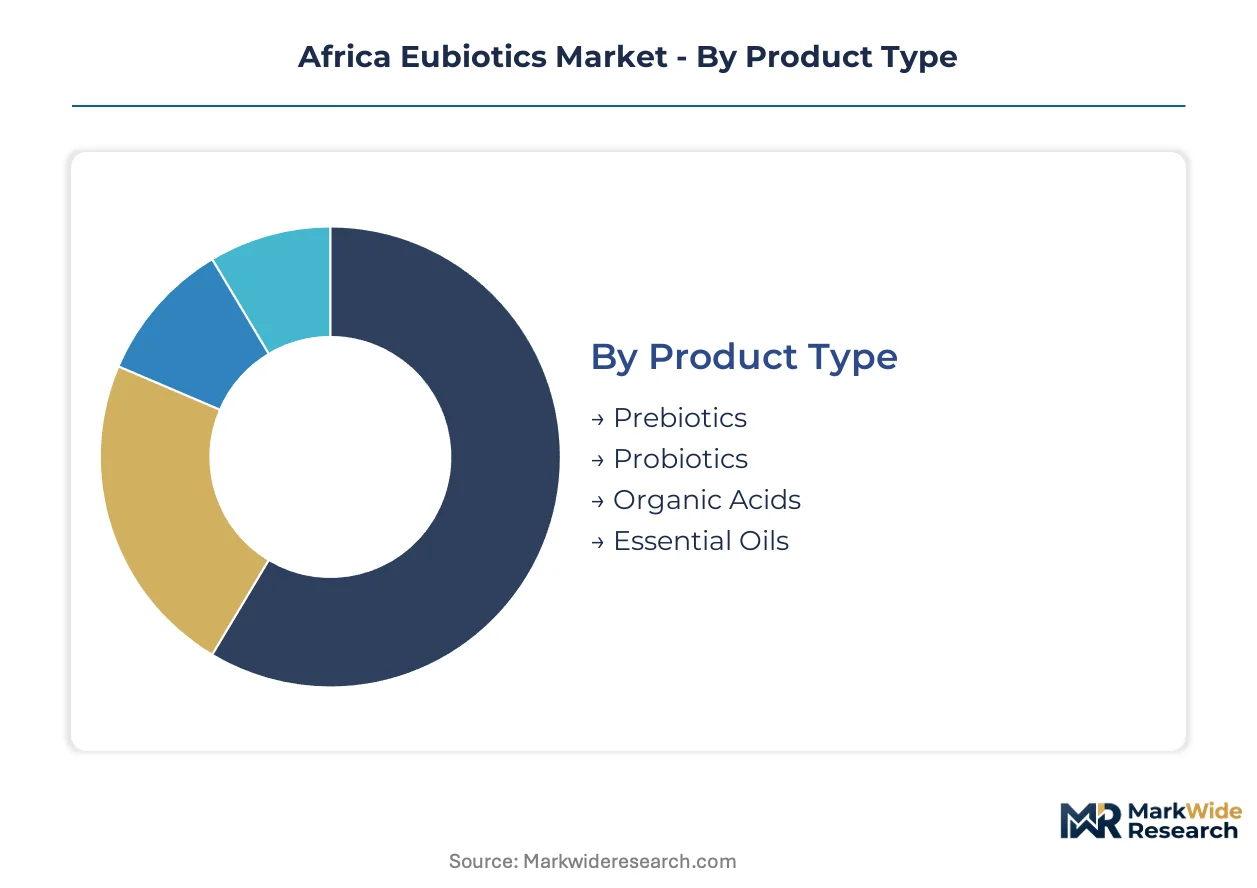
Eubiotics suppliers must align product portfolios with divergent performance requirements across African livestock systems. Segmentation reveals where formulation investments yield commercial traction versus commodity competition.
Product Type:
Probiotics and organic acids anchor domestic manufacturing investments in South Africa and Nigeria, while prebiotics and essential oils flow through import-dependent channels serving export-oriented operations.
- Probiotics:Live microbial cultures of Bacillus subtilis and Lactobacillus strains require thermostability engineering for African ambient storage. South Africa's Western Cape poultry processors concentrate procurement of thermotolerant formulations validated under Act 36 of 1947.
- Organic Acids:Short-chain acidulant blends including formic, propionic, and citric acids modulate gastrointestinal pH. West African feed mills in Lagos and Accra adopt pelleting-stable variants that survive extrusion temperatures above 85°C.
- Prebiotics:Fermentable oligosaccharides and inulin derivatives select for beneficial microbiota. Import volumes concentrate in Kenyan dairy cooperatives seeking residue-compliant feed additives.
- Essential Oils:Botanical extracts from oregano, thyme, and cinnamon deliver antimicrobial phytochemicals. Ghana's tilapia cage farming sector absorbs premium-priced encapsulated formulations for palatability enhancement.
Probiotics commands the established base. The steepest expansion runs through organic acids.
Application:
Cost tier differentiation separates high-investment integrated operations from fragmented backyard systems with divergent technical service requirements.
- Animal Feed:Complete feed incorporation of eubiotics demands precision micro-dosing infrastructure. Nigeria's integrated broiler operations drive volume through centralized procurement of thermostable formulations.
- Aquaculture:Water-soluble delivery systems for cage farming operations require specialized emulsification. Ghana's Volta Lake tilapia producers concentrate demand for essential oil-based palatability enhancers.
- Agriculture:Silage inoculants and soil microbiome amendments extend eubiotic concepts to crop production. Kenyan highland dairy systems absorb lactic acid bacterial cultures for forage preservation.
- Food & Beverage:Human-grade probiotic applications in fermented dairy and beverages operate under distinct regulatory frameworks. South African processors dominate this niche with dedicated fermentation facilities.
Animal feed absorbs the dominant procurement volumes. Aquaculture offers the steepest margin expansion trajectory.
End User:
Customer type fragmentation creates divergent sales channel requirements from technical direct relationships to distributor-dependent outreach.
- Poultry Farms:Broiler and layer operations in Nigeria and South Africa concentrate eubiotic demand through integrated processor groups controlling regional feed procurement decisions.
- Dairy Farms:East African highland cooperatives in Rwanda and Kenya present underpenetrated ruminant eubiotic opportunities before regional feed industrialization accelerates.
- Aquafeed Producers:Ghanaian and Egyptian tilapia feed manufacturers seek residue-compliant growth promoters for European export market access.
- Livestock Producers:Cattle and small ruminant operations across Sahelian zones rely on distributor networks with limited technical service capability.
Poultry farms anchor current revenue concentration. Dairy cooperatives present the most rapid penetration opportunity.
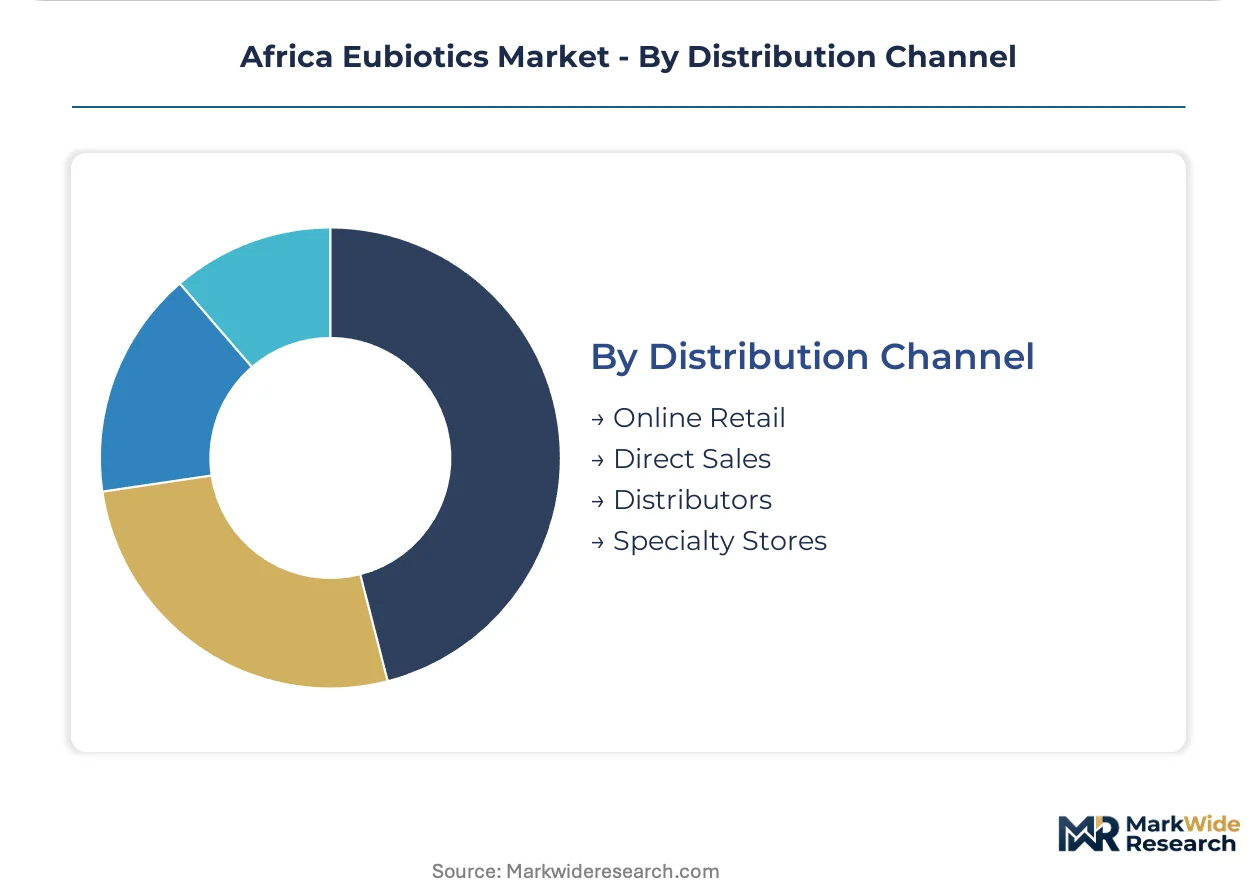
Distribution Channel:
Supply concentration in coastal manufacturing hubs dictates channel economics for interior market reach.
- Distributors:Established networks in Johannesburg, Lagos, and Nairobi warehouse inventory for fragmented backyard producer access. Legacy batch consistency documentation gaps create regulatory exposure under Kenya's Crops Act traceability mandates.
- Direct Sales:Manufacturer technical teams serve integrated poultry and aquafeed operations with veterinary nutrition expertise. South Africa's Western Cape corridor consolidates 60 percent of regional volume through three processor relationships.
- Online Retail:E-commerce platforms emerge for small-scale premix purchases by emerging commercial farms. Limited cold chain reliability constrains probiotic viability guarantees in last-mile delivery.
- Specialty Stores:Feed additive retailers in peri-urban agricultural zones stock fast-moving organic acid blends. Product knowledge gaps among counter staff impede technical specification matching.
Direct sales capture the premium tier. Distributor networks face compression from procurement centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa consumes eubiotics through integrated poultry processors seeking Act 36 compliance, while West African feed mills prioritize heat-stable acidulants for tropical extrusion conditions. East African dairy cooperatives absorb ruminant-focused formulations at earlier adoption stages than their southern counterparts.
South Africa
Integrated broiler operations in the Western Cape concentrate procurement through three processor groups controlling regional feed decisions. The Department of Agriculture, Land Reform and Rural Development enforces Act 36 of 1947 registration requirements that filter compliant products into neighboring SADC markets. Johannesburg and Cape Town host the continent's only commercial laboratories capable of strain-specific probiotic enumeration.
Nigeria
Commercial poultry sector consolidation drives centralized technical procurement of thermostable formulations previously unavailable in fragmented backyard systems. The National Agency for Food and Drug Administration and Control coordinates with the Standards Organisation of Nigeria to establish residue limits for antibiotic alternatives in exported products. Lagos feed mills adopt pelleting-stable acidulant blends that survive extrusion temperatures above 85°C.
Kenya
Highland dairy cooperatives present underpenetrated ruminant eubiotic demand before regional feed industrialization accelerates. The Agriculture and Food Authority implements Crops Act regulations mandating traceability of active concentrations from import through final manufacturing. Nairobi and Mombasa commercial feed mills consolidate supplier lists to documented batch-consistent providers.
Ghana
Tilapia cage farming operations on Volta Lake absorb premium-priced encapsulated essential oils for palatability enhancement unavailable in terrestrial livestock economics. The national food and drug regulator maintains import conformity assessments for aquaculture feed additives targeting European export markets. Accra-based feed manufacturers concentrate demand for water-soluble delivery systems requiring specialized emulsification.
Rwanda
Emerging dairy cooperatives in East African highland farming systems offer first-mover positioning before regional feed industrialization matures. The national agricultural authority implements feed safety documentation requirements aligned with broader East African Community harmonization efforts. Kigali and surrounding highland zones concentrate biosecurity investments from integrated operations scaling commercial milk production.
Africa Eubiotics Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier that competes on formulation customization and climate-adaptive strain development. The capital-intensity divergence between fermentation-based probiotic manufacturers and blended organic acid formulators reorganizes competitive tiers across distribution channels. Three archetypes dominate: multinational life-science conglomerates with strain development infrastructure, agribusiness traders with backward integration into feed-grade acid supply, and regional formulators with encapsulation technology specialization. Competitive moves center on thermostability engineering partnerships and precision-delivery system licensing.
Among Dutch-origin life-science conglomerates, Royal DSM and Royal DSM's strain development infrastructure exemplify the integrated leader archetype with thermostable culture supply capabilities. Cargill Incorporated anchors the agribusiness trader tier through captive supply relationships controlling organic acid feedstock logistics. BASF SE occupies a position within the precision-delivery specialization vector, representing encapsulation technology providers that withstand pelleting temperatures. These three companies illustrate how competitive positioning fragments across upstream control, formulation science, and climate-adaptive product engineering.
| Leading Market Players |
|---|
| Royal DSM |
| Kemin Industries Inc. |
| Cargill Incorporated |
| Addcon |
| Novus International Inc. |
| BASF SE |
| Chr. Hansen AS |
| Behn Meyer Group |
| DuPont de Nemours Inc. |
| Others |
Value Chain & Pricing Dynamics
Pelleting-stable organic acid blends displacing thermolabile probiotics in West African feed mills simultaneously concentrates supply geography around Brazilian citric acid source plants and compresses unit economics for fermentation-based manufacturers. This substitution dynamic rewards backward-integrated acid suppliers while straining probiotic cultures engineered for temperate climates.
Pricing Analysis
After-sales technical service contracts spanning strain viability monitoring and feed mill dosing calibration drive lifetime value for integrated poultry processors. Three-tier pricing structure across premium thermostable probiotics, mid-grade acidulant blends, and economy generic formulations separates Act 36-registered suppliers from unregistered competitors. Cost compression in the probiotic tier is intensifying because ambient storage failures erode effective shelf life to eight weeks. Fragmented backyard producers exhibit highest price sensitivity, while Nigeria's integrated broiler operations absorb premium positioning for documented batch consistency.
Supply Chain Analysis
Strategic stockpiling of heat-resistant acidulant blends dominates procurement behavior among Lagos and Accra feed mills confronting Atlantic shipping volatility. Brazilian source plants control feed-grade citric acid feedstock, while South African fermentation facilities anchor thermotolerant probiotic supply. Raw material dependencies center on corn-derived dextrose for culture media, palm oil for encapsulation matrices, and sulfuric acid for acidulant synthesis. Single-source vulnerability runs through the Real-Dollar currency corridor exposing formulators to exchange rate shocks. Distribution runs through coastal manufacturing hubs in Johannesburg, Lagos, and Nairobi with interior reach via established distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Africa Eubiotics Market represents early-cycle expansion as antibiotic residue limits in livestock export corridors force accelerated validation of alternative growth promoters.
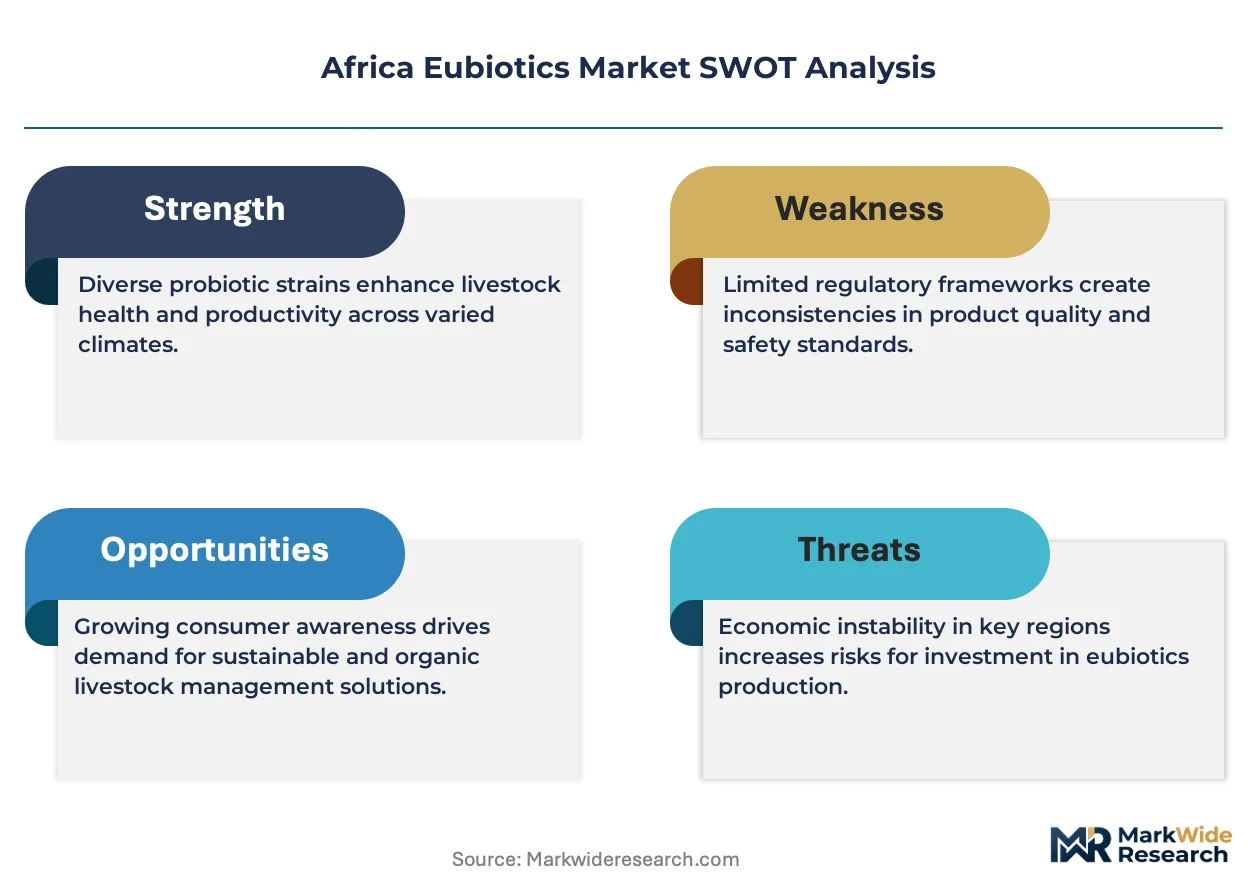
For Market Incumbents: Consolidate strain development partnerships with South African laboratories capable of Act 36 registration dossier preparation, while capturing backward integration into organic acid feedstock through offtake agreements with Brazilian source plants. Thermostability engineering investments defend against emerging regional formulators with climate-adaptive encapsulation technologies. Channel control through direct technical relationships with Nigeria's integrated poultry processors secures volume concentration against distributor network erosion. For New Entrants and Emerging Players: Technical service gaps in Rwanda's emerging dairy cooperatives present first-mover positioning before regional feed industrialization accelerates. Underpenetrated ruminant eubiotic demand in East African highland farming systems offers white-space access with lower registration burden than saturated poultry corridors. Ghana's tilapia cage farming sector absorbs premium pricing for water-soluble essential oil delivery systems requiring specialized emulsification expertise unavailable from incumbent agribusiness traders. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed precision-delivery technology specialists holding encapsulation patents for pelleting temperatures above 85°C. Five-to-ten year viability hinges on African Continental Free Trade Area harmonization collapsing redundant national approval timelines. Acquisition targets cluster around regional formulators with documented Kenya Agriculture and Food Authority compliance. The signal to watch is batch consistency documentation becoming mandatory for government-sanctioned procurement channels.| Strategic Initiative | Industry Significance |
|---|---|
| Thermostability Engineering Partnerships | Climate-adaptive strain development secures viability across African ambient storage conditions without cold chain dependency. |
| Act 36 Registration Dossier Investment | South Africa's veterinary feed additive mandate filters compliant products into neighboring SADC markets through cross-border agreements. |
| Backward Integration into Acid Feedstock | Captive supply relationships with Brazilian source plants insulate formulators from Atlantic shipping disruptions and currency volatility. |
| Precision-Delivery System Licensing | Encapsulation technologies withstanding pelleting temperatures above 85°C enable inclusion in complete feeds rather than separate premixes. |
| Analytical Partnership Localization | Commercial laboratories capable of strain-specific enumeration in Johannesburg and Lagos resolve diagnostic bottlenecks for efficacy verification. |
Study Parameters
The analysis maps probiotic cultures, organic acid blends, prebiotic fibers, and essential oil extracts, each validated through feed mill procurement managers, veterinary nutritionists at integrated poultry operations, regulatory affairs specialists navigating Act 36 compliance, and distribution channel partners in peri-urban agricultural zones. Primary interview insights triangulate against South African Department of Agriculture enforcement records, Nigerian National Agency for Food and Drug Administration residue limit guidelines, Kenya Agriculture and Food Authority Crops Act documentation requirements, and Ghanaian aquaculture feed additive import assessments. Bottom-up volume builds from named end-user procurement volumes reconcile with top-down market sizing derived from regional feed production statistics and eubiotic inclusion rate assumptions.
Consistency checks against external benchmarks validate volume and value outputs across the analysis window. Segmentation dimensions model product type, livestock application, end-user concentration tier, and distribution channel structure alongside climate-adaptive formulation requirements specific to tropical storage conditions. CAGRs derive from year-on-year growth rate compounding applied to base period market estimates. Industry-specific forecast inputs incorporate pelleting temperature survival thresholds, ambient storage viability decay curves, and regulatory harmonization progress under African Continental Free Trade Area protocols.
Forecasts assume regulatory continuity in South Africa's Act 36 enforcement, Nigeria's National Agency for Food and Drug Administration coordination with Standards Organisation of Nigeria, and Kenya's Agriculture and Food Authority Crops Act implementation; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as African Continental Free Trade Area mutualized registration dossier negotiations and strain thermostability breakthroughs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Zein Protein Market
Food Biotechnology
Research-Grade Proteins Market
Food Biotechnology
Direct-Fed Microbial Products Market
Food Biotechnology
Hemoglobin Feed Market
Food Biotechnology
Carbohydrate Enzyme Preparation Market
Food Biotechnology
Global GMO Testing Market
Food Biotechnology
Beta Lactoglobulin Protein Market
Food Biotechnology
Lupin Protein Market
Food Biotechnology
Apigenin Market
Food Biotechnology
Fruit and Vegetable-Derived Enzymes Market
Food Biotechnology
Cultured Meat Market
Food Biotechnology
Red Seaweed Extract Market
Food Biotechnology
Europe Eubiotics Market
Food Biotechnology
Brown Algae Protein Market
Food Biotechnology
Global Feed Enzymes Market
Food Biotechnology
Papain Market