
 Recombinant Therapeutic Antibodies and Proteins Market | 2026-2036
Recombinant Therapeutic Antibodies and Proteins Market Size, Share, and Industry Trends Forecast 2026-2036
Recombinant Therapeutic Antibodies and Proteins Market Analytics
Bioprocess engineering talent is bifurcating the competitive landscape, separating firms with in-house mammalian cell culture expertise from those dependent on contract manufacturing. Amgen Inc. leverages its decades of biologics manufacturing scale to sustain cost advantages in large-volume antibody production. F. Hoffmann-La Roche Ltd. anchors its position through deep specialization in oncology monoclonal antibodies, while Pfizer Inc. competes by extending its presence across multiple therapeutic modalities.
Recombinant therapeutic antibodies and proteins comprise genetically engineered immunoglobulins and polypeptides produced in bacterial, yeast, or mammalian expression systems, typically requiring post-translational glycosylation for therapeutic efficacy. These biologics target specific disease pathways with precision, replacing or supplementing endogenous proteins in cancer, autoimmune, and metabolic disorders. Monoclonal antibodies dominate value generation due to established clinical validation and premium pricing in oncology, while fusion proteins represent the fastest-expanding category as developers engineer novel mechanisms combining antibody specificity with cytokine signaling. Application demand clusters in cancer treatment, where checkpoint inhibitors and antibody-drug conjugates command the deepest margin pools.
FDA biosimilar guidelines, EMA's Good Manufacturing Practice standards for biologics, and WHO prequalification programs collectively shape product development timelines, manufacturing compliance costs, and market access pathways across jurisdictions. Regulatory stringency around host cell protein impurities and glycan profiling directly determines which candidates advance to commercial scale. Stakeholders must monitor evolving comparability protocols and real-world evidence requirements as health technology assessment bodies tighten reimbursement scrutiny.
Market Dynamics
Bioprocess engineering capability is concentrating competitive advantage among firms with proprietary mammalian cell culture platforms, while contract-dependent manufacturers face margin compression from escalating host cell protein compliance costs and glycan characterization requirements.
Growth Catalysts
- EMA streamlined assessment pathways:Accelerated biosimilar approvals in European markets are compressing time-to-market for follow-on biologics and expanding patient access to cost-effective therapies.
- Oncology monoclonal antibody demand:Checkpoint inhibitors and antibody-drug conjugates in cancer treatment command sustained volume expansion as precision medicine protocols penetrate community hospital settings.
- Specialty pharmacy network expansion:United States distribution infrastructure for temperature-controlled biologics is deepening last-mile cold chain reliability and reducing product spoilage rates.
Market Restraints
- Chinese hamster ovary cell supply concentration:Dependence on limited qualified cell line suppliers creates vulnerability to contamination events and batch failure cascades.
- FDA glycan profiling stringency:Evolving comparability protocols for post-translational modifications extend analytical validation timelines and escalate CMC documentation burdens.
- Small molecule kinase inhibitor substitution:Oral oncology therapies in BCR-ABL and EGFR mutation settings capture patient preference and payer budget allocation from infused antibodies.
Strategic Opportunities
- Indian CDMO capacity expansion:Underutilized biologics manufacturing infrastructure in Hyderabad and Bengaluru offers cost arbitrage for Western developers seeking capacity diversification.
- Multi-specific antibody engineering:Bispecific and trispecific formats combining checkpoint blockade with T-cell engager mechanisms open mechanistic white space beyond established targets.
- Japan PMDA regenerative medicine framework:Accelerated approval pathways for novel protein therapeutics in rare disease indications reward early regulatory engagement with compressed development timelines.
Industry Challenges
- Bioprocess analytical scientist scarcity:Shortage of professionals proficient in mass spectrometry-based host cell protein detection and multi-attribute method development constrains manufacturing scale-up velocity.
- Single-use system validation complexity:Extractables and leachables qualification for disposable bioreactor components extends facility commissioning timelines and escalates capital deployment risk.
- Legacy quality management system integration:Paper-based batch records and disconnected ERP systems impede real-time release testing adoption and digital twin implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recombinant Therapeutic Antibodies and Proteins Market |
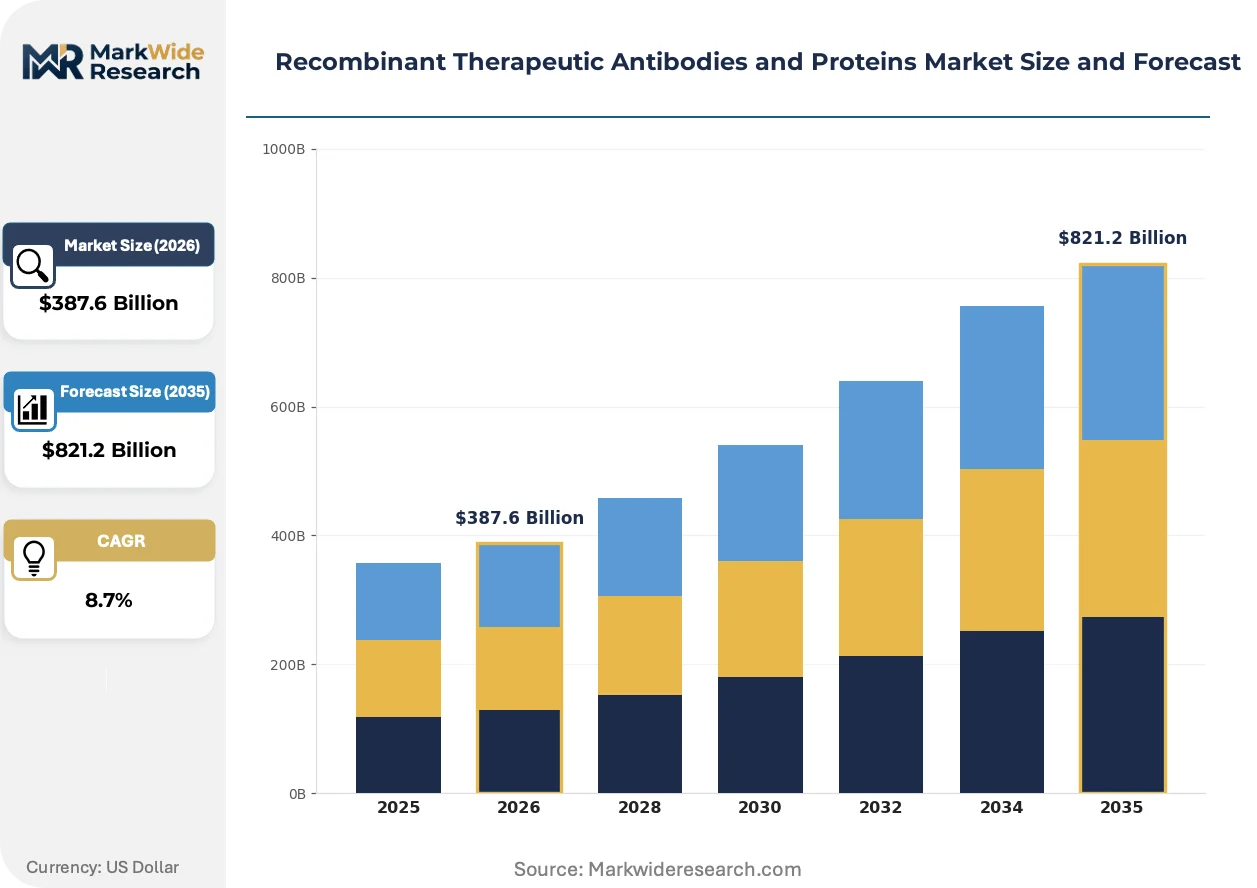
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Polyclonal Antibodies, Proteins, Fusion Proteins Application: Cancer Treatment, Autoimmune Disorders, Infectious Diseases, Cardiovascular Diseases Delivery Mode: Injection, Infusion, Oral, Transdermal End User: Hospitals, Research Laboratories, Clinics, Pharmaceutical Companies |
| Companies Covered | Amgen Inc., F. Hoffmann-La Roche Ltd., Pfizer Inc., Johnson & Johnson Services, Inc., AbbVie Inc., Merck & Co., Inc., Sanofi, Biogen, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recombinant Therapeutic Antibodies and Proteins Market Evolving Landscape
Continuous bioprocessing architectures are displacing traditional fed-batch manufacturing, while artificial intelligence applications in cell line development compress clone selection timelines. These shifts are restructuring capital deployment patterns and competitive moats across the value chain.
Continuous perfusion bioreactor technology is decomposing the economic logic of large-scale stainless steel facilities by enabling smaller footprint manufacturing with equivalent output. Mid-cap developers in Boston and San Francisco are adopting this platform to reduce upfront capital requirements. The technology is decomposing the barrier between clinical and commercial scale, allowing flexible capacity expansion without billion-dollar facility commitments.
EU MDR Article 117 requirements for device-drug combination products are tightening quality management system integration obligations for antibody-drug conjugate manufacturers. Notified body involvement in technical documentation review extends submission preparation timelines by eight to fourteen months. Oncology-focused developers with established European commercial infrastructure are absorbing these costs more readily than emerging entrants.
Hospital pharmacy consolidation into centralized procurement entities is compressing vendor negotiation cycles and demanding standardized dosing configurations. Integrated delivery networks in Texas and Florida are unbundling traditional bundled pricing into line-item transparency requirements. This pattern concentrates volume allocation decisions among fewer formulary committees with explicit total cost of ownership evaluation frameworks.
Recombinant Therapeutic Antibodies and Proteins Market Segmentation
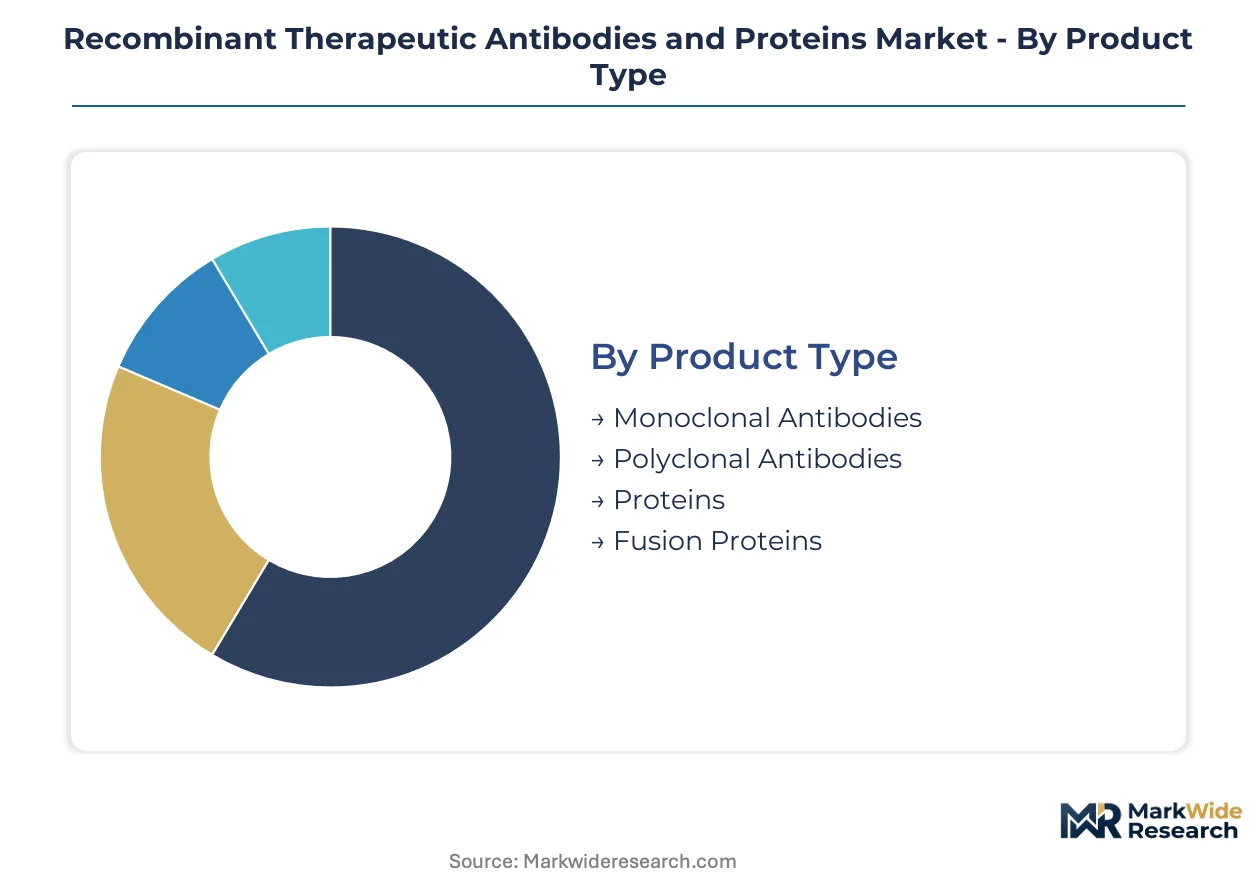
Recombinant therapeutic antibodies and proteins fragment across multiple technical and commercial dimensions. Product type determines manufacturing complexity and margin structure. Application focus shapes clinical development timelines and reimbursement pathways.
Product Type:
Monoclonal antibodies face intensifying substitution pressure from oral small molecules in oncology, while fusion proteins defend against biosimilar erosion through structural complexity barriers.
- Monoclonal Antibodies:Homogeneous immunoglobulins derived from single B-cell clones, requiring mammalian expression systems for proper glycosylation. Demand concentrates in United States oncology centers where checkpoint inhibitors and antibody-drug conjugates command premium formulary placement despite payer pressure.
- Fusion Proteins:Engineered constructs combining antibody Fc domains with cytokine or receptor ligand moieties, enabling dual-mechanism signaling. German and Swiss developers exploit these formats to extend patent protection and access EMA streamlined assessment pathways for novel mechanisms.
- Polyclonal Antibodies:Heterogeneous antibody mixtures derived from multiple immune cell lineages, typically deployed in acute toxin neutralization and transplant rejection prophylaxis.
- Proteins:Recombinant cytokines, growth factors, and enzyme replacement therapies produced in microbial or mammalian systems, dominating metabolic and hematologic indications.
Monoclonal antibodies anchor the volume base while fusion proteins gain share at the steepest rate.
Application:
Cancer treatment commands the deepest margin pools, yet autoimmune applications demonstrate more durable pricing power against biosimilar incursion.
- Cancer Treatment:Precision biologics targeting tumor microenvironment checkpoints and oncogenic signaling pathways. Japanese PMDA accelerated pathways and United States Breakthrough Therapy designations compress development timelines for novel targets.
- Autoimmune Disorders:Chronic inflammatory condition management through cytokine neutralization and B-cell depletion. Rheumatology and gastroenterology practices in France and Germany drive volume through long-acting subcutaneous formulations.
- Infectious Diseases:Monoclonal antibody cocktails for viral neutralization and toxin sequestration, with demand spikes tied to outbreak surveillance.
- Cardiovascular Diseases:PCSK9 inhibitors and anticoagulant proteins addressing residual risk in statin-treated populations, constrained by oral generic competition.
Cancer treatment absorbs the largest development investment while autoimmune applications show the most resilient pricing architecture.
Delivery Mode:
Infusion-dependent products carry higher healthcare system costs, creating vulnerability to oral and subcutaneous alternatives.
- Injection:Subcutaneous and intramuscular administration formats enabling home and clinic delivery without hospital infrastructure.
- Infusion:Intravenous delivery requiring specialized nursing and monitoring, dominating oncology and immunology biologics with high dosing volumes.
- Oral:Encapsulated protein and peptide formulations exploiting permeation enhancers, though bioavailability constraints limit therapeutic applicability.
- Transdermal:Microneedle and iontophoretic systems for localized or systemic protein delivery, emerging in pain management and hormone replacement.
Infusion maintains volume dominance in high-dose indications while injection formats expand fastest through patient preference and site-of-care economics.
End User:
Hospital procurement consolidation is compressing vendor margins while research laboratories sustain premium pricing for specialized reagents.
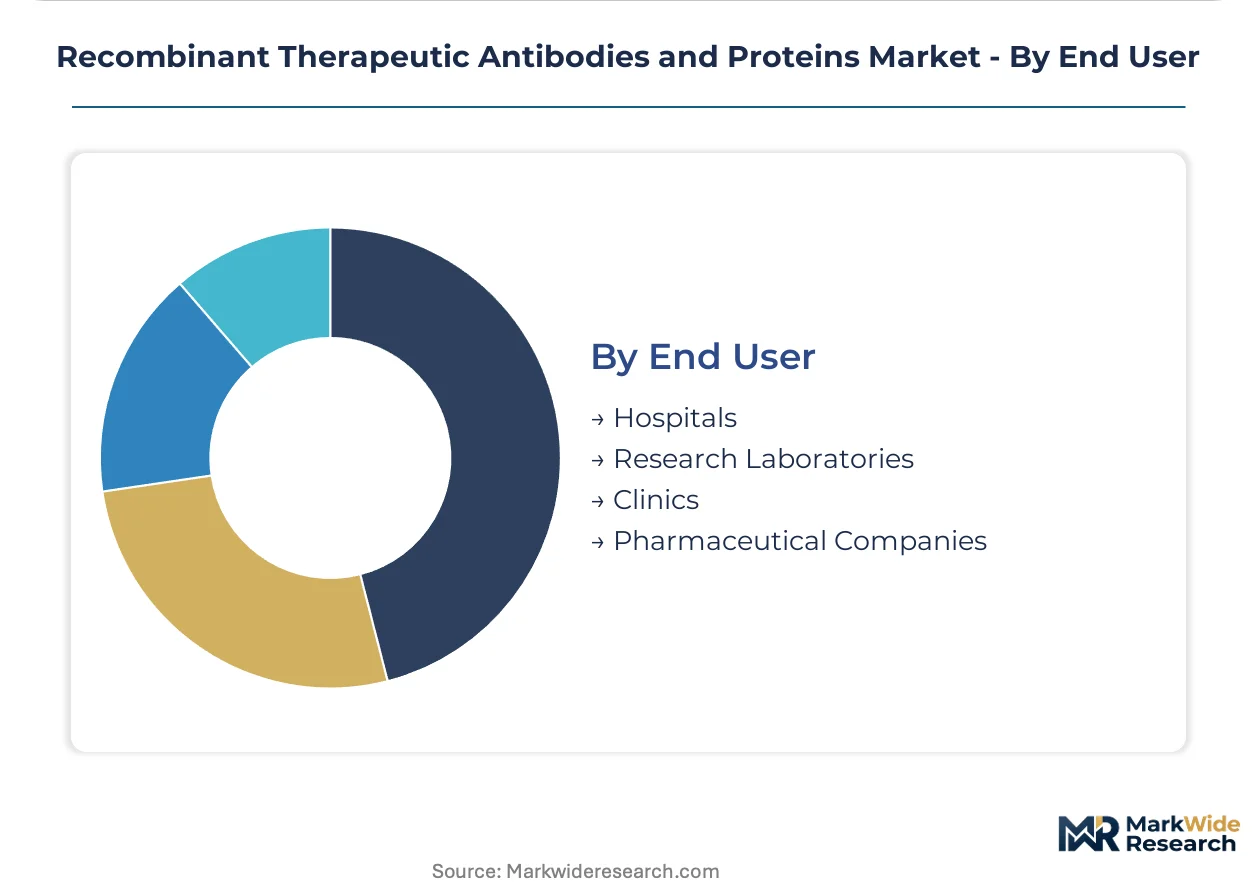
- Hospitals:Centralized pharmacy and infusion center operations managing formulary placement, inventory, and administration for inpatient and outpatient biologic therapy.
- Pharmaceutical Companies:In-licensing and acquisition targets seeking pipeline assets, with due diligence focusing on CMC readiness and regulatory pathway clarity.
- Research Laboratories:Academic and contract research organizations utilizing recombinant proteins as assay reagents, cell culture supplements, and reference standards.
- Clinics:Specialized infusion and injection centers in community settings, particularly rheumatology and dermatology practices managing chronic biologic therapy.
Hospitals command the procurement volume base while pharmaceutical company licensing activity climbs fastest as pipeline assets consolidate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's biosimilar approval pathway anchors the United States as the dominant geography, while EMA streamlined assessments and Japan PMDA frameworks reshape competitive entry across developed markets. Hospital procurement intensifies as chronic disease burdens escalate, with specialty pharmacy networks and Medicare reimbursement policies anchoring volume concentration.
United States
Specialty pharmacy networks and Medicare reimbursement policies drive hospital procurement of biologic therapies. FDA's biosimilar approval pathway compresses time-to-market for follow-on biologics while maintaining stringent glycan profiling requirements. The Greater Boston and San Francisco clusters host mid-cap developers adopting continuous perfusion bioreactor technology to reduce capital requirements.
Germany
Rheumatology and gastroenterology practices drive volume through long-acting subcutaneous formulations for autoimmune disorders. EMA's Good Manufacturing Practice standards for biologics shape manufacturing compliance costs and market access pathways. The Rhine-Main and Munich regions concentrate bioprocess engineering talent and mammalian cell culture expertise.
Switzerland
Oncology monoclonal antibody specialization commands premium formulary placement despite payer pressure. Swissmedic maintains stringent regulatory oversight of host cell protein impurities and glycan profiling for commercial scale advancement. The Basel cluster anchors deep specialization in precision biologics targeting tumor microenvironment checkpoints.
Japan
Community hospital settings absorb expanding checkpoint inhibitor and antibody-drug conjugate volumes as precision medicine protocols penetrate. PMDA's regenerative medicine framework offers accelerated approval pathways for novel protein therapeutics in rare disease indications. The Kanto and Kansai regions concentrate biologics manufacturing infrastructure and regulatory engagement expertise.
India
Western developers seek cost arbitrage through underutilized biologics manufacturing infrastructure for capacity diversification. CDSCO oversight aligns with WHO prequalification programs for product development timelines across jurisdictions. The Hyderabad and Bengaluru clusters offer contract manufacturing capacity expansion for mammalian cell culture platform diversification.
Recombinant Therapeutic Antibodies and Proteins Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with bioprocess engineering capability concentrating advantage among firms with proprietary mammalian cell culture platforms. The market structure separates consolidated large-volume antibody producers from emerging mid-cap developers and contract-dependent manufacturers facing margin compression. Three archetypes dominate: integrated biologics manufacturers with decades of scale, oncology-focused monoclonal antibody specialists, and diversified pharmaceutical competitors extending across multiple therapeutic modalities. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms navigate host cell protein compliance costs and glycan characterization requirements.
Among integrated biologics manufacturers, Amgen Inc. and F. Hoffmann-La Roche Ltd. exemplify the scale-driven archetype, with the former representing decades of biologics manufacturing expertise and the latter anchoring deep specialization in precision oncology applications. Pfizer Inc. occupies a diversified position across multiple therapeutic modalities, competing through portfolio breadth rather than singular therapeutic focus. These three entities collectively illustrate the competitive tension between manufacturing scale, therapeutic specialization, and portfolio diversification that defines market positioning.
| Leading Market Players |
|---|
| Amgen Inc. |
| F. Hoffmann-La Roche Ltd. |
| Pfizer Inc. |
| Johnson & Johnson Services, Inc. |
| AbbVie Inc. |
| Merck & Co., Inc. |
| Sanofi |
| Biogen |
| Thermo Fisher Scientific Inc. |
| Others |
Value Network & Pricing Analysis
Continuous perfusion bioreactor adoption is displacing traditional stainless steel facility economics, simultaneously redistributing manufacturing capacity toward Boston and San Francisco clusters while compressing capital-based pricing premiums for clinical-scale production.
Pricing Analysis
Geographic price spreads between United States and Indian contract manufacturing now exceed threefold for equivalent mammalian cell culture outputs. Three-tier pricing structure across originator, biosimilar, and follow-on biologic levels reflects FDA glycan profiling stringency versus CDSCO streamlined assessments. Pricing pressure stems from Chinese hamster ovary cell supply concentration and escalating host cell protein compliance documentation. Research laboratories exhibit lowest price sensitivity due to specialized reagent requirements, while hospital procurement entities demonstrate highest sensitivity through consolidated formulary negotiations.
Supply Chain Analysis
Inventory lead times for qualified cell lines and single-use bioreactor components now extend fourteen to twenty months for new facility commissioning. Supply concentrates in United States, Switzerland, and Germany for proprietary mammalian platforms, while India and China expand contract capacity. Raw material dependencies center on cell culture media, chromatography resins, and filtration membranes. Single-source vulnerability pervades chromatography resin supply from limited qualified vendors. Distribution runs through specialty pharmacy networks for temperature-controlled last-mile delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where continuous bioprocessing interoperability between clinical and commercial scale is restructuring competitive moats away from capital intensity toward engineering talent concentration.
For Market Incumbents: Consolidate mammalian cell culture expertise through captive bioprocess engineering academies in Basel and Boston clusters. Deepen backward integration into chromatography resin supply to offset single-source vulnerability. Absorb EU MDR Article 117 compliance costs through established European quality management infrastructure.
For New Entrants and Emerging Players: Anchor in Hyderabad and Bengaluru CDMO partnerships to access underutilized biologics capacity without billion-dollar facility commitments. Target rare disease protein therapeutics through Japan PMDA accelerated pathways. Pursue bispecific antibody engineering white space beyond established checkpoint targets.
For Investors and Strategic Acquirers: The market sits at a manufacturing-technology transition phase that favors mid-cap developers with continuous perfusion platforms over legacy fed-batch asset bases. Long-term viability hinges on glycan characterization capability and regulatory submission track records. Watch for FDA comparability protocol revisions as inflection signal for CMC documentation burden shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Continuous perfusion adoption reduces capital requirements for clinical-commercial transition in Boston clusters. |
| Regulatory Approval Pathway | EMA streamlined assessments compress biosimilar time-to-market for European hospital formulary access. |
| Backward Integration | In-house chromatography resin supply mitigates single-source vulnerability and batch failure cascades. |
| Platform Integration | Digital twin implementation connects legacy quality systems to real-time release testing capabilities. |
| Strategic Partnership | Indian CDMO alliances enable Western developers to diversify capacity without facility construction. |
Research Methodology
A spread of perspectives from bioprocess engineering directors, regulatory affairs leads, hospital formulary directors, and payer access specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA filings, EMA assessment reports, ClinicalTrials.gov protocols, and CMS Medicare reimbursement databases. Bottom-up patient-flow modeling and top-down manufacturer revenue triangulation anchored volume and value estimates.
Segmentation dimensions modeled span product type, therapeutic application, delivery mode, and end-user channel across the projection horizon. CAGRs derive from treatment-line expansion rates, biosimilar penetration curves, and continuous bioprocessing adoption slopes. Forecast inputs incorporate specialty pharmacy network expansion trajectories and evolving glycan profiling regulatory requirements.
Decision-makers should treat outputs as directional under stable FDA-EMA regulatory convergence assumptions; material deviation would warrant model refresh. Forecasts reflect documented assumptions around chronic disease prevalence trends and hospital procurement consolidation patterns. Revision becomes warranted when continuous perfusion technology adoption crosses threshold penetration in mid-cap developer clusters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Anti-Infective Drugs Market
Biopharmaceuticals
Vaccine Ampoules Market
Biopharmaceuticals
Radiopharmaceutical Theranostics Market
Biopharmaceuticals
Isocitrate Dehydrogenase (IDH) Inhibitors Market
Biopharmaceuticals
Combination Antibody Therapy Market
Biopharmaceuticals
Gosling Plague Vaccine Market
Biopharmaceuticals
Biological Drugs Market
Biopharmaceuticals
Somatostatin Analogs Market
Biopharmaceuticals
Diabetes Drugs Market
Biopharmaceuticals
EPO Biomarkers Market
Biopharmaceuticals
Targeted Protein Degradation Market
Biopharmaceuticals
Global Levofloxacin Market
Biopharmaceuticals
Tamoxifen Market
Biopharmaceuticals
Thailand Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Insulin Market
Biopharmaceuticals
Vaccine Adjuvants Market