
 Biopreservation Market | 2026-2036
Biopreservation Market Size, Share, and Industry Trends Forecast 2026-2036
Biopreservation Market Analysis
Modular biopreservation platform configurations are expanding buyer choice across the biopreservation landscape. Thermo Fisher Scientific leverages integrated cold-chain ecosystems to anchor its position in high-complexity cell therapy logistics. Merck KGaA sustains technology leadership through specialized cryopreservation media formulations. BioLife Solutions differentiates with serum-free media platforms designed for regenerative medicine applications.
Biopreservation encompasses the stabilization of biological specimens through temperature-controlled environments, cryoprotective media formulations, and controlled-rate freezing protocols that maintain cellular viability below glass-transition temperatures. The practice preserves functional integrity of cells, tissues, and organs for downstream therapeutic, diagnostic, or research applications. Cryopreservation dominates product-type revenue due to irreplaceable utility in stem cell banking and advanced therapy manufacturing. Cell therapy application demand outpaces biomedical research growth as commercial-stage allogeneic programs scale. Freezing techniques technology leads in installed base while vitrification commands premium positioning for sensitive oocyte and embryo protocols.
FDA cellular therapy guidance and EMA ATMP quality documentation requirements shape product validation standards and cold-chain compliance burdens across the biopreservation supply base. ISO 20387 biobanking standards and WHO Biological Reference Materials frameworks further harmonize specimen traceability and quality management system expectations. Stakeholders must monitor evolving premarket review pathways for automated closed-system cryopreservation devices as regulatory convergence between jurisdictions accelerates qualification requirements.
Market Dynamics
Cell therapy commercialization is compressing biopreservation validation timelines as FDA and EMA tighten stability documentation requirements for autologous and allogeneic products. Cold-chain compliance costs now represent a structural barrier to market entry for mid-tier biobank operators.
Growth Catalysts
- EMA ATMP Guidelines:Harmonized quality documentation standards across European member states accelerate cross-border specimen transport and multi-site clinical trial enrollment.
- CAR-T Manufacturing Scale-Up:Commercial allogeneic programs demand standardized cryopreservation protocols that preserve T-cell functionality through thaw-wash cycles.
- ISO 20387 Adoption:Biobank accreditation requirements in Japan, Australia, and South Korea drive replacement of legacy manual freezing systems with controlled-rate devices.
Market Restraints
- Liquid Nitrogen Supply Concentration:Production of cryogenic-grade nitrogen concentrates in Gulf Coast industrial clusters, exposing biorepositories to price volatility and hurricane-related supply interruptions.
- Dimethyl Sulfoxide Toxicity Constraints:DMSO remains the dominant cryoprotectant despite documented patient adverse reactions, limiting formulation innovation for direct-infusion cell therapies.
- FDA Device Classification Uncertainty:Automated closed-system cryopreservation equipment awaits definitive 510(k) pathway clarification, delaying capital deployment by bioprocessing equipment purchasers.
Strategic Opportunities
- India Biobank Infrastructure:CDSCO's expanding cell therapy trial framework and the Department of Biotechnology's biorepository funding create first-mover advantages for cold-chain integrators.
- Vitrification-Oocyte Convergence:Fertility preservation demand intersects with advancing vitrification media formulations originally developed for embryonic stem cell applications.
- Digital Twin Cold-Chain Monitoring:Integration of IoT temperature loggers with blockchain traceability systems addresses WHO Biological Reference Materials documentation requirements for international specimen exchange.
Industry Challenges
- Cryobiology Talent Scarcity:Industrial-scale cell therapy manufacturing requires practitioners trained in both bioprocessing engineering and low-temperature biology, a hybrid skill set concentrated in Boston and San Diego academic centers.
- Legacy Equipment Integration:Biobanks operating mechanical freezers installed fifteen to twenty years ago face retrofit complexity when connecting to centralized monitoring and alarm systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biopreservation Market |
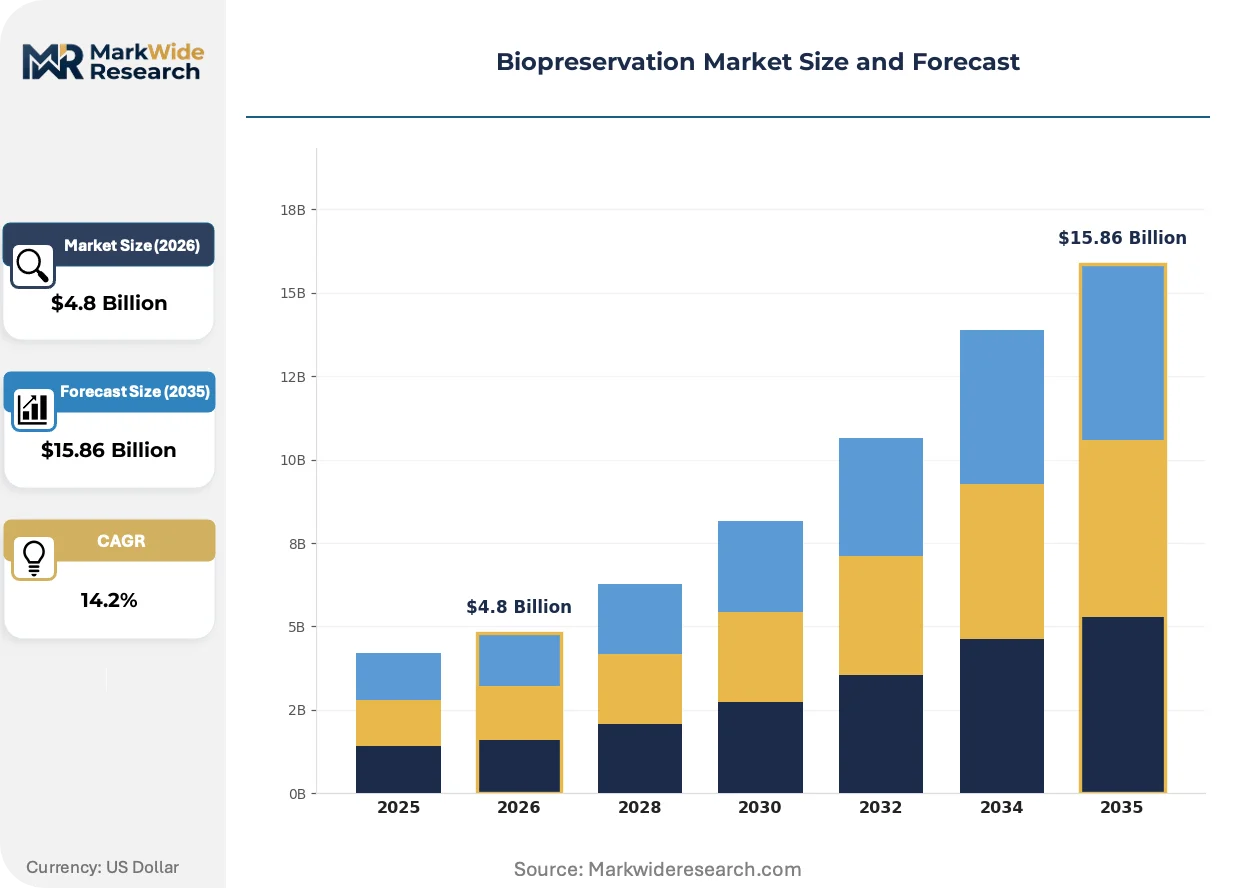
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cryopreservation, Cold Chain Storage, Biopreservation Media, Biobanking Application: Cell Therapy, Tissue Engineering, Biomedical Research, Drug Development End User: Pharmaceutical Companies, Biotech Firms, Research Institutes, Hospitals Technology: Freezing Techniques, Vitrification, Controlled Rate Freezing, Passive Cooling |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Azenta, BioLife Solutions, PHC Holdings Corporation, Panasonic Corporation, Biomatrica, BioCision, LabVantage Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biopreservation Market Emerging Trajectories
Automation is displacing manual cryopreservation workflows across cell therapy manufacturing suites. Three developments capture this transformation: closed-system processing, regulatory digitization, and procurement restructuring.
Closed-system automated cryopreservation devices are rewriting contamination risk profiles in GMP manufacturing environments. Cell therapy CDMOs adopt these systems at pilot scale before committing to commercial suite replication. This technology is compressing batch-to-batch variability and reducing open-phase exposure time from minutes to seconds.
REACH chemical registration requirements in Europe now cover novel cryoprotectant formulations entering the supply chain. Industrial consequence includes extended safety data package preparation for serum-free media alternatives. Allogeneic cell therapy developers targeting EU market access respond by qualifying dual-sourced cryoprotectant suppliers early in process development.
Biopharma procurement departments now unbundle cryopreservation media from equipment service contracts that previously locked buyers into single-vendor ecosystems. CDMOs and academic biobanks negotiate media pricing separately from controlled-rate freezer maintenance agreements. This pattern is most visible in United States regenerative medicine clusters where buyer concentration strengthens negotiation leverage.
Biopreservation Market Segmentation
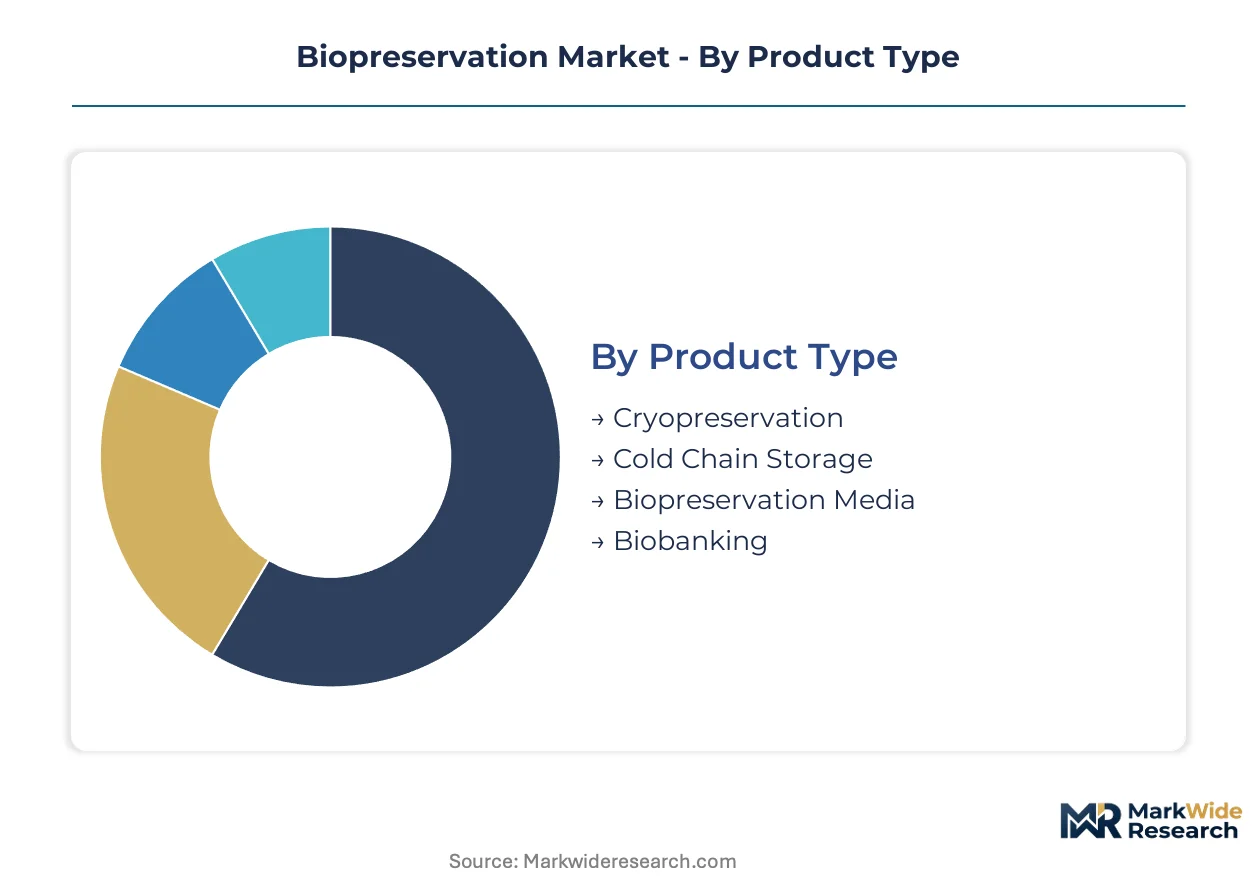
Biopreservation market segmentation reflects divergent capital requirements across temperature-controlled infrastructure, consumable formulations, and specialized equipment. Understanding these investment profiles enables buyers to align procurement strategies with operational scale and regulatory exposure.
Product Type:
Cryopreservation systems demand the heaviest upfront capital deployment, with controlled-rate freezers and liquid nitrogen infrastructure requiring seven-figure facility investments before operational clearance.
- Cryopreservation:Ultra-low temperature storage systems utilizing liquid nitrogen or mechanical cascade refrigeration maintain specimens below glass-transition thresholds. Demand concentrates in United States cell therapy manufacturing clusters around Boston and San Diego, driven by FDA stability documentation requirements for commercial-stage CAR-T products. Capital recovery timelines extend 5-7 years for biobank operators.
- Cold Chain Storage:Temperature-controlled transport and interim storage solutions bridge manufacturing sites and clinical administration points. Pharmaceutical companies in Germany and Switzerland deploy these systems to satisfy EMA ATMP cross-border distribution requirements, with compliance costs now representing a structural barrier for mid-tier operators.
- Biopreservation Media:Serum-free and chemically defined formulations stabilize cellular membranes during freeze-thaw cycles. Biotech firms prioritize DMSO-reduced alternatives to mitigate patient adverse reaction risks.
- Biobanking:Comprehensive specimen repository services encompass collection, processing, storage, and retrieval infrastructure. Research institutes in Japan and Australia drive adoption following ISO 20387 accreditation mandates.
Most installed capacity flows through Cryopreservation. Expansion is steepest in Biopreservation Media as serum-free formulations displace legacy DMSO-dependent protocols.
Application:
Application segmentation tracks divergent validation timelines, with commercial therapeutics demanding compressed qualification cycles compared to exploratory research programs.
- Cell Therapy:Autologous and allogeneic cellular product preservation requires GMP-compliant cryopreservation protocols that maintain viability through thaw-wash manufacturing steps. United States CDMOs anchor demand as allogeneic programs scale toward commercial manufacturing, with EMA quality documentation harmonization accelerating European site qualification.
- Tissue Engineering:Scaffold-seeded cellular constructs require specialized vitrification approaches to preserve three-dimensional architecture. Academic medical centers in South Korea and Singapore concentrate development activity, supported by national regenerative medicine funding initiatives.
- Biomedical Research:Specimen banking for longitudinal studies employs standardized freezing protocols with less stringent regulatory oversight than therapeutic applications. Research institutes balance cost constraints against ISO 20387 traceability requirements.
- Drug Development:Biomarker preservation and toxicology specimen archiving support regulatory submission packages. Pharmaceutical companies integrate biopreservation into centralized laboratory service contracts.
Cell Therapy commands the dominant revenue share. Tissue Engineering is gaining share fastest as organoid and engineered tissue platforms advance toward clinical translation.
End User:
End user segmentation reveals procurement sophistication gradients, with large pharmaceutical buyers unbundling media and equipment contracts while smaller operators accept bundled service arrangements.
- Pharmaceutical Companies:Global biopharma procurement departments negotiate cryopreservation media pricing separately from controlled-rate freezer maintenance agreements, leveraging buyer concentration in United States regenerative medicine clusters. These organizations maintain dedicated cold-chain compliance teams to navigate FDA and EMA stability documentation requirements.
- Biotech Firms:Venture-backed cell therapy developers outsource biopreservation validation to specialized CDMOs during early clinical phases. Boston and San Diego operators face talent scarcity for hybrid cryobiology-bioprocessing skill sets.
- Research Institutes:Academic biobanks balance accreditation compliance against legacy equipment retrofit constraints when connecting fifteen-year-old mechanical freezers to centralized monitoring systems.
- Hospitals:Clinical specimen preservation for diagnostic and therapeutic applications follows hospital-specific quality management protocols with variable adherence to ISO standards.
Pharmaceutical Companies deploy the most comprehensive infrastructure. Biotech Firms show the steepest adoption trajectory as allogeneic cell therapy financing rounds accelerate.
Technology:
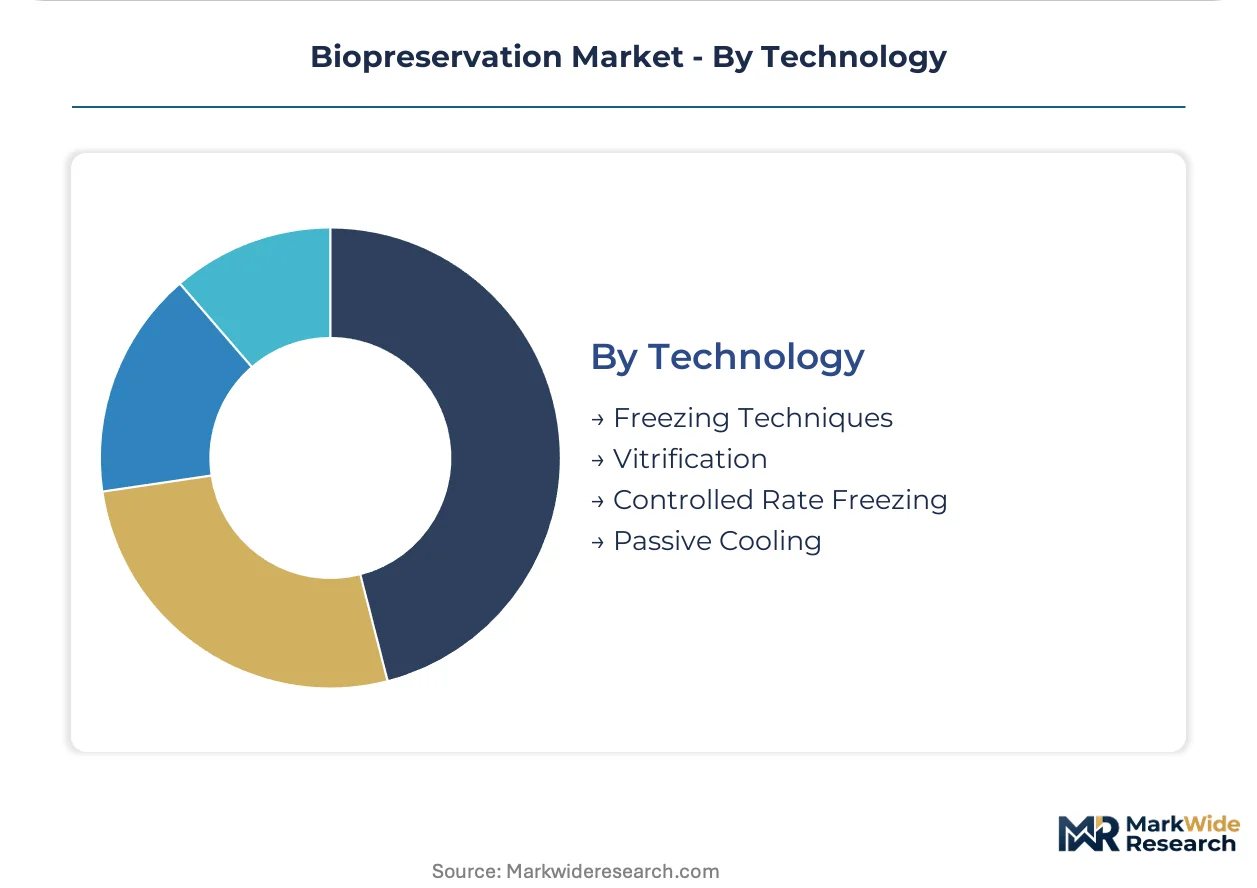
Technology segmentation distinguishes between established mechanical approaches and emerging vitrification platforms with premium positioning for sensitive biological materials.
- Freezing Techniques:Conventional slow-freeze protocols utilizing programmable rate controllers dominate installed base across biobank networks. These systems serve biomedical research applications where post-thaw recovery rates above 80% satisfy operational requirements without vitrification capital expenditure.
- Vitrification:Ultra-rapid cooling eliminates ice crystal formation through high-concentration cryoprotectant exposure and direct liquid nitrogen immersion. Fertility clinics in Spain and Czech Republic anchor demand for oocyte and embryo protocols, with media formulations originally developed for embryonic stem cell applications now cross-pollinating reproductive medicine.
- Controlled Rate Freezing:Automated programmable systems standardize cooling curves across batch operations. Biotech firms adopt these devices to reduce batch-to-batch variability in GMP manufacturing environments.
- Passive Cooling:Insulated container systems without active refrigeration serve short-duration transport and field collection scenarios. These solutions address last-mile distribution gaps in emerging market cold-chain infrastructure.
Freezing Techniques retain the largest installed footprint. Vitrification is climbing the fastest as fertility preservation demand intersects with advancing media formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cryogenic biopreservation infrastructure originated in United States academic medical centers during the 1950s, with liquid nitrogen storage systems first deployed for blood banking and reproductive tissue preservation. Industrial-scale commercialization followed three decades later as pharmaceutical cold-chain requirements formalized.
United States
FDA cellular therapy guidance drives demand for GMP-compliant cryopreservation validation as allogeneic CAR-T programs scale toward commercial manufacturing. The Department of Health and Human Services maintains biorepository quality standards through the National Institutes of Health. Boston and San Diego anchor regenerative medicine clusters where hybrid cryobiology-bioprocessing talent concentrates.
Germany
EMA ATMP quality documentation harmonization accelerates cross-border specimen transport for multi-site European clinical trials. REACH chemical registration requirements now cover novel cryoprotectant formulations entering the supply chain. Heidelberg and Munich biotech corridors host specialized CDMOs serving cell therapy developers.
Japan
ISO 20387 biobank accreditation mandates drive replacement of legacy manual freezing systems with controlled-rate devices in academic and hospital repositories. METI funding programs support regenerative medicine infrastructure under the national growth strategy. Tokyo and Osaka metropolitan areas concentrate biorepository investment.
Switzerland
Swissmedic stability documentation requirements for advanced therapy medicinal products shape validation standards for biopreservation service providers. The country's pharmaceutical manufacturing heritage supports specialized cold-chain logistics expertise. Basel and Zurich host biopreservation operations integrated with global biopharma headquarters.
India
CDSCO's expanding cell therapy trial framework and Department of Biotechnology biorepository funding create infrastructure opportunities for cold-chain integrators. National guidelines for stem cell research establish quality benchmarks for academic biobanks. Hyderabad and Bengaluru biotech clusters concentrate early-stage regenerative medicine development.
Biopreservation Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with full cold-chain ecosystem providers commanding pricing power over standalone equipment vendors. The market structure stratifies into three tiers: integrated platform suppliers, specialized media formulators, and regional equipment distributors. Consolidation pressure intensifies as cell therapy CDMOs demand single-source accountability for validation documentation. Dominant competitive moves include unbundling of media from equipment service contracts and geographic expansion into emerging biobank markets.
Within the integrated platform tier, Thermo Fisher Scientific exemplifies cold-chain ecosystem anchoring through combined equipment, media, and logistics capabilities. Merck KGaA and BioLife Solutions occupy positions as specialized media formulators, with the former representing diversified life science conglomerate structure and the latter exemplifying focused regenerative medicine positioning. These three entities illustrate the strategic divergence between breadth-driven and depth-driven competitive approaches.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Azenta |
| BioLife Solutions |
| PHC Holdings Corporation |
| Panasonic Corporation |
| Biomatrica |
| BioCision |
| LabVantage Solutions |
| Others |
Supply Flow & Price Mechanics
Liquid nitrogen spot pricing indices in Gulf Coast industrial corridors cascade through biopreservation supply tiers, compressing margins for mid-tier biobank operators while integrated platform suppliers capture premium positioning through captive cryogen sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by GMP certification grade and after-sales service bundling. FDA-validated controlled-rate freezer systems command substantial premiums over research-grade equipment. Pricing pressure stems from CDMO procurement departments unbundling media from equipment service contracts. Academic biobanks exhibit highest price sensitivity; pharmaceutical cold-chain compliance teams prioritize validation documentation over unit cost.
Supply Chain Analysis
Cryobiology-trained bioprocessing engineers concentrate in Boston and San Diego academic centers, constraining manufacturing scale-up for automated closed-system device producers. Cryogenic-grade nitrogen production anchors in United States Gulf Coast clusters, with mechanical freezer components sourcing from German and Japanese precision manufacturing bases. Single-source vulnerability runs through concentrated liquid nitrogen supply nodes exposed to hurricane disruption. Distribution runs through specialized cold-chain logistics integrators serving cell therapy CDMO networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory ratchet effects, with FDA cellular therapy guidance and EMA ATMP quality documentation tightening validation standards that lock in incumbent equipment refresh cycles.
For Market Incumbents: Extend platform ecosystem control by integrating IoT-enabled temperature monitoring with blockchain traceability documentation. Consolidate position through backward integration into serum-free cryoprotectant formulation capacity. Defend against unbundling pressure by embedding predictive maintenance algorithms that raise switching costs for CDMO buyers. For New Entrants and Emerging Players: CDSCO's expanding cell therapy trial framework in India opens a window for cold-chain infrastructure partnerships with academic biobanks and early-stage allogeneic developers. Target ISO 20387 accreditation-driven equipment replacement cycles in Japan and Australia. Enter through automated closed-system devices that compress batch-to-batch variability below incumbent manual protocol thresholds. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized media formulators possessing serum-free DMSO-reduced platforms and regulatory master files in place. Long-term viability hinges on qualification depth for commercial-stage cell therapy supply rather than research specimen volume. Monitor FDA 510(k) pathway clarification for automated cryopreservation devices as inflection signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Master File Investment | FDA Drug Master Files for cryoprotectant formulations accelerate partner qualification timelines for allogeneic programs. |
| Closed-System Automation Deployment | GMP-compliant automated cryopreservation devices reduce open-phase exposure from minutes to seconds in manufacturing suites. |
| Dual-Sourcing Qualification | REACH compliance drives early qualification of secondary cryoprotectant suppliers for EU market access. |
| Digital Twin Integration | IoT temperature loggers with blockchain traceability satisfy WHO Biological Reference Materials documentation requirements. |
| Geographic Expansion into India | CDSCO cell therapy frameworks and DBT biorepository funding create first-mover infrastructure advantages. |
Methodological Framework
Coverage spans United States, Germany, Japan, Switzerland, and India, with primary inputs from each market cluster combining structured interviews with cell therapy manufacturing executives, biobank operations directors, regulatory affairs specialists, and CDMO procurement leads. Secondary validation draws from FDA guidance documents, EMA ATMP quality guidelines, ISO 20387 accreditation records, and clinical trial registry filings. Bottom-up equipment installation data triangulates against top-down pharmaceutical cold-chain expenditure estimates.
Rate-of-change decomposition separates volume expansion from value-per-unit shifts across the projection horizon. Segmentation dimensions encompass product type, application, end user, and technology tier, with regional regulatory cluster and GMP compliance level as cross-cutting variables. CAGR derivation rests on installed base replacement cycles, accreditation mandate timelines, and commercial-stage cell therapy pipeline progression. Industry-specific inputs include cryoprotectant formulation switching rates and automated device adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA device classification delays or sustained liquid nitrogen supply disruption. Forecasts reflect assumptions regarding regulatory convergence pace and allogeneic program financing continuity. Material deviation in EMA-FDA guidance harmonization or cryogen infrastructure investment warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Global GMO Testing Market
Food Biotechnology
Bovine Colostrum Market
Food Biotechnology
Pullulanase Market
Food Biotechnology
Europe Eubiotics Market
Food Biotechnology
Fruit and Vegetable-Derived Enzymes Market
Food Biotechnology
Phycocyanin Market
Food Biotechnology
Trypsin Market
Food Biotechnology
Brown Algae Protein Market
Food Biotechnology
Salmon Polynucleotide (PN) Market
Food Biotechnology
Biotech Flavors Market
Food Biotechnology
Global Feed Enzymes Market
Food Biotechnology
North America Eubiotics Market
Food Biotechnology
Genistein Market
Food Biotechnology
Lupin Protein Market
Food Biotechnology
Red Seaweed Extract Market
Food Biotechnology
Asia Pacific Eubiotics Market