
 Global Genetically Modified (GMO) Food Market | 2026-2036
Global Genetically Modified (GMO) Food Market Size, Share, and Industry Trends Forecast 2026-2036
Global Genetically Modified (GMO) Food Market Intelligence
Wholesale markets and direct-to-farmgate sales channels for GMO seeds are rewriting traditional agricultural supply chains. Bayer AG dominates the market with its extensive portfolio of herbicide-tolerant corn and soybean seeds. Corteva Agriscience leverages its strong R&D in insect-resistant traits to secure market share. Syngenta AG competes through its focus on developing climate-resilient crop varieties for diverse agricultural regions like India and Brazil.
Genetically modified food originates from organisms whose DNA has been altered through techniques not found in nature, such as recombinant DNA technology. The primary purpose is to confer specific traits like enhanced yield or resistance to pests and environmental stressors. Herbicide tolerance and insect resistance remain the most commercially significant traits, particularly within high-volume crops. Corn and soybean product types constitute the largest segments, driven by their extensive use in animal feed and processed foods.
Regulatory frameworks create significant market access hurdles and influence consumer perception. In the United States, the FDA oversees safety assessments, while the European Food Safety Authority (EFSA) enforces stringent evaluation and mandatory labeling under EU rules. Navigating these divergent international regulations, including those from Brazil's ANVISA, is a critical competency for market participants. The key decision for developers centers on balancing trait innovation with the public acceptance and regulatory costs in target markets.
Market Dynamics
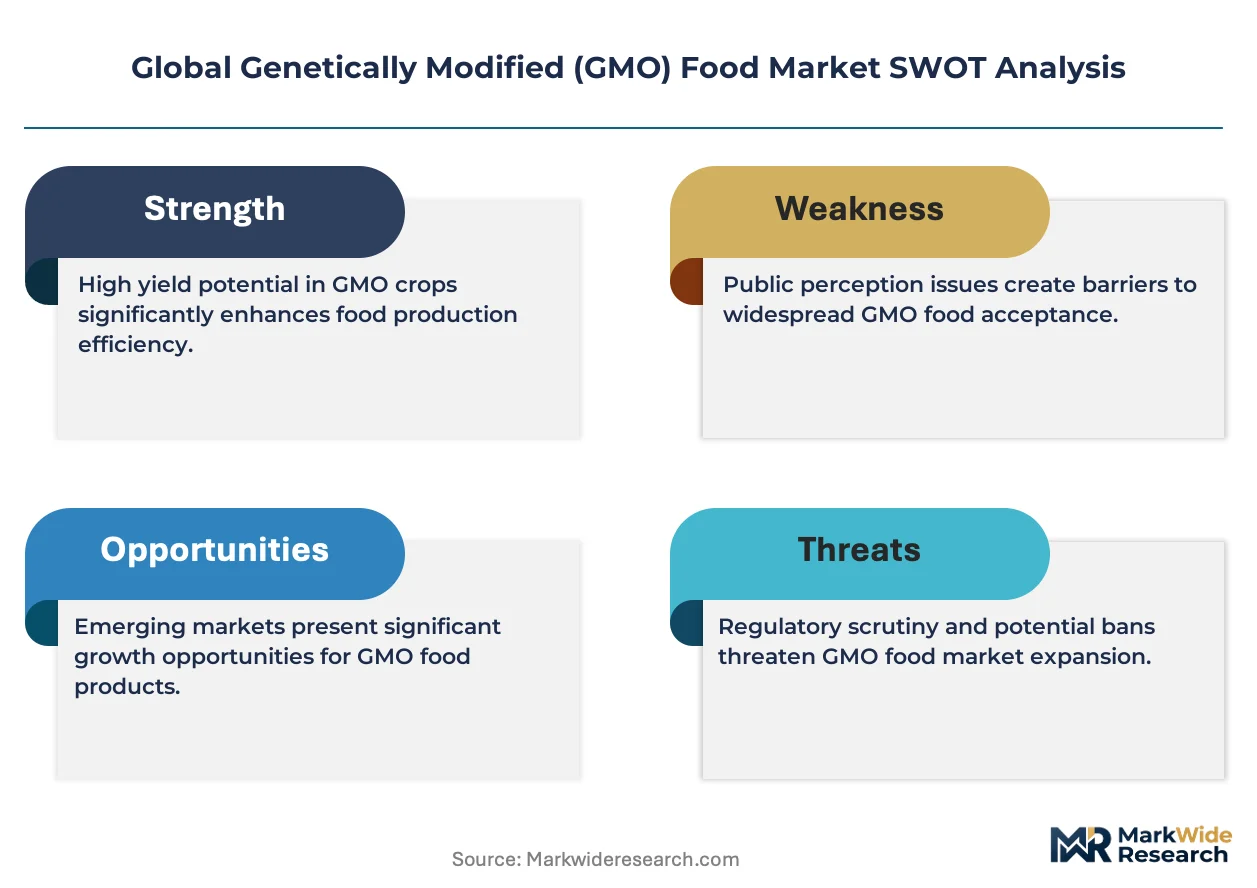
The central structural force shaping the market is the tension between rapid gene-editing innovation, led by technologies like CRISPR, and the fragmented, often contradictory, landscape of international regulations. This dynamic dictates market access, R&D investment priorities, and public acceptance strategies.
Growth Catalysts
- Advanced Gene Editing:The emergence of precise technologies like CRISPR-Cas9 accelerates the development of crops with desirable traits, such as drought tolerance or enhanced nutritional value, reducing R&D timelines compared to traditional methods.
- Biofuel and Feed Demand:Sustained demand for animal feed and biofuels, particularly in agricultural economies like Brazil and the United States, drives large-scale cultivation of high-yield genetically modified corn and soybeans.
- Climate Resilience:The development of climate-resilient crop varieties is a significant catalyst, addressing agricultural challenges like water scarcity and soil salinity in diverse regions, including India and parts of Africa.
Market Restraints
- Stringent EU Regulations:The European Food Safety Authority (EFSA) enforces strict evaluation and mandatory labeling requirements, which act as a significant market access barrier and increase compliance costs for producers targeting the European Union.
- Public Perception and Acceptance:Negative consumer perception and organized opposition in certain regions lead to political and commercial resistance, necessitating costly public relations and educational campaigns to gain market acceptance.
- Intellectual Property Costs:The high cost of licensing patented seed traits from dominant technology holders creates a significant financial barrier for smaller companies and public research institutions, limiting competition and innovation.
Strategic Opportunities
- Nutritional Enhancement:There is a significant opportunity in developing biofortified crops with enhanced nutritional profiles, such as vitamins or minerals, directly targeting consumer health benefits beyond traditional agronomic traits.
- Pharmaceutical and Industrial Applications:Genetically modified plants can be engineered to produce high-value pharmaceutical proteins, antibodies, and industrial enzymes, opening a new, non-food revenue stream known as molecular farming.
- Expansion in Developing Nations:Introducing pest-resistant and drought-tolerant staple crops in underpenetrated agricultural regions across Africa and Southeast Asia presents a major opportunity to address food security challenges and build new markets.
Industry Challenges
- Supply Chain Segregation:Maintaining identity preservation through segregated supply chains to keep GMO and non-GMO crops separate is a major logistical and financial challenge, adding complexity and cost from farm to final product.
- Asynchronous Regulatory Approvals:The lack of harmonized international regulations results in asynchronous approval timelines across key markets like the US, EU, and Brazil, creating trade disruptions and commercial uncertainty for new products.
- Complex Trait Stacking:Integrating multiple genetic traits (trait stacking) into a single seed variety involves complex breeding and intellectual property negotiations, posing a significant technical and legal challenge for developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Genetically Modified (GMO) Food Market |
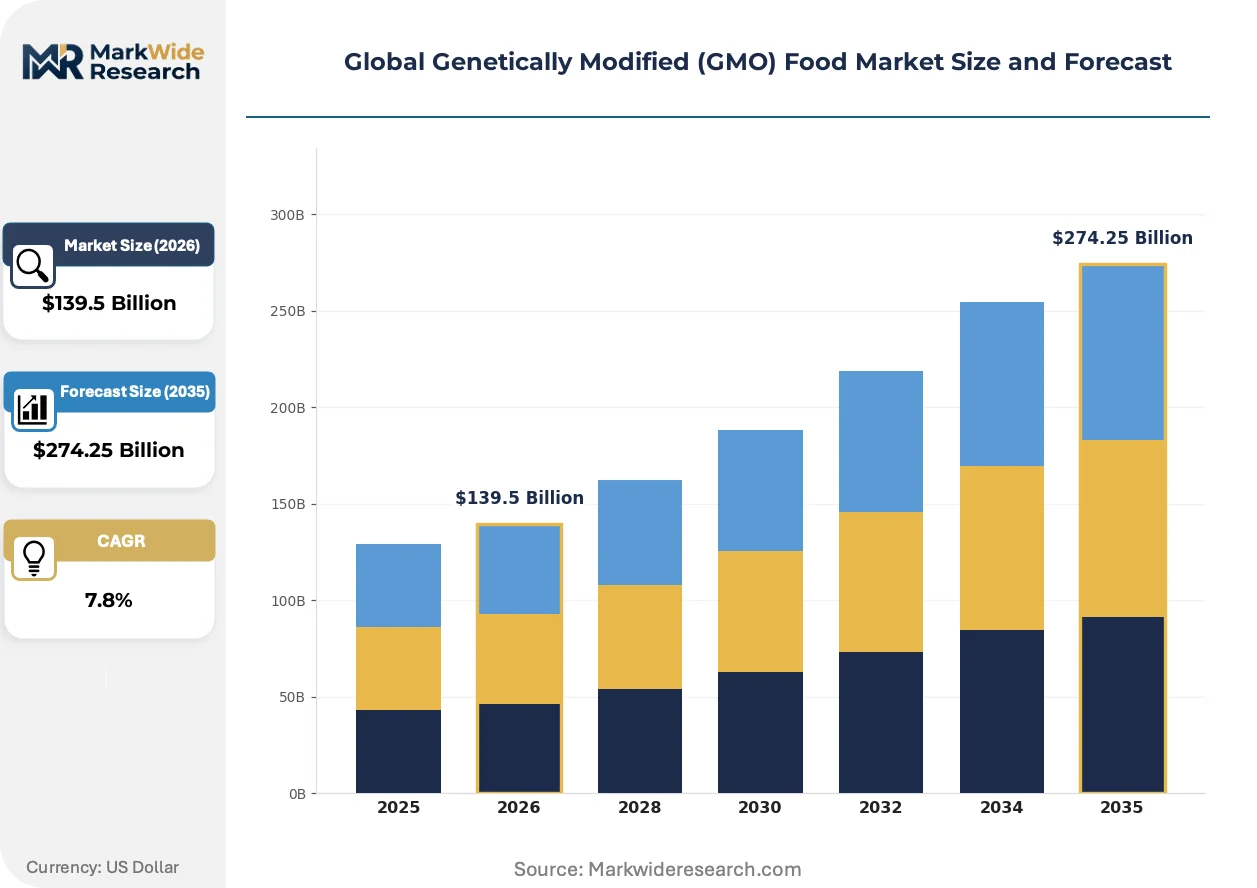
| Market Size in 2026 | $139.5 Billion |
| Market Size in 2035 | $274.25 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corn, Soybean, Cotton, Canola, Sugar Beet, Papaya Trait: Herbicide Tolerance, Insect Resistance, Virus Resistance, Drought Resistance, Nutritional Enhancement, Delayed Ripening End User: Food Processing Companies, Feed Manufacturing Firms, Biotechnology Firms, Research Institutions, Exporters Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Wholesale Markets, Food Service Providers |
| Companies Covered | BASF SE, Pioneer Hi-Bred International, Bayer AG, Groupe Limagrain, Seminis, Corteva Agriscience, DuPont, KWS SAAT SE, Syngenta AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Genetically Modified (GMO) Food Market Strategic Shifts & Innovations
A fundamental shift is underway from developing crops with input traits, such as herbicide tolerance, toward creating products with tangible output traits like improved nutrition and climate resilience. This pivot is enabled by new breeding techniques that offer greater precision and speed.
Gene Editing Accelerates Trait Development
Precise gene-editing tools, particularly CRISPR-Cas9, allow for targeted DNA modifications to enhance crop traits without necessarily introducing foreign genetic material. Agricultural biotechnology firms and academic research centers are rapidly adopting this method for its efficiency and accuracy. This powerful technology is collapsing the traditional development cycle, dramatically shortening the time between identifying a beneficial trait and creating a commercially viable seed.
Evolving Regulatory Classifications
Regulatory bodies are beginning to differentiate between traditional transgenics and products of newer gene-editing techniques. The European Union's proposed framework, for instance, may exempt certain plants developed with New Genomic Techniques (NGEs) from the stringent rules applied to legacy GMOs. This policy evolution could create a more streamlined path to market for specific bioengineered crops. Developers focusing on climate adaptation and nutritional improvement are most affected, as they re-evaluate market entry strategies for Europe.
Traceability Demands Reshape Sourcing
Heightened consumer and regulatory demand for supply chain traceability and verifiable sustainability claims is altering procurement patterns. This is moving the market away from undifferentiated commodity purchasing toward more direct-to-farm or identity-preserved sourcing models. Food manufacturers and retailers are increasingly establishing segregated channels to substantiate specific claims like non-GMO. This trend is most pronounced in the consumer-facing processed food and retail grocery sectors of North America and Europe.
Global Genetically Modified (GMO) Food Market Segmentation
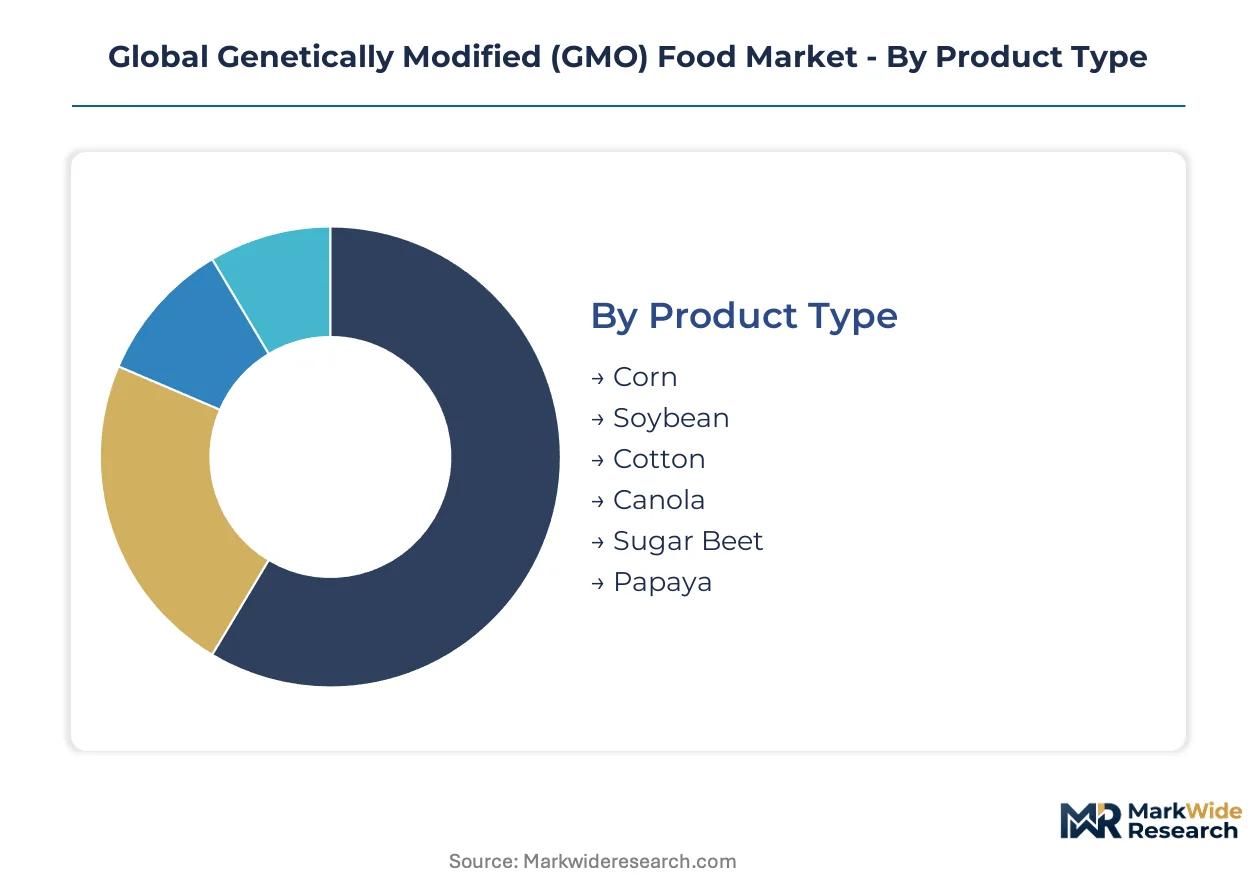
The Global Genetically Modified (GMO) Food Market categorizes its offerings to reflect the diverse applications and underlying technologies driving agricultural innovation. Understanding these segments clarifies market dynamics and investment priorities for developers and consumers alike. This segmentation highlights the various forms and functions of bioengineered crops.
Product Type:
The use-case spectrum for GMO products extends from staple food commodities to specialized industrial crops, each serving distinct market needs.
- Corn:Genetically modified corn varieties, primarily engineered for herbicide tolerance and insect resistance, represent a cornerstone of global animal feed production. Sustained demand from livestock industries in the United States and Brazil drives extensive cultivation.
- Soybean:GMO soybeans, predominantly herbicide-tolerant, are a critical source of protein for animal feed and vegetable oil for processed foods. Their widespread adoption in agricultural powerhouses like Brazil and Argentina underpins global food supply chains.
- Cotton:Bioengineered cotton varieties primarily feature insect resistance, reducing pesticide use and improving yields for textile manufacturing.
- Canola:Genetically modified canola is widely cultivated for its oil, which is used in cooking and food processing, often incorporating herbicide-tolerant traits.
- Sugar Beet:Herbicide-tolerant sugar beet varieties streamline cultivation and enhance sugar production efficiency in regions like North America.
- Papaya:Virus-resistant papaya varieties offer a solution to devastating plant diseases, ensuring crop viability in affected tropical regions.
The dominant share belongs to Corn, while Soybean is closing the gap fastest.
Trait:
The application focus for GMO traits ranges from agronomic advantages that boost farm productivity to quality enhancements benefiting consumers and processors.
- Herbicide Tolerance:This trait allows crops to withstand specific herbicides, enabling more efficient weed control and reducing manual labor for farmers. High-volume crops such as corn and soybean extensively utilize this genetic modification across global agricultural landscapes.
- Insect Resistance:Crops engineered with insect resistance produce proteins toxic to specific pests, significantly reducing crop damage and the need for chemical insecticides. This trait is crucial for protecting staple crops like cotton and corn from devastating insect infestations.
- Virus Resistance:Genetic modifications confer immunity to certain plant viruses, safeguarding crop yields and quality.
- Drought Resistance:These traits enable crops to better tolerate arid conditions, offering resilience in water-stressed agricultural regions.
- Nutritional Enhancement:Biofortified crops are engineered to possess increased levels of essential vitamins or minerals, addressing dietary deficiencies.
- Delayed Ripening:This trait extends the shelf life of fruits and vegetables, reducing post-harvest losses and improving marketability.
Herbicide Tolerance holds the largest segment, with Nutritional Enhancement demonstrating the steepest expansion trajectory.
End User:
Customer type in the GMO food market spans the entire value chain, from primary processors to specialized research entities, each driving distinct demand patterns.
- Food Processing Companies:These entities utilize GMO ingredients, primarily corn and soybean, for a wide array of processed food products, leveraging their cost-effectiveness and consistent supply. Their demand underpins the large-scale cultivation of commodity GMO crops.
- Feed Manufacturing Firms:Animal feed producers represent a substantial end-user segment, relying heavily on GMO corn and soybean meals for their protein and energy content. This sector's consistent need for high-volume, cost-efficient inputs drives significant market demand.
- Biotechnology Firms:These companies develop and commercialize new GMO traits and seeds, often acting as both innovators and suppliers within the market.
- Research Institutions:Universities and government research bodies conduct foundational and applied research into new GMO traits and applications.
- Exporters:Trading companies facilitate the international movement of GMO commodities, connecting producers in surplus regions with consumers globally.
Food Processing Companies exert the most significant market influence, while Biotechnology Firms are consistently broadening their scope.
Distribution Channel:
The volume and reach of distribution channels for GMO foods vary significantly, reflecting diverse consumer access points and supply chain complexities.
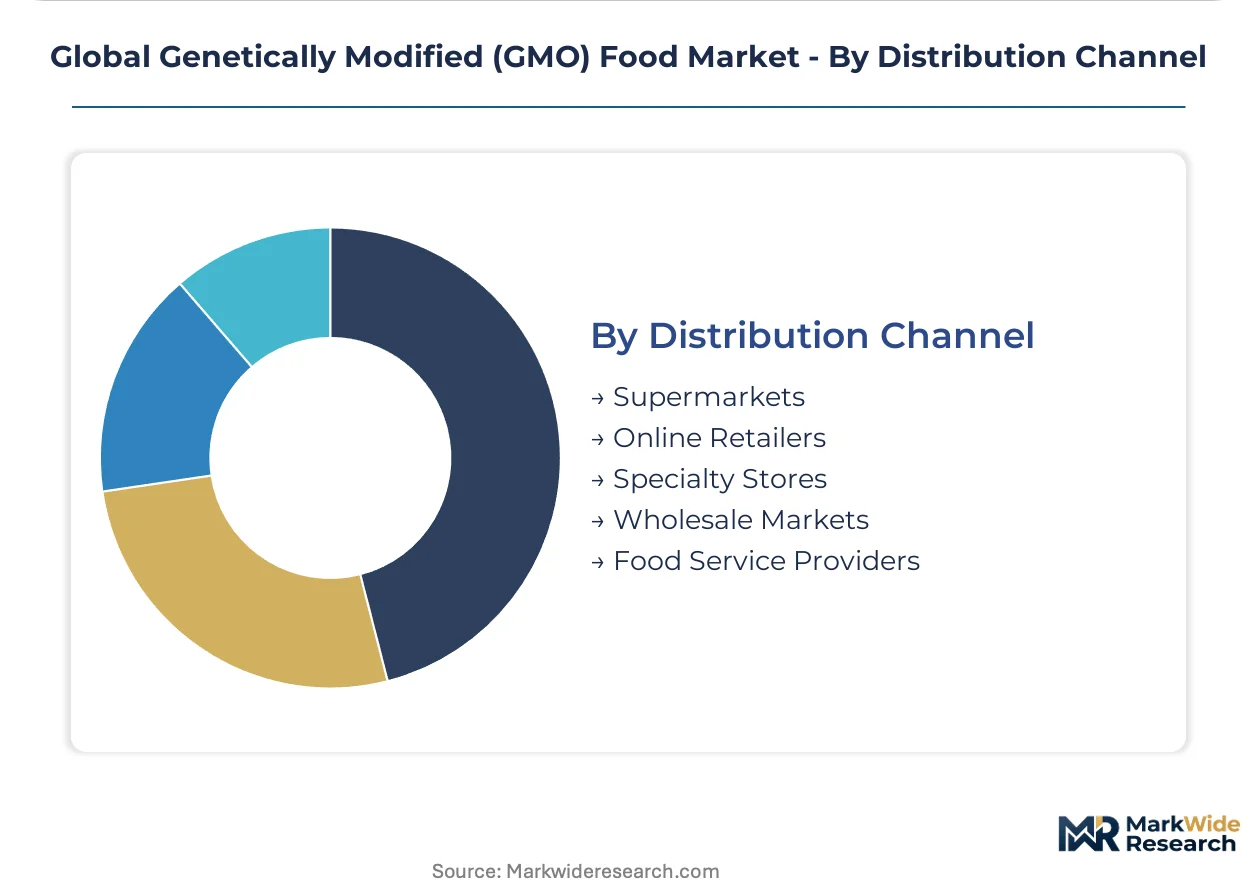
- Wholesale Markets:These channels serve as primary conduits for bulk GMO commodities, such as corn and soybeans, moving large volumes from producers to industrial users like feed manufacturers and food processors. This segment facilitates large-scale trade and supply chain efficiency.
- Food Service Providers:Restaurants, cafeterias, and institutional kitchens represent a significant demand segment for processed foods containing GMO ingredients. Their procurement patterns influence the types and quantities of GMO products entering the commercial food sector.
- Supermarkets:Retail grocery chains offer a wide selection of packaged foods, some of which contain GMO ingredients, directly to consumers.
- Online Retailers:E-commerce platforms provide a growing channel for specialty GMO products or processed foods to reach consumers directly.
- Specialty Stores:These outlets often cater to niche markets, potentially including specific GMO-derived products or ingredients.
Wholesale Markets command the largest volume, with Online Retailers rapidly expanding their reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The extensive rail and port network across the United States underpins its role as a major exporter of genetically modified agricultural commodities. This infrastructure facilitates the global distribution of high-volume crops like corn and soybeans. The nation's agricultural sector benefits significantly from advanced biotech crop development.
United States
Demand for high-yield corn and soybean varieties drives the US market. The USDA and FDA oversee the safety assessment and commercialization of GMO crops. Research and development in St. Louis, Missouri, a hub for agricultural biotechnology, accelerates new trait development.
Brazil
Brazilian agricultural expansion depends on large-scale cultivation of GMO soybeans and corn for export and animal feed. ANVISA regulates the approval and commercial release of genetically modified organisms in Brazil. Mato Grosso, a key agricultural state, concentrates vast areas of GMO crop production.
India
Cotton cultivation and potential future food security needs drive India's interest in GM crops. The Genetic Engineering Appraisal Committee (GEAC) within India's Ministry of Environment, Forest and Climate Change approves GM crop releases. Research institutes in Hyderabad focus on developing climate-resilient GM varieties.
Argentina
Argentina's role as a major global agricultural exporter relies heavily on GMO soybean and corn production. The National Advisory Commission on Agricultural Biotechnology (CONABIA) evaluates and approves GM crops. The Pampas region, a vast fertile plain, represents the heartland of GM crop cultivation.
France
Despite stringent regulations, French food processing companies utilize imported GMO ingredients for animal feed. The European Food Safety Authority (EFSA) sets strict evaluation and labeling standards for GM products within the EU. Research centers in Toulouse explore advanced gene-editing applications for crop improvement.
Global Genetically Modified (GMO) Food Market Key Industry Players
On the supply side, the industry is largely consolidated among a few multinational agricultural technology firms. These dominant players control extensive intellectual property portfolios for key genetic traits. Strategic archetypes include integrated seed and chemical providers, as well as specialized gene-editing innovators. Dominant competitive moves involve significant R&D investments and strategic acquisitions of smaller biotech firms.
Within the integrated seed and chemical provider archetype, Bayer AG and Syngenta AG exemplify companies with broad portfolios spanning crop protection and seed technologies. Corteva Agriscience occupies a similar position, anchoring its strategy on extensive research and development in insect-resistant traits. These firms collectively represent the established market leadership in high-volume genetically modified crops, influencing global agricultural practices and seed supply chains. Their extensive distribution networks, global reach, and intellectual property holdings underscore their significant market influence across diverse agricultural regions. These companies often engage in licensing agreements, further cementing their positions within the broader agro-biotechnology ecosystem.
| Leading Market Players |
|---|
| BASF SE |
| Pioneer Hi-Bred International |
| Bayer AG |
| Groupe Limagrain |
| Seminis |
| Corteva Agriscience |
| DuPont |
| KWS SAAT SE |
| Syngenta AG |
| Others |
Cost & Logistics Intelligence
Capacity utilization in key agricultural regions like Brazil and the United States drives seed supplier behavior. High demand for genetically modified corn and soybean varieties influences pricing postures for agricultural inputs.
Pricing Analysis
Volume-based contract pricing structures dominate the GMO seed market, reflecting large-scale agricultural procurement. Price differentiation stems from the specific genetic traits offered, seed volume, and bundled technical support services. Pricing pressure arises from farmers seeking to optimize input costs for commodity crops. Small-scale farmers exhibit higher price sensitivity compared to large food processing companies and feed manufacturers.
Supply Chain Analysis
International trade regulations and varying national biosafety protocols significantly limit the cross-border flow of genetically modified seeds. Global supply concentration centers on agricultural powerhouses like the United States, Brazil, and Argentina. Raw material dependencies include patented genetic traits and advanced seed treatment chemicals. Asynchronous regulatory approvals across key markets pose a structural supply chain risk. Distribution runs through wholesale markets and direct-to-farmgate channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The genetically modified food market offers a defensive moat, underpinned by significant regulatory entrenchment for approved traits and technologies. This structural advantage provides long-term stability for established players.
For Market Incumbents:Build intellectual property moats through continuous R&D investment in advanced gene-editing technologies like CRISPR. Strategic acquisitions of smaller biotech firms can consolidate novel trait pipelines, mitigating the threat from emerging competitors. Deepen regulatory expertise to navigate stringent international frameworks, particularly those from the European Food Safety Authority. This approach reinforces market dominance against evolving public perception challenges.
For New Entrants and Emerging Players:Pursue niche applications within the GMO market, focusing on biofortified crops for nutritional enhancement. Opportunities exist in developing nations across Africa and Southeast Asia, where demand for drought-tolerant staple crops is significant. Molecular farming, producing high-value pharmaceutical proteins, represents another penetrable segment. A go-to-market angle emphasizing climate resilience and direct consumer health benefits can differentiate offerings.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among integrated seed and chemical providers with extensive intellectual property portfolios. Long-term viability in this market hinges on addressing global food security and climate change challenges. Acquisition targets should include specialized gene-editing innovators or firms with proven success navigating diverse regulatory landscapes, particularly in emerging markets. The evolution of EU regulatory classifications for New Genomic Techniques is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Gene Editing | Advances crop traits like drought tolerance, accelerating new product development for Syngenta AG. |
| Regulatory Affairs Investment | Navigates complex international regulations, securing market access for Bayer AG products. |
| Biofortification Program | Develops crops with enhanced nutritional profiles, addressing dietary deficiencies in developing nations. |
| Molecular Farming Expansion | Creates new revenue streams by producing high-value pharmaceutical proteins from plants. |
| Supply Chain Segregation Technology | Ensures identity preservation for GMO and non-GMO crops, meeting consumer traceability demands. |
Research Approach
Desk research of academic journals, government agricultural reports, and corporate financial filings preceded structured interviews with biotechnology firm executives, agricultural scientists, food processing company procurement managers, and regulatory officials. This primary data collection was validated through secondary sources, employing both bottom-up and top-down triangulation. The approach ensured comprehensive market understanding.
Assumptions regarding technological advancements and regulatory stability were held fixed across the analysis window, while market penetration rates were varied. The analytical framework modeled segmentation dimensions including product type, trait, end user, distribution channel, and regional regulatory environment. Compound annual growth rates were derived from historical trends and future projections. Key inputs included crop yield data and R&D pipeline progress.
Macroeconomic conditions sit as an overlay; deviation in global commodity prices or trade policies would shift the trajectory. Forecasts reflect documented assumptions, but geopolitical trade disputes and climate change impacts represent risk factors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Non-Animal Alternative Testing Market
Food Biotechnology
Apigenin Market
Food Biotechnology
Global GMO Testing Market
Food Biotechnology
Bangladesh Starch and Starch Derivative Market
Food Biotechnology
Cultured Meat Market
Food Biotechnology
Trypsin Market
Food Biotechnology
Genistein Market
Food Biotechnology
Prebiotics Market
Food Biotechnology
Flaxseed Gum Market
Food Biotechnology
Trans-Galactooligosaccharides Market
Food Biotechnology
Red Seaweed Extract Market
Food Biotechnology
Salmon Polynucleotide (PN) Market
Food Biotechnology
Hemoglobin Feed Market
Food Biotechnology
Beta-Propeller Phytases Market
Food Biotechnology
Carbohydrate Enzyme Preparation Market
Food Biotechnology
Asia Pacific Eubiotics Market