
 Beta Lactoglobulin Protein Market | 2026-2036
Beta Lactoglobulin Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Beta Lactoglobulin Protein Market Analytics
Plant-derived and fermentation-based protein isolates is rebalancing raw material economics for beta lactoglobulin suppliers. Perfect Day leverages precision fermentation to decouple production from dairy herd cycles. Arla Foods anchors its position through backward integration into whey fractionation across Northern European facilities. Glanbia plc differentiates via clinical-grade isolate output targeting medical nutrition channels.
Beta lactoglobulin constitutes the dominant whey protein fraction, comprising approximately 50% of total bovine whey protein content with a molecular weight near 18.4 kDa and a primary structure rich in essential amino acids including leucine and cysteine. Industrial applications exploit its emulsification capacity, gelling behavior, and nutritional completeness across formulated foods and specialized nutrition products. The isolate category commands premium positioning due to superior protein content exceeding 90% and minimal lactose residue, while hydrolysate forms attract enzymatic pre-digestion demand from infant formula manufacturers. Nutritional supplements occupy the largest application volume pool, though food and beverage integration accelerates as clean-label protein fortification expands beyond traditional sports positioning.
FDA GRAS determinations and EFSA novel food evaluations govern market access for non-dairy derived beta lactoglobulin variants, with pathway complexity varying by production method. ISO 22000 and FSSC 22000 certifications function as baseline commercial requirements for ingredient supply to multinational food manufacturers. Stakeholders must monitor evolving precision fermentation regulatory frameworks across multiple jurisdictions to anticipate competitive entry timelines and labeling obligations.
Market Dynamics
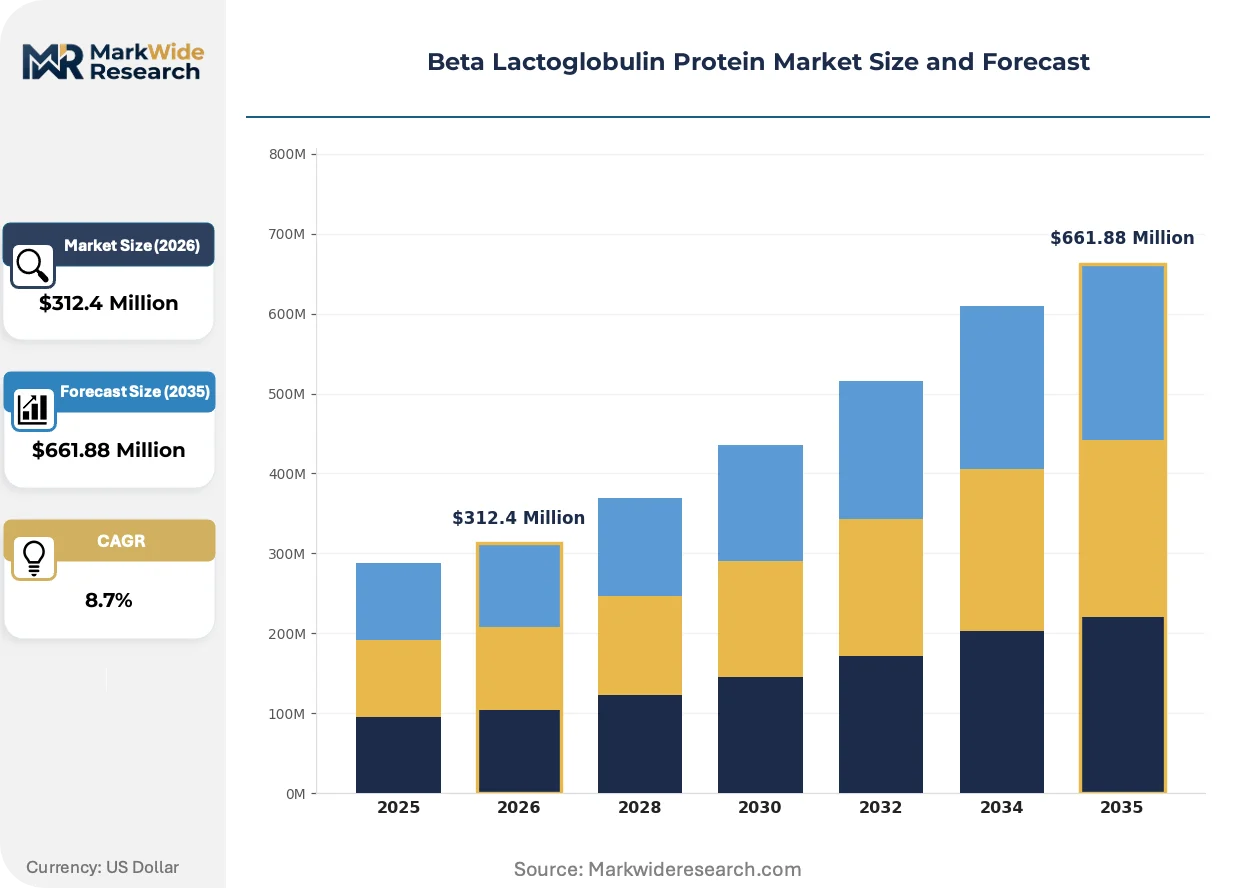
Precision fermentation technology is compressing production timelines and decoupling beta lactoglobulin supply from dairy herd volatility, fundamentally restructuring raw material economics and competitive entry barriers.
Growth Catalysts
- FDA GRAS pathway expansion:Novel food ingredient approvals for fermentation-derived proteins accelerate commercialization timelines for precision fermentation entrants targeting sports nutrition channels.
- Sports nutrition formulation demand:Fitness-oriented consumers in the United States prioritize high-purity isolates, pulling volume through clean-label protein fortification programs.
- EFSA novel food harmonization:Streamlined safety evaluations across European member states reduce regulatory fragmentation for whey fractionation suppliers seeking cross-border market access.
Market Restraints
- Input cost volatility:Dairy feed price fluctuations transmit directly to traditional whey fractionation economics, squeezing margin structures for extraction-dependent suppliers.
- Supply concentration risk:Northern European whey processing clusters dominate isolate output, creating geographic vulnerability to energy cost shocks and logistics disruptions.
- Regulatory friction:Divergent labeling requirements between FDA GRAS determinations and EFSA novel food categories force dual-track compliance investments for multi-territory suppliers.
Strategic Opportunities
- Medical nutrition channel expansion:Clinical-grade isolate specifications for enteral and parenteral nutrition products command premium positioning above commodity sports nutrition tiers.
- Infant formula hydrolysate demand:Enzymatic pre-digestion formats attract formulation investments from pediatric nutrition manufacturers seeking reduced allergenicity profiles.
- Clean-label food integration:Bakery and beverage applications beyond traditional sports positioning open volume pools as protein fortification penetrates mainstream grocery channels.
Industry Challenges
- Precision fermentation scale-up complexity:Bioreactor capacity expansion demands specialized biochemical engineering talent scarce outside established pharmaceutical bioprocessing hubs.
- ISO 22000 certification timelines:Multinational food manufacturer supply qualifications require 18-24 month audit cycles, delaying revenue recognition for new production facilities.
- IP licensing fragmentation:Strain engineering patents and downstream processing know-how distribute across academic institutions and biotech startups, complicating freedom-to-operate assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beta Lactoglobulin Protein Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolysate, Isolate, Concentrate, Native Application: Food & Beverage, Nutritional Supplements, Infant Formula, Animal Nutrition End User: Health Conscious Consumers, Fitness Enthusiasts, Athletes, Manufacturers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Arla Foods, Cargill Inc., Perfect Day, Glanbia plc, Kerry Group plc, Vivici, Fonterra Co-operative Group Limited, FrieslandCampina N.V., 21st.BIO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beta Lactoglobulin Protein Market Evolving Landscape
Bioprocessing advances and regulatory modernization are converging to accelerate non-dairy protein production, while downstream formulation science unlocks application versatility beyond legacy sports nutrition positioning.
Precision fermentation platforms utilizing microbial chassis for recombinant beta lactoglobulin expression is electrifying competitive dynamics across the ingredient supply base. Contract development and manufacturing organizations in Denmark and the Netherlands are expanding bioreactor fleets to capture pharmaceutical-grade production expertise. This technology is compressing capital recovery timelines and enabling supply security commitments independent of climatic or herd-cycle disruptions.
EFSA novel food evaluation frameworks are tightening safety documentation requirements for fermentation-derived proteins entering European markets. The industrial consequence is elevated toxicology study burdens and extended approval timelines for entrants lacking existing dairy protein safety dossiers. Infant formula manufacturers are most affected, responding by dual-sourcing traditional whey isolates alongside precision fermentation candidates to hedge regulatory uncertainty.
Direct-to-consumer protein brand procurement is consolidating volume commitments around vertically integrated suppliers offering certified isolate traceability. Sports nutrition contract manufacturers are displacing spot-market whey purchases with multi-year offtake agreements tied to sustainability certifications. This pattern is most visible in the United States, where fitness influencers and clean-label positioning drive ingredient provenance transparency requirements.
Beta Lactoglobulin Protein Market Segmentation
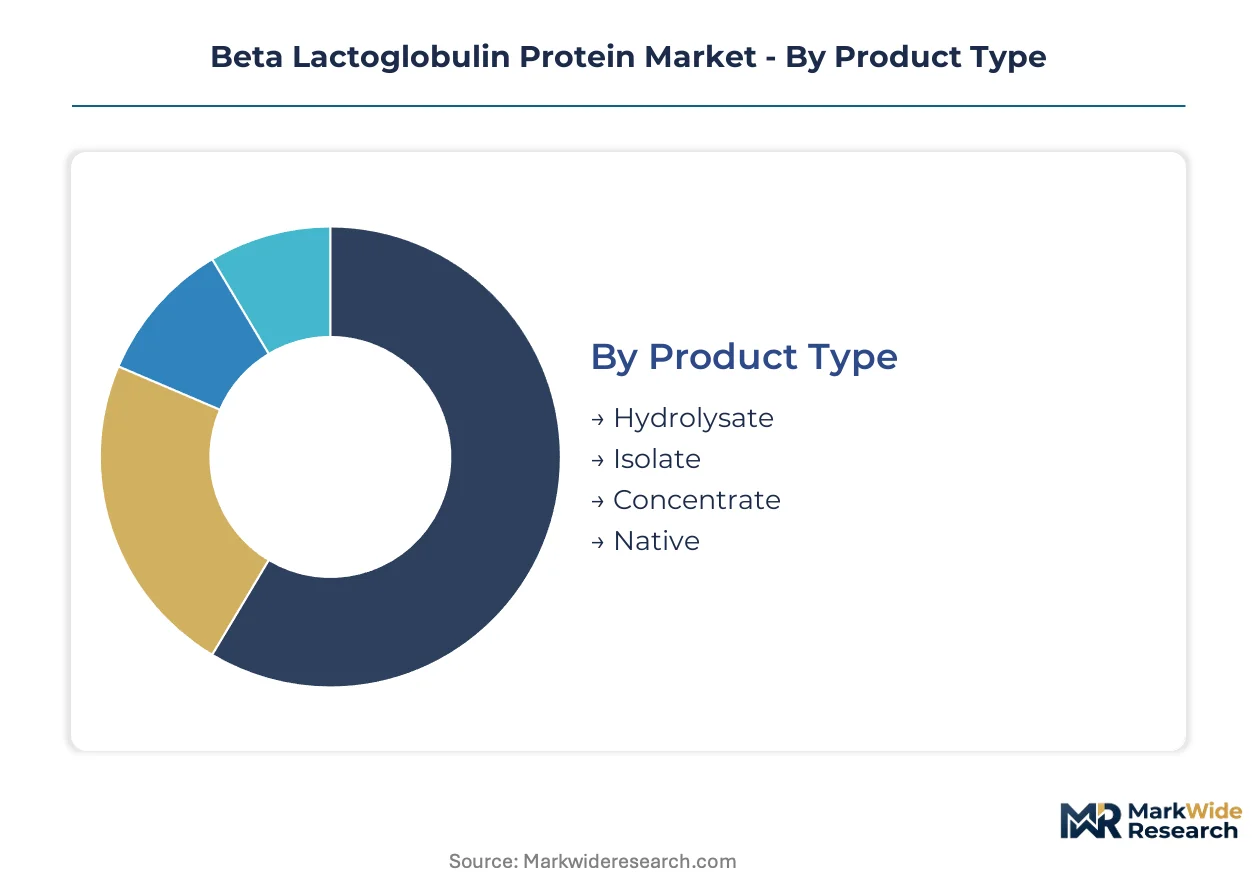
Beta lactoglobulin protein markets fragment across purification grades, end-use specifications, and channel economics. Each segment tier carries distinct margin profiles and regulatory burdens that reshape supplier prioritization.
Product Type:
Customization intensity escalates from minimally processed native forms through enzymatically modified hydrolysates, with specification stringency determining price realization and customer lock-in.
- Isolate:Protein content exceeds 90% with minimal lactose residue, commanding premium positioning in sports nutrition and clinical applications. United States sports nutrition brands pull volume through clean-label fortification programs, prioritizing batch-to-batch consistency for influencer-marketed products.
- Hydrolysate:Enzymatic pre-digestion reduces allergenicity and accelerates amino acid absorption. Infant formula manufacturers in Europe concentrate procurement here, responding to EFSA novel food frameworks that demand extensive safety documentation for alternative protein sources.
- Concentrate:Lower purity grades serve cost-sensitive food manufacturing with protein content typically ranging 70-85%. Bakery and beverage applications absorb volume where functional properties matter more than nutritional density.
- Native:Unprocessed whey fractions retain full structural integrity for research and specialized industrial applications. Academic institutions and biotech R&D programs constitute the primary demand pool.
Most installed capacity flows through Isolate. Expansion is steepest in Hydrolysate.
Application:
Volume concentration versus margin capture varies sharply across end-use channels, with regulatory sophistication and formulation complexity determining supplier qualification barriers.
- Nutritional Supplements:Fitness-oriented consumers in the United States prioritize high-purity isolates, pulling procurement through direct-to-consumer brands and specialty retailers. Clean-label positioning and sustainability certifications now function as baseline order qualifiers.
- Infant Formula:Enzymatic hydrolysate formats attract pediatric nutrition investments seeking reduced allergenicity profiles. EFSA novel food evaluations and FDA GRAS pathways impose dual-track compliance investments for multi-territory suppliers.
- Food & Beverage:Protein fortification penetrates mainstream grocery channels beyond traditional sports positioning. Bakery and beverage manufacturers exploit emulsification and gelling properties for texture modification.
- Animal Nutrition:Pet food and livestock feed applications absorb lower-grade concentrates where amino acid completeness outweighs purity requirements. Price sensitivity limits supplier margins in this tier.
Nutritional Supplements anchor current revenue. Infant Formula is gaining share fastest.
End User:
Customer sophistication and purchasing authority determine contract structure, with institutional buyers commanding volume discounts and individual consumers paying specification premiums.
- Manufacturers:Multinational food and nutrition companies drive procurement through multi-year offtake agreements tied to ISO 22000 and FSSC 22000 certifications. These buyers consolidate volume around vertically integrated suppliers offering certified traceability.
- Fitness Enthusiasts:Direct-to-consumer protein brands target this segment with subscription models and influencer partnerships. United States consumers particularly demand ingredient provenance transparency.
- Athletes:Elite and professional sports programs require clinical-grade isolate specifications with batch testing for banned substance contamination. Anti-doping certification adds cost but secures premium positioning.
- Health Conscious Consumers:Mainstream grocery shoppers seeking protein fortification prioritize clean-label claims over technical specifications. Price elasticity constrains premium capture here.
Manufacturers control the largest contract values. Fitness Enthusiasts show the steepest expansion trajectory.
Distribution Channel:
Channel selection reflects customer urgency, order size, and information requirements, with digital platforms displacing traditional retail for repeat purchases.
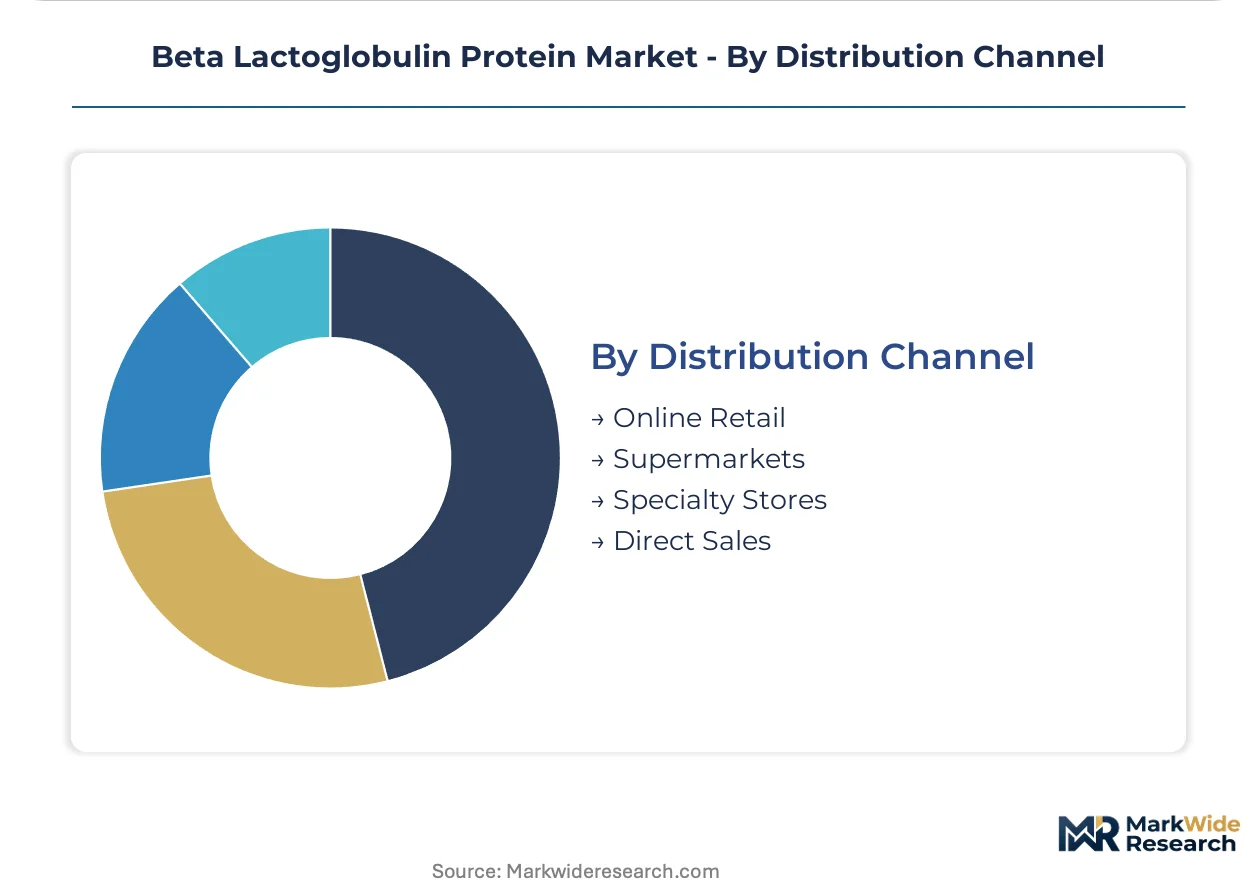
- Online Retail:Direct-to-consumer protein brands and subscription services consolidate here, leveraging influencer marketing and sustainability storytelling. United States consumers particularly favor this channel for reorder convenience.
- Specialty Stores:Sports nutrition retailers and health food chains offer educated staff and product sampling. These outlets capture premium pricing through service differentiation and curated assortment.
- Supermarkets:Mass grocery penetration accelerates as protein fortification enters mainstream food and beverage. Private label expansion pressures branded supplier margins.
- Direct Sales:Institutional buyers and manufacturers procure through bilateral negotiations, securing volume commitments and customized specifications. Long sales cycles accompany multi-year contracts.
Online Retail commands the fastest volume growth. Direct Sales retains the largest average order values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern European whey processing clusters anchor the beta lactoglobulin protein trade, though precision fermentation facilities in the United States and Denmark are redrawing capacity maps.
United States
Sports nutrition brands in California and Texas drive isolate procurement through direct-to-consumer channels. FDA GRAS determinations for fermentation-derived proteins accelerate commercialization timelines for precision fermentation entrants. Boston-area biotech clusters host contract development organizations expanding microbial chassis production.
Denmark
Arla Foods leverages backward integration across Jutland and Zealand facilities to secure whey fractionation supply. EFSA novel food frameworks govern isolate exports to European member states. Copenhagen precision fermentation startups partner with pharmaceutical-grade bioreactor operators.
Germany
Clean-label food manufacturers in Bavaria and North Rhine-Westphalia absorb hydrolysate volumes for infant formula applications. BSI certification requirements for food safety management systems filter supplier qualifications. Frankfurt logistics hubs coordinate isolate distribution to Central European nutrition compounders.
Netherlands
FrieslandCampina N.V. operates fractionation capacity in the northern provinces serving medical nutrition channels. REACH compliance obligations shape chemical handling protocols for whey-derived isolates. Wageningen research clusters advance enzymatic pre-digestion technologies for reduced allergenicity formats.
New Zealand
Fonterra Co-operative Group Limited manages seasonal herd supply volatility through South Island processing assets. MPI food safety standards govern whey protein concentrate exports to Asian markets. Canterbury dairy cooperatives invest in lactose separation infrastructure to upgrade isolate yields.
Beta Lactoglobulin Protein Market Competitive Landscape
Global majors compete with regional champions across whey fractionation and precision fermentation technology vectors. The supplier base organizes around three tiers: dairy cooperative giants with captive milk supply, biotech startups leveraging microbial expression platforms, and diversified nutrition ingredient houses with multi-channel distribution. Consolidation pressures intensify as fermentation-derived proteins erode traditional extraction economics. Capacity expansion and strategic partnerships dominate competitive moves as entrants seek ISO 22000 certifications and multi-year offtake agreements.
Among dairy cooperative incumbents, Arla Foods and Fonterra Co-operative Group Limited exemplify backward-integrated supply architectures. Precision fermentation specialists include Perfect Day, which occupies a position at the technology frontier decoupling production from herd cycles. Glanbia plc sits within the diversified nutrition tier, representing clinical-grade isolate positioning for medical nutrition channels.
| Leading Market Players |
|---|
| Arla Foods |
| Cargill Inc. |
| Perfect Day |
| Glanbia plc |
| Kerry Group plc |
| Vivici |
| Fonterra Co-operative Group Limited |
| FrieslandCampina N.V. |
| 21st.BIO |
| Others |
Value Network & Pricing Analysis
Dairy feed cost fluctuations transmit directly through whey fractionation economics to isolate pricing tiers, with Northern European processors absorbing margin compression while precision fermentation entrants reset cost baselines independent of herd-cycle volatility.
Pricing Analysis
Input-cost pass-through from dairy feed markets shapes contract-based long-term offtake structures for traditional whey suppliers, while enzymatic hydrolysate grades command premium-mid-economy pricing differentiation based on EFSA novel food certification status. Price differentiation hinges on ISO 22000 qualification tiers and batch-to-batch consistency guarantees demanded by United States sports nutrition brands. Pricing pressure stems from precision fermentation scale-up as microbial chassis production compresses unit economics for non-dairy isolates. Food and beverage manufacturers show highest price sensitivity due to commoditized protein fortification requirements, whereas infant formula compounders accept specification premiums for reduced allergenicity documentation.
Supply Chain Analysis
ISO 22000 and FSSC 22000 certifications function as mandatory gating criteria for multinational food manufacturer supply qualifications, filtering supplier access to volume contracts. Geographic supply concentration centers on Denmark, the Netherlands, and New Zealand, where dairy cooperative processing clusters anchor whey fractionation capacity. Raw material dependencies draw from seasonal milk supply cycles, lactose separation infrastructure, and pharmaceutical-grade bioreactor feedstock for fermentation entrants. Single-source vulnerability runs through Northern European energy cost exposure and logistics chokepoints at Rotterdam and Hamburg ports. Distribution runs through direct sales channels for institutional manufacturers and online retail platforms for direct-to-consumer protein brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA GRAS pathway expansion for fermentation-derived proteins compounds regulatory complexity into competitive advantage, with safety dossier sophistication separating qualified suppliers from commodity whey extractors.
For Market Incumbents: To counter precision fermentation cost compression, Arla Foods and Fonterra should deepen backward integration into captive lactose separation infrastructure and accelerate EFSA novel food dossier investments for hydrolysate grades. Securing multi-year offtake agreements with United States sports nutrition brands locks volume ahead of microbial chassis entrants achieving commercial scale. For New Entrants and Emerging Players: Contract development and manufacturing organizations in Denmark offer the most penetrable channel partnership for precision fermentation startups seeking pharmaceutical-grade bioreactor access without capital-intensive facility builds. Targeting clinical-grade isolate specifications for medical nutrition channels avoids direct price competition with commodity sports nutrition tiers. A co-manufacturing go-to-market angle with established ISO 22000 certification holders accelerates revenue recognition ahead of 18-24 month independent qualification timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where fermentation-derived protein platforms achieve cost parity with traditional whey extraction, eroding the margin buffers that sustained fragmented dairy cooperative structures. The long-term viability window favors vertically integrated precision fermentation specialists with strain engineering IP and downstream processing know-how. The signal to watch is FDA GRAS determination velocity for non-dairy beta lactoglobulin variants, which will signal competitive entry timelines and label claim permissibility.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Perfect Day's microbial chassis production decouples supply from dairy herd volatility. |
| EFSA Novel Food Dossier Investment | Streamlined safety evaluations reduce regulatory fragmentation for European market access. |
| Clinical-Grade Certification Pathway | Glanbia plc's medical nutrition positioning commands premium tiers above commodity sports applications. |
| Backward Integration into Whey Fractionation | Arla Foods' Jutland and Zealand facilities secure captive isolate supply for branded nutrition products. |
| Direct-to-Consumer Channel Expansion | Online retail platforms enable subscription models with sustainability certification transparency requirements. |
Research Methodology
Bottom-up nutritional supplement and infant formula demand modeling reconciled against top-down whey fractionation and precision fermentation capacity tracking forms the analytical core. Primary interviews with sports nutrition brand procurement directors, pediatric nutrition formulation scientists, dairy cooperative supply chain managers, and precision fermentation bioprocess engineers combined with secondary validation from FDA GRAS filings, EFSA novel food registers, ISO 22000 certification databases, and customs trade records. Triangulation across stakeholder inputs and documentary sources ensures segment-level consistency.
Historical trendline analysis of isolate and hydrolysate volume trajectories informed projection frameworks across the analysis window, with segmentation modeling spanning purification grade, application channel, end-user sophistication, and geographic regulatory cluster. CAGR derivation incorporated dairy feed price elasticity coefficients, precision fermentation yield improvement curves, and EFSA approval timeline distributions. Industry-specific forecast inputs included microbial chassis expression efficiency benchmarks and sports nutrition direct-to-consumer subscription growth patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to precision fermentation scale-up velocity and evolving FDA labeling requirements for non-dairy proteins. Forecasts reflect documented assumptions regarding EFSA harmonization progress and dairy cooperative capacity investment cycles. A model refresh is warranted upon material change in FDA GRAS determination timelines for fermentation-derived beta lactoglobulin entrants.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Colostrum Market
Food Biotechnology
Hemoglobin Feed Market
Food Biotechnology
Chlorella Market
Food Biotechnology
Global Food Biotechnology Market
Food Biotechnology
Europe Eubiotics Market
Food Biotechnology
Global Genetically Modified (GMO) Food Market
Food Biotechnology
Africa Eubiotics Market
Food Biotechnology
Casein Peptone Market
Food Biotechnology
Red Seaweed Extract Market
Food Biotechnology
Bovine Colostrum Market
Food Biotechnology
Beta-Propeller Phytases Market
Food Biotechnology
North America Eubiotics Market
Food Biotechnology
Biopreservation Market
Food Biotechnology
Genistein Market
Food Biotechnology
Pullulanase Market
Food Biotechnology
Biotech Flavors Market