
 Hemoglobin Feed Market | 2026-2036
Hemoglobin Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Hemoglobin Feed Market Outlook
Consolidation among aquaculture feed manufacturers is repositioning procurement leverage toward large-scale integrators. Nutreco leverages its integrated aquaculture nutrition platform to secure long-term hemoglobin supply contracts. Darling Ingredients, Inc. anchors its competitive stance through backward integration into rendering and protein recovery operations. Kraeber & Co GmbH specializes in pharmaceutical-grade hemoglobin extraction, occupying a premium tier distinct from commodity feed applications.
Hemoglobin feed comprises processed blood proteins derived from porcine or bovine sources, typically spray-dried or hydrolyzed to achieve protein concentrations exceeding 90% with high heme iron bioavailability for monogastric and aquatic species. The material functions primarily as a palatability enhancer, iron supplement, and digestible protein source in formulated diets. Powdered hemoglobin dominates volume flows due to superior shelf stability and blending compatibility with extruded feeds, while hemoglobin hydrolysate commands premium positioning in early-stage aquaculture diets where peptide bioavailability drives growth performance. Application demand clusters in aquaculture, with marine hatcheries and salmonid producers representing the fastest-growing consumption segment.
EFSA and REACH frameworks govern protein safety and chemical residue thresholds for hemoglobin feed entering European supply chains, while FDA oversight in the United States mandates BSE-related sourcing restrictions and pathogen control standards. These regulatory layers elevate compliance costs for cross-border ingredient trade and favor suppliers with certified rendering and traceability systems. Stakeholders must monitor evolving sustainability disclosure requirements under CSRD and emerging carbon footprint accounting rules for animal-derived feed inputs.
Market Dynamics
EU Green Deal sustainability mandates and F-Gas Regulation compliance requirements are restructuring hemoglobin feed procurement toward certified rendering operations with full chain-of-custody documentation.
Growth Catalysts
- Atlantic salmon aquaculture expansion:Norway's farming corridor is scaling hatchery production, driving concentrated demand for peptide-rich hemoglobin hydrolysate in early-stage marine diets.
- REACH chemical safety frameworks:ECHA oversight elevates entry barriers for uncertified suppliers, channeling volume toward established rendering networks with validated traceability systems.
- Spray-drying process refinement:Advanced thermal stabilization extends shelf life beyond 24 months, enabling intercontinental bulk shipment to Asian aquaculture markets.
Market Restraints
- Raw material concentration:Bovine and porcine blood collection depends on geographically clustered slaughterhouse infrastructure, creating supply vulnerability in regions without integrated meat processing.
- BSE-related sourcing restrictions:FDA ruminant feed bans limit bovine hemoglobin cross-border movement, fragmenting supply pools and complicating multi-origin formulation strategies.
- Plant protein substitution:Fermented microbial proteins and insect meal are capturing mid-tier aquaculture formulations, compressing addressable volume for commodity-grade blood proteins.
Strategic Opportunities
- Pharmaceutical-grade extraction:High-purity heme iron isolation for neonatal nutrition and anemia therapeutics commands 4-5x feed-grade pricing, opening margin expansion for specialized processors.
- CSRD-aligned carbon accounting:EU sustainability disclosure requirements favor suppliers with verified low-carbon rendering, creating differentiation for operations with biogas capture or renewable thermal systems.
- Recirculating aquaculture systems:Closed-containment salmon farming in Scotland and Iceland requires precision-formulated diets with optimized iron bioavailability, favoring hemoglobin over inorganic mineral supplements.
Industry Challenges
- Pathogen validation protocols:Salmonella and E. coli elimination requires validated thermal processing windows that complicate customization for small-batch pharmaceutical contracts.
- Cross-functional technical talent:Protein biochemistry expertise must combine with aquaculture nutrition science and regulatory compliance knowledge, a skill intersection with limited labor pool depth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemoglobin Feed Market |
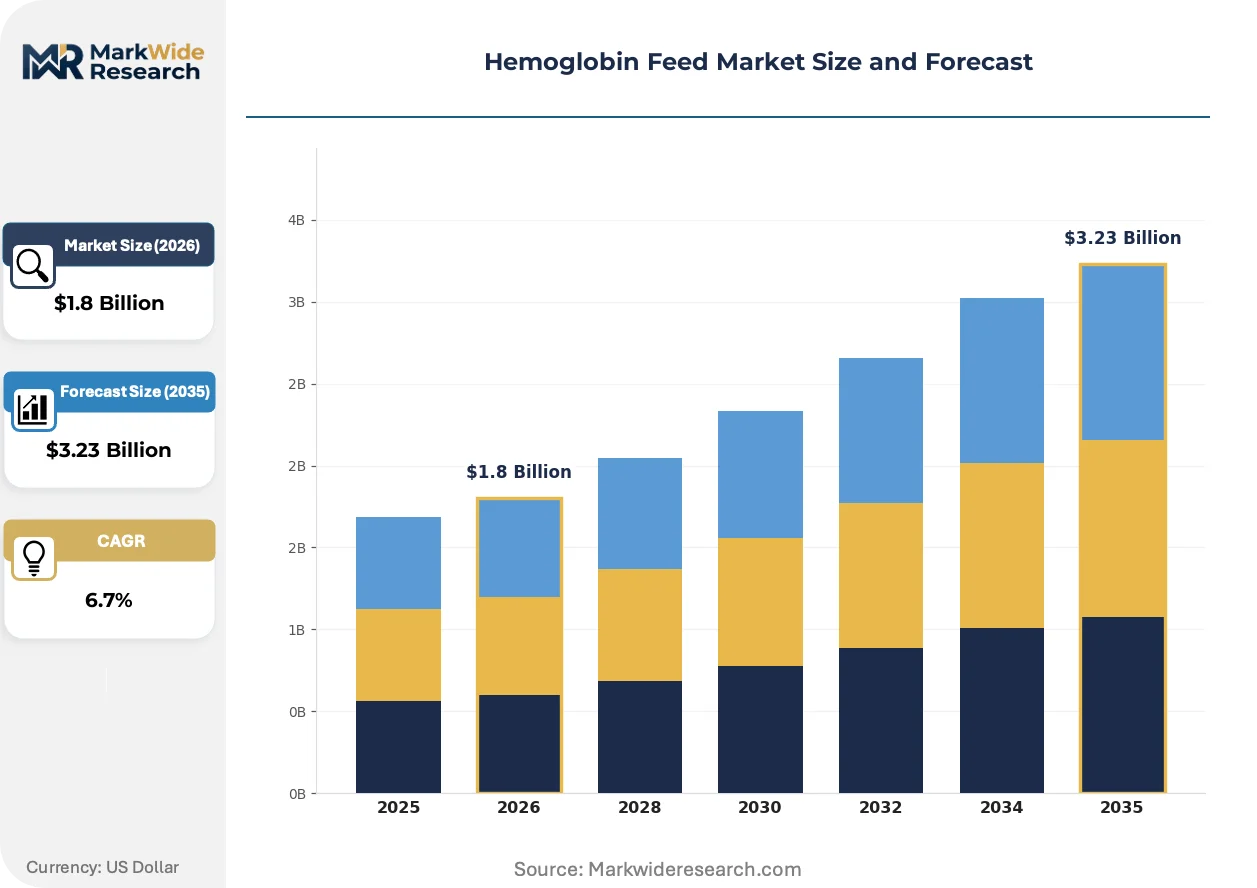
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Hemoglobin, Powdered Hemoglobin, Hemoglobin Hydrolysate, Fermented Hemoglobin Application: Aquaculture, Poultry, Swine, Ruminants End User: Feed Manufacturers, Animal Nutrition Companies, Research Institutions, Agricultural Producers Distribution Channel: Online Retail, Distributors, Direct Sales, Wholesale |
| Companies Covered | Nutreco, Kraeber & Co GmbH, Daka Denmark A/S, Darling Ingredients, Inc., Rocky Mountain Biologicals, Lauridsen Group, Inc., Puretein Agri LLC, VEOS Group, Sera Scandia A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemoglobin Feed Market Strategic Shifts
Processing technology and regulatory transparency requirements are compressing the viable supplier base while opening premium tiers for differentiated hemoglobin products with verified sustainability credentials.
Enzymatic hydrolysis is converging with membrane filtration to produce targeted peptide fractions with enhanced iron absorption kinetics. Marine hatchery operators in Norway and Scotland are adopting these precision-grade inputs for smolt diets. The technology is converging with automated feeding systems that require ultra-stable ingredient flow characteristics, compressing tolerance for batch-to-batch protein variability.
EFSA is tightening residue threshold documentation for processed animal proteins entering European feed chains, requiring quantitative PCR validation for species-of-origin confirmation. Rendering facilities must now maintain dual-certified laboratory capacity for both nutritional and safety testing. Salmon feed compounders in Denmark and Ireland are consolidating supplier relationships to reduce audit burden, favoring integrated operations with in-house analytical capabilities.
Long-term offtake contracting is displacing spot-market purchasing among large-scale aquaculture integrators. Norwegian and Chilean salmon producers are locking 24-36 month supply agreements with fixed-volume escalators, transferring price risk to rendering operations. This pattern is most pronounced among vertically integrated protein recovery specialists with captive slaughterhouse supply, compressing market access for independent traders without backward integration into raw material sourcing.
Hemoglobin Feed Market Segmentation
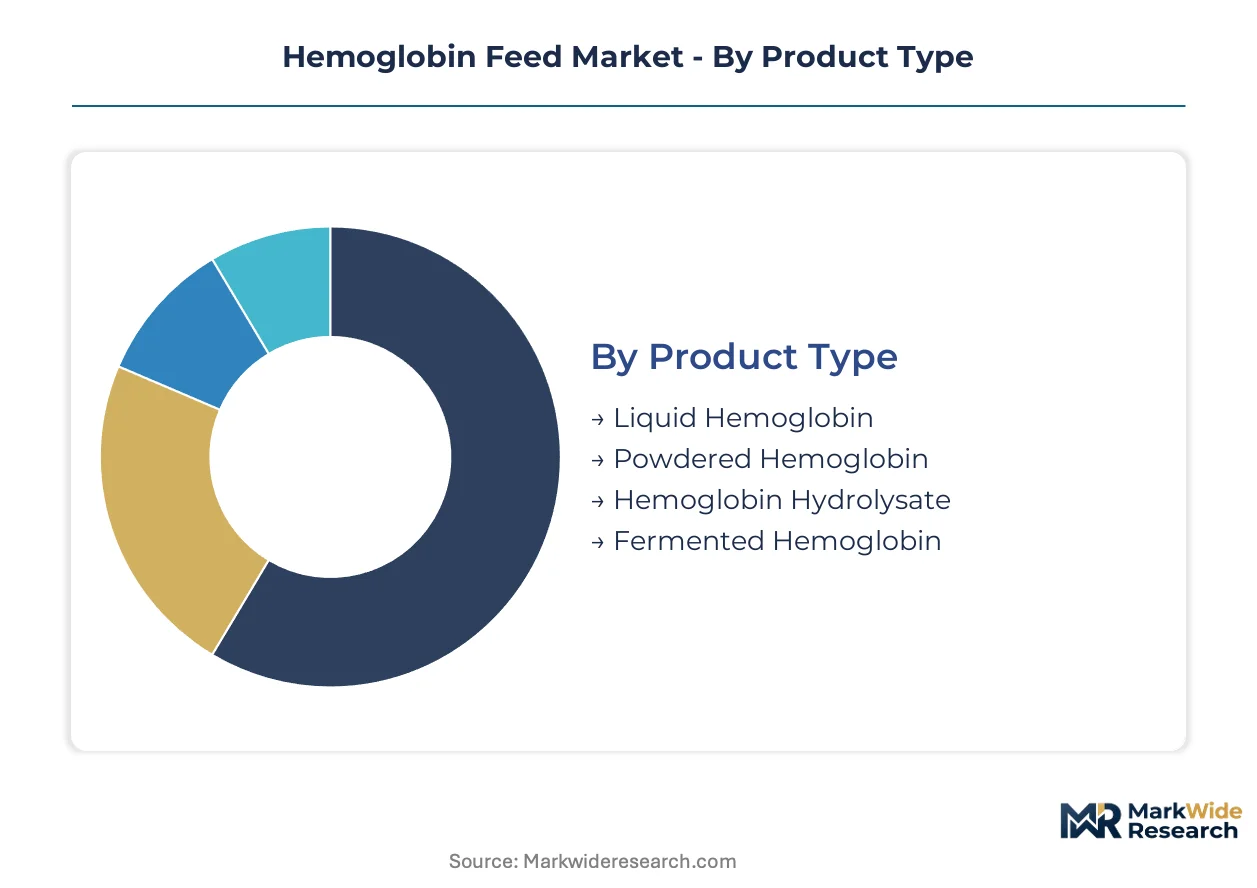
Segmentation in hemoglobin feed reveals how protein form, species application, and procurement channel each impose distinct technical and commercial requirements on suppliers. Understanding these divisions exposes where margin concentrates and where standardization yields to customization.
Product Type:
Customization intensity spans from commodity bulk powders to precision-engineered peptide fractions, with processing sophistication determining price tier and end-use access.
- Powdered Hemoglobin:Spray-dried protein concentrate exceeding 90% purity with 24-month shelf stability. Norwegian salmon feed compounders consume the largest volumes, prioritizing blending compatibility with extruded marine diets and reliable intercontinental shipment logistics.
- Hemoglobin Hydrolysate:Enzymatically cleaved peptide fractions with enhanced iron absorption kinetics for early-stage aquaculture. Scotland and Iceland's recirculating aquaculture systems drive demand for this precision-grade input where smolt growth performance justifies premium positioning.
- Liquid Hemoglobin:Unprocessed or minimally stabilized blood protein requiring refrigerated logistics and immediate use, constraining adoption to proximate rendering-to-feed mill supply chains.
- Fermented Hemoglobin:Microbially treated protein with modified amino acid profiles, occupying niche positioning in experimental poultry and swine formulations seeking reduced antinutritional factors.
Leading the category by volume: Powdered Hemoglobin. Growing fastest: Hemoglobin Hydrolysate.
Application:
Species-specific digestive physiology and iron metabolism create divergent formulation requirements across livestock and aquatic categories.
- Aquaculture:Marine hatcheries and salmonid producers in Norway's farming corridor represent the most concentrated demand pool, with peptide-rich diets for smolt stages commanding technical specifications unmatched by terrestrial applications.
- Poultry:Broiler and layer operations utilize hemoglobin as palatability enhancer and heme iron source, though plant protein substitution pressures commodity-grade blood protein volumes in mid-tier formulations.
- Swine:Post-weaning diets incorporate hemoglobin for digestible protein and iron supplementation, with EFSA processed animal protein regulations governing species-of-origin documentation for European compounders.
- Ruminants:FDA BSE-related feed bans restrict bovine hemoglobin inclusion in cattle diets, fragmenting addressable volume and complicating multi-species rendering operations.
Aquaculture dominates revenue concentration. Aquaculture also climbs the fastest as Atlantic salmon production scales.
End User:
Procurement sophistication separates large-scale integrators with captive laboratory capacity from price-sensitive agricultural producers purchasing through intermediaries.
- Feed Manufacturers:Integrated aquaculture nutrition platforms lock long-term supply agreements with fixed-volume escalators, transferring price risk upstream to rendering operations with certified traceability systems.
- Animal Nutrition Companies:Specialized formulators source pharmaceutical-grade hemoglobin for neonatal nutrition and anemia therapeutics, occupying premium tiers distinct from commodity feed applications.
- Research Institutions:Small-batch requirements for peptide biochemistry studies face constrained supplier availability due to pathogen validation protocols complicating customization.
- Agricultural Producers:Direct procurement remains limited by minimum order volumes and cold-chain logistics requirements, channeling most farm-level demand through distributor networks.
Feed Manufacturers command the largest procurement volumes. Animal Nutrition Companies expand most quickly as pharmaceutical-grade extraction scales.
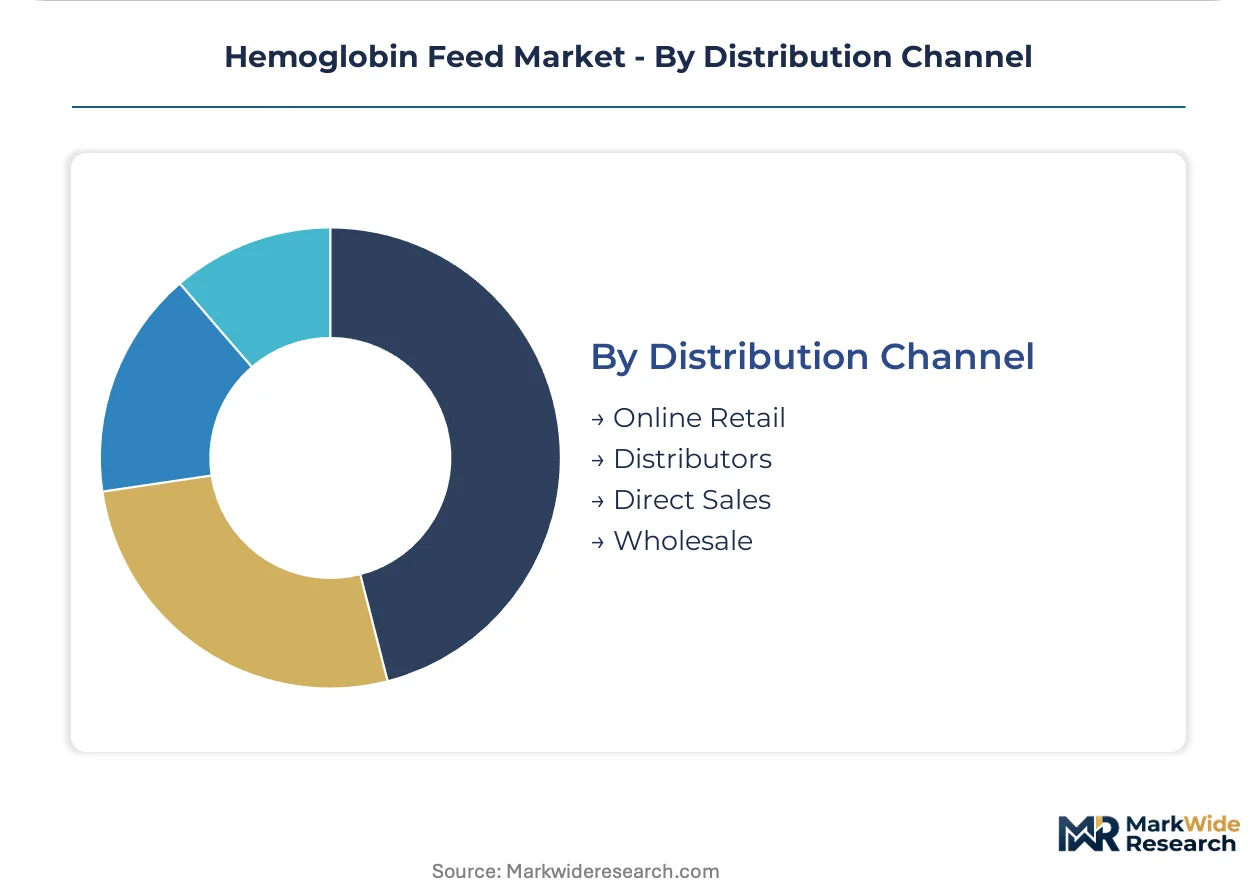
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and the geographic density of rendering infrastructure.
- Distributors:Regional protein traders aggregate volumes from multiple rendering sources, serving mid-tier feed compounders without direct supplier relationships or in-house analytical capabilities.
- Direct Sales:Vertically integrated rendering specialists with captive slaughterhouse supply negotiate bilateral contracts with Norwegian and Chilean salmon producers, eliminating intermediary margins.
- Wholesale:Bulk commodity flows serve established feed mill networks with standardized specifications and predictable offtake schedules.
- Online Retail:Limited to small-volume specialty grades and research quantities, constrained by hazardous material shipping regulations and temperature-controlled logistics complexity.
Distributors handle the greatest throughput. Direct Sales gains share fastest as long-term contracting displaces spot-market purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for hemoglobin feed concentrates in Norway's Atlantic salmon corridor, with secondary volume flows channeling through Denmark and the Netherlands into compounder networks across Northern Europe.
Norway
Atlantic salmon hatcheries in Bergen and Trondheim drive concentrated consumption of peptide-rich hemoglobin hydrolysate for smolt diets. The Norwegian Food Safety Authority enforces strict processed animal protein documentation under EFSA-aligned national regulations. Tromsø-based research clusters collaborate with feed compounders to optimize iron bioavailability in recirculating aquaculture systems.
Denmark
Integrated rendering operations in Jutland supply spray-dried hemoglobin powder to domestic aquaculture nutrition platforms and German poultry compounders. REACH compliance through ECHA governs chemical residue thresholds for cross-border protein shipments. Copenhagen-area feed technology firms develop automated blending systems requiring ultra-stable ingredient flow characteristics.
United States
Porcine hemoglobin processors in Iowa and North Carolina serve domestic swine and poultry operations despite FDA ruminant feed bans fragmenting bovine protein utilization. The Food and Drug Administration mandates BSE-related sourcing restrictions and pathogen control standards for rendered proteins. Rendering infrastructure clusters near Midwest slaughterhouse corridors, creating supply vulnerability in coastal regions without integrated meat processing.
Chile
Salmon producers in the Los Lagos and Aysén regions import hemoglobin-derived proteins for marine hatchery diets, replicating Norwegian formulation standards. Chile's national fisheries service enforces aquaculture feed safety protocols aligned with international export requirements. Puerto Montt anchors the southern farming corridor where long-term supply contracting with European renderers is displacing spot-market purchasing.
United Kingdom
Scottish recirculating aquaculture systems in the Shetland Islands and mainland Highlands require precision-formulated diets with optimized iron bioavailability. The Food Standards Agency implements EFSA-derived processed animal protein regulations post-Brexit, maintaining equivalence with EU safety frameworks. Aberdeen-based salmon integrators consolidate supplier relationships to reduce audit burden from dual-certified laboratory requirements.
Hemoglobin Feed Market Competitive Environment
European rendering specialists anchor the premium tier; North American protein recovery operations hold commodity-scale positioning. Supplier concentration favors vertically integrated operations with captive slaughterhouse supply and in-house analytical capabilities. Three archetypes dominate: integrated aquaculture nutrition platforms locking long-term contracts, pharmaceutical-grade extraction specialists occupying margin-rich tiers, and regional rendering networks serving price-sensitive terrestrial livestock markets. Competitive dynamics center on backward integration into raw material sourcing and certification investments for CSRD-aligned carbon accounting.
Among Denmark-based rendering operations, Daka Denmark A/S exemplifies the integrated model with upstream control over blood collection infrastructure. Kraeber & Co GmbH occupies a distinct premium tier as a German specialist in pharmaceutical-grade hemoglobin extraction. Nutreco represents the aquaculture nutrition platform archetype, leveraging integrated supply chain relationships to secure dedicated hemoglobin volumes for marine feed formulations. These three companies illustrate how geographic concentration near slaughterhouse corridors combines with regulatory compliance depth to determine competitive positioning.
| Leading Market Players |
|---|
| Nutreco |
| Kraeber & Co GmbH |
| Daka Denmark A/S |
| Darling Ingredients, Inc. |
| Rocky Mountain Biologicals |
| Lauridsen Group, Inc. |
| Puretein Agri LLC |
| VEOS Group |
| Sera Scandia A/S |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracting by Norwegian and Chilean salmon producers is compressing spot-market liquidity and forcing rendering operations to absorb price risk through fixed-volume escalators. This procurement shift elevates the premium commanded by vertically integrated suppliers with captive slaughterhouse supply and certified traceability systems.
Pricing Analysis
Volume flows concentrate in commodity-grade spray-dried hemoglobin powder where price competition intensifies among regional rendering networks, while peptide-rich hemoglobin hydrolysate for early-stage aquaculture captures disproportionate margin through performance-based differentiation. Price differentiation rests on certification depth under EFSA and REACH frameworks plus backward integration into rendering infrastructure. Pricing pressure stems from plant protein substitution in mid-tier poultry formulations. Feed manufacturers with integrated laboratory capacity exhibit lowest price sensitivity; agricultural producers purchasing through distributor networks face highest cost elasticity.
Supply Chain Analysis
Workforce availability constraints in Denmark, Germany, and the Netherlands limit expansion of dual-certified laboratory capacity required for EFSA-aligned species-of-origin documentation. Raw material flows draw from geographically clustered bovine and porcine slaughterhouse infrastructure in Iowa, North Carolina, and Jutland. Supply chain risk centers on single-source vulnerability where rendering operations lack captive blood collection. Distribution runs through direct bilateral contracts between vertically integrated renderers and large-scale aquaculture integrators, displacing spot-market intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EFSA's tightening residue threshold documentation functions as a barrier-to-entry moat, advantaging established rendering networks with in-house analytical capabilities over uncertified challengers.
For Market Incumbents: Hedge against plant protein substitution by deepening pharmaceutical-grade extraction capabilities for neonatal nutrition applications. Fortify backward integration into rendering infrastructure to secure captive slaughterhouse supply and reduce exposure to raw material concentration risk in geographically clustered collection zones.
For New Entrants and Emerging Players: Begin with CSRD-aligned carbon accounting services for rendering operations seeking verified low-carbon credentials under EU sustainability disclosure requirements. Target research institutions with small-batch peptide biochemistry requirements as the most penetrable segment, leveraging enzymatic hydrolysis specialization to bypass commodity-grade price competition.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated rendering specialists with dual-certified laboratory capacity and established relationships with Norwegian salmon integrators. Monitor regulatory enforcement intensity under F-Gas Regulation and EU Green Deal mandates as the primary inflection signal for compliance-cost escalation that accelerates supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Extraction Scale-Up | High-purity heme iron isolation commands 4-5x feed-grade pricing in neonatal nutrition markets. |
| CSRD-Aligned Carbon Certification | Verified low-carbon rendering creates procurement preference among EU sustainability-mandated aquaculture integrators. |
| Long-Term Supply Agreement Lock-In | Fixed-volume escalators with Norwegian and Chilean salmon producers transfer price risk upstream to rendering operations. |
| Enzymatic Hydrolysis Technology Investment | Membrane filtration convergence produces targeted peptide fractions with enhanced iron absorption kinetics for smolt diets. |
| Backward Integration into Rendering | Captive slaughterhouse supply secures raw material access and eliminates intermediary margin extraction. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with rendering plant managers, aquaculture nutrition platform procurement leads, EFSA regulatory affairs specialists, and veterinary feed compounder technical directors. Bottom-up volume estimates triangulated against top-down market sizing derived from ECHA chemical safety submissions, EU processed animal protein import statistics, and Norwegian Food Safety Authority inspection reports.
Segment-level granularity modeled protein form differentiation between powdered hemoglobin and hydrolysate variants, application concentration across aquaculture hatchery and terrestrial livestock categories, and procurement channel split between direct sales and distributor intermediation. CAGRs were derived through trend extrapolation of historical volume flows and elasticity-adjusted demand projections across the analysis window. Industry-specific forecast inputs incorporated Atlantic salmon smolt production scaling in Norway's farming corridor and regulatory enforcement trajectory under REACH chemical safety frameworks.
Underlying measurement precision varies by segment; pharmaceutical-grade extraction volumes carry tighter precision than commodity-grade powder flows given consolidated supplier base visibility. Forecasts reflect assumptions regarding sustained regulatory enforcement intensity and continued aquaculture hatchery expansion. Material deviation in EFSA documentation requirements or abrupt substitution acceleration toward fermented microbial proteins warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Bovine Colostrum Market
Food Biotechnology
Brown Algae Protein Market
Food Biotechnology
Apigenin Market
Food Biotechnology
Beta-Propeller Phytases Market
Food Biotechnology
Global GMO Testing Market
Food Biotechnology
Zein Protein Market
Food Biotechnology
South America Feed Prebiotics Market
Food Biotechnology
Europe Eubiotics Market
Food Biotechnology
Biotech Flavors Market
Food Biotechnology
Bangladesh Starch and Starch Derivative Market
Food Biotechnology
Perilla Protein Market
Food Biotechnology
North America Eubiotics Market
Food Biotechnology
Microalgae Market
Food Biotechnology
Salmon Polynucleotide (PN) Market
Food Biotechnology
Flaxseed Gum Market
Food Biotechnology
Phycocyanin Market