
 Prebiotics Market | 2026-2036
Prebiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Prebiotics Market Analysis
Chicory root fiber is shifting toward partial replacement of synthetic soluble fibers in functional food formulations. Yakult Honsha leverages its fermented dairy heritage to anchor probiotic-prebiotic synbiotic positioning across Asian retail channels. Danone competes through vertically integrated dairy streams that sustain captive inulin demand for yogurt and infant nutrition portfolios. Kerry Group specializes in customized oligosaccharide blends for beverage applications, occupying a technical-services niche that differentiates it from commodity suppliers.
Prebiotics are non-digestible food ingredients that selectively stimulate growth or activity of beneficial gastrointestinal microbiota, typically comprising carbohydrate polymers with degree-of-polymerization values ranging from 2 to 60 monomeric units. Their primary commercial purpose centers on conferring measurable physiological benefits—improved mineral absorption, pathogen exclusion, and short-chain fatty acid production—while serving as functional additives across food, pharmaceutical, and animal nutrition systems. Inulin and galactooligosaccharides dominate current volume, with the former commanding mature margin pools in dairy fortification while the latter registers accelerated growth in infant formula and clinical nutrition. Powder form leads manufacturing economics due to stability and handling advantages, though liquid prebiotic concentrates are gaining formulation share in ready-to-drink beverages where solubility and dosing precision matter.
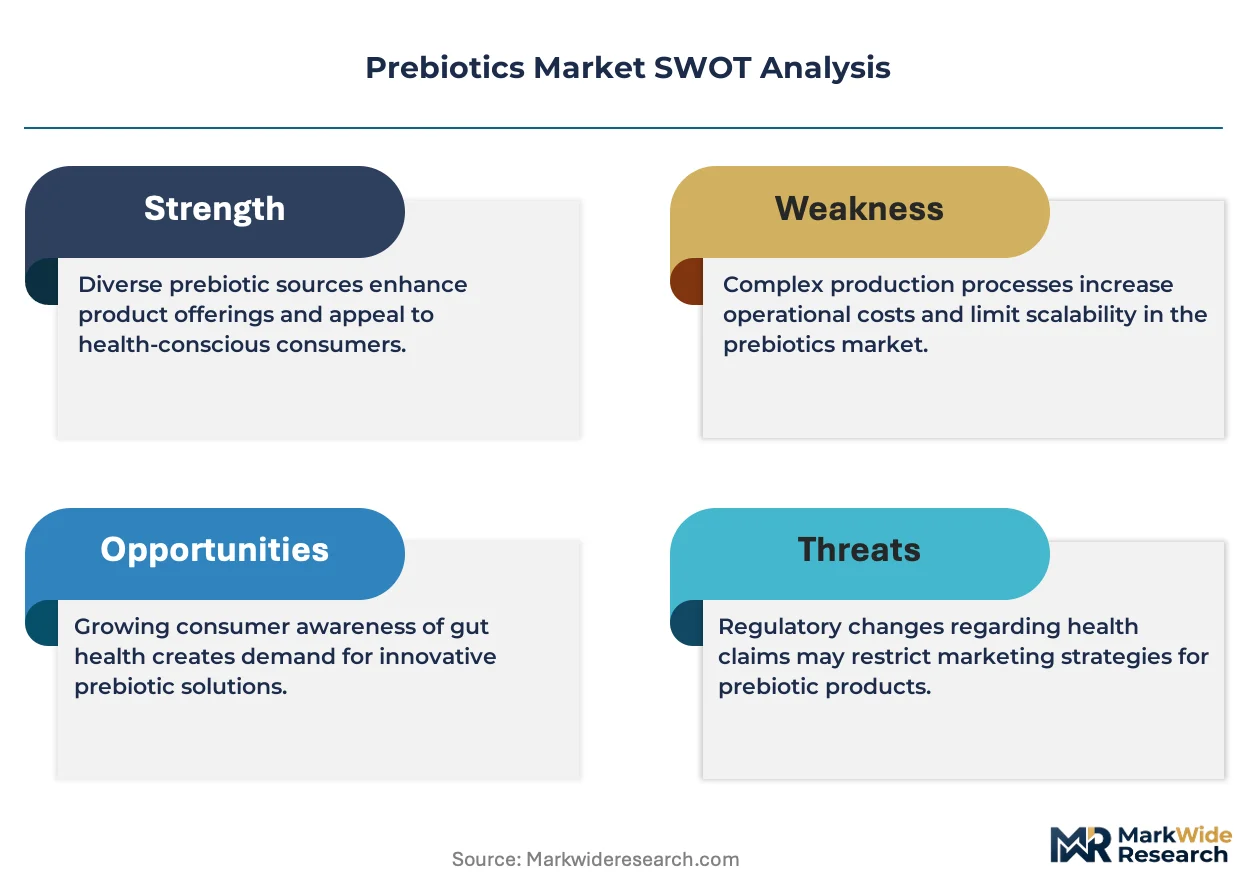
EFSA novel food assessments and FDA GRAS notifications jointly shape ingredient approval timelines and label claim permissibility, directly determining which prebiotic structures achieve commercial scale in human applications. EU F-Gas Regulation indirectly pressures extraction solvent choices in chicory processing, while REACH compliance costs filter smaller entrants from European oligosaccharide manufacturing. Stakeholders must monitor evolving microbiome health claim substantiation standards across jurisdictions, as regulatory acceptance of specific bacterial-target mechanisms will determine which prebiotic chemistries command premium positioning versus commodity substitution.
Market Dynamics
Chicory root supply concentration in France and Belgium is forcing infant formula manufacturers toward long-term offtake contracts, compressing spot market liquidity and amplifying price volatility for galactooligosaccharide alternatives.
Growth Catalysts
- EU Novel Food Regulation streamlining:Accelerated EFSA safety assessments for oligosaccharide ingredients reduce time-to-market for new prebiotic structures entering dairy fortification applications.
- Infant formula microbiome positioning:Manufacturers leverage bifidogenic clinical data to secure premium shelf placement in pharmacy and specialty retail channels across Germany and the Netherlands.
- REACH compliance consolidation:Registration cost barriers filter smaller European extraction operators, concentrating supply among scaled chicory processors with established dossier portfolios.
Market Restraints
- Chicory root input volatility:Agricultural yield sensitivity to Flemish weather patterns disrupts inulin extraction schedules and squeezes processor margins during poor harvest cycles.
- EFSA health claim substantiation rigor:Rejected bacterial-target mechanism dossiers block label permissibility for emerging prebiotic chemistries, freezing commercialization pathways.
- Synthetic soluble fiber substitution:Polydextrose and resistant maltodextrin formulations capture cost-sensitive functional food applications where prebiotic specificity is undifferentiated.
Strategic Opportunities
- Ready-to-drink beverage channel expansion:Liquid prebiotic concentrate formats penetrate Asian convenience retail where powder dissolution barriers limit adoption.
- EU F-Gas Regulation solvent transition:Supercritical CO2 extraction investments qualify processors for green chemistry certification premiums in sustainable ingredient procurement programs.
- Clinical nutrition application white space:Hospital and enteral feeding channels remain underdeveloped for galactooligosaccharide fortification outside neonatal intensive care settings.
Industry Challenges
- Microbiome assay standardization gaps:Inconsistent bifidogenic potency measurement protocols across contract research organizations complicate cross-study clinical substantiation.
- Dual-use pharmaceutical registration complexity:Prebiotic-drug hybrid candidates trigger overlapping EMA medical food and novel food jurisdictional disputes, extending approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prebiotics Market |
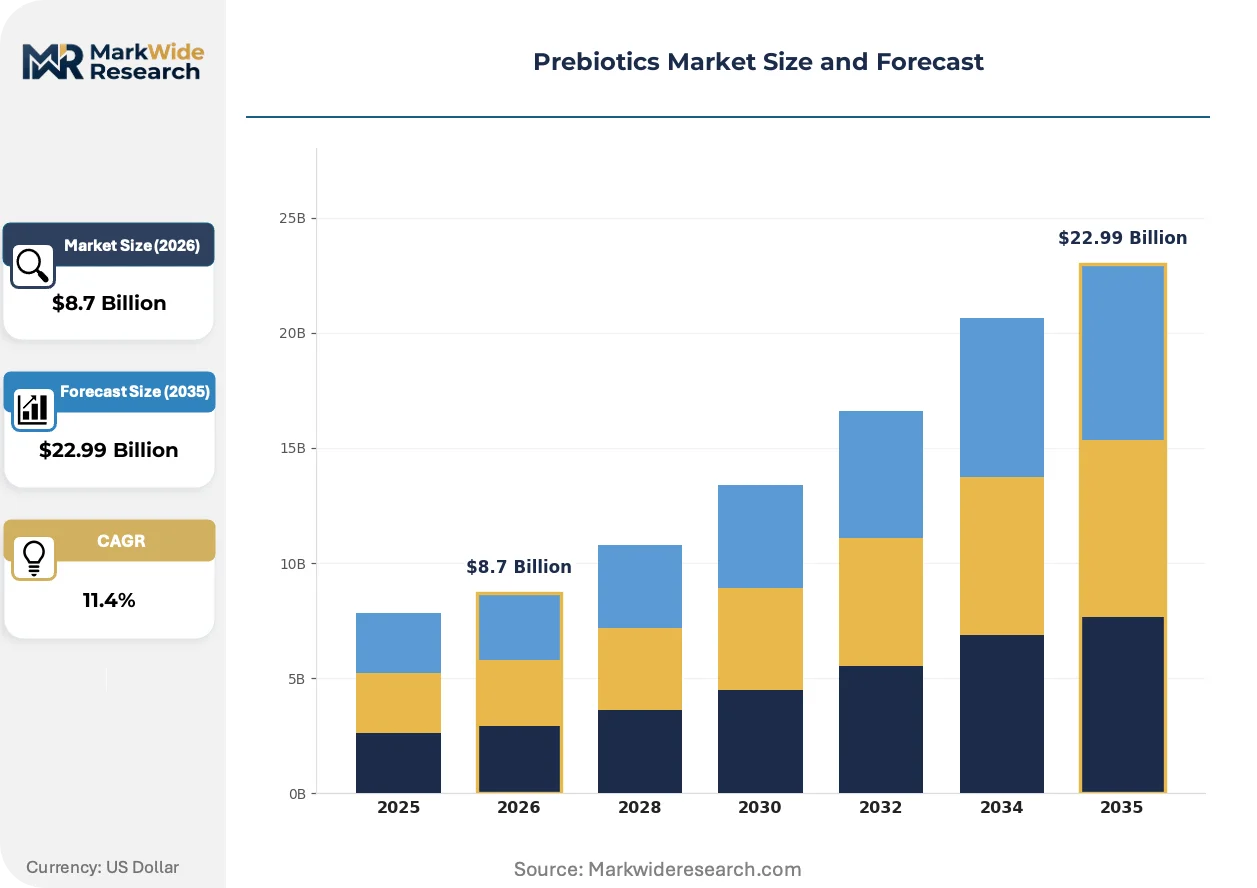
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inulin, Oligofructose, Galactooligosaccharides, Mannanooligosaccharides Form: Powder, Liquid, Granules, Tablets End User: Dietary Supplements, Food & Beverages, Animal Feed, Infant Formulas Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Yakult Honsha, Danone, Chr. Hansen, Kerry Group, ADM, DuPont, BioGaia, dsm-firmenich, Nestlé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prebiotics Market Emerging Trajectories
Prebiotic ingredient development is pivoting toward precision fermentation-derived oligosaccharides that bypass agricultural feedstock constraints, while regulatory science increasingly demands strain-specific bacterial-target substantiation rather than generic fermentability claims.
Enzymatic synthesis platforms using microbial transglycosidases are integrating into commercial manufacturing streams, enabling tailored degree-of-polymerization distributions for specific gut microbiota modulation targets. Infant formula producers in the Netherlands adopt these bioprocesses to secure supply independence from chicory root harvest cycles. The technology is integrating captive production capabilities that erode commodity inulin processor pricing power in dairy applications.
EFSA's evolving microbiome health claim guidance tightens evidentiary standards for bacterial-selectivity mechanisms, rejecting submissions that rely solely on short-chain fatty acid production metrics. This regulatory recalibration forces reformulation investments toward oligosaccharide structures with documented bifidogenic specificity. Clinical nutrition segments in Germany face the steepest compliance cost escalation as legacy inulin portfolios require supplemental human intervention studies.
Ingredient buyers in functional beverages are consolidating procurement around suppliers offering bundled prebiotic-probiotic synbiotic systems rather than standalone fiber additives. This bundling preference compresses standalone oligosaccharide supplier margins while rewarding integrated fermentation houses with formulation service capabilities. The shift is most pronounced in Japanese and South Korean retail channels where Yakult-established synbiotic education accelerates bundled product acceptance.
Prebiotics Market Segmentation
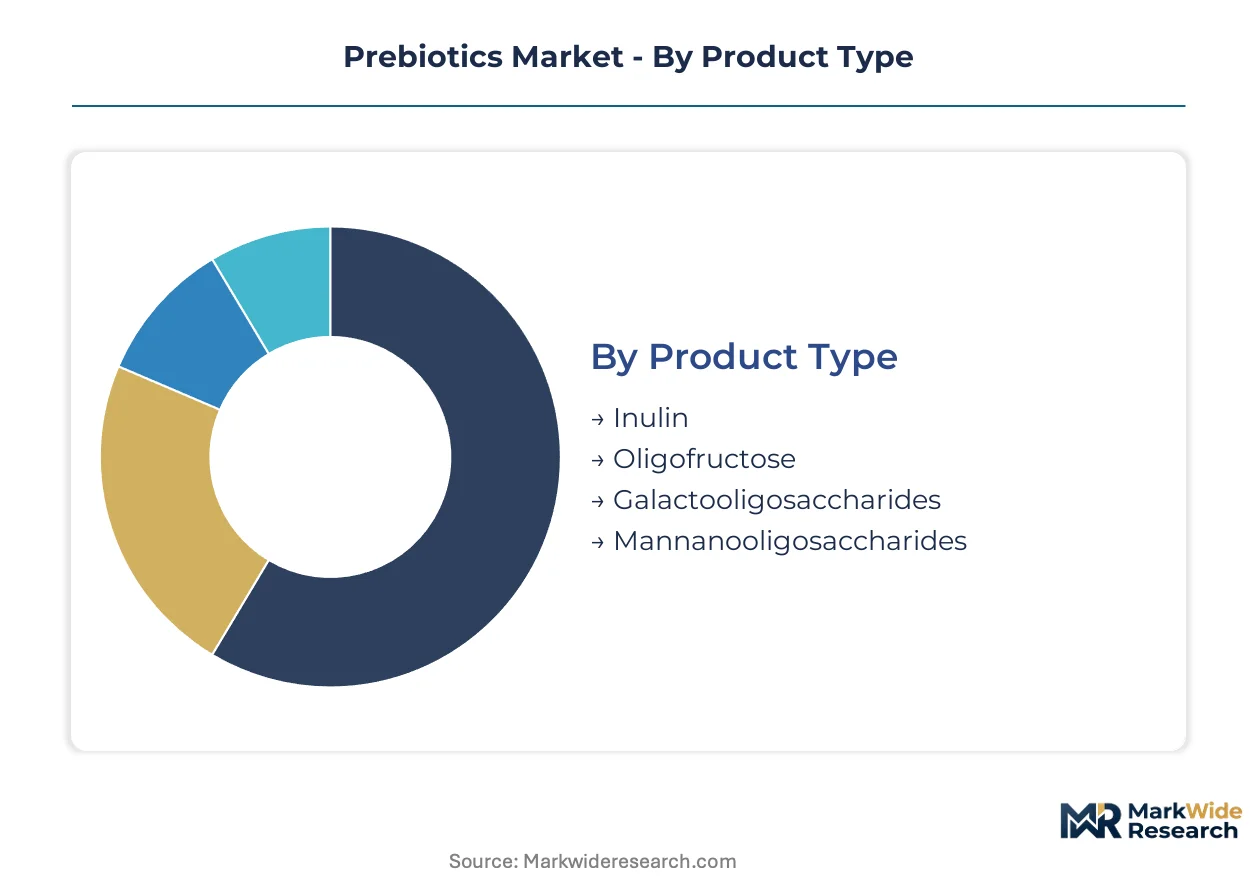
Prebiotic ingredient economics vary sharply across molecular structures and formulation states. Capital deployment decisions hinge on extraction technology requirements, regulatory dossier costs, and end-use certification standards.
Product Type:
Capital intensity peaks with enzymatic synthesis platforms and novel food dossier preparation, while agricultural extraction routes demand seasonal working capital buffers against raw material volatility.
- Inulin:Long-chain fructan polymers extracted from chicory root through hot water diffusion and spray drying. French and Belgian processors dominate installed capacity, though EFSA novel food dossier maintenance consumes recurring regulatory expenditure.
- Galactooligosaccharides:Disaccharide oligomers produced via transgalactosylation of lactose using fungal β-galactosidases. Dutch infant formula manufacturers anchor demand, with enzymatic bioreactor investments requiring sustained technical staffing.
- Oligofructose:Shorter-chain fructooligosaccharides derived from inulin partial hydrolysis. Cost-competitive positioning in functional beverages depends on shared extraction infrastructure with inulin operations.
- Mannanooligosaccharides:Yeast cell wall derivatives concentrated through autolysis and centrifugation. Animal feed applications in Germany and the Netherlands absorb volume, with lower purity thresholds reducing purification capital requirements.
Inulin absorbs the bulk of installed capacity; galactooligosaccharides are expanding most quickly.
Form:
Manufacturing asset allocation follows handling characteristics and stability profiles, with powder operations commanding the largest fixed investment base.
- Powder:Dominant format for ingredient stability and bulk logistics, requiring fluidized bed drying and nitrogen-flush packaging lines. Dairy fortification in Germany and infant formula production in the Netherlands concentrate procurement.
- Liquid:Concentrated syrup formats for ready-to-drink beverages, demanding aseptic filling and cold-chain distribution infrastructure. Asian convenience retail channels in Japan and South Korea drive formulation adoption.
- Granules:Intermediate flowability for direct compression tableting, common in dietary supplement operations. Lower capital barriers than powder lines attract regional contract manufacturers.
- Tablets:Finished dose forms for pharmacy and direct-to-consumer channels, with tableting and coating equipment representing modest incremental investment over granule production.
Powder commands the heaviest capital deployment; liquid formats gain share fastest in beverage applications.
End User:
Customer certification requirements segment capital access, with pharmaceutical-grade infant formula imposing the steepest quality system investments.
- Infant Formulas:EFSA novel food authorization and ISO 22000 certification mandatory for EU market access. Dutch and German manufacturers enforce supplier audit protocols that filter smaller extraction operators.
- Food & Beverages:Broadest volume base spanning dairy, bakery, and functional drinks. Clean-label positioning in France and Belgium drives inulin procurement, with formulation flexibility permitting multi-source supply strategies.
- Dietary Supplements:Capsule and tablet formats for pharmacy and health food retail. Lower regulatory barriers than infant nutrition enable faster ingredient switching based on spot pricing.
- Animal Feed:Mannanooligosaccharides for gut health in poultry and swine operations. Feed safety regulations under EU Feed Hygiene Regulation shape supplier qualification, though purity specifications remain below human food tiers.
Food and beverages deploy the widest supplier base; infant formulas concentrate the highest-margin procurement.
Distribution Channel:
Channel economics reflect customer technical support needs and order fragmentation, with direct sales relationships requiring specialized field application teams.
- Direct Sales:Long-term offtake contracts with infant formula and dairy processors, involving technical service agreements and joint formulation development. Kerry Group and similar integrated suppliers dominate this channel.
- Specialty Stores:Pharmacy and health food retail for finished prebiotic supplements. Staff training requirements and shelf placement fees elevate working capital intensity for brand owners.
- Supermarkets:Mass-market functional food placement, with retailer consolidation in Germany and France squeezing supplier margins through private-label substitution pressure.
- Online Retail:Direct-to-consumer and marketplace platforms, lowest capital entry point but highest customer acquisition cost volatility. Japanese and South Korean e-commerce ecosystems show advanced synbiotic bundling.
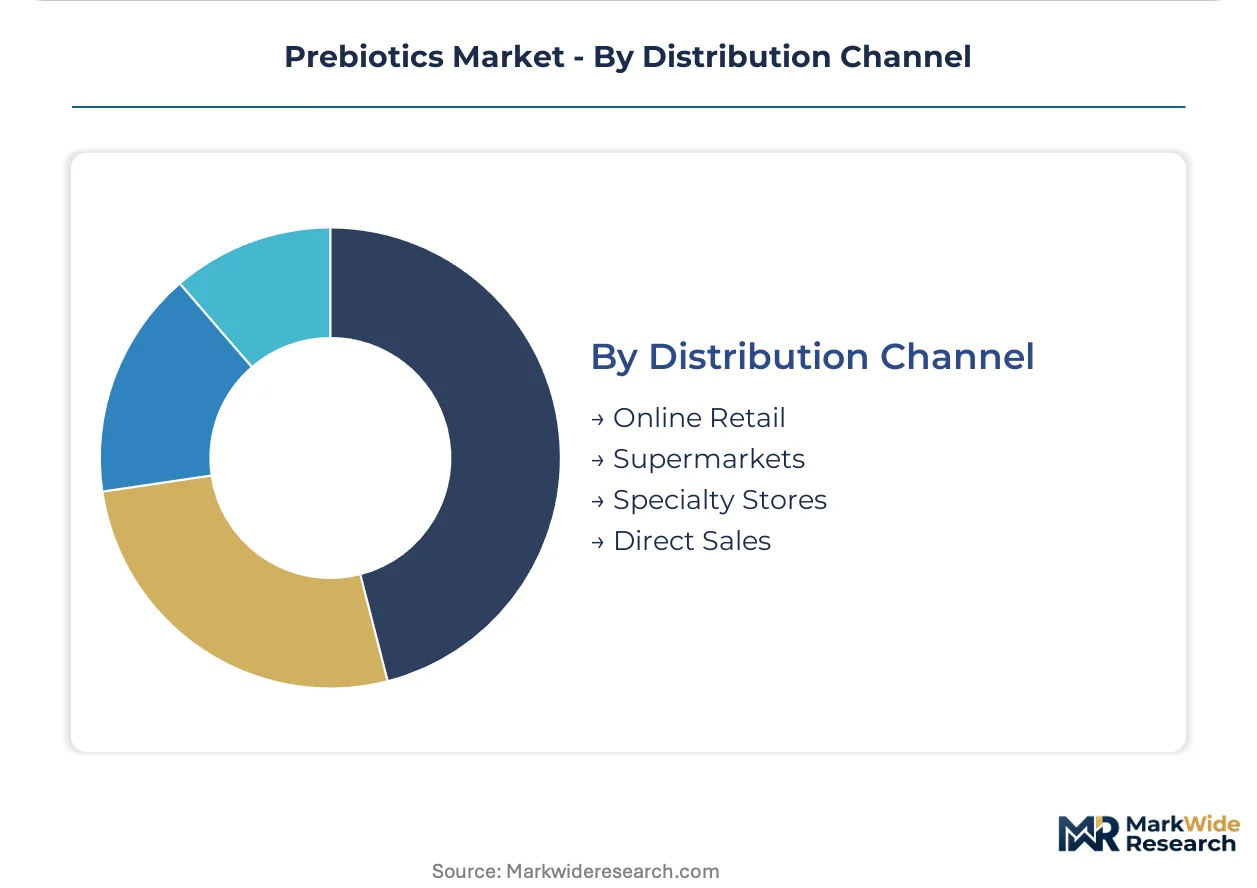
Direct sales lock in the most durable revenue; online retail climbs fastest as a share of finished product volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Benelux processing corridors and German dairy clusters concentrate prebiotic extraction capacity under EU Novel Food Regulation oversight. Tax-advantaged industrial zones in Flanders and Lower Saxony anchor chicory root processing investments.
Germany
Infant formula manufacturers in Bavaria and North Rhine-Westphalia drive galactooligosaccharide procurement for pharmacy-channel positioning. EFSA novel food assessments filter supplier qualification, with ISO 22000 certification mandatory for dairy fortification partnerships. Frankfurt-Rhine-Main logistics hubs coordinate just-in-time delivery to yogurt processors.
Netherlands
Enzymatic synthesis platforms near Rotterdam and Eindhoven bypass agricultural feedstock constraints for lactose-derived oligosaccharides. REACH compliance costs filter smaller extraction operators, concentrating supply among scaled bioreactor operators. Wageningen University clusters anchor microbiome research partnerships with formula manufacturers.
France
Chicory root inulin extraction concentrates in Hauts-de-France and Île-de-France processing corridors. EU F-Gas Regulation pressures solvent transition toward supercritical CO2 systems for green chemistry certification. Lille and Paris basin facilities supply dairy fortification channels across the Benelux corridor.
Belgium
Flemish agricultural zones anchor European chicory root supply, with extraction capacity concentrated near Antwerp and Ghent. EFSA health claim substantiation rigor blocks label permissibility for emerging chemistries, freezing commercialization pathways. Kortrijk industrial parks host spray-drying operations for powder-format exports.
Japan
Fermented dairy heritage drives synbiotic bundling in Tokyo-Osaka retail corridors. METI standards shape probiotic-prebiotic formulation protocols for convenience-store channels. Yakult-established consumer education accelerates bundled product acceptance in Kanto and Kansai metropolitan markets.
Prebiotics Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated dairy processors commanding captive demand while independent ingredient suppliers compete on technical service differentiation. The vendor base organizes around three archetypes: fermentation-derived probiotic houses with synbiotic bundling capabilities, agricultural extraction operators with seasonal raw material exposure, and enzymatic synthesis platforms with bioprocess flexibility. Dominant competitive moves include backward integration into captive oligosaccharide production and geographic expansion through joint formulation development agreements.
Within the integrated dairy tier, Danone and Nestlé exemplify vertically structured competitors leveraging captive inulin demand across yogurt and infant nutrition portfolios. Kerry Group occupies a technical-services niche distinct from commodity suppliers, specializing in customized oligosaccharide blends for beverage applications. Yakult Honsha anchors synbiotic positioning through fermented dairy heritage, representing the probiotic-prebiotic bundling archetype across Asian retail channels.
| Leading Market Players |
|---|
| Yakult Honsha |
| Danone |
| Chr. Hansen |
| Kerry Group |
| ADM |
| DuPont |
| BioGaia |
| dsm-firmenich |
| Nestlé |
| Others |
Supply Flow & Price Mechanics
Chicory root harvest volatility in Flemish agricultural zones cascades through three-tier pricing structure across premium, standard, and economy levels, with infant formula manufacturers absorbing premium tiers for EFSA-certified supply while animal feed buyers capture spot-market discounts during bumper crop cycles.
Pricing Analysis
Short lead-time premiums of 15-20 percent above contract baselines dominate spot procurement for galactooligosaccharide alternatives when Belgian chicory processors face extraction schedule disruptions. Price differentiation separates pharmaceutical-grade infant formula certifications from commodity dairy fortification tiers, with ISO 22000 and EFSA novel food dossier maintenance driving substantial uplifts. Cost compression in standard-grade inulin is intensifying because enzymatic synthesis platforms in the Netherlands erode agricultural extraction margins. Animal feed applications exhibit highest price sensitivity due to lower purity thresholds, while infant formula procurement shows lowest elasticity given regulatory lock-in effects.
Supply Chain Analysis
Technical staffing shortages in enzymatic bioreactor operations near Rotterdam and Eindhoven constrain capacity expansion timelines for lactose-derived oligosaccharide producers. Supply concentrates in France, Belgium, and the Netherlands for chicory root extraction and enzymatic synthesis respectively, with German dairy processors drawing from Benelux corridors for just-in-time fortification. Raw material dependencies span Flemish chicory root harvests, lactose feedstock from dairy cooperatives, and fungal β-galactosidase enzyme supplies. Single-source vulnerability in Flemish agricultural zones exposes processors to weather-driven yield disruptions. Distribution runs through direct sales relationships with infant formula manufacturers and specialty ingredient distributors serving beverage compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation-derived oligosaccharides are displacing legacy agricultural extraction routes, with enzymatic synthesis platforms enabling tailored degree-of-polymerization distributions that bypass chicory root harvest constraints.
For Market Incumbents: Extend captive bioreactor investments near Rotterdam and Eindhoven to secure supply independence from Flemish weather patterns, while consolidating EFSA novel food dossier maintenance capabilities to defend against emerging enzymatic competitors. Backward integration into lactose feedstock partnerships with Dutch dairy cooperatives anchors cost position against spot-market volatility. For New Entrants and Emerging Players: Hospital and enteral feeding channels outside neonatal intensive care settings represent the most penetrable white-space target, with clinical nutrition applications in Germany showing minimal existing galactooligosaccharide fortification. Ready-to-drink beverage convenience retail in Japan and South Korea offers secondary entry through synbiotic bundling partnerships with established fermented dairy houses. For Investors and Strategic Acquirers: EFSA approval of strain-specific bacterial-target health claims is the leading indicator that precision fermentation platforms will command premium positioning over commodity inulin processors. Long-term viability over the next decade rests on acquiring enzymatic synthesis operators with documented bifidogenic specificity and existing novel food dossiers, with Wageningen University research partnerships serving as quality signals for technical differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Synthesis Platform Investment | Enables bypass of Belgian chicory root harvest cycles for supply security. |
| EFSA Novel Food Dossier Expansion | Secures label permissibility for emerging bacterial-target mechanisms in dairy. |
| Supercritical CO2 Extraction Transition | Qualifies processors for EU F-Gas Regulation green chemistry certification premiums. |
| Clinical Nutrition Channel Development | Captures underdeveloped hospital and enteral feeding applications beyond neonatal care. |
| Synbiotic Bundling Partnership | Leverages Yakult-established consumer education in Japanese and South Korean retail. |
Methodological Framework
Multi-period observation of EFSA novel food approval timelines, chicory root harvest yields, and enzymatic synthesis capacity deployments anchored the trend analysis, supplemented by interviews with infant formula procurement directors, dairy fortification technical leads, enzymatic bioreactor operators, and EFSA regulatory affairs specialists. Secondary validation drew from EFSA novel food register entries, REACH compliance filings, EU F-Gas Regulation implementation reports, and customs trade data for oligosaccharide imports. Bottom-up capacity modeling and top-down demand segmentation were triangulated to cross-verify volume estimates.
Input-output matrices mapped lactose feedstock availability, transglycosidase enzyme supply constraints, and end-use certification requirements across product type, form, and end user dimensions throughout the forecast period. CAGRs were derived from segmented growth rate reconciliation against macroeconomic consumption indicators. Industry-specific forecast inputs included EFSA health claim substantiation timelines and Flemish agricultural yield variance patterns.
Revisions become necessary when EFSA rejects bacterial-target mechanism dossiers, Flemish weather patterns disrupt consecutive chicory harvests, or enzymatic synthesis platforms achieve cost parity with agricultural extraction. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Beta Lactoglobulin Protein Market
Food Biotechnology
Glucose Oxidase Market
Food Biotechnology
Direct-Fed Microbial Products Market
Food Biotechnology
Papain Market
Food Biotechnology
Salmon Polynucleotide (PN) Market
Food Biotechnology
Microalgae Market
Food Biotechnology
Pullulanase Market
Food Biotechnology
Europe Eubiotics Market
Food Biotechnology
Flaxseed Gum Market
Food Biotechnology
Global GMO Testing Market
Food Biotechnology
Bovine Colostrum Market
Food Biotechnology
Brown Algae Protein Market
Food Biotechnology
Africa Eubiotics Market
Food Biotechnology
Red Seaweed Extract Market
Food Biotechnology
Bangladesh Starch and Starch Derivative Market
Food Biotechnology
Trypsin Market