
 Europe Eubiotics Market | 2026-2036
Europe Eubiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Eubiotics Market Foresight
Specialized poultry integrators are reorganizing feed additive procurement toward microbiome-targeted solutions as conventional antibiotic growth promoters face phase-out pressure across European livestock operations. Chr. Hansen A/S leverages decades of strain-banking expertise to dominate direct-fed microbial supply for Danish and Dutch integrators. BASF SE anchors its position through captive production of butyrate derivatives serving German compound feed mills. Royal DSM competes via enzymatic prebiotic platforms that reduce feed conversion ratios in broiler operations.
Eubiotics comprise live microorganisms, microbial metabolites, and fermentable substrates that modulate gastrointestinal microbiota to enhance nutrient absorption, pathogen exclusion, and immune modulation in animals and humans. Industrial production employs submerged fermentation, spray-drying stabilization, and microencapsulation to preserve viability through pelleting temperatures exceeding eighty-five degrees Celsius. Probiotics command the largest installed fermentation capacity, while postbiotics attract fastest-growing investment due to longer shelf stability and simpler regulatory pathways. Animal feed absorbs the dominant volume share, though functional foods generate superior per-kilogram margins as human-grade certification requirements tighten supply pools.
The European Food Safety Authority mandates novel food authorization for postbiotic ingredients entering human applications, while REACH governs chemical characterization of organic acid-based eubiotics in industrial feed use. EMA guidelines on veterinary medicinal products versus feed additives create classification ambiguity that shapes commercialization timelines and clinical trial obligations. Stakeholders must monitor strain-level patent thickets and evolving EFSA Qualified Presumption of Safety protocols to secure durable market access.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing fermentation-based production economics while Danish and Dutch poultry integrators accelerate microbiome-targeted procurement, creating a bifurcation between legacy acidifiers and next-generation postbiotics.
Growth Catalysts
- EFSA Qualified Presumption of Safety protocols:Streamlined strain authorization accelerates novel probiotic commercialization for compound feed mills seeking antibiotic-free growth promotion.
- Submerged fermentation scale-up:Capital investments in spray-drying stabilization preserve viability through pelleting temperatures exceeding eighty-five degrees Celsius, unlocking premium broiler formulations.
- Netherlands poultry integration density:Specialized integrators concentrate procurement power, consolidating supplier relationships around gut-health platforms with demonstrated feed conversion ratio improvements.
Market Restraints
- Natural gas input volatility:Steam sterilization and temperature-controlled fermentation depend on energy-intensive thermal management, exposing margin structures to continental supply disruptions.
- Strain-level patent thickets:Decades of microbial banking by incumbent suppliers create licensing friction for new entrants seeking differentiated Lactobacillus and Bacillus formulations.
- REACH chemical characterization:Organic acid-based eubiotics face extended dossier requirements for industrial feed registration, elongating commercialization timelines relative to live microbial alternatives.
Strategic Opportunities
- Poland and Romania underpenetration:Eastern European compound feed capacity expansion outpaces local eubiotic formulation expertise, creating import dependency for microbiome-targeted additives.
- Human-grade functional foods:Novel food authorization pathways for postbiotics command superior per-kilogram margins versus animal feed, tightening supply pools toward certified production lines.
- Enzymatic prebiotic convergence:Carbohydrate-active enzymes paired with fermentable substrates reduce antinutritional factors in wheat-heavy rations, addressing regional grain sourcing patterns.
Industry Challenges
- Microencapsulation talent scarcity:Formulation chemists capable of engineering thermal-protective matrices for direct-fed microbials command premium compensation in a shallow labor pool.
- Veterinary medicinal product classification ambiguity:EMA guidelines create jurisdictional overlap with feed additive frameworks, forcing dual-track regulatory strategies and redundant clinical obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Eubiotics Market |
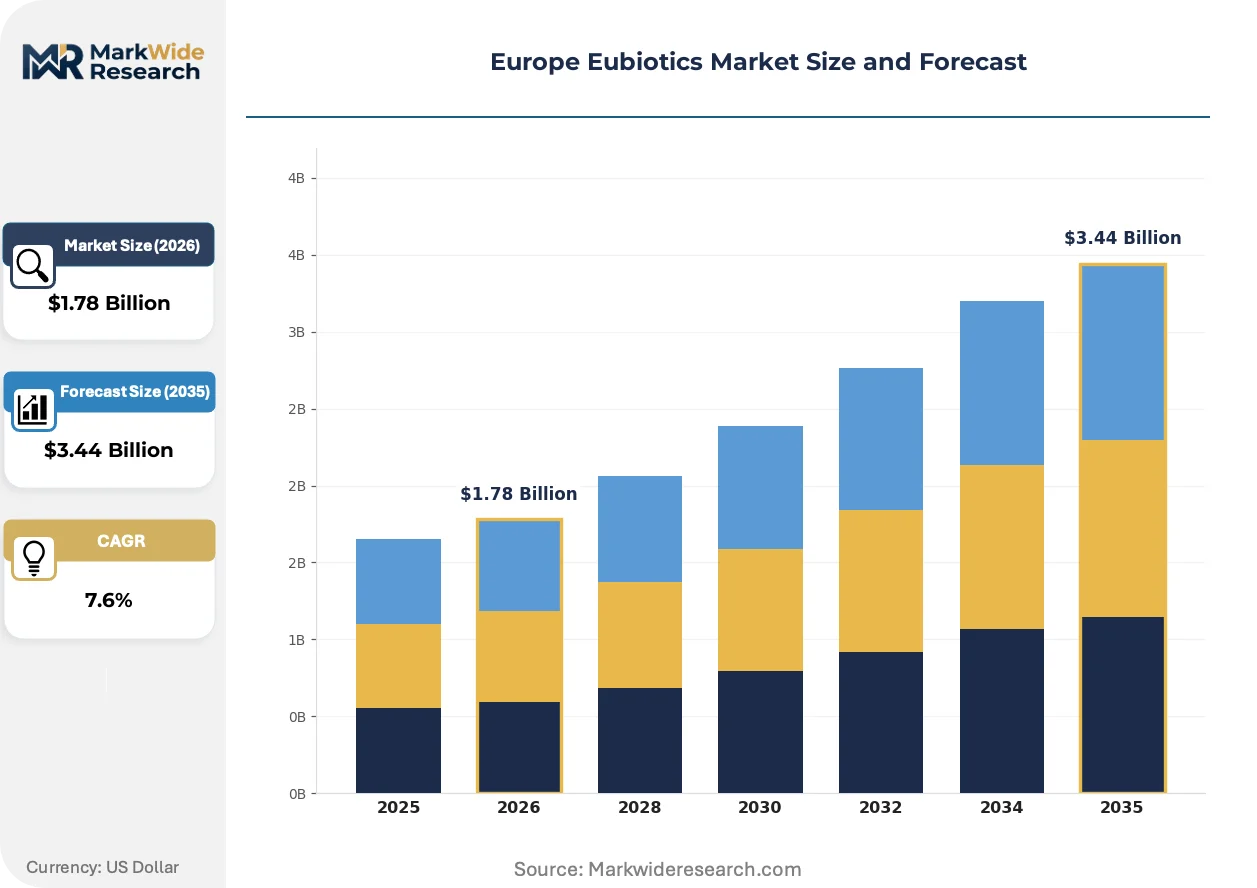
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $3.44 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Prebiotics, Postbiotics, Synbiotics End User: Animal Feed, Functional Foods, Dietary Supplements, Pharmaceuticals Application: Intestinal Health, Immune Support, Nutritional Enrichment, Metabolic Health Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Royal DSM, Cargill, BASF SE, Novus International, Kemin Industries, Syngenta AG, Chr. Hansen A/S, ADM, Bayer Crop Science, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Eubiotics Market Shifts & Advancements
Postbiotic platforms are compressing the competitive landscape as thermal stability and simplified regulatory pathways displace live culture dependency in high-temperature pelleting environments.
Spray-dried microbial metabolites is displacing freeze-dried live probiotics in German compound feed operations, where pelleting temperatures degrade traditional formulations. BASF SE and Royal DSM have redirected R&D toward butyrate derivatives and enzymatic prebiotics that withstand thermal stress without viability loss. This displacement is compressing fermentation capacity utilization for legacy probiotic strains while expanding postbiotic manufacturing footprints.
REACH and the F-Gas Regulation tighten chemical characterization and greenhouse gas accounting for organic acid production facilities across Germany, France, and the Netherlands. Fermentation plants must retrofit vapor recovery systems and document carbon intensity per kilogram of butyrate or propionate output. Danish suppliers face the strictest enforcement, accelerating capital deployment toward closed-loop bioreactor designs.
Specialized poultry integrators now specify microbiome-targeted solutions in multi-year procurement contracts, displacing spot-market purchasing of generic acidifiers. Dutch and French broiler operations consolidate supplier relationships around platforms with documented pathogen exclusion data. This concentration is most visible in the Netherlands, where vertical integration between breeding, feed milling, and processing creates closed-loop demand for certified gut-health additives.
Europe Eubiotics Market Segmentation
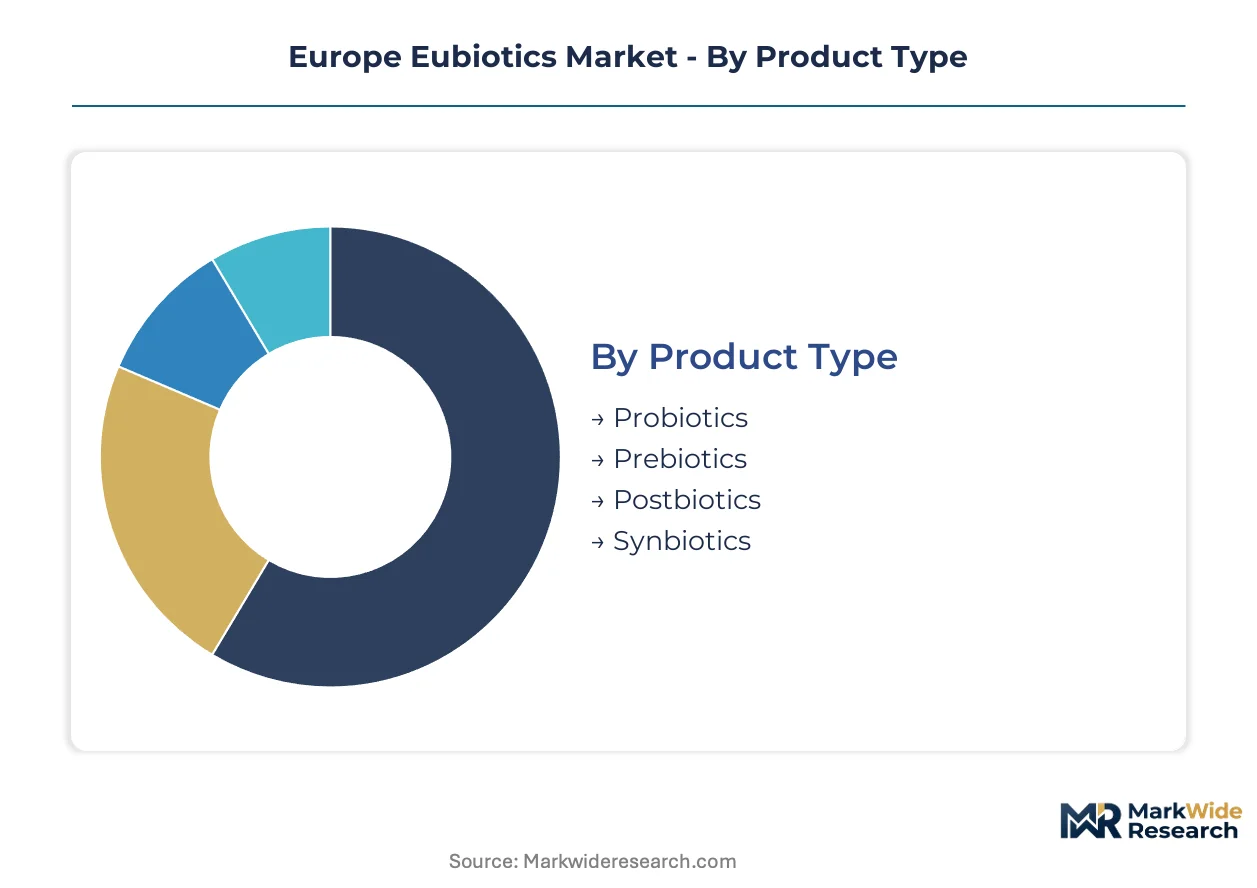
Eubiotics suppliers structure their portfolios around thermal stability requirements and regulatory pathway complexity. Segmentation reveals where live microbial formats face displacement pressure from metabolite-based alternatives.
Product Type:
Postbiotics and synbiotics exert substitution pressure on conventional live cultures as compound feed mills seek pelleting tolerance without viability loss.
- Probiotics:Live bacterial cultures of Lactobacillus, Bacillus, and Enterococcus strains require microencapsulation or spray-drying to survive pelleting temperatures. Danish and Dutch poultry integrators specify strain-level documentation for pathogen exclusion claims, tightening qualification timelines for new suppliers.
- Postbiotics:Heat-inactivated microbial cells and metabolites offer thermal stability exceeding eighty-five degrees Celsius without viability constraints. EFSA novel food authorization for human applications and simplified feed additive registration accelerate commercialization versus live alternatives.
- Prebiotics:Fermentable oligosaccharides and inulin derivatives stimulate indigenous microbiota without fermentation infrastructure constraints.
- Synbiotics:Combined probiotic-prebiotic formulations optimize colonization efficiency in intestinal health applications.
Postbiotics retains volume leadership; postbiotics holds the steepest expansion curve.
End User:
Cost tier stratification separates commodity animal feed from certified human-grade production lines demanding segregated fermentation capacity.
- Animal Feed:Compound feed mills across Germany, France, and the Netherlands absorb the dominant volume share. Broiler operations prioritize feed conversion ratio improvements, while swine integrators emphasize pathogen exclusion during post-weaning stress periods.
- Functional Foods:Human-grade certification requirements tighten supply pools toward dedicated production lines. Novel food authorization pathways command per-kilogram premiums three to five times above feed-grade equivalents.
- Dietary Supplements:Capsule and sachet formats target consumer gut health positioning with strain-specific immune modulation claims.
- Pharmaceuticals:Live biotherapeutic products face EMA veterinary medicinal product classification ambiguity, elongating clinical trial obligations.
Animal feed dominates absolute tonnage; functional foods generates the highest margin per kilogram.
Application:
Customer type concentration in vertically integrated poultry operations concentrates procurement power around intestinal health platforms with documented performance data.
- Intestinal Health:Microbiome modulation for nutrient absorption and pathogen exclusion anchors demand from Netherlands broiler integrators. Multi-year procurement contracts now specify colony-forming unit guarantees and metabolite profiling.
- Immune Support:Beta-glucan and exopolysaccharide applications target reduction of veterinary antibiotic dependence in French and German livestock operations.
- Nutritional Enrichment:Vitamin and short-chain fatty acid synthesis by gut microbiota enhances bioavailability in wheat-heavy rations common across Eastern Europe.
- Metabolic Health:Butyrate derivatives modulate insulin sensitivity and lipid profiles in transition dairy cattle.
Intestinal health commands the largest addressable base; immune support is climbing fastest on regulatory tailwinds.
Distribution Channel:
Supply concentration among specialized ingredient distributors shapes access patterns for compound feed mills versus direct manufacturer relationships.
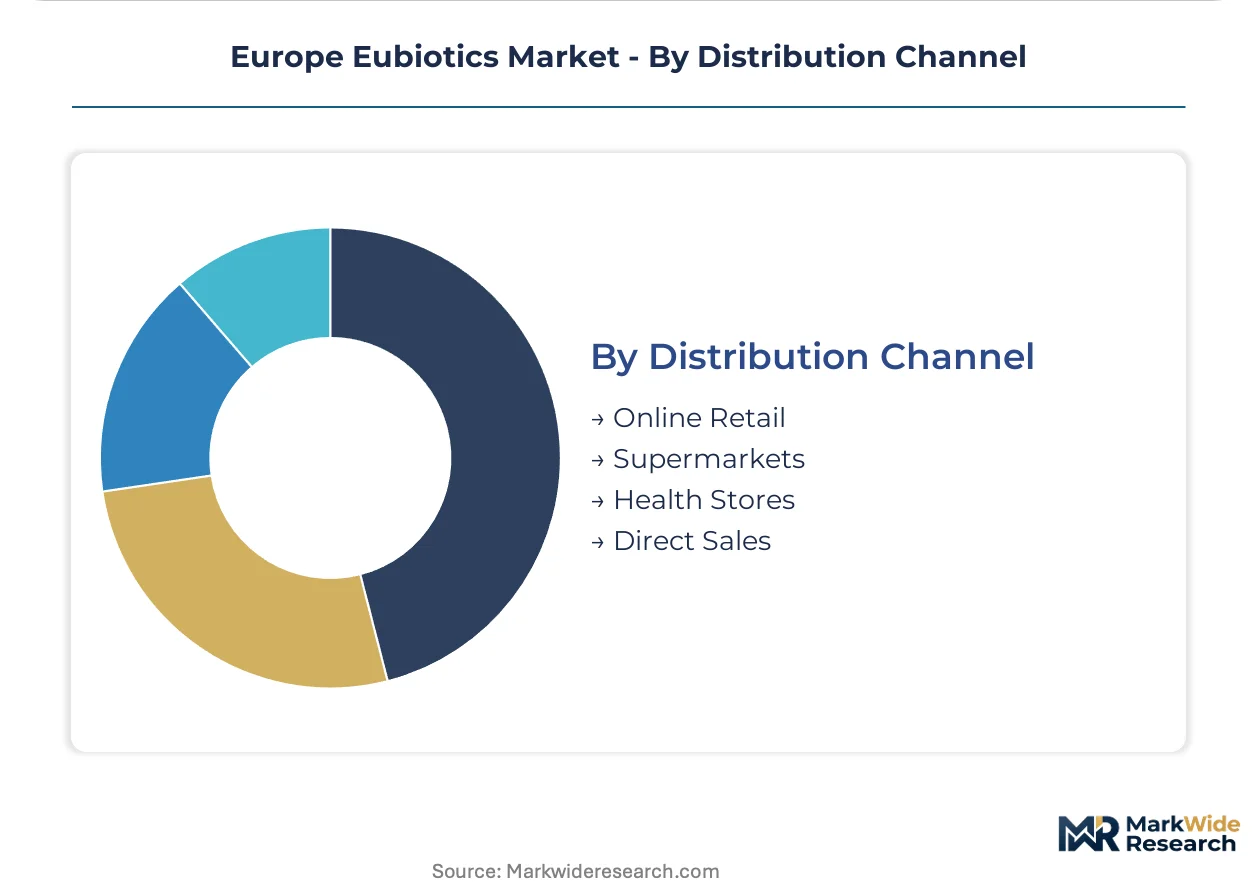
- Direct Sales:Large poultry integrators in the Netherlands and Denmark negotiate multi-year supply agreements with Chr. Hansen A/S and Royal DSM, bypassing distributor margins for strain-banked proprietary formats.
- Online Retail:Human-grade probiotics and postbiotics reach consumers through pharmacy platforms and specialized supplement portals with batch-level traceability documentation.
- Supermarkets:Functional food applications with EFSA-approved health claims penetrate mass retail through yogurt and fermented beverage formats.
- Health Stores:Premium-positioned synbiotics target consumer segments seeking organic and non-GMO certification.
Direct sales captures the bulk of animal feed volume; online retail is expanding most quickly in human applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine Corridor freight network connects Rotterdam's deepwater port to Basel's chemical complex, underwriting Northern Europe's dominance in fermentation-based feed additive supply chains.
Germany
Compound feed mills in Lower Saxony and North Rhine-Westphalia absorb the dominant volume of butyrate derivatives and enzymatic prebiotics. REACH chemical characterization requirements elongate registration timelines for organic acid-based eubiotics. BASF SE anchors captive production in Ludwigshafen, supplying German mills with thermal-stable formulations.
Netherlands
Vertically integrated poultry operations in Gelderland and Overijssel specify microbiome-targeted solutions in multi-year procurement contracts. The EU Green Deal tightens greenhouse gas accounting for fermentation facilities across the Randstad. Chr. Hansen A/S leverages strain-banking expertise to dominate direct-fed microbial supply for Dutch integrators.
France
Broiler operations in Brittany and Pays de la Loire prioritize pathogen exclusion claims in feed additive selection. EFSA Qualified Presumption of Safety protocols streamline novel probiotic authorization for compound feed applications. Royal DSM competes via enzymatic prebiotic platforms serving French livestock operations.
Denmark
Specialized poultry integrators reorganize procurement toward gut-health solutions as antibiotic growth promoters face phase-out pressure. The F-Gas Regulation compresses fermentation-based production economics for Danish suppliers. Copenhagen-based suppliers face strictest enforcement, accelerating capital deployment toward closed-loop bioreactor designs.
Poland
Eastern European compound feed capacity expansion outpaces local eubiotic formulation expertise, creating import dependency. EMA guidelines on veterinary medicinal products versus feed additives create classification ambiguity affecting commercialization timelines. Warsaw and Poznań clusters rely on German and Dutch suppliers for microbiome-targeted additives.
Europe Eubiotics Market Competitive Landscape
Listed leaders compete with private specialists across strain-banking depth and fermentation scale, creating a tiered structure where proprietary microbial collections anchor durable supply relationships. The vendor base clusters around three strategic archetypes: integrated chemical conglomerates with captive acid production, specialized microbial houses with decades of strain documentation, and diversified nutrition platforms with enzymatic prebiotic portfolios. Competitive moves concentrate on multi-year procurement contracting with poultry integrators and retrofitting fermentation capacity for postbiotic manufacturing.
Within the microbial specialist tier, Chr. Hansen A/S exemplifies strain-banking dominance, while BASF SE occupies a position as a chemical-integrated supplier. Royal DSM anchors the enzymatic prebiotic vector. These three represent distinct competitive positions: proprietary culture collections, captive organic acid derivatives, and carbohydrate-active enzyme platforms.
| Leading Market Players |
|---|
| Royal DSM |
| Cargill |
| BASF SE |
| Novus International |
| Kemin Industries |
| Syngenta AG |
| Chr. Hansen A/S |
| ADM |
| Bayer Crop Science |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day strain-banking lead times for proprietary Lactobacillus and Bacillus collections concentrate pricing power with Danish and Dutch microbial houses, while German compound feed mills absorb cost pass-throughs from captive butyrate production. This inventory intensity rewards incumbents with decades of culture documentation and squeezes spot-market buyers into premium tiering.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates strain-banked proprietary formats from generic acidifiers and commodity spot purchases. Premium tiers command certification-grade documentation for EFSA Qualified Presumption of Safety protocols, while standard tiers serve volume compound feed mills with thermal-stable postbiotics. Cost compression in the economy tier is intensifying because Eastern European import dependency creates oversupply of undifferentiated organic acid blends. Poultry integrators in the Netherlands exhibit lowest price sensitivity due to multi-year procurement contracting, whereas Polish compound feed mills face highest sensitivity from fragmented supplier relationships.
Supply Chain Analysis
Rotterdam port congestion and Rhine-Alpine freight bottlenecks elevate inbound logistics costs for fermentation feedstocks arriving from North American corn belt and Brazilian sugarcane regions. Supply concentrates in Germany, the Netherlands, and Denmark, where submerged fermentation infrastructure draws from molasses, whey permeate, and refined glucose feedstocks. Single-source vulnerability sits with Danish strain-banking facilities supplying Dutch poultry integrators. Distribution runs through specialized ingredient distributors for mid-tier compound feed mills, while direct manufacturer relationships dominate large integrator procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Postbiotic formulation services and strain-level technical support are expanding faster than commodity probiotic manufacturing, creating attach-rate opportunities for suppliers pivoting from hardware to recurring-revenue models.
For Market Incumbents: Shield proprietary culture collections through accelerated patent thicketing around thermal-tolerant Bacillus subtilis variants, while deepening backward integration into fermentation feedstock supply to offset natural gas volatility in steam sterilization operations. Regulatory ambiguity from EMA veterinary medicinal product classification demands dual-track dossier investment to preempt feed additive displacement. For New Entrants and Emerging Players: Anchor in Poland and Romania's import-dependent compound feed expansion, where local formulation expertise scarcity creates white-space for microbiome-targeted additive partnerships. The most penetrable vector lies in enzymatic prebiotic convergence for wheat-heavy Eastern European rations. A technical-service-heavy go-to-market model can bypass incumbent strain-banking advantages. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because postbiotic manufacturing footprints require capital intensity that fragments below optimal scale, and strain-level IP scarcity will drive rollup premiums. Target acquisition archetype: mid-cap microbial houses with documented EFSA safety dossiers but subscale fermentation capacity. The signal to watch is F-Gas Regulation enforcement tightening on Danish suppliers, accelerating distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Postbiotic Manufacturing Scale-Up | Captures pelleting-temperature tolerance demand from German compound feed mills replacing freeze-dried live cultures. |
| Backward Integration into Feedstock Supply | Secures molasses and whey permeate sourcing against Rhine-Alpine logistics congestion and commodity volatility. |
| EFSA Novel Food Authorization Pathway | Unlocks per-kilogram margin premiums in human-grade functional foods versus animal feed grade production. |
| Multi-Year Procurement Contracting | Locks in Dutch poultry integrator demand and displaces spot-market acidifier purchasing with guaranteed supply. |
| Closed-Loop Bioreactor Retrofit | Anticipates strictest EU Green Deal enforcement in Denmark and preserves fermentation economics under F-Gas Regulation. |
Research Methodology
Initial hypotheses were tested against primary input from fermentation plant managers, compound feed procurement leads, poultry integrator nutrition directors, and regulatory affairs specialists at EFSA and EMA, and refined through secondary validation. Data sources included customs records for organic acid and microbial culture trade flows, SEC 10-K filings from listed nutrition conglomerates, EFSA novel food authorization databases, and Cefic chemical industry reports. Bottom-up strain-level production estimates and top-down regional demand aggregation were triangulated to reconcile volume figures.
Variance decomposition across product type, end user tier, application focus, and distribution channel dimensions anchored the analytical framework. CAGRs were derived from fitted growth curves applied to segment-level baselines. Industry-specific forecast inputs included pelleting temperature tolerance adoption curves for postbiotics and EFSA authorization timeline probabilities for novel probiotic strains.
Material uncertainties — natural gas supply disruptions, EMA classification rulings, and strain-level patent litigation outcomes — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway stability and fermentation capacity expansion schedules. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Non-Animal Alternative Testing Market
Food Biotechnology
Beta-Propeller Phytases Market
Food Biotechnology
Apigenin Market
Food Biotechnology
Research-Grade Proteins Market
Food Biotechnology
Chlorella Market
Food Biotechnology
Bangladesh Starch and Starch Derivative Market
Food Biotechnology
Phycocyanin Market
Food Biotechnology
Trans-Galactooligosaccharides Market
Food Biotechnology
Cultured Meat Market
Food Biotechnology
Direct-Fed Microbial Products Market
Food Biotechnology
Microalgae Market
Food Biotechnology
Carbohydrate Enzyme Preparation Market
Food Biotechnology
Prebiotics Market
Food Biotechnology
Salmon Polynucleotide (PN) Market
Food Biotechnology
Brown Algae Protein Market
Food Biotechnology
Global Genetically Modified (GMO) Food Market