
 Papain Market | 2026-2036
Papain Market Size, Share, and Industry Trends Forecast 2026-2036
Papain Market Analysis
Pharmaceutical-grade papain is unwinding new revenue layers as contract manufacturers seek enzyme substitutes for synthetic catalysts. Senthil Papain and Food Products leverages captive papaya orchards in Tamil Nadu to control raw material quality from source. BASF SE anchors European distribution through its life sciences division, while Merck KGaA competes on GMP-certified supply chains for injectable-grade formulations.
Papain is a cysteine protease enzyme extracted from Carica papaya latex, typically standardized to activity levels between 50,000 and 1,000,000 USP units per milligram depending on purification grade. Food industry applications dominate volume consumption, where papain breaks down collagen and elastin in meat processing at temperatures between 50°C and 70°C. Powder formulations lead the form segment due to superior shelf stability and ease of bulk handling in industrial settings. Pharmaceutical applications represent the fastest-expanding application category, driven by wound debridement therapies and digestive aid formulations where stabilized papain resists gastric acid denaturation.
India's BIS and CDSCO enforce purity thresholds for enzyme preparations used in food and drug manufacturing, while the EU's REACH regulation and EFSA guidelines govern import specifications for papain entering European cosmetic and nutraceutical channels. These frameworks elevate compliance costs for smaller extractors but simultaneously reward certified producers with preferential procurement contracts from multinational end users. Stakeholders must monitor evolving enzyme classification debates between food additive and processing aid categories, as reclassification would trigger new labeling and dosage restrictions across major import jurisdictions.
Market Dynamics
Pharmaceutical-grade enzyme certification is compressing supplier margins while concentrating procurement among GMP-validated producers, fundamentally restructuring competitive access to wound care and digestive aid formulations.
Growth Catalysts
- Meat Processing Automation:Industrial tenderization systems in Brazil and Argentina are integrating papain dosing modules at scale, replacing manual brine injection with enzyme-activated spray tunnels.
- REACH Compliance Premium:ECHA registration requirements for enzyme imports into EU cosmetic channels are filtering out uncertified extractors, directing volume toward registered suppliers.
- Wound Debridement Protocols:Hospital systems in Germany and Switzerland are adopting enzymatic debridement as first-line therapy for diabetic foot ulcers, displacing mechanical methods.
Market Restraints
- Latex Yield Volatility:Carica papaya harvest cycles in Tamil Nadu and Karnataka create 15-20% seasonal variation in raw extract availability, forcing price hedging.
- Protease Substitution:Bromelain from pineapple stems and ficin from fig latex are capturing share in meat tenderization where cost sensitivity outweighs performance differentiation.
- BIS Purity Enforcement:India's Bureau of Indian Standards mandates HPLC-verified activity levels above 100,000 USP units per milligram for food-grade certification, raising QC overhead.
Strategic Opportunities
- Vietnam Cultivation Expansion:Mekong Delta provinces are establishing contract papaya orchards with 18-month maturity cycles, offering year-round latex collection outside Indian monsoon constraints.
- CDSCO Injectable Pathway:India's drug regulator is opening fast-track approval for stabilized papain formulations targeting post-surgical adhesion prevention, creating new pharmaceutical tier.
- Direct-to-Formulator Platforms:Specialty enzyme distributors are bypassing traditional chemical wholesalers to sell calibrated activity units directly to nutraceutical capsule manufacturers.
Industry Challenges
- Cold Chain Integrity:Liquid papain concentrates require maintained 4°C transport from Tamil Nadu extraction facilities to Mumbai pharmaceutical processors, with spoilage rates climbing during monsoon logistics disruptions.
- Cross-Contamination Protocols:Multi-product enzyme facilities must implement dedicated production lines to meet EFSA allergen segregation requirements for papain entering infant formula applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Papain Market |
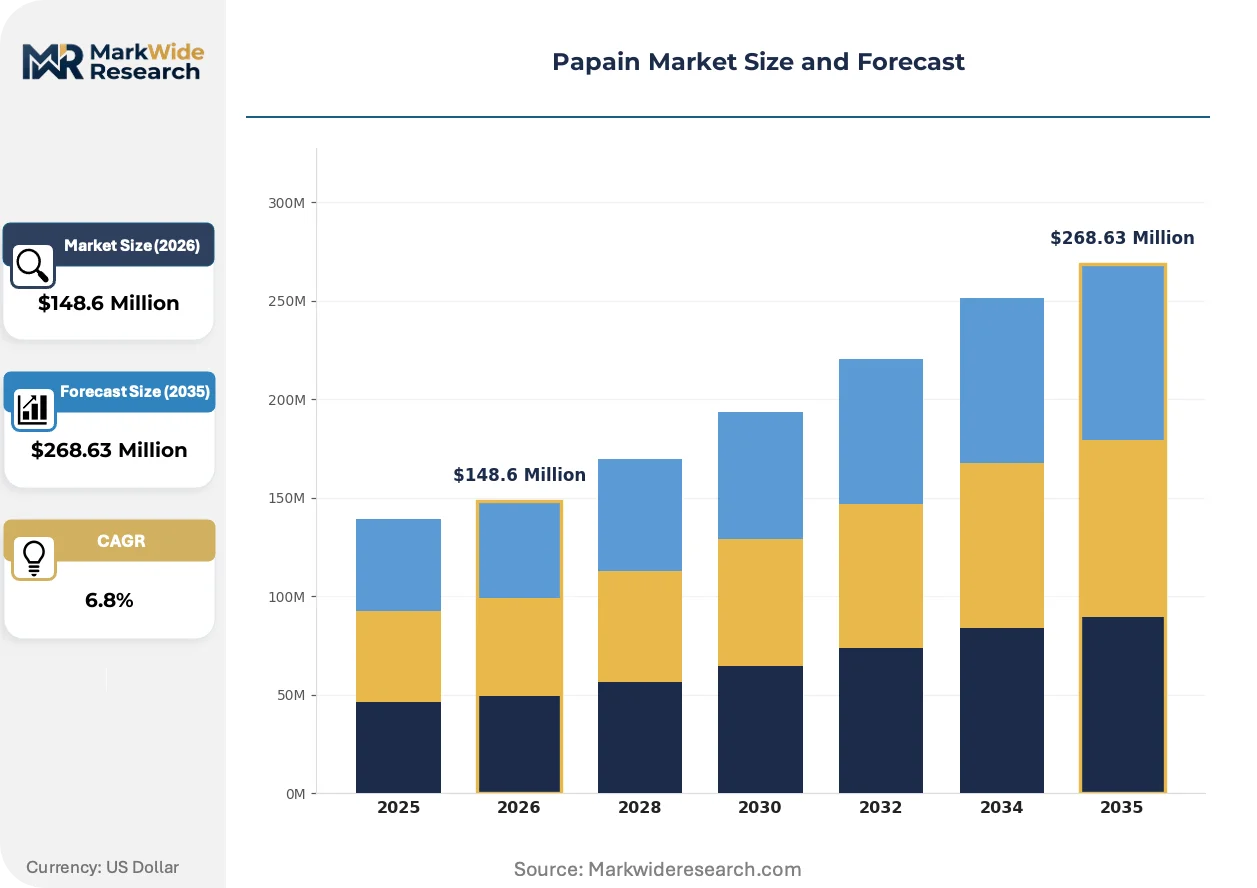
| Market Size in 2026 | $148.6 Million |
| Market Size in 2035 | $268.63 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Papain, Fermented Papain, Active Papain, Stabilized Papain Application: Food Industry, Pharmaceuticals, Cosmetics, Textile Industry End User: Food Manufacturers, Healthcare Providers, Cosmetic Companies, Textile Manufacturers Form: Powder, Liquid, Granules, Tablets |
| Companies Covered | Senthil Papain and Food Products, Fruzyme Biotech India, Shri Ganesh Industrial Enzymes, Aumgene Biosciences, Enzybel International, Ultra Bio-Logics Inc., BASF SE, Merck KGaA, Beckmann-Kenko GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Papain Market Emerging Trajectories
Enzyme stabilization chemistry and precision fermentation are converging to expand addressable applications beyond traditional food processing into therapeutic and cosmetic channels.
Immobilized papain bead technology is miniaturizing enzyme deployment in continuous-flow bioreactors. Pharmaceutical manufacturers in Switzerland are adopting packed-bed configurations for digestive aid synthesis. This architecture is compressing catalyst replacement cycles from quarterly to semi-annual intervals while reducing protein contamination in downstream purification.
REACH Annex XIV substance authorization is tightening import documentation for papain entering EU cosmetic formulations. ECHA now requires full toxicological dossiers for enzyme preparations above 1 ton annual import volume. German and French formulators are consolidating supplier bases to pre-registered producers with existing authorization numbers, marginalizing spot-market sourcing.
Certificate-of-analysis-driven procurement is displacing spot-price contracting among North American meat processors. Large packers in Nebraska and Iowa now mandate third-party-verified activity assays and allergen statements prior to shipment release. This behavioral shift is most visible in USDA-inspected facilities where HACCP documentation requirements intersect with buyer liability concerns.
Papain Market Segmentation
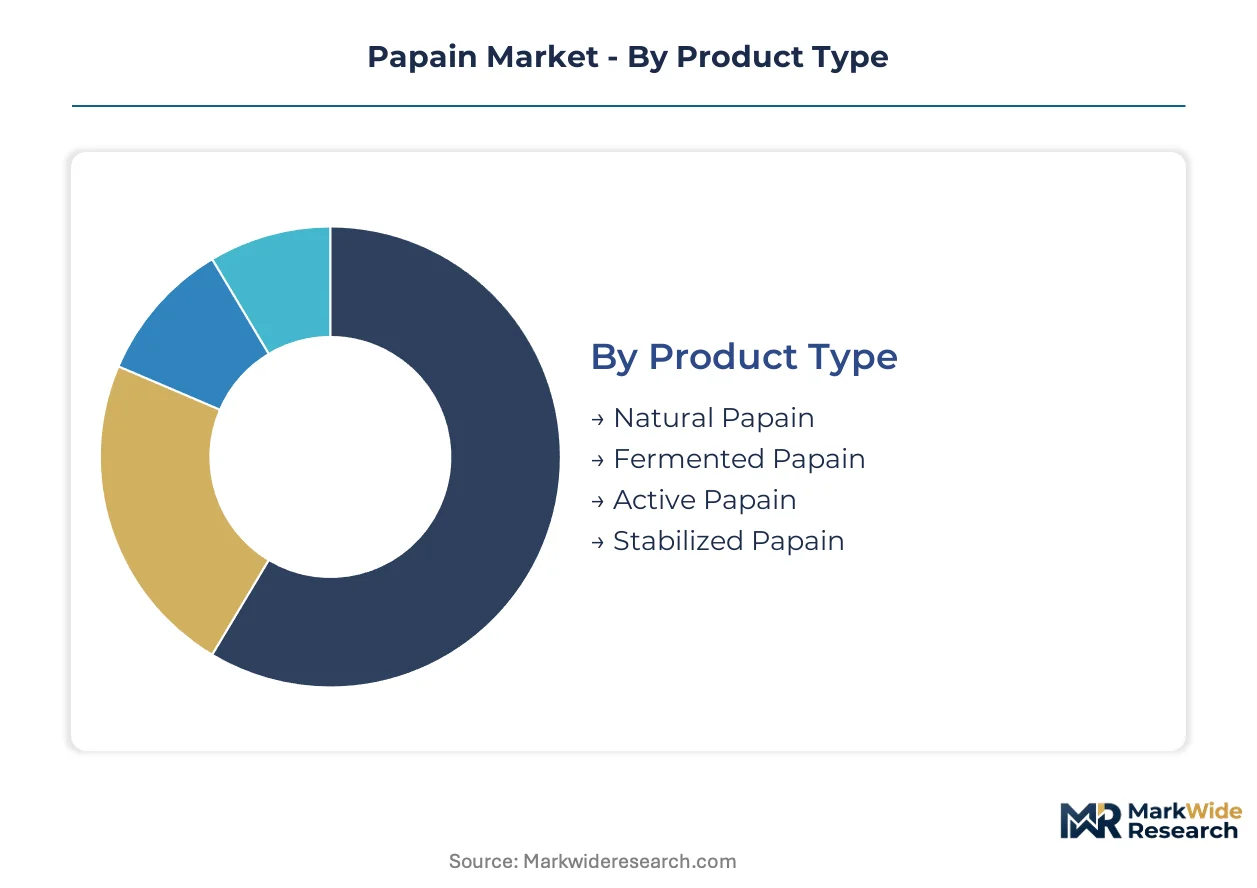
Papain's value chain fractures across purification grades and delivery formats, with each segment commanding distinct regulatory pathways and customer procurement criteria. Segmentation clarity enables suppliers to align fermentation investment with end-use certification requirements.
Product Type:
Natural and fermented variants dominate domestic Indian supply, while stabilized and active grades drive export pharmaceutical contracts to European and North American formulators.
- Natural Papain:Crude latex extract standardized to 50,000–100,000 USP units per milligram, retaining native cysteine protease ratios. Tamil Nadu extraction facilities supply bulk quantities to Brazilian meat processors seeking cost-efficient tenderization without synthetic additives.
- Fermented Papain:Submerged fermentation of recombinant strains in controlled bioreactors yields consistent activity profiles independent of harvest cycles. German pharmaceutical contract manufacturers source this grade for wound debridement formulations requiring batch-to-batch reproducibility under EMA guidelines.
- Active Papain:Lyophilized preparations with unmodified sulfhydryl groups for maximum catalytic efficiency in research applications.
- Stabilized Papain:Encapsulated or chemically protected variants resisting gastric acid denaturation in digestive aid tablets.
Natural papain holds the largest share; momentum sits with stabilized papain climbing the fastest on pharmaceutical formulation demand.
Application:
Cost tier separation is pronounced: food processing absorbs high-volume, lower-purity grades while pharmaceutical and cosmetic channels command 3–5x price multiples for certified material.
- Food Industry:Collagen and elastin hydrolysis in meat tenderization operates at 50°C–70°C process temperatures. Nebraska and Iowa beef packers now mandate HPLC-verified activity assays and allergen documentation prior to USDA-inspected facility delivery.
- Pharmaceuticals:Wound debridement therapies and digestive enzyme replacement formulations require GMP-validated supply chains. Swiss hospital systems are adopting enzymatic debridement as first-line therapy for diabetic foot ulcers, displacing mechanical methods under Swissmedic oversight.
- Cosmetics:Exfoliating enzyme masks and anti-aging formulations leverage papain's keratinolytic activity.
- Textile Industry:Biopolishing of cotton fabrics and silk degumming applications in South Asian garment manufacturing.
Food Industry maintains volume leadership; Pharmaceuticals are expanding most quickly on hospital protocol adoption.
End User:
Customer type determines procurement cadence: food manufacturers contract annually, healthcare providers tender quarterly, while cosmetic companies spot-purchase for campaign-driven production.
- Food Manufacturers:Industrial meat packers and protein hydrolysate producers purchase calibrated activity units in bulk powder form. Certificate-of-analysis-driven procurement is displacing spot-price contracting among North American processors.
- Healthcare Providers:Hospital pharmacies and specialty wound care clinics source stabilized formulations for inpatient debridement protocols.
- Cosmetic Companies:Formulators in France and Germany consolidate supplier bases to REACH-registered producers with existing ECHA authorization numbers.
- Textile Manufacturers:Bioprocessing units in Vietnam and Bangladesh integrate papain for enzymatic finishing of natural fibers.
Food Manufacturers capture the dominant procurement volume; Healthcare Providers are gaining share fastest on protocol standardization.
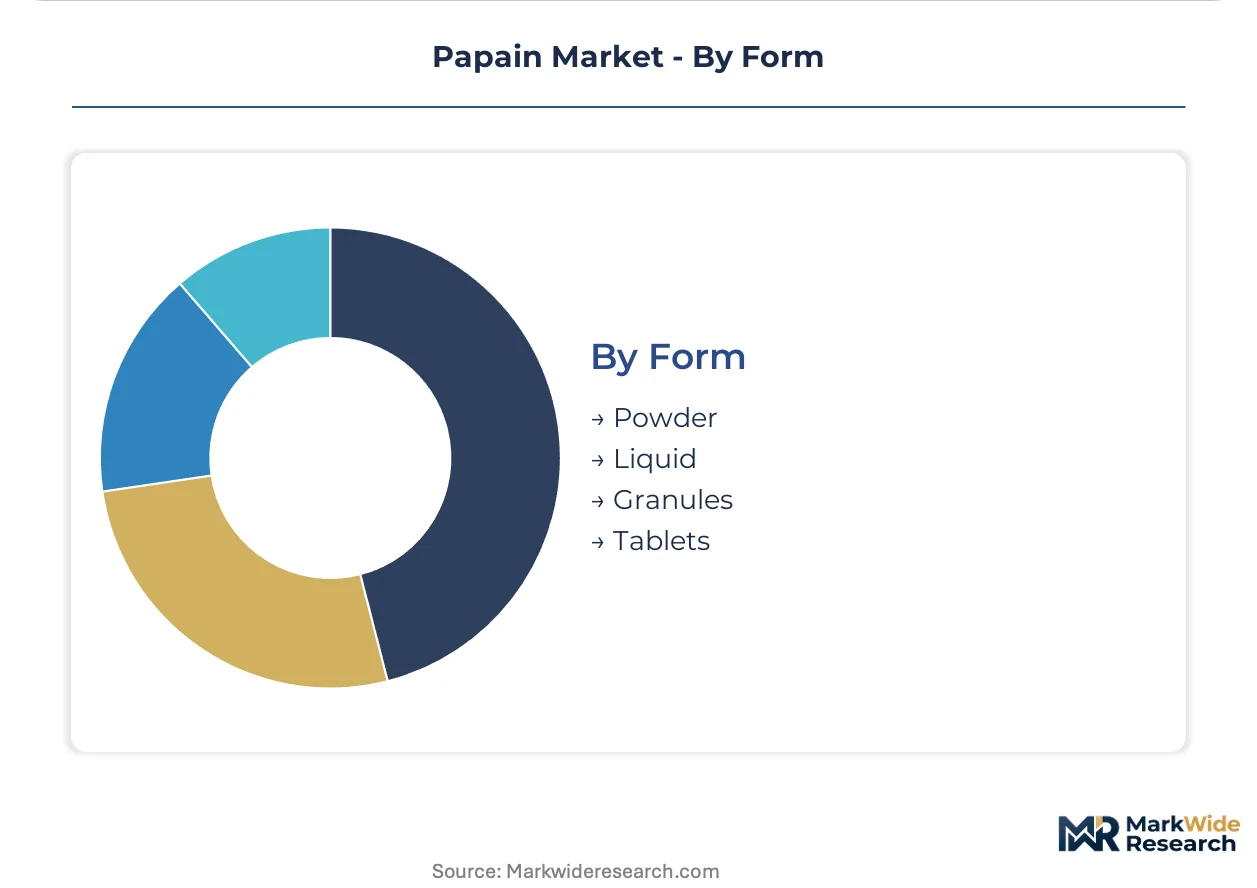
Form:
Supply concentration favors powder production in Tamil Nadu, while liquid formulations require cold-chain infrastructure concentrated near Mumbai pharmaceutical clusters.
- Powder:Spray-dried formulations with superior shelf stability and bulk handling characteristics dominate industrial procurement. Powder leads the form segment due to ease of dosing in automated meat processing lines and compatibility with standard blending equipment.
- Liquid:Concentrated extracts requiring 4°C maintained transport from extraction facilities to pharmaceutical processors, with spoilage risks climbing during monsoon logistics disruptions.
- Granules:Agglomerated particles for controlled-release applications in nutraceutical capsules.
- Tablets:Enteric-coated digestive aid formats for gastric acid resistance in retail pharmacy distribution.
Powder commands the largest installed base; Tablets are climbing the fastest on direct-to-consumer nutraceutical expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in meat tenderization applications contrasts sharply with premium procurement in pharmaceutical channels, creating divergent demand elasticity across import markets. Regulatory stringency varies: REACH-registered suppliers capture EU cosmetic contracts while BIS-certified extractors dominate Indian domestic supply.
India
Tamil Nadu and Karnataka host concentrated papaya latex extraction capacity serving Brazilian meat processors and domestic pharmaceutical formulators. CDSCO and BIS enforce HPLC-verified activity thresholds above 100,000 USP units per milligram for food-grade certification, elevating QC overhead for smaller extractors. Senthil Papain and Food Products leverages captive orchards near Coimbatore to control raw material quality from source.
Germany
Hospital systems in Bavaria and North Rhine-Westphalia are adopting enzymatic debridement as first-line therapy for diabetic foot ulcers under EMA and Swissmedic-aligned protocols. ECHA REACH Annex XIV requirements filter uncertified enzyme imports, directing cosmetic and nutraceutical volume toward pre-registered suppliers with existing authorization numbers. BASF SE anchors European distribution through its Ludwigshafen life sciences division.
United States
Nebraska and Iowa beef packers now mandate certificate-of-analysis-driven procurement with third-party-verified activity assays prior to USDA-inspected facility delivery. FDA oversight of digestive enzyme supplements and wound care formulations creates compliance barriers for non-GMP-validated foreign suppliers. Ultra Bio-Logics Inc. occupies a position among North American enzyme distributors.
Brazil
Industrial meat processing automation in São Paulo and Paraná integrates papain dosing modules at scale, replacing manual brine injection with enzyme-activated spray tunnels. ANVISA import regulations for enzyme preparations used in food manufacturing align with Mercosur technical standards. Cost sensitivity in commodity beef production favors natural papain grades over stabilized pharmaceutical alternatives.
Switzerland
Pharmaceutical contract manufacturers near Basel adopt immobilized papain bead technology in packed-bed bioreactors for digestive aid synthesis under Swissmedic GMP validation. Premium pricing for injectable-grade formulations rewards suppliers with dedicated production lines meeting EFSA allergen segregation requirements. Merck KGaA competes on certified supply chains for hospital pharmacy procurement.
Papain Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the papain value chain. The supplier base concentrates among Indian extractors with captive agricultural assets and European distributors with regulatory registration depth. Three archetypes dominate: orchard-integrated extractors controlling raw material quality, fermentation-based producers delivering batch-to-batch reproducibility, and GMP-validated pharmaceutical suppliers. Competitive moves center on REACH registration completion for EU market access and backward integration into papaya cultivation to hedge latex yield volatility.
Among Indian extraction specialists, Senthil Papain and Food Products exemplifies the orchard-integrated archetype through its Tamil Nadu-based operations. Fruzyme Biotech India and Shri Ganesh Industrial Enzymes occupy positions within the domestic supply tier serving food processing and textile applications. At the pharmaceutical-grade end, Merck KGaA and BASF SE represent the regulatory-certified distribution archetype anchoring European and North American procurement channels.
| Leading Market Players |
|---|
| Senthil Papain and Food Products |
| Fruzyme Biotech India |
| Shri Ganesh Industrial Enzymes |
| Aumgene Biosciences |
| Enzybel International |
| Ultra Bio-Logics Inc. |
| BASF SE |
| Merck KGaA |
| Beckmann-Kenko GmbH |
| Others |
Supply Flow & Price Mechanics
Bromelain substitution in Brazilian meat processing is simultaneously shifting procurement geography toward Southeast Asia and compressing natural papain price premiums, forcing Indian extractors to reposition on certification tiers rather than raw activity metrics.
Pricing Analysis
Certificate-of-analysis bundling drives lifetime value for pharmaceutical-grade suppliers. Three-tier pricing structure across GMP-certified, food-grade, and crude extract levels separates hospital procurement from commodity meat processing. Cost compression in standard-grade tenderization enzymes is intensifying because Brazilian packers now accept bromelain where performance specifications permit. Food manufacturers exhibit highest price sensitivity; Swiss hospital systems show lowest sensitivity due to protocol-locked supplier qualifications.
Supply Chain Analysis
India and Vietnam anchor global papain extraction, with Tamil Nadu facilities supplying Brazilian meat processors and Mekong Delta orchards emerging as monsoon-hedge capacity. Raw material flows draw from Carica papaya latex, fermentation substrates, and stabilized enzyme carriers. Single-source vulnerability concentrates in Tamil Nadu's monsoon-dependent harvest cycles. Distribution runs through specialty enzyme distributors serving pharmaceutical formulators and direct bulk contracts with meat packers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Papain procurement is becoming a platform-economics inflection as CDSCO fast-track pathways and REACH registration databases create interoperability between supplier certification tiers and buyer procurement systems.
For Market Incumbents: Shield GMP-validated market position by completing REACH Annex XIV authorization ahead of ECHA substance review deadlines. Deepen upstream control over papaya cultivation through contract orchard development in Vietnam's Mekong Delta, reducing exposure to Karnataka monsoon yield volatility. Prioritize dedicated production line segregation to meet EFSA allergen protocols for infant formula applications.
For New Entrants and Emerging Players: Lead with fermented papain production targeting German pharmaceutical contract manufacturers seeking batch-to-batch reproducibility under EMA guidelines. White-space availability sits with stabilized tablet formulations for direct-to-consumer digestive aid channels in North America. Go-to-market leverage: calibrated activity unit sales bypassing traditional chemical wholesalers to reach nutraceutical capsule manufacturers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors orchard-integrated extractors with captive agricultural assets and existing BIS certification. Long-term viability over the next decade rests on regulatory registration depth rather than extraction scale alone. Acquisition target archetype: Indian extractors with CDSCO pharmaceutical-grade approvals and established EU importer relationships. Signal to watch: ECHA substance authorization completion rates among mid-tier suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Annex XIV Authorization | ECHA registration unlocks EU cosmetic and nutraceutical procurement channels for certified suppliers. |
| Vietnam Cultivation Expansion | Mekong Delta contract orchards reduce monsoon-driven yield volatility affecting Tamil Nadu extraction. |
| CDSCO Injectable Pathway Entry | Fast-track approval for stabilized formulations targets post-surgical adhesion prevention applications. |
| Direct-to-Formulator Platform Launch | Calibrated activity unit sales bypass traditional chemical wholesalers serving nutraceutical manufacturers. |
| Immobilized Enzyme Technology Adoption | Packed-bed bioreactor configurations compress catalyst replacement cycles for Swiss pharmaceutical synthesis. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of CDSCO regulatory filings, ECHA registration databases, BIS certification records, and customs trade data. Primary interviews engaged extraction facility managers, pharmaceutical procurement officers at German hospital systems, Brazilian meat processing engineers, and specialty enzyme distributors. Bottom-up volume estimates from Tamil Nadu and Karnataka production clusters triangulate against top-down demand aggregation from end-use industries.
Segmentation dimensions modeled span purification grade, application channel, delivery form, and geographic regulatory cluster. CAGRs derive from trend extrapolation across the projection horizon, calibrated against historical enzyme price elasticity and substitution dynamics. Forecast inputs include latex yield volatility patterns, REACH authorization timelines, and hospital protocol adoption curves for enzymatic debridement.
The analysis sits within stated boundaries; outcomes outside sustained CDSCO regulatory stability or ECHA substance authorization progression would require recalibration. Forecasts reflect assumptions on bromelain substitution elasticity, monsoon severity patterns, and pharmaceutical-grade certification completion rates. Recalibration cycles align with material shifts in regulatory authorization deadlines and hospital procurement protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Prebiotics Market
Food Biotechnology
Hemoglobin Feed Market
Food Biotechnology
Apigenin Market
Food Biotechnology
Genistein Market
Food Biotechnology
Global Genetically Modified (GMO) Food Market
Food Biotechnology
Colostrum Market
Food Biotechnology
South America Feed Prebiotics Market
Food Biotechnology
Asia Pacific Eubiotics Market
Food Biotechnology
Beta-Propeller Phytases Market
Food Biotechnology
Chlorella Market
Food Biotechnology
Carbohydrate Enzyme Preparation Market
Food Biotechnology
Research-Grade Proteins Market
Food Biotechnology
Pullulanase Market
Food Biotechnology
Cultured Meat Market
Food Biotechnology
Non-Animal Alternative Testing Market
Food Biotechnology
Salmon Polynucleotide (PN) Market