
 Solar Oven Market | 2026-2036
Solar Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Oven Market Insights
High-efficiency vacuum tube integration is rotating the product tier upward across the Solar Oven Market. GoSun Inc. leverages proprietary evacuated tube technology to capture premium positioning in portable segments. Sunflair Solar Ovens anchors its competitive stance through lightweight fabric-panel designs optimized for humanitarian deployment. All American Sun Oven dominates the North American backyard cooking niche with thick-walled box construction and extended temperature retention.
A solar oven is a device that harnesses concentrated solar radiation through reflective surfaces or transparent enclosures to generate cooking temperatures, typically achieving operational ranges between 120°C and 290°C depending on design geometry and insulation quality. Parabolic ovens deliver the highest thermal concentration for rapid boiling and frying applications, while box ovens with glass lids provide slower, more uniform heat distribution suited to baking and extended simmering. The application dimension shows emergency cooking and outdoor recreation commanding widening procurement channels, whereas everyday cooking remains concentrated in off-grid rural households across sun-belt geographies. Material selection increasingly favors aluminum reflectors for cost-sensitive panel ovens and borosilicate glass tubes for premium portable units where thermal shock resistance determines product longevity.
The EPA oversees emissions-linked manufacturing standards for consumer products entering the United States, while the EU Ecodesign for Sustainable Products Regulation imposes material traceability and recyclability thresholds on solar ovens sold in European markets. BIS certification requirements in India govern thermal performance claims and structural safety for domestically manufactured units, creating a fragmented compliance landscape that favors regionally established producers. Stakeholders must track how evolving extended producer responsibility frameworks in multiple jurisdictions reshape cost structures and supplier qualification criteria.
Market Dynamics
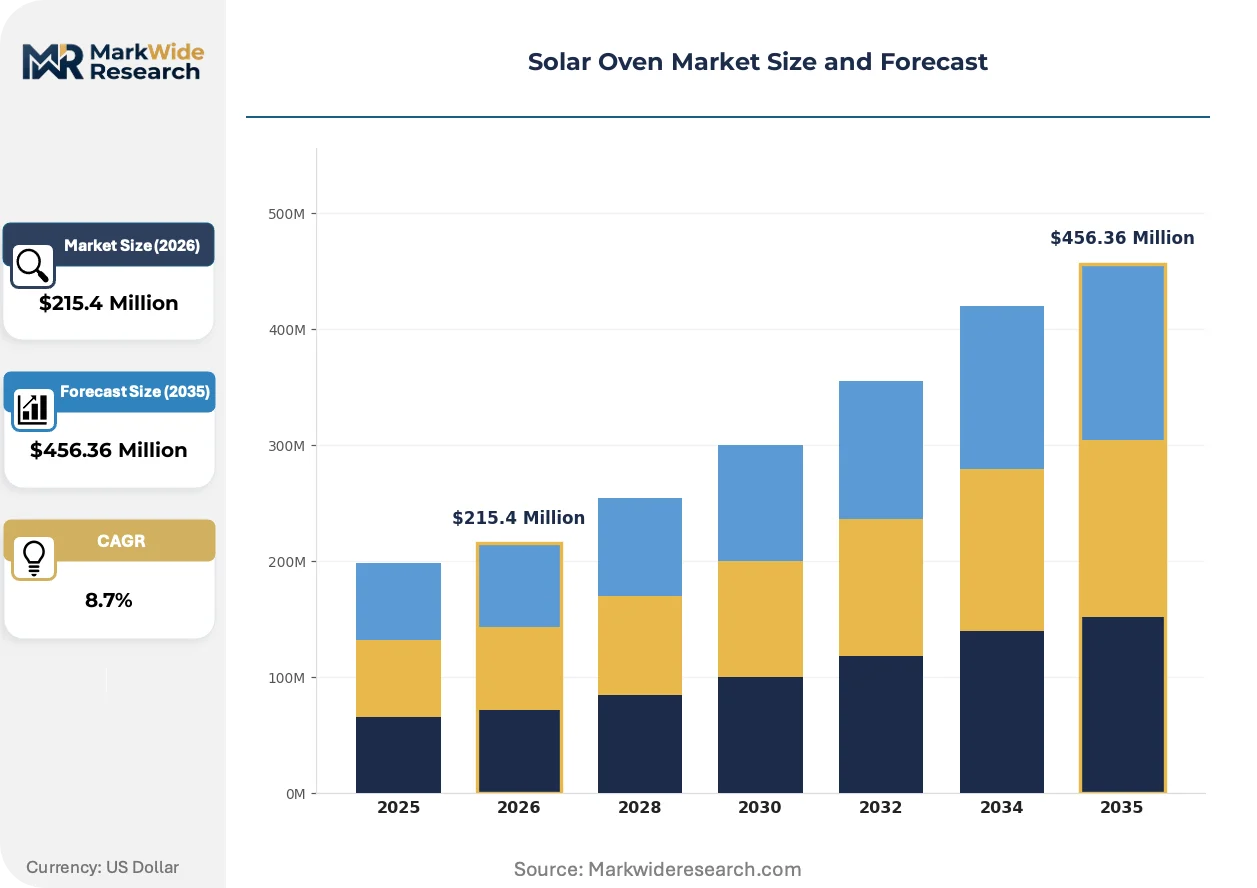
Vacuum tube integration is fragmenting the Solar Oven Market into performance tiers, as evacuated glass technology enables premium portable units while aluminum-panel designs retain cost-sensitive segments. This bifurcation reshapes procurement patterns across humanitarian, recreational, and rural household channels.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Material traceability mandates accelerate supplier qualification for European import channels, favoring producers with documented supply chains.
- Off-grid rural electrification gaps:Households across sun-belt geographies adopt box-style solar ovens as primary cooking infrastructure where grid extension remains uneconomical.
- Borosilicate glass thermal shock resistance:Premium portable segments demand tubes rated for rapid temperature cycling, extending product lifespans in field conditions.
Market Restraints
- Aluminum reflector price volatility:Input cost swings compress margins on panel-style ovens targeted at humanitarian bulk procurement.
- East African supply concentration:Displacement camp demand clusters create single-channel dependency for portable cooker manufacturers.
- Extended producer responsibility frameworks:Multi-jurisdictional recycling mandates inflate compliance overhead for cross-border sellers.
Strategic Opportunities
- Rural India penetration gaps:Box-oven adoption in unelectrified districts remains below saturation thresholds despite favorable insolation profiles.
- Emergency response stockpiling:Humanitarian agencies expand pre-positioned solar cooker inventories for climate-disaster preparedness.
- Fabric-panel weight reduction:Lightweight designs open backpack-portable segments for trekking and remote scientific fieldwork.
Industry Challenges
- BIS thermal performance certification timelines:Indian safety testing bottlenecks delay product launches for domestic manufacturers.
- Reflective surface coating durability:Degradation rates in high-UV environments complicate warranty positioning for aluminum-based units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Oven Market |
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $456.36 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Box Oven, Parabolic Oven, Panel Oven, Hybrid Oven Application: Camping, Emergency Cooking, Outdoor Cooking, Everyday Cooking Material: Glass, Aluminum, Plastic, Steel End User: Households, NGOs, Restaurants, Educational Institutions |
| Companies Covered | GoSun Inc., Sunflair Solar Ovens, All American Sun Oven, Solar Cookers International, SolSource, Global Sun Oven, SunFire Solutions, Haines Solar Cooker LLC, Sunrise Global Solar Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Oven Market Trends and Innovations
Product architecture is diverging along thermal performance lines. Evacuated tube systems capture premium positioning while simplified panel designs serve volume humanitarian contracts. Material science advances and procurement model evolution complete the transformation.
Evacuated borosilicate tube technology is fragmenting competitive positioning across portable solar oven segments. These tubes concentrate solar radiation through vacuum insulation, achieving operational temperatures exceeding 250°C in compact form factors. Humanitarian agencies and outdoor recreation buyers are adopting premium tube-based units for rapid boiling applications. This thermal performance tier is fragmenting the market into distinct price bands that resist direct comparison with aluminum-panel alternatives.
REACH substance restrictions and EU Ecodesign material traceability requirements are tightening compliance thresholds for European market entry. Manufacturers must document recyclability percentages and restricted substance content across supply chains. Panel-style ovens with aluminum reflectors face heightened scrutiny due to coating chemistry disclosure demands. European importers are consolidating supplier bases to reduce audit burden, favoring established producers with pre-qualified documentation systems.
Humanitarian procurement is consolidating around pre-approved vendor lists with multi-year framework agreements. Bulk purchasing by displacement camp operators displaces fragmented spot-market transactions. This channel concentration compresses margins for smaller manufacturers while rewarding scale-capable producers with certified production lines. East African logistics hubs are becoming the primary demand nodes for this procurement model.
Solar Oven Market Segmentation
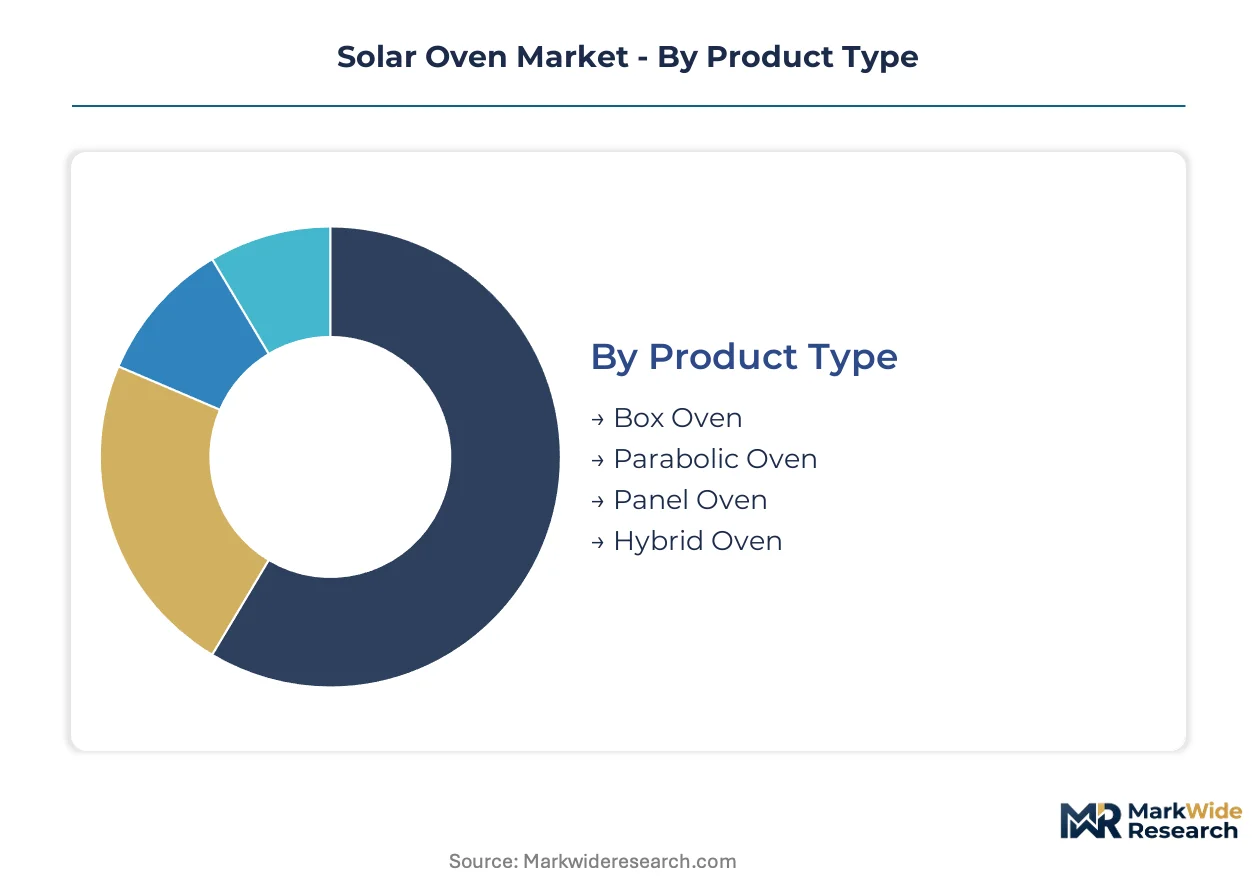
Solar oven procurement channels diverge sharply by thermal performance requirements and deployment context. Regulatory compliance thresholds fragment supplier qualification across humanitarian, recreational, and rural household segments.
Product Type:
EU Ecodesign material traceability mandates favor designs with documented supply chains and recyclable component profiles.
- Box Oven:Thick-walled insulated chambers with glass lids deliver 120-150°C operational ranges suited to baking and slow simmering. Rural India dominates procurement for unelectrified household cooking, where BIS thermal performance certification governs domestic sales.
- Parabolic Oven:Concentrated reflector geometry achieves 250-290°C peak temperatures for rapid boiling and frying tasks. East African displacement camps drive humanitarian procurement of collapsible parabolic units for high-throughput meal preparation.
- Panel Oven:Lightweight foldable reflectors surround a central cooking vessel, optimizing for backpack portability and emergency kit integration. Aluminum coating durability in high-UV environments constrains warranty positioning.
- Hybrid Oven:Combines photovoltaic elements with thermal collection for extended evening operation or battery-assisted temperature maintenance. Premium pricing limits deployment to scientific fieldwork and remote research stations.
Box ovens handle the majority of throughput; parabolic ovens are expanding most quickly on share.
Application:
Cost tier stratification separates premium recreational buyers from bulk humanitarian procurement and price-sensitive rural adopters.
- Camping:Portable tube-based units with evacuated borosilicate glass dominate premium outdoor recreation, where rapid boiling capability justifies weight penalties. GoSun's proprietary technology anchors this segment.
- Emergency Cooking:Fabric-panel lightweight designs serve stockpiling mandates by disaster preparedness agencies. Pre-positioned inventory frameworks consolidate procurement around certified vendor lists.
- Outdoor Cooking:Backyard installations in sun-belt geographies favor box-style construction with extended temperature retention for weekend meal preparation.
- Everyday Cooking:Primary cooking infrastructure for off-grid households concentrates in rural India and East African regions with favorable insolation profiles and limited grid extension economics.
Everyday cooking generates the largest installed base; emergency cooking is climbing the fastest.
Material:
Volume concentration in humanitarian channels favors cost-optimized inputs, while premium segments demand thermal shock resistance.
- Glass:Borosilicate tubes rated for rapid temperature cycling extend product lifespans in premium portable segments. REACH substance restrictions govern coating chemistry disclosure for European market entry.
- Aluminum:Reflective panel construction dominates cost-sensitive bulk procurement. Input price volatility compresses margins on humanitarian contracts.
- Plastic:Structural frames and insulated housings reduce unit weight for fabric-panel designs. UV degradation rates complicate warranty terms in equatorial deployment.
- Steel:Reinforced chassis and cooking vessel supports provide durability for institutional-scale parabolic installations. Higher material costs restrict penetration to commercial and educational end uses.
Aluminum commands the greatest tonnage throughput; glass is gaining share fastest on value.
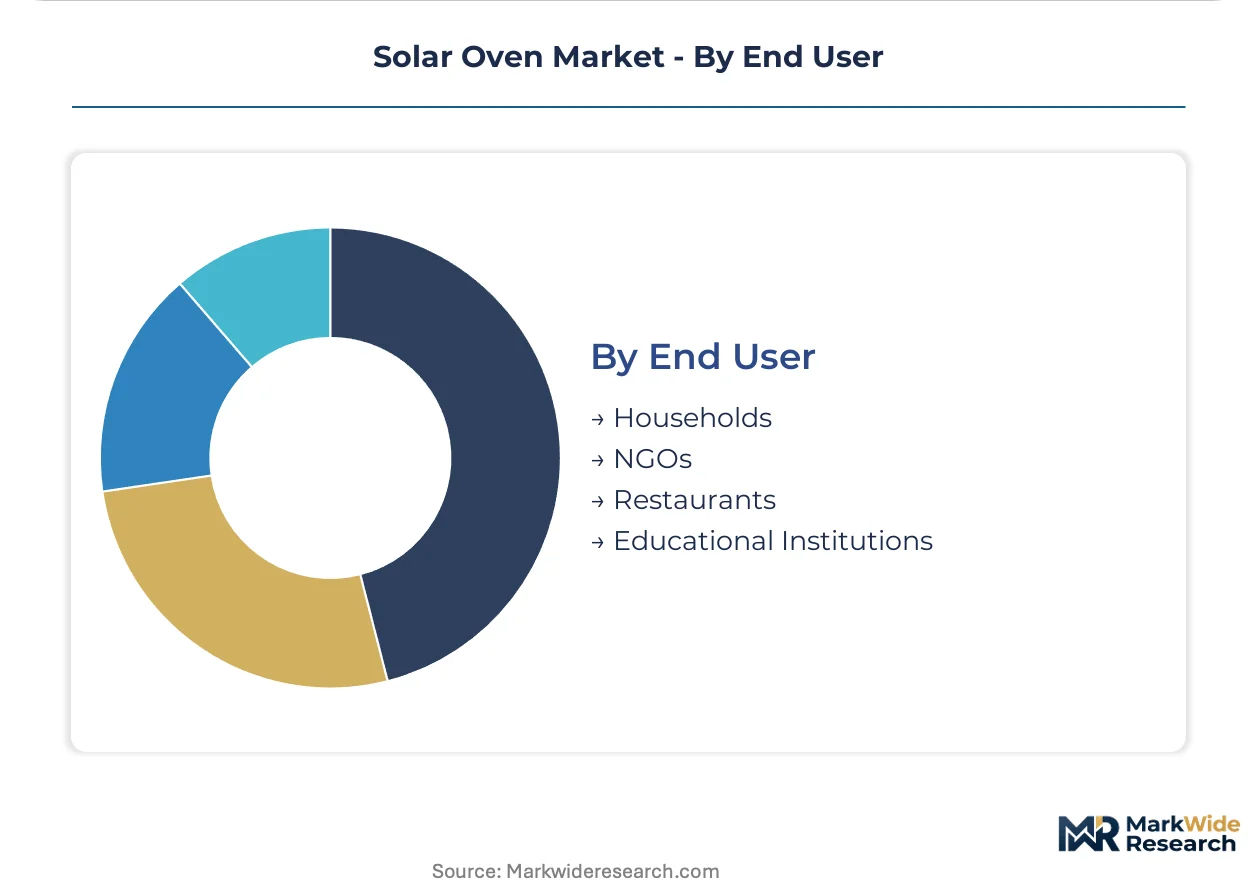
End User:
Customer type determines procurement modality, from individual retail purchase to multi-year framework agreements.
- Households:Unelectrified rural adopters in sun-belt geographies drive box-oven volume through retail and microfinance distribution channels.
- NGOs:Humanitarian agencies consolidate procurement through pre-approved vendor lists with East African logistics hub concentration.
- Restaurants:Commercial kitchen integration remains limited to demonstration projects and eco-tourism facilities with solar infrastructure investment capacity.
- Educational Institutions:Science curriculum deployment and sustainability demonstration programs generate institutional demand for classroom-scale units.
Households absorb the majority of unit volume; NGOs represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Humanitarian buyers in East Africa prioritize unit cost above thermal performance, while recreational purchasers in Germany and the United States absorb premium pricing for vacuum-tube portability.
United States
Backyard cooking applications drive steady demand for thick-walled box ovens with extended temperature retention. The EPA oversees emissions-linked manufacturing standards for consumer products entering domestic distribution channels. Arizona and New Mexico host concentrated clusters of off-grid homesteading communities where solar ovens serve as primary cooking infrastructure during grid instability events.
India
Unelectrified rural households across Rajasthan and Gujarat represent the largest installed base of box-style solar ovens worldwide. BIS certification requirements govern thermal performance claims and structural safety for domestically manufactured units, creating qualification bottlenecks for new entrants. Tamil Nadu's manufacturing corridor hosts established producers with pre-qualified documentation systems serving both domestic and export channels.
Germany
Outdoor recreation and emergency preparedness segments absorb premium portable units despite limited domestic insolation. REACH substance restrictions and EU Ecodesign material traceability mandates tighten compliance thresholds for solar ovens sold in European markets. Bavaria's sustainability-focused consumer base drives demand for documented supply chain transparency and recyclable component profiles.
Kenya
Displacement camp operators in Dadaab and Kakuma drive bulk procurement of collapsible parabolic units for high-throughput meal preparation. National energy access programs promote solar cooking as a clean alternative to charcoal and fuelwood in deforestation-stressed regions. Nairobi serves as the primary logistics hub for East African humanitarian procurement, consolidating demand from agencies operating across Somalia, South Sudan, and Ethiopia.
Australia
Scientific fieldwork and remote research stations generate specialized demand for hybrid ovens combining photovoltaic elements with thermal collection. The country's national standards body oversees product safety certification for solar thermal devices entering commercial distribution. Queensland and Western Australia's mining camps and indigenous communities represent emerging deployment contexts where grid extension remains economically unviable.
Solar Oven Market Competitive Landscape
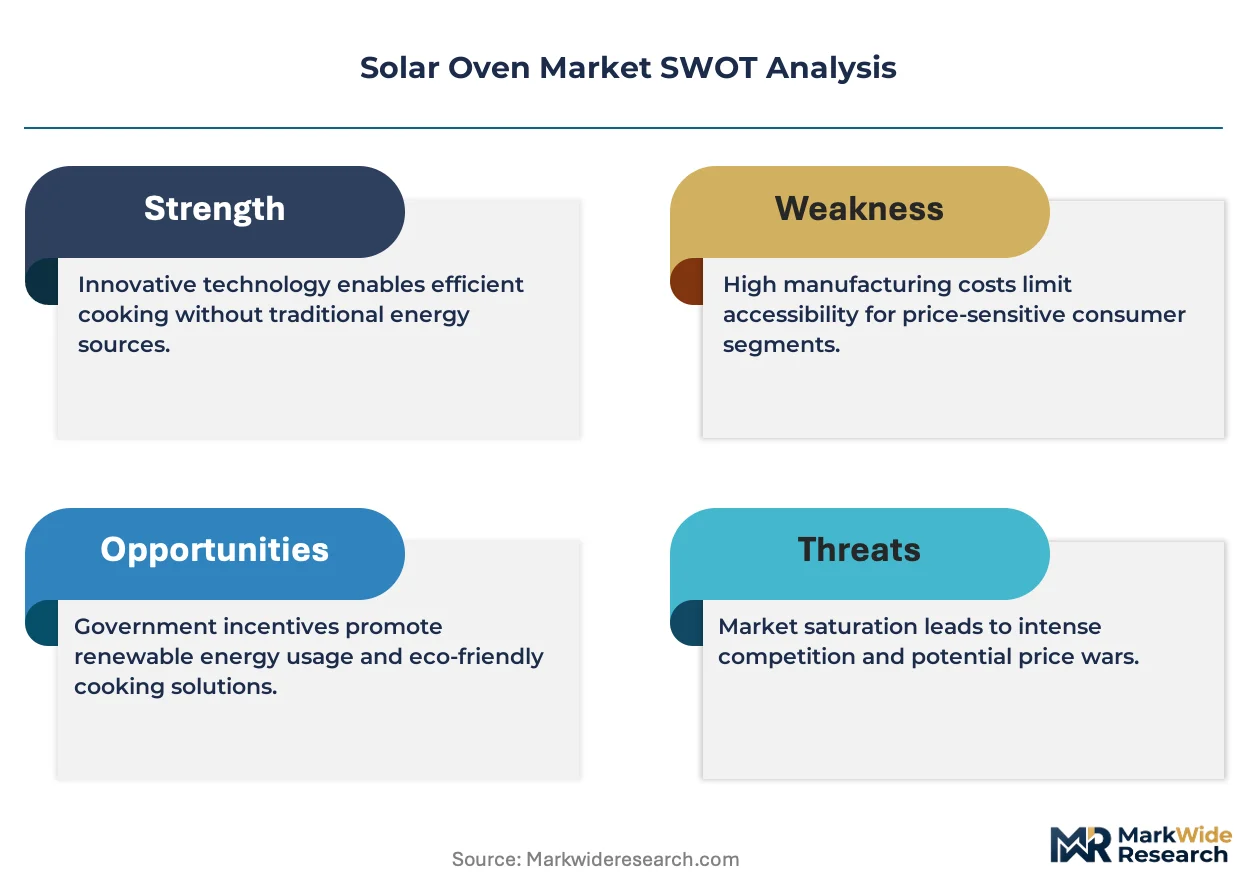
Technology leadership and cost leadership are held by different player archetypes across the Solar Oven Market. Vacuum-tube specialists command premium positioning through proprietary evacuated glass systems, while aluminum-panel fabricators compete on unit economics for humanitarian bulk contracts. The competitive terrain separates into three strategic archetypes: thermal-performance specialists, cost-optimized volume producers, and dual-use recreational-emergency suppliers. Dominant competitive moves include geographic expansion into East African logistics hubs and portfolio diversification across box, panel, and parabolic form factors.
Within the evacuated-tube specialist tier, GoSun Inc. exemplifies technology-forward positioning through proprietary thermal concentration systems. Among fabric-optimized portable producers, Sunflair Solar Ovens occupies a position aligned with humanitarian deployment requirements. At the thick-walled box construction end, All American Sun Oven anchors the North American backyard cooking segment. These three archetypes—tube-based premium, fabric-panel lightweight, and insulated-box retention—structure competitive rivalry across distinct price-performance bands.
| Leading Market Players |
|---|
| GoSun Inc. |
| Sunflair Solar Ovens |
| All American Sun Oven |
| Solar Cookers International |
| SolSource |
| Global Sun Oven |
| SunFire Solutions |
| Haines Solar Cooker LLC |
| Sunrise Global Solar Energy |
| Others |
Pricing and Supply Chain Analysis
Ninety-day component lead times for evacuated borosilicate tubes compress margin buffers for premium portable manufacturers while amplifying pricing power for pre-qualified Indian and Chinese glass suppliers serving European and East African procurement channels.
Pricing Analysis
After-market replacement tube sales and extended warranty contracts drive lifetime value capture for evacuated-glass specialists. Three-tier pricing structure across premium, standard, and economy levels separates vacuum-tube units from aluminum-panel humanitarian tenders and fabric-panel emergency kits. Price differentiation hinges on BIS thermal certification grade and REACH-compliant coating chemistry disclosure. Cost compression in panel-style segments is intensifying because aluminum reflector input volatility feeds through to fixed-price humanitarian contracts. NGOs and displacement camp operators exhibit highest price sensitivity; recreational buyers in Germany and Australia absorb premium positioning.
Supply Chain Analysis
Strategic stockpiling of borosilicate glass tubes dominates inventory strategy for premium portable producers, while just-in-time aluminum sheet procurement persists for cost-optimized panel fabricators. Manufacturing concentrates in India, China, and Germany. Supply chains draw from Chilean boron deposits, Chinese aluminum smelters, and German coating chemistry specialists. Single-source vulnerability in evacuated tube glassmaking constrains capacity expansion. Distribution runs through Nairobi logistics hubs for East African humanitarian procurement and Tamil Nadu export corridors for European REACH-compliant shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around pre-approved vendor lists with multi-year framework agreements, fragmenting spot-market access for smaller manufacturers.
For Market Incumbents: Fortify supply chain control through backward integration into borosilicate tube glassmaking or captive aluminum rolling capacity. Deepen certification investment for EU Ecodesign material traceability to defend against emerging Asian entrants with pre-qualified documentation systems. Channel control through Nairobi and Dadaab logistics hub partnerships provides defensive moats. For New Entrants and Emerging Players: Anchor in rural India's unelectrified districts below BIS certification saturation thresholds. Backpack-portable fabric-panel scientific fieldwork segments offer lowest competitive density. Go-to-market through microfinance-linked retail distribution bypasses consolidated NGO procurement channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial glass parents with dormant solar thermal assets. Five-to-ten year viability hinges on regulatory tailwinds for clean cooking infrastructure. Watch for East African displacement camp procurement volume inflection as climate disaster frequency signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Glass | Captive tube supply secures margin capture for GoSun-tier portable specialists against input volatility. |
| EU Ecodesign Pre-Qualification Investment | Documented REACH coating chemistry opens German and Bavarian sustainability-premium consumer segments. |
| Nairobi Logistics Hub Partnership | East African humanitarian consolidation rewards scale-capable producers with framework agreement access. |
| Fabric-Panel Weight Reduction R&D | Backpack-portable scientific fieldwork positioning captures premium pricing in Australian mining and research stations. |
| Hybrid Oven Photovoltaic Integration | Battery-assisted thermal maintenance extends addressable hours for remote Queensland indigenous community deployment. |
Research Methodology
The analysis maps evacuated-tube portable, box-style rural household, parabolic humanitarian, and hybrid scientific segments, each validated through procurement officers at displacement camp operators, BIS certification auditors, EU Ecodesign compliance consultants, and Tamil Nadu manufacturing executives. Primary interview intelligence triangulates against secondary sources including Indian customs export records, REACH substance restriction databases, UNHCR procurement frameworks, and EPA emissions standard filings. Bottom-up unit shipment estimates reconcile with top-down addressable population calculations across sun-belt geographies.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include thermal performance tier, material composition, application context, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated to humanitarian procurement cycle visibility, rural electrification gap persistence, and recreational outdoor spending elasticity. Industry-specific forecast inputs incorporate aluminum LME price trajectory assumptions and borosilicate glass capacity expansion announcements.
Decision-makers should treat outputs as directional under sustained EU Ecodesign enforcement and stable East African displacement funding; material deviation would warrant model refresh. Specific risk factors include BIS certification timeline delays, aluminum tariff regime shifts, and humanitarian budget reallocation. Revision becomes warranted when vacuum-tube cost curves cross panel-style parity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
In-Pipe Hydroelectric System Market
Renewable Energy
Renewable Energy MRO Market
Renewable Energy
Solar Ceiling Fans Market
Renewable Energy
Renewable Energy Sources Market
Renewable Energy
Algeria Renewable Energy Market
Renewable Energy
Europe Single-Axis Solar Tracker Market
Renewable Energy
Ocean Power Market
Renewable Energy
China Wind Energy Market
Renewable Energy
South Europe Renewable Energy Market
Renewable Energy
Saudi Arabia Renewable Energy Market
Renewable Energy
Canada Renewable Energy Market
Renewable Energy
Solar Balloon Market
Renewable Energy
Portugal Renewable Energy Market
Renewable Energy
Iran Renewable Energy Market
Renewable Energy
Composite Materials in Renewable Energy Market
Renewable Energy
South Africa Solar Energy Market