
 Drones in Renewable Energy Market | 2026-2036
Drones in Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Drones in Renewable Energy Market Insights
Utility-scale solar operators are gaining share against traditional wind farm buyers as procurement is bifurcating between established onshore wind incumbents and rapidly expanding photovoltaic developers. DJI leverages its manufacturing scale to dominate consumer-adjacent platforms that utilities now adapt for commercial inspection. Terra Drone Corporation anchors its position through specialized offshore wind services across Asian maritime zones. Flyability differentiates with collision-tolerant designs that navigate confined turbine nacelle interiors where conventional drones fail.
Drones in renewable energy are unmanned aerial systems equipped with sensors such as thermal imagers, LiDAR payloads, and multispectral cameras, typically operating at altitudes below 400 feet with flight endurance ranging from 20 minutes to several hours depending on powertrain configuration; their primary purpose is to execute automated data collection across geographically dispersed generation assets that human crews cannot efficiently or safely access. Multirotor platforms occupy the largest volume share due to versatility in close-proximity solar panel inspection, while fixed-wing systems lead in linear surveying applications such as transmission corridor mapping where endurance outweighs maneuverability. AI-driven analytics represents the fastest-expanding technology segment as machine learning pipelines convert raw imagery into predictive maintenance schedules without human interpretation bottlenecks.
The FAA's Part 107 framework governs commercial drone operations in the United States, while the EU AI Act imposes conformity requirements on automated decision systems that classify turbine defects without human-in-the-loop verification. EASA's specific category regulations for beyond-visual-line-of-sight flights directly shape product certification pathways for vendors seeking European wind farm contracts. Stakeholders must monitor evolving battery energy density standards and jurisdiction-specific airspace integration timelines to align R&D roadmaps with operational deployment windows.
Market Dynamics
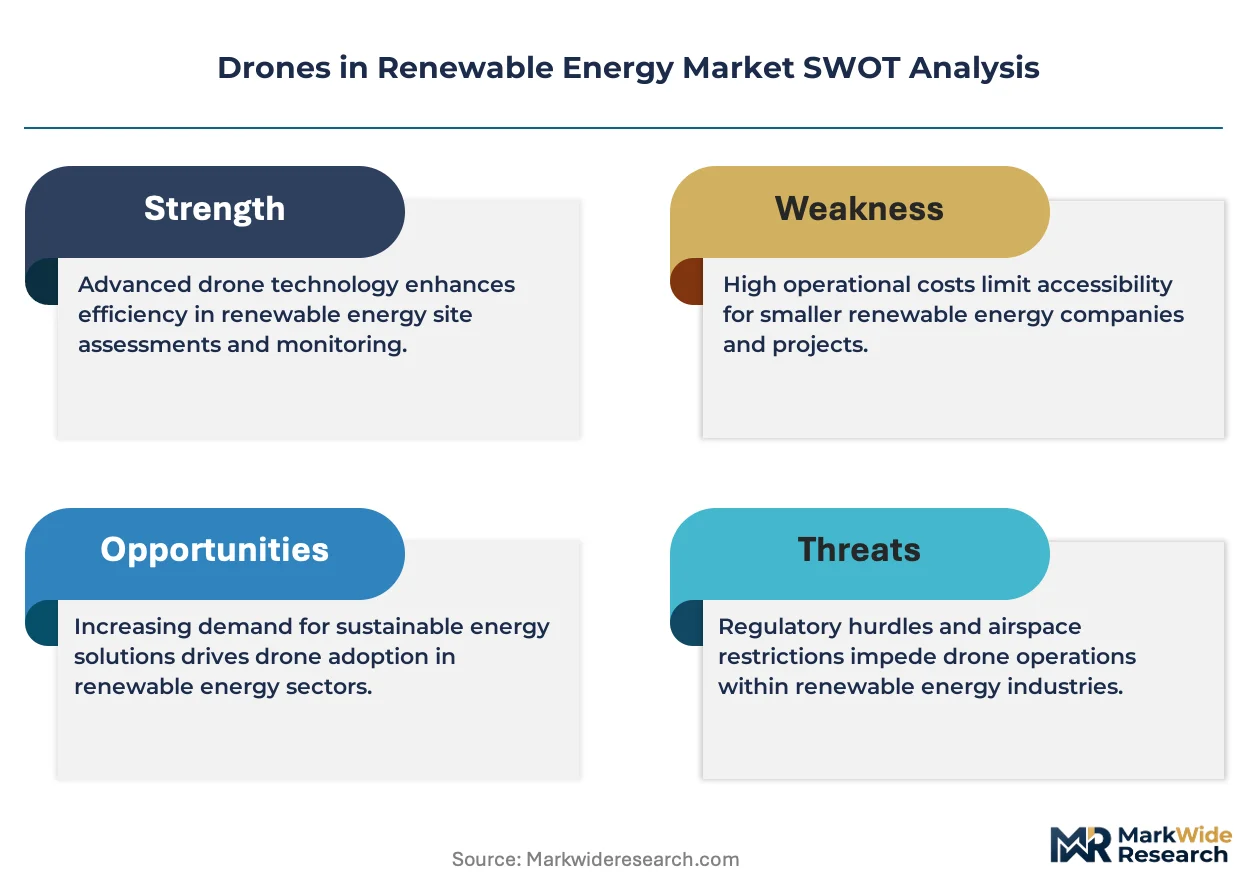
Utility-scale solar operators are displacing wind incumbents as the primary demand source, forcing vendors to reconfigure payload portfolios from blade-crack detection toward cell-level thermal anomaly identification.
Growth Catalysts
- F-Gas Regulation:Europe's refrigerant phase-down mandates non-contact thermal monitoring, eliminating ground-based sensor networks that depend on hydrofluorocarbon coolants.
- Offshore wind expansion:North Sea installations require persistent aerial surveillance that crewed vessels cannot economically provide, concentrating procurement in maritime zones.
- AI-driven analytics:Machine learning pipelines convert raw imagery into predictive maintenance schedules without human interpretation bottlenecks.
Market Restraints
- Lithium-ion supply concentration:Battery cell production clusters in East Asian manufacturing hubs, exposing flight-time specifications to raw material logistics disruptions.
- Beyond-visual-line-of-sight certification:EASA's specific category requirements impose multi-year approval timelines that delay European contract execution.
- Ground-based thermography:Handheld infrared cameras retain cost advantages for small-scale solar arrays below 50 megawatts.
Strategic Opportunities
- Floating solar installations:Reservoir-mounted photovoltaic arrays in Japan and South Korea lack established inspection protocols, creating first-mover positioning for amphibious-capable platforms.
- EU AI Act conformity:Automated defect classification systems that incorporate human-in-the-loop verification gain preferential procurement status from European utilities.
- Transmission corridor digitization:Linear surveying contracts bundle drone-based LiDAR with vegetation management services, expanding addressable spend per engagement.
Industry Challenges
- Pilot certification scarcity:Commercial operators holding Part 107 remote pilot certificates with night-operation waivers command wage premiums that compress inspection margins.
- Legacy SCADA integration:Proprietary data formats from 1990s-era wind farm control systems resist API connectivity with modern aerial analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drones in Renewable Energy Market |
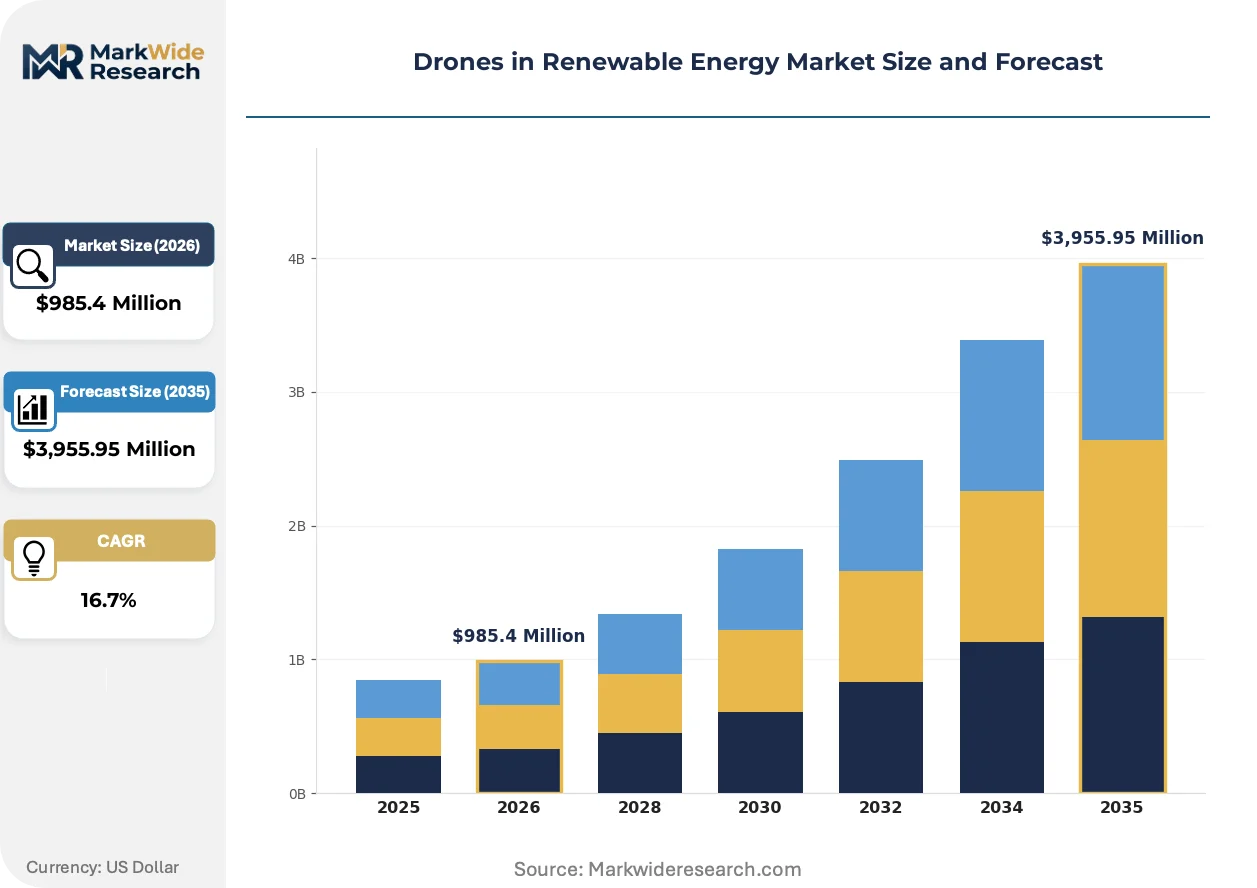
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $3,955.95 Million |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multirotor, Fixed-wing, Hybrid, Specialty Application: Inspection, Surveying, Monitoring, Maintenance End User: Utilities, Wind Farms, Solar Providers, Researchers Technology: AI-driven, GPS-guided, Thermal Imaging, LiDAR |
| Companies Covered | DroneDeploy, Parrot, ABJ Drones, Raptor Maps, Skylark Drones, Drone Volt, Flyability, Terra Drone Corporation, DJI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drones in Renewable Energy Market Trends and Innovations
Autonomous flight systems are compressing operator labor intensity while multimodal sensor fusion creates new data product categories that transcend traditional inspection deliverables.
Collision-tolerant airframes are fragmenting the conventional multirotor market. Flyability's caged-propeller architecture navigates turbine nacelle interiors where GPS-denied environments disable standard quadcopters. Offshore wind maintenance contractors in the North Sea now specify enclosed-rotor designs for gearbox housing inspections.
EASA's specific category framework for beyond-visual-line-of-sight operations is reshaping product certification pathways. Manufacturers must demonstrate detect-and-avoid capabilities and command-link redundancy to access European wind farm contracts. German utilities now require BVLOS-ready platforms for North Sea blade surveillance tenders.
Subscription-based data services are displacing per-flight pricing among utility-scale solar operators. Asset managers prefer fixed annual fees covering unlimited inspection cycles with guaranteed turnaround times. This model concentrates most visibly in California and Texas markets where portfolio owners operate gigawatt-scale installations.
Drones in Renewable Energy Market Segmentation
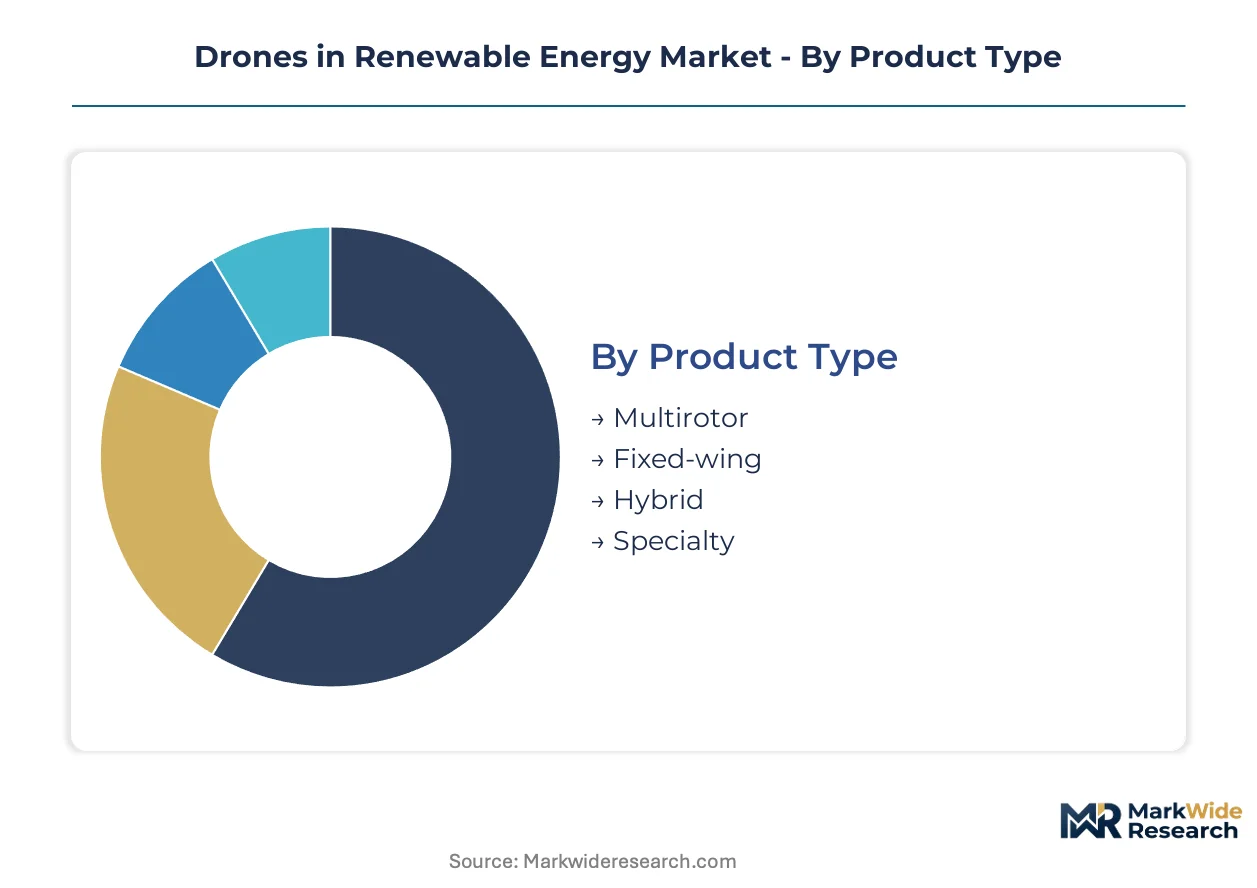
Segmentation in the drones for renewable energy market reflects divergent procurement priorities across asset types and operational environments. Platform selection, sensor configuration, and service models vary sharply between offshore wind contractors and utility-scale solar operators.
Product Type:
Geographic concentration differs markedly across platform architectures, with European offshore wind driving specialty designs while Asian manufacturing scales dominate multirotor supply.
- Multirotor:Vertical-takeoff platforms with four to eight rotors enable precise hovering for solar panel thermal scanning at close range. Demand clusters in Germany and California where utility-scale photovoltaic operators require frequent, localized inspection cycles without runway infrastructure.
- Fixed-wing:Aerodynamic airframes with extended endurance excel at linear corridor mapping across transmission networks and wind farm perimeters. Procurement concentrates in Texas and the North Sea where operators prioritize acreage coverage over maneuverability.
- Hybrid:Tilt-rotor designs combine vertical takeoff with efficient forward flight for offshore logistics.
- Specialty:Collision-tolerant caged systems penetrate turbine nacelle interiors where GPS signals fail.
Multirotor systems command the established base. The steepest expansion runs through specialty platforms purpose-built for confined-space wind turbine maintenance.
Application:
Cost tier separation distinguishes automated inspection subscriptions from capital-intensive surveying contracts, with pricing models diverging between recurring service fees and project-based deliverables.
- Inspection:Automated defect detection using thermal and visual sensors identifies cell-level hot spots in photovoltaic arrays and blade surface erosion in wind turbines. European utilities under F-Gas Regulation mandates drive replacement of ground-based thermography with aerial alternatives.
- Surveying:LiDAR and photogrammetric mapping generate three-dimensional terrain models for greenfield site selection and construction progress monitoring. Demand concentrates in emerging markets where developers lack historical geographic data.
- Monitoring:Persistent aerial surveillance tracks vegetation encroachment and equipment degradation across dispersed generation assets.
- Maintenance:Payload delivery and contact-based interventions extend beyond passive observation into active repair support.
Inspection services command the established base. Surveying applications are climbing the fastest as pre-construction site assessment accelerates.
End User:
Customer type determines procurement sophistication, with integrated utilities demanding enterprise-grade analytics while independent solar developers prioritize cost-efficient per-flight economics.
- Utilities:Vertically integrated power companies operate diversified generation portfolios requiring standardized inspection protocols across solar, wind, and transmission infrastructure. Procurement in Germany and Texas favors multi-year service agreements with guaranteed data turnaround.
- Wind Farms:Onshore and offshore turbine operators require specialized blade and nacelle access solutions. North Sea installations specify BVLOS-capable platforms for maritime operations beyond ground crew reach.
- Solar Providers:Independent power producers and asset managers focus on cell-level thermal anomaly detection at gigawatt-scale installations.
- Researchers:Academic and government institutions deploy drones for renewable resource assessment and technology validation.
Wind farm operators command the established base. Utility procurement departments are gaining share fastest as centralized fleet management replaces fragmented vendor relationships.
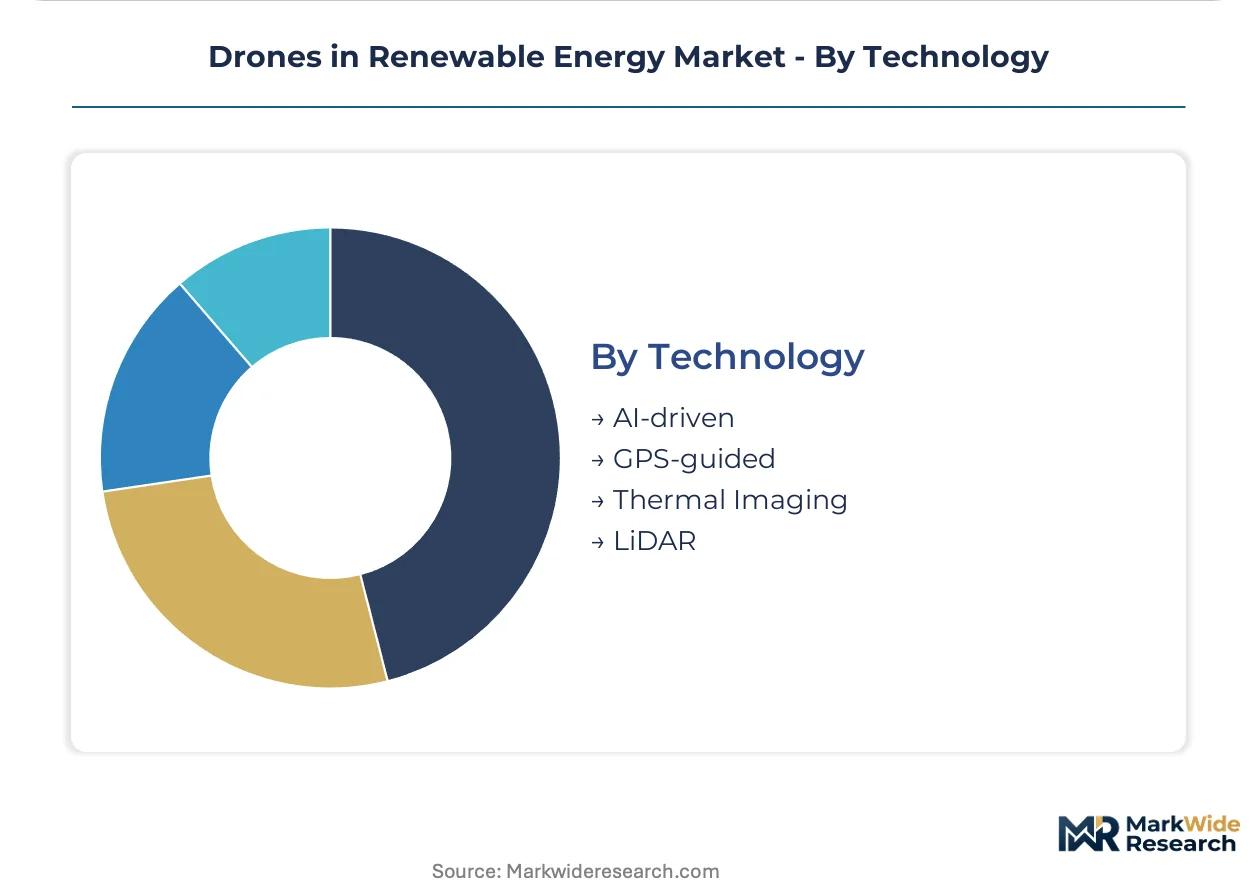
Technology:
Technology maturity separates field-proven navigation systems from emerging AI capabilities, with regulatory frameworks lagging autonomous decision-making deployment.
- AI-driven:Machine learning pipelines classify defects and generate predictive maintenance schedules without human interpretation. EU AI Act conformity requirements impose human-in-the-loop verification for European utility contracts.
- GPS-guided:Satellite navigation enables standard waypoint missions across open terrain with established regulatory acceptance.
- Thermal Imaging:Infrared sensors detect temperature anomalies indicating electrical faults or mechanical degradation.
- LiDAR:Laser ranging generates precise topographic and structural measurements for vegetation management and construction planning.
GPS-guided systems command the established base. AI-driven analytics are expanding most quickly as utilities automate defect classification workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German drone manufacturers export collision-tolerant inspection platforms to North Sea wind farm operators, while Chinese producers supply multirotor systems to utility-scale solar developers across Southeast Asia and the Middle East.
United States
Texas and California utility-scale solar portfolios drive procurement of subscription-based inspection services. FAA Part 107 frameworks govern commercial operations, with night-operation waivers commanding wage premiums for certified pilots. The Southwest corridor concentrates gigawatt-scale photovoltaic installations requiring persistent aerial monitoring.
Germany
North Sea offshore wind expansion mandates BVLOS-capable platforms for blade surveillance beyond crewed vessel range. EASA specific category regulations impose detect-and-avoid certification requirements for maritime tenders. Hamburg and Bremen harbor clusters anchor drone logistics operations serving North Sea turbine arrays.
China
Dual carbon goals accelerate utility-scale solar and offshore wind deployment across coastal provinces. MIIT standards govern industrial drone manufacturing, while GB certification requirements shape platform specifications for domestic energy operators. The Yangtze River Delta concentrates manufacturing of thermal imaging payloads for export markets.
Japan
Floating solar installations on reservoirs lack established inspection protocols, creating demand for amphibious-capable platforms. METI renewable energy targets drive procurement from domestic and foreign drone vendors. Kyushu and Chubu regions concentrate geothermal and photovoltaic assets requiring aerial monitoring.
United Kingdom
North Sea offshore wind lease rounds require persistent blade inspection services that crewed helicopters cannot economically provide. Maritime and Coastguard Agency regulations intersect with EASA frameworks for cross-border North Sea operations. Scottish waters host expanding floating wind demonstrators demanding specialized aerial access solutions.
Drones in Renewable Energy Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with manufacturing scale advantages alongside specialized inspection service providers with domain expertise in confined-space turbine access. The vendor base separates into three strategic archetypes: consumer-adjacent platform adapters, offshore wind specialists, and collision-tolerant design innovators. Dominant competitive moves include geographic expansion into floating solar markets and portfolio diversification from hardware sales toward subscription-based data services.
Within the collision-tolerant tier, Flyability exemplifies enclosed-rotor architectures that penetrate GPS-denied turbine interiors where standard multirotors fail. DJI represents manufacturing-scale platform adaptation from consumer markets into utility inspection workflows. Terra Drone Corporation anchors specialized offshore wind services across Asian maritime zones, occupying a position between equipment supply and integrated service delivery.
| Leading Market Players |
|---|
| DroneDeploy |
| Parrot |
| ABJ Drones |
| Raptor Maps |
| Skylark Drones |
| Drone Volt |
| Flyability |
| Terra Drone Corporation |
| DJI |
| Others |
Pricing and Supply Chain Analysis
Lithium-polymer battery packs displacing cylindrical lithium-ion cells in endurance-focused platforms simultaneously shift procurement geography toward Shenzhen and Dongguan manufacturing clusters while compressing per-unit platform costs for North American solar operators. This substitution dynamic redistributes value capture from Japanese cell suppliers toward Chinese pack integrators, altering vendor margin structures across the inspection services tier.
Pricing Analysis
Next-generation AI-enabled platforms command 40-60% premiums over GPS-guided baseline systems, while prior-generation thermal-only configurations face accelerated price erosion in European utility tenders. Subscription-based SaaS pricing now dominates utility-scale solar procurement in Texas and California, with differentiation anchored in BVLOS certification tier and guaranteed data turnaround SLAs. Cost compression in standard multirotor hardware intensifies as DJI manufacturing scale floods commercial channels. Independent solar developers exhibit highest price sensitivity, while integrated European utilities under F-Gas mandates accept premium positioning for compliant analytics bundles.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam lane inflate inbound logistics costs for European offshore wind contractors sourcing collision-tolerant platforms from Asian manufacturers. Component concentration centers on China for thermal imaging sensors, South Korea for advanced lithium cells, and Germany for precision navigation modules. Single-source vulnerability persists in gimbal stabilization subassemblies sourced exclusively from Shenzhen tier-one suppliers. Distribution runs through authorized dealer networks for hardware sales, while integrated service providers bypass channel intermediaries for direct utility contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits defensive-moat characteristics rooted in regulatory entrenchment: EASA BVLOS certification timelines and FAA Part 107 night-operation waivers create multi-year barriers that protect incumbent positioning against fast-follower replication.
For Market Incumbents: Fortify data moats by deepening API integration with legacy SCADA systems that resist newcomer connectivity attempts. Accelerate EU AI Act conformity investments to capture procurement preference from German and UK utilities evaluating automated defect classification vendors. Vertical integration into predictive analytics software layers captures recurring revenue streams that hardware-only competitors cannot match. For New Entrants and Emerging Players: EASA fast-track certification pathways for detect-and-avoid systems unlock white-space positioning in North Sea offshore wind tenders where incumbents lack maritime-specialized platforms. Floating solar installations in Japan and South Korea present the most penetrable segment, with amphibious-capable designs commanding first-mover premiums absent established protocols. Target asset-manager relationships directly through pilot subscription programs that demonstrate turnaround time superiority against per-flight incumbents. For Investors and Strategic Acquirers: The market sits at a consolidation-ready phase that favors vertically integrated service providers with captive data science capabilities over pure-play hardware manufacturers. Long-term viability hinges on recurring revenue attachment rates exceeding 60% of total contract value. Acquisition target archetype: inspection service firms holding multi-year utility agreements with embedded AI analytics pipelines. Monitor EASA specific-category approval velocity as inflection signal—accelerated timelines would erode certification moats and compress incumbent valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| BVLOS Certification Investment | EASA specific-category approval unlocks North Sea offshore wind contracts beyond crewed vessel range. |
| AI Analytics Platform Acquisition | Machine learning defect classification pipelines convert hardware vendors into recurring-revenue service providers. |
| Floating Solar Protocol Development | Amphibious platform specialization captures unmet demand from Japan's reservoir-mounted photovoltaic expansion. |
| SCADA Integration Partnership | API connectivity with 1990s-era wind farm control systems locks out competitors lacking legacy compatibility. |
| Subscription Pricing Migration | Fixed annual fees displace per-flight economics among California and Texas gigawatt-scale solar portfolios. |
Research Methodology
Operator-level perspectives from utility planning officers, offshore wind maintenance contractors, solar asset managers, and EASA certification specialists anchored the qualitative base for this study. Primary interviews with drone service providers and payload manufacturers were cross-validated against secondary sources including EASA regulatory filings, FAA Part 107 waiver databases, IEA renewable energy deployment statistics, and utility procurement tender documents. Bottom-up segment sizing triangulated against top-down market aggregation across platform type, application, and end-user categories.
Sensitivity analysis tested forecast robustness against variable assumptions for battery energy density improvement trajectories, EASA BVLOS approval timeline scenarios, and utility-scale solar deployment acceleration patterns across the projection horizon. Segmentation dimensions modeled include platform architecture, sensor payload configuration, service delivery model, and regional regulatory framework cluster. CAGRs were derived from logistic adoption curve fitting applied to technology penetration rates within each end-user segment, with explicit incorporation of F-Gas Regulation compliance deadlines and offshore wind lease round schedules as demand-pull inputs.
Underlying assumptions cover sustained lithium supply chain stability, EASA regulatory framework continuity, and utility procurement centralization trends, with deviation risk concentrated in battery raw material logistics disruptions and accelerated AI Act enforcement timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Europe IoT in Renewable Energy Market
Renewable Energy
Uzbekistan Renewable Energy Market
Renewable Energy
Iran Renewable Energy Market
Renewable Energy
Renewable Energy Inverters Market
Renewable Energy
Philippines Power Market
Renewable Energy
Global Green Energy Market
Renewable Energy
Global Renewable Energy Market
Renewable Energy
Mexico Renewable Energy Market
Renewable Energy
West Europe Renewable Energy Market
Renewable Energy
Sweden Renewable Energy Market
Renewable Energy
Solar Chair Market
Renewable Energy
Solar Oven Market
Renewable Energy
Solar Balloon Market
Renewable Energy
Renewable Naphtha Market
Renewable Energy
Renewable Energy Consulting Service Market
Renewable Energy
China Wind Energy Market