
 Oil and Gas Downhole Vibration Monitoring and Control System Market | 2026-2036
Oil and Gas Downhole Vibration Monitoring and Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Downhole Vibration Monitoring and Control System Market Analytics
The Permian Basin capacity build-out is narrowing the operational margin between high-frequency drilling and equipment fatigue failures. Weatherford International plc leverages integrated wired-to-wireless platform architectures to capture service contracts across North American shale basins. Schlumberger Limited anchors its position through proprietary downhole dynamics sensor networks deployed in Middle Eastern extended-reach wells. Baker Hughes Company differentiates via fiber-optic sensing systems engineered for geothermal-grade temperature tolerance.
Oil and Gas Downhole Vibration Monitoring and Control Systems comprise sensor arrays, signal processors, and actuation modules that measure torsional, axial, and lateral oscillations within the drillstring at frequencies up to 10 kHz, transmitting data to surface control units for real-time damping adjustment to prevent stick-slip and bit bounce. Their primary purpose is eliminating destructive resonant modes that destroy bottom-hole assemblies and reduce rate of penetration. Wired Systems still dominate capital expenditure allocation in offshore environments where telemetry reliability overrides installation cost concerns. Wireless Systems represent the fastest-expanding segment as lithium-powered micro-transmitters penetrate onshore pad drilling operations. Integrated Systems concentrate margin pools by bundling accelerometer hardware with predictive analytics software platforms that forecast bearing wear intervals.
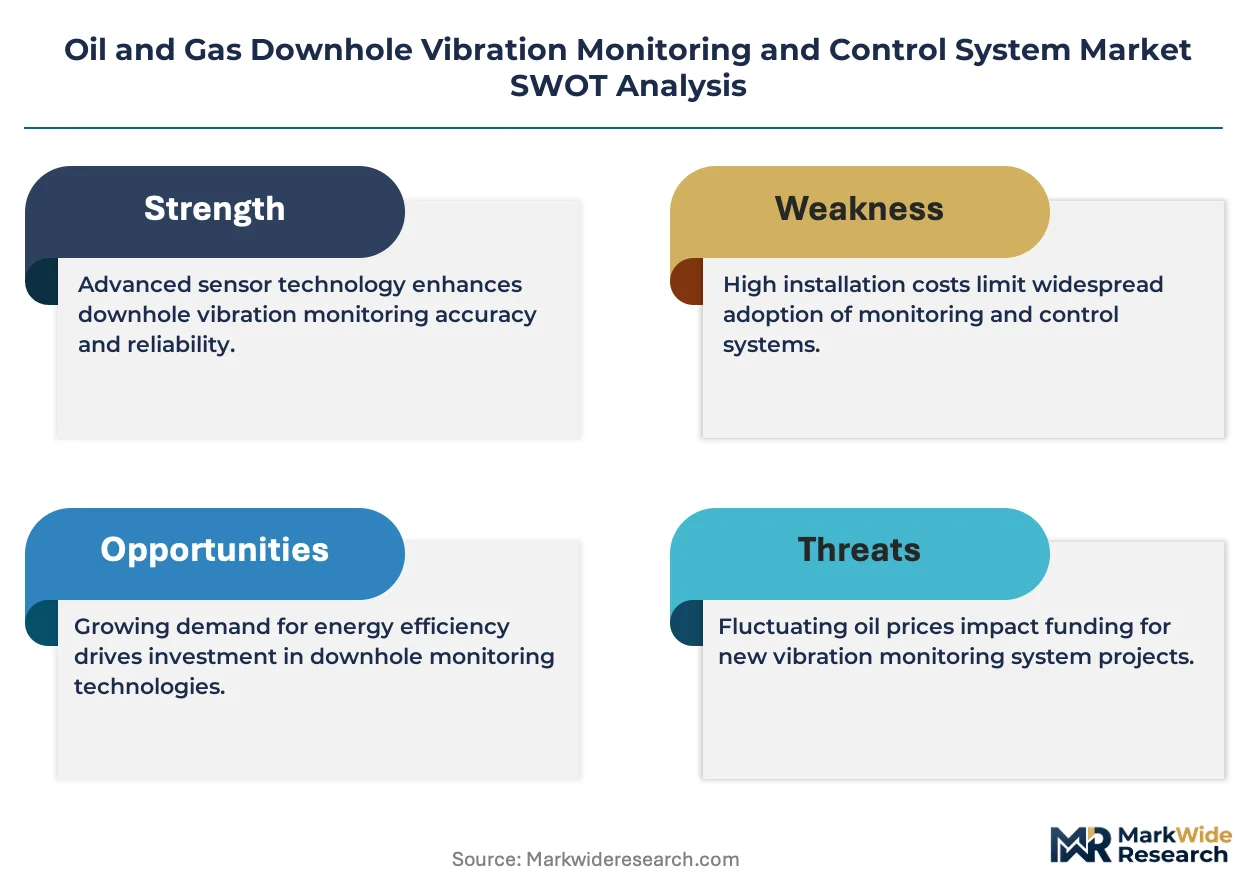
The US Bureau of Safety and Environmental Enforcement mandates real-time monitoring for high-pressure high-temperature wells in federal waters, forcing operators to upgrade legacy passive damping tools. API RP 7G and ISO 13628-7 establish minimum vibration measurement protocols that equipment must satisfy for North Sea and Gulf of Mexico market access. Stakeholders must decide whether to develop proprietary sensor fusion algorithms or license third-party machine-learning platforms as vibration data becomes the primary input for automated drilling optimization.
Market Dynamics
Deepwater operators are consolidating procurement around integrated vibration management platforms that bundle hardware with predictive analytics, compressing vendor margins for standalone sensor suppliers and favoring full-stack service providers.
Growth Catalysts
- US BSEE Mandates:Federal regulations for high-pressure high-temperature wells in the Gulf of Mexico require real-time downhole monitoring, forcing operators to upgrade legacy passive damping systems.
- Extended-Reach Drilling:Middle Eastern operators are deploying advanced vibration suppression to manage torque and drag in laterals exceeding 15,000 feet.
- Lithium-Powered Micro-Transmitters:Onshore pad drilling operations are adopting wireless telemetry to reduce rig-up time and eliminate cable maintenance.
Market Restraints
- High-Grade Accelerometer Supply:MEMS fabrication capacity for geothermal-grade sensors concentrates among a limited set of semiconductor foundries.
- Fiber-Optic Cable Fragility:Downhole fiber sensing systems face reliability constraints in high-shock directional drilling environments.
- API RP 7G Certification Timelines:Equipment qualification protocols for North Sea market access extend product development cycles by 18-24 months.
Strategic Opportunities
- Geothermal Energy Expansion:Temperature-tolerant vibration monitoring systems developed for oil and gas are transferring to geothermal drilling in Nevada and Iceland.
- Machine-Learning Convergence:Sensor fusion algorithms combined with edge computing are enabling automated stick-slip mitigation without surface operator intervention.
- Permian Basin Pad Density:Multi-well pad configurations in West Texas create demand for wireless mesh networks that share telemetry infrastructure across adjacent wells.
Industry Challenges
- Downhole Electronics Reliability:Engineering teams struggle to maintain signal integrity in mud pulse telemetry systems above 175°C bottom-hole temperatures.
- Legacy Rig Integration:Retrofitting 1990s-era drilling platforms with real-time damping actuators requires custom mechanical interface designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Downhole Vibration Monitoring and Control System Market |
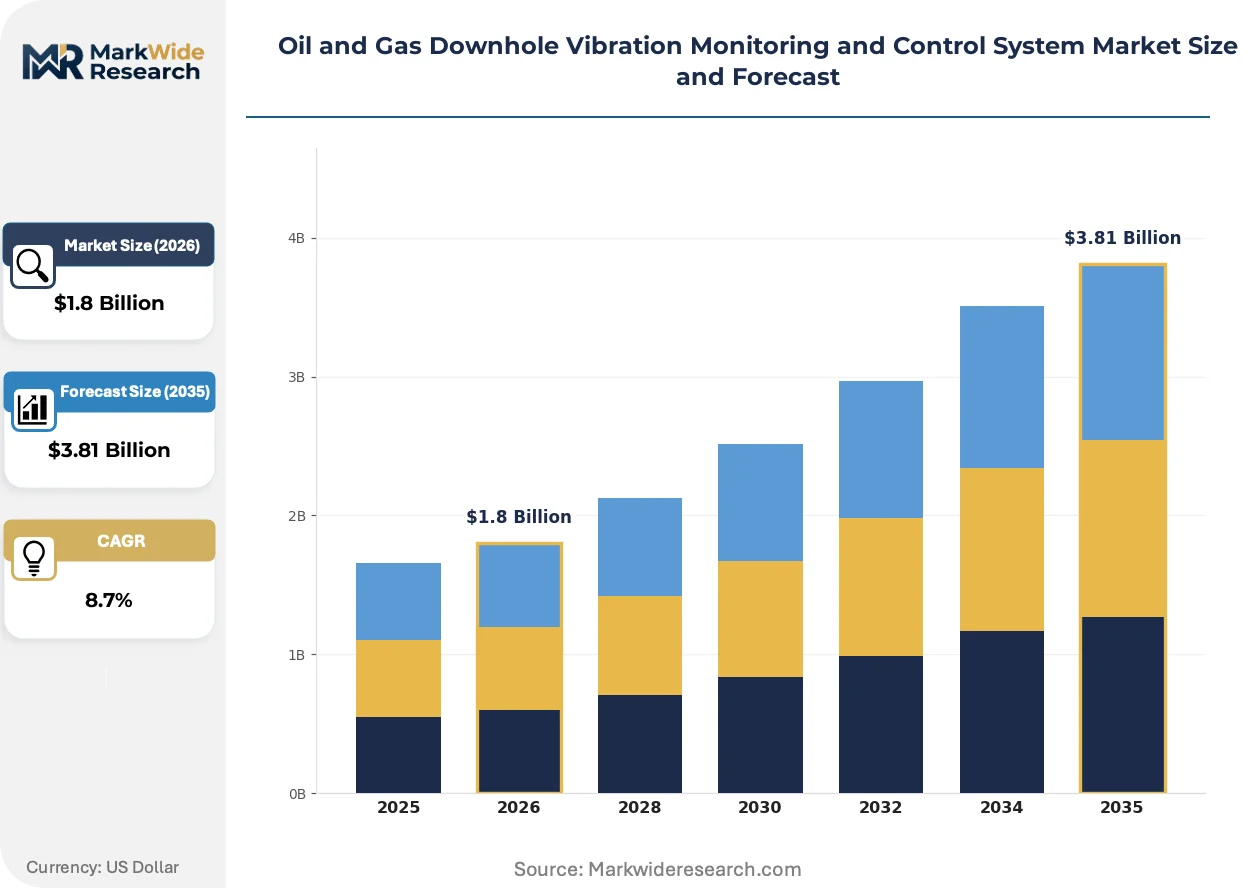
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Wireless Systems, Wired Systems, Integrated Systems, Software Platforms Deployment Model: Onshore, Offshore, Subsea, Hybrid End User: Exploration Companies, Production Companies, Service Providers, OEMs Technology: Accelerometers, Strain Gauges, Fiber Optic Sensors, MEMS Sensors |
| Companies Covered | Weatherford International plc, Emerson Electric, Schlumberger Limited, Nabors Industries Ltd, GE Oil and Gas, Baker Hughes Company, National Oilwell Varco, Honeywell International Inc, Halliburton Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Downhole Vibration Monitoring and Control System Market Evolving Landscape
Digital twin architectures are displacing rule-based vibration control across offshore fleets, compressing the feedback loop between downhole measurement and surface response from minutes to milliseconds.
MEMS-based triaxial accelerometers are digitizing vibration signature capture in the drillstring, replacing analog strain gauge arrays. Shale operators in the Permian and Bakken formations are adopting these solid-state packages for their shock resistance and reduced calibration drift. The shift is digitizing how drilling contractors model bit wear, enabling predictive replacement schedules that reduce non-productive time.
EU F-Gas Regulation restrictions on sulfur hexafluoride are pressuring manufacturers to redesign high-voltage isolation components in downhole power supplies. Equipment suppliers serving the North Sea must certify alternative gas-insulated switchgear by 2026. The regulatory pressure is accelerating fluoronitrile adoption in subsea control modules, with Norwegian operators piloting retrofits ahead of mandate deadlines.
Integrated service contracts are unbundling hardware ownership from data analytics subscriptions. Offshore drillers in the US Gulf of Mexico now lease vibration monitoring infrastructure while purchasing predictive maintenance software separately. The purchasing model shift is visible most acutely among independent operators lacking capital reserves for full system acquisition.
Oil and Gas Downhole Vibration Monitoring and Control System Market Segmentation
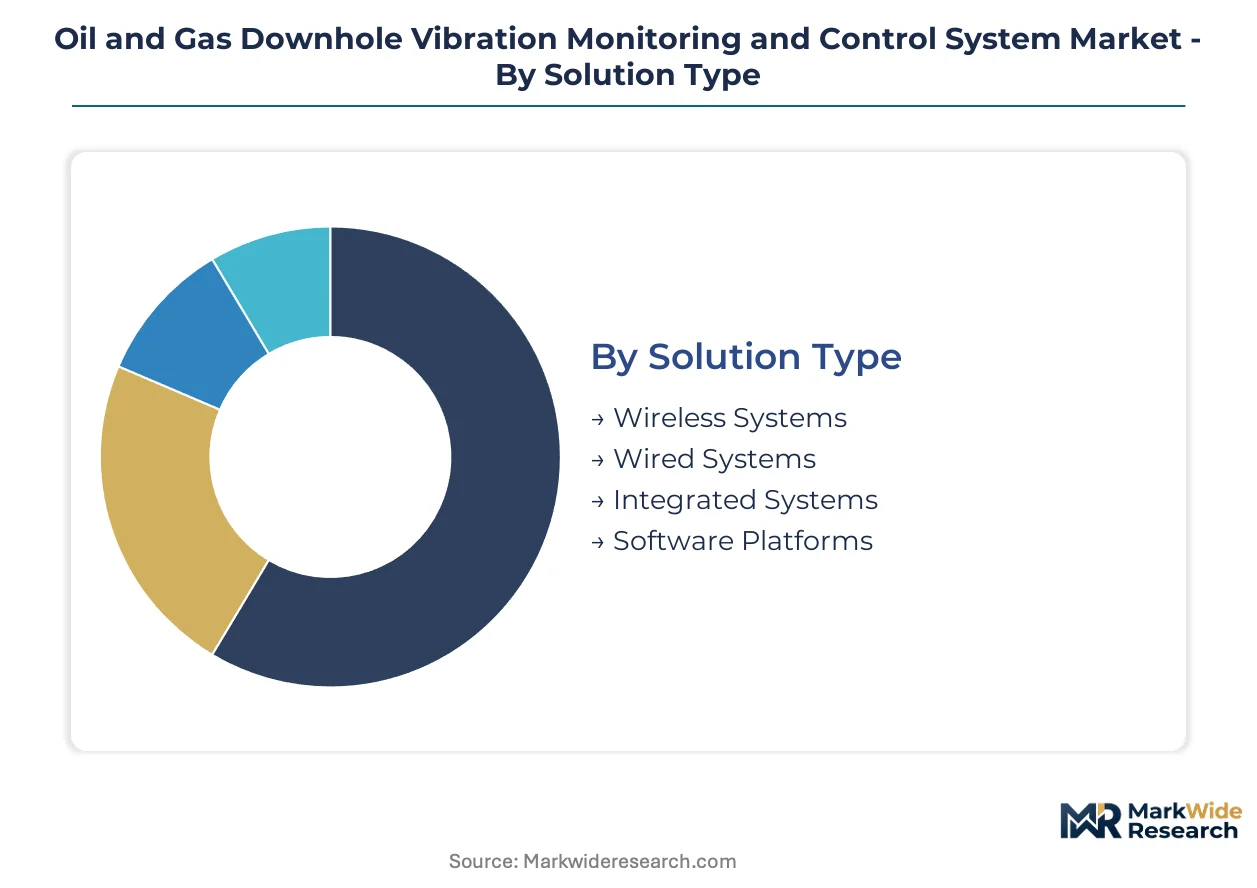
Vibration monitoring architectures fragment across telemetry reliability, installation economics, and data integration depth. Procurement decisions hinge on whether operators prioritize real-time bandwidth or rig-up speed. Each segment category reflects a distinct trade-off between capital intensity and operational flexibility.
Solution Type:
Cost tier determines adoption patterns across drilling environments, with premium integrated platforms competing against modular wireless alternatives.
- Wired Systems:Coaxial and fiber-optic cable assemblies transmit high-fidelity vibration data from downhole sensor arrays to surface acquisition units without electromagnetic interference. Gulf of Mexico deepwater operators mandate these systems for high-pressure high-temperature wells where telemetry dropout risks catastrophic bottom-hole assembly failure. US BSEE regulations cement their position in federal waters.
- Wireless Systems:Lithium-powered micro-transmitters eliminate cable deployment and retrieval cycles, cutting rig-up time by half. Permian Basin pad drilling contractors favor these for multi-well sequences where rapid equipment repositioning compresses drilling schedules. Signal degradation in high-density mud limits their reach beyond 12,000-foot measured depths.
- Integrated Systems:Bundled hardware-software packages combine triaxial accelerometer networks with cloud-based predictive analytics portals.
- Software Platforms:Standalone vibration data visualization and machine-learning modules licensed separately from sensor infrastructure.
Wired Systems command the established base. The steepest expansion runs through Wireless Systems.
Deployment Model:
Application environment dictates sensor packaging specifications, with subsea installations demanding pressure-rated housings unavailable in onshore variants.
- Offshore:Platform-based and floating rig installations require explosion-proof junction boxes and saltwater-resistant cable armoring. North Sea operators specify these for jack-up rigs drilling HPHT formations beneath the Norwegian Continental Shelf. API RP 7G certification timelines extend procurement cycles.
- Onshore:Land rig deployments favor rapid-deployment wireless nodes and battery-swappable transmitter pods. West Texas shale operators standardize these for batch drilling programs across 10-well pads where infrastructure reuse amortizes equipment costs.
- Subsea:Seabed-deployed sensor modules integrated with blowout preventer control systems for post-drilling production monitoring.
- Hybrid:Configurations mixing wired bottom-hole assemblies with wireless topside repeaters for extended-reach laterals.
Offshore deployments anchor revenue concentration. Onshore installations are climbing the fastest.
End User:
Customer type shapes purchasing authority, with production companies controlling capital budgets that exploration firms must route through service contracts.
- Production Companies:Operating subsidiaries of integrated majors and national oil companies own vibration monitoring assets as permanent well infrastructure. Saudi Aramco and ADNOC deploy company-owned sensor networks across their extended-reach drilling campaigns. Long-term amortization horizons justify premium integrated system investments.
- Service Providers:Schlumberger, Baker Hughes, and Weatherford lease vibration management packages to operators under performance-based contracts. Their procurement decisions prioritize equipment interoperability across diverse rig fleets.
- Exploration Companies:Independent E&P firms renting drilling services without owning downhole monitoring hardware.
- OEMs:Original equipment manufacturers embedding vibration sensors into drillstring components at the factory.
Production Companies retain the dominant installed base. Service Providers are gaining share fastest through rental model expansion.
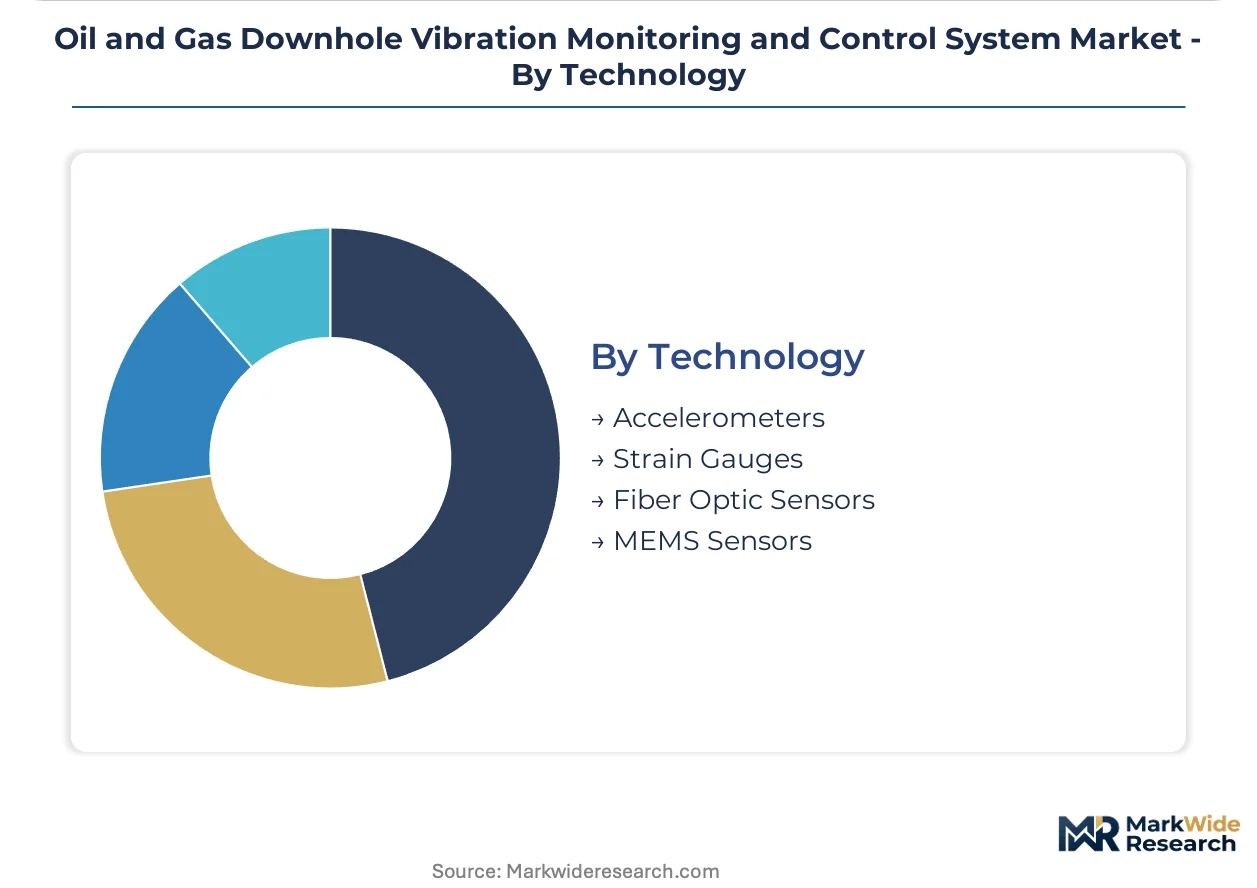
Technology:
Sensor modality selection trades measurement precision against environmental tolerance, with MEMS devices displacing legacy strain gauges in high-shock applications.
- MEMS Sensors:Micro-electromechanical systems package triaxial accelerometer arrays in shock-hardened ceramic housings smaller than conventional gauges. Bakken formation operators specify these for their resistance to calibration drift through 200°C thermal cycling. Semiconductor foundry capacity constraints limit supply elasticity.
- Fiber Optic Sensors:Intrinsic and extrinsic Fabry-Perot interferometers measure strain and vibration without electrical components, surviving geothermal-grade temperatures exceeding 300°C. Icelandic geothermal drilling contractors pilot these for volcanic reservoir characterization. Cable fragility in high-torque directional drilling constrains oilfield adoption.
- Accelerometers:Piezoelectric and piezoresistive vibration transducers delivering analog or digital output signals.
- Strain Gauges:Foil and semiconductor resistance-based sensors measuring drillstring torsional and axial loading.
MEMS Sensors command technology transition momentum. Fiber Optic Sensors represent the steepest expansion trajectory for extreme-temperature applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication for extreme-temperature downhole sensors concentrates among semiconductor foundries in the United States, Germany, and Japan. Demand deployment follows drilling campaign intensity across the US Gulf of Mexico, Middle Eastern extended-reach fields, and North Sea deepwater provinces.
United States
Deepwater operators in the Gulf of Mexico drive demand for wired telemetry systems capable of withstanding high-pressure high-temperature well conditions. The US Bureau of Safety and Environmental Enforcement mandates real-time monitoring for HPHT wells in federal waters, forcing upgrades from passive damping tools. Houston serves as the primary procurement hub where service companies consolidate integrated platform contracts.
Saudi Arabia
Extended-reach drilling campaigns exceeding 15,000-foot laterals require advanced vibration suppression to manage torque and drag. Saudi Aramco deploys company-owned sensor networks across its drilling programs, favoring permanent well infrastructure over rental models. The Eastern Province concentration of drilling activity anchors regional demand for predictive analytics-integrated systems.
Norway
North Sea jack-up rig operators specify explosion-proof junction boxes and saltwater-resistant cable armoring for HPHT formations beneath the Norwegian Continental Shelf. EU F-Gas Regulation restrictions on sulfur hexafluoride pressure manufacturers to certify alternative gas-insulated switchgear by 2026. Stavanger-based operators pilot fluoronitrile retrofits ahead of mandate deadlines.
China
Domestic shale development in Sichuan-Chongqing and Ordos Basin formations drives adoption of wireless telemetry systems for rapid rig repositioning. MIIT standards for industrial IoT equipment shape procurement specifications for downhole data transmission hardware. Beijing-Tianjin-Hebei corridor engineering firms develop localized sensor fusion algorithms for automated drilling optimization.
United Kingdom
North Sea decommissioning timelines and remaining field life extension projects sustain demand for vibration monitoring retrofits on legacy platforms. API RP 7G certification requirements extend equipment qualification cycles for market access. Aberdeen clusters specialize in subsea control module integration with blowout preventer systems for post-drilling production monitoring.
Oil and Gas Downhole Vibration Monitoring and Control System Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying MEMS accelerometers and fiber-optic transducers. The vendor structure organizes around three archetypes: full-stack service providers bundling hardware with analytics, pure-play sensor manufacturers, and drilling contractors leasing integrated packages. Competitive moves concentrate on strategic partnerships between telemetry hardware firms and cloud analytics platforms, plus backward integration into semiconductor foundry capacity.
Among US-based energy service conglomerates, Schlumberger Limited, Baker Hughes Company, and Halliburton Company exemplify the full-stack archetype through their integrated hardware-software offerings. Weatherford International plc occupies a position bridging wired and wireless platform architectures. These entities represent the dominant competitive force as procurement consolidates around bundled vibration management systems.
| Leading Market Players |
|---|
| Weatherford International plc |
| Emerson Electric |
| Schlumberger Limited |
| Nabors Industries Ltd |
| GE Oil and Gas |
| Baker Hughes Company |
| National Oilwell Varco |
| Honeywell International Inc |
| Halliburton Company |
| Others |
Value Network & Pricing Analysis
Houston's concentration of oilfield service engineering talent and integrated platform providers concentrates pricing power among full-stack vendors capable of bundling hardware with predictive analytics subscriptions. The Permian Basin's pad drilling intensity feeds demand for rapid-deployment wireless systems, while Gulf of Mexico operators absorb premium pricing for wired telemetry meeting federal safety mandates.
Pricing Analysis
US BSEE mandates dictate the pricing tier structure for vibration monitoring systems in federal waters, separating certified HPHT-compliant wired platforms from standard wireless alternatives. Pricing stratifies across premium integrated systems, standard modular hardware, and economy sensor-only configurations, with differentiation anchored in API RP 7G certification status and telemetry bandwidth guarantees. Cost compression in the wireless segment is intensifying because lithium-powered micro-transmitter suppliers compete for Permian Basin pad drilling contracts. Production companies show least price sensitivity for offshore deployments where regulatory compliance overrides capital concerns, while independent exploration firms drive hardest bargaining for onshore rental packages.
Supply Chain Analysis
Extended payment terms from integrated service providers to MEMS foundry partners in the United States, Germany, and Japan strain working capital across the supplier base. Semiconductor fabrication for geothermal-grade accelerometers draws from silicon wafer suppliers, ceramic packaging specialists, and lithium battery cell manufacturers, with supply chain risk concentrated in single-source vulnerability for high-temperature MEMS capacity. Distribution runs through Houston-based procurement hubs serving Gulf of Mexico operators, Stavanger clusters supplying North Sea jack-up rigs, and Dubai logistics centers supporting Middle Eastern extended-reach campaigns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Downhole vibration monitoring sits at the intersection of regulatory mandate acceleration and machine-learning convergence, creating a high-growth disruption as automated stick-slip mitigation displaces rule-based surface control.
For Market Incumbents: Entrench market position through backward integration into MEMS semiconductor foundry capacity, securing captive supply of high-temperature accelerometers as foundry constraints tighten. Deepen API RP 7G certification investment ahead of competitors to lock North Sea and Gulf of Mexico procurement cycles, while developing proprietary sensor fusion algorithms that resist commoditization by third-party machine-learning platforms. For New Entrants and Emerging Players: Geothermal drilling contractors in Nevada and Iceland represent the most penetrable entry point for temperature-tolerant fiber-optic sensing systems, transferring oilfield-hardened technology to energy transition applications. Wireless mesh network architectures for Permian Basin multi-well pads offer a second white-space target, with go-to-market execution best pursued through equipment leasing partnerships with regional drilling contractors lacking capital reserves for full system acquisition. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because federal safety mandates create durable demand floors that insulate revenue from oil price volatility. Acquisition targets should prioritize pure-play sensor manufacturers with MEMS fabrication relationships and existing API certification portfolios. Monitor US BSEE rulemaking expansion beyond HPHT wells as the critical inflection signal for addressable market step-change.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Backward Integration | Captive accelerometer supply secures margin control against semiconductor capacity constraints. |
| API RP 7G Certification Acceleration | Early qualification locks North Sea procurement cycles before competitor entry. |
| Geothermal Technology Transfer | Fiber-optic sensing systems pivot to Nevada and Iceland energy transition drilling. |
| Wireless Mesh Network Deployment | Shared telemetry infrastructure amortizes costs across Permian Basin multi-well pads. |
| Machine-Learning Platform Licensing | Sensor fusion algorithm commercialization creates recurring software revenue streams. |
Research Methodology
The analysis maps wired telemetry systems, wireless micro-transmitter platforms, integrated hardware-software bundles, and predictive analytics software modules, each validated through drilling engineers, procurement officers at production companies, vibration sensor R&D directors, and offshore rig operations managers. Primary interview findings triangulate against API standards documentation, US BSEE regulatory filings, SEC 10-K equipment revenue disclosures, and customs data for downhole electronics imports. Bottom-up segment sizing and top-down market constraint checks ensure internal consistency across the projection horizon.
Forecast assumptions hold fixed current regulatory mandate scope and lithium battery energy density trajectories, while varying oil price scenarios and extended-reach drilling penetration rates across the modeling period. Segmentation dimensions include solution type, deployment environment, end-user category, and sensor technology modality, with CAGRs derived from elasticity-adjusted adoption curves and replacement cycle analysis. Inputs incorporate rig count forecasts, HPHT well permitting trends, and MEMS foundry capacity expansion announcements.
Practitioners should monitor US BSEE rulemaking scope expansion, EU F-Gas Regulation enforcement timing, and geothermal drilling permit acceleration for early signals of demand inflection. Forecasts reflect documented assumptions; macroeconomic commodity price collapse, abrupt regulatory relaxation, or breakthrough solid-state battery technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Middle East and Africa Drill Collar Market
Oil & Gas
Global Oil and Chemical Spill Kits Market
Oil & Gas
Global Completion Equipment and Services Market
Oil & Gas
Slickline Services Market
Oil & Gas
Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Oil & Gas Defoaming Separator Market
Oil & Gas
Enclosed Flares Market
Oil & Gas
Wellhead Equipment Market
Oil & Gas
Cuttings Re-Injection Services Market
Oil & Gas
Oilfield Roller Chain Market
Oil & Gas
Brazil Oil and Gas Midstream Market
Oil & Gas
Oil Well Cement Market
Oil & Gas
Chad Oil and Gas Market
Oil & Gas
North America Wireline Logging Services Market
Oil & Gas
Oil and Gas Industry Turbomachinery Market
Oil & Gas
Republic of Congo Oil and Gas Market