
 Marine Energy Market | 2026-2036
Marine Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Energy Market Insights
The marine energy sector is restructuring around a sharp divergence between premium tidal stream systems and commodity wave energy hardware. Andritz Hydro leverages its hydroelectric heritage to dominate turbine manufacturing scale. Orbital Marine Power anchors the premium tier through specialized floating platform engineering. CorPower Ocean differentiates via advanced wave energy converter architectures that target higher capacity factors.
Marine energy encompasses the capture and conversion of ocean kinetic and thermal resources into grid-ready electricity, typically through tidal barrages, oscillating water columns, or temperature differential engines operating across 10-30°C thermal gradients. The technology serves baseload renewable generation for coastal grids and isolated industrial loads. Tidal Power leads installed capacity due to predictable resource availability and mature turbine designs. Wave Energy occupies the fastest-expansion trajectory as survivability engineering improves. Ocean Thermal Energy Conversion holds concentrated margin pools in tropical zones where surface-to-deep temperature differentials exceed 20°C year-round.
The EU Green Deal and F-Gas Regulation shape European deployment pathways by mandating low-carbon marine infrastructure standards. The UK's Marine Management Organisation and Crown Estate leasing frameworks control site access and determine project economics through consenting timelines. Stakeholders must monitor regulatory fragmentation between national maritime spatial plans and emerging international seabed governance instruments.
Market Dynamics
The marine energy sector is restructuring around a sharp divergence between premium tidal stream systems and commodity wave energy hardware, with deployment economics increasingly dictated by site-specific consenting timelines rather than technology cost curves alone.
Growth Catalysts
- EU Green Deal marine infrastructure mandates:The EU Green Deal and F-Gas Regulation mandate low-carbon standards for offshore installations, accelerating capital flows into tidal barrage and floating platform projects across coastal member states.
- Predictable baseload demand from island grids:Isolated industrial loads and coastal utilities in the United Kingdom, France, and South Korea are contracting long-term power purchase agreements with tidal stream developers to displace diesel generation.
- Survivability engineering advances:Improved materials science and dynamic load management systems are extending wave energy converter operational lifespans, reducing levelized cost thresholds for commercial deployment.
Market Restraints
- Specialized vessel supply bottlenecks:Heavy-lift installation vessels capable of handling floating tidal platforms concentrate in North Sea ports, creating queue risks for project developers.
- Copper and rare-earth magnet cost volatility:Permanent magnet synchronous generators depend on neodymium and dysprosium supply chains dominated by Chinese processing capacity.
- Extended Crown Estate leasing timelines:The UK's Marine Management Organisation consenting processes frequently exceed 36 months, freezing project returns and deterring pre-revenue financing.
Strategic Opportunities
- Underpenetrated tropical OTEC zones:Ocean Thermal Energy Conversion holds concentrated margin pools in Indonesia and the Philippines where surface-to-deep temperature differentials exceed 20°C year-round.
- Hybrid offshore wind-tidal co-location:Shared electrical infrastructure and grid connection points create capital efficiency gains at sites in Scotland's Pentland Firth and France's Raz Blanchard.
- Green hydrogen offtake integration:Electrolyzer co-location with marine energy assets enables power-to-X revenue stacking for projects facing grid interconnection constraints.
Industry Challenges
- Marine electrical engineer talent scarcity:Subsea cable termination and wet-mate connector specialists command premium wages, constraining deployment velocity.
- Type certification timeline compression:DNV and Bureau Veritas marine energy certification protocols require multi-year tank testing and sea trials, delaying revenue recognition.
- Legacy grid integration protocols:Transmission system operators lack standardized interconnection requirements for variable marine renewable inverters, forcing bespoke engineering per project.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Energy Market |
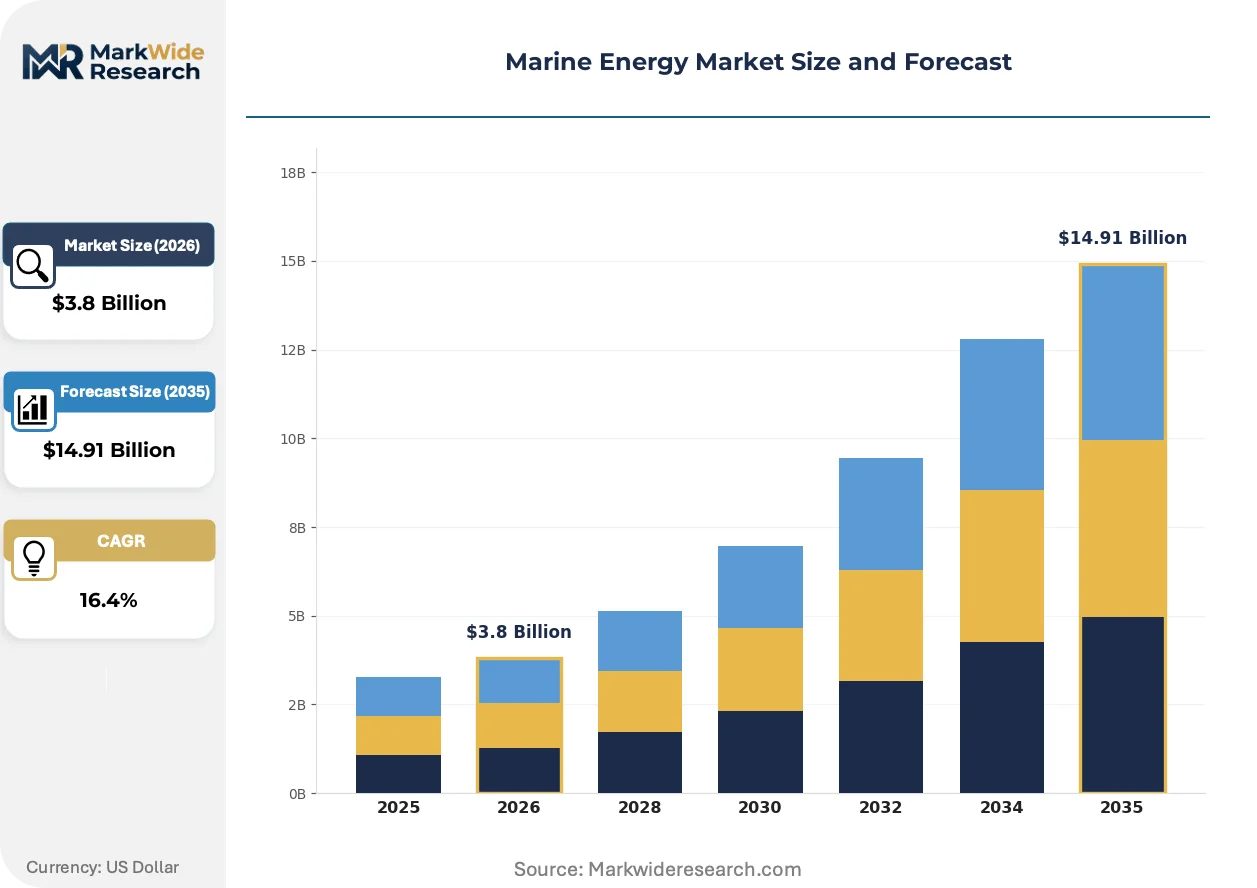
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Tidal Power, Wave Energy, Ocean Thermal Energy Conversion, Salinity Gradient, Current Power Application: Remote Island Power, Offshore Platforms, Desalination Plants, Coastal Community Electrification, Marine Research Stations Installation Type: Fixed Platforms, Floating Units, Submarine Installations, Shoreline Systems, Hybrid Structures End User: Renewable Utilities, Marine Industrial Facilities, Government Agencies, Research Institutions, Maritime Operators |
| Companies Covered | Andritz Hydro, Orbital Marine Power, CorPower Ocean, Ocean Power Technologies, Minesto, Carnegie Clean Energy, Ocean Renewable Power Company, AW-Energy, Nova Innovation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Energy Market Trends and Innovations
Active experimentation with modular platform architectures and digital twin-based predictive maintenance is compressing operational expenditure profiles while extending asset lifespans beyond original design assumptions.
Floating tidal turbine platforms are absorbing the engineering complexity previously handled by fixed-bottom foundations, enabling deployment in deeper water sites where current velocities intensify. Scottish and French project developers are adopting these systems for 40-60 meter depth zones. The shift is absorbing capital that would otherwise flow toward conventional monopile fabrication, redirecting supply chain investment toward dynamic cable and mooring system specialists.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in offshore electrical switchgear, forcing manufacturers to redesign insulating gas formulations or transition to vacuum interruption technology. Equipment suppliers serving North Sea projects face accelerated redesign timelines to maintain CE marking compliance. Tidal stream array developers in the United Kingdom are prioritizing SF6-free switchgear specifications in tender documents to preempt regulatory retrofit liabilities.
Long-term power purchase agreements are displacing merchant exposure as the dominant offtake structure for commercial-scale marine energy projects. Institutional investors and pension funds are underwriting 15-20 year contracts with tidal stream developers in the United Kingdom and South Korea, accepting lower returns in exchange for inflation-linked revenue certainty. This behavioral shift is most visible in the United Kingdom, where the Contracts for Difference auction mechanism has conditioned sponsors to prioritize secured revenue over merchant optimization.
Marine Energy Market Segmentation
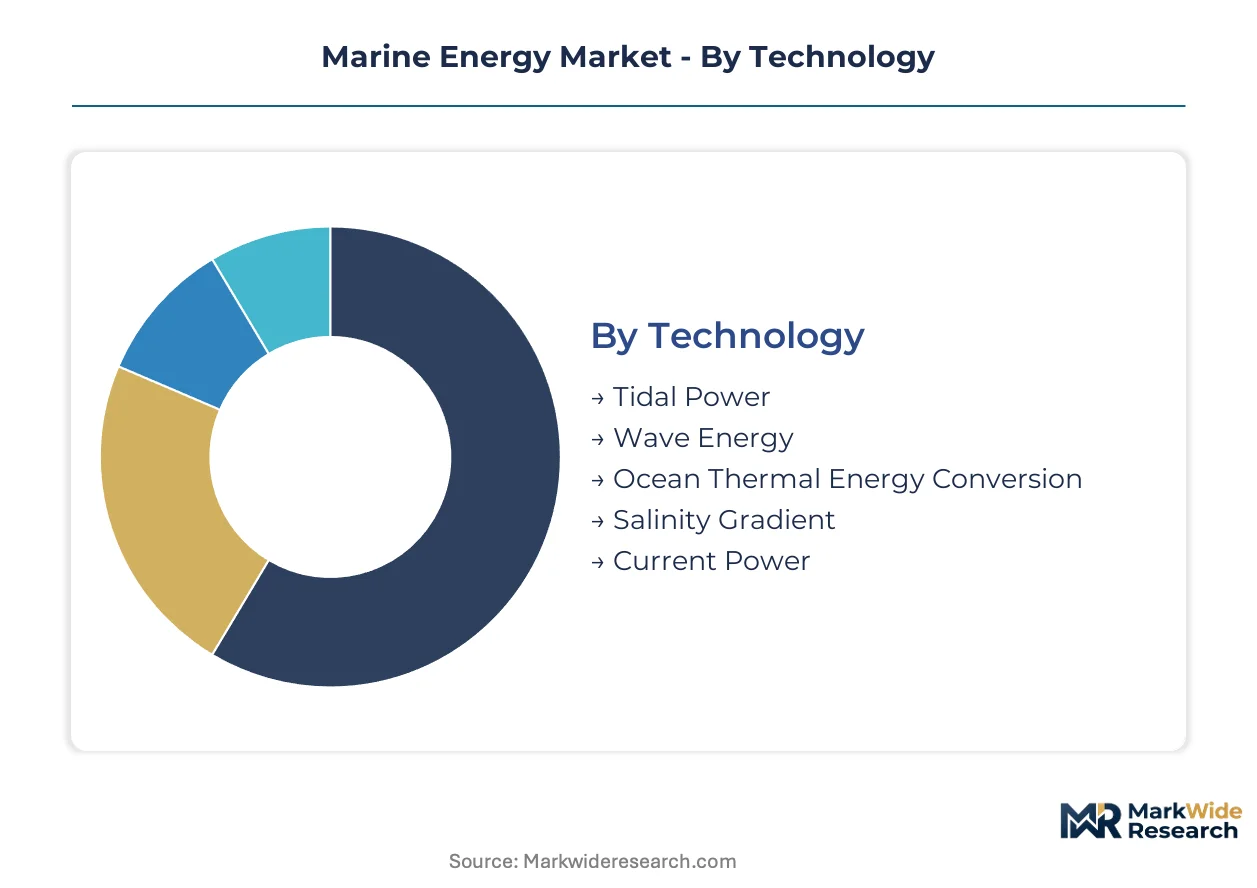
Marine energy deployment varies sharply by technology maturity and site-specific resource profiles. Installation architecture and end-user risk tolerance further fragment procurement patterns across coastal jurisdictions.
Technology:
The customization-to-standardization spectrum runs from bespoke tidal turbine arrays to modular wave energy converter platforms.
- Tidal Power:Barrage and stream turbine systems exploit predictable lunar-cycle current patterns. Demand concentrates in the United Kingdom and France where Crown Estate and state concession frameworks provide revenue certainty through long-term offtake contracts.
- Wave Energy:Oscillating water column and point absorber architectures target higher capacity factors through advanced materials science. Scottish developers and Portuguese project sponsors are contracting first commercial arrays as survivability engineering extends operational lifespans.
- Ocean Thermal Energy Conversion:Closed-cycle and open-cycle systems harness 20°C+ surface-to-deep thermal differentials in tropical zones.
- Salinity Gradient:Pressure-retarded osmosis and reverse electrodialysis technologies remain pre-commercial with limited pilot installations.
- Current Power:Horizontal-axis turbines capture sub-surface kinetic flows in fjord and strait configurations.
Leading the category by volume: Tidal Power. Expanding most quickly: Wave Energy.
Application:
Cost tier stratification separates premium offshore oil-and-gas substitution from subsidized rural electrification mandates.
- Remote Island Power:Diesel displacement contracts drive procurement in archipelago jurisdictions. The Philippines and Indonesia are tendering hybrid marine-solar microgrids for island provinces under national universal electrification programs.
- Offshore Platforms:Oil and gas operators contract tidal stream power for drilling rig electrification to meet Scope 3 reduction targets. North Sea operators are specifying marine energy integration in decommissioning-to-renewables transition plans.
- Desalination Plants:Co-located renewable generation reduces energy costs for reverse osmosis facilities in water-stressed coastal zones.
- Coastal Community Electrification:Government-backed rural electrification schemes in Scotland and Wales prioritize tidal stream connections for harbor towns.
- Marine Research Stations:Antarctic and Arctic scientific outposts deploy small-scale wave and current systems to reduce fuel resupply logistics.
Dominant by revenue: Offshore Platforms. Steepest expansion trajectory: Remote Island Power.
Installation Type:
Volume concentration favors floating platforms as water depth requirements push deployment beyond fixed-foundation economics.
- Fixed Platforms:Gravity-base and monopile structures anchor tidal turbines in shallow high-velocity channels. The Pentland Firth and Raz Blanchard host dense arrays where bathymetry permits cost-effective seabed preparation.
- Floating Units:Tension-leg and semi-submersible platforms enable deeper water deployment where current velocities intensify. French developers are advancing floating tidal systems for 40-60 meter Atlantic coast zones previously inaccessible to fixed structures.
- Submarine Installations:Seabed-anchored current turbines operate below surface traffic lanes in busy shipping corridors.
- Shoreline Systems:Oscillating water columns integrated into breakwater structures serve dual coastal protection and generation functions.
- Hybrid Structures:Combined wind-tidal platforms share moorings and export cables at multi-resource sites.
Highest deployment share: Floating Units. Gaining share fastest: Hybrid Structures.
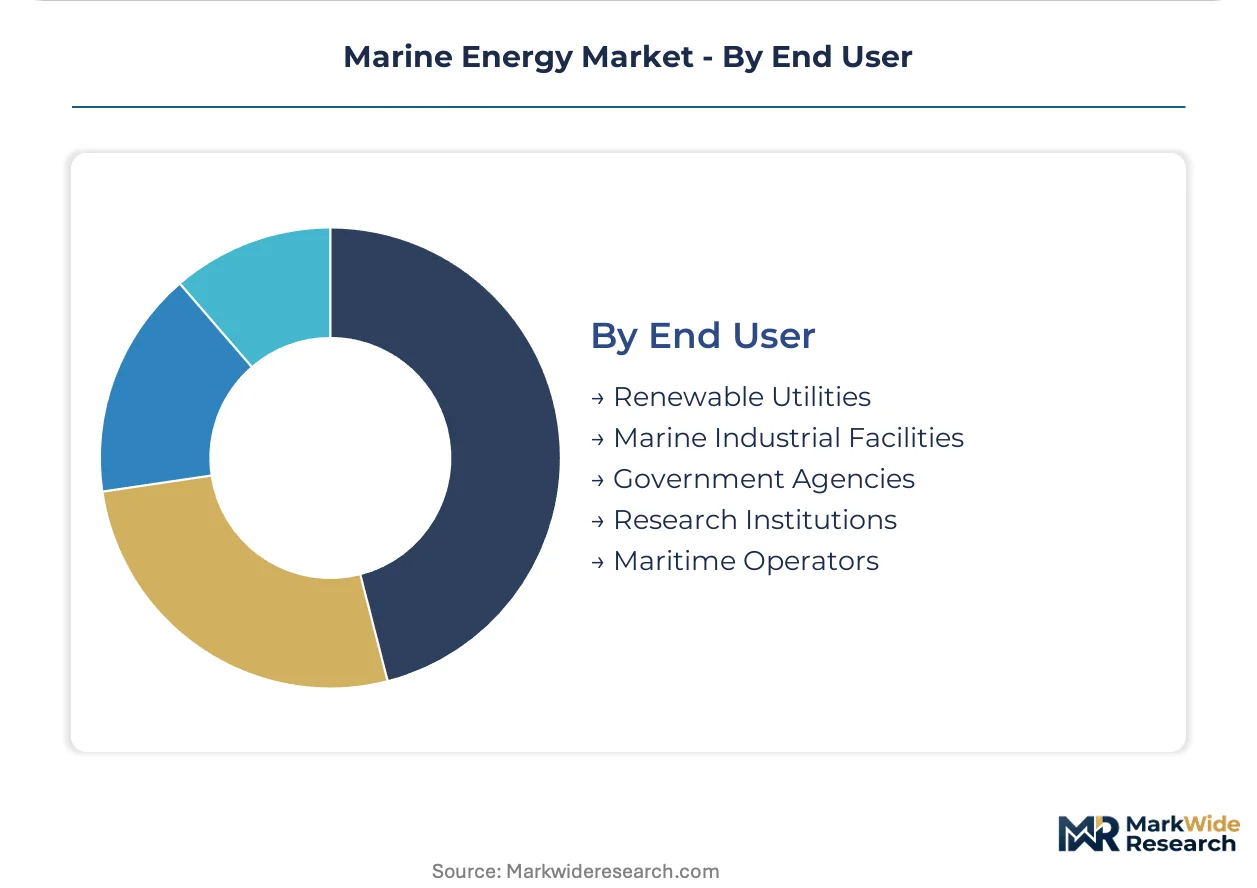
End User:
Customer type determines contracting structure, with institutional investors favoring utility-scale offtake over industrial self-supply.
- Renewable Utilities:Vertically integrated power companies contract marine energy under feed-in tariff and contract-for-difference mechanisms. United Kingdom utilities dominate procurement through CfD auction participation and marine spatial planning site control.
- Marine Industrial Facilities:Port operators and shipyards seek behind-the-meter generation to stabilize energy costs. South Korean heavy industry clusters are evaluating tidal stream integration for steel and chemical complex power supply.
- Government Agencies:Defense and coastal management authorities procure marine energy for sovereign energy security objectives.
- Research Institutions:Universities and oceanographic institutes operate test berths and demonstration arrays.
- Maritime Operators:Ferry and cargo terminal operators pilot wave energy for shore power and vessel charging.
Primary volume concentration: Renewable Utilities. Fastest-growing procurement category: Marine Industrial Facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orkney Islands anchor marine energy deployment density through the European Marine Energy Centre test berths and operational tidal arrays. Project pipelines concentrate in coastal jurisdictions with active seabed leasing frameworks and established consenting pathways.
United Kingdom
Crown Estate leasing rounds and Contracts for Difference auctions drive tidal stream procurement in Scottish waters and Welsh coastal zones. The Marine Management Organisation consenting framework governs site access timelines. Pentland Firth developers deploy floating platforms in 40-60 meter depth corridors previously inaccessible to fixed foundations.
France
State concession frameworks and feed-in tariffs support tidal array development in Raz Blanchard and Brittany coastal zones. The Agence de l'Environnement et de la Maîtrise de l'Énergie administers marine renewable support schemes. Normandy project sponsors advance semi-submersible platforms for Atlantic coast deep-water sites.
South Korea
Heavy industry clusters in Ulsan and Busan evaluate tidal stream integration for steel and chemical complex power supply under national renewable portfolio standards. The Ministry of Trade, Industry and Energy oversees offshore energy licensing. Southwestern coastal provinces tender hybrid marine-solar configurations for island electrification.
Indonesia
Archipelago electrification mandates and 20°C+ surface-to-deep thermal differentials attract Ocean Thermal Energy Conversion feasibility studies in Sulawesi and Maluku waters. The national energy regulator issues geothermal and marine energy permits under unified licensing reforms. Eastern province developers pilot closed-cycle systems for resort island baseload generation.
Canada
Bay of Fundy tidal resource assessments and indigenous partnership frameworks shape project development in Nova Scotia and New Brunswick. Fisheries and Oceans Canada coordinates marine spatial planning with provincial energy authorities. Fundy Ocean Research Center for Energy operates demonstration berths for technology validation.
Marine Energy Market Competitive Landscape
Capital-heavy turbine manufacturers compete with asset-light platform engineering specialists across divergent technology pathways. The vendor base stratifies between integrated industrial conglomerates with hydroelectric heritage and dedicated marine energy developers with concentrated intellectual property portfolios. Two strategic archetypes dominate: scale-driven turbine fabricators leveraging existing supply chains, and premium-tier system integrators specializing in floating platform dynamics. Competitive moves center on seabed leasing queue positioning and type certification timeline acceleration through regulator pre-engagement.
Within the industrial conglomerate tier, Andritz Hydro exemplifies scale-driven manufacturing architecture, while Orbital Marine Power and CorPower Ocean occupy specialized engineering positions. Andritz Hydro represents established hydroelectric supply chain extension into marine turbine fabrication. Orbital Marine Power anchors the floating platform specialization vector through dedicated marine energy focus. CorPower Ocean exemplifies wave energy converter architecture differentiation targeting survivability engineering premiums.
| Leading Market Players |
|---|
| Andritz Hydro |
| Orbital Marine Power |
| CorPower Ocean |
| Ocean Power Technologies |
| Minesto |
| Carnegie Clean Energy |
| Ocean Renewable Power Company |
| AW-Energy |
| Nova Innovation |
| Others |
Pricing and Supply Chain Analysis
Premium floating platform engineering commands substantial cost premiums over fixed-bottom tidal systems, with this performance gap manifesting in divergent procurement structures and geographically concentrated supplier networks. The United Kingdom's Crown Estate leasing premiums and French state concession fees embed site-access costs into project-level pricing, while EU F-Gas Regulation compliance costs reshape electrical component sourcing toward SF6-free switchgear specialists.
Pricing Analysis
Long-term power purchase agreement pricing anchors commercial viability for tidal stream developers, with 15-20 year contract tenors trading yield for revenue certainty. Price differentiation hinges on certification tier—DNV type-approved systems command premiums over pre-certified prototypes—and geographic delivery cost differentials between North Sea fabrication yards and tropical OTEC sites. Cost compression in wave energy converter manufacturing is intensifying as survivability engineering standardizes, though marine electrical engineer scarcity sustains premium labor pricing. Island grid utilities exhibit highest price sensitivity due to diesel displacement economics, while offshore oil-and-gas operators prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Marine electrical engineer scarcity in Scotland and France constrains fabrication velocity for floating platform assembly yards. Supply concentration centers on China for neodymium and dysprosium processing, Germany for precision gearbox manufacturing, and South Korea for heavy-lift vessel chartering. Permanent magnet synchronous generator production draws from Chinese rare-earth supply chains, dynamic cable systems rest on Norwegian subsea specialists, and tension-leg platform components feed from French offshore oil-and-gas fabricators. Single-source vulnerability in heavy-lift installation vessel availability creates queue risks for project developers. Distribution runs through EPC contractor-led turnkey contracting with utility offtakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine energy competitive positioning is becoming a vertical-integration race, with turbine manufacturers pursuing captive control over rare-earth magnet supply chains and platform specialists acquiring mooring system capabilities.
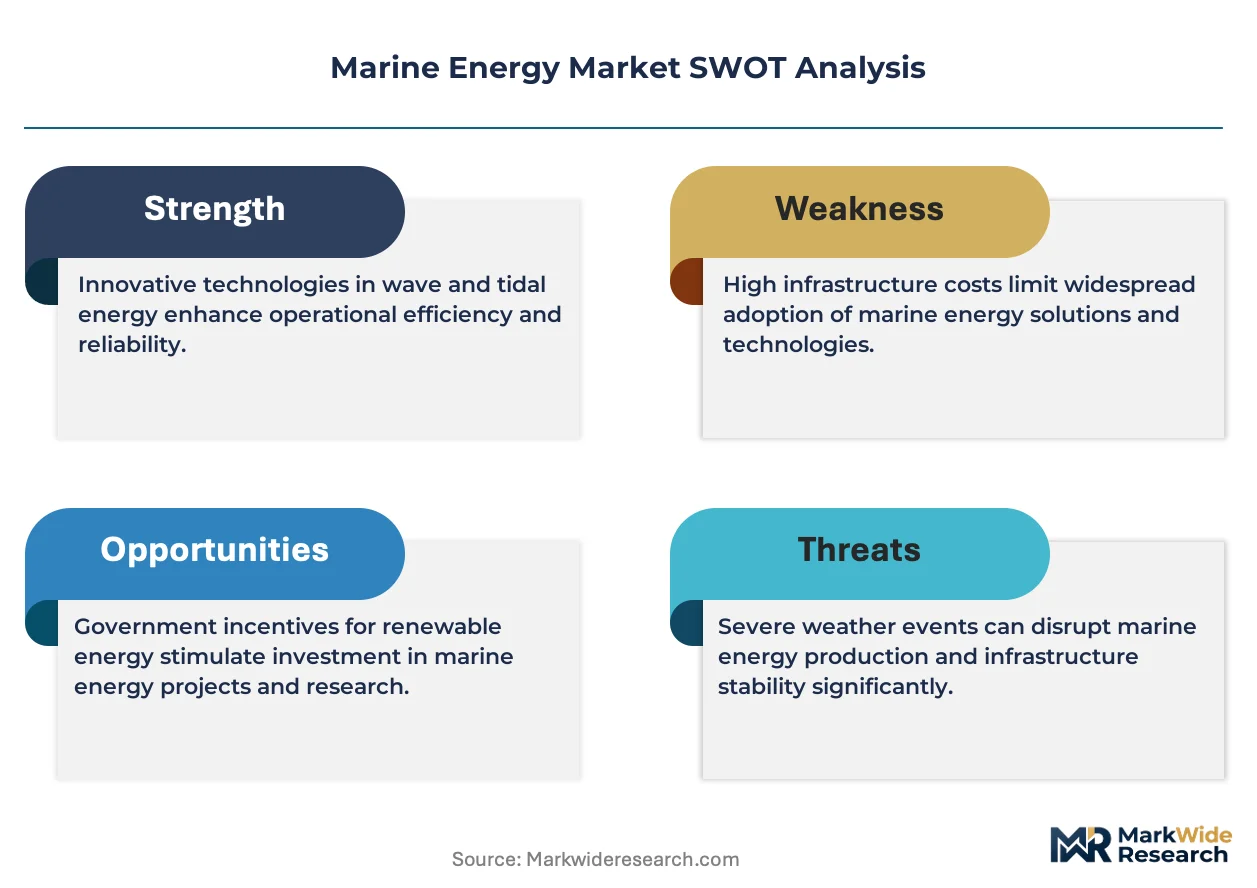
For Market Incumbents: Cement market position through Crown Estate leasing queue consolidation and accelerated DNV type certification pre-engagement. Floating platform developers face substitution threat from hybrid offshore wind-tidal co-location projects; defend through backward integration into dynamic cable manufacturing and exclusive mooring system supplier agreements. For New Entrants and Emerging Players: EU Green Deal marine infrastructure mandates in France and state concession frameworks in South Korea open a window for specialized OTEC engineering services in underpenetrated tropical zones. Target Indonesia's archipelago electrification programs and the Philippines' resort island baseload generation tenders. Pursue joint development structures with established EPC contractors to bypass type certification timeline barriers. For Investors and Strategic Acquirers: Re-rating potential sits with floating platform engineering specialists given Contracts for Difference auction mechanism expansion and institutional investor appetite for inflation-linked offtake structures. Long-term viability framing favors asset-light technology licensors over capital-heavy turbine fabricators across the 5-10 year project finance window. Watch Crown Estate leasing round participation rates as inflection indicator for deployable pipeline depth.| Strategic Initiative | Industry Significance |
|---|---|
| Type Certification Acceleration | DNV pre-engagement compresses multi-year sea trial timelines for floating tidal platforms. |
| Rare-Earth Supply Integration | Captive magnet sourcing insulates turbine manufacturers from Chinese processing volatility. |
| Hybrid Co-location Development | Shared grid infrastructure at Scottish Pentland Firth sites improves capital efficiency. |
| Green Hydrogen Revenue Stacking | Electrolyzer co-location enables power-to-X monetization where grid constraints bite. |
| SF6-Free Switchgear Specification | EU F-Gas Regulation compliance preempts regulatory retrofit liabilities in North Sea projects. |
Research Methodology
Document review covered EIA marine energy project databases, IEA ocean energy technology roadmaps, and FERC interconnection filings, complemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Primary fieldwork engaged tidal stream array sponsors in the United Kingdom and France, wave energy converter manufacturers in Scotland and Portugal, and OTEC feasibility study leads in Indonesia. Secondary validation drew from Crown Estate leasing round documentation, Marine Management Organisation consenting records, and EU Green Deal implementation guidance. Bottom-up project pipeline aggregation triangulated against top-down regulatory capacity targets.
Installed capacity and revenue estimates were generated across the analysis window through technology-specific deployment modeling segmented by resource type, installation architecture, water depth tier, and regulatory framework cluster. CAGRs were derived from project finance milestone tracking and offtake contract execution velocity. Forecast inputs incorporated Crown Estate leasing round timing, Contracts for Difference auction clearing prices, and heavy-lift vessel charter rate trajectories.
The model assumes a particular technology adoption path; alternative pathways for wave energy converter commercialization would alter the outlook if survivability engineering fails to extend operational lifespans as projected. Forecasts reflect assumptions regarding EU Green Deal implementation pacing and UK CfD auction continuity. Material deviation in rare-earth supply chain access or Crown Estate consenting timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Renewable Energy Cable Market
Renewable Energy
Global Organic Rankine Cycle Market
Renewable Energy
Hybrid Solar Wind System Market
Renewable Energy
China Renewable Energy Market
Renewable Energy
Drones in Renewable Energy Market
Renewable Energy
Renewable Energy Policy Fit Analysis Market
Renewable Energy
North America Ocean Power Market
Renewable Energy
Blockchain in Renewable Energy Market
Renewable Energy
Solar Traffic Light Market
Renewable Energy
East Europe Renewable Energy Market
Renewable Energy
Net-Zero Energy Buildings Market
Renewable Energy
Solar Balloon Market
Renewable Energy
Middle East Renewable Energy Market
Renewable Energy
Variable Renewable Energy Market
Renewable Energy
Drone Inspection Service for Renewable Energy Market
Renewable Energy
Italy Renewable Energy Market