
 Industrial Energy Monitoring Market | 2026-2036
Industrial Energy Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Energy Monitoring Market Foresight
Equipment-as-a-service and performance-contracting arrangements is reconfiguring capital deployment across the competitive landscape. Siemens AG leverages its digital twin platform to anchor long-term service relationships with heavy process industries. Schneider Electric sustains differentiation through integrated edge-to-cloud architectures that reduce deployment friction. ABB competes on the strength of its electromagnetic metering heritage and embedded analytics in power distribution hardware.
Industrial energy monitoring encompasses the continuous measurement, aggregation, and analysis of electrical, thermal, and mechanical energy flows across production facilities, typically achieving sampling rates from one-second intervals for power quality to fifteen-minute windows for utility billing reconciliation. The primary purpose centers on identifying waste vectors, enabling predictive load management, and verifying efficiency investments against baseline consumption patterns. Software and integrated solutions command expanding margin pools as buyers shift from hardware ownership to subscription-based visibility platforms. IoT-enabled sensing layers represent the fastest-growing technology dimension, though data analytics services capture disproportionate value by translating raw telemetry into actionable maintenance and scheduling recommendations.
EPA industrial efficiency guidelines and OSHA electrical safety standards shape product certification requirements and installation protocols in the United States. The EU Green Deal and REACH chemical disclosure frameworks extend compliance obligations to embedded electronics and sensor materials across European deployments. Stakeholders must weigh interoperability commitments against proprietary ecosystem lock-in as utility tariff structures evolve toward real-time pricing and carbon-intensity signaling.
Market Dynamics
Equipment-as-a-service and performance-contracting arrangements are reconfiguring capital deployment across the competitive landscape. Siemens AG leverages its digital twin platform to anchor long-term service relationships with heavy process industries. Schneider Electric sustains differentiation through integrated edge-to-cloud architectures that reduce deployment friction. ABB competes on the strength of its electromagnetic metering heritage and embedded analytics in power distribution hardware.
Growth Catalysts
- EU Green Deal compliance mandates:Steel manufacturers in Germany are expanding deployment of sub-metering networks to meet binding carbon reduction targets and secure green financing eligibility.
- State-level efficiency mandates in India:Maharashtra's industrial corridor is accelerating retrofit programs across cement and textile clusters through mandatory energy audit requirements and penalty structures.
- IoT-enabled sensing layers:Wireless sensor networks are proliferating in process industries, enabling one-second sampling rates for power quality monitoring that were previously cost-prohibitive with wired infrastructure.
Market Restraints
- Semiconductor supply concentration:Edge computing chipsets and precision ADC components face sourcing bottlenecks concentrated in Taiwan and South Korea, constraining hardware delivery timelines.
- Copper and rare earth input volatility:Electromagnetic metering hardware remains exposed to lanthanide price swings and refined copper premiums, compressing margins on legacy product lines.
- Interoperability fragmentation:Proprietary communication protocols from incumbent vendors create integration friction and extend commissioning cycles for multi-vendor deployments.
Strategic Opportunities
- Underpenetrated ASEAN manufacturing bases:Vietnam's electronics assembly corridors and Indonesia's nickel processing zones lack comprehensive monitoring infrastructure, presenting first-mover installation opportunities.
- Real-time carbon intensity signaling:Utility tariff structures in Denmark and California are introducing dynamic pricing tied to grid carbon content, creating demand for predictive load management software.
- Digital twin convergence with energy analytics:Process simulation platforms are merging with consumption telemetry to enable virtual commissioning of efficiency interventions before physical deployment.
Industry Challenges
- OT-IT integration complexity:Bridging operational technology protocols like Modbus and Profibus with cloud-native analytics platforms requires specialized engineering talent that remains scarce in industrial heartlands.
- Cybersecurity certification timelines:IEC 62443 compliance for critical infrastructure deployments extends product validation cycles and fragments vendor development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Energy Monitoring Market |
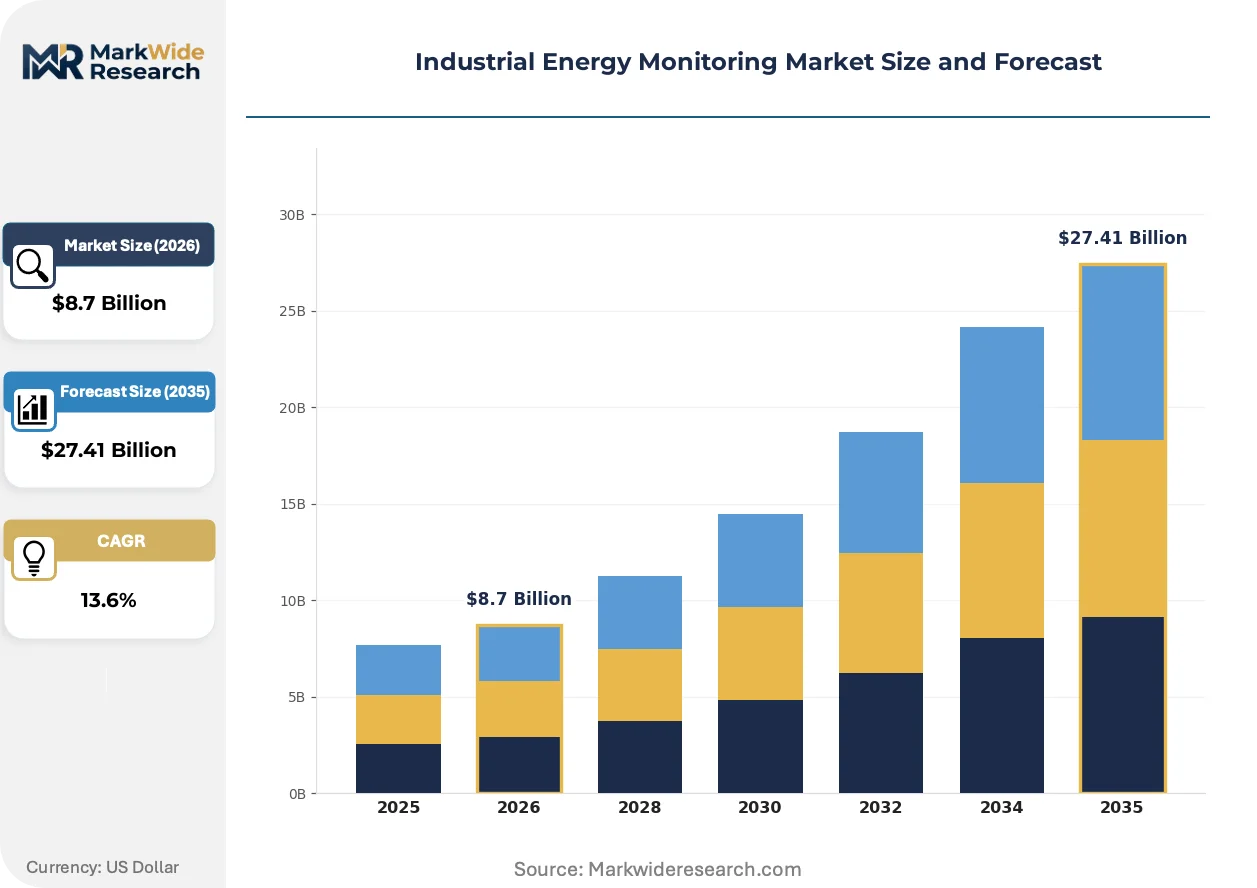
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Services, Integrated Solutions Technology: IoT, AI, Cloud Computing, Data Analytics End User: Manufacturing, Oil & Gas, Utilities, Transportation Service Type: Consulting, Implementation, Support, Maintenance |
| Companies Covered | Schneider Electric, Siemens AG, ABB, Eaton, Honeywell International Inc., Emerson Electric Company, General Electric, Rockwell Automation, Johnson Controls International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Energy Monitoring Market Shifts & Advancements
Software and integrated solutions command expanding margin pools as buyers shift from hardware ownership to subscription-based visibility platforms. IoT-enabled sensing layers represent the fastest-growing technology dimension, though data analytics services capture disproportionate value by translating raw telemetry into actionable maintenance and scheduling recommendations.
Edge-native artificial intelligence inference engines are rendering obsolete centralized cloud-only analytics architectures for fault detection and predictive maintenance. Petrochemical complexes in Texas and Rotterdam are deploying tensor processing units directly at substation level, compressing response latency from seconds to milliseconds for arc flash prevention and load shedding decisions. This distributed intelligence model is collapsing the traditional hierarchy between field instrumentation and enterprise software tiers.
REACH chemical disclosure frameworks are extending compliance obligations to embedded electronics and sensor materials across European deployments. Manufacturers must now document substance concentrations in solder joints, conformal coatings, and lithium battery electrolytes through full supply chain tiers, elevating documentation costs but creating competitive separation for vendors with pre-certified component libraries. German automotive suppliers are responding by consolidating vendor panels to reduce audit burden.
Steel and cement buyers are consolidating procurement authority into centralized energy management offices, displacing plant-level autonomous purchasing decisions. These centralized functions negotiate enterprise-wide platform licenses and demand standardized dashboards across multi-site portfolios, compressing vendor count and elevating contract values. This concentration pattern is most visible in India's integrated steel majors and Mexico's Grupo Cementos de Chihuahua operations.
Industrial Energy Monitoring Market Segmentation
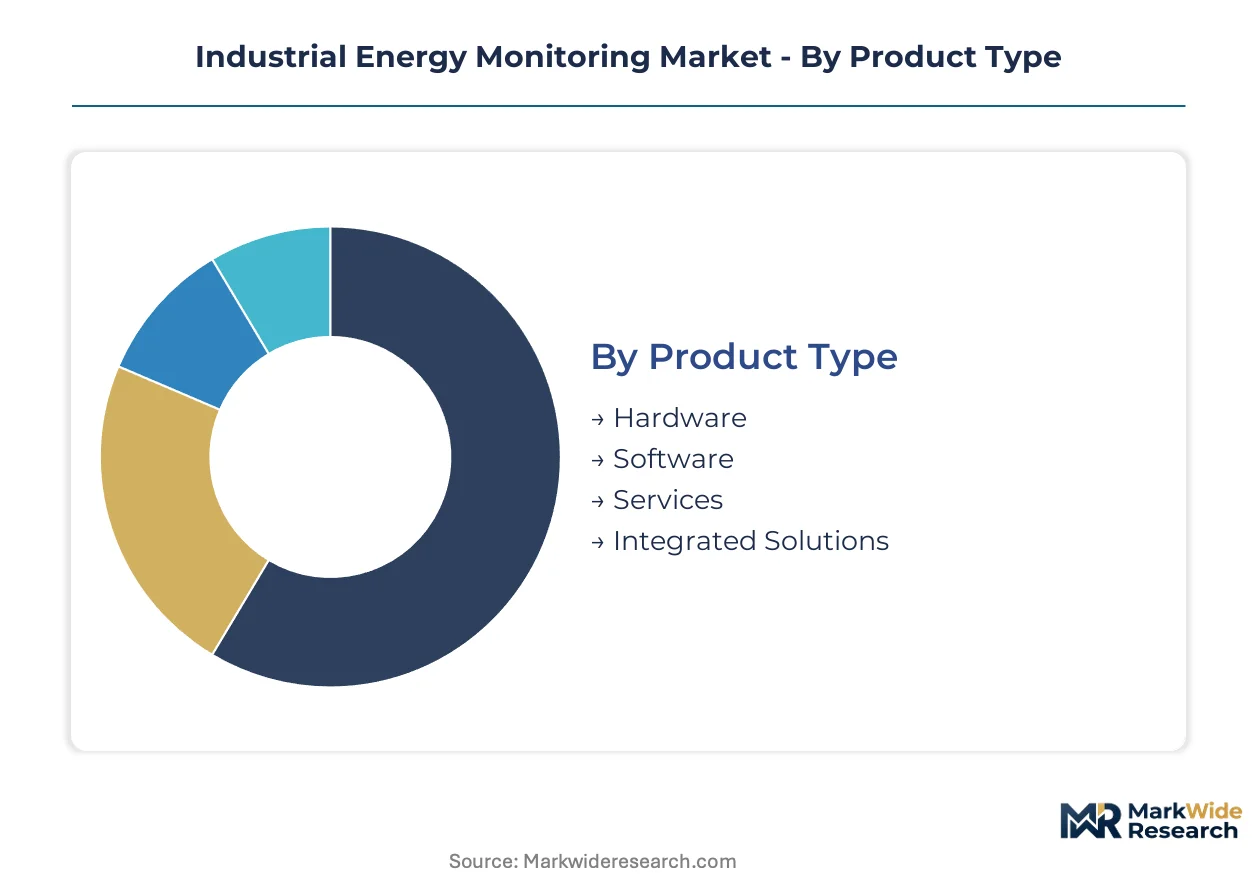
Industrial energy monitoring deployments vary sharply by operational maturity and data infrastructure sophistication. Buyers in heavy process industries prioritize integrated platforms that collapse sensing, analytics, and service layers into unified contracts, while fragmented manufacturing bases still procure hardware and software separately.
Product Type:
Procurement patterns span from capital-intensive meter installations to recurring software subscriptions that displace ownership entirely.
- Hardware:Electromagnetic meters, wireless sensor nodes, and edge computing gateways form the physical sensing layer. German steel manufacturers under EU Green Deal mandates are retrofitting sub-metering networks across blast furnace complexes to capture one-second power quality data for carbon accounting verification.
- Software:Visibility platforms aggregate telemetry into dashboards for load scheduling, efficiency benchmarking, and predictive maintenance. Maharashtra's cement and textile clusters are accelerating adoption of cloud-native analytics to comply with state-level energy audit mandates and avoid penalty structures.
- Services:Performance contracting and energy-as-a-service arrangements transfer operational risk from facility managers to vendors. These contracts typically bundle hardware provisioning, data interpretation, and guaranteed efficiency outcomes into multi-year agreements.
- Integrated Solutions:Combined hardware-software-service packages reduce commissioning friction and lock in long-term vendor relationships through single-point accountability.
Established volume favors hardware; emerging adoption favors integrated solutions.
Technology:
Technology selection hinges on latency requirements, connectivity infrastructure, and in-house data science capabilities.
- IoT:Wireless sensor networks proliferate in process industries previously constrained by wired infrastructure costs. One-second sampling rates for power quality monitoring are now cost-viable across petrochemical complexes in Texas and Rotterdam.
- AI:Edge-native inference engines compress fault detection response from seconds to milliseconds for arc flash prevention. Tensor processing units deployed at substation level are displacing centralized cloud-only architectures.
- Cloud Computing:Scalable data lakes enable multi-site portfolio visibility for buyers consolidating procurement authority into centralized energy management offices.
- Data Analytics:Value capture concentrates here—translating raw telemetry into actionable maintenance and scheduling recommendations commands expanding margin pools relative to commoditized sensing hardware.
Deployment maturity favors IoT; margin expansion favors data analytics.
End User:
End-use concentration reflects regulatory exposure, energy intensity, and capital availability for efficiency investments.
- Manufacturing:Steel, cement, and automotive assembly anchor demand in Germany and India. Centralized procurement functions at integrated steel majors are standardizing dashboards across multi-site portfolios.
- Oil & Gas:Upstream and downstream operations require hazardous-area-certified instrumentation with IEC 62443 cybersecurity compliance. Extended validation cycles fragment vendor development roadmaps.
- Utilities:Grid operators deploy monitoring at industrial interconnection points to enable real-time carbon intensity signaling and dynamic tariff structures.
- Transportation:Rail electrification and port cargo handling represent emerging application vectors with distinct mobility-focused telemetry requirements.
Regulatory pressure concentrates in manufacturing; carbon-accounting sophistication concentrates in oil and gas.
Service Type:
Service packaging determines customer lifetime value and vendor defensibility against commoditization.
- Consulting:Baseline establishment, efficiency opportunity identification, and technology roadmap development precede physical deployment. REACH chemical disclosure requirements elevate documentation costs for European engagements.
- Implementation:OT-IT integration complexity creates scarcity premiums for engineering talent capable of bridging Modbus and Profibus protocols with cloud-native platforms.
- Support:Subscription-based technical assistance ensures platform uptime and data continuity for buyers who have shifted from ownership to visibility-as-a-service models.
- Maintenance:Predictive calibration and sensor replacement contracts anchor recurring revenue streams and reduce customer churn.
Project economics favor consulting and implementation; recurring revenue stability favors support and maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German steel manufacturers command premium pricing for EU Green Deal-compliant sub-metering installations, while Indian retrofit programs in Maharashtra operate on compressed margins driven by penalty-avoidance procurement.
Germany
Blast furnace complexes in the Ruhr region are retrofitting one-second sampling networks for carbon accounting verification. EU Green Deal binding targets and green financing eligibility rules drive capital allocation toward integrated monitoring platforms. Duisburg's steel corridor hosts the densest concentration of vendor pilot programs.
India
Maharashtra's cement and textile clusters face mandatory energy audit requirements with penalty structures for non-compliance. State-level efficiency mandates accelerate cloud-native analytics adoption to document baseline consumption patterns. Mumbai-Pune industrial belt procurement concentrates on subscription-based visibility platforms.
United States
Petrochemical complexes in Texas deploy tensor processing units at substation level for arc flash prevention. EPA industrial efficiency guidelines and OSHA electrical safety standards shape certification requirements and installation protocols. Houston Ship Channel operations prioritize IEC 62443 cybersecurity compliance for hazardous-area instrumentation.
China
Yangtze River Delta manufacturing bases integrate edge-native AI inference engines for predictive load management. Dual carbon goals and provincial emissions trading schemes elevate monitoring infrastructure to strategic priority status. Shanghai's automotive assembly corridors standardize enterprise-wide platform licenses across multi-site portfolios.
Vietnam
Electronics assembly corridors in Bac Ninh and Hai Phong lack comprehensive monitoring infrastructure, presenting first-mover installation opportunities. National industrial efficiency directives and foreign direct investment incentives accelerate capital deployment. Northern manufacturing zones favor wireless sensor networks over wired alternatives.
Industrial Energy Monitoring Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in electromagnetic metering and edge computing chipsets. The vendor base organizes into three functional layers: hardware fabricators with captive analytics, software-native visibility platforms, and integrated solution providers bundling service obligations. Consolidation pressure concentrates at the middle tier as buyers demand single-point accountability. Dominant competitive moves include portfolio diversification into predictive maintenance software and geographic expansion through localized implementation partnerships.
Within the integrated platform tier, Schneider Electric, Siemens AG, and ABB represent distinct architectural approaches to collapsing sensing, analytics, and service layers. Schneider Electric exemplifies the edge-to-cloud convergence model. Siemens AG occupies a position anchored on digital twin platform relationships with heavy process industries. ABB sits within the electromagnetic metering heritage segment, leveraging embedded analytics in power distribution hardware. These three European-headquartered entities illustrate how vendor origin shapes ecosystem lock-in strategies and interoperability commitments.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens AG |
| ABB |
| Eaton |
| Honeywell International Inc. |
| Emerson Electric Company |
| General Electric |
| Rockwell Automation |
| Johnson Controls International |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp freight corridors transmit refined copper premium volatility directly into electromagnetic meter pricing, amplifying margin compression for hardware fabricators while rewarding vendors with captive rare earth sourcing arrangements in downstream contract negotiations.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with EU Green Deal certification tiers and volume scale driving differentiation. Cost compression in economy-tier hardware is intensifying because lanthanide price swings feed directly into electromagnetic metering component costs. Cement and textile clusters in Maharashtra exhibit acute price sensitivity, whereas German steel manufacturers under binding carbon targets demonstrate inelastic demand for verified sub-metering networks.
Supply Chain Analysis
Extended payment terms from Taiwanese foundries and South Korean packaging houses now stretch to 120 days for edge computing chipsets, straining working capital for mid-tier hardware vendors. Component sourcing draws from Taiwan, South Korea, and Germany for precision ADCs and tensor processing units. Copper windings, lithium battery electrolytes, and conformal coatings constitute critical input dependencies. Single-source vulnerability concentrates in Taiwan semiconductor fabrication. Distribution runs through authorized industrial automation distributors with certified integration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial energy monitoring sits in early-cycle expansion as EU Green Deal compliance deadlines and India's state-level penalty structures force first-time infrastructure deployment across previously unmonitored facilities.
For Market Incumbents: Build switching-cost moats through digital twin platform entrenchment in heavy process industries. Deepen edge-to-cloud integration investments to capture telemetry aggregation contracts before standardization erodes proprietary protocol advantages. Defend against software-native entrants by embedding analytics directly into power distribution hardware, leveraging electromagnetic metering heritage as a distribution anchor. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's electronics assembly corridors, where foreign direct investment incentives and absent incumbent relationships create first-mover installation opportunities. Target Indonesia's nickel processing zones with wireless sensor network offerings that bypass wired infrastructure cost barriers. Lead with performance-contracting arrangements that transfer operational risk and accelerate procurement decisions. For Investors and Strategic Acquirers: Edge-native AI inference specialists with hazardous-area certification pipelines represent the most defensible acquisition archetype for medium-term platform consolidation. Long-term viability hinges on vendors capturing data analytics margin pools rather than commoditized sensing hardware revenue. Monitor utility tariff evolution toward real-time carbon intensity signaling as the inflection indicator for predictive load management software demand.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-to-Cloud Platform Integration | Schneider Electric's architecture reduces commissioning friction for Maharashtra cement cluster retrofits. |
| Digital Twin Convergence | Siemens AG anchors multi-year service relationships through virtual commissioning capabilities. |
| Backward Integration into Rare Earth Sourcing | ABB's captive magnet supply insulates electromagnetic metering margins from lanthanide volatility. |
| Performance Contracting Expansion | Energy-as-a-service arrangements transfer operational risk and accelerate procurement in India's textile belt. |
| IEC 62443 Certification Investment | Cybersecurity compliance extends product validation cycles but locks out unqualified competitors in US petrochemical deployments. |
Research Methodology
Cross-validation between primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and energy management office directors and secondary sources including SEC filings, customs trade data, EIA industrial consumption reports, and EU ETS verification records anchors the qualitative findings. Bottom-up telemetry deployment counts and top-down industrial electricity consumption estimates were reconciled across the analysis window.
Calibration against historical efficiency investment cycles and regulatory compliance deadlines shaped the projection framework. Segmentation dimensions span hardware-software-service packaging, IoT-AI-cloud-analytics technology tiers, and manufacturing-oil & gas-utilities end-use verticals. CAGRs were derived from elasticity modeling of regulatory penalty structures and green financing eligibility rules.
Stress conditions across semiconductor supply continuity, copper price bands, and EU carbon border adjustment implementation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology cost trajectories and regulatory enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
Utility Analytics and Energy Analytics Market
Energy Analytics and Software
India Big Data Analytics in Energy Market
Energy Analytics and Software
Solar Analyzer Market
Energy Analytics and Software
China Big Data Analytics in Energy Market
Energy Analytics and Software
Power Monitoring and Control Software Market
Energy Analytics and Software
US Big Data Analytics in Energy Market
Energy Analytics and Software
Automated Power Generation Dispatch Software Market
Energy Analytics and Software
Energy Intelligence Solutions Market
Energy Analytics and Software
Big Data Analytics in Energy Market
Energy Analytics and Software
Big Data Analytics in Power Sector Market
Energy Analytics and Software
Energy and Utilities Analytics Market
Energy Analytics and Software
Netherlands Big Data Analytics in Energy Market
Energy Analytics and Software
Building Energy Simulation Software Market
Energy Analytics and Software
Canada Big Data Analytics in Energy Market
Energy Analytics and Software
Big Data in Oil and Gas Market
Energy Analytics and Software
Carbon and Energy Software Market