
 Kidney Fibrosis Treatment Market | 2026-2036
Kidney Fibrosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Kidney Fibrosis Treatment Market Analysis
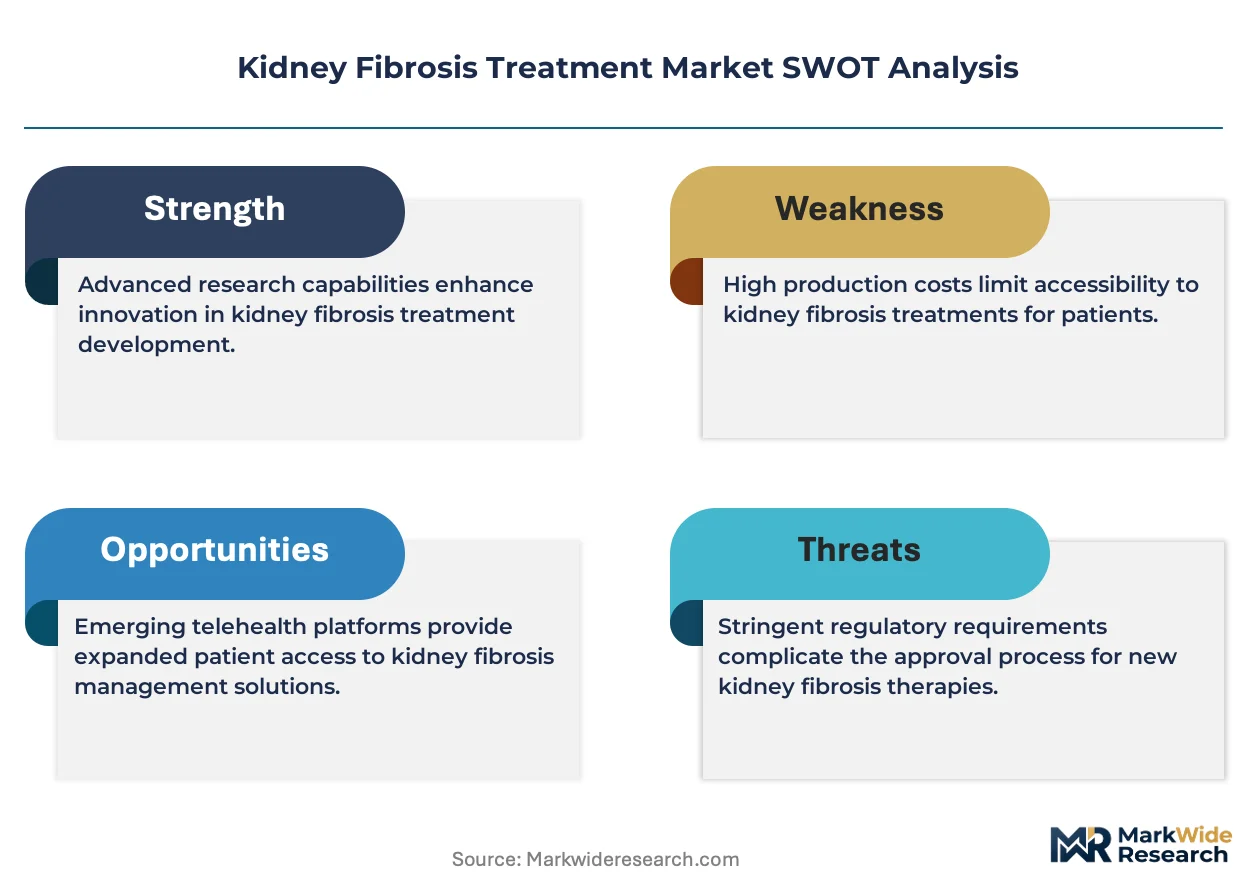
Project finance for late-stage renal drug development is narrowing the field of viable competitors to those with dedicated biotech venture backing or pharmaceutical cash reserves. Sanofi leverages its global nephrology franchise to sustain Phase III programs across multiple fibrosis targets. AstraZeneca anchors its position through deep investment in chronic kidney disease biomarker discovery. Vertex Pharmaceuticals differentiates by applying its cystic fibrosis protein-folding expertise to renal scarring mechanisms.
Kidney fibrosis treatment encompasses pharmacological interventions targeting the pathological accumulation of extracellular matrix proteins within renal interstitium, primarily involving TGF-beta pathway modulation and collagen synthesis inhibition to preserve glomerular filtration rate. These therapies serve the clinical imperative of halting or reversing progressive renal function decline before dialysis dependency. Biologics command premium positioning due to manufacturing complexity and targeted mechanism specificity, while small molecules retain broader accessibility through oral delivery routes. Among applications, chronic kidney disease represents the deepest patient pool, though acute kidney injury generates faster therapy initiation timelines in intensive care settings.
FDA accelerated approval designations and EMA orphan drug incentives are compressing development timelines for novel renal fibrosis candidates, while Japan's PMDA Sakigake designation attracts early filings from Western sponsors seeking Asian market access. REACH compliance in Europe and evolving EPA pharmaceutical discharge standards in the United States add manufacturing cost layers that favor scaled producers. Stakeholders must monitor biomarker-validated surrogate endpoints as regulatory acceptance of these measures will determine which development programs advance without decade-long mortality trials.
Market Dynamics
FDA accelerated approval pathways for rare renal diseases are compressing clinical trial timelines and attracting venture capital toward late-stage fibrosis programs, while biomarker-validated surrogate endpoints reshape which development candidates advance without mortality trials.
Growth Catalysts
- EMA Orphan Drug Incentives:European regulatory frameworks grant market exclusivity and fee reductions for rare renal indications, accelerating sponsor filings from Western developers seeking pediatric extensions.
- Japan's PMDA Sakigake Designation:Priority review status for innovative renal therapies draws early regulatory submissions and enables faster Asian market access for antifibrotic candidates.
- Hospital-Based Nephrology Expansion:Specialized interstitial fibrosis research consortia in the United States, Germany, and Japan are expanding adoption of targeted antifibrotic therapies within academic medical centers.
Market Restraints
- Biologics Manufacturing Complexity:Cell culture and purification requirements for TGF-beta pathway modulators create supply bottlenecks that favor scaled producers with dedicated biotech venture backing.
- REACH Compliance Burden:European chemical registration mandates add manufacturing cost layers for small-molecule collagen synthesis inhibitors, compressing margins for mid-tier developers.
- Biomarker Validation Uncertainty:Regulatory acceptance of surrogate endpoints remains inconsistent across FDA, EMA, and PMDA, forcing sponsors to maintain parallel trial designs.
Strategic Opportunities
- Acute Kidney Injury Protocols:Intensive care settings generate faster therapy initiation timelines than chronic disease management, creating a channel for rapid antifibrotic deployment.
- Protein-Folding Expertise Transfer:Cystic fibrosis research platforms are converging with renal scarring mechanisms, opening mechanistic white space for novel collagen synthesis approaches.
- EPA Pharmaceutical Discharge Standards:Evolving environmental compliance requirements in the United States favor scaled manufacturers with integrated waste management infrastructure.
Industry Challenges
- Chronic Kidney Disease Biomarker Discovery:Deep investment requirements for GFR preservation endpoints strain R&D budgets and extend preclinical timelines.
- Interstitial Fibrosis Research Talent Scarcity:Specialized expertise in extracellular matrix protein accumulation sits concentrated within limited academic and industry clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kidney Fibrosis Treatment Market |
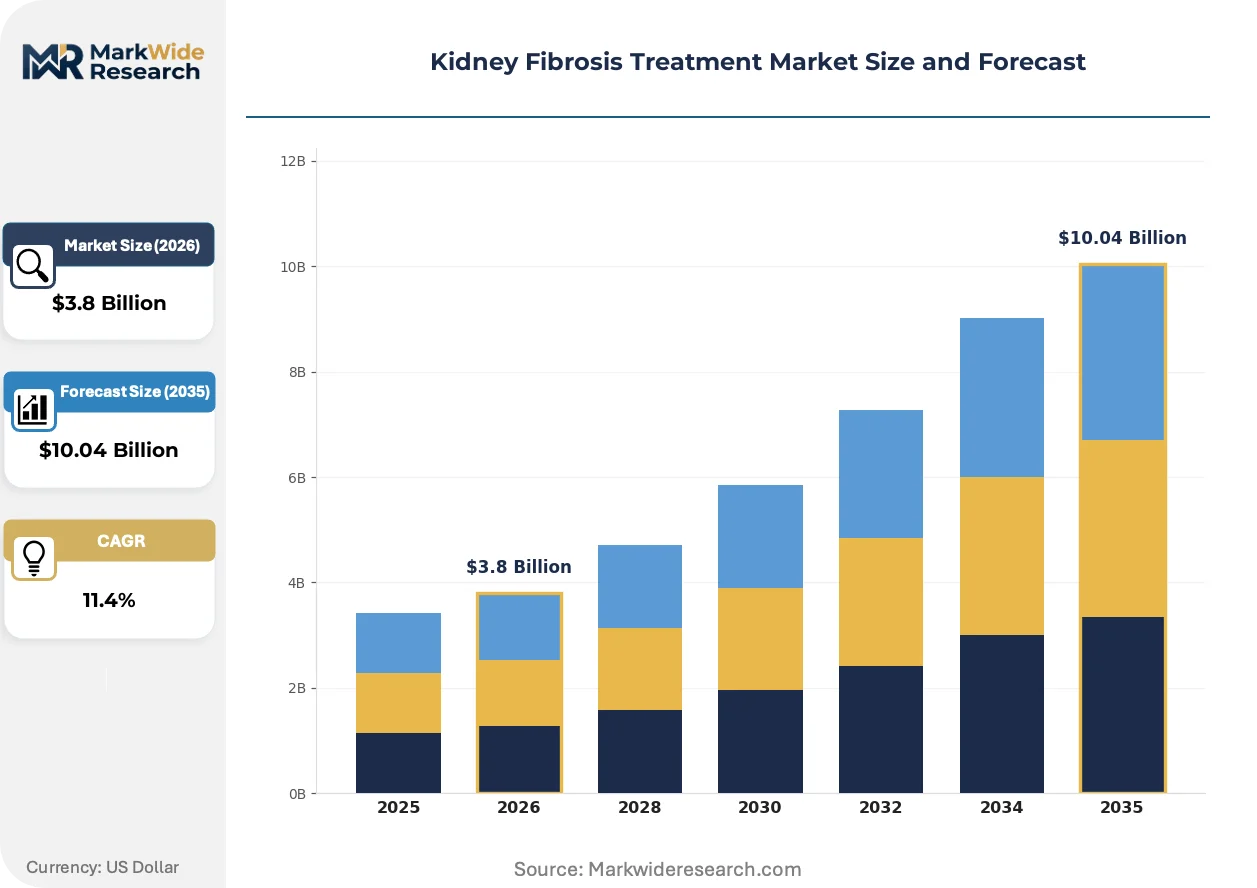
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antifibrotic Agents, Immunosuppressants, Small Molecules, Biologics Application: Chronic Kidney Disease, Acute Kidney Injury, Polycystic Kidney Disease, End-Stage Renal Disease End User: Hospitals, Specialty Clinics, Home Care Settings, Research Institutions Delivery Mode: Oral, Intravenous, Subcutaneous, Transdermal |
| Companies Covered | Sanofi, Insilico Medicine, AstraZeneca, Vera Therapeutics, Biogen, Amgen, Vertex Pharmaceuticals, Otsuka Pharmaceutical, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kidney Fibrosis Treatment Market Emerging Trajectories
Renal fibrosis therapeutics are pivoting toward mechanism-specific platforms that bridge biologic precision with small-molecule accessibility, while regulatory frameworks increasingly reward biomarker-driven development strategies.
Antifibrotic drug platforms are hybridizing TGF-beta pathway modulation with collagen synthesis inhibition to preserve glomerular filtration rate across progressive renal decline. Hospital-based nephrology departments are adopting these combination approaches at accelerating pace for chronic kidney disease management. This convergence is compressing the traditional divide between biologic and small-molecule development tracks.
REACH compliance mandates in Europe are forcing reformulation of small-molecule candidates to meet pharmaceutical discharge standards. Manufacturing sites in Germany and Switzerland are retrofitting purification infrastructure to satisfy ECHA registration requirements. Collagen synthesis inhibitors face the steepest compliance cost escalation, shifting competitive advantage toward integrated producers.
Procurement patterns in United States academic medical centers are unbundling after-sales biomarker testing from drug supply contracts. Hospital nephrology departments now source TGF-beta pathway diagnostics through separate laboratory channels, fragmenting vendor relationships. This disintermediation is most visible in tertiary care networks with dedicated interstitial fibrosis research programs.
Kidney Fibrosis Treatment Market Segmentation
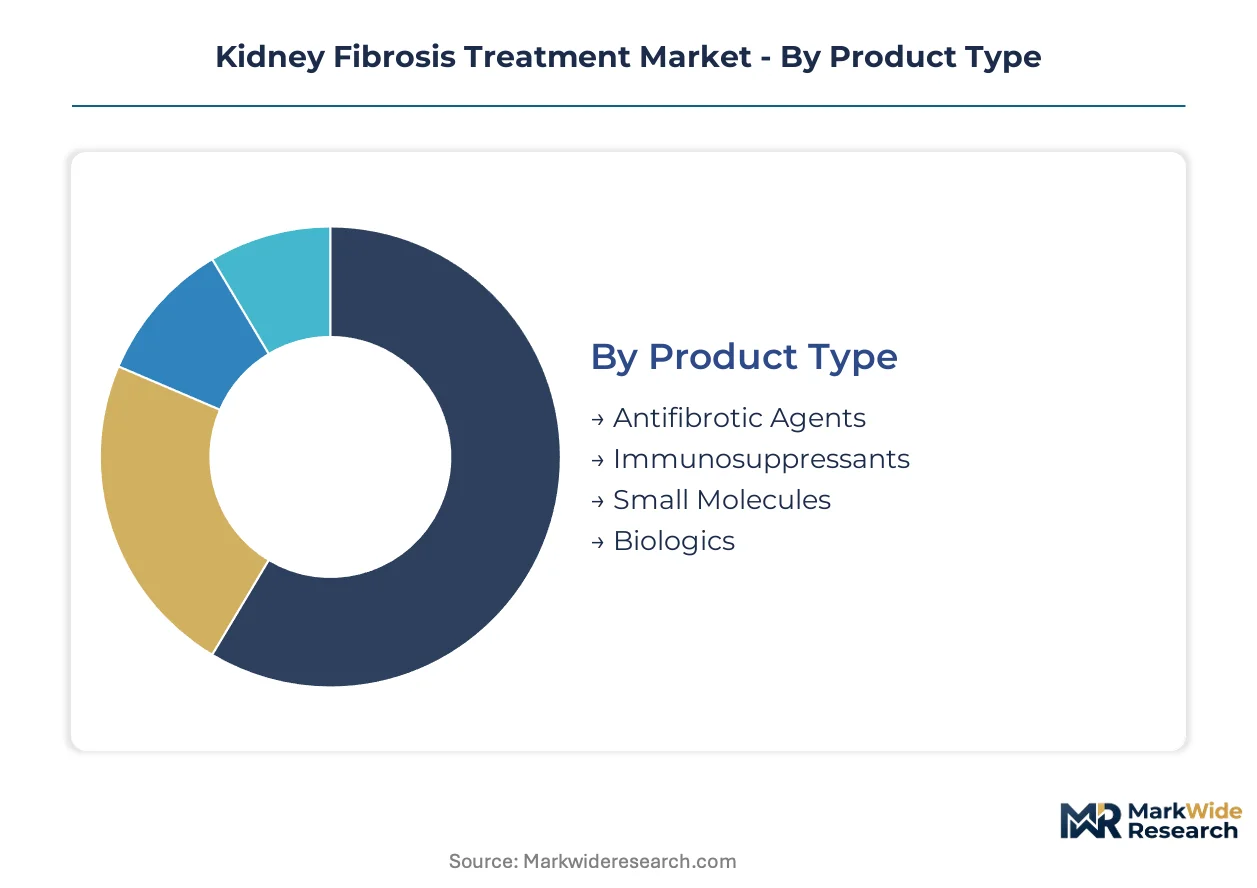
Segmentation in the kidney fibrosis treatment market reveals divergent commercial rhythms across therapeutic modalities. Cycle times vary dramatically between chronic disease management protocols and acute intervention settings, reshaping inventory and partnership strategies for developers.
Product Type:
Antifibrotic agents and biologics command extended development timelines measured in years, while small molecules compress regulatory pathways through established oral delivery frameworks.
- Antifibrotic Agents:These therapeutics directly target TGF-beta pathway modulation and collagen synthesis inhibition to preserve glomerular filtration rate. Demand concentrates in United States academic medical centers with dedicated interstitial fibrosis research programs, driven by hospital-based nephrology department expansion and accelerated FDA approval pathways for rare renal diseases.
- Biologics:Manufactured through cell culture and purification processes, these protein-based therapies offer targeted mechanism specificity against extracellular matrix accumulation. Procurement clusters in Germany and Japan where specialized research consortia justify premium positioning despite manufacturing complexity bottlenecks that favor scaled producers.
- Immunosuppressants:Broad immunomodulatory agents address inflammatory drivers of renal scarring through corticosteroid and calcineurin inhibitor mechanisms.
- Small Molecules:Oral delivery routes enable broader accessibility across outpatient settings, though REACH compliance in Europe adds manufacturing cost layers for collagen synthesis inhibitors.
Small molecules anchor the volume base while biologics gain share at the steepest rate.
Application:
Cost tier differentiation separates chronic maintenance therapies from premium-priced acute interventions, with reimbursement intensity varying across disease progression stages.
- Chronic Kidney Disease:The deepest patient pool requires sustained pharmacological intervention to halt progressive renal function decline before dialysis dependency. United States demand concentrates in Medicare-reimbursed nephrology practices, constrained by lengthy biomarker validation timelines for GFR preservation endpoints.
- Acute Kidney Injury:Intensive care settings generate faster therapy initiation timelines than chronic disease management, creating premium pricing power for rapid antifibrotic deployment. Japan's PMDA Sakigake designation accelerates regulatory submissions for innovative candidates targeting this indication.
- Polycystic Kidney Disease:Orphan disease status unlocks EMA fee reductions and market exclusivity incentives for targeted cyst growth inhibitors.
- End-Stage Renal Disease:Pre-dialysis intervention window narrows clinical utility, limiting addressable population to transplant-eligible candidates.
Chronic kidney disease anchors the volume base while acute kidney injury commands the steepest expansion trajectory.
End User:
Customer type fragmentation separates institutional procurement from emerging direct-to-patient channels, with research institutions operating on grant-funded cycles distinct from commercial reimbursement.
- Hospitals:Academic medical centers in the United States, Germany, and Japan dominate adoption of targeted antifibrotic therapies through specialized interstitial fibrosis research consortia. Tertiary care networks are unbundling biomarker diagnostics from drug supply contracts, fragmenting vendor relationships.
- Specialty Clinics:Focused nephrology practices concentrate high-complexity case management and clinical trial recruitment for novel candidates.
- Home Care Settings:Oral small-molecule accessibility enables outpatient administration, though monitoring infrastructure gaps limit penetration.
- Research Institutions:Grant-funded academic laboratories drive preclinical biomarker discovery and mechanism validation for extracellular matrix protein accumulation.
Hospitals anchor the volume base while specialty clinics climb the fastest on procedure migration trends.
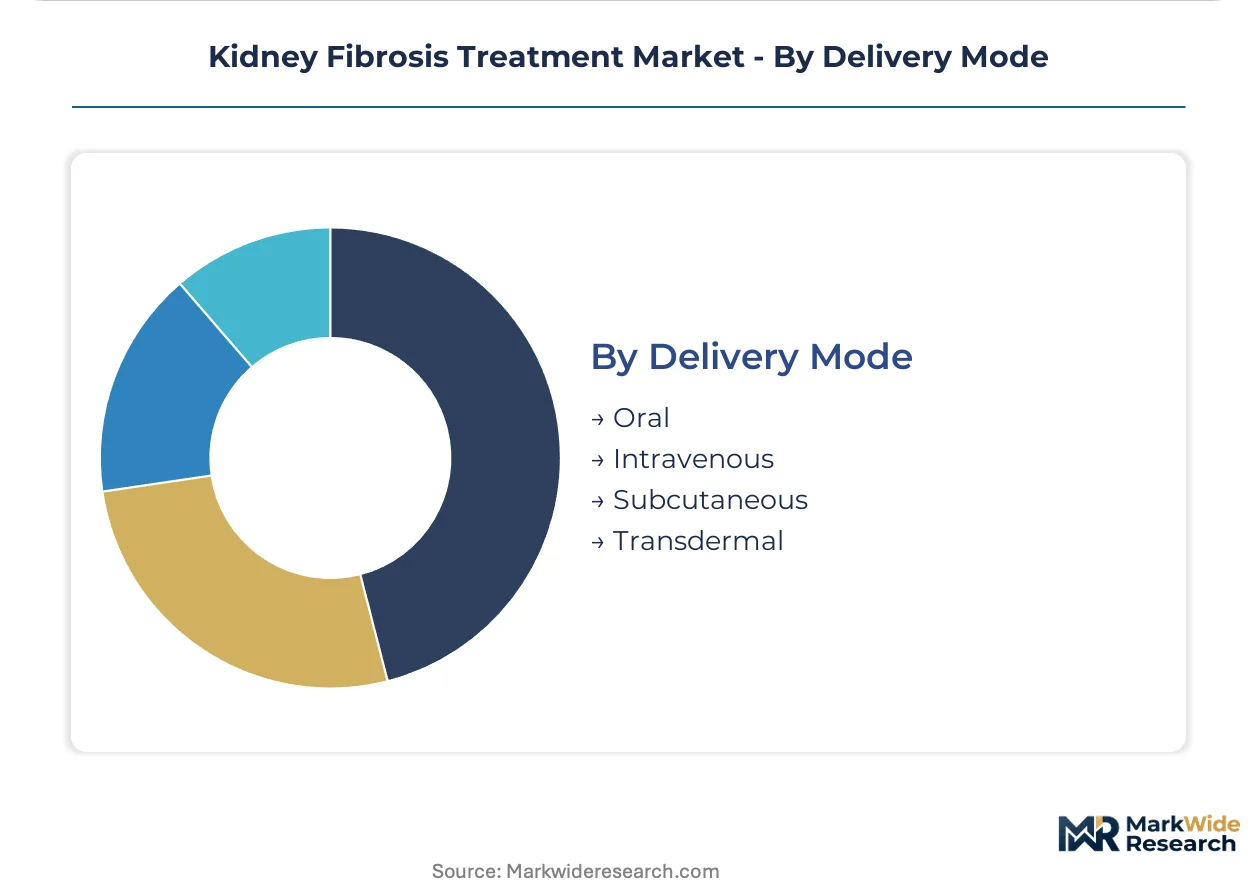
Delivery Mode:
Supply concentration favors parenteral manufacturing infrastructure in Germany and Switzerland, while oral formulation expertise distributes more broadly across mid-tier developers.
- Intravenous:Hospital-administered biologics require cold-chain infrastructure and infusion center capacity concentrated in major metropolitan academic medical centers. EMA orphan drug incentives accelerate sponsor filings for IV-delivered rare disease candidates.
- Oral:Small-molecule accessibility enables outpatient chronic disease management, though EPA pharmaceutical discharge standards in the United States favor scaled manufacturers with integrated waste management infrastructure.
- Subcutaneous:Self-administration potential bridges institutional and home settings, requiring patient training programs.
- Transdermal:Limited penetration due to molecular weight constraints on antifibrotic agent permeation.
Oral delivery anchors the volume base while intravenous administration retains the steepest pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and specialized nephrology research consortia concentrate procurement of antifibrotic therapies across four major national markets. Hospital-based adoption patterns vary significantly by reimbursement structure and regulatory acceleration pathways.
United States
Medicare-reimbursed nephrology practices in academic medical centers drive demand for TGF-beta pathway modulators. FDA accelerated approval pathways for rare renal diseases compress clinical trial timelines and attract venture capital toward late-stage fibrosis programs. The Boston-Cambridge cluster anchors specialized interstitial fibrosis research consortia with dedicated biomarker validation infrastructure.
Germany
University hospitals in Baden-Württemberg and Bavaria expand adoption of targeted antifibrotic therapies through integrated nephrology departments. REACH compliance mandates from ECHA force reformulation of small-molecule collagen synthesis inhibitors, retrofitting manufacturing sites in Switzerland and Germany with upgraded purification infrastructure. The Rhine-Ruhr metropolitan region concentrates biologics manufacturing capacity serving European hospital networks.
Japan
PMDA Sakigake designation attracts early regulatory submissions from Western sponsors seeking priority review status for innovative renal therapies. Intensive care settings in Tokyo and Osaka academic hospitals generate faster therapy initiation timelines for acute kidney injury protocols. The Kanto region hosts specialized research consortia bridging cystic fibrosis protein-folding expertise with renal scarring mechanisms.
United Kingdom
NHS England's specialized commissioning frameworks channel funding toward rare renal disease treatments through designated tertiary nephrology centers. EMA orphan drug incentives accelerate sponsor filings from developers seeking pediatric extensions and market exclusivity. The Oxford-Cambridge-London golden triangle concentrates extracellular matrix protein accumulation research talent within limited academic clusters.
Switzerland
Swissmedic regulatory frameworks align with EMA standards while offering streamlined pathways for biologics manufacturing site approvals. Basel and Zurich host scaled producers with integrated waste management infrastructure satisfying evolving pharmaceutical discharge standards. The country's precision medicine ecosystem supports biomarker-validated surrogate endpoint development for GFR preservation trials.
Kidney Fibrosis Treatment Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented vendor relationships in hospital procurement. Large pharmaceutical conglomerates with dedicated nephrology franchises sustain Phase III programs through global cash reserves, while mid-tier biotech ventures concentrate on single-mechanism candidates. Two archetypes dominate: diversified giants leveraging cross-therapeutic area expertise, and focused developers transferring protein-folding platforms from adjacent disease areas. Competitive moves center on strategic partnerships for biomarker discovery and geographic expansion through regulatory designation stacking.
Within the diversified pharmaceutical tier, Sanofi and AstraZeneca exemplify channel-controlling players with established global nephrology franchises. Sanofi leverages its hospital network relationships to sustain multiple late-stage fibrosis targets simultaneously. AstraZeneca anchors its position through deep investment in chronic kidney disease biomarker discovery infrastructure. Vertex Pharmaceuticals occupies a distinct archetype as a focused developer applying cystic fibrosis protein-folding expertise to renal scarring mechanisms, representing the platform-transfer strategy visible among mid-cap specialists.
| Leading Market Players |
|---|
| Sanofi |
| Insilico Medicine |
| AstraZeneca |
| Vera Therapeutics |
| Biogen |
| Amgen |
| Vertex Pharmaceuticals |
| Otsuka Pharmaceutical |
| Novartis |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Swiss biologics manufacturing facilities is compressing contract manufacturing margins and pushing sponsors toward fixed-price development agreements with indexation clauses tied to EMA approval timelines. This utilization slack simultaneously weakens supplier bargaining power and intensifies price competition for late-stage renal fibrosis candidates.
Pricing Analysis
Cost-plus contracts with CPI indexation dominate biologics development partnerships, particularly for TGF-beta pathway modulators where manufacturing complexity justifies pass-through arrangements. Price differentiation rests on GMP certification tier and after-sales biomarker testing bundling, with premium tiers capturing academic medical centers in Germany and Japan. Pricing pressure stems from REACH compliance cost escalation for small-molecule collagen synthesis inhibitors, compressing margins for mid-tier developers. Outpatient nephrology practices exhibit highest price sensitivity due to Medicare reimbursement constraints, while intensive care protocols in tertiary hospitals tolerate premium positioning for rapid therapy initiation.
Supply Chain Analysis
Upstream cell culture media and single-use bioreactor components draw from concentrated suppliers in Germany, Switzerland, and the United States, creating feedstock dependencies for TGF-beta pathway biologics. Raw material sourcing rests on recombinant protein production, chromatography resins, and pharmaceutical-grade collagen synthesis precursors. Single-source vulnerability permeates chromatography resin supply, with purification infrastructure retrofitting lagging ECHA registration deadlines. Distribution runs through hospital-based nephrology departments and specialty pharmacy channels, with academic medical centers in the United States, Germany, and Japan anchoring procurement volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biomarker-validated surrogate endpoint services are expanding faster than antifibrotic drug supply, creating a service-attach opportunity where diagnostic recurring revenue outpaces hardware margins for integrated platform vendors.
For Market Incumbents: Pre-empt biosimilar pressure by locking exclusive biomarker testing partnerships with United States academic medical centers before patent cliffs on first-generation TGF-beta modulators. Deepen backward integration into collagen synthesis inhibitor raw material production to offset REACH compliance cost escalation and defend margin position against European mid-tier developers. For New Entrants and Emerging Players: Build out acute kidney injury protocol presence in Japanese intensive care settings, where PMDA Sakigake designation accelerates regulatory timelines faster than chronic disease entry paths. Target hospital nephrology departments in Germany's Baden-Württemberg region through EMA orphan drug incentive positioning, leveraging faster therapy initiation timelines to establish pricing power before chronic disease market saturation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biologics manufacturing infrastructure as ECHA purification retrofit requirements compound cell culture complexity. Long-term viability favors platform-transfer specialists with cystic fibrosis protein-folding expertise applicable to renal scarring mechanisms. Watch for FDA accelerated approval pathway expansion for rare renal diseases as the signal indicating viable exit windows for late-stage development programs.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Validation Partnership | Hospital nephrology departments unbundle diagnostics from drug contracts, fragmenting vendor relationships. |
| REACH Compliance Retrofit | Manufacturing sites in Germany and Switzerland upgrade purification infrastructure to satisfy ECHA registration mandates. |
| PMDA Sakigake Filing | Priority review status attracts Western sponsors seeking faster Asian market access for antifibrotic candidates. |
| Protein-Folding Platform Transfer | Cystic fibrosis research expertise converges with renal scarring mechanisms, opening mechanistic white space. |
| Hospital System Partnership | Tertiary care networks concentrate procurement of targeted antifibrotic therapies through specialized research consortia. |
Methodological Framework
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions underlying demand projections. Primary interview insights combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored market size estimation across the analysis window.
Demand-supply-balance framing structured the analytical approach, with segmentation dimensions spanning therapeutic modality, disease indication, end-user setting, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to biomarker-validated surrogate endpoint adoption timelines and hospital-based nephrology department expansion trajectories. Forecast inputs incorporated FDA accelerated approval pathway utilization rates and EMA orphan drug incentive filing patterns throughout the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive moves by platform-transfer specialists from adjacent disease areas would shift outcomes beyond modeled ranges. Material shifts in regulatory acceptance of surrogate endpoints or REACH compliance cost trajectories would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Glomerulonephritis Treatment Market
Nephrology
US Dialysis Market
Nephrology
Global Nephroblastoma Treatment Market
Nephrology
Aldosterone-Renin Screening Market
Nephrology
Hemodialysis Vascular Graft Market
Nephrology
Renal Artery Embolization Market
Nephrology
Proteinuria Treatment Market
Nephrology
Hollow Fiber Dialyzers Market
Nephrology
US Hemodialysis and Peritoneal Dialysis Market
Nephrology
Global Hemodialysis Market
Nephrology
Membranous Nephropathy Treatment Market
Nephrology
Dialysis Centers Market
Nephrology
Renal Anemia Treatment Market
Nephrology
Hemodialysis Services Market
Nephrology
Blood Dialyzer Market
Nephrology
Ketoanalogue for Kidney Disease Market