
 Oman Third-Party Logistics (3PL) Market | 2026-2036
Oman Third-Party Logistics (3PL) Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Third-Party Logistics (3PL) Market Analytics
The Oman 3PL market is shifting toward differentiated service tiers as oil-and-gas contract logistics stagnates while e-commerce fulfillment commands premium pricing for speed and visibility. DHL Supply Chain leverages its pharmaceutical cold-chain certification to anchor high-margin healthcare contracts in Muscat. Asyad Express competes through its exclusive rail-port integration at Sohar, giving it captive last-mile access to northern industrial zones. Aramex specializes in cross-border e-commerce clearance, exploiting its customs brokerage density between Oman and the UAE.
Third-party logistics encompasses outsourced supply chain execution where providers manage transportation, warehousing, and inventory coordination under service-level agreements specifying on-time delivery thresholds, temperature compliance, and real-time tracking granularity. These operations reduce capital lockup in owned distribution assets while converting fixed logistics costs to variable spend aligned with shipment volume. Transportation and warehousing together form the structural core of Oman's 3PL revenue pool, though inventory management is growing fastest as manufacturers adopt vendor-managed inventory to buffer against Gulf supply volatility. E-commerce end users are pulling automation and data analytics adoption ahead of traditional retail, creating a technology bifurcation where cloud-based visibility platforms concentrate among digital-native customers while legacy manufacturing clients remain on scheduled delivery models.
Oman's logistics sector operates under the Ministry of Transport, Communications and Information Technology's national strategy, with customs procedures governed by the Royal Oman Police Directorate General of Customs and free zone incentives administered by the Public Authority for Special Economic Zones and Free Zones. These frameworks shape market access through bonded warehouse licensing, foreign ownership allowances in logistics services, and tariff structures at Sohar and Salalah ports. Stakeholders must monitor how Oman's accession to WTO trade facilitation commitments and evolving GCC customs union rules reshape cross-border clearance economics and warehouse location decisions.
Market Dynamics
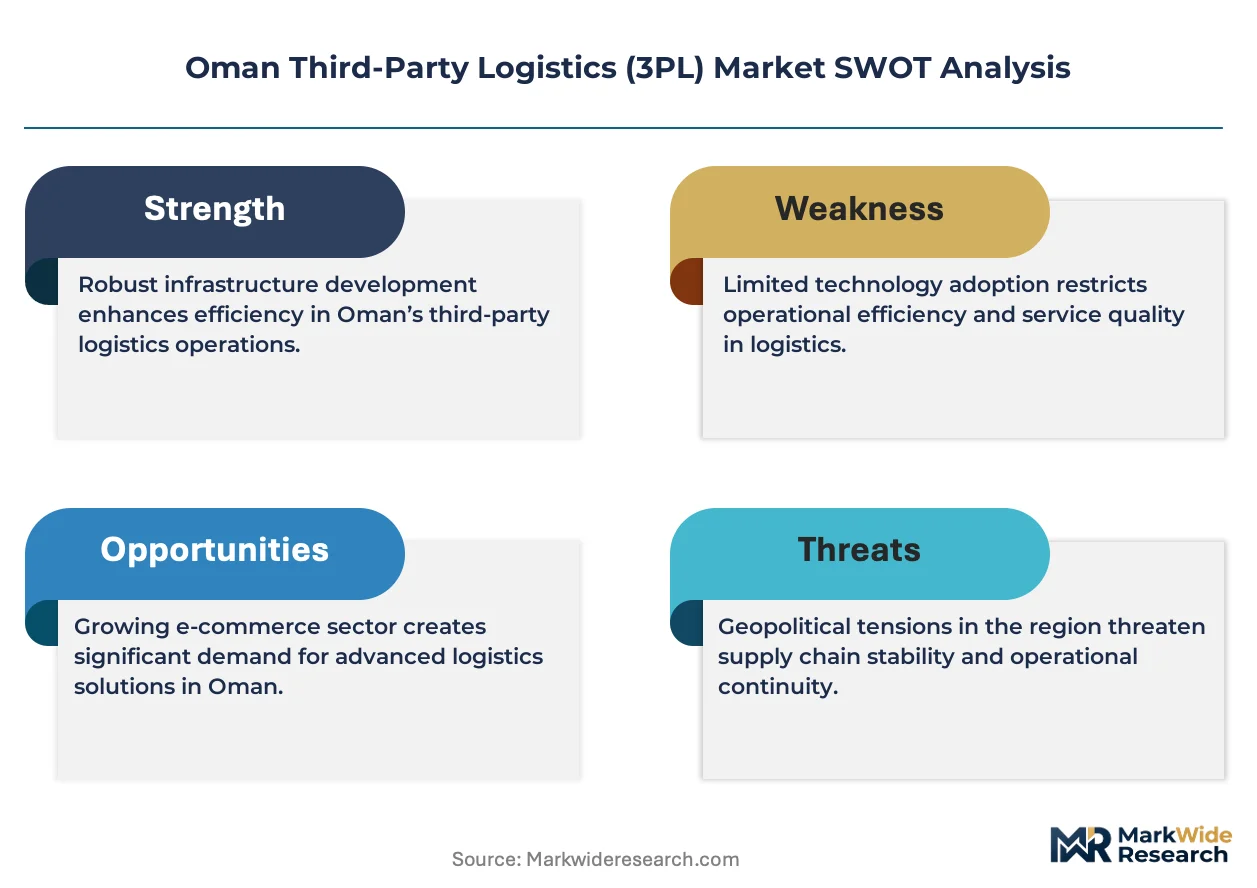
E-commerce fulfillment velocity requirements are compressing delivery windows across Oman's 3PL sector, forcing warehouse automation investments and real-time inventory visibility upgrades that favor capital-heavy operators over traditional freight brokers.
Growth Catalysts
- Duqm Port modernization:The Special Economic Zone Authority at Duqm is expanding container throughput capacity, creating captive demand for bonded warehousing and cross-docking services along the Arabian Sea corridor.
- Vendor-managed inventory adoption:Industrial manufacturers in Sohar's aluminum and steel clusters are outsourcing stockholding to 3PLs to buffer against GCC supply volatility, converting fixed warehouse costs to variable logistics spend.
- Royal Oman Police customs digitization:The Risk-Based Selectivity System is accelerating clearance times at land borders with the UAE, reducing dwell costs and enabling just-in-time replenishment models for retail distributors.
Market Restraints
- Labor cost inflation:Warehouse operative wages in Muscat industrial zones have risen sharply, eroding margins for asset-heavy 3PLs with large dedicated workforces.
- Port capacity concentration:Overreliance on Sohar and Salalah container terminals creates chokepoint vulnerability during peak import seasons, particularly for automotive parts distributors.
- Land scarcity near demand centers:Limited zoned logistics plots within 50 kilometers of Muscat's retail clusters inflate facility rents and constrain last-mile network expansion.
Strategic Opportunities
- Al Dhahirah hinterland penetration:Underdeveloped cold-chain infrastructure between Ibri and the Saudi border offers first-mover advantage for temperature-controlled food distribution to emerging retail catchments.
- Green hydrogen logistics clusters:The Ministry of Energy and Minerals' hydrogen roadmap is mandating specialized handling protocols for ammonia and liquid hydrogen exports, creating premium certification requirements that filter out generalist competitors.
- Rail-integrated multimodal contracts:Asyad Rail's network expansion toward the UAE border enables 3PLs to bundle port-rail-truck services under single-source agreements, locking in industrial manufacturing accounts.
Industry Challenges
- Warehouse Management System integration:Legacy manufacturing clients in Rusayl Industrial Estate operate on ERP platforms that resist API connectivity with cloud-based 3PL visibility tools, forcing expensive middleware development.
- Pharmaceutical GDP certification timelines:Cold-chain operators seeking Ministry of Health distribution licenses face 12-18 month validation periods for temperature mapping and qualification protocols, delaying contract commencement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Third-Party Logistics (3PL) Market |
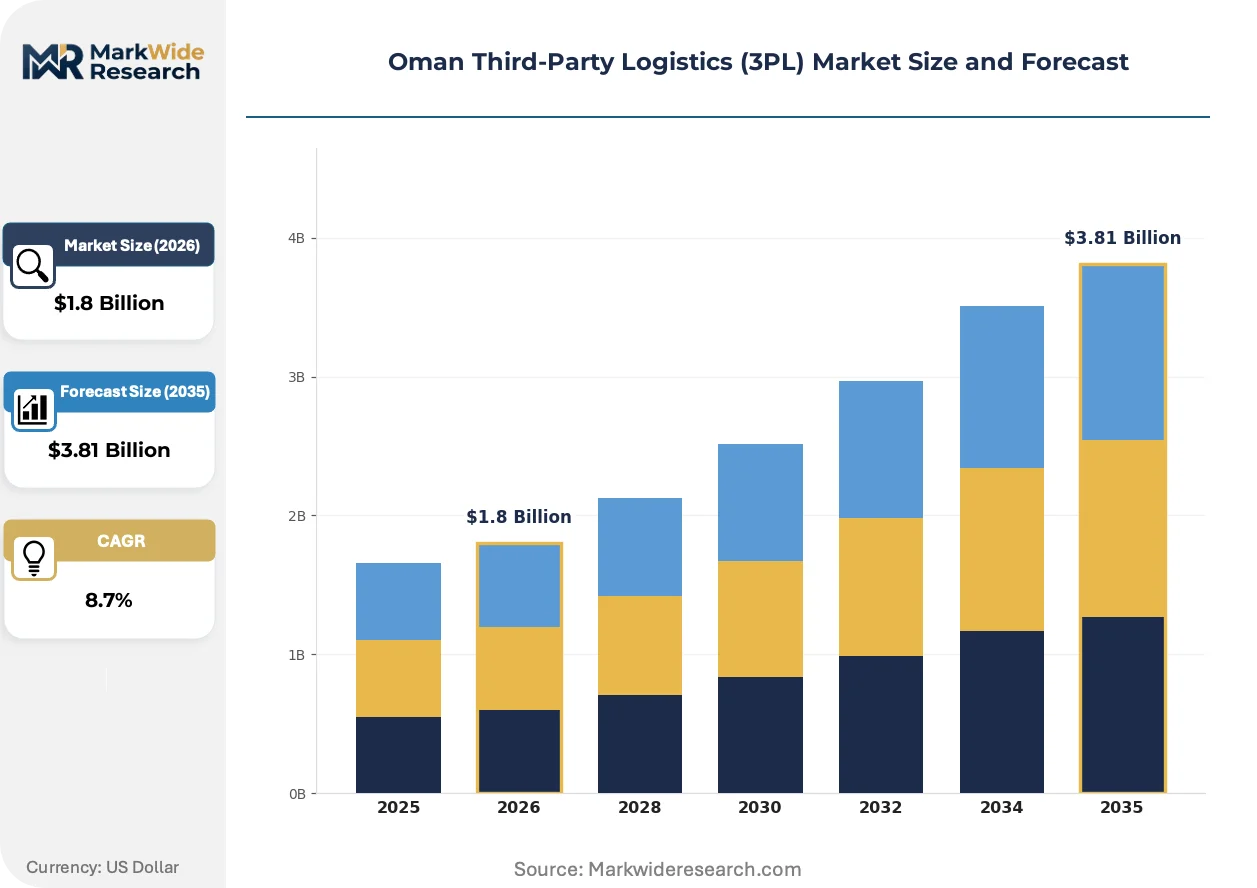
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Inventory Management End User: Retail, E-commerce, Automotive, Manufacturing Technology: Automation, IoT, Cloud Computing, Data Analytics Delivery Model: On-Demand, Scheduled, Dedicated, Shared |
| Companies Covered | CEVA Logistics, FedEx Oman, DHL Supply Chain, GAC, Asyad Express, Kuehne + Nagel, Aramex, Al Madina Logistics, DSV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Third-Party Logistics (3PL) Market Evolving Landscape
Digital-native freight platforms and automated warehouse robotics are compressing the technology gap between multinational 3PLs and local logistics providers, reshaping competitive bidding dynamics for e-commerce contracts.
Cloud-based Transportation Management Systems (TMS) with embedded AI load-optimization is unifying previously siloed freight procurement, route planning, and carrier settlement functions. Mid-sized Omani distributors serving hypermarket chains are adopting these platforms faster than industrial clients, consolidating spot-market trucking into contracted lane networks that reduce empty-backhaul ratios and compress working capital cycles.
The Ministry of Transport, Communications and Information Technology's national logistics strategy is mandating single-window customs data exchange between port authorities, free zone operators, and Royal Oman Police clearance systems. This interoperability requirement is accelerating API standardization across Sohar and Salalah terminals, forcing 3PLs to retire proprietary EDI formats and absorb compliance costs that favor scaled operators with dedicated IT integration teams.
Same-day delivery expectations from fashion and electronics e-commerce platforms are compressing order fulfillment windows from 24 hours to 4-6 hours in Greater Muscat. This velocity shift is displacing centralized distribution models with micro-fulfillment nodes in Al Mawaleh and Ghala industrial zones, where 3PLs lease smaller footprints closer to residential density and deploy autonomous mobile robots for piece-picking efficiency.
Oman Third-Party Logistics (3PL) Market Segmentation
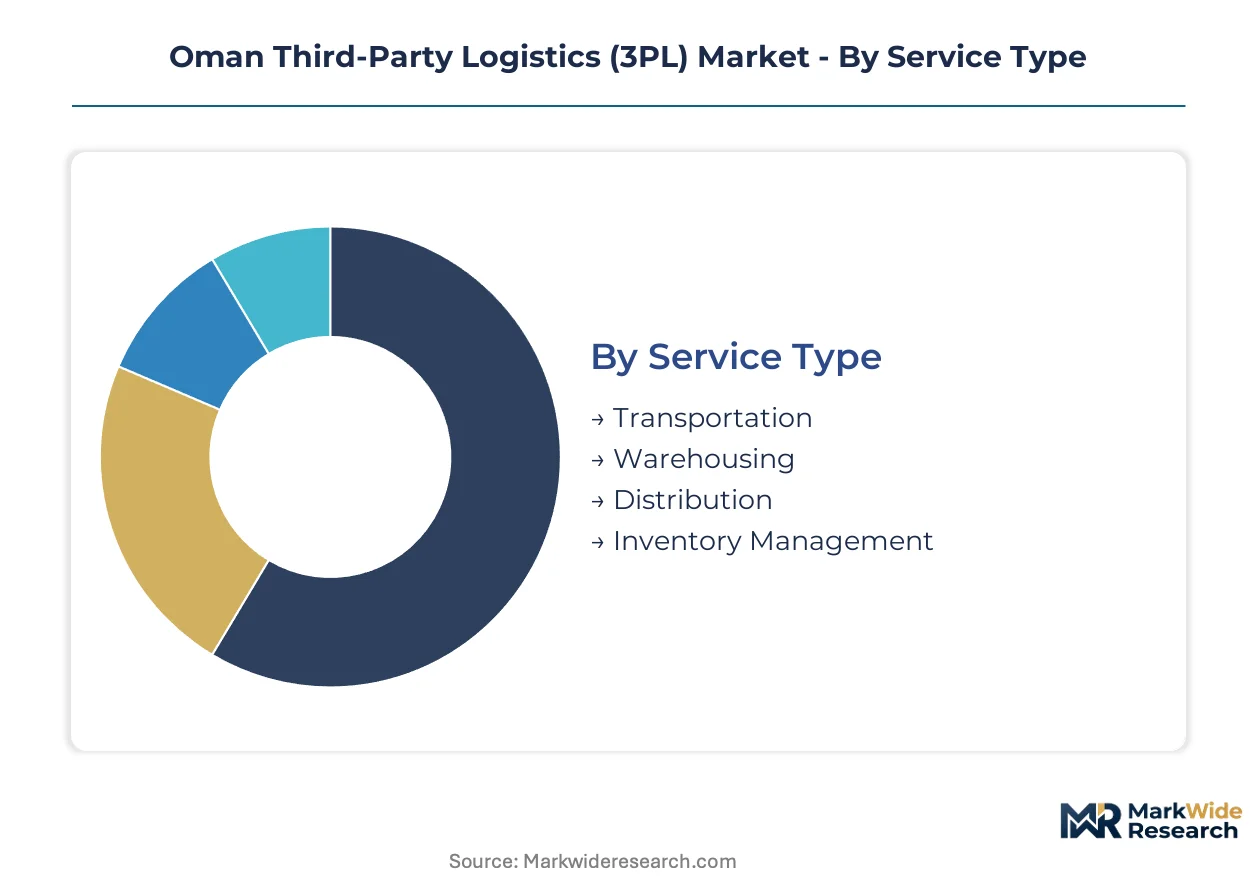
Service differentiation in Oman's 3PL sector hinges on certification depth and asset intensity, with bonded warehousing and cold-chain operations commanding premium positioning against commoditized freight brokerage. Segmentation reveals how e-commerce velocity requirements are splitting the market between capital-heavy integrated operators and technology-light traditional providers.
Service Type:
Certification burdens vary sharply across service lines, with pharmaceutical cold-chain and customs-bonded warehousing requiring Ministry of Health and Royal Oman Police approvals that general freight forwarding escapes.
- Transportation:Asset-heavy road and rail carriage dominates revenue concentration, particularly along the Sohar-Muscat- UAE corridor where Asyad Rail integration creates captive lane economics. Fleet ownership requirements and driver certification under the Ministry of Transport, Communications and Information Technology's commercial licensing regime filter out undercapitalized entrants.
- Warehousing:Bonded storage at Sohar and Salalah free zones demands Public Authority for Special Economic Zones and Free Zones operating permits, with temperature-controlled facilities facing additional Ministry of Health GDP validation. Land scarcity within 50 kilometers of Muscat retail clusters inflames facility rents and concentrates market share among established operators with legacy leaseholds.
- Distribution:Last-mile networks require municipal operating permits from Muscat Municipality and specialized vehicle classifications for oversized or hazardous cargo.
- Inventory Management:Vendor-managed inventory contracts impose ERP integration burdens that favor 3PLs with dedicated IT engineering teams capable of middleware development for legacy manufacturing clients.
Transportation sits at the top of the volume ranking, with Inventory Management climbing the fastest.
End User:
Customer-type concentration shapes margin structures, with automotive and manufacturing clients demanding scheduled reliability while retail and e-commerce compete on speed premiums.
- Retail:Hypermarket chains in Muscat's Al Mawaleh and Ghala zones drive scheduled replenishment contracts with fixed lane pricing, compressing margins through volume guarantees but offering payment security.
- E-commerce:Same-day delivery expectations from fashion and electronics platforms force micro-fulfillment node investments and autonomous mobile robot deployment, creating technology bifurcation against traditional retail clients.
- Automotive:Parts distributors cluster around Sohar port import channels, facing peak-season chokepoint vulnerability during container terminal congestion.
- Manufacturing:Sohar's aluminum and steel clusters outsource stockholding to buffer GCC supply volatility, converting fixed warehouse costs to variable logistics spend under multi-year service agreements.
Retail commands the largest contract volume, though E-commerce expands most rapidly.
Technology:
Technology adoption splits along customer digital maturity, with cloud-native platforms concentrating among e-commerce clients while legacy manufacturing remains on scheduled delivery models.
- Automation:Warehouse robotics and autonomous mobile robots deploy primarily in Greater Muscat micro-fulfillment nodes, where 4-6 hour delivery windows displace centralized distribution economics.
- IoT:Real-time temperature monitoring and geofencing capabilities anchor pharmaceutical cold-chain contracts requiring continuous Ministry of Health audit trails.
- Cloud Computing:Transportation Management Systems with embedded AI load-optimization consolidate freight procurement and route planning for mid-sized distributors serving hypermarket chains.
- Data Analytics:Predictive inventory positioning and demand forecasting tools gain traction among vendor-managed inventory accounts seeking to buffer Gulf supply volatility.
Cloud Computing leads technology spending, while Automation gains share fastest.
Delivery Model:
Delivery model selection reflects asset commitment levels, with dedicated fleets and shared networks representing opposing poles of capital intensity.
- On-Demand:Spot-market trucking procurement serves peak-season overflow and emergency replenishment, though empty-backhaul ratios erode economics without contracted lane consolidation.
- Scheduled:Fixed-route replenishment for retail and manufacturing clients offers volume predictability but limits pricing power during fuel cost spikes.
- Dedicated:Captive fleet and driver assignments for industrial manufacturing accounts lock in multi-year relationships through Asyad Rail port-rail-truck bundling.
- Shared:Multi-client consolidation models spread fixed costs across accounts, though service-level agreement complexity increases operational coordination overhead.
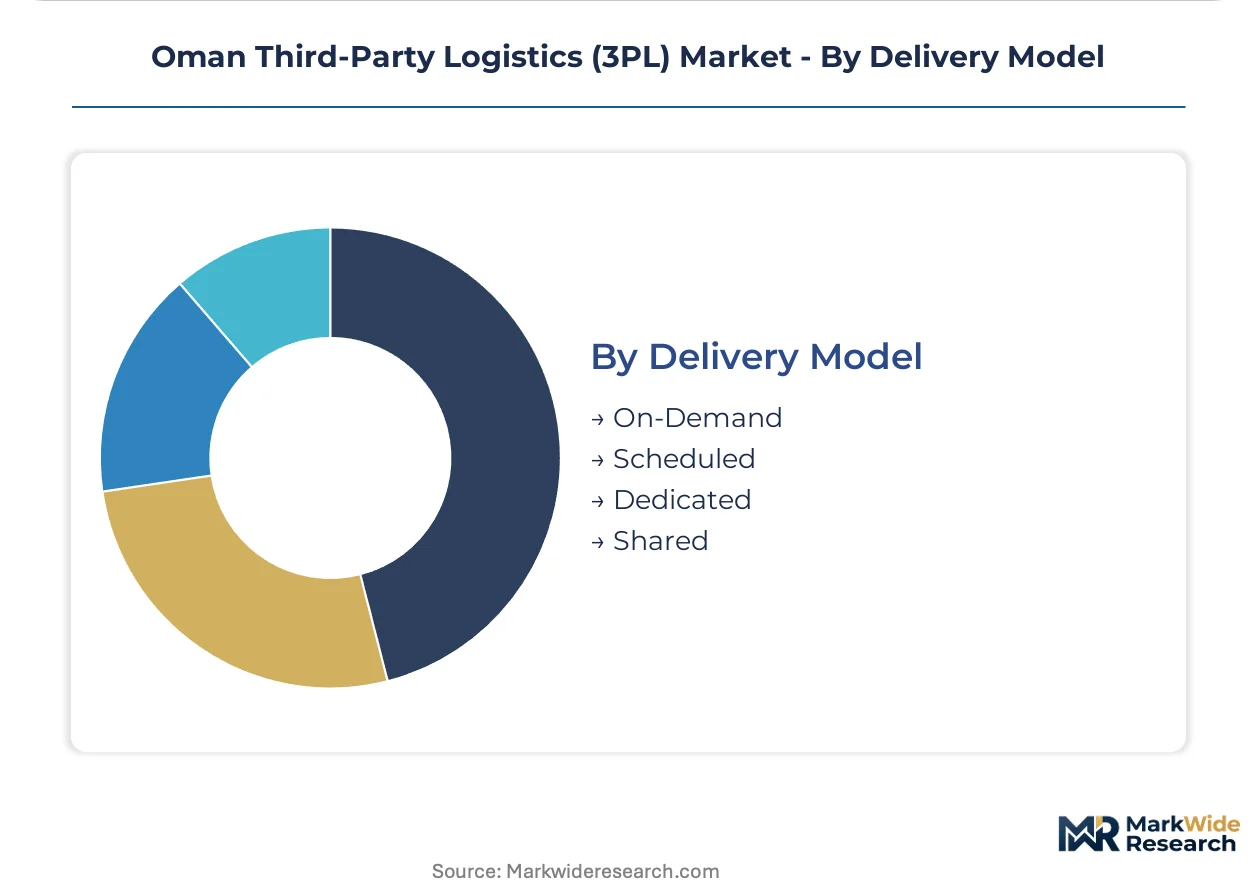
Scheduled delivery holds the volume lead, with On-Demand showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oman's logistics sector operates on a different scale than Saudi Arabia's integrated rail-port network, yet both Gulf states are redirecting capital toward multimodal corridors as oil-sector logistics stagnates.
Muscat Governorate
E-commerce fulfillment velocity concentrates demand in Al Mawaleh and Ghala industrial zones, where micro-fulfillment nodes compress delivery windows to 4-6 hours. The Ministry of Transport, Communications and Information Technology mandates single-window customs data exchange, forcing API standardization across port systems. Free zone clusters near Muscat International Airport anchor pharmaceutical cold-chain operations requiring Ministry of Health GDP certification.
Al Batinah North Governorate
Sohar Port's container throughput drives bonded warehousing demand along the industrial corridor to the UAE border. The Public Authority for Special Economic Zones and Free Zones administers operating permits for temperature-controlled facilities serving aluminum and steel clusters. Asyad Rail integration creates captive lane economics for manufacturers outsourcing stockholding to buffer GCC supply volatility.
Al Wusta Governorate
Duqm Special Economic Zone expansion generates demand for cross-docking services along the Arabian Sea corridor. The Special Economic Zone Authority at Duqm is expanding container throughput capacity, creating captive demand for logistics providers. Green hydrogen export protocols under the Ministry of Energy and Minerals roadmap mandate specialized handling for ammonia and liquid hydrogen.
Dhofar Governorate
Salalah Port's transshipment role connects East African trade lanes to Gulf distribution networks. Royal Oman Police customs digitization through the Risk-Based Selectivity System accelerates clearance times. The port's free zone concentrates automotive parts distributors facing peak-season chokepoint vulnerability during terminal congestion.
Oman Third-Party Logistics (3PL) Market Competitive Landscape
Top-tier vendors anchor integrated multimodal service bundles, while mid-tier freight brokers compete on spot-market lane pricing. Market structure reflects asset intensity bifurcation, with capital-heavy operators controlling bonded warehousing and cold-chain certification tiers. Strategic archetypes include rail-port integrators, pharmaceutical cold-chain specialists, and cross-border customs brokers. Dominant competitive moves encompass warehouse automation investments and API standardization for single-window customs compliance.
Within the integrated logistics tier, DHL Supply Chain represents pharmaceutical cold-chain certification depth, while Asyad Express exemplifies rail-port captive lane economics at Sohar. Aramex occupies a position as cross-border e-commerce clearance specialist between Oman and UAE customs corridors. These three anchors illustrate how certification density and asset control separate premium service tiers from commoditized freight brokerage.
| Leading Market Players |
|---|
| CEVA Logistics |
| FedEx Oman |
| DHL Supply Chain |
| GAC |
| Asyad Express |
| Kuehne + Nagel |
| Aramex |
| Al Madina Logistics |
| DSV |
| Others |
Value Network & Pricing Analysis
Green hydrogen export protocols under the Ministry of Energy and Minerals roadmap gate qualified supply access for ammonia and liquid hydrogen logistics, filtering out generalist competitors and enabling premium-tier pricing for certified operators serving industrial energy corridors.
Pricing Analysis
Capacity additions in Duqm and Sohar are reshaping price floors for bonded warehousing and cold-chain services, compressing margins for asset-heavy operators while creating tiered pricing stratification across certification levels. Price differentiation rests on Ministry of Health GDP validation and Royal Oman Police bonded warehouse permits, with pharmaceutical cold-chain commanding substantial premiums over general freight brokerage. Pricing pressure stems from labor cost inflation in Muscat industrial zones, eroding margins for dedicated workforce operators. E-commerce platforms exhibit acute price sensitivity for last-mile velocity, while industrial manufacturing clients prioritize reliability over cost.
Supply Chain Analysis
Dual-sourcing requirements from automotive and pharmaceutical clients mandate multi-supplier qualification across bonded warehousing and temperature-controlled distribution, preventing single-source dependency in port-centric logistics clusters. Geographic supply concentration draws from UAE cross-border corridors, Saudi hinterland networks, and Indian Ocean transshipment lanes through Salalah. Raw material dependencies center on container handling equipment, refrigeration units, and warehouse automation hardware. Supply chain risk manifests in port capacity concentration at Sohar and Salalah terminals during peak import seasons. Distribution runs through multimodal corridors integrating Asyad Rail with port and free zone infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oman's 3PL sector represents a late-cycle quality story where e-commerce fulfillment velocity requirements pull investment toward automation and real-time visibility platforms, rewarding operators with capital depth and certification density.
For Market Incumbents: Anchor defensive positioning through exclusive rail-port integration agreements at Sohar and accelerated warehouse robotics deployment in Greater Muscat micro-fulfillment nodes. Deepen backward integration into captive fleet ownership to offset labor cost inflation eroding asset-heavy margins. Prioritize Ministry of Health GDP certification renewal timelines to lock out undercapitalized challengers from pharmaceutical cold-chain contracts.
For New Entrants and Emerging Players: The premium-economy tier gap in Al Dhahirah hinterland cold-chain infrastructure offers white-space entry for temperature-controlled food distribution serving emerging retail catchments between Ibri and the Saudi border. Target customs brokerage density gaps at UAE land borders where Royal Oman Police digitization has compressed clearance times but specialized cross-border e-commerce expertise remains scarce. Lead with cloud-based TMS platforms offering AI load-optimization to mid-sized distributors seeking contracted lane consolidation.
For Investors and Strategic Acquirers: Roll-up economics work for regional freight brokers with bonded warehouse permits because regulatory licensing scarcity creates durable moats against unqualified competitors. Long-term viability centers on operators controlling multimodal corridor access through Asyad Rail partnerships and free zone leaseholds. Monitor Asyad Rail network expansion milestones toward the UAE border as the signal for rail-integrated contract bundling inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Rail-Port Integration Agreement | Asyad Rail network access locks in captive industrial manufacturing accounts through bundled multimodal service contracts. |
| Pharmaceutical GDP Certification Investment | Ministry of Health validation enables premium cold-chain pricing and filters out generalist warehouse competitors. |
| Micro-Fulfillment Node Expansion | Al Mawaleh and Ghala zone proximity compresses e-commerce delivery windows to 4-6 hour service levels. |
| Customs Digitization Platform Deployment | Royal Oman Police API standardization accelerates clearance times and reduces dwell costs for just-in-time replenishment. |
| Green Hydrogen Logistics Certification | Ministry of Energy and Minerals specialized handling protocols create premium service tiers for ammonia export corridors. |
Research Methodology
Direct dialogue with 3PL operations directors, free zone authority managers, customs brokerage heads, and industrial procurement leads at Sohar aluminum and steel clusters grounded qualitative findings in operational reality. Secondary validation drew from Royal Oman Police customs procedure disclosures, Public Authority for Special Economic Zones and Free Zones permit databases, Ministry of Transport regulatory filings, and port authority throughput statistics. Bottom-up service line sizing and top-down macroeconomic alignment triangulated market estimates across the analysis window.
Bottom-up modeling segmented revenue by service type, end-user vertical, technology adoption tier, and delivery model commitment level, while top-down validation cross-checked against national logistics strategy investment targets and GCC trade flow patterns. CAGRs were derived from trend extrapolation of e-commerce penetration rates, industrial outsourcing adoption curves, and infrastructure completion timelines. Forecast inputs incorporated Asyad Rail expansion phases, Duqm port capacity commissioning schedules, and vendor-managed inventory adoption velocity among manufacturing clusters.
The model assumes a particular technology adoption path; alternative pathways for warehouse automation and cloud-based visibility platform deployment would alter the outlook for capital intensity requirements and competitive consolidation timing. Deviation in Royal Oman Police customs digitization rollout speed or GCC customs union rule harmonization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Europe Domestic Courier Market
Logistics and Shipping
North America Pharmaceutical Logistics Market
Logistics and Shipping
France Cold Chain Logistics Market
Logistics and Shipping
US Express Delivery Market
Logistics and Shipping
North America Shipping Agency Market
Logistics and Shipping
Express Delivery Market
Logistics and Shipping
Thailand E-Commerce Logistics Market
Logistics and Shipping
Hong Kong Freight and Logistics Market
Logistics and Shipping
Sweden Cold Chain Logistics Market
Logistics and Shipping
United States Chemical Logistics Market
Logistics and Shipping
Global Dry Bulk Shipping Market
Logistics and Shipping
Japan Freight and Logistics Market
Logistics and Shipping
Asia Pacific Sea Freight Forwarding Market
Logistics and Shipping
Retail Logistics Market
Logistics and Shipping
Mexico Freight and Logistics Market
Logistics and Shipping
US Air Freight Transport Market