
 Digital Logistics Market | 2026-2036
Digital Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Logistics Market Intelligence
Mid-market retailers are rotating toward integrated digital logistics platforms as their primary technology investment priority. Blue Yonder leverages AI-native supply chain planning to anchor enterprise accounts across North America. project44 competes through real-time visibility APIs that connect multimodal freight networks. FourKites sustains growth by specializing in predictive ETAs for refrigerated and chemical transport segments.
Digital logistics encompasses software platforms, IoT sensor networks, and algorithmic optimization engines that coordinate the movement, storage, and fulfillment of goods across distributed supply chains. These systems process telemetry from GPS, RFID, and warehouse robotics to automate routing, inventory positioning, and carrier selection decisions. Cloud-based deployment leads solution architecture due to elastic compute requirements for demand forecasting workloads, while warehouse management systems capture concentrated margin pools as fulfillment complexity rises. Last mile delivery applications are expanding fastest as urban density and same-day service expectations force route density optimization.
The EU AI Act and GDPR shape algorithmic transparency requirements for automated dispatch systems operating in Europe, while the US DOT and FAA regulate autonomous last-mile vehicles and drone delivery pilots. China's MIIT enforces data localization for cross-border logistics platforms under national cybersecurity frameworks. Stakeholders must monitor evolving liability standards for AI-driven routing decisions as jurisdictions diverge on accountability assignment between software vendors and fleet operators.
Market Dynamics
Cloud-native logistics platforms are fragmenting traditional supply chain software hierarchies as mid-market shippers bypass monolithic ERP modules in favor of API-first orchestration layers. This architectural shift compresses vendor consolidation timelines and forces incumbents to unbundle pricing around specific freight modes.
Growth Catalysts
- E-commerce fulfillment mandates:Same-day delivery service-level agreements from Amazon and regional marketplaces are forcing third-party logistics operators to deploy real-time inventory positioning systems. Warehouse robotics integration accelerates across Germany, China, and the United States.
- EU AI Act compliance deadlines:Automated dispatch systems operating in Europe must demonstrate algorithmic transparency by documented technical standards. Logistics software vendors are accelerating explainable AI roadmaps to maintain continental market access.
- 5G private networks:Ultra-reliable low-latency connectivity enables millisecond-grade coordination between autonomous yard trucks and warehouse management systems. Port authorities in Rotterdam, Singapore, and Los Angeles are deploying these networks for container terminal automation.
Market Restraints
- Silicon supply concentration:Edge computing hardware for IoT gateways depends on concentrated semiconductor fabrication capacity in Taiwan and South Korea. Logistics operators face extended lead times for telemetry device deployments.
- GDPR data localization:Cross-border freight visibility platforms must maintain EU-resident data processing infrastructure. This fragments global cloud architectures and raises operational complexity for multinational operators.
- Battery chemistry constraints:Electric last-mile vehicle fleets face lithium-ion cell allocation competition from automotive and energy storage sectors. Charging infrastructure capex requirements strain mid-market carrier balance sheets.
Strategic Opportunities
- India warehouse automation:The country's PLI scheme for electronics manufacturing is generating demand for automated storage and retrieval systems. Domestic 3PL operators lack sophisticated WMS deployments relative to throughput growth.
- Pharmaceutical cold chain:Temperature-sensitive biologics distribution requires predictive ETA capabilities with deviation alerting. Specialty chemical and refrigerated food segments present adjacent expansion vectors for visibility platform vendors.
- Blockchain-IoT convergence:Immutable ledger architectures combined with sensor telemetry enable automated smart contracts for freight settlement. Container shipping lines are piloting these systems for intermodal handoff verification.
Industry Challenges
- Legacy WMS integration:Brownfield warehouse environments run decades-old inventory management codebases. API abstraction layers require custom middleware development that extends deployment timelines.
- Autonomous vehicle liability:Jurisdictions diverge on fault assignment between fleet operators, software vendors, and component manufacturers when AI-driven routing decisions cause incidents. Insurance product development lags technical capability.
- Interoperability standardization:Competing data exchange protocols fragment visibility networks. The industry lacks unified container event taxonomies comparable to airline booking code standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Logistics Market |
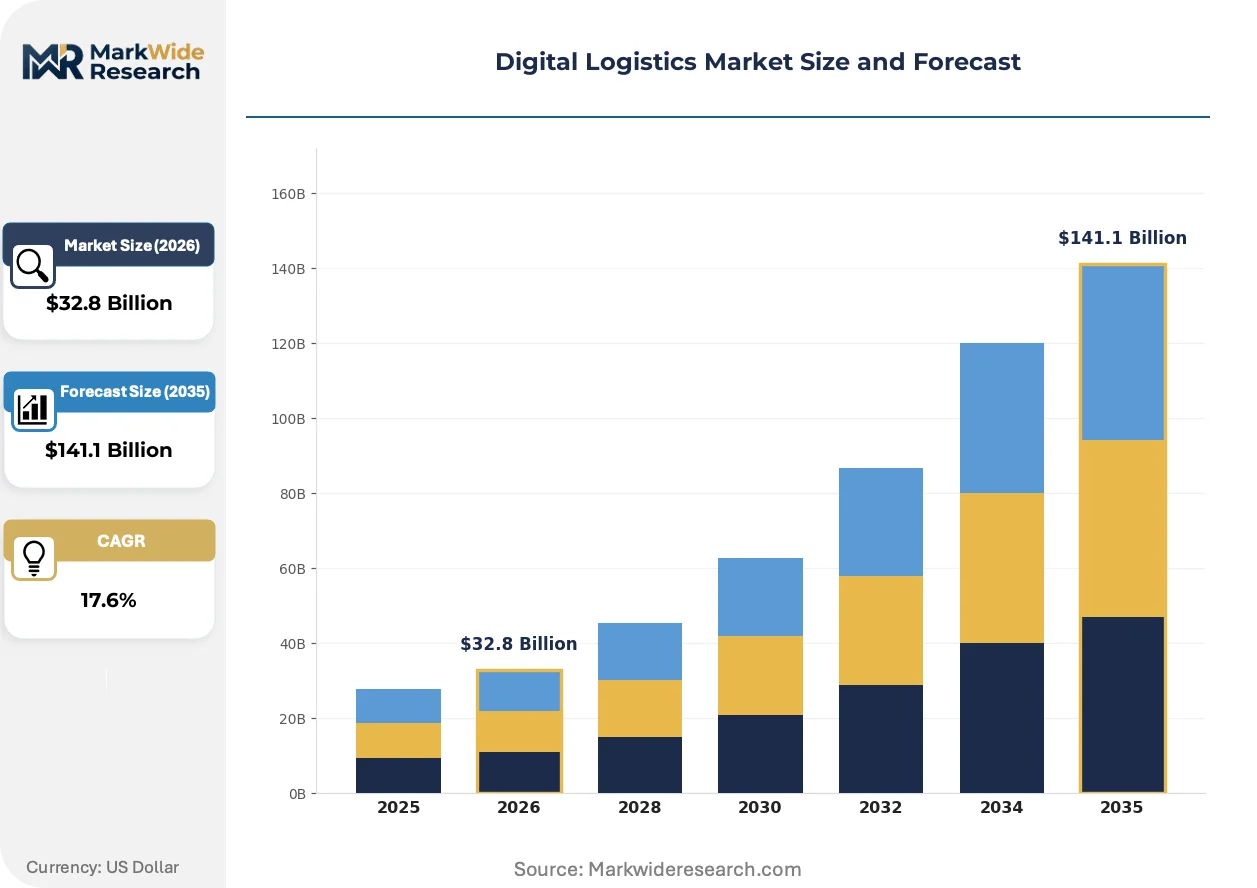
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $141.1 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-Premises, Hybrid, Edge Computing Solution: Transportation Management, Warehouse Management, Fleet Management, Order Management Application: Last Mile Delivery, Inventory Optimization, Route Planning, Demand Forecasting End User: Third-Party Providers, Freight Forwarders, Courier Services, Retailers |
| Companies Covered | Blue Yonder, project44, FourKites, Oracle Logistics Cloud, Descartes Systems Group, Symbotic, Manhattan Associates, Delhivery, Locus Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Logistics Market Strategic Shifts & Innovations
Computational architectures for supply chain planning are migrating from batch optimization toward continuous streaming models that ingest telemetry and recalculate routing decisions in sub-second intervals.
Digital twin technology is decomposing traditional network design consulting engagements into self-service simulation platforms. Mid-market shippers in retail and automotive verticals are adopting these tools without dedicated operations research staff. The technology is decomposing the historical vendor lock-in of tier-one supply chain consultancies by democratizing scenario modeling capabilities.
China's MIIT data localization requirements are mandating that cross-border logistics platforms maintain domestic cloud infrastructure for shipper and consignee records. Multinational operators must replicate system architectures or partner with licensed domestic cloud providers. Freight forwarders serving China-Europe rail corridors are restructuring IT governance to satisfy these frameworks.
Shipper procurement patterns are compressing vendor evaluation cycles from multi-year ERP-style selections toward modular six-month pilot programs. Subscription pricing for visibility APIs displaces perpetual license structures in North American and European accounts. Food and beverage manufacturers represent the most aggressive adopters of this consumption-based contracting approach.
Digital Logistics Market Segmentation
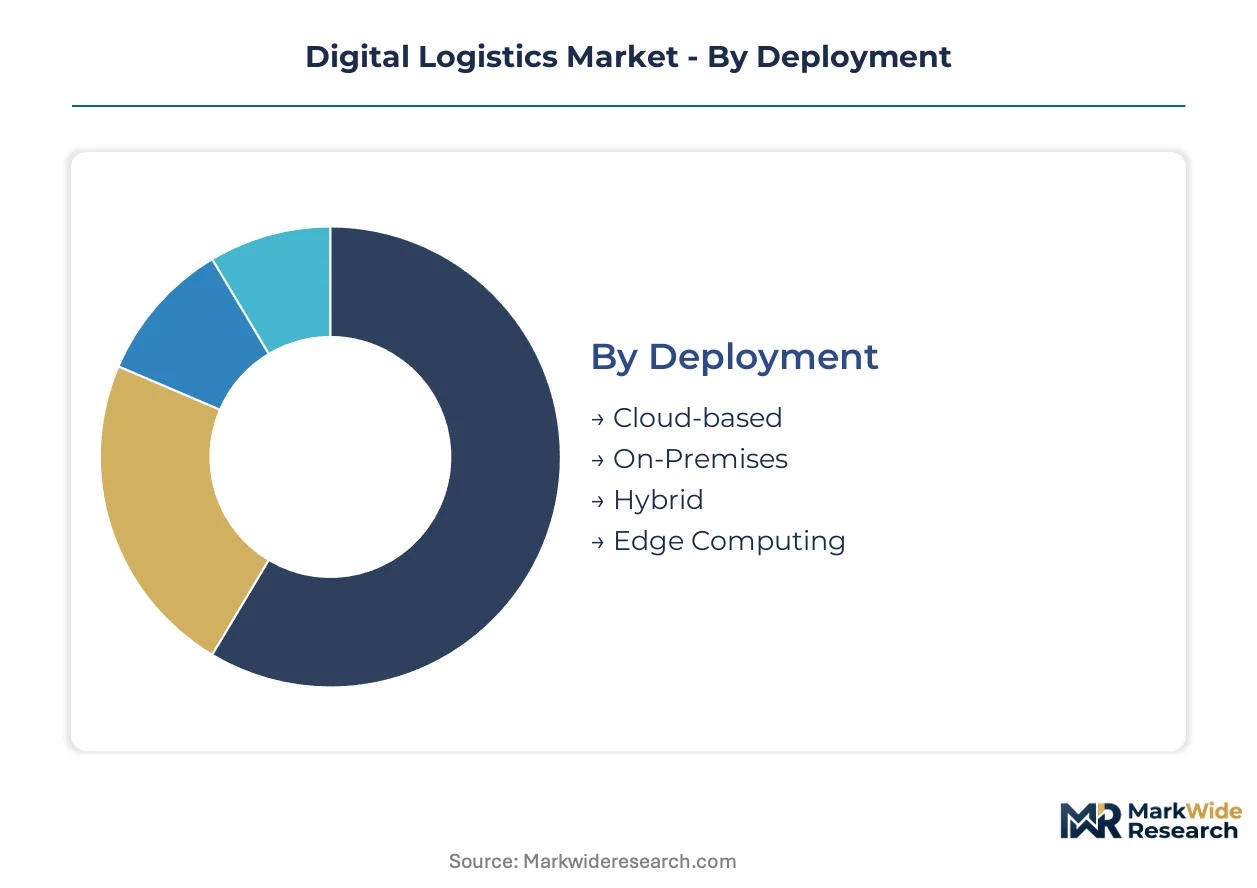
Segmentation in digital logistics reveals how software architecture, operational function, and customer type intersect to determine procurement patterns. Vendors configure pricing and deployment models around these dimensions as buyers prioritize integration flexibility over monolithic suites.
Deployment:
Margin pools concentrate in cloud-native architectures where recurring revenue scales faster than perpetual license maintenance.
- Cloud-based:Elastic compute infrastructure supports demand forecasting workloads without capital-intensive server procurement. Retailers in the United States and Germany favor this model for seasonal volume spikes. Subscription pricing displaces upfront licensing across North American and European accounts.
- On-Premises:Legacy data sovereignty requirements and specialized compliance mandates sustain this segment in regulated industries. Financial services and pharmaceutical shippers in Switzerland and Germany retain on-site control over routing algorithms. High implementation costs limit expansion to replacement cycles.
- Hybrid:Combines cloud orchestration with local processing for latency-sensitive warehouse robotics coordination.
- Edge Computing:Millisecond-grade telemetry processing for autonomous yard trucks and port terminal automation.
On-premises holds installed capacity. Cloud-based is rotating up the share rankings.
Solution:
Cost tier differentiation separates enterprise-grade orchestration platforms from modular point solutions targeting mid-market penetration.
- Warehouse Management:Automated storage and retrieval system integration captures concentrated margin as fulfillment complexity rises. E-commerce operators in China and the United States deploy these systems for same-day service mandates. Robotics coordination APIs extend deployment timelines but lock in recurring integration revenue.
- Transportation Management:Multimodal freight optimization across rail, ocean, and air modes requires real-time carrier connectivity. Freight forwarders serving China-Europe corridors prioritize these platforms for intermodal handoff visibility. API-first architectures fragment traditional ERP module hierarchies.
- Fleet Management:Vehicle telematics and driver behavior analytics for asset-heavy carriers.
- Order Management:Distributed inventory positioning across fulfillment nodes for omnichannel retail.
Warehouse Management dominates current bookings. Transportation Management is climbing the fastest as multimodal complexity intensifies.
Application:
Volume concentration tracks urban density gradients where last-mile density economics determine platform viability.
- Last Mile Delivery:Route optimization algorithms process real-time traffic and customer availability signals. Courier services in Los Angeles, Rotterdam, and Singapore deploy these systems for sub-two-hour delivery windows. Urban congestion charges in European cities accelerate electric fleet coordination requirements.
- Inventory Optimization:Probabilistic demand modeling positions stock across distributed fulfillment nodes. Mid-market retailers bypass dedicated operations research staff through self-service simulation interfaces. Digital twin technology democratizes scenario modeling previously locked in tier-one consultancies.
- Route Planning:Static and dynamic routing for line-haul and regional distribution networks.
- Demand Forecasting:Machine learning pipelines ingesting point-of-sale and external signal data.
Inventory Optimization holds installed capacity. Last Mile Delivery is gaining share fastest as same-day expectations harden.
End User:
Customer type determines contract structure, with asset-light intermediaries favoring consumption-based pricing against asset-heavy operators preferring perpetual licenses.
- Third-Party Providers:Integrated platform requirements span warehousing, transportation, and value-added services. 3PL operators in India lack sophisticated WMS deployments relative to electronics manufacturing throughput growth. The country's PLI scheme generates demand for automated storage and retrieval system integration.
- Freight Forwarders:Cross-border documentation and customs clearance automation for international trade lanes. Operators serving China-Europe rail corridors restructure IT governance for MIIT data localization compliance. Blockchain-IoT pilot programs target intermodal handoff verification.
- Courier Services:Point-to-point parcel networks requiring real-time customer communication and delivery confirmation.
- Retailers:Direct-to-consumer fulfillment integration with existing e-commerce infrastructure.
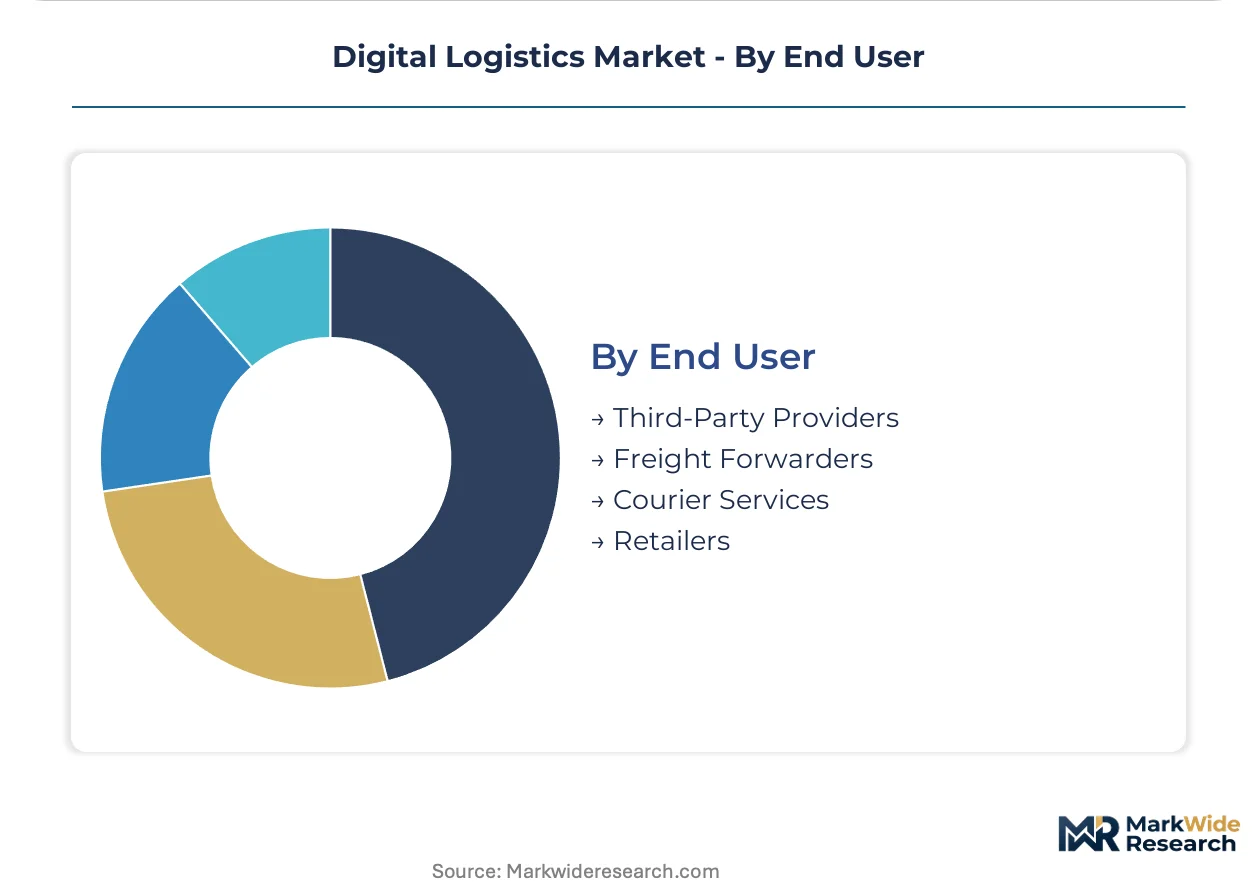
Third-Party Providers hold installed capacity. Freight Forwarders is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smart port and automated warehouse infrastructure investments concentrate in the United States, Germany, and China as these markets absorb the bulk of platform procurement spend. E-commerce fulfillment operators across these geographies are accelerating cloud migration and AI-driven route optimization adoption.
United States
Amazon's same-day delivery service-level agreements are forcing third-party logistics operators to deploy real-time inventory positioning systems. The FAA regulates autonomous last-mile vehicle and drone delivery pilots through experimental certification frameworks. Los Angeles port authorities are deploying 5G private networks for container terminal automation.
Germany
Automotive and industrial manufacturers are driving demand for multimodal freight optimization across rail, ocean, and air modes. The EU AI Act mandates algorithmic transparency for automated dispatch systems operating across German logistics networks. Rotterdam-adjacent operators leverage ultra-reliable low-latency connectivity for autonomous yard truck coordination.
China
Electronics manufacturing throughput growth under the MIIT's industrial policies is generating demand for automated storage and retrieval system integration. National cybersecurity frameworks enforce data localization for cross-border logistics platforms. Shanghai and Shenzhen port clusters are restructuring IT governance to satisfy domestic cloud infrastructure mandates.
India
The country's PLI scheme for electronics manufacturing is outpacing domestic 3PL operators' warehouse management system sophistication. BIS standards and DGFT regulations shape import-export documentation automation requirements. Maharashtra and Karnataka industrial corridors are attracting automated fulfillment node investments.
Singapore
Regional freight forwarders serving China-Europe rail corridors are establishing data residency-compliant operations. The Maritime and Port Authority coordinates 5G private network deployment for smart port initiatives. The city-state's logistics technology cluster is piloting blockchain-IoT systems for intermodal handoff verification.
Digital Logistics Market Key Industry Players
Concentration sits with cloud-native platform vendors that have unbundled traditional ERP module hierarchies through API-first architectures. The vendor landscape fragments across specialized visibility providers, warehouse robotics integrators, and supply chain planning suites. Two strategic archetypes dominate: AI-native planning specialists and real-time visibility platform operators. Competitive moves center on API ecosystem expansion and vertical integration into warehouse robotics coordination.
Within the AI-native planning tier, Blue Yonder anchors enterprise account positioning across North American markets. project44 and FourKites occupy distinct positions in the real-time visibility segment, with the former emphasizing multimodal freight network connectivity and the latter specializing in predictive ETA capabilities for temperature-sensitive transport. These three companies exemplify the architectural shift toward modular, consumption-based contracting that is displacing perpetual license structures in retail and manufacturing accounts.
| Leading Market Players |
|---|
| Blue Yonder |
| project44 |
| FourKites |
| Oracle Logistics Cloud |
| Descartes Systems Group |
| Symbotic |
| Manhattan Associates |
| Delhivery |
| Locus Robotics |
| Others |
Cost & Logistics Intelligence
Ninety-day semiconductor lead times for IoT gateway edge hardware compress margin buffers across cloud-native logistics platforms while amplifying pricing power for Taiwan and South Korea fabrication capacity holders. This inventory tension feeds directly into subscription pricing elasticity as mid-market shippers absorb hardware procurement delays into their total cost of ownership calculations.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across European deployments, separating explainable AI-certified orchestration platforms from standard cloud offerings. Three-tier pricing structure across premium, standard, and economy levels stratifies by algorithmic transparency documentation depth and cross-border data residency compliance. Cost compression in the standard tier is intensifying because mid-market retailers are consolidating vendor relationships around API-first consumption models. Third-party logistics operators exhibit the highest price sensitivity due to thin margin profiles, while pharmaceutical shippers accept premium positioning for cold chain deviation alerting capabilities.
Supply Chain Analysis
Ninety-day semiconductor lead times expose cloud-native logistics platforms to single-source vulnerability in Taiwan and South Korea fabrication capacity. Edge computing hardware draws from concentrated lithium-ion cell supply anchored in China, South Korea, and Japan, with battery chemistry allocation competition from automotive and energy storage sectors. Distribution runs through hyperscale cloud provider regional data centers with EU-resident processing mandates fragmenting global architectures under GDPR localization requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to e-commerce fulfillment volume normalization following pandemic-era overcapacity corrections. Inventory destocking completion across retail verticals is restoring platform procurement momentum.
For Market Incumbents: Consolidate API ecosystem dominance through backward integration into warehouse robotics coordination capabilities, neutralizing the threat from specialized automation vendors. Prioritize certification investment for EU AI Act algorithmic transparency standards to maintain continental market access against emerging cloud-native challengers.
For New Entrants and Emerging Players: BIS fast-track certification for electronics manufacturing logistics platforms unlocks India's PLI scheme warehouse automation demand as the most penetrable geography. Target domestic 3PL operators lacking sophisticated WMS deployments relative to throughput growth, with a channel partnership go-to-market angle through regional system integrators.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure software play because supply chain digitization penetration remains below saturation across mid-market manufacturing verticals. Acquisition target archetype: AI-native planning specialists with embedded customer workflows. Monitor 5G private network deployment velocity at Rotterdam, Singapore, and Los Angeles port authorities as the inflection signal for autonomous yard truck coordination demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first orchestration layers displace monolithic ERP modules across mid-market shipper accounts. |
| Strategic Partnership | Licensed domestic cloud provider alliances satisfy MIIT data localization mandates for China-Europe corridors. |
| Acquisition of Specialist Firm | Warehouse robotics integrators extend recurring revenue through coordination API lock-in. |
| Geographic Expansion | India PLI scheme electronics manufacturing generates automated storage and retrieval system demand. |
| Product Launch | Explainable AI roadmaps maintain EU market access under algorithmic transparency deadlines. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, customs trade data, and EU regulatory submissions, with bottom-up and top-down triangulation across deployment model, solution type, application function, and end-user category segmentation. Primary interviews engaged supply chain planning directors, IT procurement officers at 3PL operators, platform integration specialists, and warehouse robotics engineers. Secondary validation drew from FAA experimental certification frameworks, MIIT industrial policy documents, and port authority automation procurement records.
Segmentation dimensions modeled include deployment architecture, operational solution type, application function, and end-user category across the analysis window. CAGRs were derived from elasticity modeling of e-commerce fulfillment volume growth against platform adoption curves, with inputs from 5G private network deployment timelines and EU AI Act compliance cost burden estimates.
Underlying assumptions cover sustained cloud migration momentum and semiconductor supply normalization, with deviation risk concentrated in battery chemistry allocation competition and autonomous vehicle liability framework divergence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Latin America Fourth Party Logistics (4PL) Market
Logistics and Shipping
Multi-Enterprise Logistics Contract and SLA Performance Management Platforms Market
Logistics and Shipping
GCC Trailer Market
Logistics and Shipping
Baggage Handling System Market
Logistics and Shipping
China Cold Chain Logistics Market
Logistics and Shipping
Global 3PL in Cold Chain Logistics Market
Logistics and Shipping
Intra-Asia Freight Forwarding Market
Logistics and Shipping
Secure Logistics Market
Logistics and Shipping
Germany Dangerous Goods Logistics Market
Logistics and Shipping
Indonesia Freight and Logistics Market
Logistics and Shipping
Colombia Third-Party Logistics (3PL) Market
Logistics and Shipping
Government and Education Logistics Market
Logistics and Shipping
Saudi Arabia Third-Party Logistics (3PL) Market
Logistics and Shipping
Air Cargo Container Market
Logistics and Shipping
Colombia Freight and Logistics Market
Logistics and Shipping
Inland Container Depot and Dry Port Market