
 Mexico Logistics Market | 2026-2036
Mexico Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Logistics Market Insights
Modular service bundling is decoupling as buyers unbundle transportation from warehousing contracts to optimize cost visibility. Estafeta leverages its domestic parcel density to anchor last-mile coverage across Mexican territory. DHL Group sustains cross-border freight corridors through integrated customs brokerage and bonded warehousing. Traxion differentiates via specialized heavy-haul and dedicated fleet services for industrial clients.
Logistics encompasses the planning, execution, and control of goods movement, requiring coordination across multimodal transport nodes, temperature-controlled storage specifications, and real-time inventory tracking systems to ensure supply chain continuity. Its primary commercial purpose centers on reducing total landed costs while meeting delivery velocity requirements for time-sensitive production schedules. Freight forwarding and customs brokerage command disproportionate margin pools due to regulatory complexity and documentation intensity at USMCA border crossings. Transportation services dominate absolute revenue contribution, though warehouse management systems within the technology segment attract accelerated capital deployment as facilities automate inventory positioning.
SICT governs commercial freight licensing and highway safety standards, while the Tax Administration Service (SAT) enforces customs valuation and origin certification rules that directly determine cross-border clearance speed. COFEPRIS regulates pharmaceutical and food-grade cold chain protocols, creating compliance barriers that favor certified third-party logistics providers. Stakeholders must monitor whether nearshoring manufacturing commitments translate into sustained infrastructure investment at Lázaro Cárdenas and Veracruz port complexes.
Market Dynamics
Nearshoring manufacturing commitments are compressing cross-border transit windows across Mexico's industrial corridor, forcing logistics providers to synchronize just-in-time inventory flows with USMCA customs protocols. This structural pressure is reshaping facility placement and multimodal routing decisions throughout the Bajío and northern border zones.
Growth Catalysts
- USMCA Origin Certification:The trade agreement's rules-of-origin requirements are accelerating demand for bonded warehousing and documentation services at Laredo-Nuevo Laredo crossings.
- Automotive Just-in-Time Networks:OEMs expanding assembly operations in Guanajuato and Querétaro are mandating sub-24-hour component replenishment cycles from suppliers.
- Port Modernization:Lázaro Cárdenas and Veracruz container terminal expansions are attracting transshipment volume previously routed through US West Coast gateways.
Market Restraints
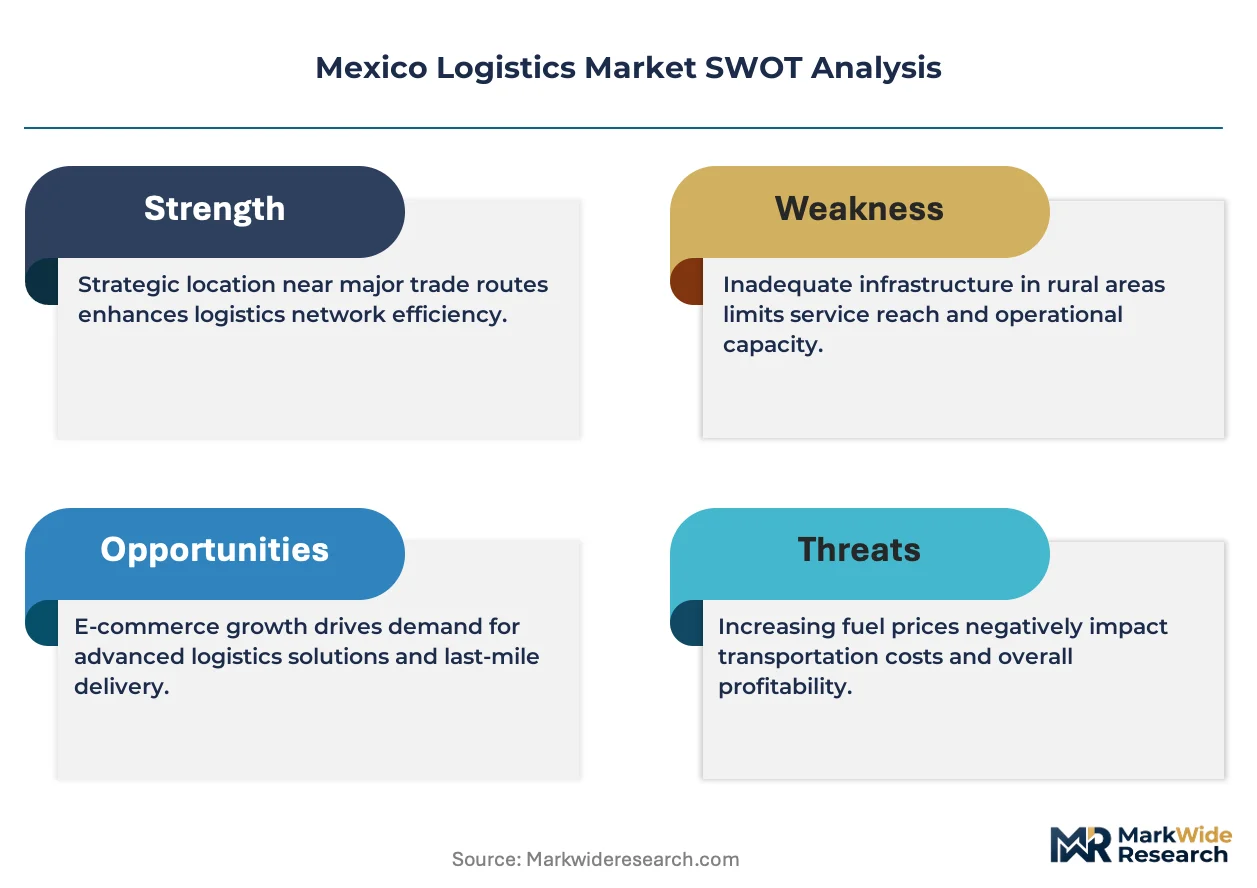
- Fuel Price Volatility:Diesel cost fluctuations directly compress trucking margins on long-haul routes between Mexico City and Monterrey corridors.
- Highway Infrastructure Gaps:Federal toll road capacity constraints around Puebla and Toluca create bottlenecks for time-sensitive freight movements.
- Customs Documentation Intensity:SAT valuation audits and origin verification procedures generate clearance delays that erode shipper cost advantages.
Strategic Opportunities
- Yucatán Peninsula Underpenetration:Merida and Cancún industrial zones lack integrated cold chain infrastructure for pharmaceutical distribution.
- Pharmaceutical Cold Chain:COFEPRIS temperature-compliance mandates are creating certified 3PL white space for biologics storage in Querétaro.
- Rail-Truck Intermodal:Ferromex and Kansas City Southern Mexico network expansions enable cost-competitive alternatives to pure trucking on Mexico-US lanes.
Industry Challenges
- Certified Driver Scarcity:Hazardous materials and oversized load endorsements require specialized training programs that lag current demand.
- Warehouse Management System Integration:Legacy inventory platforms at mid-market 3PLs resist real-time API connectivity with shipper ERP systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Logistics Market |
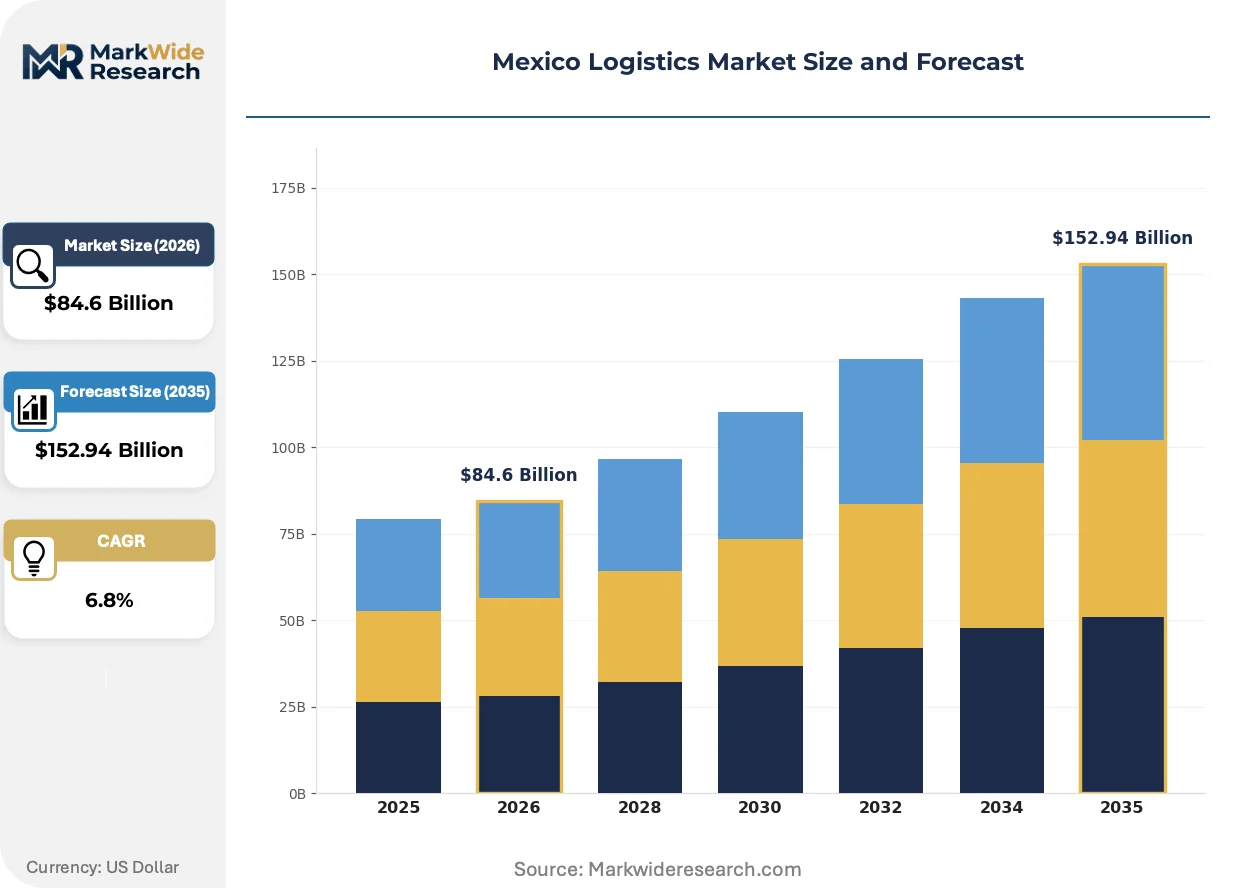
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $152.94 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Customs Brokerage Technology: GPS Tracking, RFID, Warehouse Management Systems, TMS End User: E-Commerce, Retail, Manufacturing, Automotive Distribution Channel: Direct Sales, Online Platforms, Distributors, Agents |
| Companies Covered | Estafeta, DHL Group, Correos de México, Traxion, UPS, FedEx, Penske Logistics, Kuehne+Nagel, C.H. Robinson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Logistics Market Trends and Innovations
Digital freight matching and automated customs clearance are compressing transaction cycles across Mexico's logistics stack. Technology deployment is accelerating fastest where regulatory complexity intersects with high-velocity supply chains.
Telematics-enabled fleet management is automating route optimization and driver performance monitoring for dedicated contract carriage operations. Automotive manufacturers operating in San Luis Potosí and Aguascalientes are mandating real-time shipment visibility as a procurement prerequisite. This capability compression is eliminating manual dispatch processes and reducing empty-mile ratios on return legs.
SICT electronic manifest requirements and SAT pre-arrival filing mandates are tightening documentation standards for cross-border freight. The regulatory burden falls heaviest on small trucking operators lacking in-house customs brokerage capabilities. Large integrated providers are responding by embedding bonded warehouse capacity directly within their terminal networks.
Shippers are unbundling transportation from warehousing contracts to improve cost visibility and supplier accountability. Automotive and aerospace manufacturers in Querétaro are negotiating separate rates for line-haul, last-mile, and storage services. This disaggregation is most pronounced among multinational corporations with centralized procurement functions and detailed freight spend analytics.
Mexico Logistics Market Segmentation
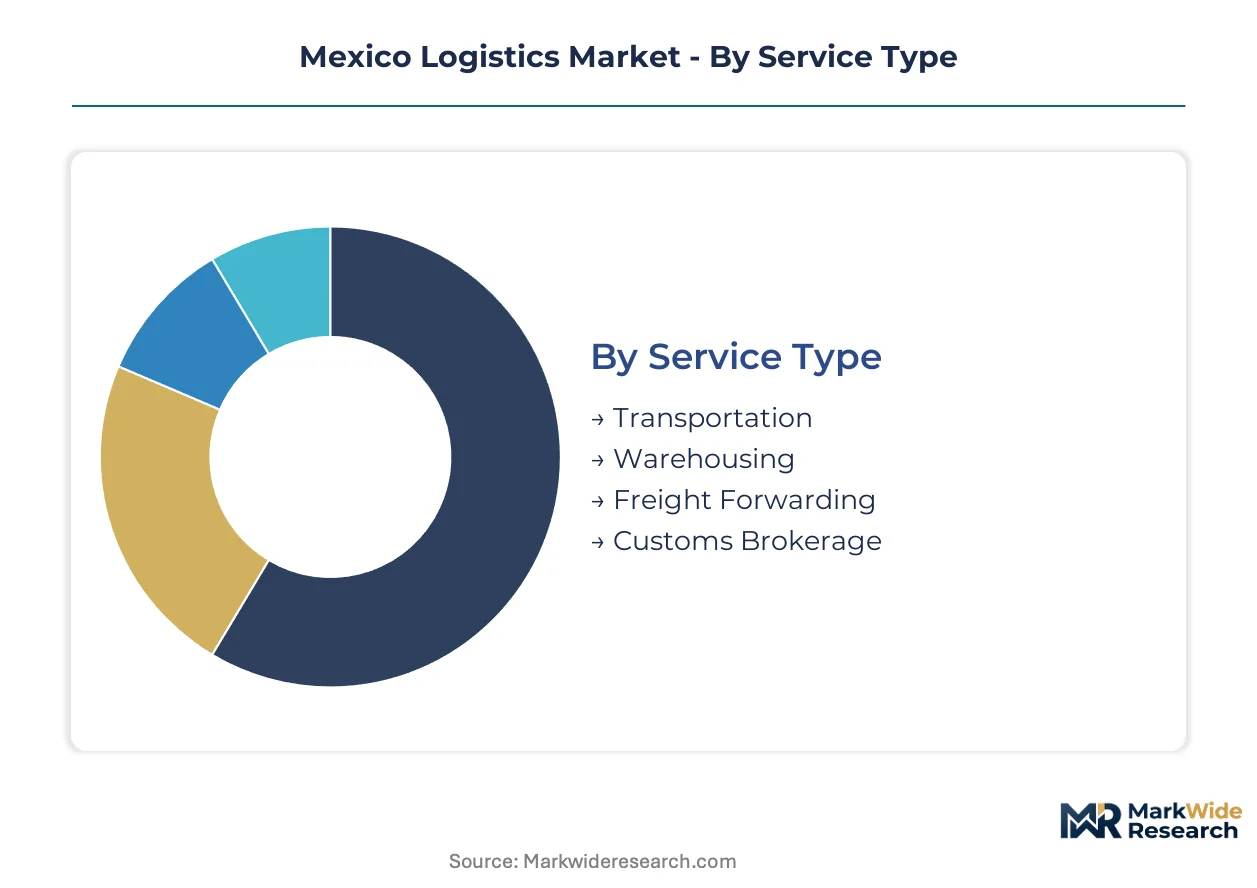
Segmentation in Mexico's logistics market reveals how procurement decisions split across service bundling preferences and technology readiness. Buyers in the Bajío automotive corridor and northern border zones prioritize different capability combinations based on their USMCA compliance exposure and inventory velocity requirements.
Service Type:
Cost tier determines contract structure, with buyers unbundling services to isolate transportation spend from storage costs.
- Transportation:Line-haul trucking and dedicated fleet operations dominate absolute revenue contribution. Automotive OEMs in Guanajuato and Querétaro mandate sub-24-hour replenishment cycles that compress routing decisions and favor asset-based carriers with cross-border permits.
- Warehousing:Bonded storage facilities at Laredo-Nuevo Laredo and Lázaro Cárdenas anchor inventory positioning for USMCA origin certification. COFEPRIS-compliant cold chain specifications create compliance barriers that favor certified third-party providers in pharmaceutical distribution.
- Freight Forwarding:Documentation-intensive coordination across multimodal nodes, concentrating margin pools at SAT-regulated border crossings.
- Customs Brokerage:Pre-arrival filing mandates and valuation audit protocols drive demand for integrated brokerage within larger logistics networks.
Transportation leads on scale; customs brokerage leads on momentum as documentation intensity accelerates.
Technology:
Application focus separates automotive-grade visibility requirements from retail inventory accuracy needs.
- Warehouse Management Systems:Real-time inventory positioning and API connectivity with shipper ERP systems are accelerating capital deployment. Mid-market 3PLs face integration barriers with legacy platforms resisting automated data exchange.
- GPS Tracking:Telematics-enabled fleet management automates route optimization and driver performance monitoring. San Luis Potosí and Aguascalientes manufacturers require real-time shipment visibility as a procurement prerequisite.
- RFID:Automated identification for high-velocity sorting operations in e-commerce fulfillment centers.
- TMS:Transportation management systems coordinating multimodal routing decisions across Ferromex rail and Kansas City Southern Mexico networks.
GPS tracking leads on scale; warehouse management systems are gaining share fastest as automation investments deepen.
End User:
Volume concentration and margin structure vary sharply across production-driven versus consumption-driven demand.
- Automotive:Just-in-time inventory networks mandate synchronized component flows from suppliers to assembly plants. The Bajío corridor's OEM expansion is reshaping facility placement decisions throughout Guanajuato and Querétaro.
- Manufacturing:Nearshoring commitments in aerospace and electronics generate demand for specialized heavy-haul and dedicated fleet services.
- E-Commerce:Last-mile density requirements drive parcel network expansion across Mexican territory, with coverage gaps persisting in the Yucatán Peninsula.
- Retail:Inventory positioning for consumer goods distribution concentrates in Mexico City and Monterrey corridors.
Automotive leads on scale; e-commerce shows the steepest expansion trajectory as digital commerce penetrates secondary cities.
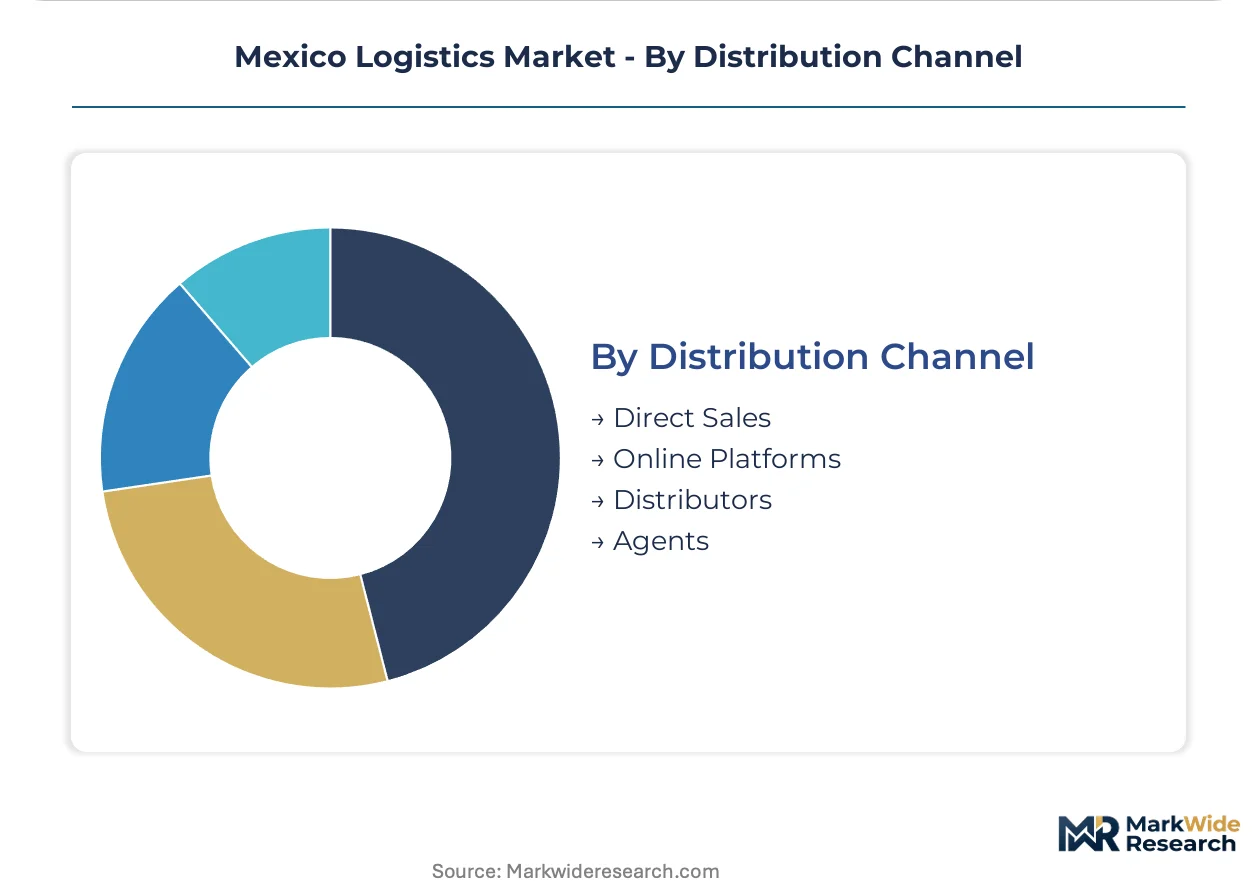
Distribution Channel:
Customer type and procurement sophistication determine whether buyers access services through direct relationships or intermediary structures.
- Direct Sales:Multinational corporations with centralized procurement functions negotiate separate rates for line-haul, last-mile, and storage services to improve cost visibility.
- Distributors:Regional logistics aggregators serving mid-market manufacturers lacking in-house freight spend analytics.
- Online Platforms:Digital freight matching compresses transaction cycles for spot market capacity.
- Agents:Local intermediaries facilitating customs clearance and last-mile coordination in underpenetrated zones.
Direct sales leads on scale; online platforms are climbing the fastest as digital adoption spreads to smaller shippers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's logistics infrastructure originated from colonial trade routes connecting silver mining centers to Atlantic and Pacific ports. Modern freight networks evolved through 20th-century industrial corridor development linking manufacturing zones to US border crossings.
Northern Border States
Automotive assembly plants and electronics maquiladoras drive cross-border freight volume through Nuevo Laredo and Ciudad Juárez. SAT enforces USMCA origin certification protocols that compress clearance timelines at these gateways. Tijuana and Mexicali concentrate aerospace component manufacturing requiring synchronized just-in-time delivery schedules.
Bajío Region
Guanajuato and Querétaro anchor automotive and aerospace logistics demand from OEM expansion programs. SICT updates commercial freight licensing standards to align with highway safety requirements across federal corridors. San Luis Potosí and Aguascalientes host supplier parks mandating sub-24-hour inventory replenishment cycles.
Central Mexico
Mexico City Metro generates consumption-driven freight from retail distribution and e-commerce fulfillment networks. The Tax Administration Service audits customs valuations for imports arriving through Mexico City International Airport. Puebla and Toluca face federal toll road capacity constraints creating bottlenecks for time-sensitive movements.
Jalisco
Guadalajara's electronics manufacturing base generates specialized heavy-haul and dedicated fleet requirements. COFEPRIS regulates pharmaceutical cold chain protocols for medical device distribution from the city's health sciences cluster. Puerto Vallarta and coastal zones attract tourism-related logistics services with seasonal demand spikes.
Yucatán Peninsula
Merida and Cancún industrial zones lack integrated cold chain infrastructure for pharmaceutical and perishable distribution. The Secretariat of Infrastructure maintains port modernization schedules for Progreso to capture transshipment volume. Underpenetration in temperature-controlled warehousing creates white space for certified third-party logistics investment.
Mexico Logistics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service integration and customs brokerage capabilities. Asset-heavy carriers with cross-border permits command pricing power on USMCA corridors, while parcel networks compete on domestic density and last-mile coverage. Three archetypes dominate: integrated multinational networks, specialized domestic heavy-haul operators, and digital freight matching platforms. Capacity expansion through bonded warehouse construction and strategic partnerships with rail operators represent the primary competitive moves reshaping market positioning.
Within the integrated multinational tier, DHL Group and Kuehne+Nagel exemplify cross-border freight coordination through embedded customs brokerage and bonded warehousing networks. Among domestic specialists, Estafeta and Traxion occupy distinct positions—Estafeta anchoring parcel density across Mexican territory, Traxion representing dedicated fleet and heavy-haul capabilities for industrial clients. These three companies illustrate how geographic coverage specialization and service bundling decisions separate premium-tier positioning from commodity-margin competition.
| Leading Market Players |
|---|
| Estafeta |
| DHL Group |
| Correos de México |
| Traxion |
| UPS |
| FedEx |
| Penske Logistics |
| Kuehne+Nagel |
| C.H. Robinson |
| Others |
Pricing and Supply Chain Analysis
Automotive OEM procurement clusters in Guanajuato and Querétaro anchor contract-based long-term offtake agreements that compress spot market liquidity and concentrate pricing power among asset-based carriers holding USMCA cross-border permits. SICT commercial freight licensing requirements and SAT customs valuation protocols layer compliance costs that carriers recover through dedicated fleet premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates bonded warehouse-integrated providers from pure trucking operators and spot-market brokers. Certification grade for COFEPRIS cold chain compliance and volume scale through annual committed lane contracts drive price differentiation. Cost compression in standard-tier line-haul services is intensifying because diesel price volatility erodes margins on Mexico City-Monterrey corridors. Small trucking operators lacking in-house customs brokerage capabilities exhibit highest price sensitivity; multinational manufacturers with centralized procurement functions show lowest sensitivity due to total landed cost optimization priorities.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand through dedicated contract carriage arrangements, while distributor networks aggregate mid-market manufacturers lacking freight spend analytics. Supply concentrates in Mexico's Bajío automotive corridor, US border zone maquiladora clusters, and Lázaro Cárdenas port complex. Raw material dependencies include diesel fuel for long-haul trucking, bonded warehouse capacity at SAT-regulated crossings, and specialized chassis equipment for heavy-haul industrial movements. Single-source vulnerability around certified hazardous materials drivers with SAT endorsements creates recruitment bottlenecks that constrain capacity expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's logistics market represents a late-cycle quality story where nearshoring manufacturing commitments are compressing transit windows and elevating premium specifications for real-time visibility and USMCA-compliant documentation.
For Market Incumbents: Hedge margin erosion from digital freight matching platforms by embedding bonded warehouse capacity within terminal networks at Laredo-Nuevo Laredo crossings. Prioritize backward integration into customs brokerage capabilities to capture documentation-intensive margin pools that resist pure-commoditization pressures from automated clearance technologies. For New Entrants and Emerging Players: Regional logistics aggregators serving Yucatán Peninsula industrial zones offer the most penetrable white-space target, where Merida and Cancún lack integrated cold chain infrastructure for pharmaceutical distribution. Pursue COFEPRIS certification investment as the go-to-market angle, positioning certified 3PL services for biologics storage demand migrating from underpenetrated zones. For Investors and Strategic Acquirers: Automotive OEMs and aerospace tier-one suppliers are the most active acquirer in this space, seeking captive control over just-in-time inventory flows. Long-term viability favors asset-heavy operators with cross-border permits and rail intermodal partnerships. Monitor whether Lázaro Cárdenas and Veracruz port modernization schedules sustain transshipment volume capture from US West Coast gateways as the inflection indicator for infrastructure-led competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Bonded Warehouse Network Expansion | Embedded SAT-compliant storage at Laredo-Nuevo Laredo crossings accelerates USMCA origin certification cycles. |
| Rail-Truck Intermodal Partnership | Ferromex and Kansas City Southern Mexico network access enables cost-competitive alternatives to pure trucking lanes. |
| Cold Chain Certification Investment | COFEPRIS-compliant biologics storage in Querétaro captures pharmaceutical distribution white space. |
| Telematics Platform Deployment | Real-time shipment visibility meets San Luis Potosí OEM procurement prerequisites for supplier qualification. |
| Last-Mile Density Buildout | Parcel network expansion across secondary cities addresses e-commerce penetration gaps in Yucatán Peninsula zones. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with logistics procurement managers at automotive OEMs, customs brokerage operations leads, 3PL warehouse directors, SICT regulatory affairs specialists, and SAT valuation auditors with secondary validation. Trade flow databases, SICT commercial freight licensing records, SAT customs clearance statistics, and bonded warehouse capacity registries anchored bottom-up volume estimates, while macroeconomic indicators and manufacturing FDI trajectories informed top-down market sizing triangulation.
Historical reference periods spanning pre-USMCA implementation through nearshoring acceleration phases anchored the forecast window's baseline trajectory. The analytical framework modeled demand across service type, technology application, end-use vertical, and distribution channel dimensions, with regional production cluster granularity for Bajío, northern border, and central Mexico corridors. CAGRs derived from segment-level growth rate convergence analysis incorporated automotive assembly plant expansion schedules, port modernization investment timelines, and e-commerce penetration curves as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SAT customs documentation intensity shifts, diesel price volatility regimes, and infrastructure completion schedules at Lázaro Cárdenas and Veracruz. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
United States 3PL Market
Logistics and Shipping
Global Courier Market
Logistics and Shipping
China Shipping Agency Services Market
Logistics and Shipping
Mexico Road Freight Transport Market
Logistics and Shipping
France Parcel Market
Logistics and Shipping
GCC Warehousing and Distribution Logistics Market
Logistics and Shipping
UAE Contract Logistics Market
Logistics and Shipping
North America Freight Brokerage Market
Logistics and Shipping
South Africa Third-Party Logistics (3PL) Market
Logistics and Shipping
Logistics Data Quality and Normalization Services Market
Logistics and Shipping
Baggage Handling System Market
Logistics and Shipping
US Event Logistics Market
Logistics and Shipping
Renewable Resources Logistics Market
Logistics and Shipping
Brazil Freight and Logistics Market
Logistics and Shipping
GCC Event Logistics Market
Logistics and Shipping
Chile Freight and Logistics Market