
 China Digital Freight Forwarding Market | 2026-2036
China Digital Freight Forwarding Market Size, Share, and Industry Trends Forecast 2026-2036
China Digital Freight Forwarding Market Outlook
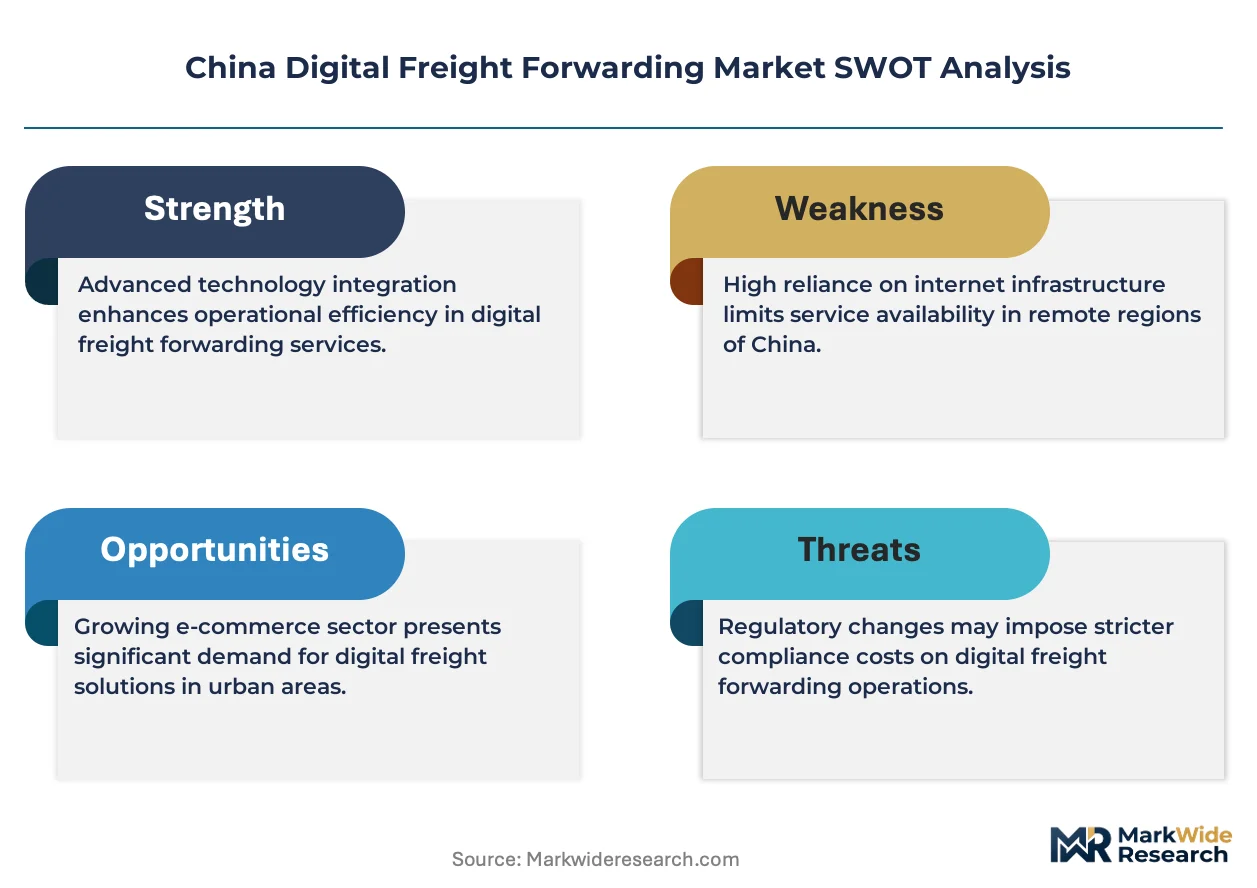
Logistics software engineering talent scarcity is reorganizing competitive dynamics across China's digital freight sector. Full Truck Alliance leverages its driver-network density to sustain pricing power on domestic lanes. Kuehne + Nagel International AG anchors its position through specialized ocean freight digitization for European trade corridors. Flexport competes by integrating customs brokerage workflows directly into its platform interface.
Digital freight forwarding encompasses the algorithmic orchestration of cargo movement across multimodal networks, where electronic data interchange replaces paper bills of lading and real-time visibility APIs connect shippers to carriers. Cloud computing infrastructure enables instantaneous rate quotation and capacity matching across fragmented trucking markets. Ocean freight digitization currently occupies the largest margin pool due to documentation complexity and vessel capacity volatility. Artificial intelligence applications in predictive routing represent the fastest-expanding technology segment as shippers prioritize delivery reliability over pure cost minimization.
SAMR enforces platform economy antitrust provisions that constrain dominant freight marketplaces from exclusive carrier contracts. MIIT's logistics digitization mandates require API interoperability between enterprise shippers and forwarder platforms. GB standards for electronic waybill formatting shape data architecture investments across the vendor landscape. Stakeholders must weigh regulatory compliance costs against network effects when selecting technology partners for cross-border operations.
Market Dynamics
MIIT's logistics digitization mandates are compressing adoption timelines for API interoperability standards, forcing freight platforms to rearchitect data infrastructure before compliance deadlines crystallize competitive separation.
Growth Catalysts
- Cross-border e-commerce concentration:Merchants along the Yangtze River Delta corridor connecting Shanghai, Hangzhou, and Ningbo are consolidating freight procurement onto unified platforms to manage multi-country destination complexity.
- GB standards for electronic waybills:National standardization of digital documentation formats is eliminating paper-based friction in multimodal handoffs between trucking, rail, and ocean segments.
- Dual carbon goals:Beijing's emissions reduction framework is incentivizing route optimization algorithms that minimize empty-mileage and fuel waste across domestic trucking networks.
Market Restraints
- Cloud infrastructure cost volatility:Real-time visibility APIs and predictive routing engines require sustained compute expenditure that compresses margins for mid-tier platform operators.
- Driver-network concentration:Domestic lane capacity aggregates disproportionately around tier-one manufacturing clusters, leaving interior provinces with thinner matching liquidity and rate instability.
- SAMR antitrust enforcement:Platform economy provisions constrain dominant marketplaces from exclusive carrier contracts, limiting defensive moat construction through vertical lock-in.
Strategic Opportunities
- European trade corridor digitization:Ocean freight workflows connecting Chinese manufacturing to Rotterdam and Hamburg remain underpenetrated by integrated customs brokerage platforms.
- AI-driven predictive routing:Machine learning convergence with telematics hardware is opening white space for delivery reliability guarantees that command premium positioning over pure rate competition.
- Western region manufacturing migration:Sichuan and Chongqing production capacity expansion is creating demand for digital freight infrastructure in previously underserved interior logistics nodes.
Industry Challenges
- Software engineering talent scarcity:Logistics technology platforms compete with consumer internet giants for full-stack developers capable of building real-time matching engines at scale.
- Legacy TMS integration complexity:Enterprise shippers operate heterogeneous enterprise resource planning systems that resist standardized API connectivity without costly middleware development.
- Electronic data interchange certification timelines:GB compliance validation for electronic bills of lading requires extended testing cycles that delay platform commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Digital Freight Forwarding Market |
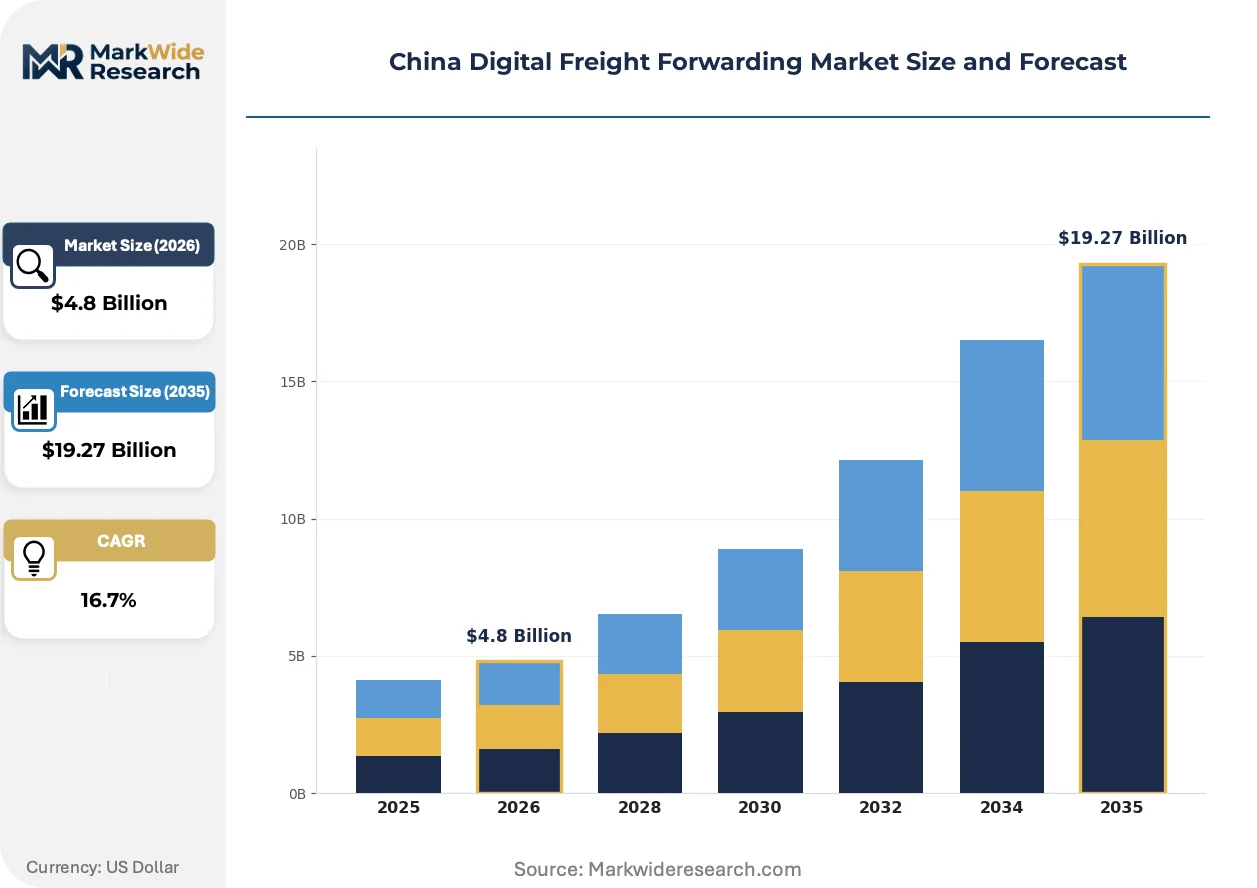
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Air Freight, Ocean Freight, Ground Transport, Customs Brokerage Technology: Blockchain, Artificial Intelligence, IoT Integration, Cloud Computing End User: E-commerce, Retail, Manufacturing, Automotive Delivery Model: Door-to-Door, Port-to-Port, Intermodal, Express Service |
| Companies Covered | SINO SHIPPING, Kuehne + Nagel International AG, Full Truck Alliance, YouTrans, Freightos, Flexport, Cogoport, FreightBro, DHL Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Digital Freight Forwarding Market Strategic Shifts
Algorithmic orchestration of cargo movement is supplanting traditional broker-mediated matching, compressing quotation cycles from days to seconds while reshaping how shippers evaluate forwarder relationships.
Artificial intelligence applications in predictive routing are supplanting static rate-card procurement for time-sensitive shipments. Automotive and electronics manufacturers operating just-in-sequence supply chains are adopting these capabilities fastest. The structural consequence is a market bifurcation between reliability-premium providers and commodity rate aggregators.
MIIT's logistics digitization mandates are accelerating API interoperability requirements between enterprise shippers and forwarder platforms. Industrial consequence includes forced rearchitecture of data pipelines to accommodate real-time customs pre-clearance. Cross-border e-commerce segments are responding by consolidating vendor relationships onto compliant single-window platforms.
Shipper procurement patterns are compressing contract durations as spot-market liquidity improves. Annual rate agreements are giving way to quarterly or monthly engagements with dynamic adjustment clauses. This behavioral shift is most visible among apparel and consumer electronics exporters in the Yangtze River Delta corridor.
China Digital Freight Forwarding Market Segmentation
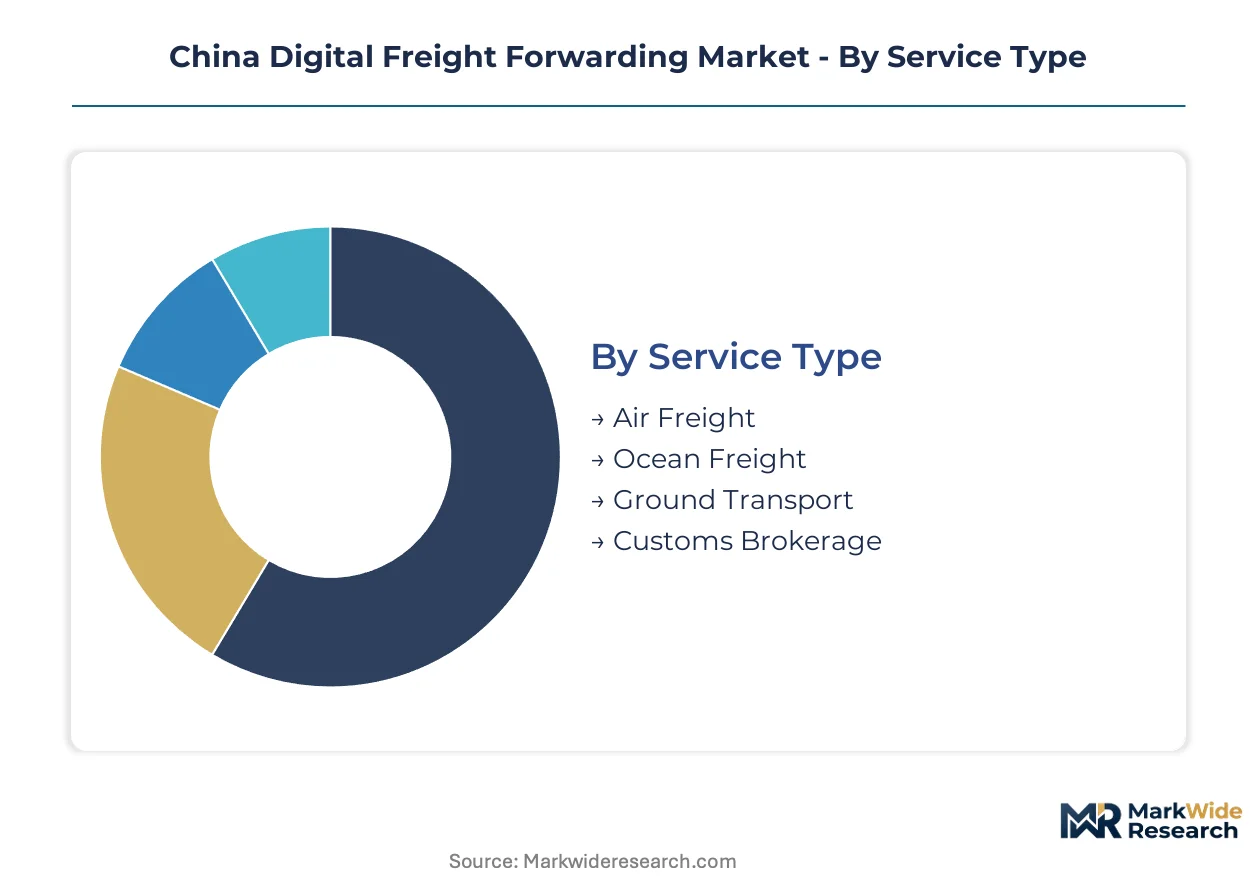
Service configurations across China's digital freight sector determine which technology investments platforms prioritize and which regulatory compliance pathways dominate operational architecture. Segment boundaries are blurring as multimodal orchestration becomes standard, yet procurement behavior still clusters around distinct delivery expectations and documentation requirements.
Service Type:
Channel-mix dynamics vary sharply across service categories, with ocean freight flowing predominantly through enterprise sales teams while ground transport concentrates on self-serve platform interfaces.
- Ocean Freight:Documentation complexity around vessel capacity volatility and customs pre-clearance creates the largest margin pool. Demand concentrates among Yangtze River Delta exporters shipping to Rotterdam and Hamburg, where MIIT's digitization mandates are compressing paper-to-digital transition timelines.
- Ground Transport:Real-time matching algorithms connect fragmented domestic trucking capacity to manufacturing clusters. Sichuan and Chongqing production expansion is pulling platform infrastructure investment into previously underserved interior nodes.
- Air Freight:Time-sensitive electronics and pharmaceutical shipments dominate lane selection. Premium positioning depends on predictive reliability guarantees rather than pure rate competition.
- Customs Brokerage:Integrated workflow platforms are consolidating previously standalone broker relationships. SAMR antitrust provisions constrain exclusive carrier lock-in strategies.
Ocean freight dominates installed base. Ground transport is where expansion concentrates.
Technology:
Cost tier differentiation separates enterprise-grade infrastructure investments from mid-tier platform configurations, with AI and cloud computing commanding premium positioning against blockchain pilots.
- Artificial Intelligence:Predictive routing engines consuming telematics data streams enable delivery reliability guarantees. Automotive and electronics manufacturers operating just-in-sequence supply chains are adopting these capabilities fastest.
- Cloud Computing:Elastic infrastructure supports instantaneous rate quotation and capacity matching across fragmented markets. Compute expenditure volatility compresses margins for operators without scale economies.
- IoT Integration:Sensor hardware deployment across refrigerated containers and dry van fleets generates visibility data. Hardware certification cycles delay platform commercialization.
- Blockchain:Electronic bill of lading validation and smart contract settlement remain pilot-phase. GB standards for electronic waybill formatting are eliminating proprietary protocol fragmentation.
Cloud computing anchors current infrastructure spend. Artificial intelligence is climbing the fastest as shippers prioritize reliability over cost minimization.
End User:
Application-specific requirements reshape platform feature prioritization, with e-commerce demanding real-time visibility APIs while manufacturing prioritizes ERP integration depth.
- E-commerce:Cross-border merchants along the Shanghai-Hangzhou-Ningbo corridor consolidate procurement onto unified platforms. Multi-country destination complexity drives single-window vendor consolidation.
- Manufacturing:Just-in-sequence supply chains require predictive routing with dynamic adjustment clauses. Legacy TMS integration complexity resists standardized API connectivity without middleware development.
- Automotive:Component sequencing tolerates minimal delivery variance. Tier-one suppliers are contracting for reliability-premium positioning over commodity rate aggregation.
- Retail:Seasonal volume spikes favor spot-market liquidity over annual rate agreements. Quarterly or monthly engagements with dynamic clauses are displacing fixed contracts.
Manufacturing commands the deepest integration requirements. E-commerce is gaining share fastest as platform adoption accelerates among Yangtze River Delta merchants.
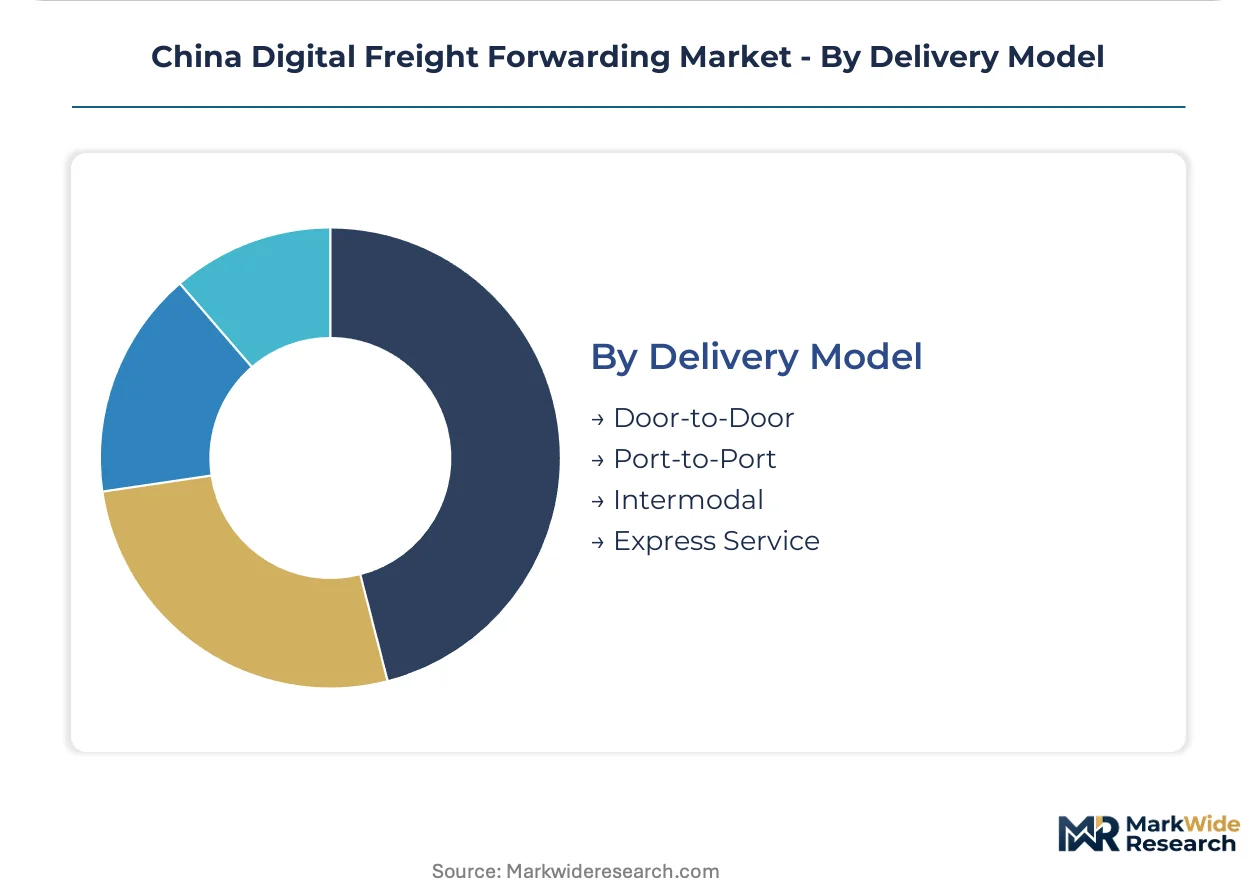
Delivery Model:
Customer type stratification separates enterprise shippers seeking control over handoff points from small merchants prioritizing convenience and price transparency.
- Door-to-Door:Full custody chains minimize shipper coordination burden. Apparel and consumer electronics exporters are compressing contract durations as platform liquidity improves.
- Intermodal:Rail-truck-ocean orchestration requires API interoperability between modal operators. MIIT mandates are forcing rearchitecture of data pipelines to accommodate real-time handoff visibility.
- Port-to-Port:Traditional forwarder relationships persist where customs complexity exceeds platform automation maturity. European trade corridors remain underpenetrated by integrated brokerage platforms.
- Express Service:Premium positioning depends on guaranteed transit windows rather than rate competition. Documentation pre-clearance capabilities separate providers.
Door-to-door dominates merchant adoption. Intermodal is where infrastructure investment concentrates as multimodal digitization mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's logistics digitization mandates anchor competitive dynamics across Chinese provinces, forcing platform rearchitecture to meet API interoperability deadlines while manufacturing migration reshapes demand geography.
Yangtze River Delta
Cross-border e-commerce merchants concentrate freight procurement onto unified platforms to manage multi-country destination complexity. GB standards for electronic waybill formatting eliminate paper-based friction in multimodal handoffs. Shanghai, Hangzhou, and Ningbo form the corridor where ocean freight digitization currently occupies the largest margin pool.
Pearl River Delta
Electronics manufacturers operating just-in-sequence supply chains adopt AI-driven predictive routing capabilities fastest. SAMR antitrust enforcement constrains dominant marketplaces from exclusive carrier contracts. Shenzhen and Guangzhou anchor demand for real-time visibility APIs connecting shippers to fragmented trucking capacity.
Beijing-Tianjin-Hebei
Automotive tier-one suppliers contract for reliability-premium positioning over commodity rate aggregation. Dual carbon goals incentivize route optimization algorithms that minimize empty-mileage across domestic networks. Tianjin port operations drive customs brokerage platform consolidation onto single-window interfaces.
Sichuan-Chongqing
Western region manufacturing migration creates demand for digital freight infrastructure in previously underserved interior logistics nodes. Cloud infrastructure cost volatility compresses margins for mid-tier platform operators without scale economies. Chongqing's expanding production capacity pulls platform investment inland from coastal clusters.
Shandong Peninsula
Legacy TMS integration complexity resists standardized API connectivity without costly middleware development for enterprise shippers. Driver-network concentration leaves interior provinces with thinner matching liquidity and rate instability. Qingdao and Yantai ports remain underpenetrated by integrated customs brokerage platforms for European trade corridors.
China Digital Freight Forwarding Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with domestic platform operators and international forwarders occupying distinct competitive spaces. The structure fragments across technology archetypes rather than consolidating around pure scale. Algorithmic orchestration specialists, ocean freight digitizers, and driver-network aggregators represent three strategic postures. Capacity expansion through cloud infrastructure investment and strategic partnerships for customs brokerage integration dominate competitive moves.
Within the domestic platform tier, Full Truck Alliance exemplifies driver-network density strategies, while Kuehne + Nagel International AG anchors international ocean freight digitization. Flexport occupies a position integrating customs brokerage workflows directly into platform interfaces, representing the convergence archetype between technology and traditional forwarding.
| Leading Market Players |
|---|
| SINO SHIPPING |
| Kuehne + Nagel International AG |
| Full Truck Alliance |
| YouTrans |
| Freightos |
| Flexport |
| Cogoport |
| FreightBro |
| DHL Group |
| Others |
Value Chain & Pricing Dynamics
Algorithmic rate quotation is displacing traditional broker-mediated pricing, compressing procurement cycles while simultaneously redistributing freight volume toward platform-dense coastal corridors and away from interior nodes with thinner matching liquidity. This substitution simultaneously concentrates pricing power among Yangtze River Delta platforms and erodes rate stability in Sichuan-Chongqing manufacturing zones.
Pricing Analysis
Rate spreads between Shanghai-Ningbo corridor lanes and western interior routes exceed those observed in any other major freight market. Three-tier pricing structure across premium, standard, and economy levels segments procurement behavior, with automotive tier-one suppliers occupying the premium reliability tier and spot-market apparel exporters dominating economy positioning. Pricing pressure stems from cloud infrastructure cost volatility compressing margins for mid-tier operators. E-commerce merchants exhibit highest price sensitivity, while just-in-sequence automotive manufacturers prioritize reliability guarantees over rate minimization.
Supply Chain Analysis
China anchors cloud computing infrastructure deployment for freight platforms, while Taiwan and South Korea supply critical semiconductor components for IoT telematics hardware. Software engineering talent scarcity in logistics technology draws from the same talent pools as consumer internet giants. Supply chain risk centers on single-source vulnerability in driver-network aggregation around tier-one manufacturing clusters. Distribution runs through API-interoperable platform interfaces connecting enterprise shippers to fragmented domestic trucking capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's digital freight forwarding sector is recovering from a cyclical trough driven by cross-border e-commerce platform consolidation, with procurement patterns normalizing as merchants rebuild inventory positions.
For Market Incumbents: Consolidate driver-network density in the Yangtze River Delta corridor to defend pricing power against emerging platform entrants. Deepen customs brokerage integration for European trade corridors before MIIT digitization mandates crystallize compliance-driven vendor switching. Prioritize backward integration into predictive routing AI development to offset software engineering talent scarcity. For New Entrants and Emerging Players: Differentiate on Sichuan-Chongqing interior logistics infrastructure, where manufacturing migration has outpaced platform investment. Target European trade corridor digitization as the most penetrable white space, with ocean freight workflows to Rotterdam and Hamburg remaining underdeveloped. Pursue direct customs pre-clearance certification as the primary go-to-market wedge. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed domestic platform operators that consolidated during the 2021-2023 capacity glut. Long-term viability hinges on API interoperability compliance rather than pure network scale. Monitor MIIT enforcement timelines as the critical inflection signal for platform rearchitecture spending cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API interoperability investments satisfy MIIT mandates while locking in enterprise shipper relationships. |
| Strategic Partnership | Customs brokerage alliances accelerate European trade corridor penetration beyond organic development timelines. |
| Geographic Expansion | Sichuan-Chongqing infrastructure deployment captures western manufacturing migration before incumbent platform density solidifies. |
| Acquisition of Specialist Firm | Predictive routing AI specialists address software engineering talent scarcity through capability absorption. |
| Product Launch | Reliability-guarantee service tiers command premium positioning over commodity rate aggregation for automotive clients. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with freight platform executives, logistics software engineers, cross-border e-commerce procurement directors, and MIIT policy researchers; and secondary validation through SAMR regulatory filings, MIIT digitization mandate documentation, GB standards repositories, and customs trade flow databases. Bottom-up platform revenue triangulation against top-down addressable market sizing anchored volume estimates.
Across the analysis window, the forecasting framework modeled service type segmentation, technology tier differentiation, end-user vertical clustering, and delivery model stratification alongside regional adoption intensity. CAGRs derived from platform transaction volume trajectories, e-commerce export growth elasticities, and digitization mandate compliance timelines. Cloud infrastructure spend curves and driver-network density metrics fed predictive routing adoption scenarios.
Decision-makers should treat outputs as directional under sustained cross-border e-commerce growth and MIIT enforcement continuity; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in regulatory compliance deadlines and manufacturing migration patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
GCC Air Freight Transport Market
Logistics and Shipping
Last Mile Delivery Transportation Market
Logistics and Shipping
Europe Sea Freight Forwarding Market
Logistics and Shipping
Delivery Tracking Platform Market
Logistics and Shipping
Global Port Logistics Market
Logistics and Shipping
Asia Pacific Domestic Courier Market
Logistics and Shipping
Canada 3PL Market
Logistics and Shipping
Europe Third Party Logistics Market
Logistics and Shipping
UK Logistics Market
Logistics and Shipping
China Cold Chain Logistics Market
Logistics and Shipping
Intralogistics Containers Market
Logistics and Shipping
Germany Last Mile Delivery Market
Logistics and Shipping
Latin America Fourth Party Logistics (4PL) Market
Logistics and Shipping
China Freight and Logistics Market
Logistics and Shipping
North America Freight Brokerage Market
Logistics and Shipping
Remanufacturing and Core Returns Logistics Management Market