
 Air Freight Market | 2026-2036
Air Freight Market Size, Share, and Industry Trends Forecast 2026-2036
Air Freight Market Intelligence
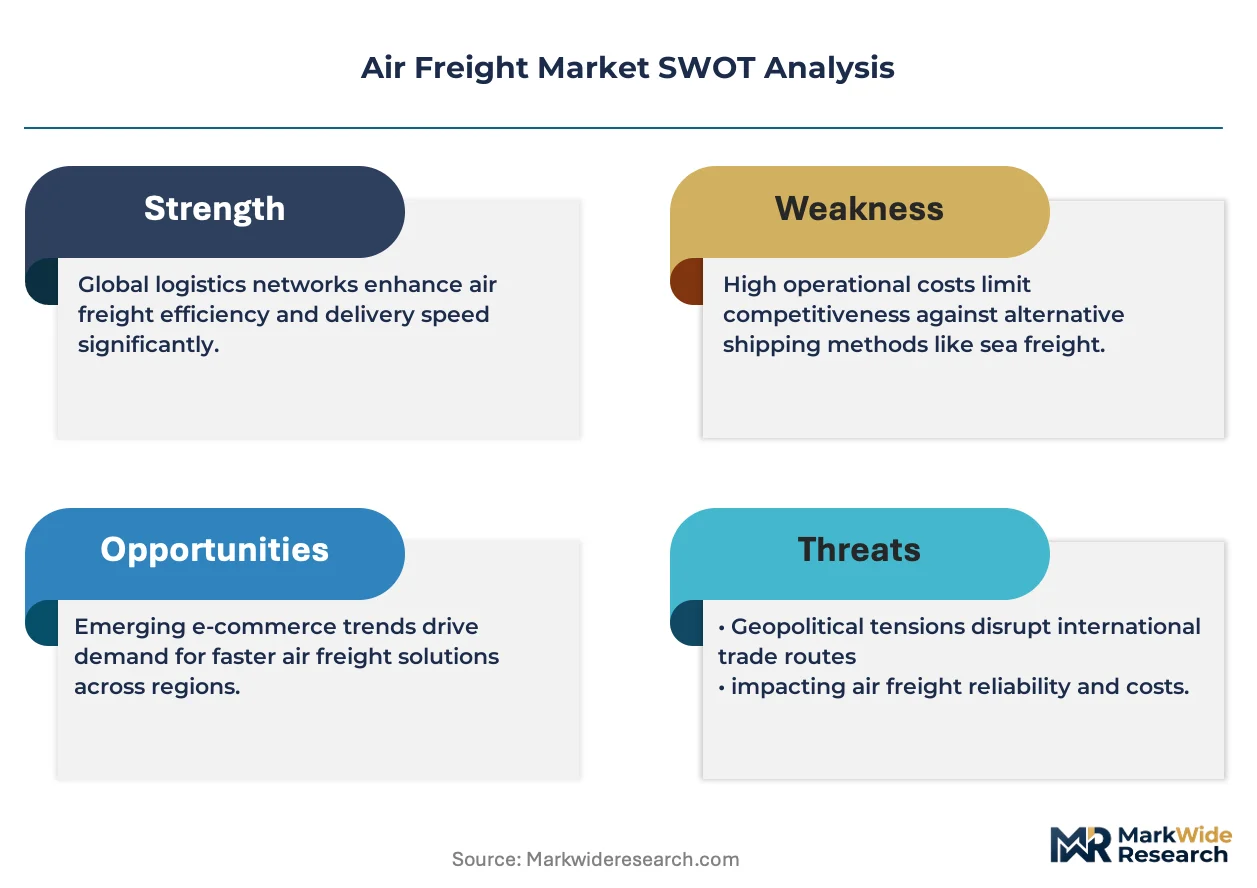
Airport-to-airport forwarding is fragmenting as e-commerce platforms build direct carrier relationships and bypass traditional consolidators. FedEx Express leverages its Memphis superhub to sustain time-definite dominance across North American lanes. Emirates SkyCargo anchors long-haul belly capacity through Dubai, while Cargolux specializes in outsized and project cargo with its all-freighter 747-8 fleet.
Air freight encompasses the commercial transport of goods via fixed-wing aircraft, operating within weight-and-balance limits typically from 100 kg to over 100 tonnes per consignment and requiring IATA-compliant dangerous goods documentation where applicable. Express Delivery captures premium margin pools from pharmaceutical cold chains and just-in-time manufacturing inputs, while Perishable Goods represents the fastest-growing product category as temperature-controlled packaging extends shelf-life integrity across intercontinental lanes. General Cargo still occupies the largest volume share but faces margin compression from ocean-air intermodal alternatives on less time-sensitive routes.
The EU Green Deal's F-Gas Regulation and ICAO's Carbon Offsetting and Reduction Scheme for International Aviation tighten emissions accountability, forcing carriers to accelerate sustainable aviation fuel offtake or risk slot restrictions at European hubs. The FAA's Part 121 safety standards and OSHA cargo handling protocols shape ground operations liability and insurance structures across US terminals. Stakeholders must monitor SAF certificate liquidity and bilateral open-skies negotiations, as these mechanisms will determine which carriers retain network flexibility and which face stranded capacity.
Market Dynamics
E-commerce fulfillment networks are collapsing traditional forwarding hierarchies by pulling capacity directly into express delivery lanes, bypassing legacy consolidators and reshaping how carriers monetize belly-hold and freighter assets.
Growth Catalysts
- EU Green Deal F-Gas Regulation:The emissions trading scheme forces fleet renewal toward sustainable aviation fuel compatibility, creating compliant capacity premiums at Amsterdam and Frankfurt hubs.
- Pharmaceutical cold chain expansion:Temperature-controlled packaging advances extend shelf-life integrity for biologics, pulling high-yield express volumes onto intercontinental lanes from Belgium and Singapore manufacturing clusters.
- Dubai logistics free zones:Jebel Ali's bonded infrastructure and open-skies bilateral density anchor transhipment growth between Africa, South Asia, and European consumer markets.
Market Restraints
- Jet fuel price volatility:Kerosene constitutes 25-30% of operating costs for freighter operators, compressing margins on long-haul routes when Brent crude spikes.
- Freighter feedstock scarcity:Boeing 777-300ER and A330 passenger-to-freighter conversion slots concentrate at Israel Aerospace Industries and Singapore Technologies, creating 18-month delivery backlogs.
- Ocean-air intermodal substitution:Sea freight from Shanghai to Los Angeles followed by domestic air leg captures 40% cost savings versus direct air for sub-7-day lead time tolerance.
Strategic Opportunities
- India pharmaceutical exports:Hyderabad and Ahmedabad bulk drug clusters lack direct freighter capacity to North American markets, creating white space for dedicated lane development.
- Warehouse automation convergence:Autonomous mobile robots and AI-powered dimensioning systems reduce parcel handling time by 40% at ground facilities, enabling hub-and-spoke density without proportional labor expansion.
- ICAO Carbon Offsetting and Reduction Scheme:CORSIA phase-in creates certified emission reduction arbitrage for early SAF adopters, locking in network access advantages at EU and UK airports.
Industry Challenges
- Certified dangerous goods handlers:IATA DGR-qualified personnel shortages constrain pharmaceutical and lithium battery throughput at secondary airports in Vietnam and Indonesia.
- Legacy cargo management system integration:Mainframe-based weight-and-balance software at established carriers resists API connectivity with e-commerce platform order management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Freight Market |
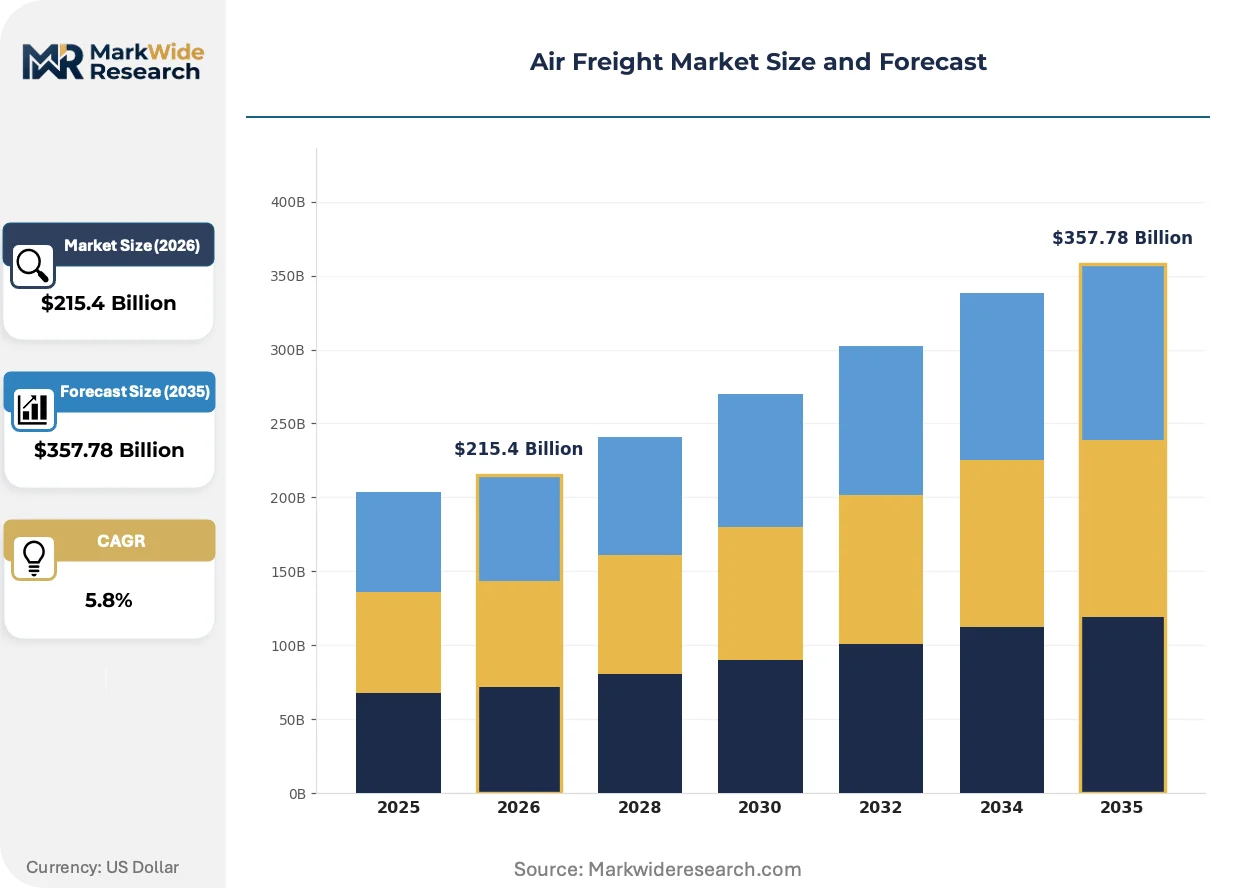
| Market Size in 2026 | $215.4 Billion |
| Market Size in 2035 | $357.78 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express Delivery, Cargo Charter, Standard Freight, Door-to-Door Product Type: General Cargo, Perishable Goods, Pharmaceuticals, Hazardous Materials End User: E-Commerce, Retail, Manufacturing, Healthcare Delivery Mode: Airport-to-Airport, Direct Delivery, Consolidated Shipment, Intermodal |
| Companies Covered | FedEx Express, UPS Airlines, Emirates SkyCargo, Qatar Airways Cargo, Cargolux, Kuehne + Nagel, DHL Supply Chain & Global Forwarding, Lufthansa Cargo, Atlas Air, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Freight Market Strategic Shifts & Innovations
Digital freight platforms and sustainable aviation fuel certification mechanisms are rewriting how capacity is priced, allocated, and verified across lane networks previously governed by bilateral agreements and paper airway bills.
Artificial intelligence-powered demand forecasting is collapsing the information asymmetry between carriers and forwarders that historically sustained spot-rate volatility. Pharmaceutical shippers in Switzerland and Massachusetts now deploy machine learning models predicting lane congestion 14 days forward, shifting volume to secondary gateways like Huntsville and Liège before capacity crunches materialize. This transparency compression erodes the margin pools that legacy consolidators extracted from opaque capacity access.
ReFuelEU Aviation mandates binding SAF blending quotas rising to 70% by 2050, forcing carriers to secure offtake agreements with Neste, World Energy, and LanzaJet before certificate liquidity tightens. The regulation's extraterritorial reach covers all flights departing EU airports regardless of carrier registry, compelling Emirates, Qatar Airways, and Turkish Airlines to reconfigure fleet deployment or absorb compliance penalties into Dubai-Istanbul-Europe triangle economics.
Direct platform-to-carrier contracting is displacing traditional forwarder intermediation on high-velocity lanes. Amazon Air and Alibaba's Cainiao build dedicated freighter relationships with Atlas Air and AeroLogic, extracting volume commitments that freeze out neutral consolidators on Shanghai-Liege and Cincinnati-Anchorage corridors. This channel compression concentrates pricing power with integrated e-commerce logistics networks while fragmenting residual general cargo into lower-yield spot markets.
Air Freight Market Segmentation
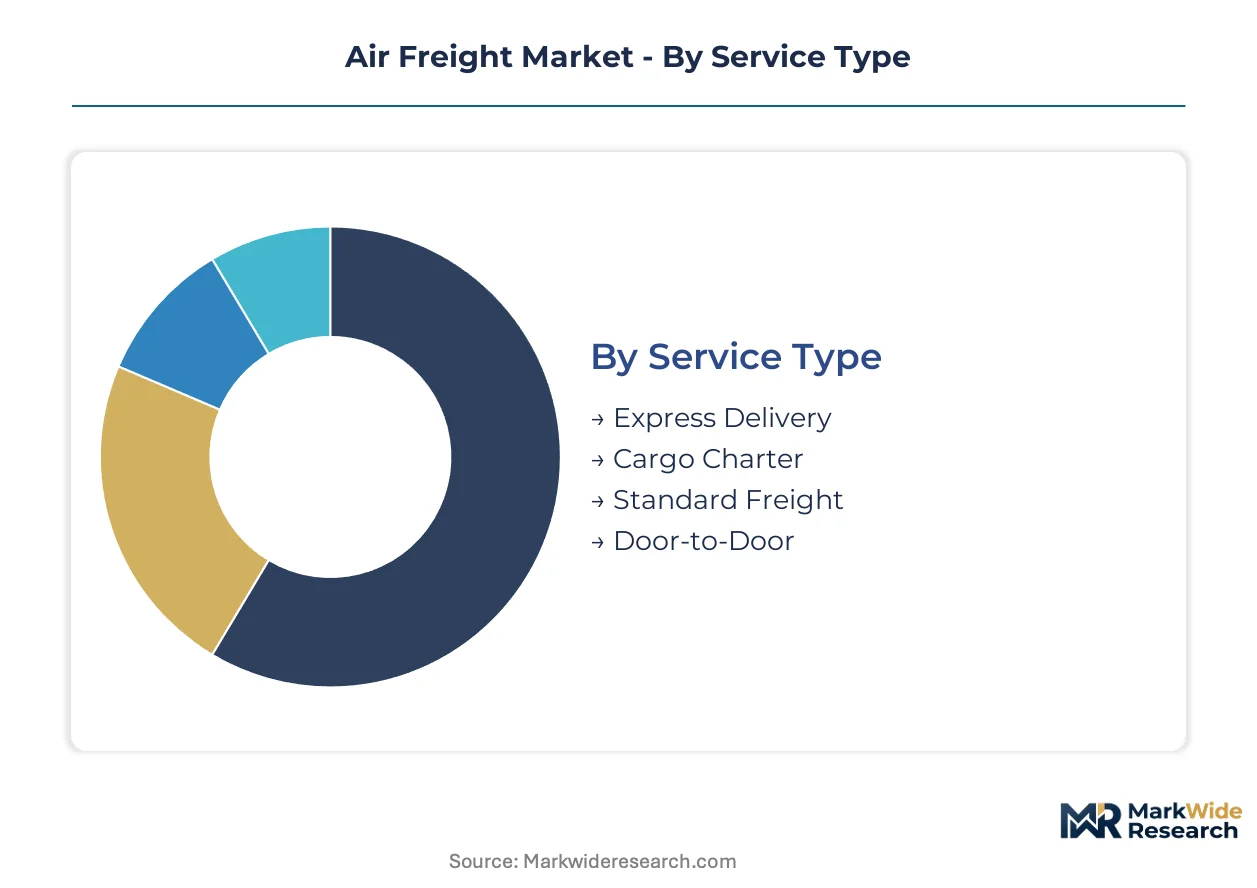
Air freight segmentation reveals how carriers monetize speed, temperature control, and handling complexity differently across lane networks. Service and product categories determine asset deployment, while end-user concentration shapes hub location strategies and ground infrastructure investment.
Service Type:
Mature consolidator models coexist with emerging platform-direct channels that collapse traditional forwarding hierarchies.
- Express Delivery:Time-definite service guarantees within 24-72 hours leverage dedicated freighter networks and superhub sorting infrastructure. Pharmaceutical cold chains and just-in-time manufacturing inputs from Belgium and Singapore manufacturing clusters pull premium volumes onto intercontinental lanes.
- Cargo Charter:On-demand aircraft deployment serves project cargo, humanitarian relief, and peak season overflow when scheduled capacity saturates. Mining equipment movements from Perth to West Africa and energy sector logistics from Houston to Kazakhstan generate episodic demand spikes.
- Standard Freight:Scheduled belly-hold and freighter space sold through forwarder networks accommodates less time-sensitive general cargo. Consolidation at Amsterdam and Frankfurt hubs captures cost-conscious shippers with 5-7 day lead time tolerance.
- Door-to-Door:Integrated pickup and last-mile delivery bundles customs brokerage and ground transport into single-contract solutions. E-commerce platforms in the United Arab Emirates and India increasingly specify this modality to bypass traditional forwarder intermediation.
Standard Freight handles the majority of throughput; Express Delivery is the fastest mover on share.
Product Type:
Cost tier stratification separates temperature-controlled premium cargo from commoditized general freight competing with ocean-air intermodal alternatives.
- General Cargo:Unspecialized manufactured goods, machinery, and consumer products move via standard handling protocols without environmental controls. Margin compression intensifies as sea freight from Shanghai to Los Angeles followed by domestic air leg captures 40% cost savings versus direct air.
- Perishable Goods:Temperature-sensitive agricultural products, seafood, and flowers require continuous cold chain integrity from origin to destination. Chilean salmon exports to Miami and Kenyan flower shipments to Amsterdam drive dedicated freighter positioning on south-north lanes.
- Pharmaceuticals:Biologics, vaccines, and active pharmaceutical ingredients demand IATA CEIV Pharma certification and real-time temperature monitoring. Hyderabad and Ahmedabad bulk drug clusters lack direct freighter capacity to North American markets, creating white space for lane development.
- Hazardous Materials:Lithium batteries, chemicals, and radioactive substances require IATA DGR-compliant documentation and specialized handling infrastructure. Certified personnel shortages constrain throughput at secondary airports in Vietnam and Indonesia.
General Cargo dominates volume contribution; Perishable Goods exhibits the steepest expansion trajectory as temperature-controlled packaging extends shelf-life integrity.
End User:
Customer type concentration determines whether carriers prioritize hub-and-spoke density or point-to-point frequency in network design.
- E-Commerce:Platform-driven parcel volumes demand automated sortation and predictive capacity allocation. Amazon Air and Alibaba's Cainiao extract volume commitments that freeze out neutral consolidators on Shanghai-Liege and Cincinnati-Anchorage corridors.
- Retail:Seasonal inventory replenishment and fast fashion distribution require flexible capacity contracts with surge options. Zara's Spain-to-global distribution network exemplifies compressed lead time requirements.
- Manufacturing:Just-in-time component flows and production line feeding impose strict arrival windows. Automotive parts from Stuttgart to Alabama assembly plants and electronics from Shenzhen to Mexico maquiladoras sustain dedicated lane economics.
- Healthcare:Medical device and diagnostic specimen shipments prioritize reliability over cost minimization. Swiss and Massachusetts pharmaceutical shippers deploy machine learning models predicting lane congestion 14 days forward.
Manufacturing anchors contracted baseline capacity; E-Commerce is expanding most quickly as direct platform-to-carrier contracting displaces traditional forwarder intermediation.
Delivery Mode:
Supply concentration in bonded free zones versus fragmented origin points dictates modal selection and customs integration depth.
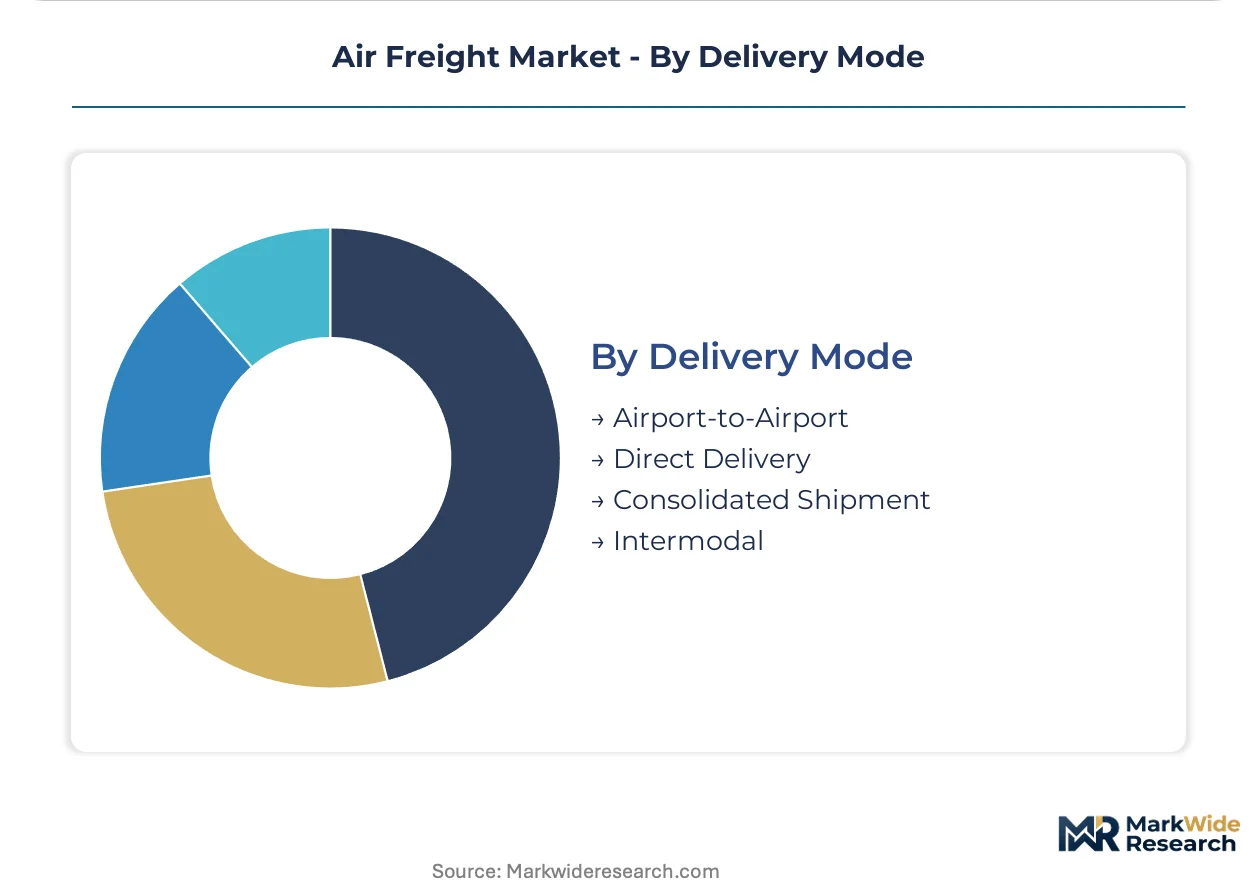
- Airport-to-Airport:Traditional forwarding model consigns goods to airline terminals for consignee pickup or onward arrangement. This modality fragments as e-commerce platforms build direct carrier relationships and bypass traditional consolidators.
- Direct Delivery:Point-to-point service eliminates intermediate handling for high-value or time-critical shipments. FedEx Express leverages its Memphis superhub to sustain time-definite dominance across North American lanes.
- Consolidated Shipment:Multiple consignments combined into single master air waybills achieve economies of scale for smaller shippers. Dubai's Jebel Ali bonded infrastructure anchors transhipment growth between Africa, South Asia, and European consumer markets.
- Intermodal:Ocean-air and road-air combinations optimize cost-speed tradeoffs for sub-7-day lead time tolerance. Sea freight from Shanghai to Los Angeles followed by domestic air leg exemplifies this hybrid approach.
Airport-to-Airport retains the largest volume base; Direct Delivery gains share fastest as integrated logistics networks internalize control over end-to-end velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's Jebel Ali Port and Al Maktoum International Airport anchor transhipment gravity between Africa, South Asia, and European consumer markets, while Memphis and Louisville superhubs sustain North American express density.
United States
E-commerce platform fulfillment networks pull dedicated freighter capacity into Cincinnati and Anchorage corridors, bypassing traditional forwarder intermediation. FAA Part 121 safety standards and OSHA cargo handling protocols shape ground operations liability across Memphis, Louisville, and Indianapolis superhubs. Pharmaceutical cold chain demand from Massachusetts biotech clusters drives temperature-controlled lane development to Brussels and Singapore.
Germany
Automotive just-in-time component flows from Stuttgart sustain dedicated freighter economics to Alabama and Mexico assembly plants. The EU Green Deal's F-Gas Regulation and ReFuelEU Aviation mandates force Lufthansa Cargo and Leipzig-based operators toward sustainable aviation fuel offtake agreements. Frankfurt and Cologne-Bonn hubs capture pharmaceutical transhipment from Swiss and Belgian manufacturing clusters under emissions trading compliance pressure.
China
Shanghai Pudong and Zhengzhou anchor electronics export flows to North American and European consumer markets, with Alibaba's Cainiao extracting direct carrier volume commitments. MIIT dual carbon goals and GB standards on aviation emissions accelerate domestic SAF production targets. Shenzhen-to-Mexico maquiladora lanes sustain contracted baseline capacity for automotive and electronics manufacturing inputs.
United Arab Emirates
Dubai's logistics free zones and open-skies bilateral density position Emirates SkyCargo as the dominant long-haul belly capacity provider between Africa and Asia. MOHAP pharmaceutical handling certifications and bonded Jebel Ali infrastructure attract cold chain transhipment from Hyderabad and Ahmedabad bulk drug clusters. Abu Dhabi's Etihad Cargo competes for African perishable and South Asian textile volumes through similar regulatory frameworks.
India
Hyderabad and Ahmedabad pharmaceutical exports lack direct freighter capacity to North American markets, creating white space for dedicated lane development. DGFT export promotion schemes and PLI scheme incentives for active pharmaceutical ingredients expand temperature-controlled shipment volumes. Bangalore electronics manufacturing clusters drive express delivery demand to European and US distribution networks.
Air Freight Market Key Industry Players
On the supply side, the industry is consolidating around integrated express networks, specialized freighter operators, and platform-direct channels that collapse traditional forwarding hierarchies. Three archetypes dominate: superhub-dependent integrators with time-definite guarantees, long-haul belly capacity providers anchored at geographic transhipment nodes, and all-freighter specialists serving outsized project cargo. Competitive moves concentrate on dedicated freighter procurement and sustainable aviation fuel offtake agreements that secure EU network access.
Among integrated express carriers, FedEx Express and UPS Airlines exemplify the superhub-dependent archetype, while Emirates SkyCargo occupies a position within the long-haul belly capacity tier. Cargolux represents the all-freighter specialist model with heavy-lift and project cargo orientation.
| Leading Market Players |
|---|
| FedEx Express |
| UPS Airlines |
| Emirates SkyCargo |
| Qatar Airways Cargo |
| Cargolux |
| Kuehne + Nagel |
| DHL Supply Chain & Global Forwarding |
| Lufthansa Cargo |
| Atlas Air |
| Others |
Cost & Logistics Intelligence
Freighter feedstock scarcity at Israel Aerospace Industries and Singapore Technologies—where 777-300ER and A330 conversion slots face 18-month backlogs—drives utilization premiums that compress spot-rate volatility while forcing long-term contract commitments from yield-sensitive pharmaceutical shippers.
Pricing Analysis
Three-tier pricing structure across express, standard, and deferred levels stratifies air freight according to temperature certification and speed guarantees. Express lanes commanding cold-chain premiums separate from standard belly-hold rates and ocean-air intermodal economy tiers. Pricing pressure stems from e-commerce platforms extracting volume commitments that freeze neutral consolidators out of high-velocity corridors. Pharmaceutical and healthcare buyers show least price sensitivity, while general cargo shippers with sub-7-day lead time tolerance migrate to sea-air alternatives.
Supply Chain Analysis
Extended payment terms from Dubai-based lessors and supply-chain finance facilities at Jebel Ali free zones ease freighter acquisition for carriers facing SAF compliance deadlines. Feedstock concentration in Israel, Singapore, and the United States for passenger-to-freighter conversions creates single-source vulnerability when geopolitical disruptions constrain slot access. Distribution runs through Memphis, Louisville, and Dubai superhubs that consolidate fragmented origin volumes into density-efficient trunk lanes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Air freight operates on a cyclical recovery trajectory as inventory destocking cycles reverse and e-commerce fulfillment networks rebuild safety stock positions.
For Market Incumbents: Harden dedicated freighter positions on pharmaceutical lanes from Hyderabad and Ahmedabad to North American markets before regional competitors secure bilateral traffic rights. Deepen backward integration into temperature-controlled ground infrastructure at Cincinnati and Anchorage to defend against platform-direct channel displacement by Amazon Air and Cainiao.
For New Entrants and Emerging Players: Build out white-space capacity on India-to-US pharmaceutical corridors where bulk drug clusters lack direct freighter service. Target secondary African perishable gateways—Nairobi flower exports, Johannesburg automotive components—where Emirates and Qatar Airways belly capacity saturates during peak seasons. Lead with CEIV Pharma certification as differentiation anchor.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across dedicated freighter fleets as ReFuelEU Aviation mandates accelerate SAF offtake commitments. Long-term viability favors carriers with locked-in Neste or World Energy supply agreements and European slot access. Watch CORSIA certificate liquidity as inflection signal—tightening markets reward early SAF adopters with network flexibility premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Sustainable Aviation Fuel Offtake Agreement | ReFuelEU mandates binding 70% blending quotas that determine EU network access for Emirates and Turkish Airlines. |
| Passenger-to-Freighter Conversion Slot Reservation | Boeing 777-300ER feedstock scarcity at Israel Aerospace Industries creates 18-month delivery backlogs for capacity expansion. |
| CEIV Pharma Certification Investment | Temperature-controlled handling credentials unlock Hyderabad and Ahmedabad biologics volumes to North American markets. |
| Superhub Automation Deployment | Autonomous mobile robots at Memphis and Louisville reduce parcel handling time by 40% without proportional labor expansion. |
| Direct Platform-Carrier Contracting | Amazon Air and Cainiao volume commitments freeze neutral consolidators out of Shanghai-Liege and Cincinnati-Anchorage corridors. |
Research Approach
Desk research of IATA cargo traffic databases, ICAO emissions filings, and EU ETS transaction records preceded structured interviews with cargo revenue management directors, freighter fleet planners, pharmaceutical logistics procurement leads, and ground handling operations managers. Primary fieldwork with Emirates SkyCargo, Lufthansa Cargo, and FedEx Express network planners cross-validated against secondary trade lane data from customs authorities and airport cargo throughput disclosures. Bottom-up capacity deployment models triangulated with top-down market sizing from bilateral traffic rights and slot allocation records.
Assumptions held fixed include ReFuelEU Aviation mandate phase-in schedules, CORSIA baseline carbon intensity thresholds, and existing open-skies bilateral frameworks. Variables included SAF production capacity buildout trajectories, e-commerce platform captive fleet expansion rates, and ocean-air intermodal elasticity coefficients across lane distance bands. Segmentation modeling covered service type, product temperature requirements, end-user industry concentration, and delivery mode integration depth. CAGRs derived from weighted average of capacity growth, yield trajectory, and load factor recovery assumptions.
Sensitivities concentrate around SAF certificate market liquidity, freighter conversion slot availability, and EU ETS price volatility. Forecasts reflect documented assumptions on regulatory compliance timelines and carrier fleet renewal decisions. Macroeconomic recession triggering inventory destocking, regulatory delay in CORSIA enforcement, or breakthrough in battery-electric regional freighter technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Spain Third-Party Logistics (3PL) Market
Logistics and Shipping
Mexico Freight and Logistics Market
Logistics and Shipping
India Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Global Air Cargo and Freight Logistics Market
Logistics and Shipping
Saudi Arabia Third-Party Logistics (3PL) Market
Logistics and Shipping
Project Logistics Market
Logistics and Shipping
Asia-Pacific Courier Market
Logistics and Shipping
Saudi Arabia Freight and Logistics Market
Logistics and Shipping
Global Dry Bulk Shipping Market
Logistics and Shipping
Mexico Containerized Shipping Market
Logistics and Shipping
Saudi Arabia Contract Logistics Market
Logistics and Shipping
Asia-Pacific Last Mile Delivery Market
Logistics and Shipping
Vehicle Routing and Scheduling Market
Logistics and Shipping
Colombia Freight and Logistics Market
Logistics and Shipping
Central and Eastern Europe Cold Chain Logistics Market
Logistics and Shipping
Latin America Air Freight Market