
 Singapore Shipping Agency Services Market | 2026-2036
Singapore Shipping Agency Services Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Shipping Agency Services Market Analytics
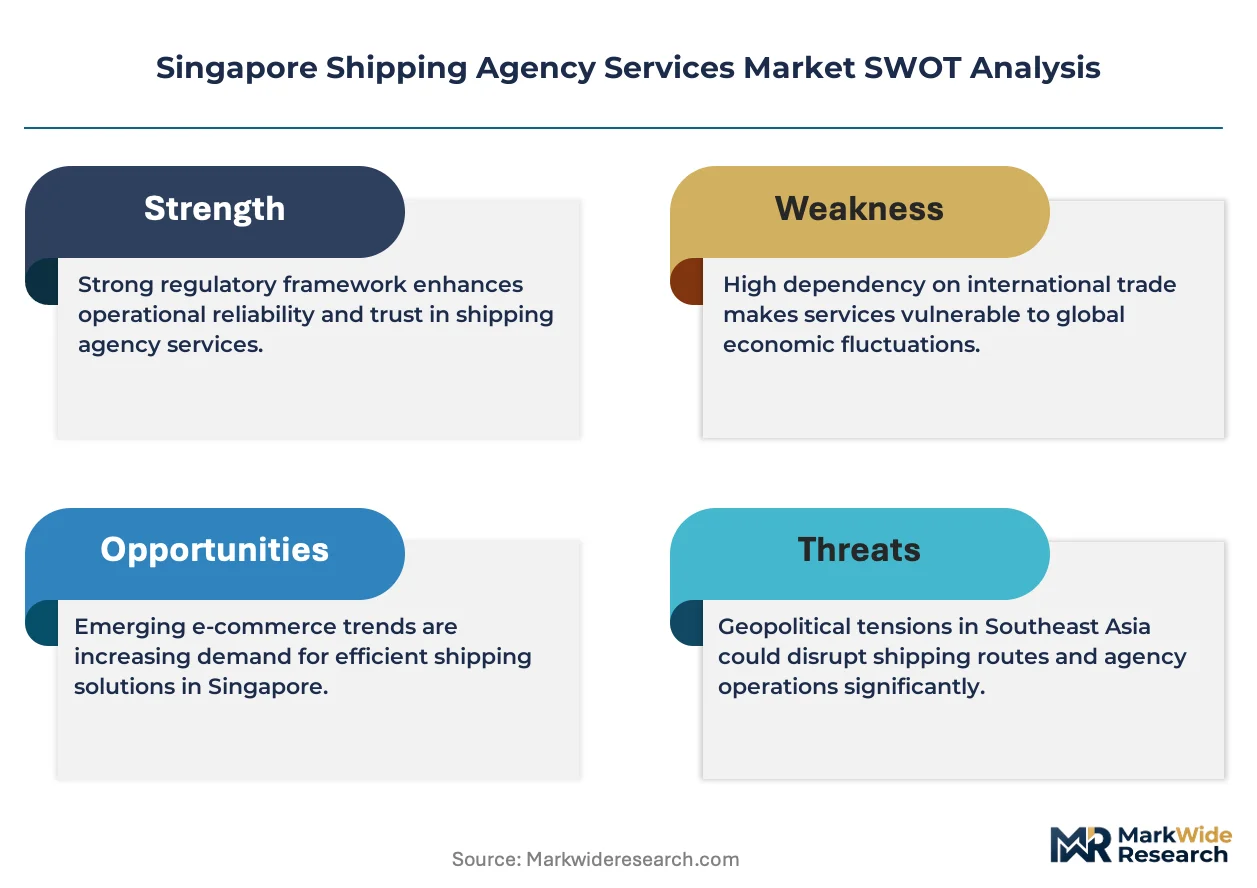
The capability gap between capital-heavy integrated operators and fragmented local agents is collapsing. Singapore Shipping Corporation Limited leverages its fleet ownership to sustain captive agency volumes across regional liner routes. AlfaShip Agencies anchors its position through specialized tanker and bulk carrier husbandry services. Sinoda Shipping Agency competes on documentation speed for intra-ASEAN short-sea trades.
Singapore shipping agency services encompass port representation, cargo coordination, customs documentation, and vessel husbandry performed under the authority of a shipowner or charterer. The function requires real-time integration with terminal operating systems, immigration protocols, and bunker scheduling to maintain port stay efficiency below twenty-four hours for mainline calls. Cargo handling and port operations command the largest revenue pools due to tonnage-based fee structures tied to container throughput. Customs clearance and documentation services are gaining structural importance as Singapore Customs advances its TradeFIRST framework and shippers prioritize duty optimization. Full agency services retain premium positioning against husbandry-only providers, though technology-enabled unbundling through tracking systems and data analytics platforms is fragmenting traditional service bundles.
Singapore's Maritime and Port Authority governs port licensing and safety compliance, while the Infocomm Media Development Authority shapes digital platform standards for maritime data exchange. The International Maritime Organization's emissions reporting frameworks, adopted into Singapore's Green Port Programme, are pushing agencies to validate bunker delivery documentation and carbon intensity indicators for vessel calls. Stakeholders must monitor how port community system mandates redistribute data control between incumbent agencies and technology intermediaries.
Market Dynamics
The Maritime and Port Authority's digital port clearance mandates are collapsing the traditional capability gap between capital-heavy integrated operators and fragmented local agents, forcing technology adoption across all service tiers.
Growth Catalysts
- Container shipping outsourcing:Mainline carriers are expanding agency delegation across Southeast Asian trade lanes, creating volume concentration at Singapore hub ports.
- TradeFIRST framework advancement:Singapore Customs' tiered trade facilitation program is elevating documentation services from commodity to strategic value-add.
- Green Port Programme integration:IMO emissions reporting requirements adopted into national policy are mandating validated bunker documentation and carbon intensity tracking for every vessel call.
Market Restraints
- Terminal operating system concentration:Port of Singapore's PSA infrastructure dominance creates single-point dependency for real-time cargo data integration.
- Specialized maritime talent scarcity:Licensed ship agents with dual competence in customs protocols and digital platform operation command premium compensation.
- Technology unbundling pressure:Tracking systems and data analytics platforms are fragmenting traditional full-service agency bundles into componentized offerings.
Strategic Opportunities
- Jurong anchorages expansion:Adjacent deep-water zones outside main terminal boundaries offer husbandry service specialization for tanker and bulk segments.
- Port community system intermediation:Maritime data exchange platforms are creating new revenue pools for technology-enabled agencies bridging legacy and digital workflows.
- Intra-ASEAN short-sea documentation:Regional trade lane growth is accelerating demand for rapid customs clearance speed as a competitive differentiator.
Industry Challenges
- Twenty-four-hour port stay compression:Mainline carrier scheduling demands require real-time integration across terminal operating systems, immigration protocols, and bunker scheduling.
- Infocomm Media Development Authority platform compliance:Digital standards for maritime data exchange are redistributing control between incumbent agencies and technology intermediaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Shipping Agency Services Market |
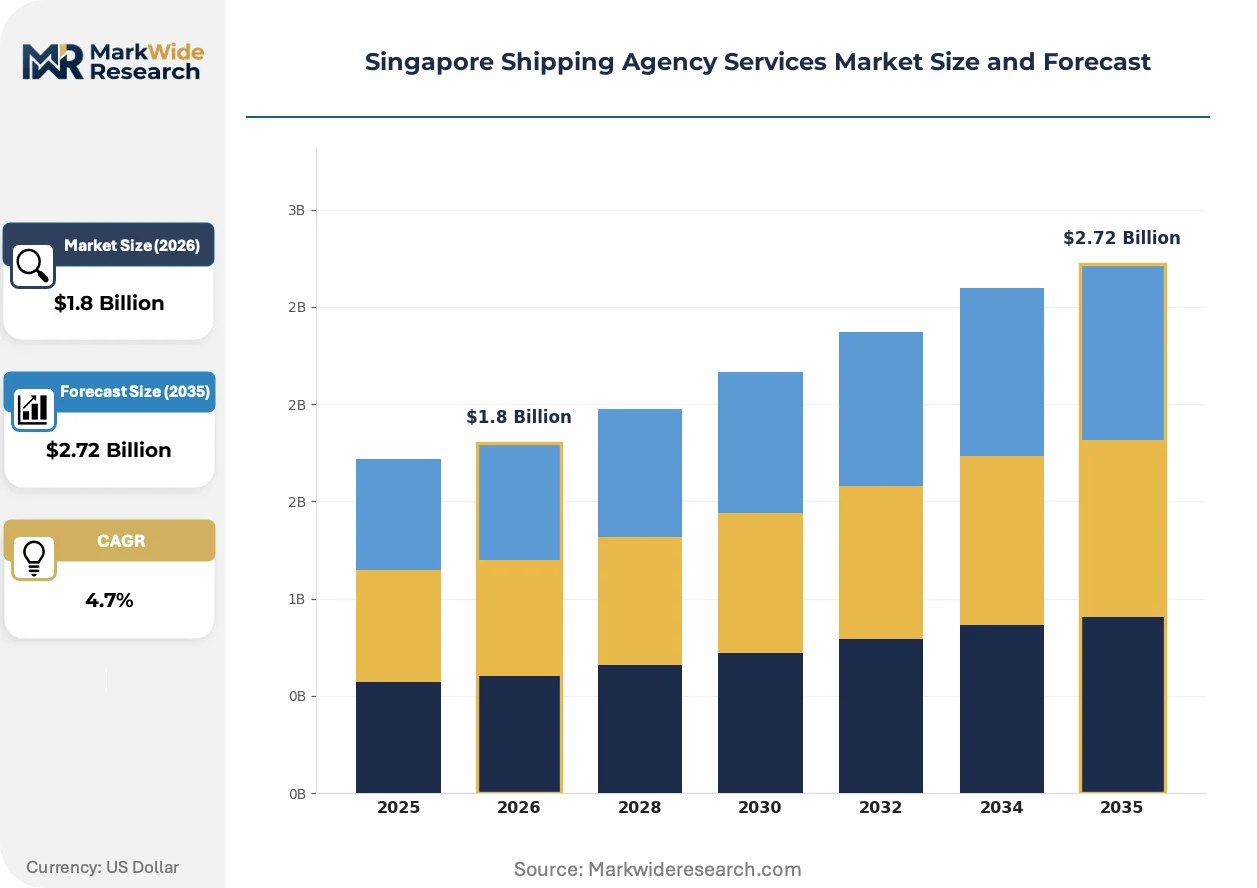
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cargo Handling, Documentation, Customs Clearance, Port Operations Customer Type: Importers, Exporters, Ship Owners, Freight Forwarders Offering: Full Agency Services, Husbandry Services, Port Agency Services, Professional Services Technology: Tracking Systems, Communication Tools, Data Analytics, E-commerce Platforms |
| Companies Covered | Singapore Shipping Corporation Limited, AlfaShip Agencies (Singapore) Pte Ltd, Sinoda Shipping Agency Pte Ltd, Golden Harvest Shipping Agency, Singapore Maritime Services, Nortrans, Trinity Shipping Agency (S) Pte Ltd, Straits Link Ship Agencies & Management Pte Ltd, Capital Shipping Agency (S) Pte Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Shipping Agency Services Market Evolving Landscape
Technology adoption is bifurcating the Singapore shipping agency landscape between platform-integrated operators and legacy documentation providers, with regulatory pressure accelerating the transition timeline.
Blockchain-enabled bunker delivery documentation is supplanting paper-based verification processes across Singapore port calls. Container lines and independent tanker operators are adopting distributed ledger systems for fuel provenance tracking within eighteen-month implementation windows. This shift is compressing dispute resolution cycles and reducing agency liability exposure for carbon intensity validation.
Singapore's Maritime and Port Authority licensing requirements now mandate real-time data exchange with port community systems for all vessel calls above specified tonnage thresholds. The industrial consequence is forced technology stack upgrades for mid-tier agencies previously operating on manual workflows. Full-service providers with captive IT development are capturing documentation speed premiums while husbandry-only specialists face margin compression.
Shippers are consolidating agency relationships around integrated port logistics capabilities rather than discrete service procurement. Container lines and commodity traders are bundling cargo handling, customs clearance, and vessel husbandry under single-provider contracts with performance-based fee structures. This consolidation is most visible among intra-ASEAN short-sea operators prioritizing documentation velocity over point-service cost minimization.
Singapore Shipping Agency Services Market Segmentation
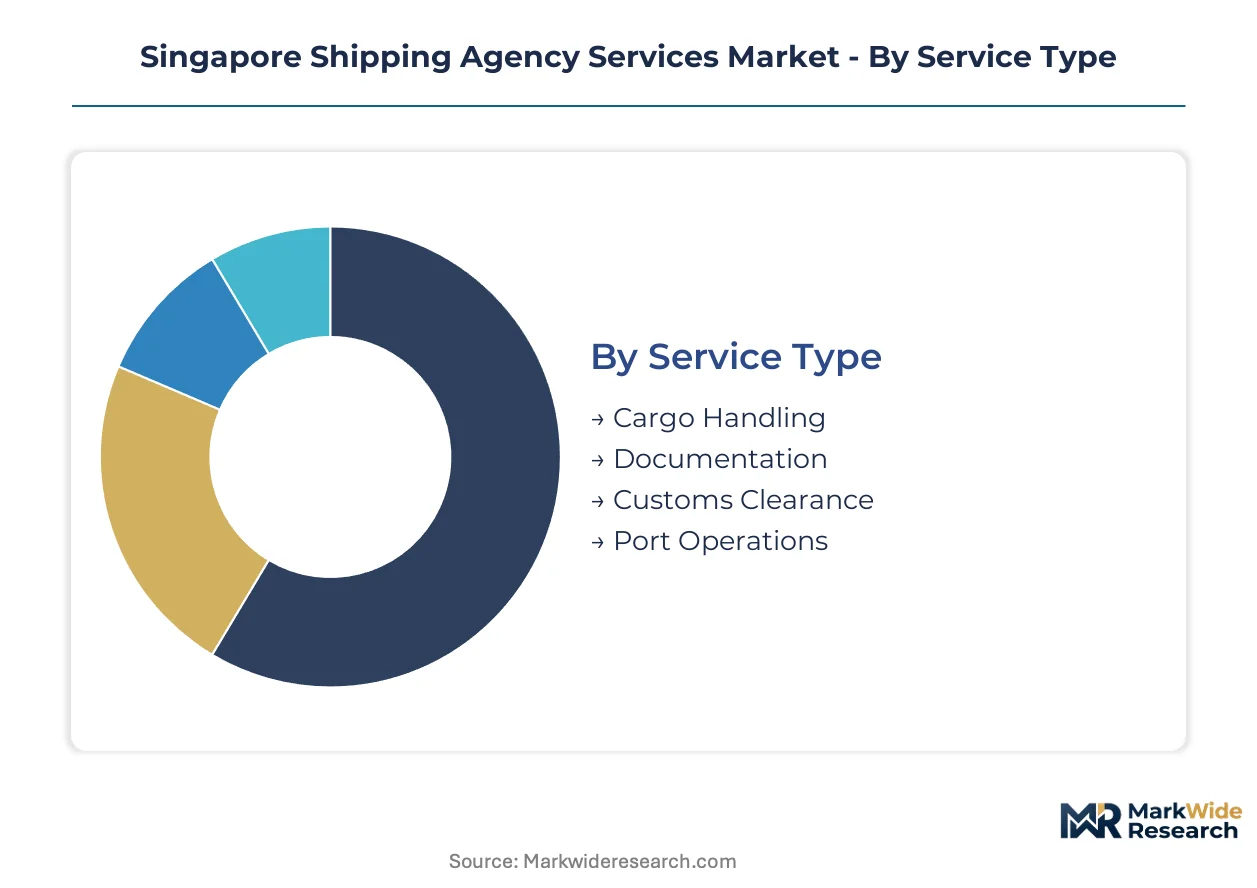
Singapore shipping agency services fragment across service delivery models, customer procurement patterns, and technology integration levels. Understanding these divisions reveals where margin pools concentrate and which capability investments yield competitive separation.
Service Type:
Domestic transshipment cargo dominates volume flows through the Port of Singapore, while export-led documentation services capture premium pricing from regional trade lane complexity.
- Cargo Handling:Physical coordination of container, bulk, and breakbulk movements between vessel and terminal. Demand concentrates at PSA Singapore terminals where tonnage-based fee structures tie revenue directly to container throughput volumes.
- Documentation:Preparation and submission of bills of lading, manifests, and port declarations. Singapore Customs TradeFIRST framework adoption is elevating this from administrative task to strategic compliance function for intra-ASEAN shippers.
- Customs Clearance:Duty optimization and regulatory filing services. Jurong Port and Tuas terminal operators drive specialized demand for bulk and project cargo classifications.
- Port Operations:Berth scheduling, pilotage coordination, and stevedoring oversight. Mainline carrier twenty-four-hour port stay mandates compress execution windows and reward real-time data integration capabilities.
Cargo Handling commands the established base. The steepest expansion runs through Documentation.
Customer Type:
Procurement patterns diverge sharply between asset-owning principals seeking captive control and intermediary traders prioritizing speed and cost arbitrage.
- Ship Owners:Principals with fleet assets demanding full agency representation across husbandry, documentation, and port coordination. Singapore-flagged and regional liner operators consolidate relationships around integrated service contracts with performance penalties.
- Freight Forwarders:Intermediaries procuring discrete services for cargo consolidation and multimodal coordination. NVOCCs and logistics integrators drive demand for API-connected documentation platforms enabling real-time status visibility.
- Importers:Manufacturing and commodity trading houses requiring customs clearance and last-mile coordination. Electronics and pharmaceutical shippers in Tuas industrial zones prioritize TradeFIRST tier certification for expedited processing.
- Exporters:Agricultural processors and industrial manufacturers seeking outbound cargo handling and export documentation. Palm oil and rubber traders across Jurong anchorages require specialized bulk cargo husbandry expertise.
Ship Owners anchor revenue concentration. Freight Forwarders are climbing the fastest as platform-enabled unbundling accelerates.
Offering:
Margin structures separate bundled full-service relationships from componentized husbandry and port-only arrangements.
- Full Agency Services:Comprehensive representation spanning vessel arrival through departure including cargo, documentation, and husbandry coordination. Container lines and commodity traders consolidate procurement here to reduce interface complexity and capture volume discounts.
- Port Agency Services:Terminal-focused coordination limited to berth scheduling, pilotage, and cargo operations. Regional short-sea operators with in-house documentation capabilities use this to control port stay costs.
- Husbandry Services:Crew change, provisioning, and vessel maintenance coordination. Tanker and bulk carrier operators across Singapore's eastern anchorage zones demand this specialization for extended port stays.
- Professional Services:Advisory on regulatory compliance, carbon intensity reporting, and bunker documentation validation. Green Port Programme mandates are expanding this category from niche to mandatory.
Full Agency Services retain the revenue base. Professional Services show the steepest trajectory as emissions compliance complexity deepens.
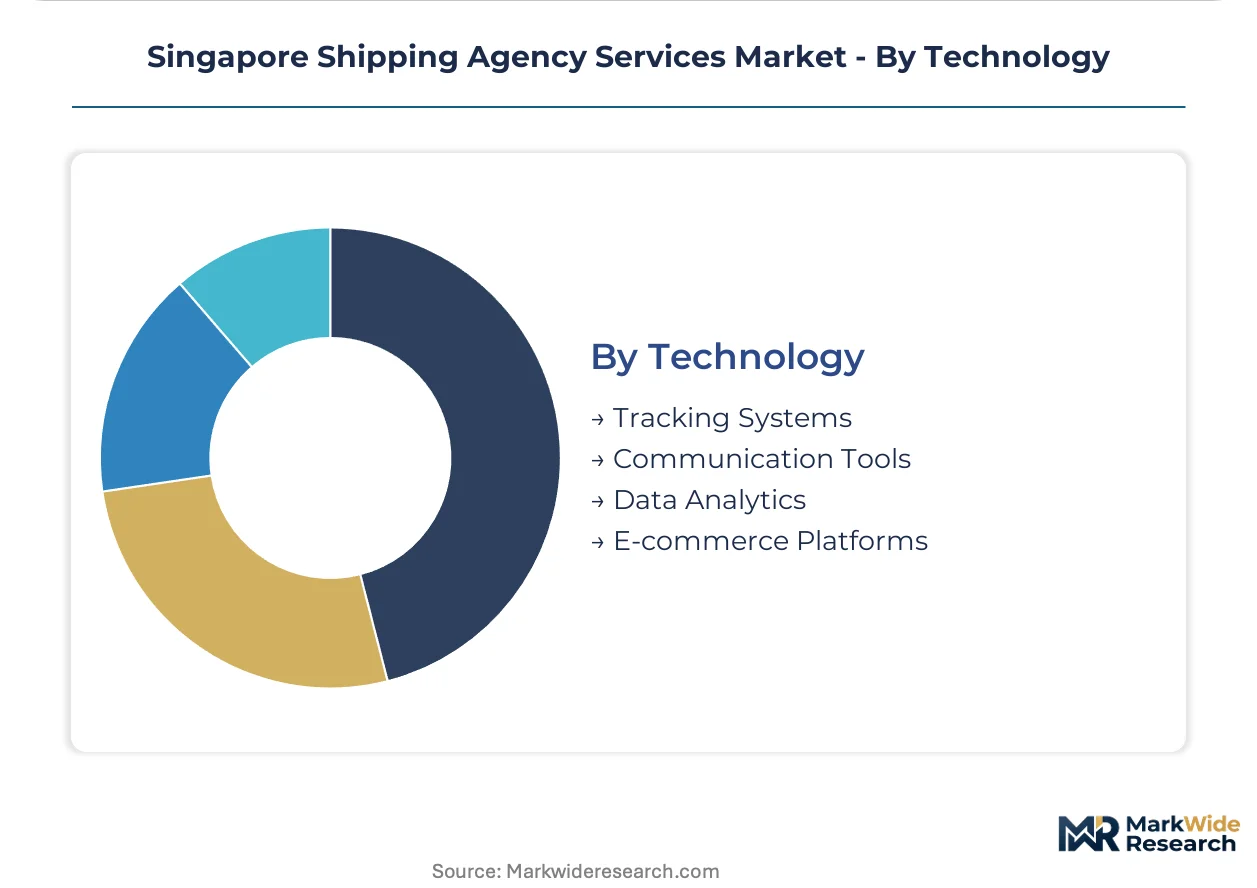
Technology:
Adoption intensity separates platform-integrated operators from legacy documentation providers facing forced upgrade cycles.
- Tracking Systems:Real-time container and vessel position monitoring through GPS and terminal operating system integration. Maritime and Port Authority port community system mandates are making this baseline rather than differentiating.
- Data Analytics:Predictive cargo flow optimization and port stay duration forecasting. Large integrated agencies deploy proprietary models to reduce demurrage exposure for bulk commodity clients.
- Communication Tools:Digital messaging platforms connecting ship agents with terminal operators, customs, and vessel masters. Standardization pressure from Infocomm Media Development Authority protocols is commoditizing this layer.
- E-commerce Platforms:Self-service portals for documentation submission and status tracking. Intra-ASEAN short-sea operators and SME shippers drive adoption for twenty-four-hour accessibility.
Tracking Systems represent the installed base. Data Analytics is gaining share fastest as predictive capabilities become procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's export-import balance tilts heavily toward transshipment cargo, with agency service demand radiating outward to neighboring Southeast Asian trade lanes. The Maritime and Port Authority's digital clearance mandates are reshaping service procurement patterns across the region.
Indonesia
Batam and Bintan anchorages drive cross-border husbandry demand for tanker operators seeking Singapore-licensed agency coordination. The country's national maritime regulator enforces port state control alignment with IMO conventions, pushing documentation standardization. Surabaya and Jakarta container terminals are expanding agency outsourcing as mainline carriers consolidate Southeast Asian hub strategies.
Malaysia
Port Klang and Tanjung Pelepas compete directly with Singapore for transshipment volumes, creating arbitrage opportunities for dual-licensed agents. The Malaysia Marine Department implements port clearance protocols that mirror Singapore's TradeFIRST framework. Johor Bahru's proximity to the Port of Singapore generates specialized demand for cross-border cargo coordination and crew change services.
Vietnam
Cai Mep deep-water terminals are attracting mainline carrier calls that require Singapore-based agency networks for regional coordination. The Vietnam Maritime Administration mandates electronic customs filing systems that interface with Singapore port community platforms. Ho Chi Minh City logistics clusters are driving demand for integrated documentation and customs clearance speed.
Thailand
Laem Chabang port expansion is pulling intra-ASEAN short-sea volumes that depend on Singapore agency networks for transshipment connectivity. The Port Authority of Thailand enforces container tracking requirements that accelerate technology adoption among service providers. Bangkok-based freight forwarders are consolidating procurement around agencies with real-time data integration capabilities.
Philippines
Manila and Subic Bay container terminals rely on Singapore agency partnerships for mainline carrier representation and bunker coordination. The Maritime Industry Authority implements crew change regulations that intersect with Singapore's immigration protocols. Cebu industrial zones are generating export documentation demand tied to regional electronics supply chains.
Singapore Shipping Agency Services Market Competitive Landscape
Concentration sits with integrated operators possessing captive fleet relationships and proprietary technology stacks. The market structure separates capital-heavy full-service providers from husbandry specialists and documentation-focused boutiques. Three archetypes dominate: fleet-linked integrated agencies, tanker-bulk specialists, and platform-enabled documentation providers. Competitive moves center on technology stack upgrades and strategic partnerships with port community system intermediaries.
Within the integrated tier, Singapore Shipping Corporation Limited anchors fleet-linked positioning through regional liner route coverage. AlfaShip Agencies and Sinoda Shipping Agency occupy specialized niches—tanker-bulk husbandry and short-sea documentation velocity respectively. These three represent the structural segmentation between asset-backed, segment-focused, and speed-driven competitive vectors.
| Leading Market Players |
|---|
| Singapore Shipping Corporation Limited |
| AlfaShip Agencies (Singapore) Pte Ltd |
| Sinoda Shipping Agency Pte Ltd |
| Golden Harvest Shipping Agency |
| Singapore Maritime Services |
| Nortrans |
| Trinity Shipping Agency (S) Pte Ltd |
| Straits Link Ship Agencies & Management Pte Ltd |
| Capital Shipping Agency (S) Pte Ltd |
| Others |
Value Network & Pricing Analysis
Blockchain-enabled bunker delivery documentation displaces paper-based verification across Singapore port calls, simultaneously compressing supply chain latency for carbon intensity validation and eroding traditional documentation premiums that once anchored agency margins.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium TradeFIRST-certified agencies, standard integrated operators, and economy documentation-only providers. Price differentiation hinges on customs clearance speed tiers and real-time port community system integration depth. Pricing pressure intensifies from technology unbundling as tracking platforms fragment traditional full-service bundles into componentized offerings. Freight forwarders exhibit highest price sensitivity due to thin NVOCC margins, while Singapore-flagged ship owners prioritize performance guarantees over unit cost.
Supply Chain Analysis
Inventory compression to sub-twenty-four-hour port stays eliminates buffer stocks for documentation and husbandry coordination, forcing just-in-time service delivery across PSA Singapore terminals and Jurong anchorages. Supply concentration rests on Singapore, Malaysia, and Indonesia for licensed ship agent talent pools and cross-border crew change logistics. Raw material dependencies include proprietary terminal operating system licenses, customs protocol certification programs, and bunker delivery verification infrastructure. Single-source vulnerability concentrates around PSA's cargo data integration chokepoints. Distribution runs through direct carrier contracts and freight forwarder intermediation channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore shipping agency services are cycling through a recovery phase driven by container shipping line outsourcing expansion across Southeast Asian trade lanes.
For Market Incumbents: Secure captive fleet relationships through backward integration into vessel ownership or long-term exclusive representation agreements. Deepen TradeFIRST tier certification investments to maintain documentation speed premiums against platform-enabled entrants. The Maritime and Port Authority's digital clearance mandates threaten legacy manual workflows; technology stack upgrades represent the critical defensive lever. For New Entrants and Emerging Players: Lead with specialized husbandry services for tanker and bulk carrier segments at Jurong anchorages, where integrated operators underinvest in extended port stay coordination. White-space targets include professional services for Green Port Programme emissions compliance and carbon intensity documentation validation. A go-to-market angle through port community system intermediation bridges legacy carrier workflows with digital platform requirements. For Investors and Strategic Acquirers: Maritime and Port Authority licensing requirements for real-time data exchange reshape the acquisition landscape toward technology-enabled mid-tier agencies with forced upgrade trajectories. Long-term viability centers on agencies with proprietary data analytics capabilities and captive regional liner relationships. Acquisition target archetypes include husbandry specialists with deep tanker-bulk expertise and documentation boutiques with TradeFIRST tier certification. The signal to watch is port community system mandate enforcement accelerating technology adoption timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Stack Modernization | Maritime and Port Authority mandates force real-time port community system integration for license retention. |
| TradeFIRST Certification Investment | Singapore Customs tier advancement elevates documentation services from commodity to strategic compliance function. |
| Husbandry Service Specialization | Jurong anchorages expansion creates defensible positioning for tanker and bulk carrier extended port stays. |
| Carbon Intensity Documentation Capability | Green Port Programme integration mandates validated bunker delivery tracking as mandatory service layer. |
| Regional Network Partnership | Intra-ASEAN short-sea trade growth requires cross-border agency coordination across Batam, Port Klang, and Laem Chabang. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Maritime and Port Authority regulatory filings, Singapore Customs TradeFIRST framework documentation, and container line procurement disclosures. Primary interviews engaged ship agency principals, carrier procurement directors, terminal operating system vendors, and licensed customs brokers across Singapore, Malaysia, and Indonesia. Secondary validation drew from Infocomm Media Development Authority platform standards, IMO emissions reporting frameworks, and PSA Singapore throughput statistics. Bottom-up service volume estimates triangulated against top-down market size benchmarks.
Segmentation dimensions modeled span service type, customer procurement pattern, technology integration level, and regional trade lane exposure across the analysis window. Cargo handling, documentation, customs clearance, and port operations segments were projected separately with CAGRs derived from tonnage throughput forecasts and fee structure elasticity assumptions. Forecast inputs incorporated mainline carrier port stay compression targets, digital clearance mandate implementation timelines, and intra-ASEAN short-sea trade lane expansion trajectories.
The analysis sits within stated boundaries; outcomes outside sustained container shipping outsourcing momentum or accelerated TradeFIRST adoption would require recalibration. Forecasts reflect assumptions around regulatory enforcement consistency and technology platform interoperability standards. Specific risks include terminal operating system concentration disrupting real-time data integration and specialized maritime talent scarcity constraining service expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Peru Road Freight Transport Market
Logistics and Shipping
Less-Than-Truckload Market
Logistics and Shipping
US Fourth-Party Logistics (4PL) Market
Logistics and Shipping
Vehicle Routing and Scheduling Market
Logistics and Shipping
Global Sea Air Logistics Market
Logistics and Shipping
GCC Contract Logistics Market
Logistics and Shipping
South Africa Air Freight Market
Logistics and Shipping
Turkey Freight and Logistics Market
Logistics and Shipping
Bangladesh Freight and Logistics Market
Logistics and Shipping
UAE Logistics Market
Logistics and Shipping
Italy Apparel Logistics Market
Logistics and Shipping
Australia Freight Forwarding Market
Logistics and Shipping
Air Freight Software Market
Logistics and Shipping
North America FMCG Logistics Market
Logistics and Shipping
Colombia Third-Party Logistics (3PL) Market
Logistics and Shipping
Illinois Freight and Logistics Market