
 Asia Pacific Domestic Courier Market | 2026-2036
Asia Pacific Domestic Courier Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Domestic Courier Market Insights
India's PLI scheme for logistics and warehousing is rebalancing capital deployment toward automated sortation and cold-chain infrastructure. SF Express leverages its captive air fleet and ground hub network to sustain next-day coverage across China's tier-2 cities. ZTO Express anchors its cost position through in-house production of sorting equipment and line-haul trucks. CJ Logistics Corporation competes on multimodal integration, connecting Korean manufacturing clusters with Southeast Asian distribution nodes.
Asia Pacific domestic courier services encompass the collection, sortation, line-haul transport, and last-mile delivery of parcels and documents within national boundaries, typically operating through hub-and-spoke networks with automated sortation throughput exceeding parcels per hour. These services function as commercial circulatory infrastructure, enabling inventory velocity for just-in-time manufacturing and direct-to-consumer retail fulfillment. Express delivery commands premium pricing and absorbs disproportionate investment in air capacity and real-time tracking infrastructure, while standard shipping occupies the volume-heavy, margin-thin core of most national operations. Ground shipping dominates unit economics across archipelagic and continental geographies alike, though air freight captures urgent medical and high-value electronics movements where dwell-time penalties exceed transport premiums.
China's SAMR enforces antitrust scrutiny on platform logistics pricing, while India's RBI governs cash-on-delivery reconciliation flows that still underpin e-commerce courier economics. Japan's METI promotes standardization of drone delivery corridors and autonomous vehicle testing protocols. Stakeholders must monitor how fragmented national customs regimes and emerging data-localization rules reshape cross-border domestic courier adjacencies and technology licensing requirements.
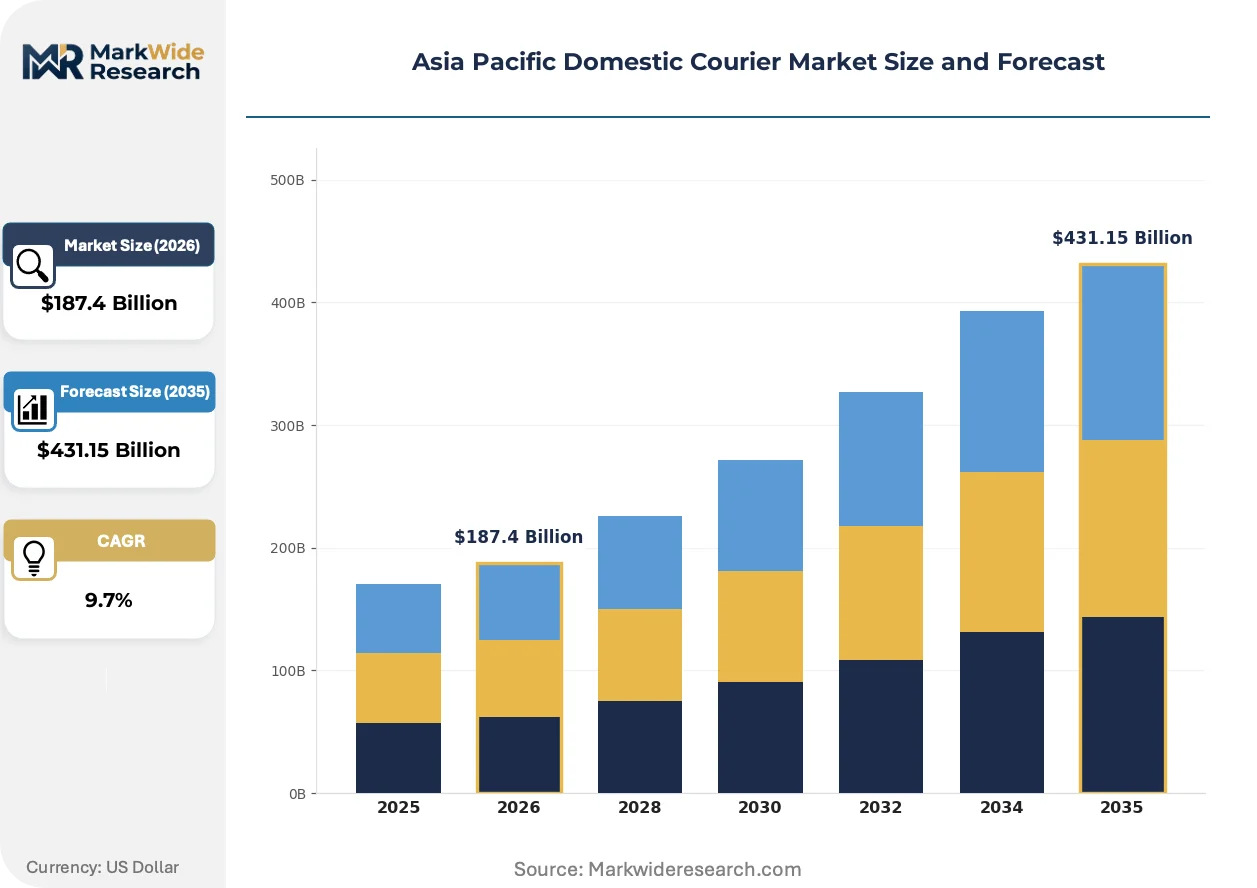
Market Dynamics
China's dual carbon goals are forcing fleet electrification timelines across the Asia Pacific Domestic Courier Market, compressing diesel truck replacement cycles and mandating green packaging standards that reshape capital allocation across hub networks.
Growth Catalysts
- E-commerce Same-Day Mandates:Platform fulfillment guarantees in China's Yangtze River Delta and India's Mumbai-Pune corridor are pulling air capacity and automated sortation investment into tier-2 urban nodes.
- India's PLI Scheme for Logistics:The production-linked incentive framework is redirecting capital toward automated sortation systems and cold-chain infrastructure, accelerating domestic courier modernization.
- Drone Delivery Corridors:Japan's METI standardization protocols for autonomous aerial routes are unlocking last-mile density in mountainous prefectures and remote island chains.
Market Restraints
- Lithium-Ion Battery Supply Concentration:Fleet electrification depends on cell supply chains concentrated in Chinese manufacturing clusters, exposing operators to input volatility and geopolitical friction.
- SAMR Antitrust Enforcement:China's State Administration for Market Regulation is scrutinizing platform logistics pricing algorithms, constraining revenue optimization for e-commerce-integrated couriers.
- Inter-Island Maritime Bottlenecks:Archipelagic geographies in Indonesia and the Philippines impose dwell-time penalties that air freight cannot economically offset for standard parcel flows.
Strategic Opportunities
- Vietnam's Manufacturing Corridor Expansion:Underpenetrated courier density between Ho Chi Minh City and the northern industrial provinces offers first-mover advantage for automated ground networks.
- Autonomous Vehicle-Conveyor Convergence:Integration of self-driving line-haul trucks with robotic sortation hubs promises labor cost compression in Australia's interstate corridors.
- Thailand's Eastern Economic Corridor Incentives:Tax advantages and infrastructure subsidies for logistics operators are attracting multimodal investment connecting Bangkok with Laem Chabang port.
Industry Challenges
- Electrical Technician Scarcity:Fleet electrification and charging infrastructure deployment outpace vocational training output in India and Southeast Asian markets, delaying maintenance response times.
- Legacy Warehouse Management Integration:Automated sortation systems require API reconciliation with decade-old inventory platforms still prevalent in Japanese and Australian distribution centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Domestic Courier Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $431.15 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express Delivery, Same-Day Service, Standard Shipping, Freight Transport End User: E-commerce, Retail Sector, Healthcare Providers, Manufacturing Companies Delivery Mode: Ground Shipping, Air Freight, Sea Freight, Multimodal Transportation Package Type: Documents, Parcels, Pallets, Freight Containers |
| Companies Covered | China Post, SF Express, SG Holdings Co., Ltd., Shanghai YTO Express (Logistics) Co., Ltd., ZTO Express, Yamato Holdings Co., Ltd., CJ Logistics Corporation, DHL Group, Blue Dart Express, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Domestic Courier Market Trends and Innovations
Robotic process automation is compressing labor intensity across Asia Pacific courier operations while regulatory mandates and buyer behavior shifts reshape network design priorities.
Automated sortation systems deploying machine vision and dynamic routing algorithms are automating parcel handling throughput in Chinese and Indian mega-hubs. SF Express and ZTO Express are scaling these installations to exceed parcels per hour across tier-2 city networks. The technology is automating workforce requirements while compressing mis-sort rates and enabling next-day coverage expansion.
China's SAMR is enforcing data-localization requirements for logistics platforms operating cross-border domestic courier adjacencies, mandating onshore server infrastructure and audit transparency. This regulatory friction is raising compliance costs for e-commerce-integrated operators while creating competitive moats for domestically capitalized players with established local data architecture.
Buyer procurement of courier services is fragmenting from annual volume contracts toward dynamic spot-rate platforms with real-time capacity bidding. This shift is disintermediating traditional sales relationships in Australia's SME retail segment and compressing contract renewal cycles from twelve months to quarterly renegotiation windows.
Asia Pacific Domestic Courier Market Segmentation
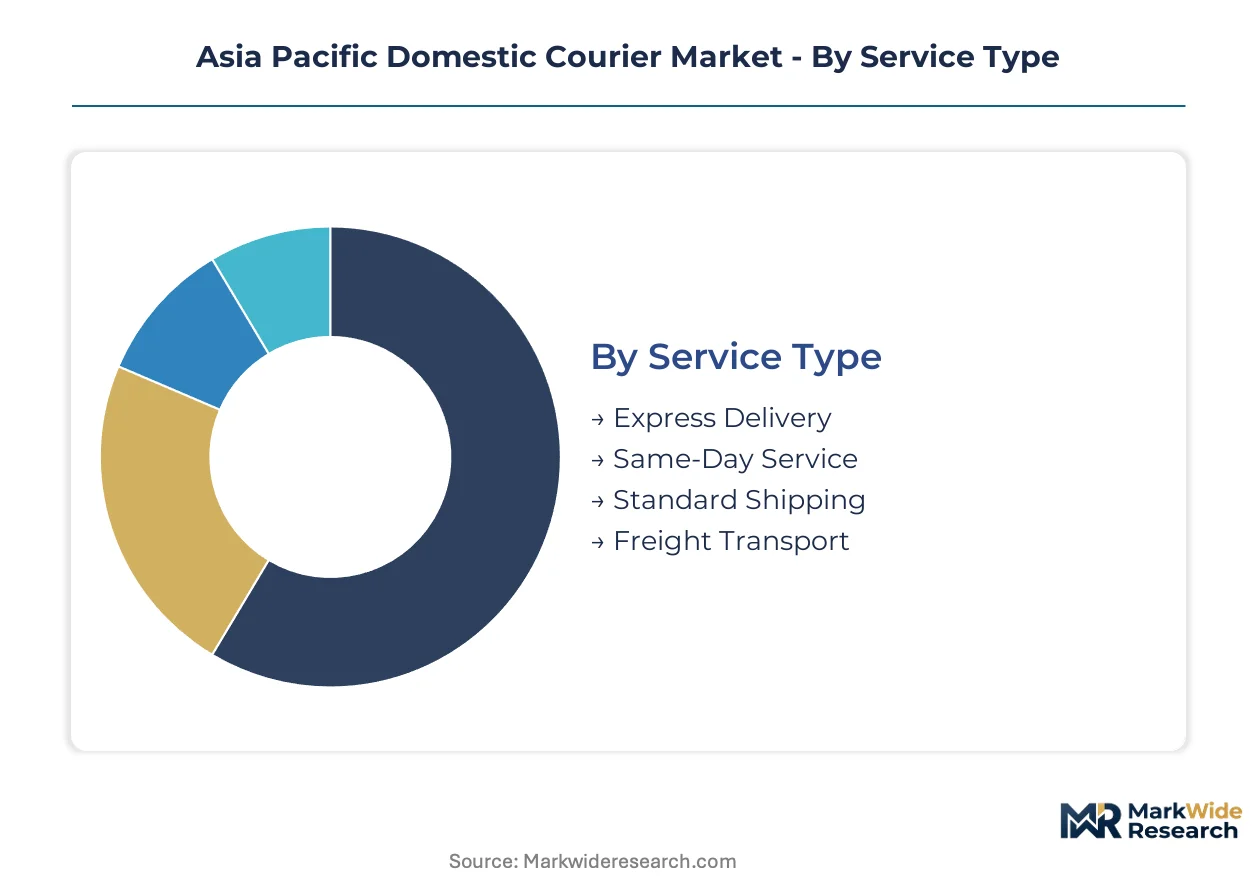
Segmentation in the Asia Pacific domestic courier market reveals how service architecture, customer requirements, and infrastructure constraints fragment operational models. Buyers select service tiers based on dwell-time penalties, inventory velocity needs, and geographic coverage requirements.
Service Type:
Speed guarantees command the primary buyer decision calculus, with platform fulfillment mandates compressing delivery windows across China's Yangtze River Delta and India's Mumbai-Pune corridor.
- Express Delivery:Premium service tier leveraging dedicated air capacity and real-time tracking infrastructure for next-day coverage. China's tier-2 cities absorb disproportionate investment in automated sortation and captive air fleets as e-commerce platforms mandate sub-24-hour fulfillment.
- Same-Day Service:Ultra-premium segment requiring urban micro-fulfillment nodes and dynamic routing algorithms. Demand concentrates in Seoul, Singapore, and Sydney metropolitan cores where dwell-time penalties exceed transport premiums for high-value electronics and urgent medical shipments.
- Standard Shipping:Volume-heavy core occupying margin-thin economics through hub-and-spoke ground networks.
- Freight Transport:Palletized and containerized movements serving manufacturing clusters with scheduled line-haul reliability.
Standard shipping leads on scale; same-day service leads on momentum.
End User:
Customer procurement patterns diverge sharply between platform-integrated volume contracts and spot-rate bidding for SME retail fulfillment.
- E-commerce:Platform-driven demand requiring API-integrated tracking, automated returns processing, and cash-on-delivery reconciliation flows governed by India's RBI. This segment anchors network design priorities across automated sortation investments and last-mile density.
- Retail Sector:Omnichannel fulfillment combining store-based inventory with home delivery, pulling investment into urban micro-hubs and dynamic capacity allocation.
- Healthcare Providers:Temperature-controlled logistics for pharmaceuticals and medical devices with regulatory compliance mandates from Japan's PMDA and India's CDSCO.
- Manufacturing Companies:Just-in-time component delivery with penalty clauses for production line stoppages, favoring multimodal integration and scheduled reliability.
E-commerce dominates volume concentration; healthcare providers show the steepest expansion trajectory.
Delivery Mode:
Geography and archipelagic fragmentation dictate modal selection, with inter-island maritime constraints in Indonesia and the Philippines imposing dwell-time penalties that reshape network economics.
- Ground Shipping:Dominant unit economics across continental geographies and intra-island movements, with fleet electrification timelines compressing diesel truck replacement cycles under China's dual carbon goals.
- Air Freight:Captures urgent medical and high-value electronics movements where speed premiums outweigh transport costs. SF Express leverages captive air fleet coverage across China's tier-2 networks to sustain competitive positioning.
- Sea Freight:Archipelagic standard parcel flows between Indonesian islands and Philippine provinces where air capacity cannot economically offset maritime dwell times.
- Multimodal Transportation:CJ Logistics Corporation anchors competitive differentiation through integrated Korean manufacturing cluster connections with Southeast Asian distribution nodes.
Ground shipping leads on scale; multimodal transportation leads on momentum.
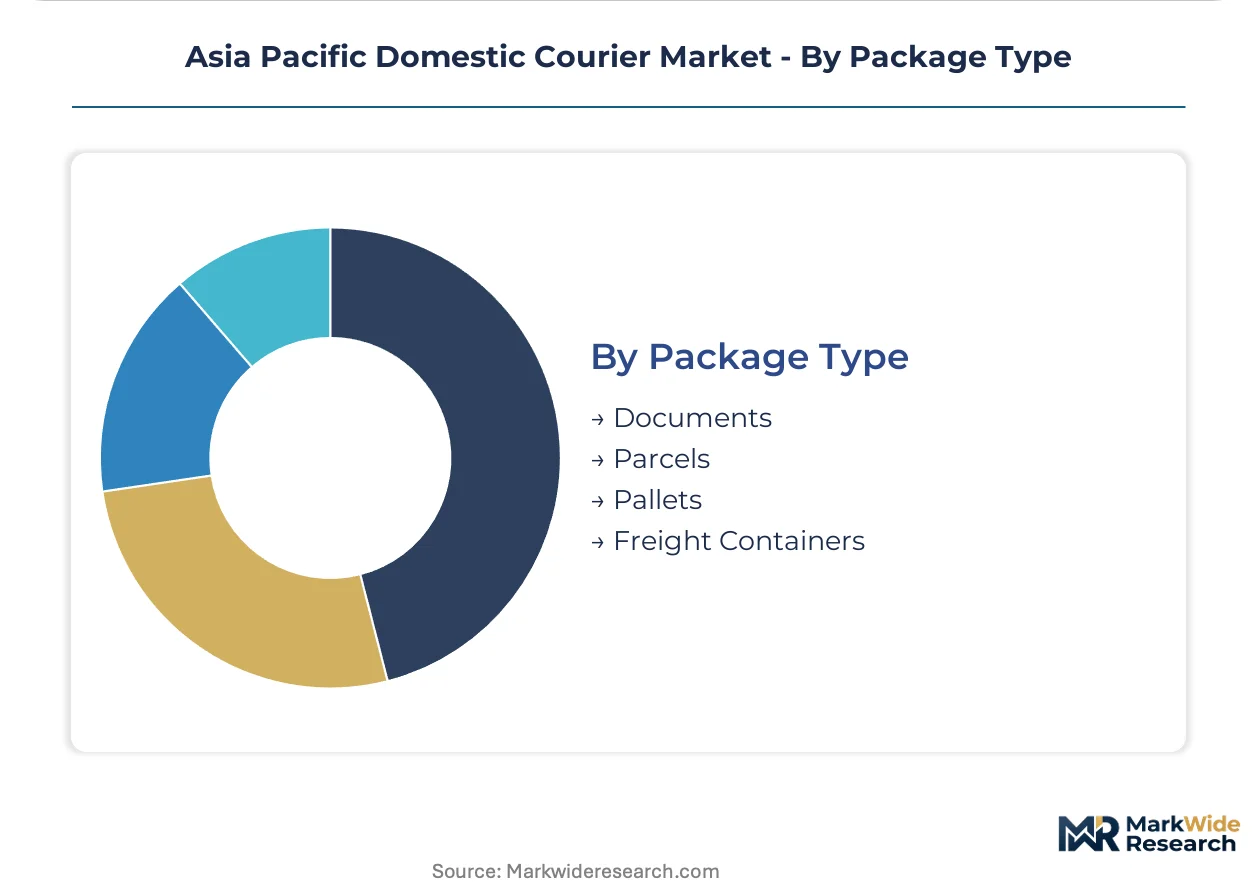
Package Type:
Physical characteristics determine sortation technology requirements, with automated systems scaling throughput based on dimensional weight and fragility constraints.
- Documents:Flat, lightweight items requiring minimal handling infrastructure, though volume is declining as digital substitution accelerates in Japanese and Australian corporate segments.
- Parcels:Core revenue driver with dimensional weight pricing and machine vision sortation enabling throughput exceeding manual handling capacity in Chinese and Indian mega-hubs.
- Pallets:Manufacturing and retail distribution requiring forklift-compatible handling and scheduled line-haul capacity.
- Freight Containers:Full-truckload and containerized movements between industrial zones and port facilities, with Thailand's Eastern Economic Corridor incentives attracting multimodal investment.
Parcels lead on scale; freight containers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled logistics technicians concentrate in China's Yangtze River Delta manufacturing belt, India's Mumbai-Pune industrial corridor, and Southeast Asian urban agglomerations. These workforce pools anchor automated sortation deployment and fleet electrification timelines across national courier networks.
China
E-commerce same-day mandates from Alibaba and JD.com pull air capacity investment into Chengdu and Xi'an. SAMR enforces antitrust scrutiny on platform logistics pricing algorithms. The Yangtze River Delta corridor anchors automated mega-hub construction exceeding parcels per hour throughput.
India
Cash-on-delivery reconciliation flows still underpin e-commerce courier economics across tier-2 urban nodes. RBI governs payment settlement protocols for last-mile delivery networks. The Mumbai-Pune corridor attracts PLI scheme capital toward automated sortation and cold-chain infrastructure.
Japan
Aging workforce demographics accelerate robotic process automation adoption in last-mile delivery networks. METI promotes standardization of drone delivery corridors and autonomous vehicle testing protocols. The Kanto region surrounding Tokyo deploys aerial route density in mountainous prefectures.
Vietnam
Manufacturing corridor expansion between Ho Chi Minh City and northern industrial provinces generates underpenetrated courier density. The country's national transport ministry issues fleet modernization directives for cross-provincial logistics operators. The Eastern Economic Corridor incentives attract multimodal investment connecting Ho Chi Minh City with Cai Mep port.
Indonesia
Archipelagic geography imposes inter-island maritime bottlenecks that reshape network economics for standard parcel flows. The national logistics council mandates domestic shipping preference rules for government procurement. Java's Jakarta-Surabaya corridor concentrates ground fleet electrification pilot programs.
Asia Pacific Domestic Courier Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market strata. The vendor base organizes around three strategic archetypes: integrated platform-captive operators, independent network scale players, and regional multimodal specialists. Consolidation pressure intensifies as e-commerce platforms internalize logistics capabilities. Dominant competitive moves include captive air fleet expansion and automated sortation technology licensing.
Within the integrated platform-captive tier, SF Express and ZTO Express exemplify operators leveraging in-house production of sorting equipment and line-haul trucks to sustain cost positions. CJ Logistics Corporation anchors the regional multimodal specialist archetype, connecting manufacturing clusters with distribution nodes through integrated capacity. These three companies occupy positions across the premium service tier where next-day coverage mandates absorb disproportionate infrastructure investment.
| Leading Market Players |
|---|
| China Post |
| SF Express |
| SG Holdings Co., Ltd. |
| Shanghai YTO Express (Logistics) Co., Ltd. |
| ZTO Express |
| Yamato Holdings Co., Ltd. |
| CJ Logistics Corporation |
| DHL Group |
| Blue Dart Express |
| Others |
Pricing and Supply Chain Analysis
Diesel price benchmarks in Singapore and crude oil futures in Shanghai anchor cost structures across ground and air freight tiers, cascading through fuel surcharges into express delivery premiums and compressing margins on standard shipping contracts across the Asia Pacific Domestic Courier Market.
Pricing Analysis
Bundled service contracts combining sortation, line-haul, and last-mile delivery dominate enterprise procurement, while unbundled spot-rate bidding fragments SME relationships. Three-tier pricing structure across premium, standard, and economy levels separates express air-backed guarantees from ground-based deferred delivery. Price differentiation hinges on volume scale commitments and real-time tracking API integration. Cost compression in standard shipping intensifies as platform logistics algorithms optimize route density. E-commerce platforms show least price sensitivity for same-day mandates; SME retailers exhibit highest sensitivity to fuel surcharge fluctuations.
Supply Chain Analysis
Reverse logistics flows for e-commerce returns and failed cash-on-delivery attempts consume sortation capacity and reshape hub network design across Chinese and Indian operations. Lithium-ion cell manufacturing concentrates in China, South Korea, and Japan, anchoring fleet electrification timelines. Electric vehicle powertrains, automated sortation equipment, and sustainable packaging materials constitute critical input dependencies. Single-source vulnerability in battery cell supply chains exposes operators to input volatility and geopolitical friction. Distribution runs through hub-and-spoke mega-facilities in the Yangtze River Delta, Mumbai-Pune corridor, and Jakarta-Surabaya belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific Domestic Courier Market reads as a late-cycle quality story where buyer procurement shifts toward guaranteed delivery windows and carbon-certified service tiers justify premium positioning over pure rate competition.
For Market Incumbents: Lock in automated sortation throughput advantages through captive equipment production and tier-2 city hub expansion before PLI scheme subsidies expire in India. Platform logistics internalization by Alibaba and JD.com threatens independent carrier volumes. Vertical integration into electric vehicle fleet manufacturing compresses total cost of ownership against diesel replacement cycles. For New Entrants and Emerging Players: Launch via white-label last-mile partnerships with underpenetrated grocery and pharmacy chains in Vietnam's northern industrial provinces. Vietnam's manufacturing corridor between Ho Chi Minh City and Hai Phong offers lowest courier density relative to freight volume growth. Target healthcare cold-chain compliance as a certification-differentiated entry angle against commoditized parcel competition. For Investors and Strategic Acquirers: Asymmetric upside sits with regional multimodal specialists possessing integrated sea-air-ground capabilities and established customs brokerage licenses. Five-to-ten year viability favors operators with captive data infrastructure meeting SAMR localization mandates. Monitor lithium-ion battery supply contract renegotiation cycles as inflection signals for fleet electrification capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sortation Scale-Up | SF Express and ZTO Express exceed parcels per hour throughput across tier-2 Chinese hubs. |
| Captive Air Fleet Expansion | Dedicated cargo capacity insulates next-day coverage from passenger belly-hold volatility. |
| Fleet Electrification Partnership | China's dual carbon goals compress diesel truck replacement timelines across Yangtze Delta networks. |
| Multimodal Integration Investment | CJ Logistics Corporation connects Korean manufacturing clusters with Southeast Asian distribution nodes. |
| Cold-Chain Certification Program | Japan's PMDA and India's CDSCO compliance mandates anchor pharmaceutical logistics premiums. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with courier operations executives, e-commerce platform logistics directors, automated sortation equipment manufacturers, and fleet electrification specialists with secondary validation from SAMR regulatory filings, RBI payment system reports, METI drone corridor protocols, and customs trade flow databases. Bottom-up volume modeling across national courier networks triangulated against top-down e-commerce gross merchandise value projections.
Comparable historical periods anchored the projection horizon, with growth trajectories derived from segment-level elasticity modeling across service type, end user, delivery mode, and package type dimensions. CAGRs reflect convergence between demand-side platform fulfillment mandates and supply-side infrastructure deployment timelines. Forecast inputs incorporated fleet electrification cost curves, automated sortation throughput benchmarks, and inter-island maritime capacity constraints specific to Indonesian and Philippine archipelagic logistics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged lithium-ion supply disruption or accelerated SAMR antitrust enforcement on platform pricing algorithms. Practitioners should monitor battery supply contract renegotiations, PLI scheme disbursement rates, and drone corridor regulatory finalization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
South America Freight and Logistics Market
Logistics and Shipping
WAN Connected Returnable Transport Asset Tracking Market
Logistics and Shipping
United States Contract Logistics Market
Logistics and Shipping
Mexico Containerized Shipping Market
Logistics and Shipping
Global Container Terminal Operations Market
Logistics and Shipping
North America Same Day Delivery Market
Logistics and Shipping
Romania Freight and Logistics Market
Logistics and Shipping
Saudi Arabia Freight and Logistics Market
Logistics and Shipping
United States Freight and Logistics Market
Logistics and Shipping
Australia Cold Chain Logistics Market
Logistics and Shipping
Apparel Logistics Market
Logistics and Shipping
GCC Air Freight and Logistics Market
Logistics and Shipping
UAE Logistics Market
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
US Event Logistics Market
Logistics and Shipping
United States Apparel Logistics Market