
 South Africa Air Freight Market | 2026-2036
South Africa Air Freight Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Air Freight Market Insights
The South Africa air freight sector is rebalancing between premium express services and commodity general cargo as shippers segment reliability needs from cost-minimization lanes. DHL Express leverages its integrated network to dominate time-definite pharmaceutical deliveries from Johannesburg. Bidvest International Logistics anchors domestic perishable exports through specialized cold-chain infrastructure at Cape Town. Emirates SkyCargo competes on long-haul connectivity, extending Gulf hub advantages into southern African lanes.
Air freight denotes the commercial transport of goods via fixed-wing aircraft, typically operating at cruising altitudes with pressurized cargo holds maintained between 15°C and 25°C for standard shipments, though specialized containers achieve -20°C to -80°C for active pharmaceutical ingredients. The primary industrial purpose centers on velocity-sensitive supply chains where inventory carrying costs exceed premium transportation expenditures. Express delivery commands the highest margin pools as pharmaceutical and electronics end users prioritize chain-of-custody certainty over freight expenditure. Freight forwarding exhibits structural growth as small and mid-sized enterprises outsource customs brokerage and multimodal coordination to specialist intermediaries. Perishable cargo represents the fastest-expanding cargo type category, driven by citrus and deciduous fruit export seasons requiring accelerated cold-chain transit to European retail deadlines.
The South African Civil Aviation Authority enforces ICAO-aligned dangerous goods regulations that mandate certified handling staff and segregated storage facilities, elevating operational compliance costs for smaller forwarders. The International Air Transport Association's CEIV Pharma certification increasingly functions as a market access threshold for pharmaceutical tenders from multinational manufacturers. Stakeholders must monitor evolving carbon offset requirements under the ICAO Carbon Offsetting and Reduction Scheme for International Aviation as European destination markets harden emissions disclosure expectations for air cargo supply chains.
Market Dynamics
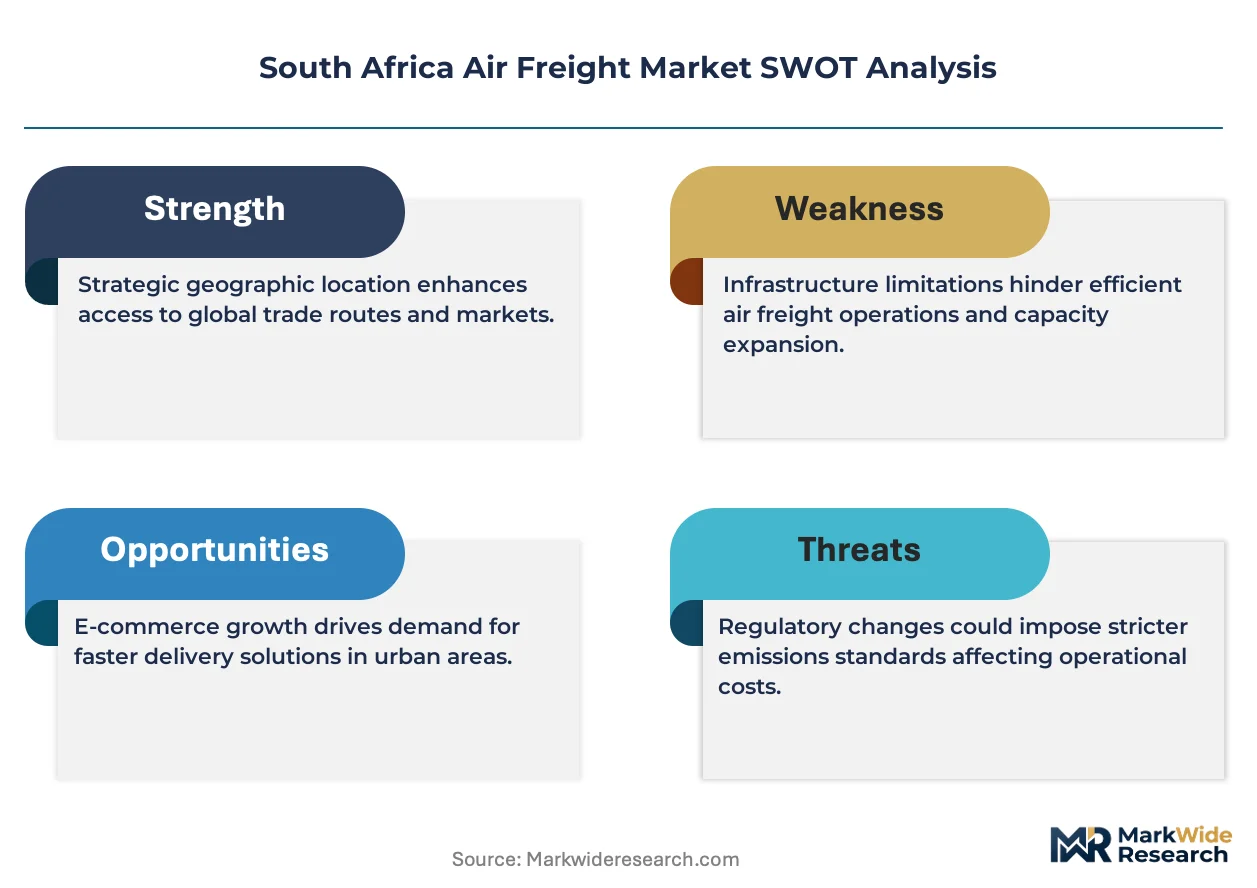
Pharmaceutical cold-chain compliance requirements are compressing forwarder margins while concentrating volumes among CEIV Pharma-certified operators in the Gauteng corridor.
Growth Catalysts
- Biologics Distribution:Temperature-sensitive biologics are expanding their share of domestic pharmaceutical networks, creating specialized handling demand at OR Tambo International Airport.
- IATA CEIV Pharma:Certification mandates from multinational manufacturers are filtering tender access, elevating operational standards across Johannesburg-based cargo terminals.
- Citrus Export Seasons:Accelerated cold-chain transit requirements for European retail deadlines are driving perishable cargo volumes through Cape Town's specialized infrastructure.
Market Restraints
- Jet Fuel Volatility:Kerosene price swings directly compress yields on long-haul African-European lanes where fuel surcharges lag spot movements.
- OR Tambo Concentration:Premium express volumes cluster at a single hub, creating systemic vulnerability to weather disruptions or runway closures.
- Road Freight Substitution:Cross-border trucking improvements on the Maputo Corridor are capturing time-flexible general cargo at 40-60% of air rates.
Strategic Opportunities
- KwaZulu-Natal Expansion:King Shaka International Airport remains underutilized for pharmaceutical exports, offering greenfield cold-chain development potential.
- Carbon Offset Integration:ICAO CORSIA alignment creates premium service tiering for European-bound shippers facing emissions disclosure mandates.
- Drone-Last-Mile Convergence:Unmanned aerial systems for remote mining site deliveries are converging with traditional air freight networks in Northern Cape platinum belts.
Industry Challenges
- Dangerous Goods Certification:South African Civil Aviation Authority protocol updates mandate retraining cycles that drain smaller forwarder working capital.
- Active Container Capex:Pharmaceutical-grade temperature-controlled units require capital outlays that strain mid-tier operators' balance sheets.
- Multimodal Integration:Disparate IT systems between air and road carriers create visibility gaps in pharmaceutical chain-of-custody documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Air Freight Market |
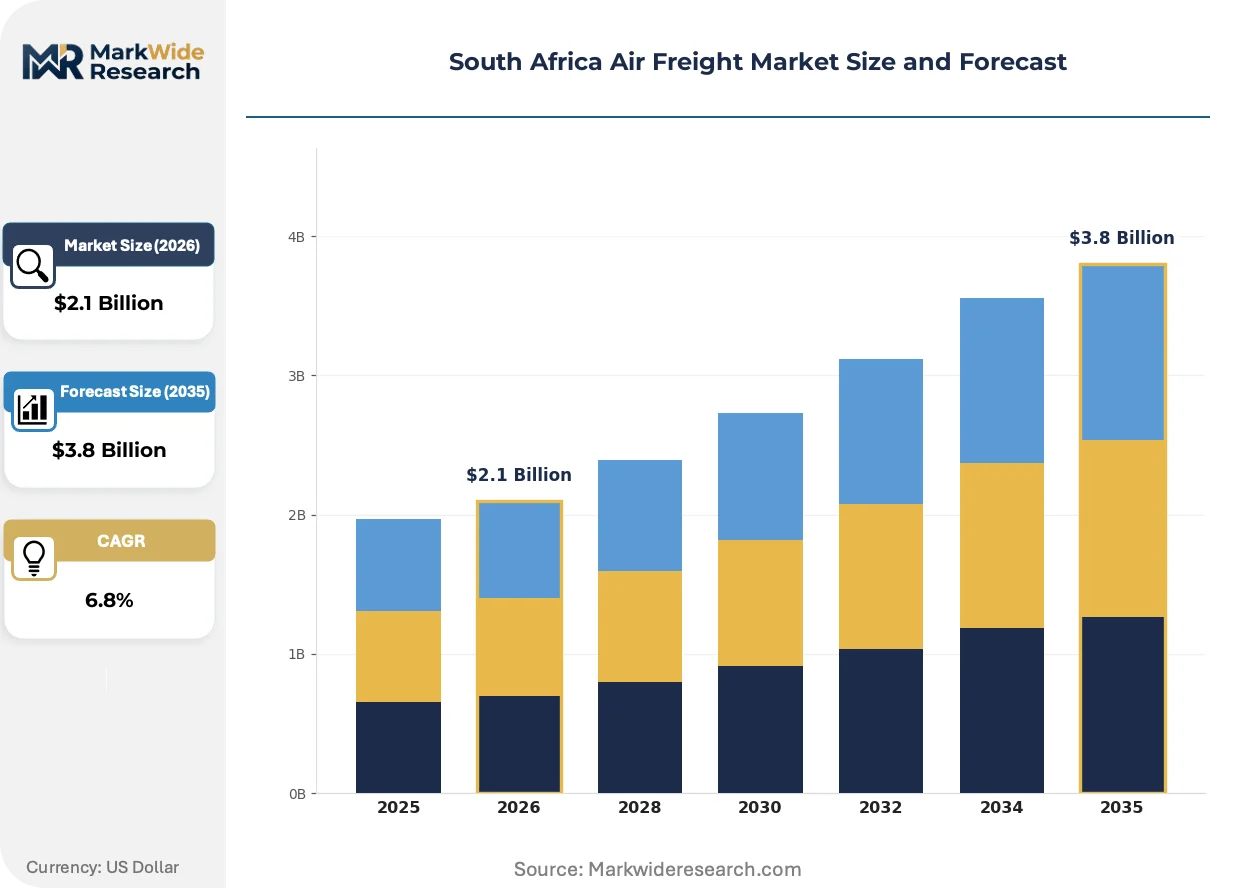
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express Delivery, Charter Services, Cargo Airlines, Freight Forwarding End User: Aerospace, Pharmaceuticals, Electronics, Retail Carrier Type: Dedicated Freight Carriers, Passenger Airlines, All-Cargo Airlines, Integrated Carriers Cargo Type: Perishable Goods, Dangerous Goods, Heavy Cargo, General Cargo |
| Companies Covered | DHL Express, FedEx Express, South African Airways Cargo, Emirates SkyCargo, DSV, Kuehne + Nagel, DB Schenker, UPS, Bidvest International Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Air Freight Market Trends and Innovations
Digital cargo tracking and passive container innovation are compressing the cost-performance gap between premium and standard cold-chain services.
Active temperature-controlled containers with embedded IoT sensors are overtaking traditional passive cool boxes on high-value pharmaceutical lanes. Multinational manufacturers now specify real-time visibility as a tender precondition. This technology is overtaking conventional monitoring approaches by enabling intervention before excursions breach stability budgets.
South African Civil Aviation Authority dangerous goods protocols are tightening segregation requirements for lithium battery shipments. Certified handling staff mandates are elevating facility costs at Johannesburg cargo terminals. Pharmaceutical forwarders are responding by consolidating operations into purpose-built compliance centers rather than retrofitting legacy warehouses.
Shippers are unbundling express and economy decisions across separate procurement cycles rather than defaulting to integrated service tiers. Large citrus exporters now tender perishable lanes separately from general cargo, pressuring forwarders to demonstrate lane-specific performance data. This behavioral shift is most visible in Western Cape deciduous fruit supply chains serving German retail networks.
South Africa Air Freight Market Segmentation
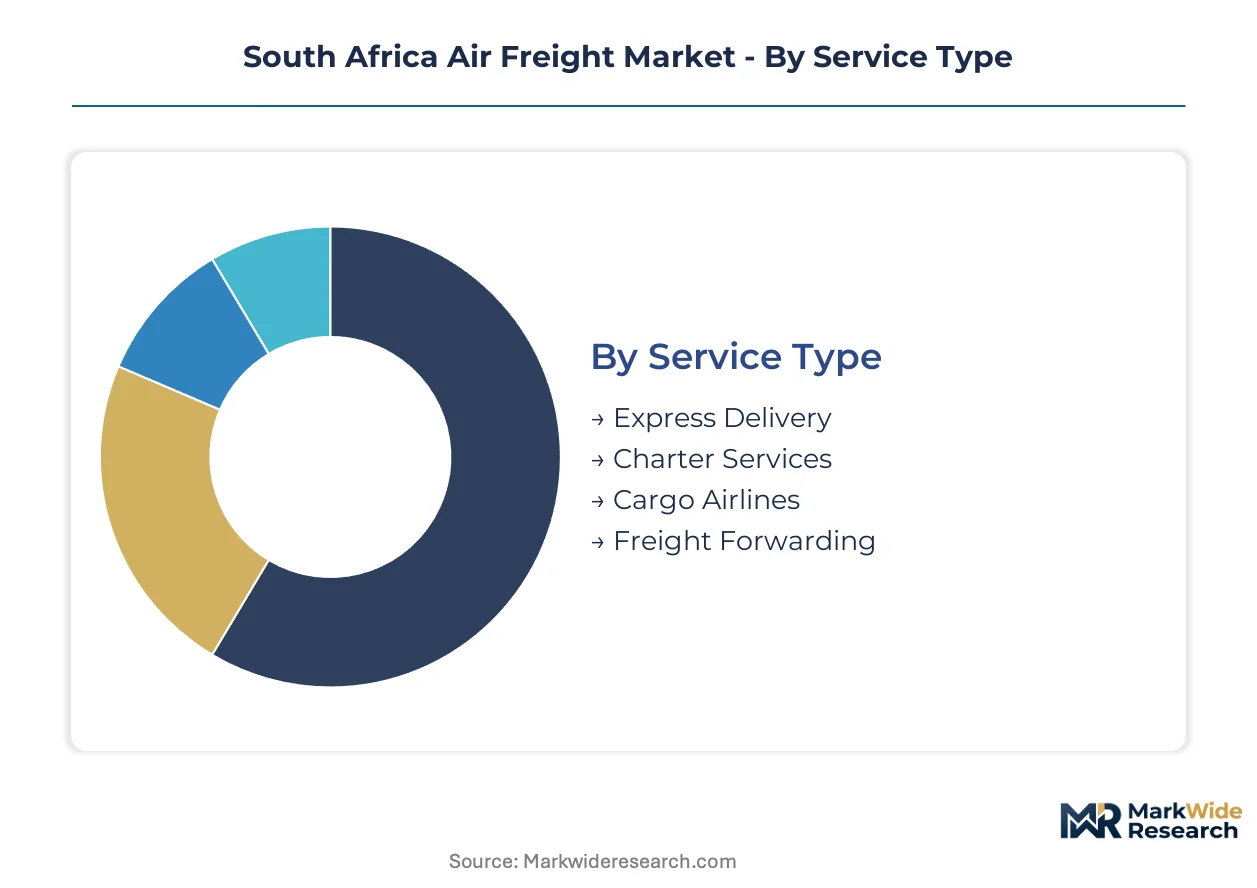
Air freight segmentation in South Africa reflects divergent velocity requirements and compliance thresholds across cargo categories. Service differentiation concentrates around temperature-sensitive pharmaceutical networks versus commodity general cargo lanes.
Service Type:
Customization spans from integrated door-to-door solutions to unbundled charter arrangements, with cost tiers separating premium velocity from scheduled reliability.
- Express Delivery:Time-definite services with guaranteed transit windows dominate pharmaceutical and electronics corridors through OR Tambo International Airport. Multinational manufacturers specify chain-of-custody certainty over freight expenditure in tender requirements.
- Freight Forwarding:Customs brokerage and multimodal coordination outsourced by small and mid-sized enterprises. Forwarders aggregate fragmented cargo into consolidated loads, capturing margin from documentation complexity and regulatory navigation.
- Cargo Airlines:Scheduled belly-hold and freighter operations on trunk routes connecting Johannesburg to European distribution hubs. Fuel surcharge mechanisms lag spot kerosene movements, compressing yields during volatility spikes.
- Charter Services:On-demand aircraft deployment for oversized project cargo or emergency pharmaceutical replenishment. Mining sector demand in Northern Cape platinum belts drives ad-hoc capacity procurement.
Leading the category by volume: Freight Forwarding. Expanding most quickly: Express Delivery.
End User:
Application-driven segmentation separates cold-chain pharmaceutical networks from standard-temperature retail distribution.
- Pharmaceuticals:Temperature-sensitive biologics requiring active containers maintaining -20°C to -80°C. IATA CEIV Pharma certification functions as a market access threshold for multinational manufacturer tenders.
- Electronics:High-value components prioritizing chain-of-custody certainty and security protocols. Gauteng-Johannesburg logistics corridor concentrates procurement for time-definite delivery.
- Retail:Fashion and consumer goods segmenting across express and economy lanes based on inventory carrying cost calculations. Seasonal peaks align with European buying calendars.
- Aerospace:Aircraft parts and maintenance components demanding urgent AOG (aircraft on ground) response capabilities. OR Tambo serves as the primary distribution node for sub-Saharan airline fleets.
Pharmaceuticals command the highest margin pools. Retail captures the greatest cargo tonnage.
Carrier Type:
Supply concentration varies from asset-heavy dedicated operators to variable-cost passenger belly-hold models.
- Integrated Carriers:Door-to-door network control combining aircraft, ground transport, and customs brokerage. DHL Express dominates time-definite pharmaceutical deliveries through captive infrastructure.
- Passenger Airlines:Belly-hold capacity on long-haul passenger routes offering lower unit costs for non-urgent cargo. Emirates SkyCargo extends Gulf hub advantages into southern African lanes.
- All-Cargo Airlines:Pure freighter operations on dense trade lanes with payload optimization for heavy or outsized shipments. Bidvest International Logistics anchors perishable exports through specialized cold-chain infrastructure.
- Dedicated Freight Carriers:Niche operators serving specific commodity verticals or geographic corridors. Mining and energy project logistics drive specialized fleet configurations.
Integrated Carriers hold the premium pricing tier. Passenger Airlines provide the widest route coverage.
Cargo Type:
Margin stratification follows handling complexity, with dangerous goods and temperature-controlled shipments commanding substantial premiums over commodity flows.
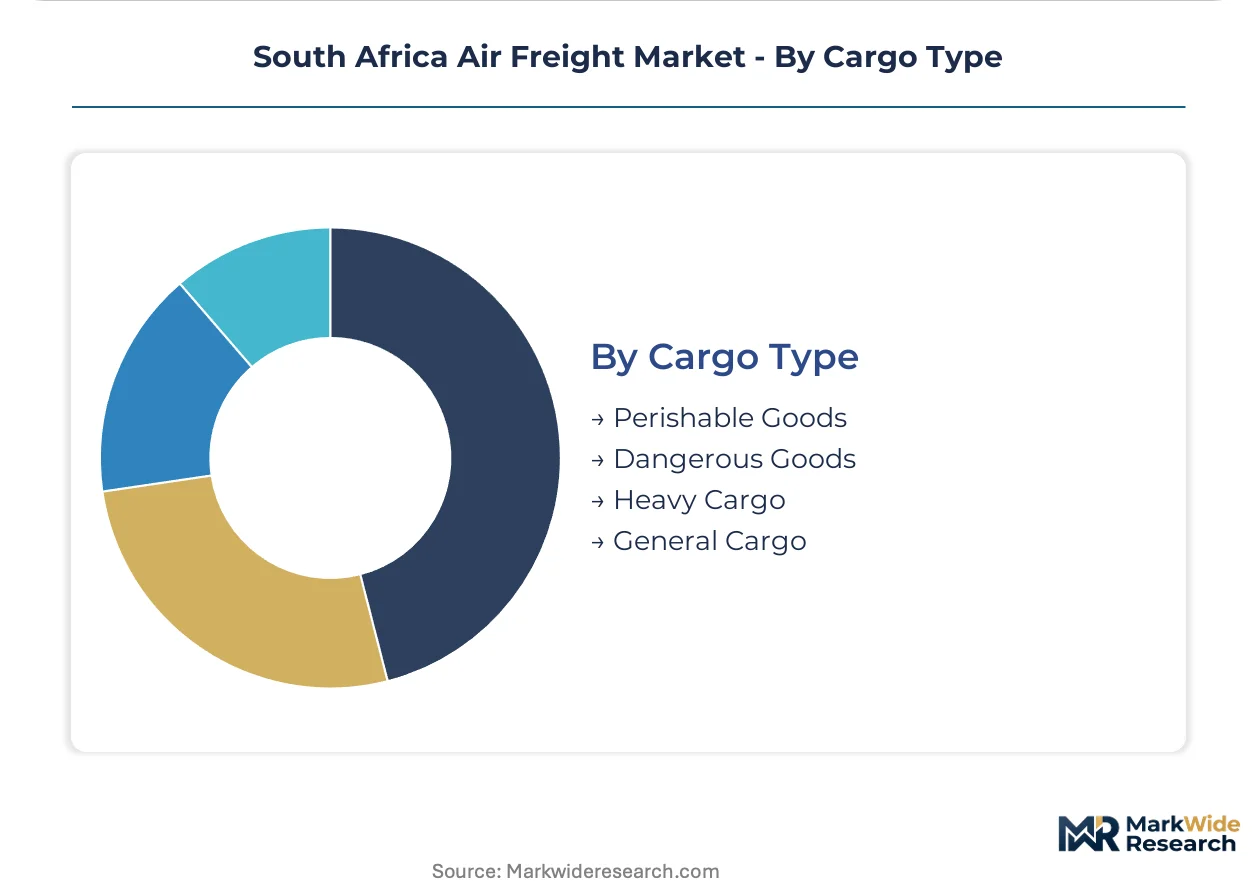
- Perishable Goods:Citrus and deciduous fruit exports requiring accelerated cold-chain transit to European retail deadlines. Cape Town's specialized infrastructure anchors Western Cape export seasons.
- Dangerous Goods:Lithium batteries, chemicals, and hazardous materials subject to South African Civil Aviation Authority segregation mandates. Certified handling staff requirements elevate facility costs at Johannesburg terminals.
- Heavy Cargo:Mining equipment, oil and gas components, and infrastructure project materials exceeding standard dimensional limits. Charter deployment dominates this category.
- General Cargo:Standardized non-specialized shipments competing with road freight substitution on time-flexible lanes. Maputo Corridor trucking captures volumes at 40-60% of air rates.
General Cargo moves the highest aggregate tonnage. Perishable Goods show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gauteng-Johannesburg logistics corridor concentrates South Africa's premium air freight activity, with OR Tambo International Airport processing the majority of express pharmaceutical volumes and electronics components destined for European and Asian markets.
Gauteng Province
Temperature-sensitive biologics and high-value electronics drive specialized handling demand at OR Tambo International Airport. The South African Civil Aviation Authority enforces ICAO-aligned dangerous goods regulations that mandate certified handling staff and segregated storage. Johannesburg's cargo terminals serve as the primary consolidation point for multinational pharmaceutical manufacturers distributing across sub-Saharan Africa.
Western Cape
Citrus and deciduous fruit export seasons require accelerated cold-chain transit to meet European retail deadlines. Perishable cargo infrastructure at Cape Town International Airport anchors specialized handling for agricultural producers. The region's wine and stone fruit sectors generate seasonal peaks that strain temperature-controlled capacity during harvest windows.
KwaZulu-Natal
King Shaka International Airport remains underutilized for pharmaceutical exports despite possessing greenfield development potential. The province's automotive manufacturing base generates component shipments requiring time-definite delivery to European assembly plants. Durban's port-airport multimodal connections offer alternative routing for cargo seeking to avoid Gauteng congestion.
Eastern Cape
Automotive component exports from the Coega Industrial Development Zone drive scheduled freighter demand. The South African government's Special Economic Zone incentives support air freight-linked manufacturing investment. Port Elizabeth's proximity to industrial clusters enables just-in-time supply chain configurations for original equipment manufacturers.
Northern Cape
Remote mining operations in platinum belts generate ad-hoc charter demand for critical spare parts and emergency replenishment. Unmanned aerial systems for last-mile delivery to isolated sites are converging with traditional air freight networks. Kimberley and Upington airports serve as staging points for project cargo bound for extraction sites.
South Africa Air Freight Market Competitive Landscape
Capital-heavy integrated carriers compete with asset-light freight forwarders for differentiated margin pools across South Africa's air freight sector. The market structure concentrates premium pharmaceutical and express volumes among CEIV Pharma-certified operators with captive ground infrastructure, while commodity general cargo fragments across numerous customs brokerage intermediaries. Three strategic archetypes dominate: integrated door-to-door networks controlling aircraft and last-mile delivery, specialized perishable handlers with dedicated cold-chain assets, and neutral freight forwarders aggregating fragmented shipper demand. Competitive dynamics center on certification acquisition for pharmaceutical tender access and multimodal IT integration to close visibility gaps in chain-of-custody documentation.
Within the integrated carrier tier, DHL Express and FedEx Express exemplify network control strategies combining owned aircraft with ground distribution infrastructure. Among specialized perishable handlers, Bidvest International Logistics anchors Western Cape export seasons through dedicated cold-chain facilities. Emirates SkyCargo occupies a position extending Gulf hub connectivity into southern African lanes via passenger belly-hold and freighter operations. These three archetypes represent the structural segmentation between premium velocity services and commodity consolidation plays.
| Leading Market Players |
|---|
| DHL Express |
| FedEx Express |
| South African Airways Cargo |
| Emirates SkyCargo |
| DSV |
| Kuehne + Nagel |
| DB Schenker |
| UPS |
| Bidvest International Logistics |
| Others |
Pricing and Supply Chain Analysis
ICAO CORSIA carbon offset mandates gate qualified supply access and premium-tier pricing power for European-bound pharmaceutical shipments, compressing margins for non-compliant forwarders while concentrating tender awards among certified operators with captive ground infrastructure at OR Tambo International Airport.
Pricing Analysis
Yield-per-kilogram pricing anchors South Africa's air freight structure, with pharmaceutical cold-chain services commanding substantial premiums over general cargo based on IATA CEIV Pharma certification status and real-time temperature visibility capabilities. Price differentiation separates certified operators from commodity forwarders, with multinational manufacturers prioritizing chain-of-custody certainty over freight expenditure in tender awards. Cost compression in general cargo lanes intensifies as road freight substitution on the Maputo Corridor captures time-flexible volumes at substantially lower rates. Small and mid-sized enterprises exhibit highest price sensitivity, while biologics manufacturers demonstrate lowest sensitivity due to stability budget thresholds.
Supply Chain Analysis
Single-source vulnerability sits with OR Tambo International Airport's dominance of premium express pharmaceutical volumes, creating systemic exposure to weather disruptions or runway capacity constraints. Active temperature-controlled container manufacturing draws from Germany, the United States, and China, while jet fuel supply rests on refined product imports from Middle Eastern refining centers. Tariff exposure on pharmaceutical packaging materials and lithium battery components elevates landed costs for specialized cargo handling equipment. Distribution runs through integrated carrier networks combining owned aircraft with captive ground infrastructure, neutral freight forwarders aggregating fragmented demand, and passenger airline belly-hold capacity on long-haul routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's air freight sector is transitioning from passive cool-box monitoring to active IoT-enabled container systems, with real-time intervention capabilities displacing legacy temperature excursion protocols across pharmaceutical supply chains.
For Market Incumbents: Acquire specialized cold-chain infrastructure assets in underutilized corridors, particularly King Shaka International Airport's greenfield pharmaceutical development potential. Bidvest International Logistics and DHL Express should consolidate CEIV Pharma-certified handling capacity to defend against Emirates SkyCargo's Gulf hub connectivity advantages. Certification investment represents the critical lever for maintaining tender access as multinational manufacturers harden compliance requirements. For New Entrants and Emerging Players: Enter via drone-last-mile convergence opportunities in Northern Cape platinum belts, where unmanned aerial systems for remote mining site deliveries remain structurally underserved. KwaZulu-Natal automotive component corridors offer penetrable white-space for time-definite services bypassing Gauteng congestion. A niche go-to-market angle targets carbon offset integration for European-bound shippers facing emissions disclosure mandates. For Investors and Strategic Acquirers: IATA CEIV Pharma certification acquisition announcements are the leading indicator that operational standards are hardening sufficiently to justify premium asset valuations. Long-term viability centers on multimodal IT integration capabilities that close visibility gaps in pharmaceutical chain-of-custody documentation. Acquisition targets should display captive ground infrastructure combined with certification moats, with inflection signals tracked through pharmaceutical tender award patterns and dangerous goods retraining cycle completions.| Strategic Initiative | Industry Significance |
|---|---|
| CEIV Pharma Certification Acquisition | IATA certification functions as market access threshold for multinational pharmaceutical manufacturer tenders. |
| Cold-Chain Infrastructure Expansion | Purpose-built compliance centers at King Shaka International Airport capture underutilized export potential. |
| Carbon Offset Service Tiering | ICAO CORSIA alignment creates premium positioning for European-bound shippers facing emissions mandates. |
| Drone-Last-Mile Network Integration | Unmanned aerial systems converge with traditional air freight for remote Northern Cape mining site deliveries. |
| Multimodal IT Platform Development | Disparate system integration closes visibility gaps in pharmaceutical chain-of-custody documentation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across cargo terminal operators, pharmaceutical logistics managers, freight forwarder executives, and South African Civil Aviation Authority compliance officers. IATA operational statistics, ICAO emissions disclosure frameworks, and airline cargo yield reports provided demand-side validation. Bottom-up volume estimates from OR Tambo and Cape Town International Airport throughput figures were triangulated against top-down pharmaceutical export value assessments.
Data-stream reconciliation across carrier yield reports, forwarder margin structures, and shipper procurement patterns informed the analytical framework. Segmentation dimensions modeled include service type, end-user vertical, carrier archetype, and cargo category across the projection horizon. CAGRs were derived from trend extrapolation of pharmaceutical cold-chain expansion, perishable export seasonality, and road freight substitution elasticity. Jet fuel price volatility assumptions and dangerous goods certification cycle frequencies served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended OR Tambo runway closure scenarios or accelerated Maputo Corridor road infrastructure investment. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Shipping Supplies Market
Logistics and Shipping
United States Chartered Air Freight Transport Market
Logistics and Shipping
Malaysia Road Freight Transport Market
Logistics and Shipping
Argentina Freight and Logistics Market
Logistics and Shipping
Asia Pacific Freight and Logistics Market
Logistics and Shipping
United States Courier, Express and Parcel (CEP) Market
Logistics and Shipping
US Dangerous-Hazardous Goods Logistics Market
Logistics and Shipping
Dry Van Container Market
Logistics and Shipping
United States Cold Chain Logistics Market
Logistics and Shipping
Latin America Air Freight Market
Logistics and Shipping
Brazil 3PL Market
Logistics and Shipping
Turkey Freight and Logistics Market
Logistics and Shipping
Warehousing and Distribution Logistics Market
Logistics and Shipping
Event Logistics Market
Logistics and Shipping
Cloud Logistics Market
Logistics and Shipping
Japan Domestic Courier, Express, and Parcel (CEP) Market