
 Asia-Pacific Logistics Automation Market | 2026-2036
Asia-Pacific Logistics Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Logistics Automation Market Analytics
Multi-source equipment procurement is recalibrating how third-party logistics providers assemble automation stacks across the region. Daifuku Co., Ltd. anchors Japanese demand through its dominance in airport baggage and semiconductor cleanroom logistics systems. KION Group AG competes via its Linde and STILL forklift automation lines, leveraging German engineering credibility in Chinese manufacturing plants. SSI Schaefer AG specializes in modular shuttle systems that extend into Australian cold-chain distribution networks.
Asia-Pacific logistics automation encompasses the integration of mechanized handling, robotic manipulation, and software-directed control systems to execute storage, retrieval, sorting, and transport operations within supply chain nodes, typically involving conveyor speeds exceeding 2.5 meters per second and real-time inventory tracking at the stock-keeping-unit level. Its primary purpose is to reduce order-cycle times and labor dependency in high-throughput distribution environments. Warehouse Management System deployments lead the technology dimension due to their role as the data layer orchestrating robotic and mechanized subsystems. Automated Guided Vehicles represent the fastest-expanding hardware category as lithium-ion traction battery costs decline and navigation shifts from magnetic tape to lidar-based simultaneous localization and mapping. Cloud Solutions within the offering dimension concentrate margin pools through recurring software-as-a-service contracts tied to throughput-based pricing.
Japan's METI enforces JIS standards for industrial robot safety and interoperability, while China's SAMR administers GB standards for automated storage equipment that condition market access for foreign suppliers. Australia's TGA and WorkSafe Victoria impose material-handling equipment certifications that shape product specifications for healthcare and pharmaceutical logistics automation deployments. Stakeholders must monitor how India's PLI scheme for electronics manufacturing redirects warehouse automation investment toward semiconductor and smartphone export hubs.
Market Dynamics
China's MIIT smart logistics guidance and Japan's METI Industry 4.0 subsidies are compressing capital deployment timelines, forcing equipment suppliers to pre-certify systems against divergent national standards before market entry.
Growth Catalysts
- MIIT Smart Logistics Infrastructure Mandate:China's Ministry of Industry and Information Technology directives accelerate port automation and bonded warehouse robotics deployment in the Yangtze River Delta cluster.
- E-commerce Fulfillment Center Expansion:Southeast Asian third-party logistics providers are expanding automated sortation and robotic picking systems to match same-day delivery service-level agreements.
- Lithium-ion Traction Battery Cost Decline:Automated Guided Vehicle adoption accelerates as battery economics improve and navigation shifts from magnetic tape to lidar-based simultaneous localization and mapping.
Market Restraints
- GB Standards Compliance Burden:China's SAMR-administered national standards for automated storage equipment create protracted certification timelines that condition market access for foreign suppliers.
- Semiconductor Component Concentration:Control system chipsets and servo motors concentrate in specialized East Asian manufacturing zones, exposing automation projects to input bottlenecks.
- Interoperability Friction:Japan's JIS industrial robot safety standards diverge from China's GB framework, forcing multi-source equipment procurement strategies to absorb integration complexity.
Strategic Opportunities
- India PLI Scheme Redirection:India's production-linked incentive scheme for electronics manufacturing redirects warehouse automation investment toward semiconductor and smartphone export hubs in Gujarat and Tamil Nadu.
- Australian Cold-Chain Distribution:Modular shuttle systems extend into temperature-controlled pharmaceutical and perishable goods networks where TGA certification requirements create defendable margin pools.
- Cloud-Native Warehouse Management:Software-as-a-service deployments with throughput-based pricing models concentrate recurring revenue streams among logistics automation vendors serving mid-market third-party logistics providers.
Industry Challenges
- Simultaneous Localization and Mapping Talent Scarcity:Lidar navigation deployment outpaces availability of robotics engineers capable of calibrating sensor fusion algorithms in dynamic warehouse environments.
- Legacy Warehouse Management System Integration:Brownfield facilities in Japan and South Korea require middleware development to bridge proprietary WMS architectures with modern robotic control APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Logistics Automation Market |
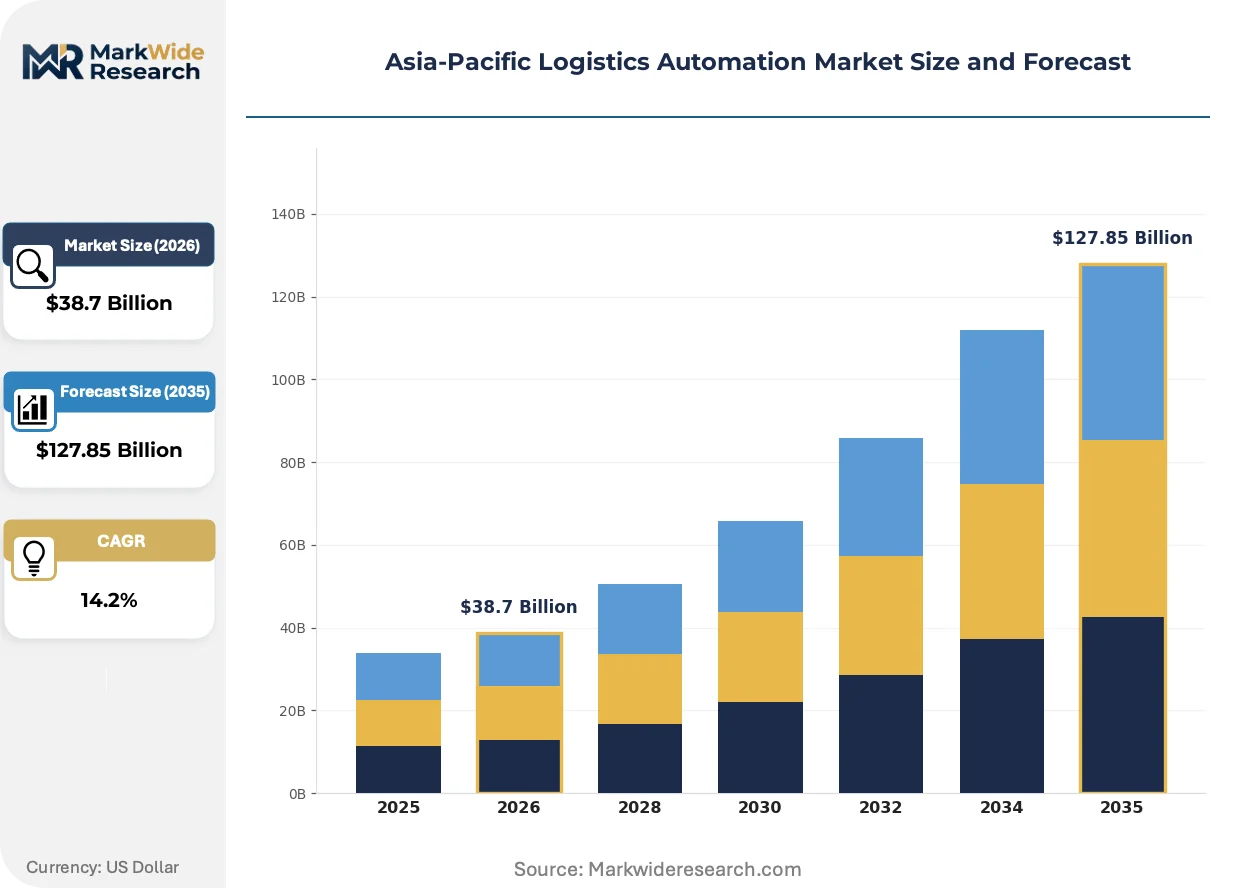
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Robotic Process Automation, Warehouse Management System, Automated Guided Vehicles, Sorting Systems End User: E-commerce, Retail, Manufacturing, Healthcare Offering: Software, Hardware, Services, Cloud Solutions Installation: On-premises, Off-site, Hybrid, Turnkey |
| Companies Covered | ABB Ltd., KION Group AG, Daifuku Co., Ltd., KNAPP AG, SSI Schaefer AG, Murata Machinery, Ltd., Toyota Industries Corporation, TGW Logistics Group, Swisslog Holding AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Logistics Automation Market Evolving Landscape
Navigation autonomy and software-defined control architectures are compressing the traditional hardware-software boundary in logistics automation, enabling equipment suppliers to capture margin through recurring digital services rather than perpetual license sales.
Lidar-based simultaneous localization and mapping is consolidating market position as the dominant navigation modality for Automated Guided Vehicles and autonomous mobile robots. Third-party logistics providers operating high-throughput e-commerce fulfillment centers in Vietnam and Indonesia are specifying lidar-native platforms exclusively. This technology shift is consolidating vendor market share around suppliers with in-house sensor fusion software capabilities, marginalizing magnetic tape and QR-code navigation alternatives.
China's SAMR enforcement of GB standards for automated storage equipment is tightening compliance verification requirements for foreign suppliers seeking market access. Industrial consequence includes mandatory third-party safety certification for robotic picking systems and conveyor modules above specified throughput thresholds. European and Japanese equipment manufacturers are responding by establishing localized testing partnerships in Shanghai and Suzhou to compress pre-market approval timelines.
Buyer procurement patterns are gravitating toward equipment-as-a-service arrangements with uptime guarantees replacing traditional capital expenditure models. Mid-market third-party logistics providers across Thailand and Malaysia are demanding outcome-based contracts where vendor remuneration ties directly to order-line fulfillment rates. This shift is most visible in ambient temperature e-commerce fulfillment, where balance-sheet-constrained operators prefer operational expenditure treatment for automation investments.
Asia-Pacific Logistics Automation Market Segmentation
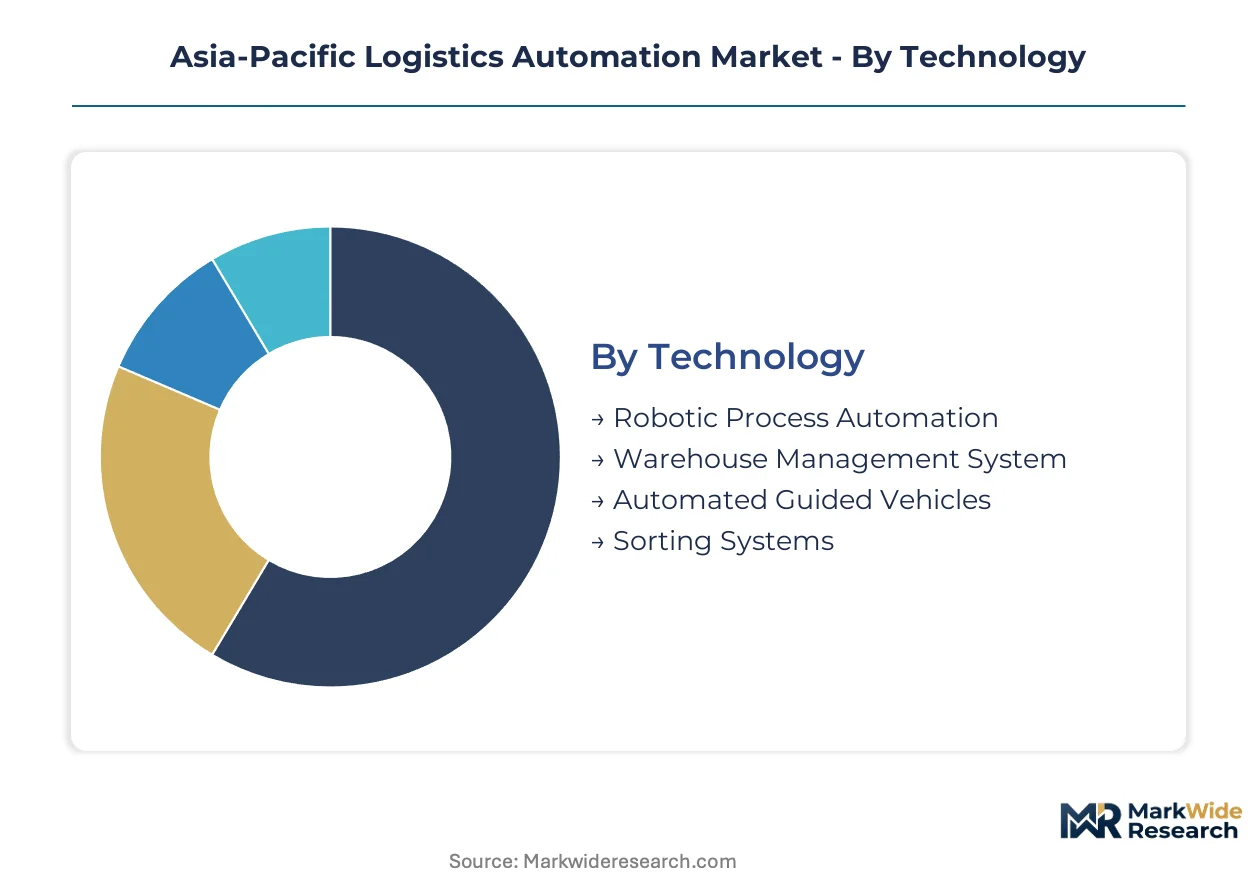
Segmentation in Asia-Pacific logistics automation reveals how procurement patterns diverge across technology maturity, end-use throughput requirements, and capital deployment preferences. Buyers in China's Yangtze River Delta cluster prioritize integrated technology stacks, while Southeast Asian third-party logistics providers favor modular offerings that preserve operational flexibility.
Technology:
Standardization dominates high-volume hardware categories, whereas software layers demand extensive customization to interface with legacy warehouse management architectures in Japan and South Korea.
- Warehouse Management System:Orchestrates robotic subsystems through real-time inventory tracking at the stock-keeping-unit level. Demand concentrates in China's bonded warehouse zones where MIIT smart logistics guidance mandates data interoperability between port automation and inland distribution nodes.
- Automated Guided Vehicles:Lithium-ion traction systems with lidar-based simultaneous localization and mapping navigation displace magnetic tape alternatives. Vietnamese and Indonesian e-commerce fulfillment centers specify lidar-native platforms exclusively, consolidating vendor share around suppliers with in-house sensor fusion capabilities.
- Robotic Process Automation:Software bots automate order entry, invoice matching, and carrier selection workflows. Australian pharmaceutical distributors deploy RPA to satisfy TGA documentation requirements.
- Sorting Systems:Conveyor modules exceeding 2.5 meters per second handle parcel throughput in Southeast Asian same-day delivery networks. Thailand's mid-market third-party logistics providers favor equipment-as-a-service arrangements with uptime guarantees.
Leading the category by volume: Warehouse Management System. Expanding most quickly: Automated Guided Vehicles.
End User:
Volume concentration and margin structure vary sharply across end-use verticals, with e-commerce operators absorbing capital intensity that healthcare and retail segments deflect toward operational expenditure models.
- E-commerce:Same-day delivery service-level agreements drive automated sortation and robotic picking deployment across Southeast Asian fulfillment centers. Malaysia's balance-sheet-constrained operators prefer throughput-based pricing contracts.
- Manufacturing:Semiconductor cleanroom logistics and automotive assembly line feeding dominate Japanese demand through Daifuku's installed base. India's PLI scheme for electronics redirects warehouse automation investment toward Gujarat and Tamil Nadu export hubs.
- Retail:Ambient temperature distribution networks in Australian metropolitan corridors adopt modular shuttle systems for seasonal demand surges.
- Healthcare:Temperature-controlled pharmaceutical logistics require TGA certification in Australia and MFDS compliance in South Korea, creating defendable margin pools for specialized integrators.
E-commerce commands the largest capital deployment. Healthcare posts the steepest expansion trajectory as regulatory compliance complexity deepens.
Offering:
Margin capture shifts from perpetual hardware licenses toward recurring software-as-a-service revenue as cloud-native architectures displace on-premises control systems.
- Cloud Solutions:Software-as-a-service deployments with throughput-based pricing concentrate recurring revenue streams among vendors serving mid-market third-party logistics providers. Southeast Asian buyers favor operational expenditure treatment for automation investments.
- Hardware:Conveyor modules, robotic manipulators, and automated storage equipment face GB standards compliance burdens from China's SAMR, protracting certification timelines for foreign suppliers.
- Software:Middleware development bridges proprietary WMS architectures with modern robotic control APIs in Japan and South Korea's brownfield facilities.
- Services:Integration, maintenance, and uptime guarantee contracts accompany equipment-as-a-service arrangements across Thailand and Malaysia.
Hardware retains the largest revenue base. Cloud Solutions gain share fastest as procurement patterns gravitate toward outcome-based contracts.
Installation:
Capital availability and technical staffing depth determine whether buyers absorb integration risk or transfer it to turnkey providers with localized engineering presence.
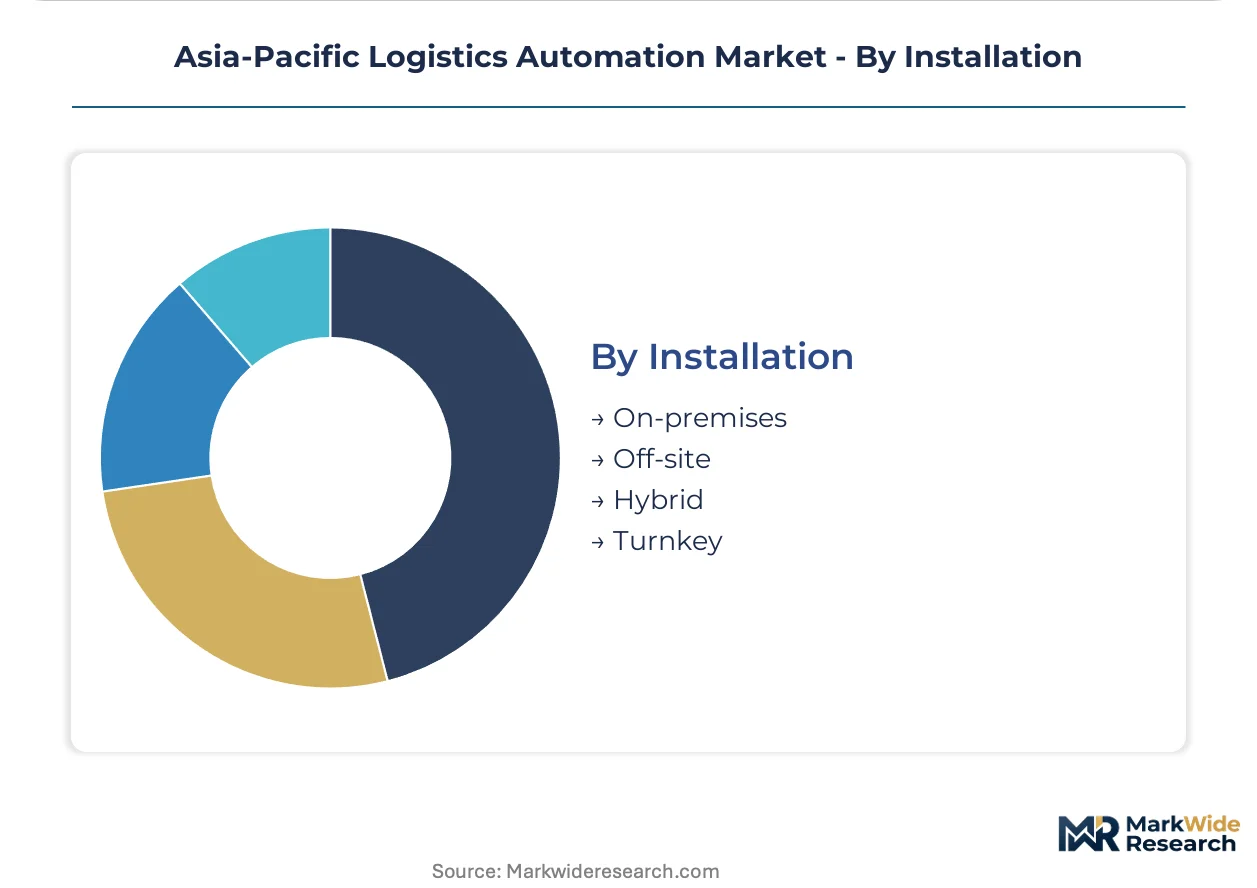
- Turnkey:Single-source accountability for design, installation, and commissioning appeals to operators lacking in-house robotics engineering capabilities. European and Japanese manufacturers establish localized testing partnerships in Shanghai and Suzhou to compress pre-market approval timelines.
- Hybrid:On-premises control hardware interfaces with cloud-based optimization layers, balancing data sovereignty requirements against software update velocity. South Korean electronics manufacturers favor this architecture.
- On-premises:Complete local deployment satisfies data residency requirements in China's bonded warehouse zones and Australia's pharmaceutical distribution networks.
- Off-site:Remote monitoring and diagnostics from vendor operations centers supplement on-site maintenance staff in Indonesia's archipelago logistics corridors.
Turnkey captures the majority of new project awards. Hybrid climbs fastest as brownfield modernization accelerates across Northeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China's Yangtze River Delta cluster, where port automation and bonded warehouse robotics absorb the majority of regional capital deployment. Southeast Asian third-party logistics providers are expanding automated sortation capacity to match same-day delivery service-level agreements. Japan and South Korea maintain advanced installed bases requiring brownfield modernization middleware.
China
MIIT smart logistics guidance accelerates port automation and bonded warehouse robotics deployment in the Yangtze River Delta cluster. SAMR-administered GB standards for automated storage equipment create protracted certification timelines that condition market access for foreign suppliers. Shanghai and Suzhou testing partnerships compress pre-market approval timelines for European and Japanese equipment manufacturers.
Japan
METI Industry 4.0 subsidies compress capital deployment timelines for semiconductor cleanroom logistics and automotive assembly line feeding systems. JIS industrial robot safety standards diverge from China's GB framework, forcing multi-source equipment procurement strategies to absorb integration complexity. The Kanto region around Tokyo anchors demand through Daifuku's installed base dominance.
India
The PLI scheme for electronics manufacturing redirects warehouse automation investment toward semiconductor and smartphone export hubs. Gujarat and Tamil Nadu emerge as concentration points for capital deployment tied to export-oriented manufacturing. The country's national electronics regulator shapes compliance requirements for automated storage equipment in these zones.
Vietnam
E-commerce fulfillment centers specify lidar-native Automated Guided Vehicle platforms exclusively, consolidating vendor share around suppliers with in-house sensor fusion capabilities. The country's rapid logistics infrastructure buildout attracts equipment-as-a-service arrangements from balance-sheet-constrained operators. Ho Chi Minh City and Hanoi corridors concentrate automated sortation deployment for same-day delivery networks.
Australia
TGA certification requirements for temperature-controlled pharmaceutical logistics create defendable margin pools for specialized integrators. Modular shuttle systems extend into cold-chain distribution networks serving metropolitan corridors. WorkSafe Victoria imposes material-handling equipment certifications that shape product specifications for healthcare logistics automation deployments.
Asia-Pacific Logistics Automation Market Competitive Landscape
Multi-source equipment procurement dominates the current landscape as third-party logistics providers assemble automation stacks from specialized vendors. The vendor base segments across Japanese cleanroom specialists, German forklift automation lines, and modular shuttle system providers. Three archetypes occupy distinct positions: integrated turnkey providers, component specialists with sensor fusion capabilities, and software-native orchestration platforms. Strategic partnerships and localized certification partnerships represent the dominant competitive moves as suppliers pre-validate systems against divergent national standards.
Among Japanese industrial conglomerates, Daifuku Co., Ltd. and Murata Machinery, Ltd. occupy positions representing the cleanroom logistics and precision automation archetype. KION Group AG and SSI Schaefer AG exemplify the European engineering credibility segment serving Chinese manufacturing plants and Australian cold-chain networks respectively. These named entities anchor broader patterns of geographic specialization and technology focus without exhaustively mapping competitive positions.
| Leading Market Players |
|---|
| ABB Ltd. |
| KION Group AG |
| Daifuku Co., Ltd. |
| KNAPP AG |
| SSI Schaefer AG |
| Murata Machinery, Ltd. |
| Toyota Industries Corporation |
| TGW Logistics Group |
| Swisslog Holding AG |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between GB-compliant systems for China's SAMR-administered bonded warehouses and JIS-certified installations for Japan's METI-subsidized facilities manifests in divergent pricing power and supply chain routing. Premium-tier vendors absorb localized testing partnerships in Shanghai and Suzhou to compress pre-market approval timelines, while commodity-tier suppliers face margin compression from lithium-ion traction battery cost declines and lidar sensor commoditization.
Pricing Analysis
Volume-mass hardware categories face margin erosion while software-orchestration layers capture pricing premiums. Three-tier pricing structure across premium certification-grade, standard interoperability-compliant, and economy non-certified equipment segments stratifies buyer access. Premium tiers command sustained pricing power through SAMR GB standards compliance and METI JIS certification investments. Cost compression in economy-tier conveyor modules and magnetic-tape AGVs intensifies because Vietnamese and Indonesian buyers specify lidar-native platforms exclusively. Mid-market third-party logistics providers across Thailand and Malaysia exhibit highest price sensitivity, preferring throughput-based SaaS contracts over capital expenditure models.
Supply Chain Analysis
Regional distribution centers in China's Yangtze River Delta cluster anchor hub-and-spoke patterns for port automation and bonded warehouse robotics deployment. Control system chipsets and servo motors concentrate in specialized East Asian manufacturing zones across China, Japan, and South Korea. Semiconductor component concentration exposes automation projects to input bottlenecks from single-source vulnerability in specialized foundry capacity. Distribution runs through turnkey integrators with localized engineering presence in Shanghai, Tokyo, and Ho Chi Minh City corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific logistics automation operates as a supply-constrained market where SLAM algorithm engineering talent scarcity props pricing for sensor-fusion-capable vendors. Capacity bottlenecks in certified systems integration preserve margin pools for pre-validated equipment suppliers.
For Market Incumbents: Lock in certification partnerships with SAMR-authorized testing bodies in Shanghai and Suzhou to compress GB standards compliance timelines. Deepen backward integration into lidar sensor fusion software development to marginalize magnetic-tape navigation alternatives. Channel control through equipment-as-a-service uptime guarantees defends against balance-sheet-constrained Southeast Asian operators demanding outcome-based contracts.
For New Entrants and Emerging Players: Launch via cloud-native Warehouse Management System orchestration platforms targeting mid-market third-party logistics providers in Vietnam and Indonesia. Australia's TGA-certified cold-chain pharmaceutical distribution networks represent the most penetrable geography given defendable margin pools and specialized integrator scarcity. Go-to-market angle centers on throughput-based SaaS pricing with embedded compliance documentation automation.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by industrial conglomerates seeking sensor fusion capabilities and regional certification assets. Long-term viability over the projection horizon hinges on software-defined control architectures displacing perpetual hardware licenses. Acquisition target archetype: modular shuttle system providers with Australian cold-chain TGA certification and in-house SLAM calibration expertise. Watch India's PLI scheme for electronics manufacturing as inflection indicator redirecting warehouse automation capital toward Gujarat and Tamil Nadu semiconductor export hubs.
| Strategic Initiative | Industry Significance |
|---|---|
| Localized Certification Partnership | Shanghai and Suzhou testing partnerships compress SAMR GB standards pre-market approval timelines for foreign equipment manufacturers. |
| Sensor Fusion Capability Buildout | In-house SLAM algorithm development consolidates vendor share as Vietnamese buyers specify lidar-native AGV platforms exclusively. |
| Equipment-as-a-Service Launch | Throughput-based SaaS contracts with uptime guarantees penetrate Thailand's balance-sheet-constrained mid-market third-party logistics segment. |
| Cold-Chain Certification Investment | TGA compliance for Australian pharmaceutical distribution creates defendable margin pools against commodity-tier conveyor competitors. |
| PLI-Aligned Geographic Expansion | Gujarat and Tamil Nadu facility deployment captures India's electronics manufacturing incentive-driven warehouse automation demand. |
Research Methodology
Multi-period observation of MIIT smart logistics infrastructure deployment rates, METI Industry 4.0 subsidy absorption timelines, and SAMR GB standards certification queues anchored the trend analysis, supplemented by interviews with warehouse operations directors at third-party logistics providers, robotics integration engineers, procurement leads at e-commerce fulfillment centers, and aftermarket service heads at AGV maintenance networks. Secondary validation drew from SAMR regulatory filings, METI subsidy disbursement records, Vietnam's e-commerce logistics infrastructure development databases, and Australian TGA medical device certification registers. Bottom-up project pipeline enumeration triangulated against top-down regional capital flow estimates.
Segment-weighting across technology type, end-use vertical, offering dimension, and installation model informed the analytical framework throughout the forecast period. Deployment velocity differentials between China's Yangtze River Delta cluster and Southeast Asian greenfield fulfillment centers shaped regional growth assumptions. CAGRs derived from equipment procurement cycle analysis, lithium-ion battery cost trajectory modeling, and cloud-native WMS subscription renewal rates across the projection horizon. Industry-specific inputs included SLAM engineer availability indices and brownfield modernization middleware development timelines for Japan and South Korea.
Semiconductor component supply disruptions, divergence between JIS and GB standards enforcement intensity, and lithium-ion raw material price volatility are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding subsidy continuity, certification timeline compression, and navigation technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Asia-Pacific Cold Chain Logistics Market
Logistics and Shipping
Mexico Road Freight Transport Market
Logistics and Shipping
Courier, Express and Parcel Services Market
Logistics and Shipping
India Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Air Cargo Capacity and Allotment Marketplace Platforms Market
Logistics and Shipping
Global Container Terminal Operations Market
Logistics and Shipping
Asia Pacific Finished Vehicle Logistics Market
Logistics and Shipping
Intralogistics Containers Market
Logistics and Shipping
Australia 3PL Market
Logistics and Shipping
Singapore Last Mile Delivery Market
Logistics and Shipping
Canada Road Freight Transport Market
Logistics and Shipping
North America Logistics Automation Market
Logistics and Shipping
Inbound Logistics Market
Logistics and Shipping
South Africa Air Freight Market
Logistics and Shipping
Tennessee Freight and Logistics Market
Logistics and Shipping
LAOS Freight and Logistics Market