
 Latin America Cold Chain Logistics Market | 2026-2036
Latin America Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Cold Chain Logistics Market Foresight
Pharmaceutical distribution is broadening the end-use vertical mix across Latin America as temperature-sensitive biologics and vaccines claim larger share of regional healthcare procurement. Frialsa Frigorificos anchors Mexican cold storage capacity through extensive refrigerated warehouse networks. Emergent Cold Latin America specializes in multi-temperature zone facilities serving Andean pharmaceutical corridors. Lineage Logistics extends automated warehousing technology into Brazilian protein export hubs.
Latin America cold chain logistics encompasses the temperature-controlled movement and storage of perishable goods, maintaining precise thermal bands from negative twenty degrees Celsius through fifteen degrees Celsius using vapor-compression refrigeration, insulated panels, and real-time telemetry. The primary commercial purpose centers on preserving biochemical stability of pharmaceuticals, nutritional value of fresh produce, and safety of frozen proteins across tropical and subtropical climates. Warehousing claims the dominant margin pool due to high fixed-asset barriers and multi-year customer contracts, while monitoring systems represent the fastest-expanding technology segment as traceability mandates intensify. Refrigerated transport remains the volume backbone, though margin compression persists from fuel cost volatility and driver scarcity across Central American corridors.
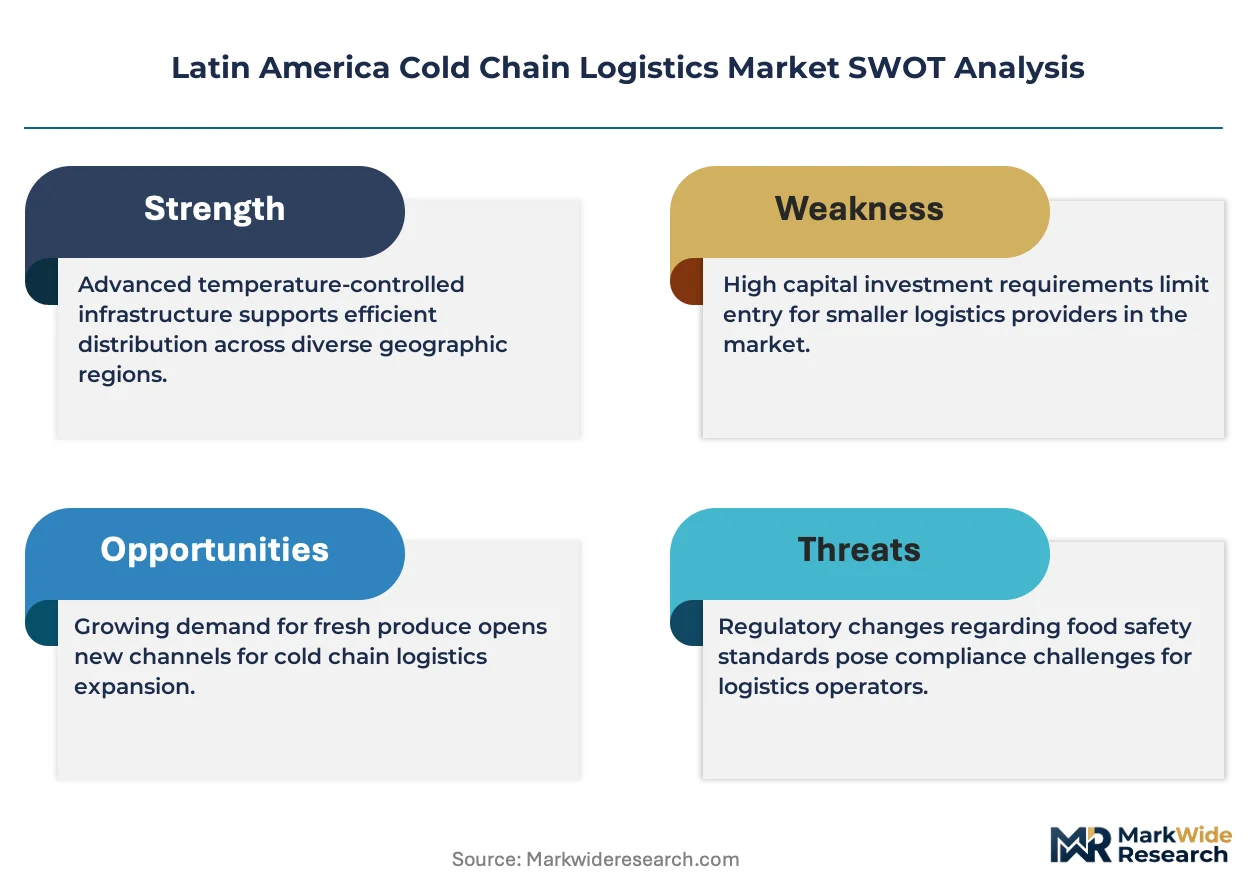
ANVISA in Brazil, COFEPRIS in Mexico, and INVIMA in Colombia enforce Good Distribution Practice standards that mandate continuous temperature documentation for pharmaceutical products, directly shaping capital allocation toward validated cold rooms and calibrated fleet equipment. The EU F-Gas Regulation and parallel Montreal Protocol phase-down commitments across Latin American signatories are accelerating fleet retrofit decisions away from high-GWP refrigerants. Stakeholders must monitor regulatory divergence between Mercosur and Pacific Alliance frameworks when configuring cross-border compliance architectures.
Market Dynamics
ANVISA, COFEPRIS, and INVIMA enforcement of Good Distribution Practice standards is compressing capital deployment timelines across pharmaceutical cold chain infrastructure. Operators must validate warehouse temperature mapping and fleet calibration before commercial launch, extending project cycles and elevating technical barriers to entry.
Growth Catalysts
- Biologics expansion:Temperature-sensitive monoclonal antibodies and cell therapies are claiming larger share of regional healthcare procurement, forcing distributors to upgrade from standard cold storage to ultra-low temperature infrastructure.
- EU F-Gas Regulation alignment:Montreal Protocol phase-down commitments across Latin American signatories are accelerating fleet retrofit decisions toward lower-GWP refrigerants, stimulating equipment replacement cycles.
- Southeastern Brazil logistics corridor:Concentration of protein processing and pharmaceutical manufacturing in São Paulo and Minas Gerais states is anchoring demand for multi-temperature zone warehousing capacity.
Market Restraints
- Diesel fuel volatility:Refrigerated transport operators face margin compression from fuel price swings across Central American corridors where rail alternatives remain underdeveloped.
- Driver scarcity:Qualified heavy vehicle operators with hazardous materials certification are concentrated in aging demographic cohorts, constraining fleet expansion.
- High-GWP refrigerant lock-in:Existing vapor-compression infrastructure using R-404A and R-507A faces accelerated obsolescence risk under national ozone layer protection regulations.
Strategic Opportunities
- Colombian Andean corridors:Bogotá and Medellín pharmaceutical clusters lack sufficient validated cold storage relative to production growth, creating white space for temperature-controlled logistics specialists.
- Real-time telemetry convergence:Integration of IoT sensors with blockchain traceability protocols is enabling outcome-based service contracts that tie logistics fees to temperature compliance performance.
- Direct-to-clinic distribution:Bypassing wholesale intermediaries for vaccine delivery to municipal health networks is opening channel restructuring opportunities in Mexican and Brazilian public procurement.
Industry Challenges
- Thermal validation engineering talent:Shortage of professionals capable of executing IQ/OQ/PQ protocols for pharmaceutical cold rooms is extending commissioning timelines.
- Multi-jurisdiction compliance complexity:Divergent Mercosur and Pacific Alliance technical standards for cross-border refrigerated transport create documentation friction for regional operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Cold Chain Logistics Market |
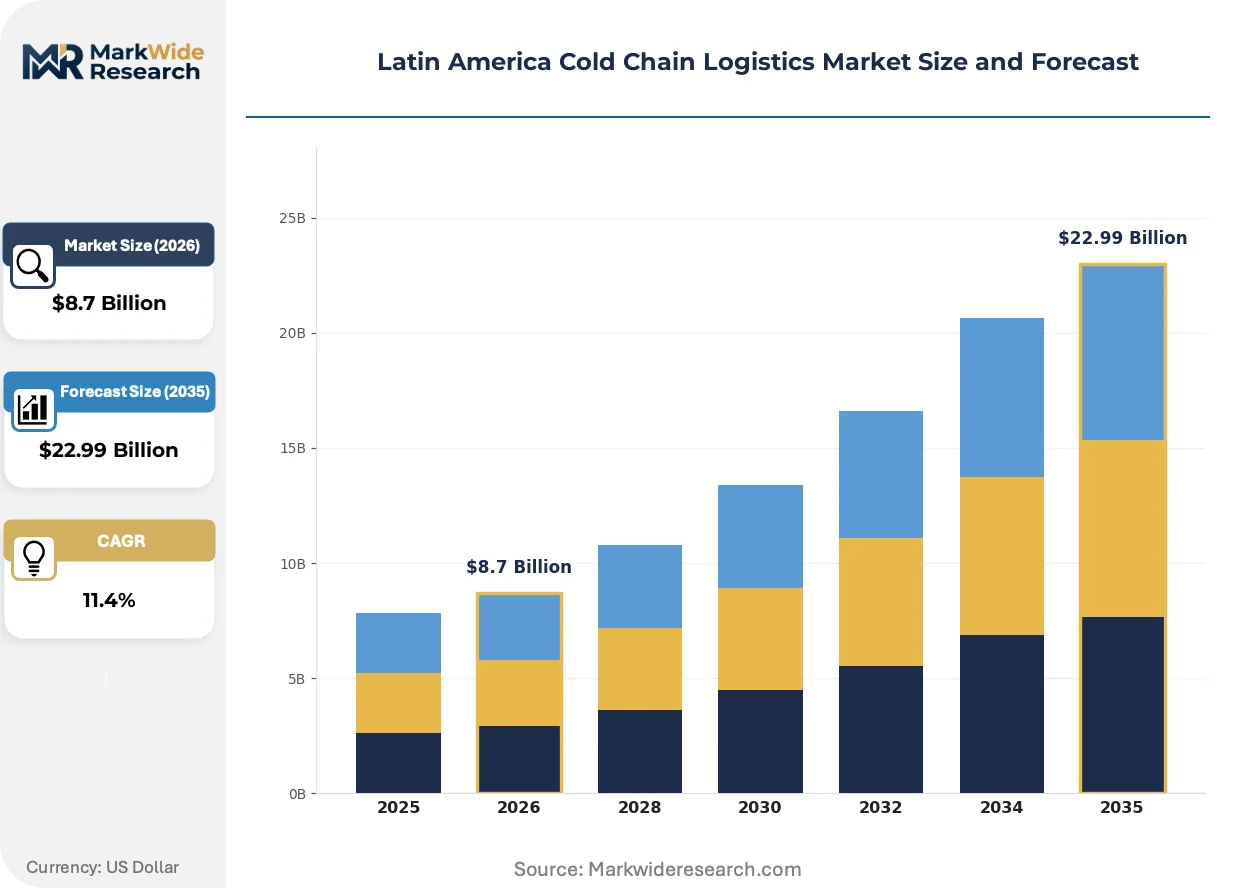
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Final Delivery Technology: Refrigerated Transport, Monitoring Systems, Packaging Solutions, Temperature Control End User: Pharmaceuticals, Food & Beverage, Biotechnology, Flowers Product Type: Fruits, Vegetables, Dairy Products, Frozen Foods |
| Companies Covered | Frialsa Frigorificos, Ransa Comercial, Emergent Cold Latin America, Comfrio Inteligencia em Solucoes Logisticas, DHL Supply Chain, Americold Logistics, SuperFrio Logistica Frigorificada, Friozem Logistica em Temperaturas Controladas, Lineage Logistics, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Cold Chain Logistics Market Shifts & Advancements
Automation and digital traceability are compressing operational cost structures while regulatory mandates harden compliance requirements. Equipment suppliers and logistics operators are converging on integrated platform strategies that bundle hardware, software, and validation services.
Phase-change materials and vacuum-insulated panels are expanding into last-mile vaccine distribution where passive thermal protection reduces mechanical refrigeration dependency. Municipal health ministries in Brazil and Mexico are adopting these systems for remote community outreach. The technology is expanding into territory previously served by active compressor units, enabling cost reduction in low-density geographic catchments.
ANVISA's updated Good Distribution Practice technical regulation is mandating continuous temperature documentation with audit trail integrity for pharmaceutical products. Wholesale distributors must deploy validated monitoring systems with alarm escalation protocols. Cold storage operators in São Paulo and Rio de Janeiro states are responding by consolidating fragmented warehouse footprints into centralized validated facilities.
Public health procurement is consolidating vaccine purchasing through federal centralized tenders, compressing supplier bases and elevating technical qualification thresholds. Smaller regional distributors are losing access to municipal health network contracts. This concentration is most visible in Brazilian Ministry of Health immunization programs, where three national logistics providers now capture majority volume.
Latin America Cold Chain Logistics Market Segmentation
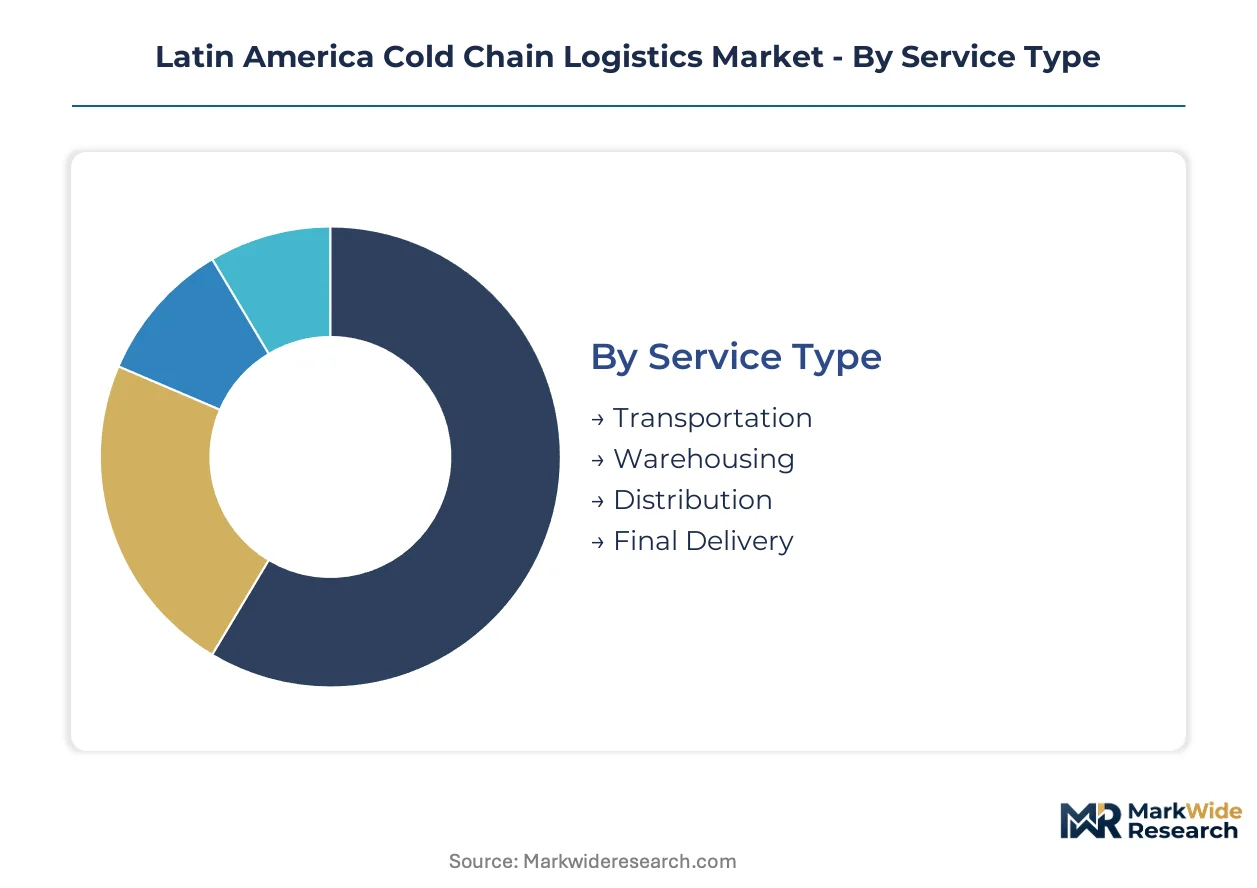
Cold chain logistics in Latin America fragments across service modalities, technology layers, and end-use verticals with diverging thermal requirements. Each segmentation axis reveals distinct buyer priorities: pharmaceutical distributors demand validated compliance infrastructure while protein exporters prioritize throughput velocity.
Service Type:
Buyers differentiate primarily by asset control requirements—those seeking captive capacity versus those accepting shared infrastructure.
- Transportation:Temperature-controlled fleet movement using vapor-compression refrigeration across highway corridors connecting São Paulo, Mexico City, and Bogotá. Diesel-powered refrigerated trucks dominate Brazilian protein export lanes where ANVISA mandates continuous temperature logging.
- Warehousing:Multi-temperature zone facilities with validated cold rooms serving pharmaceutical distributors under COFEPRIS and INVIMA compliance protocols. São Paulo's southeastern corridor concentrates regional capacity investments due to manufacturing density.
- Distribution:Consolidation and cross-dock operations linking import gateways to inland consumption centers. Mexican operators leverage Laredo-Nuevo Laredo corridors for US-bound produce re-export.
- Final Delivery:Last-mile refrigerated vans and passive thermal containers reaching municipal health networks and retail endpoints. Phase-change material systems are displacing mechanical units in remote Colombian Andean communities.
Volume sits with Transportation; growth tilts toward Warehousing.
Technology:
Capital deployment intensity separates segments—hardware-heavy refrigeration versus software-weighted monitoring platforms.
- Refrigerated Transport:Mechanical vapor-compression systems using R-404A and R-507A refrigerants facing accelerated retrofit timelines under Montreal Protocol phase-down commitments. Fleet operators in Central American corridors absorb fuel price volatility as margin pressure.
- Monitoring Systems:IoT-enabled telemetry with blockchain traceability integration capturing continuous temperature data for regulatory audit trails. ANVISA's updated GDP technical regulation is forcing wholesale distributor adoption of alarm-escalation protocols.
- Packaging Solutions:Vacuum-insulated panels and phase-change materials for passive thermal protection in low-density geographic catchments. Brazilian Ministry of Health immunization programs deploy these for remote outreach.
- Temperature Control:Precision HVAC and zone-segregation systems maintaining negative twenty through fifteen degrees Celsius bands. Ultra-low temperature infrastructure is expanding fastest for monoclonal antibody storage.
Revenue concentrates in Refrigerated Transport; Monitoring Systems are expanding most quickly.
End User:
Regulatory stringency stratifies buyers—pharmaceutical GDP compliance versus food safety protocols.
- Pharmaceuticals:Biologics, vaccines, and cell therapies requiring validated cold rooms with IQ/OQ/PQ protocols. COFEPRIS enforcement is compressing capital deployment timelines for Mexican distributors.
- Food & Beverage:Fresh produce, processed proteins, and dairy moving through temperature-controlled supply chains. Brazilian protein export hubs drive automated warehousing technology adoption.
- Biotechnology:Temperature-sensitive research materials and clinical trial specimens. Andean pharmaceutical corridors in Colombia lack sufficient validated storage relative to production growth.
- Flowers:Cut flower exports from Colombia and Ecuador requiring precise cold chain maintenance from farm to international air freight. Miami-bound corridors represent critical throughput volume.
Procurement volume centers on Food & Beverage; Pharmaceuticals show the steepest expansion trajectory.
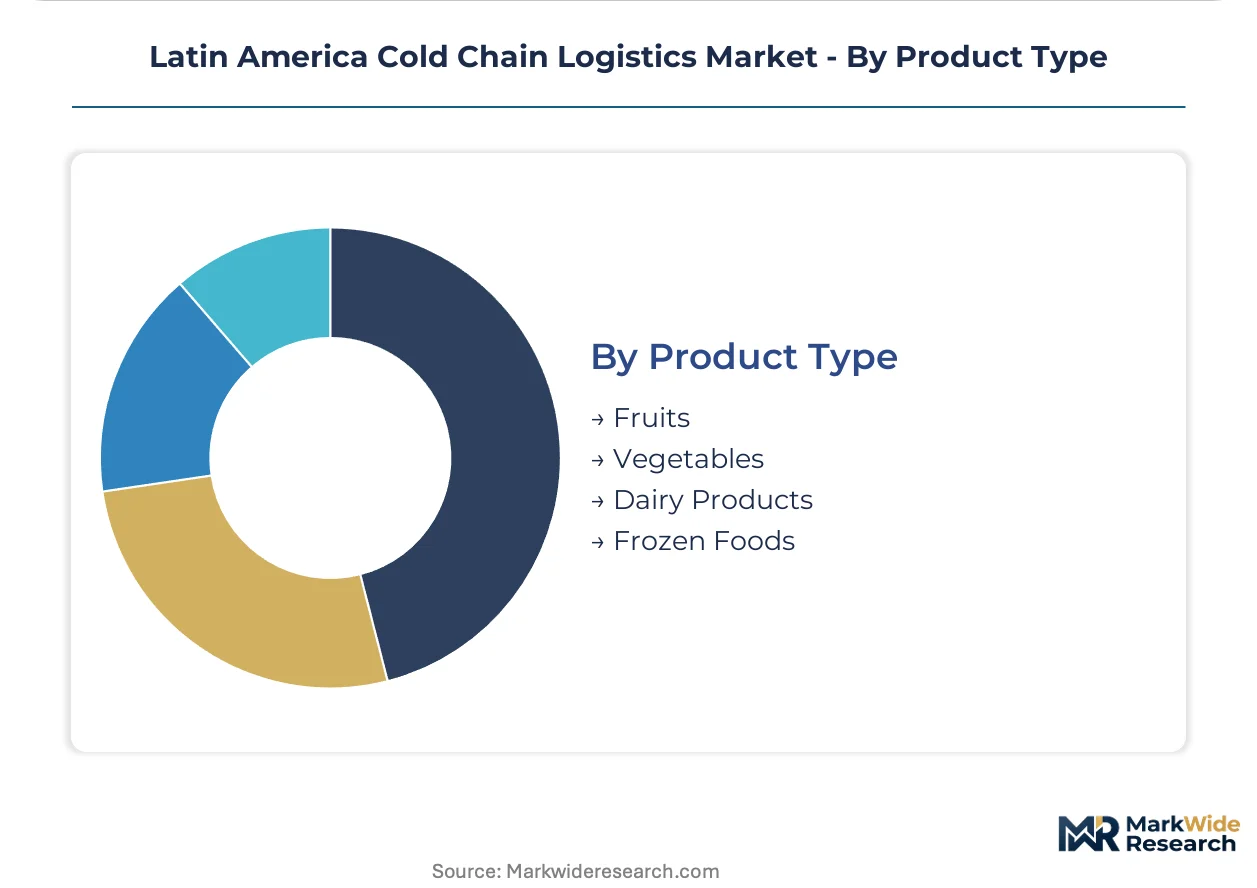
Product Type:
Perishability windows dictate infrastructure requirements—days versus months of shelf stability.
- Fruits:Tropical and temperate varieties moving through precooling and controlled atmosphere storage. Mexican export corridors to the United States concentrate seasonal volume spikes.
- Vegetables:Leafy greens and brassicas with compressed harvest-to-retail timelines demanding rapid cold chain entry. Central American production zones face transport infrastructure gaps.
- Dairy Products:Fresh milk, cheese, and yogurt requiring uninterrupted cooling from processing through retail. Brazilian southeastern states anchor domestic consumption gravity.
- Frozen Foods:Processed proteins and prepared meals stored at negative eighteen degrees Celsius. Frozen food demand is climbing fastest in urban Brazilian and Mexican markets.
Throughput concentrates in Fruits; Frozen Foods are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manaus Free Trade Zone incentives and São Paulo state logistics subsidies concentrate Brazilian cold chain investment. Mexican IMMEX maquiladora programs and Colombian Zona Franca benefits anchor Andean corridor development.
Brazil
São Paulo and Minas Gerais states concentrate pharmaceutical manufacturing and protein processing demand. ANVISA enforces Good Distribution Practice standards mandating continuous temperature documentation with audit trail integrity. The southeastern logistics corridor anchors multi-temperature zone warehousing capacity serving domestic distribution and export lanes.
Mexico
Biologics and vaccine procurement through federal centralized tenders is compressing supplier bases. COFEPRIS mandates validated cold rooms and calibrated fleet equipment under updated technical regulations. The Laredo-Nuevo Laredo corridor handles US-bound produce re-export with temperature-controlled cross-dock operations.
Colombia
Bogotá and Medellín pharmaceutical clusters lack sufficient validated cold storage relative to production growth. INVIMA enforces temperature validation protocols for monoclonal antibody and cell therapy distribution. Cut flower exports from the Sabana de Bogotá to Miami require precise cold chain maintenance through international air freight.
Argentina
Buenos Aires province concentrates domestic consumption gravity for frozen foods and dairy products. The national pharmaceutical regulator mandates compliance with Mercosur technical standards for cross-border refrigerated transport. Rosario and Córdoba industrial zones anchor grain and protein export cold storage infrastructure.
Chile
Salmon export volumes from Los Lagos and Aysén regions drive demand for ultra-low temperature logistics. The national fisheries service enforces cold chain integrity documentation for international market access. Santiago metropolitan distribution networks connect port terminals to inland consumption centers.
Latin America Cold Chain Logistics Market Competitive Landscape
Top-tier vendors anchor integrated platform strategies, while mid-scale operators concentrate on single-temperature specializations. The market exhibits moderate consolidation around warehousing-heavy players with multi-year pharmaceutical contracts. Three archetypes dominate: automation-integrated multinationals, regionally rooted cold storage specialists, and transport-focused fleet operators. Competitive moves center on capacity expansion in underserved Andean corridors and M&A consolidation of fragmented Brazilian warehouse footprints.
Within the regional specialist tier, Frialsa Frigorificos anchors Mexican refrigerated warehouse networks, Emergent Cold Latin America occupies a position serving Andean pharmaceutical corridors, and Lineage Logistics represents automated warehousing technology deployment in Brazilian protein export hubs. These three exemplify divergent strategic positions: captive domestic market density, cross-border corridor specialization, and technology-forward scale operations respectively.
| Leading Market Players |
|---|
| Frialsa Frigorificos |
| Ransa Comercial |
| Emergent Cold Latin America |
| Comfrio Inteligencia em Solucoes Logisticas |
| DHL Supply Chain |
| Americold Logistics |
| SuperFrio Logistica Frigorificada |
| Friozem Logistica em Temperaturas Controladas |
| Lineage Logistics |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up warehousing specialists in Brazil and Mexico anchor pricing discipline through multi-year pharmaceutical contracts, while sovereign-backed development finance in Colombia's Zona Franca zones subsidizes capacity buildouts that compress spot-market rates for transport-only operators. This ownership bifurcation creates tiered margin structures where validated cold rooms command premium economics against commoditized fleet services.
Pricing Analysis
Short lead-time premiums dominate pharmaceutical logistics contracts, with ANVISA-validated warehouse slots commanding substantial markups over standard cold storage while spot-market refrigerated transport faces persistent discount pressure. Three-tier pricing structure across GDP-certified, temperature-monitored, and basic refrigerated tiers reflects compliance investment differentiation. Price differentiation stems from certification grade and geographic delivery cost, with Andean corridor routes absorbing fuel volatility. Cost compression in Central American transport tiers is intensifying because diesel price swings outpace contract escalation clauses. Municipal health networks show highest price sensitivity; monoclonal antibody distributors show least.
Supply Chain Analysis
Domestic-content mandates in Brazil's Manaus Free Trade Zone and Mexico's IMMEX programs are reshaping sourcing patterns for refrigeration equipment and insulated panel systems. Manufacturing concentrates in Brazil, Mexico, and Colombia, with vapor-compression components drawing from Asian suppliers and control systems resting on European imports. Supply chain risk centers on single-source vulnerability for ultra-low temperature compressors. Distribution runs through São Paulo and Mexico City consolidation hubs before radiating to municipal endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ANVISA's updated Good Distribution Practice technical regulation erects barrier-to-entry moats that favor incumbents with validated infrastructure investments.
For Market Incumbents: Anticipate margin compression from passive thermal packaging substitution in last-mile vaccine distribution and consolidate fragmented warehouse footprints in São Paulo state before emerging cold storage specialists capture municipal health network contracts. Certification investment in ultra-low temperature infrastructure represents the priority defensive lever against biologics distributors insourcing storage capacity. For New Entrants and Emerging Players: COFEPRIS enforcement in Mexico opens a window for temperature-controlled logistics specialists to capture share from wholesale distributors losing federal tender access. White space concentrates in Colombian Andean corridors where Bogotá pharmaceutical clusters lack validated cold storage relative to production growth. Target direct-to-clinic distribution restructuring in Brazilian public procurement as the most penetrable entry angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Brazilian cold storage operators with ANVISA-validated facilities but suboptimal scale in São Paulo's southeastern corridor. Long-term viability hinges on multi-year pharmaceutical contract backlogs and automation technology deployment. Watch INVIMA enforcement intensity in Colombia as the signal indicating inflection toward consolidated supplier bases.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Validated cold room buildout in Colombian Andean corridors captures biologics production growth under INVIMA protocols. |
| Backward Integration | In-house phase-change material production reduces dependency on European packaging suppliers for vaccine outreach. |
| Regulatory Approval Pathway | ANVISA GDP certification accelerates contract eligibility for federal pharmaceutical tenders in Brazil. |
| Strategic Partnership | IoT telemetry alliances with blockchain providers enable outcome-based service contracts tied to temperature compliance. |
| Geographic Expansion | Central American corridor presence captures US-bound produce re-export through Laredo-Nuevo Laredo cross-dock operations. |
Research Methodology
Multi-period observation of refrigerated warehouse utilization rates, pharmaceutical tender award patterns, and fleet capacity deployments anchored the trend analysis, supplemented by interviews with cold storage operators, pharmaceutical distribution executives, fleet procurement managers, and regulatory compliance officers. Secondary validation drew from ANVISA technical regulations, COFEPRIS enforcement bulletins, customs trade data for refrigerated equipment imports, and industry association capacity surveys. Bottom-up facility-level capacity modeling and top-down healthcare procurement flow analysis provided triangulation.
Input-output matrices mapped service type, technology layer, and end-use vertical dimensions across the projection horizon, with CAGRs derived from segment-level capacity expansion announcements and pharmaceutical production forecasts. Segmentation modeling incorporated temperature zone requirements, regulatory compliance tiers, and geographic corridor density. Industry-specific forecast inputs included biologics pipeline advancement timelines and Montreal Protocol refrigerant phase-down schedules.
Caveats apply where diesel price volatility, driver demographic shortages, or Mercosur-Pacific Alliance regulatory divergence could materially shift the outlook for transport-heavy operators. Forecasts reflect assumptions regarding continued enforcement of GDP standards and pharmaceutical procurement centralization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
New Zealand Freight and Logistics Market
Logistics and Shipping
Fifth-Party Logistics Market
Logistics and Shipping
Last Mile Delivery Transportation Market
Logistics and Shipping
Asia-Pacific Pharmaceutical Logistics Market
Logistics and Shipping
GCC Finished Vehicle Logistics Market
Logistics and Shipping
Germany Contract Logistics Market
Logistics and Shipping
Canada 3PL Market
Logistics and Shipping
Automotive Logistics Market
Logistics and Shipping
ASEAN Domestic Courier Market
Logistics and Shipping
India Contract Logistics Market
Logistics and Shipping
Vietnam Express Delivery Services Market
Logistics and Shipping
China Automotive Logistics Market
Logistics and Shipping
Freight Brokerage Market
Logistics and Shipping
North America Cross Border Road Freight Transport Market
Logistics and Shipping
Netherlands Cold Chain Logistics Market
Logistics and Shipping
US Courier, Express, and Parcel Market