
 Rehabilitation Robots Market | 2026-2036
Rehabilitation Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Rehabilitation Robots Market Intelligence
Modular exoskeleton platforms that separate the powered hip-knee drive unit from the ankle module is repositioning procurement economics for hospital systems. Ekso Bionics leverages this architecture to sustain premium pricing in acute rehabilitation while offering stripped configurations for outpatient clinics. Hocoma AG anchors its European installed base through long-term service contracts tied to its Lokomat treadmill systems. Fourier Intelligence competes aggressively on sensor density, embedding force-torque arrays at six lower-limb joints to differentiate gait analytics.
Rehabilitation robots are electromechanical systems that apply controlled forces to human limbs during repetitive therapeutic movement, typically achieving positional accuracy within one degree and force resolution below one Newton for safe neuroplasticity induction. Their commercial purpose centers on accelerating motor recovery while reducing therapist physical strain during high-repetition sessions. Exoskeleton robots currently dominate capital expenditure budgets due to their versatility across stroke and spinal cord indications, whereas end-effector robots concentrate margin pools in upper-extremity clinics where workspace footprint constraints dominate. Artificial Intelligence integration represents the fastest-expanding technology layer, with machine learning models now predicting patient-specific gait patterns from initial assessment data to shorten device calibration protocols.
The FDA breakthrough device program and the EU Medical Device Regulation jointly shape market access timelines, with the former compressing premarket review for novel neuromotor platforms and the latter imposing clinical evidence requirements that favor established players with post-market surveillance infrastructure. Japan's Ministry of Health, Labour and Welfare reimbursement decisions for robot-assisted therapy codes directly determine addressable volume in the world's most penetrated rehabilitation robot market. Stakeholders must monitor evolving payer evidence requirements across these three jurisdictions, as divergence in clinical endpoints accepted for coverage will increasingly fragment product development roadmaps and regional go-to-market sequencing.
Market Dynamics
Japan's MHLW reimbursement expansion for robot-assisted gait therapy is compressing procurement cycles and redirecting capital flows toward lower-limb exoskeleton platforms, fundamentally altering how post-acute care facilities evaluate electromechanical investments.
Growth Catalysts
- FDA Breakthrough Device Designation:The pathway accelerates premarket review timelines for novel neuromotor platforms, reducing regulatory friction for first-mover entrants in stroke rehabilitation.
- German Bundled Reimbursement Contracts:Statutory health insurers and rehabilitation centers now favor capital-intensive electromechanical installations, locking in multi-year equipment refresh schedules.
- Sensor Density Advancement:Force-torque arrays embedded at six lower-limb joints enable granular gait analytics that justify premium pricing in competitive tenders.
Market Restraints
- EU MDR Clinical Evidence Burden:Post-market surveillance infrastructure requirements favor established players and erect barriers for mid-scale manufacturers lacking regulatory affairs capacity.
- Actuator Cost Volatility:Rare earth magnet supply concentration in China creates input cost instability for powered hip-knee drive units.
- Therapist Training Bottleneck:Specialized certification requirements for robot-assisted protocol administration limit deployment velocity in outpatient networks.
Strategic Opportunities
- Outpatient Clinic Stripped Configurations:Modular architectures separating hip-knee drive units from ankle modules unlock addressable volume in workspace-constrained ambulatory settings.
- AI-Driven Calibration Compression:Machine learning models predicting patient-specific gait patterns from initial assessment data reduce device setup time and expand daily patient throughput.
- Japanese Post-Acute Penetration:National insurer procedural code expansion creates direct reimbursement pathways for facilities scaling lower-limb exoskeleton purchases.
Industry Challenges
- Legacy EMR Integration Complexity:Gait analytics platforms face interoperability friction with entrenched hospital information systems, extending implementation timelines.
- Biomechanist Talent Scarcity:The specialized workforce combining robotics engineering with neurorehabilitation clinical knowledge commands premium compensation and constrains R&D velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rehabilitation Robots Market |
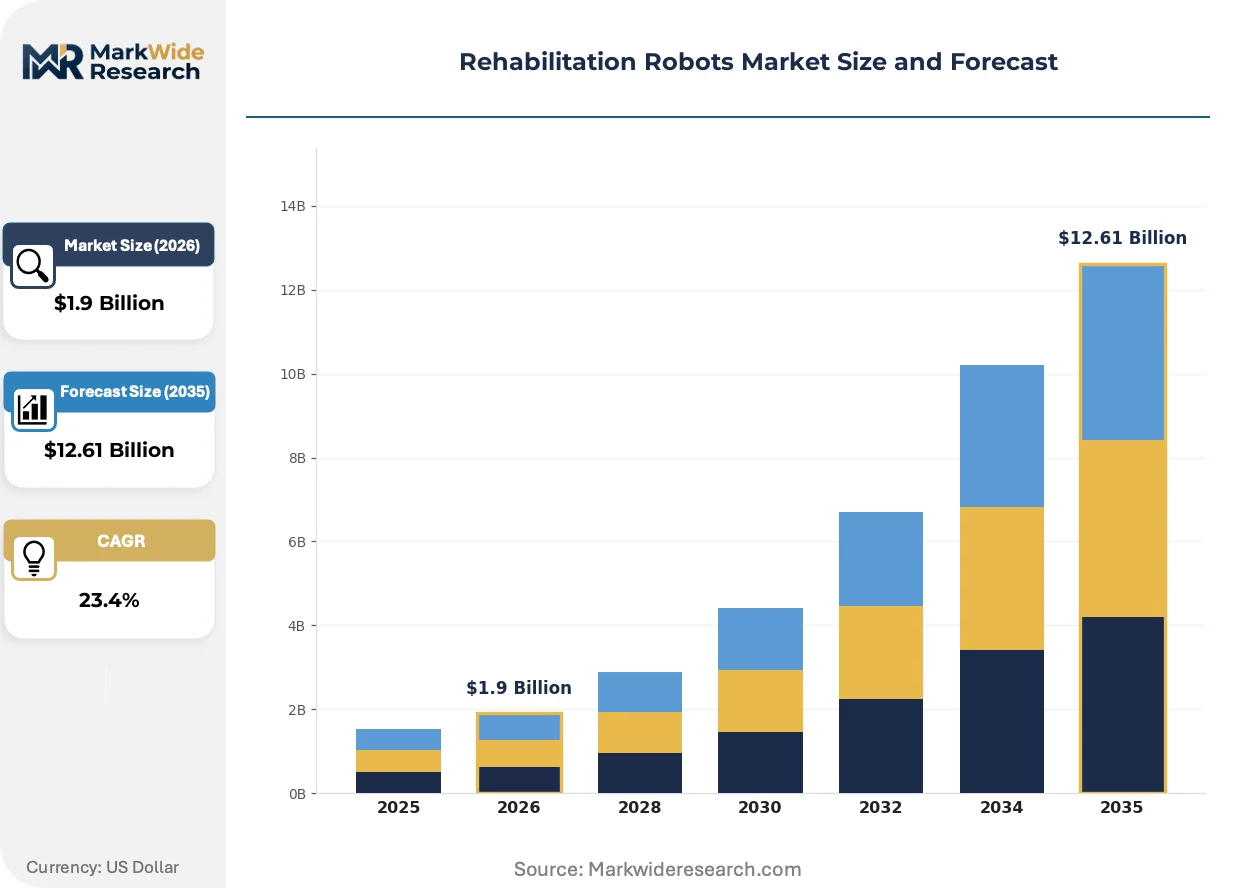
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $12.61 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exoskeleton Robots, End-Effector Robots, Treadmill-Based Robots, Wheelchair Robots Therapy Area: Stroke Rehabilitation, Orthopedic Rehabilitation, Neurological Rehabilitation, Sports Injury Recovery Care Setting: Rehabilitation Centers, Home Care, Outpatient Clinics, Nursing Facilities Technology: Artificial Intelligence, Sensor-Based Feedback, Electromechanical Systems, Virtual Reality Integration |
| Companies Covered | CYBERDYNE INC., Ekso Bionics, BIONIK, ReWalk Robotics, Hocoma AG, Rex Bionics Ltd., Tyromotion GmbH, AlterG, Inc., Fourier Intelligence, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rehabilitation Robots Market Strategic Shifts & Innovations
Artificial intelligence integration is compressing device calibration protocols and enabling predictive gait modeling, while regulatory pathway differentiation across FDA, EU MDR, and Japan's MHLW is fragmenting product development roadmaps.
Soft actuation technology is electrifying competitive positioning in pediatric and geriatric segments where rigid exoskeleton frames create safety liabilities. Children's rehabilitation centers in Germany and Japan are piloting pneumatic muscle-driven systems that reduce joint loading during fall events. The structural consequence is electrifying premium pricing power for platforms achieving compliant force control below one Newton resolution.
REACH substance restrictions and EU MDR post-market surveillance mandates are extending clinical evidence requirements for electromechanical rehabilitation devices. Manufacturers must now maintain active implantable-equivalent vigilance systems for non-implantable gait platforms. Upper-extremity end-effector robots face the steepest compliance cost escalation, pushing margin concentration toward exoskeleton architectures with clearer risk classification pathways.
Hospital procurement committees are unbundling long-term service contracts from initial capital purchases, forcing equipment vendors to compete on discrete maintenance pricing. Rehabilitation centers in Germany and Japan now separately negotiate Lokomat-style treadmill system servicing against third-party technical support providers. This disintermediation is most visible in statutory health insurer-contracted facilities where bundled reimbursement contracts previously locked in captive service relationships.
Rehabilitation Robots Market Segmentation
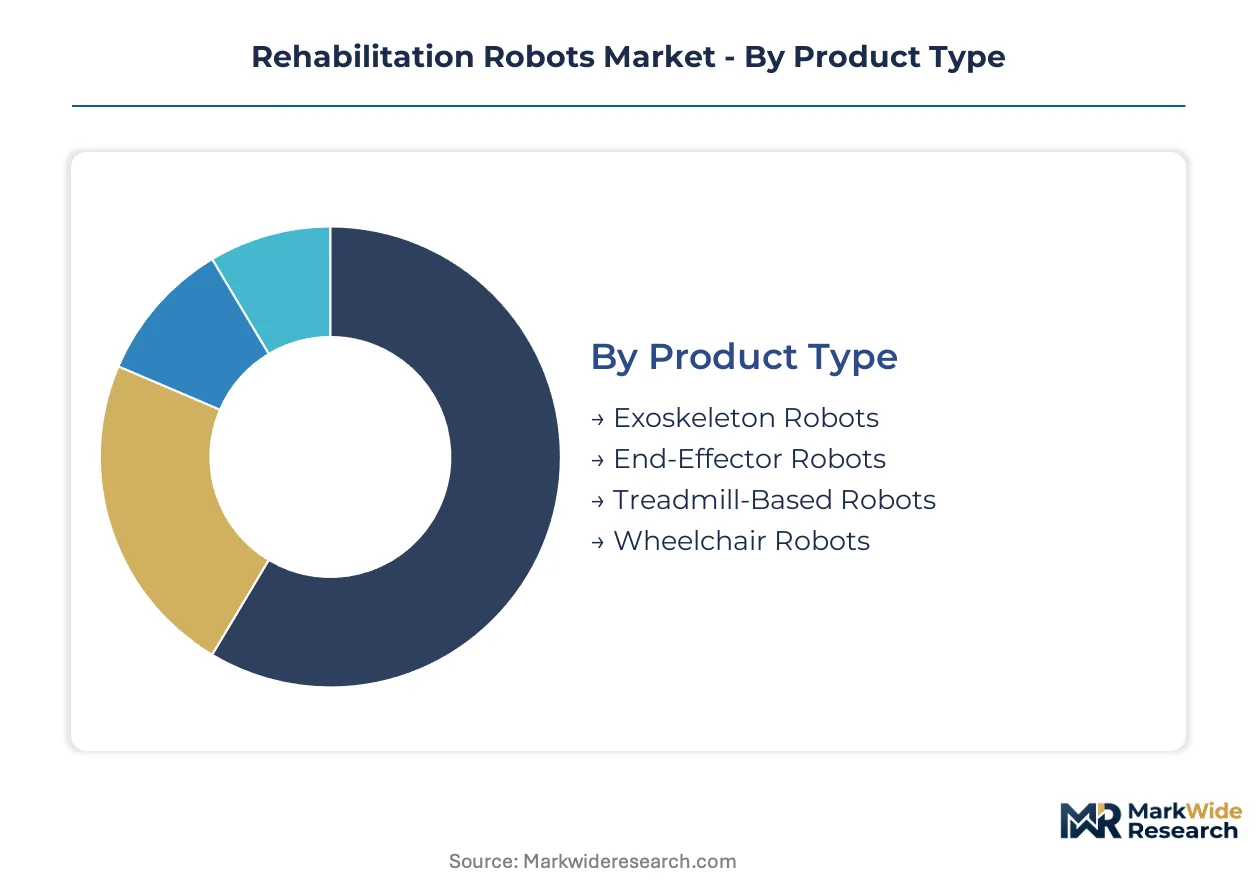
Segmentation in rehabilitation robotics reveals how procurement priorities diverge across care settings and therapeutic applications. Buyers evaluate capital intensity, workspace constraints, and reimbursement alignment differently depending on their patient volume and clinical specialization.
Product Type:
Hospital systems and outpatient networks select product architectures based on floor space availability, patient acuity, and therapist staffing ratios.
- Exoskeleton Robots:Powered hip-knee-ankle architectures deliver positional accuracy within one degree for neuroplasticity induction in stroke and spinal cord populations. Post-acute facilities in Japan concentrate procurement here as MHLW reimbursement codes expand for robot-assisted gait therapy.
- End-Effector Robots:Distal attachment systems manipulate patient limbs through mechanical linkages rather than full orthotic frames. Upper-extremity clinics in Germany favor these configurations where workspace footprint constraints dominate capital planning.
- Treadmill-Based Robots:Lokomat-style systems combine body-weight support with programmable gait patterns on moving belts.
- Wheelchair Robots:Mobile platforms integrate seated mobility with therapeutic limb manipulation for patients with severe motor impairment.
Exoskeleton robots lead volumes today; end-effector configurations are gaining share fastest in workspace-constrained ambulatory settings.
Therapy Area:
Clinical endpoints accepted by national insurers determine addressable demand within each therapeutic indication.
- Stroke Rehabilitation:Hemiparetic gait recovery protocols demand repetitive, high-intensity stepping practice that electromechanical systems deliver consistently. FDA breakthrough device designations compress time-to-market for novel neuromotor platforms targeting this population.
- Neurological Rehabilitation:Multiple sclerosis and Parkinson's disease presentations require adaptive force control that sensor-dense platforms provide. Bundled reimbursement contracts between German statutory health insurers and rehabilitation centers favor capital-intensive installations serving these chronic conditions.
- Orthopedic Rehabilitation:Post-surgical joint replacement recovery emphasizes range-of-motion restoration with controlled loading.
- Sports Injury Recovery:High-performance athletes require rapid return-to-play protocols with precise biomechanical monitoring.
Stroke rehabilitation anchors current installed base; neurological applications show steepest expansion trajectory as chronic disease prevalence rises.
Care Setting:
Capital deployment cycles and reimbursement pathways vary sharply across institutional and home-based environments.
- Rehabilitation Centers:High-throughput facilities amortize equipment costs across daily patient volumes exceeding outpatient benchmarks. German statutory health insurer contracts lock in multi-year equipment refresh schedules at these sites.
- Outpatient Clinics:Stripped modular configurations separating drive units from ankle modules unlock addressable volume where floor space and capital budgets constrain full-platform acquisition.
- Home Care:Lightweight, portable systems face reimbursement friction outside institutional procedural codes.
- Nursing Facilities:Long-term care operators prioritize fall-risk reduction over intensive motor recovery protocols.
Rehabilitation centers dominate capital expenditure; outpatient clinics represent the most rapidly expanding deployment channel.
Technology:
Technology layer selection determines calibration efficiency, clinical workflow integration, and premium pricing justification in competitive tenders.
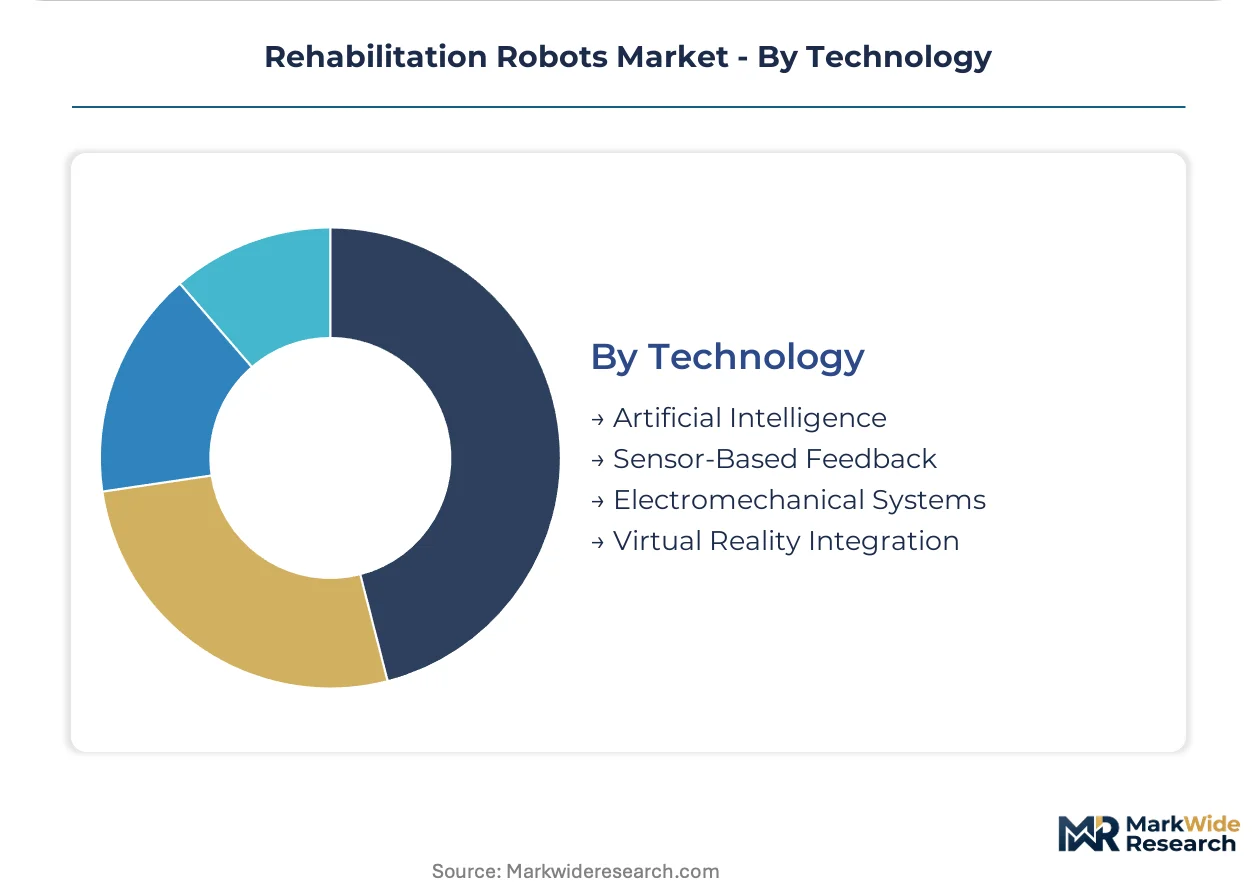
- Artificial Intelligence:Machine learning models predict patient-specific gait patterns from initial assessment data, compressing device setup protocols and expanding daily throughput. Sensor density advancement at six lower-limb joints enables granular analytics that justify premium positioning.
- Sensor-Based Feedback:Force-torque arrays embedded at hip, knee, and ankle joints capture real-time biomechanical data for therapist monitoring and protocol adjustment.
- Electromechanical Systems:Traditional motor-and-gearbox architectures remain cost-competitive where basic repetitive movement suffices.
- Virtual Reality Integration:Immersive environments enhance patient engagement during monotonous repetition protocols.
Artificial intelligence integration commands the highest R&D investment; sensor-based feedback layers expand most quickly across mid-tier product lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The rehabilitation robots industry traces its commercial origins to Switzerland and Japan, where early electromechanical gait systems emerged from university medical engineering programs in the late 1990s. These two countries established the regulatory and reimbursement templates that subsequent markets adapted.
United States
Post-acute rehabilitation networks in Florida and California are expanding capital budgets for exoskeleton platforms as Medicare Advantage plans pilot bundled payments for stroke recovery. FDA breakthrough device designations compress premarket review timelines for novel neuromotor platforms. The Boston-Worcester corridor hosts concentrated clinical trial activity for upper-extremity end-effector systems.
Japan
Post-acute care facilities in Osaka and Nagoya are scaling purchases of lower-limb exoskeleton units as MHLW expands procedural codes for robot-assisted gait therapy. National insurer reimbursement decisions directly determine addressable volume in the world's most penetrated rehabilitation robot market. The Kanto region around Tokyo anchors installed base maintenance for Lokomat-style treadmill systems.
Germany
Statutory health insurers and rehabilitation centers in Bavaria and North Rhine-Westphalia favor capital-intensive electromechanical installations through bundled reimbursement contracts. These agreements lock in multi-year equipment refresh schedules at high-throughput facilities. The Baden-Württemberg cluster around Stuttgart concentrates sensor engineering talent for force-torque array development.
Switzerland
Rehabilitation centers in Zurich and Geneva maintain premium pricing tolerance for AI-integrated platforms that compress device calibration protocols. Swissmedic's streamlined risk classification for non-implantable gait systems accelerates market access relative to EU MDR timelines. The Basel-Lucerne corridor hosts specialized biomechanist training programs that constrain regional R&D velocity.
South Korea
Outpatient clinic networks in Seoul and Busan are piloting stripped modular configurations where floor space constraints dominate capital planning. MFDS regulatory harmonization with FDA breakthrough pathways reduces time-to-market for imported neuromotor platforms. The Gyeonggi-do manufacturing belt around Seoul supplies rare earth magnet components for powered hip-knee drive units.
Rehabilitation Robots Market Key Industry Players
Premium-margin players sit above commodity-margin players across sensor density and AI integration capabilities, with the former commanding pricing power through granular gait analytics. The vendor base stratifies into three tiers: integrated platform developers, modular subsystem specialists, and regional assembly operations. Strategic archetypes include sensor-dense differentiation specialists, long-term service contract anchors, and aggressive pricing entrants from East Asian manufacturing bases. Dominant competitive moves encompass technology licensing for AI calibration modules and backward integration into force-torque sensor production.
Within the integrated platform tier, CYBERDYNE INC. and Ekso Bionics occupy positions as archetype representatives of full-system developers with established clinical validation pathways. Hocoma AG exemplifies the service-contract anchor model through its European installed base maintenance operations. Fourier Intelligence sits within the sensor-density competitive vector, embedding force-torque arrays at multiple lower-limb joints to justify premium positioning in competitive tenders.
| Leading Market Players |
|---|
| CYBERDYNE INC. |
| Ekso Bionics |
| BIONIK |
| ReWalk Robotics |
| Hocoma AG |
| Rex Bionics Ltd. |
| Tyromotion GmbH |
| AlterG, Inc. |
| Fourier Intelligence |
| Others |
Cost & Logistics Intelligence
Soft actuation technology migration from rigid motor-and-gearbox architectures to pneumatic muscle-driven systems simultaneously reduces per-unit bill-of-materials complexity and concentrates component sourcing among specialized elastomer suppliers in Germany and Japan. This production-method transition compresses manufacturing overhead for pediatric configurations while creating captive supply relationships that insulate premium-tier vendors from rare earth magnet price volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies rehabilitation robot procurement by sensor density and AI integration depth. Price differentiation rests on FDA breakthrough designation status and bundled service contract attachment rates. Cost compression in the economy tier intensifies because outpatient clinics now unbundle long-term maintenance from capital purchases. Post-acute facilities in Japan exhibit lowest price sensitivity due to direct MHLW reimbursement codes, whereas German statutory insurer-contracted centers negotiate hardest on discrete maintenance pricing.
Supply Chain Analysis
Biomechanist talent scarcity in Baden-Württemberg and the Boston-Worcester corridor constrains R&D velocity and forces manufacturers to premium-compensate specialized engineering teams. Component sourcing concentrates in South Korea for rare earth magnet actuators, Germany for force-torque sensor arrays, and Switzerland for precision drive units. Supply chain risk centers on single-source vulnerability for pneumatic muscle elastomers subject to REACH substance restrictions. Distribution runs through hospital procurement committees and GPO contracts at rehabilitation centers, with direct manufacturer relationships dominating high-throughput German facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in rehabilitation robotics hinges on AI-driven calibration compression reducing therapist setup time and expanding daily patient throughput. Soft actuation adoption in pediatric segments enables premium pricing power through compliant force control below one Newton resolution.
For Market Incumbents: Acquire force-torque sensor production capabilities to backward-integrate into critical component supply and defend against Fourier Intelligence-style sensor-density competition. Lock in multi-year service contracts at German statutory health insurer-contracted facilities before procurement committees complete unbundling of maintenance from capital purchases. Invest in FDA breakthrough designation pursuit for novel neuromotor platforms to compress regulatory timelines against emerging entrants. For New Entrants and Emerging Players: FDA breakthrough device designation in the United States opens a window for first-mover positioning in stroke rehabilitation where premarket review timelines compress competitive entry. Target outpatient clinic networks in South Korea piloting stripped modular configurations where floor space constraints dominate capital planning and full-platform incumbents face pricing disadvantage. Pursue reimbursement strategy partnerships with Japanese MHLW procedural code expansion to access the world's most penetrated rehabilitation robot market. For Investors and Strategic Acquirers: Roll-up economics work for sensor-differentiated modular subsystem specialists because hospital procurement committees increasingly unbundle long-term service contracts and create acquisition targets with captive installed base relationships. Five-to-ten year viability favors platforms with demonstrated FDA breakthrough pathway navigation and established post-market surveillance infrastructure satisfying EU MDR clinical evidence burdens. Watch for divergence in clinical endpoints accepted by Japan's MHLW versus FDA versus EU MDR as inflection indicator for regional go-to-market sequencing fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| AI Calibration Module Development | Machine learning gait prediction reduces setup time and expands daily patient throughput at high-volume rehabilitation centers. |
| FDA Breakthrough Designation Pursuit | Accelerated premarket review compresses time-to-market for novel neuromotor platforms in stroke rehabilitation indications. |
| Force-Torque Sensor Backward Integration | In-house production of six-joint sensor arrays defends premium positioning against Fourier Intelligence differentiation tactics. |
| Japanese MHLW Reimbursement Strategy | Direct procedural code expansion unlocks addressable volume in post-acute care facilities scaling lower-limb exoskeleton purchases. |
| Modular Architecture Platform Launch | Separable hip-knee drive and ankle modules unlock workspace-constrained outpatient clinic demand outside rehabilitation center dominance. |
Research Approach
Multiple input streams — structured interviews with rehabilitation center clinical directors, biomedical engineers at exoskeleton manufacturers, and statutory health insurer contracts managers — were reconciled against FDA 510(k) and breakthrough device filings, EU MDR post-market surveillance databases, and Japanese MHLW reimbursement code announcements. Secondary validation drew from hospital procurement database records, GPO contract terms, and CMS Medicare Advantage bundled payment pilot disclosures. Bottom-up equipment shipment modeling and top-down addressable patient population sizing were triangulated to constrain forecast variance.
Historical volume trajectories from installed base maintenance records were cross-referenced against expert panel assessments of reimbursement expansion timing and AI integration adoption curves. Segmentation modeling spanned product architecture, therapy area indication, care setting capital deployment cycle, and technology layer integration depth. CAGRs were derived from regression analysis of procedural code expansion rates and equipment refresh schedules across German bundled reimbursement contracts. Industry-specific forecast inputs included therapist certification bottleneck severity and rare earth magnet supply concentration metrics.
Revisions become necessary when MHLW reimbursement code divergence from FDA clinical endpoints materializes, when EU MDR post-market surveillance infrastructure requirements shift, or when rare earth magnet supply disruptions propagate through actuator cost structures. Forecasts reflect assumptions about regulatory pathway harmonization and payer evidence acceptance thresholds. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
Global Gait Trainer Market
Rehabilitation Services
US Assisted Living Facility and Neurorehabilitation Market
Rehabilitation Services
US Speech Therapy Market
Rehabilitation Services
Outpatient Rehabilitation Services Market
Rehabilitation Services
Veterinary Rehabilitation Services Market
Rehabilitation Services
Wearable Neurorehabilitation Devices Market
Rehabilitation Services
Home Rehabilitation Products Market
Rehabilitation Services
Global Women Health Rehabilitation Products Market
Rehabilitation Services
Neurorehabilitation Gaming Systems Market
Rehabilitation Services
Rehabilitation Equipment Market
Rehabilitation Services
Occupational and Physical Therapy Services Market
Rehabilitation Services
United States Behavioral Rehabilitation Market
Rehabilitation Services
Global Outpatient Rehabilitation Centers Market
Rehabilitation Services
Speech Pathology Services Market
Rehabilitation Services
Global Medical Rehabilitation Services Market
Rehabilitation Services
US Physical Therapy Services Market