
 US Physical Therapy Services Market | 2026-2036
US Physical Therapy Services Market Size, Share, and Industry Trends Forecast 2026-2036
US Physical Therapy Services Market Intelligence
Episode-based bundling for joint replacement rehabilitation is consolidating buyer choice around comprehensive care pathways rather than discrete visits. U.S. Physical Therapy, Inc. leverages its outpatient clinic density to anchor regional network contracts in Sun Belt states. Select Medical competes through co-located inpatient and outpatient assets that sustain patient capture across acute-to-post-acute transitions. Hinge Health differentiates via digital musculoskeletal platforms that extend remote therapeutic monitoring into employer benefit designs.
Physical therapy services encompass evidence-based movement interventions delivered by licensed therapists to restore function, reduce pain, and prevent disability following injury, surgery, or chronic disease progression; treatment protocols typically specify session duration, therapeutic exercise load, and modality intensity calibrated to functional outcome measures. Manual therapy dominates service mix in orthopedic-focused outpatient clinics where higher reimbursement rates and established referral patterns concentrate margin pools. Telehealth delivery mode is expanding fastest within home health segments as remote patient monitoring integration and CMS billing code expansion enable virtual therapeutic exercise supervision. Aquatic therapy occupies a specialized niche in geriatric care settings where buoyancy-assisted movement reduces joint loading for osteoarthritis and fall-recovery populations.
CMS rules on outpatient therapy caps and functional limitation reporting shape provider documentation burden and reimbursement access for Medicare beneficiaries. State physical therapy boards and the Federation of State Boards of Physical Therapy govern licensure reciprocity and direct access authority, determining whether patients can self-refer without physician gatekeeping. Stakeholders must monitor evolving FDA guidance on software-as-medical-device classifications for digital therapeutic platforms that increasingly supplement or substitute in-person intervention.
Market Dynamics
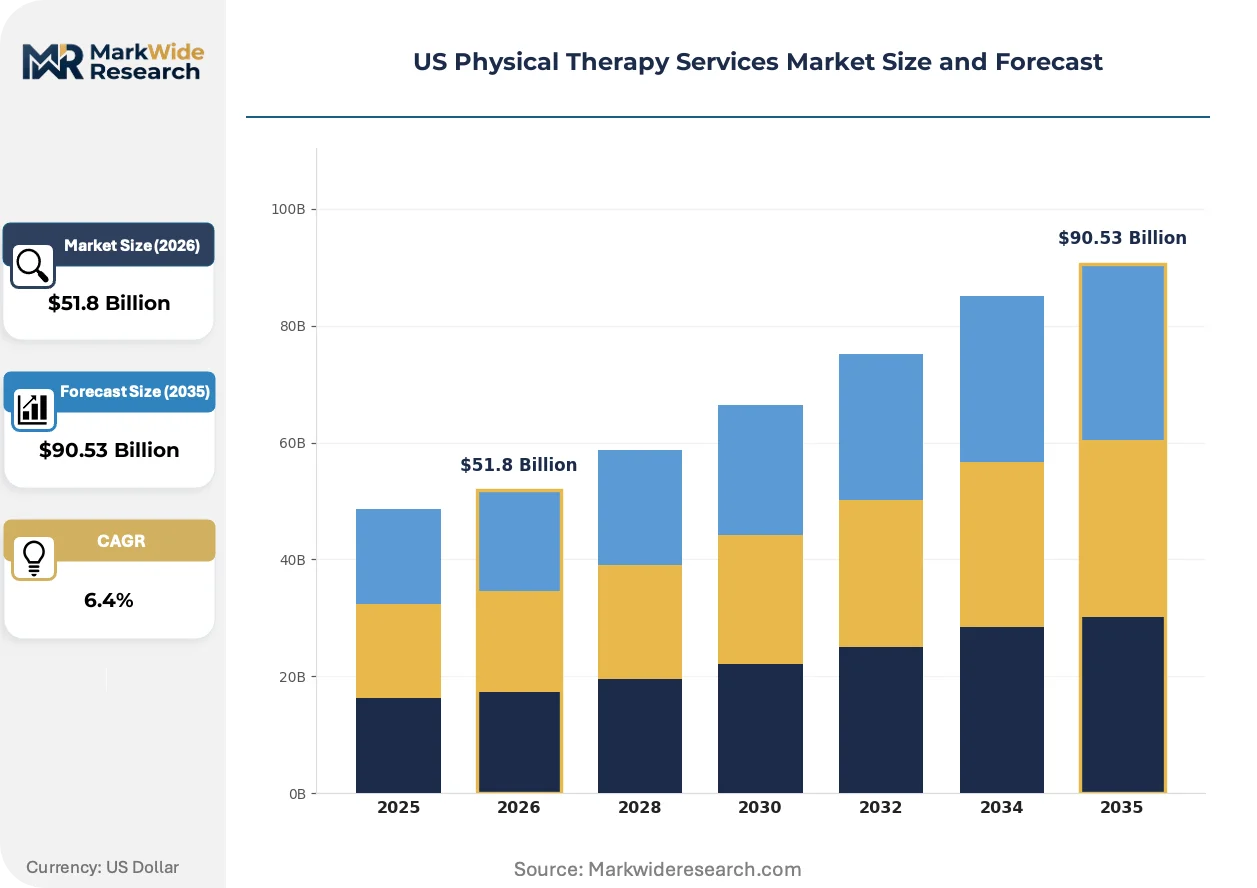
Medicare reimbursement expansion for outpatient rehabilitation services is consolidating provider economics around episode-based care models, compressing margins for standalone clinics while favoring integrated networks that can manage total cost of care across acute-to-post-acute transitions.
Growth Catalysts
- CMS Billing Code Expansion:Remote therapeutic monitoring codes now reimburse virtual exercise supervision, accelerating telehealth adoption in home health segments across Texas and Florida.
- Post-Acute Orthopedic Concentration:Joint replacement volume in California metropolitan corridors drives demand for bundled rehabilitation pathways that capture patients immediately post-discharge.
- Direct Access Authority:State-level self-referral permissions reduce physician gatekeeping friction, expanding addressable patient populations in Sun Belt markets.
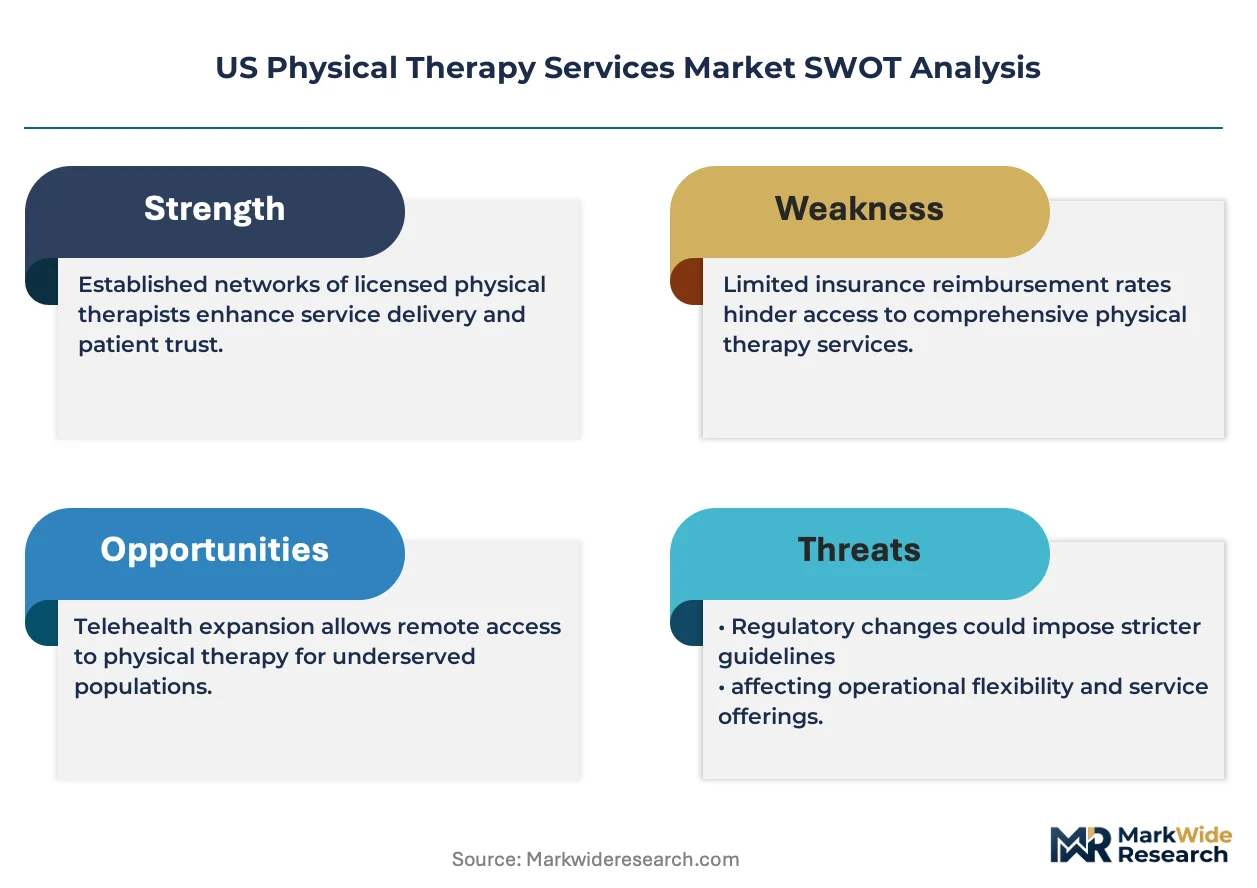
Market Restraints
- Functional Limitation Reporting Burden:CMS documentation requirements for therapy caps increase administrative overhead and claim denial risk for Medicare beneficiaries.
- Manual Therapy Labor Concentration:Service mix dependence on hands-on orthopedic intervention limits scalability and exposes margins to wage inflation in dense urban markets.
- Digital Therapeutic Regulatory Uncertainty:Pending FDA software-as-medical-device classifications for remote musculoskeletal platforms create compliance timeline risk for hybrid care models.
Strategic Opportunities
- Rural Underservice Gaps:Telehealth-enabled platforms can capture dispersed populations in non-metropolitan Texas and Florida counties lacking clinic density.
- Employer Benefit Design Integration:Digital musculoskeletal solutions embedded in self-insured health plans offer direct-to-payer contracting outside traditional referral networks.
- Aquatic Therapy Geriatric Specialization:Buoyancy-assisted movement programs for osteoarthritis and fall recovery address aging demographic concentration in California retirement corridors.
Industry Challenges
- Licensed Therapist Supply Constraints:State board licensure reciprocity limitations restrict labor mobility and create regional staffing shortages in high-demand metropolitan areas.
- Legacy Electronic Health Record Integration:Interoperability gaps between clinic management systems and hospital discharge planning tools fragment care coordination for bundled episodes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Physical Therapy Services Market |
| Market Size in 2026 | $51.8 Billion |
| Market Size in 2035 | $90.53 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Manual Therapy, Electrotherapy, Exercise Therapy, Aquatic Therapy End User: Hospitals, Rehabilitation Centers, Home Health, Outpatient Clinics Delivery Mode: In-Person, Telehealth, Group Sessions, Individual Sessions Treatment Focus: Musculoskeletal Disorders, Neurological Conditions, Sports Injuries, Geriatric Care |
| Companies Covered | Acadia Healthcare, Tenet Healthcare, U.S. Physical Therapy, Inc., FYZICAL, HCA Healthcare, Select Medical, Universal Health Services, Hinge Health, Encompass Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Physical Therapy Services Market Strategic Shifts & Innovations
Digital musculoskeletal platforms and remote monitoring technologies are compressing the traditional clinic-centric delivery model, enabling continuous therapeutic intervention outside facility walls while regulatory frameworks scramble to align reimbursement with virtual care modalities.
Sensor-enabled motion tracking systems paired with artificial intelligence coaching engines are rewriting how therapeutic exercise adherence is measured and reimbursed. Self-insured employers and Medicare Advantage plans are adopting these platforms fastest, seeking alternatives to per-visit fee structures. The technology is rewriting contract economics by substituting remote monitoring for supervised clinic visits in stable post-operative populations.
CMS rules on outpatient therapy caps and functional limitation reporting are tightening documentation standards for Medicare fee-for-service claims. Providers now face heightened audit exposure and pre-authorization requirements for extended treatment courses. Hospital-based outpatient departments in Texas and California are responding by embedding physical therapists in discharge planning workflows to justify medical necessity upfront.
Episode-based bundling for joint replacement rehabilitation is displacing discrete visit reimbursement with comprehensive care pathway contracts. Orthopedic surgery groups and skilled nursing facilities are consolidating purchasing around integrated providers that can guarantee functional outcome metrics. This shift is most visible in Florida metropolitan markets where Medicare Advantage penetration drives risk-based contracting preference.
US Physical Therapy Services Market Segmentation
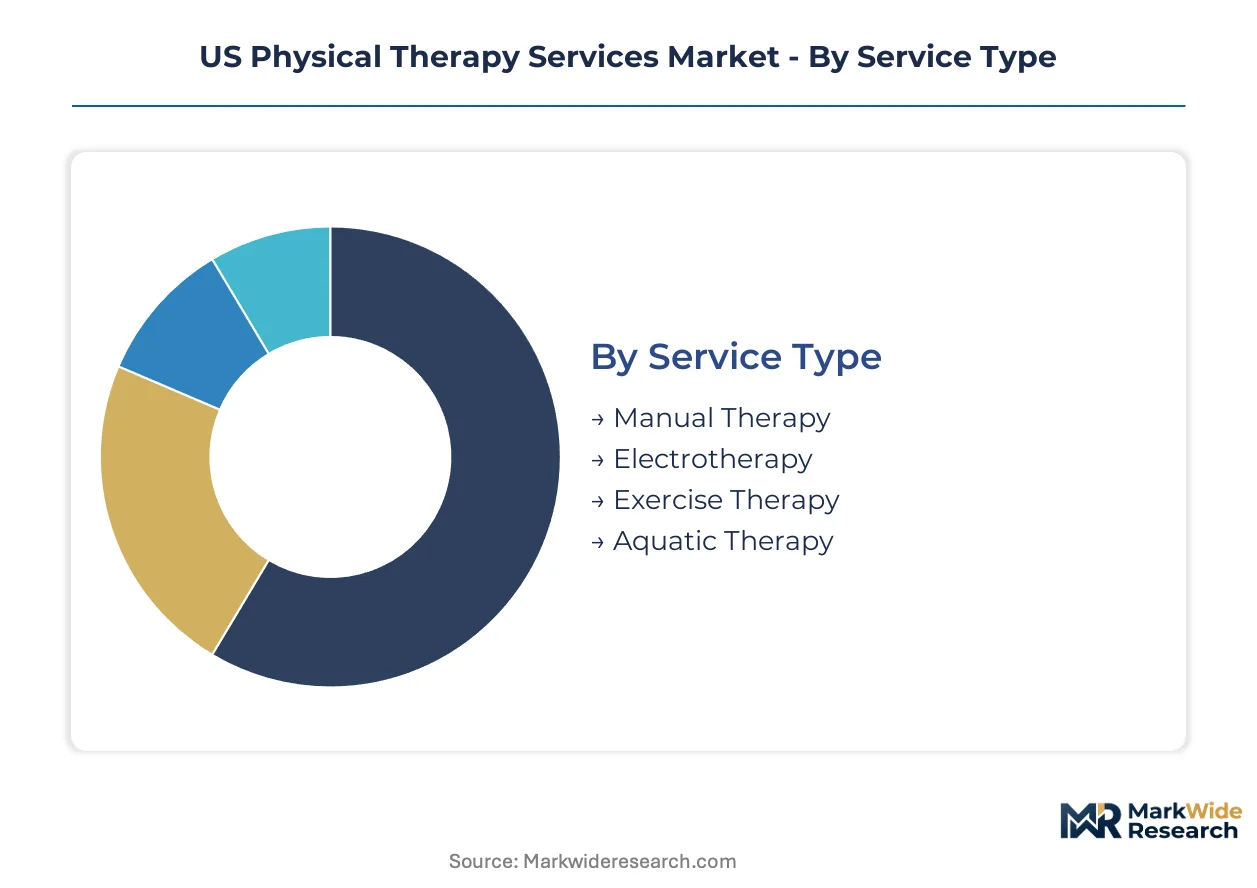
Service configuration determines reimbursement rates and labor intensity across the US physical therapy landscape. Segment boundaries increasingly blur as hybrid delivery models and bundled payment contracts reshape traditional category definitions.
Service Type:
Volume concentrates in hands-on orthopedic intervention, while premium margins accrue to specialized modalities requiring capital equipment or certified expertise.
- Manual Therapy:Hands-on joint mobilization and soft tissue manipulation techniques dominate outpatient orthopedic clinic revenue. Demand clusters in California metropolitan corridors where post-acute joint replacement rehabilitation drives referral volume and established physician relationships sustain pricing power.
- Exercise Therapy:Therapeutic exercise protocols emphasizing progressive loading and functional movement patterns anchor most treatment plans. Home health segments across Texas and Florida deploy remote monitoring to extend exercise supervision beyond clinic walls, capturing dispersed Medicare Advantage populations.
- Electrotherapy:Modalities including ultrasound and electrical stimulation supplement primary interventions for pain management and tissue healing. Equipment costs and technician training requirements limit penetration in independent practices.
- Aquatic Therapy:Buoyancy-assisted movement programs in specialized pool environments serve geriatric osteoarthritis and fall-recovery populations. California retirement corridors concentrate addressable demand for this labor-intensive, facility-dependent service.
Today's leader: Manual Therapy. Tomorrow's challenger: Exercise Therapy.
End User:
Site-of-care economics and referral control determine competitive positioning across institutional settings.
- Outpatient Clinics:Freestanding and hospital-affiliated facilities capture the majority of elective orthopedic rehabilitation volume. Episode-based bundling contracts in Florida metropolitan markets favor clinic networks with geographic density and outcome measurement infrastructure.
- Home Health:Skilled nursing and therapy services delivered in patient residences expand fastest under CMS remote therapeutic monitoring reimbursement expansion. Texas and Florida rural counties lacking clinic infrastructure represent untapped addressable populations for telehealth-enabled platforms.
- Hospitals:Inpatient and hospital-based outpatient departments retain surgical referral capture and complex case management. Discharge planning integration with physical therapy teams justifies medical necessity documentation for extended treatment courses.
- Rehabilitation Centers:Comprehensive inpatient rehabilitation facilities manage high-acuity neurological and polytrauma recovery. Length-of-stay regulations and prospective payment systems compress margins compared to outpatient alternatives.
Outpatient Clinics command current volume leadership. Home Health demonstrates the steepest expansion trajectory as virtual care modalities mature.
Delivery Mode:
Reimbursement alignment and patient acuity shape modality selection across the care continuum.
- In-Person:Traditional supervised clinic visits retain dominance for manual therapy and complex neurological rehabilitation. Dense urban markets in California face wage inflation pressure on labor-intensive delivery economics.
- Telehealth:Virtual therapeutic exercise supervision and remote patient monitoring accelerate under expanded CMS billing codes. Employer benefit designs and Medicare Advantage plans in Sun Belt states adopt fastest for stable post-operative populations.
- Individual Sessions:One-on-one therapist-patient encounters justify higher reimbursement rates and sustain margin pools in orthopedic-focused practices. Documentation requirements for medical necessity intensify under functional limitation reporting rules.
- Group Sessions:Concurrent treatment of multiple patients with similar conditions improves therapist productivity metrics. Geriatric fall prevention and chronic disease management programs deploy this model for maintenance-phase populations.
In-Person retains structural dominance. Telehealth emerges as the primary volume disruptor in post-acute and maintenance-phase segments.
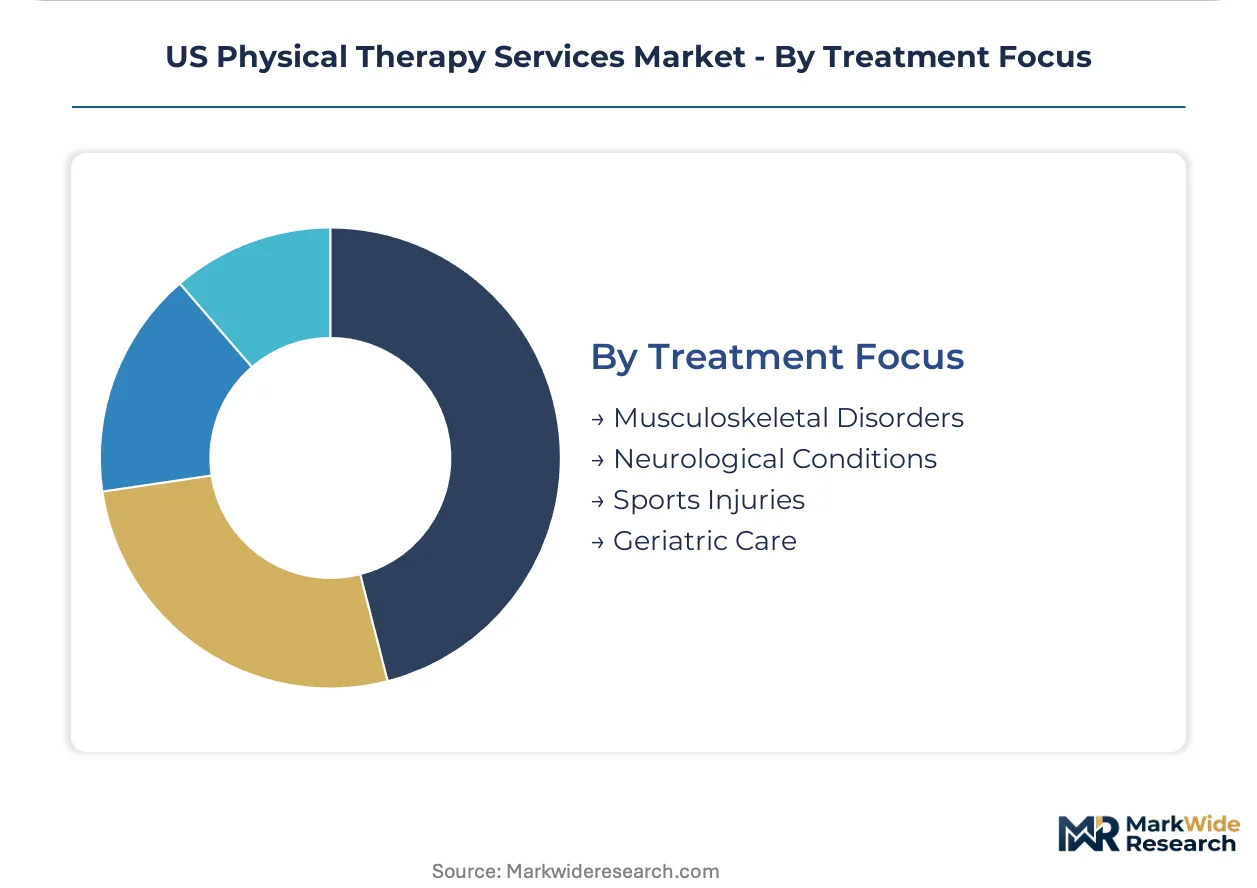
Treatment Focus:
Demographic concentration and surgical volume drive demand distribution across clinical indications.
- Musculoskeletal Disorders:Orthopedic conditions including joint replacement recovery, spine dysfunction, and sports injuries constitute the largest addressable population. Bundled payment contracts for joint replacement rehabilitation concentrate purchasing power in integrated provider networks.
- Geriatric Care:Age-related functional decline, osteoarthritis, and fall prevention address the fastest-growing demographic segment. California and Florida retirement corridors concentrate demand for mobility preservation and chronic condition management.
- Neurological Conditions:Stroke recovery, Parkinson's disease, and traumatic brain injury require specialized therapist certification and longer treatment durations. Inpatient rehabilitation facilities and dedicated neuro-focused outpatient centers capture this complex case volume.
- Sports Injuries:Athletic population rehabilitation spans acute injury management through return-to-sport protocols. Direct access authority in Sun Belt states reduces physician gatekeeping friction for this younger, commercially insured demographic.
Musculoskeletal Disorders anchor current revenue concentration. Geriatric Care presents the most durable long-term demand expansion profile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Physical therapy services first achieved systematic scale in the United States through post-World War II rehabilitation programs for veterans, establishing the clinical infrastructure and educational pathways that now concentrate demand across Sun Belt metropolitan corridors and aging coastal retirement zones.
California
Joint replacement rehabilitation volume in Los Angeles and San Francisco metropolitan areas anchors the nation's largest orthopedic therapy market. CMS functional limitation reporting requirements shape provider documentation practices across the state's hospital-based outpatient departments. Kaiser Permanente's integrated delivery networks in Oakland and Sacramento embed physical therapists in discharge planning workflows to capture bundled payment contracts.
Texas
Rapid metropolitan expansion in Dallas-Fort Worth and Houston generates sustained demand for post-acute musculoskeletal recovery services. State direct access authority permits patient self-referral without physician gatekeeping, expanding addressable populations in Austin and San Antonio corridors. Rural counties in West Texas and the Panhandle present telehealth-enabled service gaps that virtual therapeutic monitoring platforms target for penetration.
Florida
Retirement corridor concentration along the Gulf and Atlantic coasts concentrates geriatric mobility preservation demand in Tampa, Orlando, and Miami metropolitan zones. Medicare Advantage penetration rates exceed national averages, accelerating risk-based contracting preference among integrated provider networks. Episode-based bundling for joint replacement rehabilitation consolidates purchasing power around comprehensive care pathway guarantees in Jacksonville and Fort Lauderdale markets.
New York Metro
Dense urban infrastructure and aging building stock elevate fall-recovery rehabilitation needs across Brooklyn, Queens, and Manhattan patient populations. State physical therapy board licensure requirements create labor mobility friction that compounds wage inflation pressure in the five-borough zone. Hospital-affiliated outpatient departments in Long Island and Westchester County leverage discharge planning integration to justify extended treatment course medical necessity.
Illinois/Michigan/Ohio Midwest Cluster
Legacy manufacturing economies in Detroit, Cleveland, and Chicago industrial corridors sustain occupational therapy and work-hardening program demand. Blue Cross Blue Shield state plan variations influence reimbursement rate dispersion across the Rust Belt zone. Academic medical centers in Ann Arbor and Cleveland anchor specialized neurological rehabilitation capacity for stroke and traumatic brain injury recovery protocols.
US Physical Therapy Services Market Key Industry Players
The competitive structure tilts toward integrated network operators over standalone clinic operators. Consolidation pressure from episode-based bundling contracts compresses margins for independent practices while favoring multi-site platforms with geographic density and outcome measurement infrastructure. Two strategic archetypes dominate: clinic-dense regional networks anchoring bundled contracts, and technology-enabled virtual care platforms embedding in employer benefit designs. Competitive moves concentrate on M&A-driven geographic expansion and strategic partnerships with orthopedic surgery groups for referral capture.
Within the integrated network tier, U.S. Physical Therapy, Inc. and Select Medical exemplify the clinic-density archetype through multi-state outpatient platform scale. Hinge Health occupies a distinct position representing the digital-native therapeutic platform model that extends remote musculoskeletal intervention into self-insured employer contracts. These three entities anchor the competitive spectrum from facility-based to virtual-first delivery modalities.
| Leading Market Players |
|---|
| Acadia Healthcare |
| Tenet Healthcare |
| U.S. Physical Therapy, Inc. |
| FYZICAL |
| HCA Healthcare |
| Select Medical |
| Universal Health Services |
| Hinge Health |
| Encompass Health |
| Others |
Cost & Logistics Intelligence
Telehealth platform integration into Medicare reimbursement frameworks is simultaneously compressing per-visit fee structures and redistributing margin pools toward technology-enabled providers with scalable remote monitoring infrastructure. This shift concentrates pricing power among integrated networks that can substitute virtual touchpoints for labor-intensive clinic visits while standalone practices face margin erosion from wage inflation and documentation burden.
Pricing Analysis
Episode-based bundled contracts for joint replacement rehabilitation anchor the dominant pricing structure, replacing discrete per-visit reimbursement with comprehensive care pathway guarantees. Price differentiation rests on geographic clinic density and outcome measurement infrastructure, with integrated networks commanding premium rates in Florida metropolitan corridors. Cost compression in manual therapy segments intensifies because CMS functional limitation reporting requirements inflate administrative overhead. Self-insured employers demonstrate highest price sensitivity, while Medicare Advantage plans prioritize outcome guarantees over unit cost.
Supply Chain Analysis
State licensure reciprocity limitations and direct access authority variations create certification gating that fragments therapist labor mobility across state lines. Geographic supply concentration clusters in Texas, Florida, and California metropolitan corridors where aging demographics and orthopedic surgical volume concentrate demand. Licensed physical therapist workforce expansion draws from accredited university programs and cross-state recruitment. Single-source vulnerability runs through concentrated graduating class pipelines in high-demand urban markets. Distribution feeds from hospital discharge planning workflows through integrated provider networks and direct-to-patient telehealth platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Physical Therapy Services Market functions as a stable compounder anchored by demographic aging and chronic disease prevalence that sustains durable demand expansion regardless of cyclical fluctuations.
For Market Incumbents: Anchor regional network density through targeted clinic acquisitions in Texas and Florida retirement corridors to secure episode-based bundling contracts. Invest in remote therapeutic monitoring platform integration to defend against digital-native entrants substituting virtual care for in-person visits. Pursue backward integration into orthopedic surgery group partnerships to lock referral capture across acute-to-post-acute transitions. For New Entrants and Emerging Players: Enter via telehealth-enabled service gaps in rural Texas and Florida counties lacking clinic infrastructure, where CMS billing code expansion now reimburses virtual exercise supervision. Target Medicare Advantage penetration zones in Sun Belt states where risk-based contracting preference favors technology-enabled outcome guarantees. Deploy direct-to-payer contracting with self-insured employers outside traditional physician referral networks. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap regional clinic platforms with Medicare-heavy payer mixes facing reimbursement pressure. Long-term viability favors integrated networks with hybrid virtual-infrastructure capabilities and orthopedic surgery group affiliations. Watch FDA software-as-medical-device classification timelines as the signal indicating regulatory clarity for digital therapeutic platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Integration | CMS remote therapeutic monitoring codes enable virtual exercise supervision reimbursement in home health segments. |
| Orthopedic Surgery Group Partnership | Co-located or affiliated surgical practices secure referral capture for joint replacement rehabilitation episodes. |
| Geographic Clinic Density Expansion | Multi-site networks in Florida metropolitan corridors anchor bundled payment contract negotiations with Medicare Advantage plans. |
| Aquatic Therapy Specialization | Capital-intensive pool facilities in California retirement corridors address geriatric osteoarthritis demand with premium pricing. |
| Direct Access Authority Leverage | State-level self-referral permissions in Texas and Florida reduce physician gatekeeping friction for patient acquisition. |
Research Approach
Coverage spans California, Texas, Florida, New York Metro, and the Illinois-Michigan-Ohio Midwest cluster, with primary inputs from each region triangulated against secondary validation. Primary interviews incorporated physical therapy practice owners, hospital discharge planning directors, Medicare Advantage plan contracting officers, and state physical therapy board administrators. Secondary sources included CMS Medicare claims data, state licensure board filings, hospital procurement databases, and Federation of State Boards of Physical Therapy regulatory tracking. Bottom-up clinic capacity modeling and top-down payer expenditure analysis were cross-referenced for triangulation.
Rate-of-change decomposition across the projection horizon segmented volume and value outputs by service type, end user, delivery mode, and treatment focus dimensions. CAGRs were derived from historical Medicare expenditure trajectories, surgical volume forecasts, and demographic aging curves applied to regional penetration assumptions. Forecast inputs incorporated CMS billing code expansion timelines, state direct access authority legislative tracking, and FDA software-as-medical-device classification status.
Inputs from CMS administrative claims and state physical therapy board licensure databases were available through the study window; gaps in private payer contract rate transparency introduce uncertainty bands around revenue concentration estimates. Deviation in Medicare Advantage risk-based contracting adoption velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
Behavioral Rehabilitation Market
Rehabilitation Services
Rehabilitation Equipment Market
Rehabilitation Services
Exoskeleton and Rehabilitation Robot Safety and Performance Test Equipment Market
Rehabilitation Services
Physiotherapy Services Market
Rehabilitation Services
Rehabilitation Therapy Services Market
Rehabilitation Services
Rehabilitation Products Market
Rehabilitation Services
Global Gait Trainer Market
Rehabilitation Services
Veterinary Rehabilitation Services Market
Rehabilitation Services
United States Outpatient Rehabilitation Centers Market
Rehabilitation Services
Asia-Pacific Repair and Rehabilitation Market
Rehabilitation Services
US Speech Therapy Market
Rehabilitation Services
Global Home Rehabilitation Products and Services Market
Rehabilitation Services
Rehabilitation Robots Market
Rehabilitation Services
VR Stroke Rehabilitation Market
Rehabilitation Services
Global Women Health Rehabilitation Products Market
Rehabilitation Services
Portable Postpartum Rehabilitation Instrument Market