
 Global Pharma Knowledge Management Software Market | 2026-2036
Global Pharma Knowledge Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharma Knowledge Management Software Market Foresight
Modular platform bundling is restructuring how pharmaceutical buyers evaluate knowledge management vendors. SAP leverages its ERP backbone to embed compliance workflows directly into enterprise stacks. IQVIA anchors its offering with real-world data integration that spans clinical and commercial operations. Oracle Health Sciences dominates in large-cap biopharma accounts through database infrastructure that supports multi-site trial coordination.
Pharma knowledge management software comprises systems that capture, structure, and retrieve scientific, regulatory, and operational information across drug development lifecycles, typically integrating natural language processing and semantic search to surface insights from unstructured documents. Cloud-based deployment leads solution uptake as biotech firms prioritize scalable infrastructure without capital-intensive server commitments; pharmacovigilance application segments attract disproportionate investment due to stringent adverse-event reporting mandates. Document management and compliance management solution types command durable margin pools because validation requirements create switching costs that protect incumbent positions.
FDA 21 CFR Part 11, EMA GxP data integrity guidelines, and ISO 13485 quality management standards collectively elevate software validation requirements and shape procurement criteria across North America and Europe. The EU AI Act introduces new documentation burdens for machine-learning components embedded in knowledge retrieval systems. Stakeholders must weigh interoperability investments against emerging regulatory demands for algorithmic transparency in automated decision support.
Market Dynamics
Modular cloud architectures are fragmenting vendor lock-in across pharmaceutical enterprises, forcing incumbents to unbundle monolithic suites into interoperable components that buyers can mix across suppliers.
Growth Catalysts
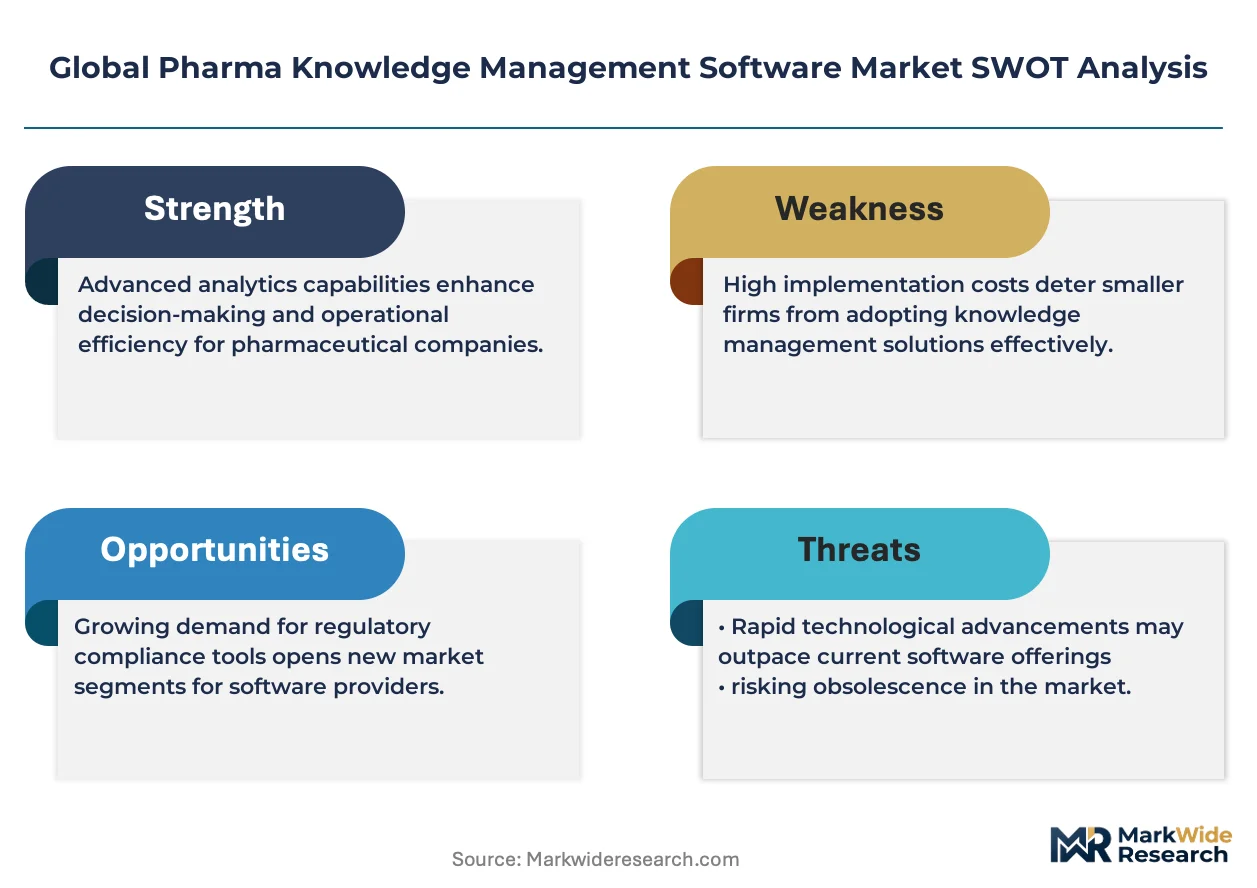
- FDA 21 CFR Part 11:Electronic records mandates compel legacy system upgrades, creating replacement cycles for validated document management platforms.
- Pharmacovigilance automation:Adverse-event reporting workloads expand as biologics pipelines thicken, driving demand for NLP-enabled case processing.
- Boston-San Francisco corridor:Venture-backed biotech clusters prioritize cloud-native knowledge infrastructure over capital-intensive on-premise deployments.
Market Restraints
- Validation cost structure:FDA-compliant software qualification requires 18-24 month documentation cycles that deter mid-tier buyers.
- Specialized talent scarcity:Professionals combining GxP compliance expertise with cloud architecture skills command premium compensation.
- Legacy system entrenchment:Document repositories built on 1990s-era databases resist API-based integration with modern analytics layers.
Strategic Opportunities
- India CDMO expansion:Contract manufacturing growth in Hyderabad and Bengaluru creates demand for multilingual regulatory submission platforms.
- EU AI Act documentation:Algorithmic transparency requirements for machine-learning retrieval systems open consulting-adjacent revenue streams.
- Real-world evidence convergence:Integration of clinical trial data with post-market surveillance records enables new subscription pricing models.
Industry Challenges
- Data migration complexity:Semantic normalization across unstructured document formats consumes 40% of implementation timelines.
- Cross-functional alignment:R&D, regulatory, and commercial teams maintain incompatible metadata taxonomies that fragment search efficacy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharma Knowledge Management Software Market |
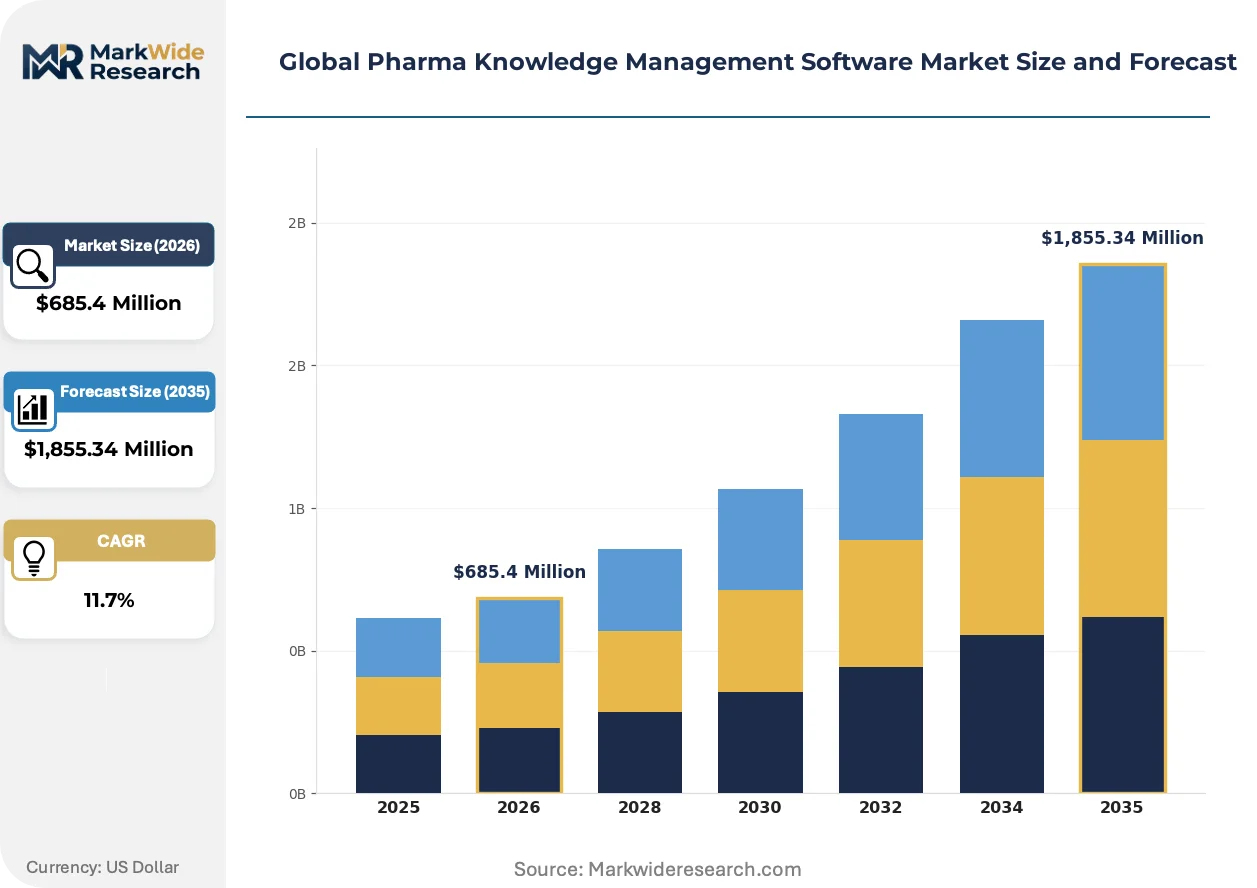
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,855.34 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Private Cloud Solution Type: Document Management, Collaboration Tools, Data Analytics, Compliance Management, Workflow Automation Application: Drug Discovery, Regulatory Intelligence, Clinical Trials, Medical Affairs, Pharmacovigilance End User: Pharmaceutical Companies, Contract Research Organizations, Biotech Firms, Academic Institutions, Government Agencies |
| Companies Covered | SAP, BenchSci, IQVIA, MasterControl, Sinequa, Oracle Health Sciences, Elsevier, Dassault Systèmes, Veeva Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharma Knowledge Management Software Market Shifts & Advancements
Knowledge retrieval architectures are pivoting from keyword indexing toward semantic graph structures that surface causal relationships between scientific findings.
Large language models fine-tuned on biomedical literature are overtaking traditional Boolean search in pharmacovigilance departments. Mid-size biotech firms deploy these systems within six-month procurement cycles. The shift compresses signal detection timelines from weeks to hours.
EMA GxP data integrity guidelines now mandate audit trails for knowledge system modifications. Pharmaceutical quality units must demonstrate procedural controls over AI-generated search rankings. European CROs are prioritizing vendors with pre-validated algorithmic transparency modules.
Subscription pricing for knowledge platforms is displacing perpetual license structures. Procurement teams negotiate usage-based tiers tied to document volume rather than seat counts. This restructuring is most pronounced among Series B biotechs in Cambridge and South San Francisco.
Global Pharma Knowledge Management Software Market Segmentation
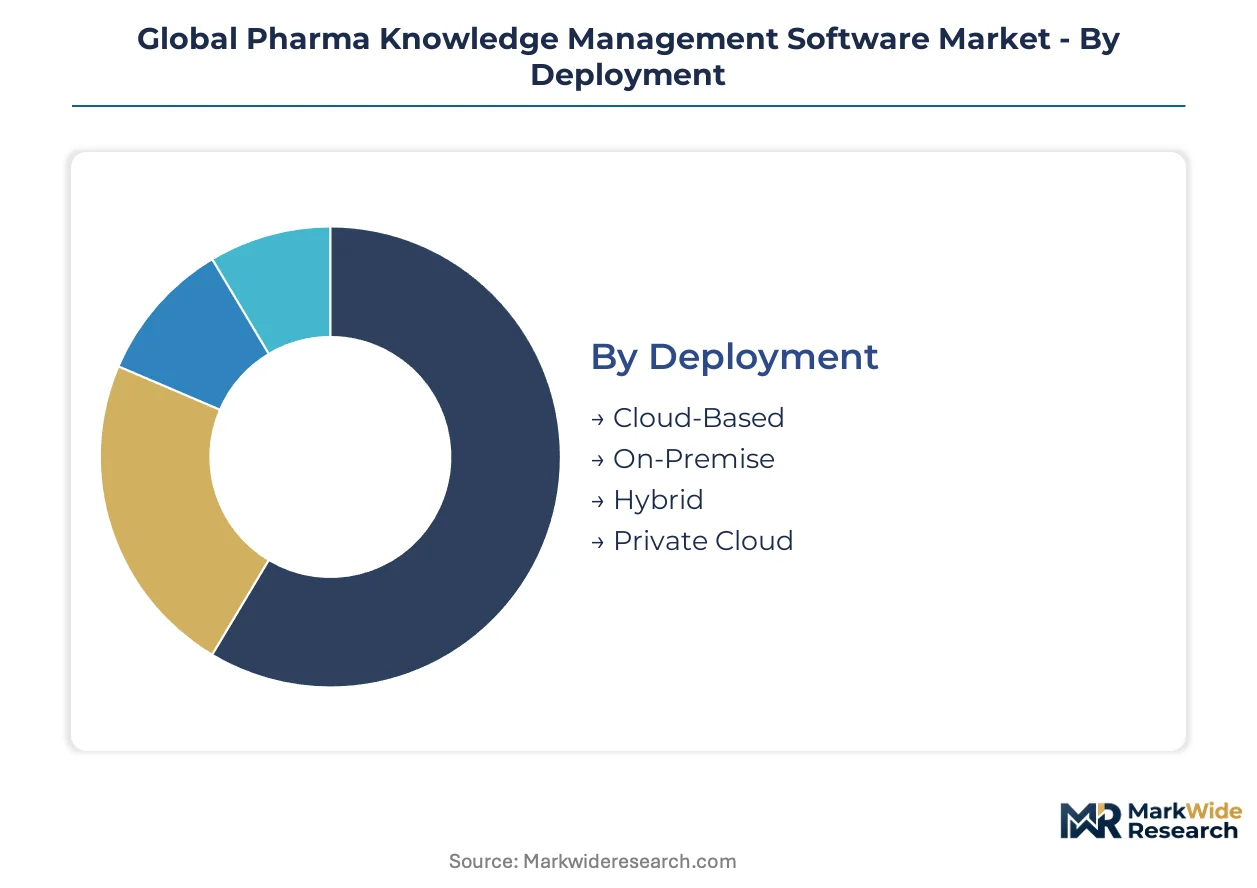
Pharmaceutical procurement teams evaluate knowledge management platforms through four intersecting lenses: infrastructure flexibility, functional depth, scientific use case, and organizational scale. Each segmentation axis carries distinct margin profiles and switching-cost dynamics that reshape vendor competitive positioning.
Deployment:
Cloud-based configurations dominate transaction volume while private cloud and hybrid deployments command premium pricing tiers.
- Cloud-Based:Multi-tenant SaaS architectures eliminate capital expenditure for server infrastructure. Series B biotechs in Cambridge and South San Francisco prioritize these platforms for rapid trial documentation deployment without IT headcount expansion.
- On-Premise:Legacy validated systems running on client-owned hardware persist among top-20 pharmaceutical manufacturers with existing data center investments. FDA 21 CFR Part 11 compliance documentation for these installations spans 18-24 month cycles.
- Hybrid:Split architectures segment sensitive regulatory data on-premise while pushing analytics workloads to cloud infrastructure.
- Private Cloud:Single-tenant dedicated environments address data sovereignty requirements from EMA and national European regulators.
Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
Solution Type:
Compliance and document management modules generate recurring revenue through validation-dependent renewal cycles, while workflow automation tools expand fastest among mid-market buyers.
- Document Management:Centralized repositories with version control and audit trails form the technical backbone of regulatory submission workflows. Pharmaceutical quality units in Germany and Switzerland mandate these systems for EMA GxP data integrity compliance.
- Compliance Management:Pre-validated workflow engines embed FDA, EMA, and ISO 13485 requirements directly into software logic. Switching costs protect incumbent positions as re-qualification expenses deter platform migration.
- Collaboration Tools:Real-time co-authoring and annotation features accelerate cross-functional protocol development.
- Data Analytics:Semantic search and natural language processing layers extract insights from unstructured clinical literature.
- Workflow Automation:Rules-based routing engines streamline pharmacovigilance case processing and adverse-event reporting.
Compliance Management anchors current margins. Workflow Automation is gaining share fastest.
Application:
Pharmacovigilance and clinical trials attract disproportionate investment due to regulatory mandate density, while drug discovery applications expand through AI-enabled literature mining.
- Pharmacovigilance:NLP-enabled case processing systems automate adverse-event detection from spontaneous reports and medical literature. EMA and FDA reporting mandates thicken workload volumes as biologics pipelines expand.
- Clinical Trials:Multi-site coordination platforms manage investigator brochures, protocol amendments, and regulatory correspondence across distributed research networks. Oracle Health Sciences dominates large-cap accounts through database infrastructure supporting global trial operations.
- Drug Discovery:Semantic graph architectures surface causal relationships between molecular targets and disease mechanisms.
- Regulatory Intelligence:Automated monitoring of submission requirements across FDA, EMA, PMDA, and NMPA jurisdictions.
- Medical Affairs:Scientific communication platforms coordinate publication planning and KOL engagement.
Clinical Trials command the largest installed base. Pharmacovigilance shows the steepest expansion trajectory.
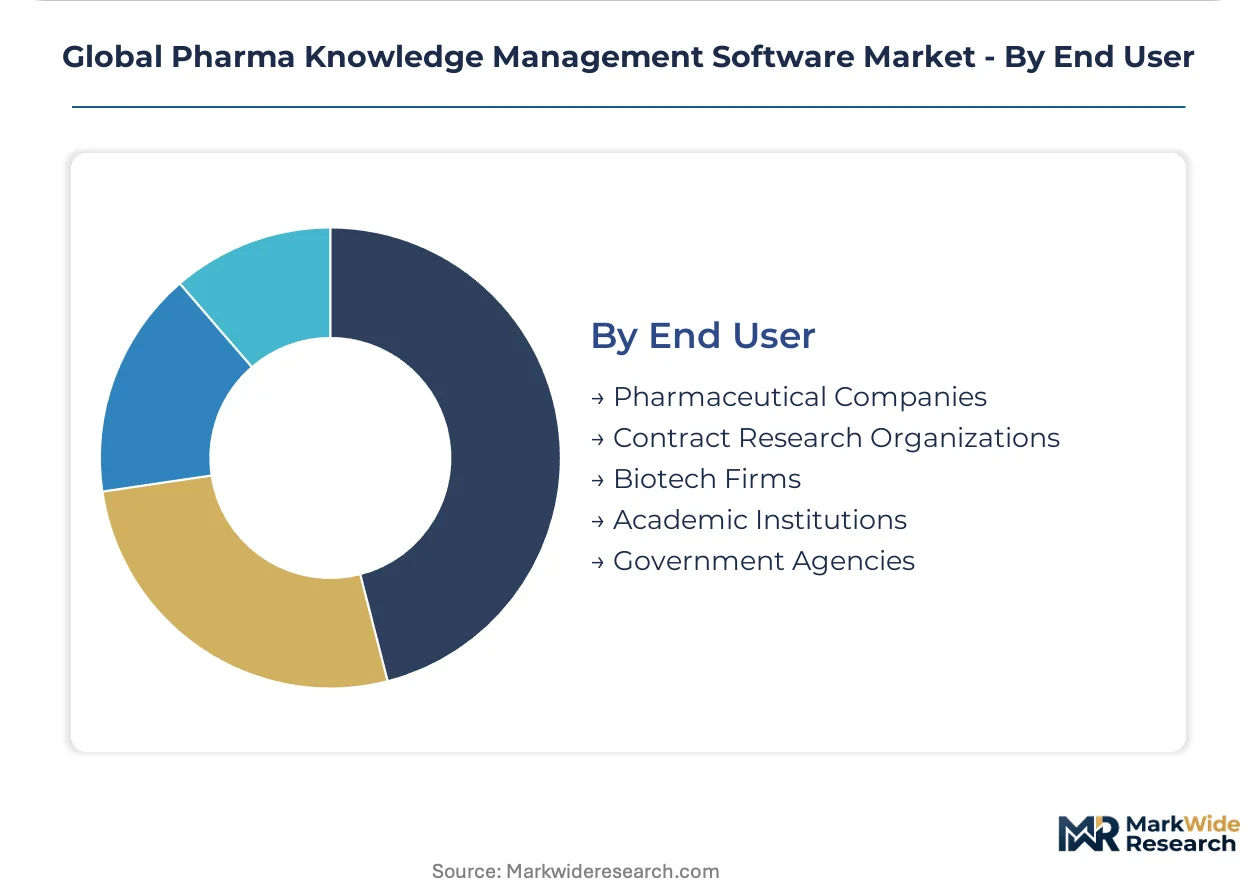
End User:
Contract research organizations and biotech firms drive cloud-native procurement, while pharmaceutical companies and academic institutions maintain heterogeneous legacy footprints.
- Contract Research Organizations:IQVIA, Parexel, and PPD prioritize platforms with real-world data integration spanning clinical and commercial operations. CDMO expansion in Hyderabad and Bengaluru creates demand for multilingual regulatory submission capabilities.
- Biotech Firms:Venture-backed clusters in Boston and San Francisco favor subscription pricing tied to document volume over perpetual licenses. Six-month procurement cycles contrast with 18-month enterprise sales cycles.
- Pharmaceutical Companies:Top-50 manufacturers maintain validated document repositories built on 1990s-era database architectures resistant to API integration.
- Academic Institutions:Research universities prioritize open-access publication archiving and grant compliance documentation.
- Government Agencies:National health authorities require secure knowledge systems for regulatory decision support and post-market surveillance.
Contract Research Organizations set the pace for cloud migration. Biotech Firms represent the fastest-growing customer segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical knowledge management software originated in United States enterprise computing centers during the 1990s, when FDA electronic records mandates first compelled validated document systems. German and Swiss pharmaceutical manufacturers subsequently developed parallel regulatory technology infrastructures under EMA supervision.
United States
FDA 21 CFR Part 11 compliance requirements drive replacement cycles for legacy document repositories. Biopharma clusters in Boston and San Francisco prioritize cloud-native platforms with six-month procurement timelines. Oracle Health Sciences maintains dominant positioning in large-cap accounts through multi-site trial coordination infrastructure.
Germany
EMA GxP data integrity guidelines mandate audit trails for knowledge system modifications across pharmaceutical quality units. Heidelberg and Munich host specialized vendors embedding ISO 13485 requirements directly into workflow engines. German manufacturers resist API integration with 1990s-era database architectures.
Switzerland
Swissmedic oversight of biologics manufacturing elevates pharmacovigilance automation priorities. Basel anchors Novartis and Roche headquarters, driving demand for NLP-enabled adverse-event processing. Swiss firms command premium compensation for professionals combining GxP expertise with cloud architecture skills.
India
CDSCO regulatory submission requirements expand alongside Hyderabad and Bengaluru CDMO growth. Contract manufacturers demand multilingual platforms supporting FDA and EMA dual filings. Indian procurement teams negotiate usage-based pricing tiers tied to document volume rather than perpetual licenses.
United Kingdom
MHRA post-Brexit regulatory divergence creates documentation complexity for multinational pharmaceutical firms. Cambridge biotech clusters adopt subscription pricing models displacing traditional license structures. UK quality units prioritize pre-validated algorithmic transparency modules under emerging EU AI Act documentation burdens.
Global Pharma Knowledge Management Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across validation depth and regulatory pre-certification. The vendor ecosystem consolidates around three tiers: ERP-anchored incumbents with compliance workflow embedding, specialized clinical data platforms with real-world evidence integration, and cloud-native challengers with semantic search architectures. Dominant competitive moves include modular unbundling of monolithic suites and strategic partnerships bridging legacy database infrastructure with modern analytics layers.
Within the ERP-anchored tier, SAP represents enterprise stack integration archetypes. IQVIA and Oracle Health Sciences occupy positions spanning clinical and commercial operations. Veeva Systems exemplifies cloud-native specialization for life sciences verticals. These three companies anchor competitive positioning across distinct procurement evaluation criteria: infrastructure flexibility, functional depth, and deployment velocity.
| Leading Market Players |
|---|
| SAP |
| BenchSci |
| IQVIA |
| MasterControl |
| Sinequa |
| Oracle Health Sciences |
| Elsevier |
| Dassault Systèmes |
| Veeva Systems |
| Others |
Supply & Pricing Matrix
Cloud infrastructure subscription indices cascade through pharmaceutical software procurement, compressing enterprise pricing tiers while elevating validation cost premiums for FDA 21 CFR Part 11 compliant installations. Buyer archetypes segment sharply: venture-backed biotechs negotiate usage-based SaaS contracts while top-20 manufacturers absorb 18-24 month qualification cycles for on-premise deployments.
Pricing Analysis
Subscription pricing stratifies across validated compliance tiers, volume-scaled document processing bands, and integration complexity levels. Price differentiation hinges on GxP certification depth and pre-configured regulatory workflow modules. Cost compression in mid-market SaaS tiers intensifies as cloud-native challengers undercut incumbent perpetual licenses. Series B biotechs in Cambridge and South San Francisco exhibit highest price sensitivity; top-50 pharmaceutical manufacturers demonstrate lowest sensitivity due to switching cost entrenchment.
Supply Chain Analysis
Software lifecycle services—including validation documentation updates, algorithmic retraining, and compliance recertification—flow back to original vendors through mandatory maintenance contracts. Development talent concentrates in the United States, Germany, and Switzerland. Cloud compute infrastructure draws from hyperscaler networks anchored in Virginia, Frankfurt, and Singapore. Single-source vulnerability permeates specialized GxP compliance engineering pools. Distribution runs through direct enterprise sales teams with embedded regulatory consultants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical knowledge management procurement functions as a geographic-arbitrage play: EMA GxP validation requirements in Germany and Switzerland command 40-60% pricing premiums over equivalent FDA-compliant U.S. installations, creating margin expansion opportunities for vendors with dual-certification capabilities.
For Market Incumbents: Cement market position through backward integration into specialized GxP compliance talent pools and pre-validated algorithmic transparency modules addressing EU AI Act documentation burdens. Oracle Health Sciences and SAP should expand Hyderabad and Bengaluru delivery centers to capture CDMO procurement growth while defending against cloud-native semantic search challengers.
For New Entrants and Emerging Players: Mid-size European CROs represent the most penetrable buyer archetype, underserved by incumbent workflow rigidity and demanding modular API-first architectures. Target pharmacovigilance automation with six-month deployment guarantees and usage-based pricing tied to adverse-event case volumes rather than seat counts.
For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native platforms combining biomedical large language model capabilities with pre-validated regulatory submission workflows. Acquisition targets should demonstrate installed bases across both FDA and EMA jurisdictions. Monitor FDA 21 CFR Part 11 enforcement actions and EU AI Act implementation timelines as inflection indicators for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Certification Investment | FDA 21 CFR Part 11 and EMA GxP dual validation compresses sales cycles for enterprise accounts. |
| Real-World Data Integration Partnership | IQVIA-style clinical-commercial convergence enables subscription pricing tied to evidence generation value. |
| Semantic Search Architecture Deployment | Biomedical LLM fine-tuning displaces Boolean search in pharmacovigilance signal detection workflows. |
| Geographic Delivery Center Expansion | Hyderabad and Bengaluru CDMO proximity captures multilingual regulatory submission platform demand. |
| Algorithmic Transparency Module Development | EU AI Act compliance documentation opens consulting-adjacent revenue streams for European CROs. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's pharmaceutical software procurement centers. Conversations with drug development executives, regulatory affairs leads, GxP compliance officers, and cloud procurement managers combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and vendor SEC disclosures. Bottom-up segment sizing and top-down market triangulation anchored quantitative outputs.
Granularity-level modeling deployed deployment mode, organization size, application use case, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from trend extrapolation of validated system replacement cycles, cloud migration velocity in biotech clusters, and pharmacovigilance workload expansion tied to biologics pipeline growth. Treatment line prioritization and adverse-event reporting mandate density informed application-level forecasts across the projection horizon.
Inputs from regulatory filing databases and vendor financial disclosures were available through the study window; gaps in private biotech procurement transaction data introduce uncertainty bands around cloud-native segment sizing. Forecasts reflect assumptions regarding FDA enforcement consistency, EU AI Act implementation sequencing, and hyperscaler infrastructure cost trajectories. Practitioners should monitor CDSCO regulatory harmonization progress and large language model validation guideline developments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Cognitive Assessment and Training in Healthcare Market
Healthcare IT
Hospital Capacity Management Solutions Market
Healthcare IT
Patient Access Solutions Market
Healthcare IT
Europe Outpatient Software Market
Healthcare IT
Non-Clinical Homecare Software Market
Healthcare IT
Pharma Management Software Market
Healthcare IT
US Revenue Cycle Management Market
Healthcare IT
Global Pharmacy Inventory Management Software Solutions and Cabinets Market
Healthcare IT
Global Patient Intake Software Market
Healthcare IT
Aged Care Software Market
Healthcare IT
Patient Registry Software Market
Healthcare IT
Healthcare IT Services Market
Healthcare IT
Pharmaceutical Quality Management Systems Market
Healthcare IT
Global Back-End Revenue Cycle Management Market
Healthcare IT
Global RFID in Healthcare Market
Healthcare IT
North America Long-Term Care Software Market