
 Functional Electrical Stimulation Market | 2026-2036
Functional Electrical Stimulation Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Electrical Stimulation Market Analysis
European medical device manufacturing is broadening output capacity for implantable neurostimulators. Otto Bock leverages its prosthetics heritage to anchor electromechanical integration expertise. Restorative Therapies sustains leadership in cycle ergometry systems for spinal cord injury rehabilitation. HASOMED GmbH competes through specialized software-hardware bundles for clinical gait analysis.
Functional electrical stimulation delivers controlled electrical impulses to activate paralyzed or weakened muscles, typically operating at pulse frequencies between 20-50 Hz with current amplitudes up to 100 mA for therapeutic recruitment of motor nerves. Its primary commercial purpose spans motor recovery after neurological injury, muscle re-education following orthopedic trauma, and augmentation of voluntary movement in neurodegenerative conditions. Neurostimulators command the dominant revenue pool due to premium pricing of implantable pulse generators, while wearable devices represent the fastest-expanding segment as skin-surface electrode arrays achieve clinical parity for ambulatory rehabilitation. Rehabilitation centers anchor steady demand volumes, though home care delivery is accelerating as Bluetooth-enabled stimulators gain reimbursement traction.
The FDA governs premarket approval pathways for implantable FES devices under neurological therapeutic device classifications, while the EU Medical Device Regulation mandates clinical evidence thresholds for active implantable systems marketed under CE marking. ISO 13485 quality management certification shapes supplier eligibility for OEM partnerships across North American and European hospital procurement frameworks. Stakeholders must monitor evolving CMS coverage determinations for at-home FES therapy and the EU's impending EUDAMED database transparency requirements.
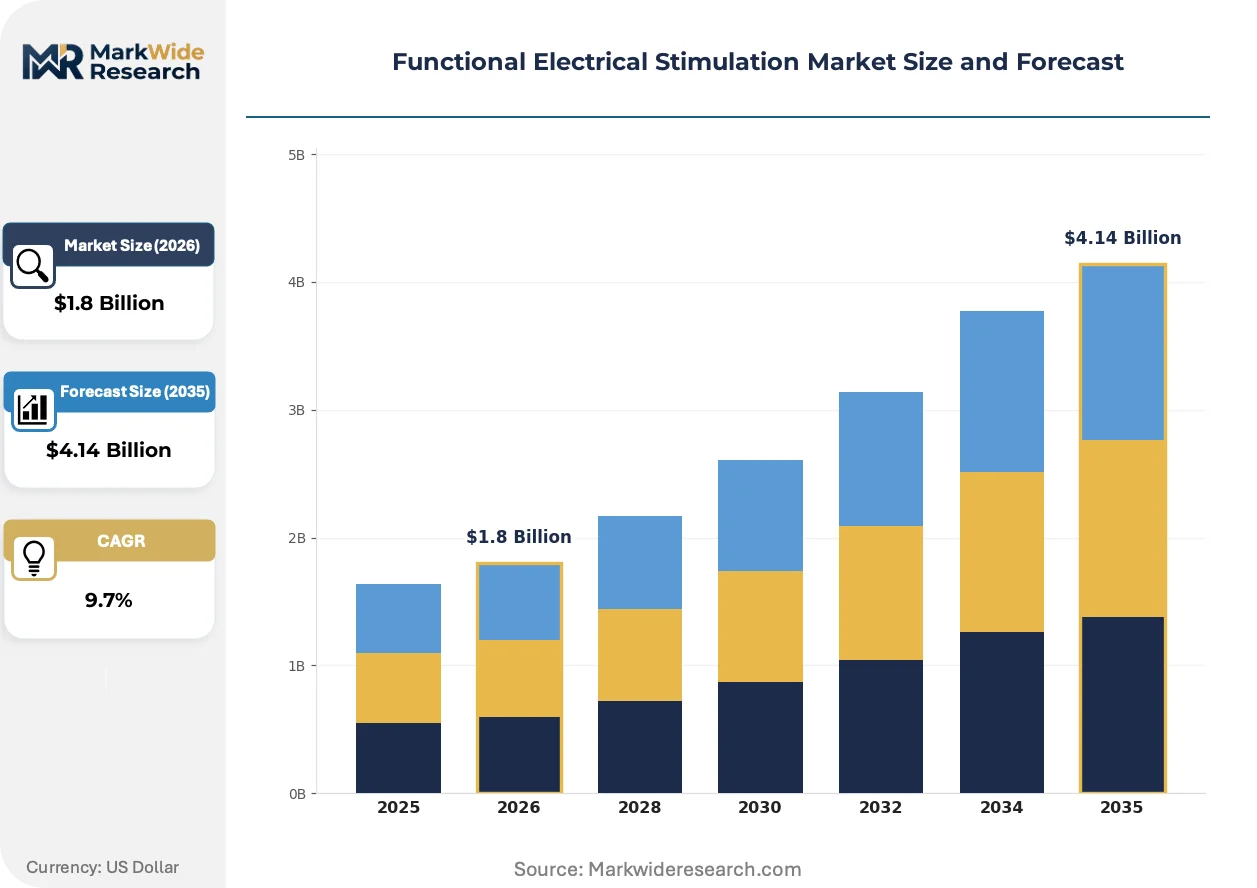
Market Dynamics
Implantable neurostimulators are capturing premium revenue pools as stroke rehabilitation protocols shift toward closed-loop feedback systems, compressing development timelines for manufacturers racing FDA breakthrough designation pathways.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review timelines compress commercialization cycles for novel FES platforms targeting spinal cord injury motor recovery.
- Bluetooth-Enabled Wearables:Skin-surface electrode arrays achieve clinical parity for ambulatory rehabilitation, opening reimbursement pathways for home care delivery.
- German Neurology Clinic Expansion:Academic medical centers in Munich and Heidelberg scale implantable neurostimulator programs for post-stroke motor re-education.
Market Restraints
- Premium Pricing Concentration:Implantable pulse generators require platinum-iridium electrode materials subject to precious metal volatility.
- EU MDR Clinical Evidence Thresholds:Active implantable systems face extended CE marking timelines under Medical Device Regulation Article 52.
- Surface Electrode Substitution:Transcutaneous electrical nerve stimulation devices compete for lower-acuity musculoskeletal rehabilitation cases.
Strategic Opportunities
- CMS At-Home Coverage Expansion:Medicare reimbursement determinations for remote FES therapy create channel access beyond institutional settings.
- Parkinson's Disease Gait Augmentation:Freezing-of-gait protocols represent an emerging application vertical with limited incumbent penetration.
- AI-Closed Loop Convergence:Machine learning algorithms paired with real-time electromyography feedback enable adaptive stimulation parameter adjustment.
Industry Challenges
- ISO 13485 Certification Bottlenecks:Quality management system audits for OEM supplier qualification extend procurement timelines for electrode array manufacturers.
- Neurorehabilitation Specialist Scarcity:Clinical training programs for FES parameter programming lag device deployment in community hospital settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Electrical Stimulation Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neurostimulators, Muscle Stimulators, Electrodes, Wearable Devices Therapy Area: Neurology, Orthopedics, Rehabilitation, Sports Medicine End User: Hospitals, Rehabilitation Centers, Home Care, Sports Facilities Delivery Mode: Non-Invasive, Invasive, Remote Monitoring, Continuous Therapy |
| Companies Covered | Otto Bock, Restorative Therapies, HASOMED GmbH, g.tec medical engineering GmbH, Hobbs Rehabilitation, Bioness Inc., Odstock Medical Limited, Synapse Biomedical Inc., Trulife, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Electrical Stimulation Market Emerging Trajectories
Electrode miniaturization and wireless power transfer are compressing form factors for implantable systems while expanding ambulatory use cases previously confined to clinical settings.
Thin-film electrode arrays with polyimide substrates are expanding into subcutaneous applications previously dominated by percutaneous lead systems. Neurorehabilitation centers in Boston and San Francisco adopt these platforms for upper-extremity stroke protocols. The technology is expanding into home-based rehabilitation programs as patients demonstrate self-management competency.
The EU Medical Device Regulation mandates post-market clinical follow-up for active implantable neurological devices under Annex XIV. Manufacturers must submit periodic safety update reports to notified bodies, increasing regulatory compliance overhead. Implantable pulse generator portfolios face the steepest documentation burden as legacy devices transition from MDD to MDR certificates.
Hospital procurement departments now bundle FES device acquisition with multi-year service contracts covering electrode replacement and software updates. Traditional capital equipment purchasing gives way to subscription-based models in North American academic medical centers. This restructuring concentrates vendor selection authority within supply chain committees rather than individual clinical departments.
Functional Electrical Stimulation Market Segmentation
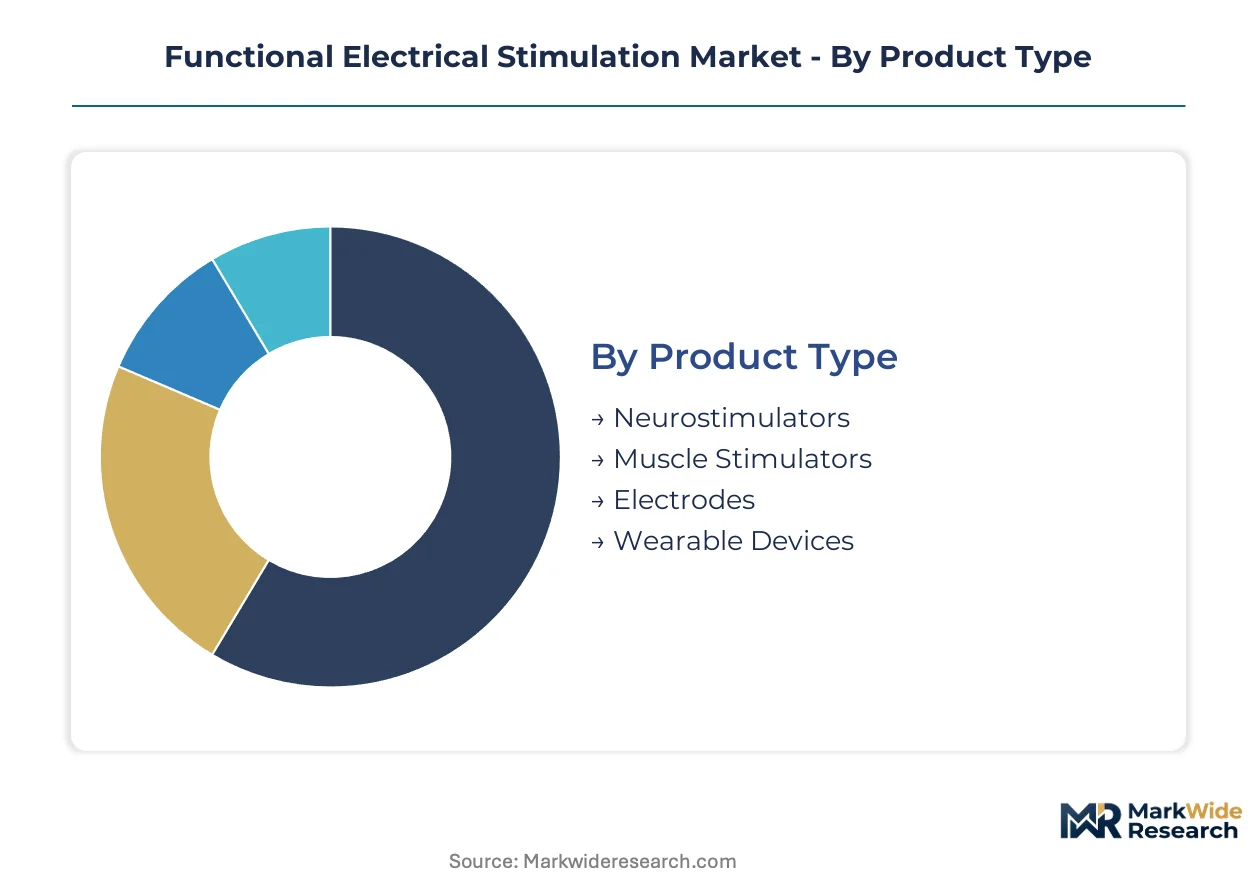
Functional electrical stimulation markets fragment across four critical dimensions that determine pricing power, regulatory pathway, and channel strategy. Product type governs reimbursement codes and clinical trial requirements. Therapy area dictates prescriber specialty and patient acuity profiles.
Product Type:
Replacement cycles vary sharply—implantable systems demand surgical revision every 5-7 years while surface electrodes require quarterly refresh.
- Neurostimulators:Implantable pulse generators with platinum-iridium electrodes deliver targeted motor nerve activation at 20-50 Hz. German neurology clinics in Munich and Heidelberg anchor demand for stroke rehabilitation protocols. Premium pricing concentrates revenue here despite smaller unit volumes.
- Wearable Devices:Bluetooth-enabled skin-surface arrays achieve clinical parity for ambulatory motor recovery. North American academic medical centers in Boston and San Francisco scale home-based programs as patients demonstrate self-management competency. Fastest-expanding segment by placement volume.
- Muscle Stimulators:Transcutaneous units target orthopedic trauma recovery with lower reimbursement tiers.
- Electrodes:Disposable consumables with polyimide substrates for subcutaneous applications.
Volume placements concentrate in Wearable Devices; the faster expansion belongs to Neurostimulators as closed-loop feedback protocols mature.
Therapy Area:
Margin profiles diverge—neurology commands premium pricing for implantable systems while sports medicine competes on device accessibility.
- Neurology:Stroke motor recovery and spinal cord injury rehabilitation drive FDA breakthrough designation submissions. Post-market clinical follow-up under EU MDR Annex XIV elevates compliance overhead for active implantable portfolios.
- Rehabilitation:Cycle ergometry systems for spinal cord injury anchor institutional purchasing. Academic medical centers bundle multi-year service contracts covering electrode replacement and software updates.
- Orthopedics:Muscle re-education following trauma competes with TENS devices for lower-acuity cases.
- Sports Medicine:Athletic performance augmentation faces limited reimbursement traction.
Revenue concentration sits with Neurology; Rehabilitation gains share fastest as home-care delivery models proliferate.
End User:
Channel access is restructuring—capital equipment purchasing yields to subscription models in procurement committees.
- Rehabilitation Centers:Specialized neurorehabilitation programs anchor steady demand volumes. Boston and San Francisco facilities adopt thin-film electrode arrays for upper-extremity stroke protocols.
- Home Care:Remote FES therapy gains Medicare reimbursement traction as Bluetooth-enabled stimulators demonstrate safety profiles. CMS coverage determinations create channel access beyond institutional settings.
- Hospitals:Supply chain committees consolidate vendor selection authority away from individual clinical departments.
- Sports Facilities:Out-of-pocket payment limits scale.
Device placements concentrate in Rehabilitation Centers; Home Care climbs the fastest as at-home competency validation protocols standardize.
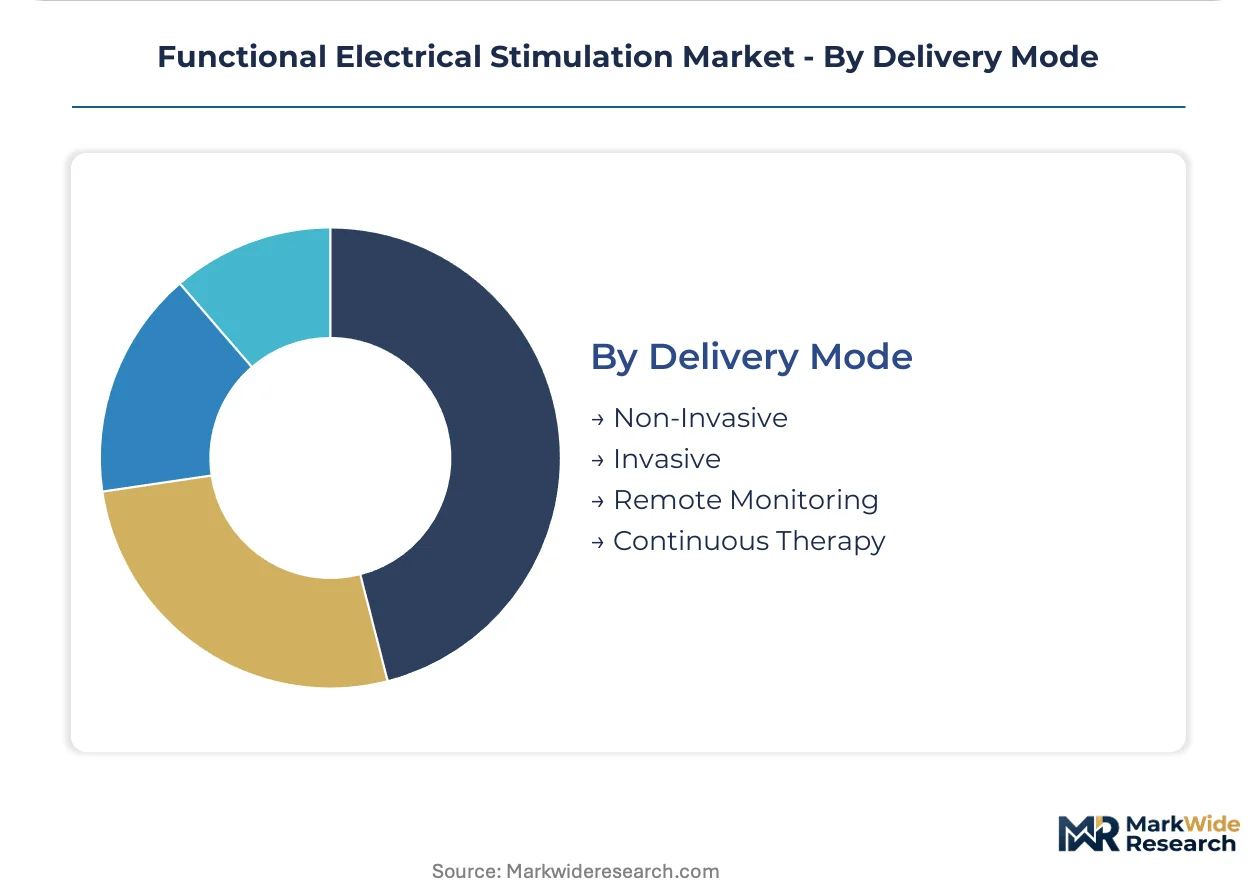
Delivery Mode:
Regulatory burden scales with invasiveness—MDR Article 52 extends CE marking timelines for implantable systems.
- Invasive:Surgical implantation with percutaneous leads requires ISO 13485-certified electrode array suppliers. EU MDR periodic safety update reports increase documentation burden for legacy device transitions.
- Remote Monitoring:Real-time parameter adjustment via machine learning algorithms enables adaptive stimulation. FDA breakthrough pathway accelerates commercialization for AI-closed loop convergence platforms.
- Non-Invasive:Surface electrode substitution threatens lower-acuity musculoskeletal cases.
- Continuous Therapy:Wearable form factors with wireless power transfer expand ambulatory use cases.
Clinical adoption concentrates in Invasive systems; Remote Monitoring expands most quickly as electromyography feedback integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platinum-iridium electrode sourcing from South African mining operations anchors supply security for implantable neurostimulator manufacturers serving stroke rehabilitation centers worldwide.
United States
FDA breakthrough device designations compress commercialization timelines for spinal cord injury platforms. Medicare coverage determinations for at-home FES therapy expand channel access beyond Boston and San Francisco academic medical centers. The Pacific Northwest cluster advances Bluetooth-enabled wearable electrode arrays for ambulatory motor recovery protocols.
Germany
Neurology clinics in Munich and Heidelberg scale implantable neurostimulator adoption for post-stroke motor re-education. EU MDR Article 52 extends CE marking timelines for active implantable systems, elevating documentation burdens for legacy device transitions. The Baden-Württemberg industrial corridor concentrates electromechanical integration expertise for closed-loop feedback systems.
United Kingdom
NHS England specialized commissioning frameworks determine reimbursement access for cycle ergometry systems in spinal cord injury rehabilitation. MHRA post-market surveillance requirements align with EU MDR periodic safety update report standards during the Northern Ireland protocol transition. The Oxford-Cambridge arc anchors thin-film electrode array development for upper-extremity stroke protocols.
Japan
PMDA accelerated approval pathways for neurological therapeutic devices reduce time-to-market for novel FES platforms targeting Parkinson's gait augmentation. METI medical device export promotion programs support domestic manufacturers expanding into Southeast Asian rehabilitation markets. The Kansai region concentrates polymer substrate research for subcutaneous electrode miniaturization.
Australia
TGA priority review designation for breakthrough neurological devices attracts offshore clinical trial investment from European implantable pulse generator developers. The Medical Research Future Fund allocates capital toward AI-closed loop convergence research in Melbourne neurorehabilitation institutes. Sydney academic medical centers adopt subscription-based procurement models bundling device acquisition with multi-year electrode replacement service contracts.
Functional Electrical Stimulation Market Vendor Landscape
Global majors compete with regional champions across regulatory pathway expertise and neurorehabilitation specialist training infrastructure. The vendor base stratifies into three tiers: diversified medical technology conglomerates with implantable device portfolios, specialized FES platform developers with therapy-specific software integration, and regional distributors with clinical training service capabilities. Dominant competitive moves include M&A activity targeting electromyography feedback algorithm developers and strategic partnerships securing ISO 13485-certified electrode array supply chains.
Among Germany-based engineering specialists, Otto Bock GmbH and HASOMED GmbH exemplify the electromechanical integration archetype, leveraging prosthetics heritage and clinical gait analysis software expertise respectively. Restorative Therapies occupies a position within the therapy-specific platform tier, representing cycle ergometry system specialization for institutional rehabilitation settings. These three anchors demonstrate how geographic proximity to Munich and Heidelberg clinical research centers shapes competitive positioning in European neurostimulator markets.
| Leading Market Players |
|---|
| Otto Bock |
| Restorative Therapies |
| HASOMED GmbH |
| g.tec medical engineering GmbH |
| Hobbs Rehabilitation |
| Bioness Inc. |
| Odstock Medical Limited |
| Synapse Biomedical Inc. |
| Trulife |
| Others |
Supply Flow & Price Mechanics
Biomedical engineering talent clusters in the Boston and San Francisco metro areas compress development overhead for premium-tier implantable systems while surface-electrode manufacturing migrates toward lower-cost assembly regions, widening the labor-cost differential between closed-loop neurostimulator platforms and disposable wearable arrays.
Pricing Analysis
Multi-year service bundling now dominates institutional procurement, with academic medical centers purchasing electrode replacement schedules and software update commitments alongside hardware acquisition while home-care channels favor unbundled device-only transactions. Three-tier pricing structure across premium implantable systems, mid-tier Bluetooth-enabled wearables, and economy muscle stimulators reflects ISO 13485 certification grade and after-sales coverage depth. Cost compression in surface-electrode tiers intensifies because transcutaneous electrical nerve stimulation devices compete for lower-acuity orthopedic cases. Hospital supply chain committees exhibit lowest price sensitivity due to bundled contract structures, whereas individual patients in home-care settings face highest out-of-pocket exposure.
Supply Chain Analysis
Regional distribution centers in the German Baden-Württemberg corridor and the US Pacific Northwest maintain hub-and-spoke patterns for just-in-time electrode array delivery to neurorehabilitation centers. Platinum-iridium electrode materials draw from South African mining operations, polyimide substrates feed from Japanese polymer research clusters, and Bluetooth module assembly concentrates in Taiwanese electronics facilities. Single-source vulnerability in precious metal electrode supply creates exposure to commodity volatility and export restriction risk. Distribution runs through specialized medical device distributors with ISO 13485-certified warehousing rather than general healthcare logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The functional electrical stimulation market sits in a technology-transition phase where AI-closed loop convergence platforms with real-time electromyography feedback are displacing open-loop programmable stimulators that dominated the prior decade.
For Market Incumbents: Lock in electrode array supply security through backward integration into polyimide substrate manufacturing or captive sourcing agreements with ISO 13485-certified suppliers, while accelerating FDA breakthrough designation submissions for adaptive stimulation algorithms that defend premium pricing against transcutaneous electrical nerve stimulation substitution in lower-acuity cases. For New Entrants and Emerging Players: Home care delivery partnerships with Medicare Advantage plans represent the most penetrable channel given CMS coverage determination momentum for remote FES therapy, targeting Parkinson's disease gait augmentation protocols where incumbent penetration remains limited and reimbursement pathways are stabilizing. For Investors and Strategic Acquirers: Re-rating potential sits with electromyography feedback algorithm developers given FDA breakthrough pathway acceleration for AI-closed loop convergence platforms, with long-term viability hinging on 5-10 year Medicare coverage expansion for at-home therapy; the signal to watch is CMS national coverage determination publication frequency for ambulatory rehabilitation indications.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Submission | Accelerated review timelines compress commercialization cycles for spinal cord injury motor recovery platforms. |
| CE Marking Pathway Under EU MDR Article 52 | Extended clinical evidence thresholds elevate compliance overhead for active implantable legacy device transitions. |
| Hospital System Partnership | Boston and San Francisco academic medical centers bundle multi-year service contracts consolidating vendor selection authority. |
| Software Companion Development | Bluetooth-enabled parameter adjustment apps enable patient self-management competency validation for home-care reimbursement. |
| Reimbursement Strategy | Medicare coverage determinations for remote FES therapy create channel access beyond institutional rehabilitation settings. |
Methodological Framework
Independent corroboration across neurorehabilitation clinician interviews, hospital purchasing committee discussions, and biomedical engineering R&D director conversations underwrites the qualitative findings, with secondary validation drawing from FDA 510(k) and PMA filings, EU MDR notified body documentation, CMS national coverage determination records, and hospital procurement database extracts. Bottom-up demand modeling triangulates against top-down market sizing across implantable pulse generator, wearable device, and electrode consumable categories.
Rate-of-change decomposition separates volume expansion from pricing dynamics across the projection horizon, with segmentation modeling spanning product type, therapy area, end user channel, and delivery mode dimensions plus regulatory pathway cluster as an industry-specific overlay. CAGRs derive from installed base growth rates, replacement cycle compression, and reimbursement elasticity parameters, incorporating electromyography feedback integration maturity and EU MDR transition timelines as forecast inputs.
Caveats apply where FDA breakthrough designation approval velocity, EU MDR notified body capacity constraints, or CMS coverage determination scope revisions could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Powered Mattress System Market
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
North America and Europe Medical Technology Market
Medical Devices
France Contraceptive Devices Market
Medical Devices
Global Breast Biopsy Devices Market
Medical Devices
Global Medical Kiosk Market
Medical Devices
Hydrogel Contact Lenses Market
Medical Devices
Canada Anesthesia Devices Market
Medical Devices
Skull Clamp Market
Medical Devices
Interventional Spine Devices Market
Medical Devices
Cervical Artificial Discs Market
Medical Devices
Global Mobile ECG Devices Market
Medical Devices
Neonatal Hearing Screening Devices Market
Medical Devices
Autotransfusion Devices Market
Medical Devices
Power Wheelchairs and Mobility Scooters Market
Medical Devices
Middle East and Africa Biomedical Sensors Market