
 Global Cast Saw Devices Market | 2026-2036
Global Cast Saw Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cast Saw Devices Market Foresight
Single-source procurement for cast saw blade assemblies is decoupling from multi-vendor service contracts as hospitals seek cost predictability. Stryker Corporation leverages its integrated orthopedic ecosystem to sustain captive demand across hospital networks. De Soutter Medical anchors its position in European markets through specialized surgical power tool manufacturing. Smith & Nephew plc competes on brand strength in trauma and extremities, extending its reach into ambulatory settings.
Cast saw devices are electrically or pneumatically powered cutting instruments that utilize oscillating, reciprocating, or rotary blades to section orthopedic casts and splints without contacting underlying skin, typically operating at blade speeds between 15,000 and 25,000 oscillations per minute. Cordless cast saws are gaining share fastest as lithium-ion battery platforms eliminate tethering constraints and reduce operating room trip hazards. Oscillating blade technology dominates unit shipments due to its established safety profile and compatibility with fiberglass and plaster casting materials. Orthopedic surgery remains the largest application segment, while sports medicine represents a concentrated margin pool tied to outpatient clinic expansion.
The FDA's 510(k) pathway governs market entry for powered cast removal devices in the United States, while the EU Medical Device Regulation (MDR) imposes enhanced clinical evidence requirements for reclassification of surgical power tools in Europe. China's NMPA implements GB standards for electromagnetic compatibility and electrical safety that foreign manufacturers must address for market access. Stakeholders must monitor regulatory divergence between major jurisdictions to optimize registration sequencing and avoid delayed commercialization.
Market Dynamics
Cordless lithium-ion platforms are compressing replacement cycles across hospital networks as procurement committees prioritize battery standardization and reduced OR trip hazards over legacy pneumatic tethering systems.
Growth Catalysts
- FDA 510(k) pathway clarity:Streamlined premarket notification for powered surgical instruments accelerates product iterations for oscillating blade systems in United States hospital networks.
- Aging demographics in Germany:Trauma caseloads among patients over 65 sustain replacement demand for cast removal devices in orthopedic clinics and rehabilitation centers.
- Outpatient clinic expansion:Ambulatory surgical centers in China deploy compact cordless units to handle rising sports medicine volumes without infrastructure retrofit.
Market Restraints
- Lithium-ion cell cost volatility:Battery pack input costs fluctuate with cobalt and nickel spot markets, pressuring OEM margins on cordless platform rollouts.
- EU MDR clinical evidence requirements:Reclassification of surgical power tools under enhanced scrutiny extends registration timelines and elevates documentation burdens for European market entry.
- Manual cast removal persistence:Shear cutters and bandage scissors retain share in resource-constrained settings where capital equipment procurement faces budget freezes.
Strategic Opportunities
- India orthopedic infrastructure buildout:Government hospital modernization programs create first-mover advantage for battery-powered cast saw vendors addressing tier-2 and tier-3 city networks.
- Pediatric application specialization:Reduced-noise, reduced-vibration blade designs open dedicated product lines for children's hospitals and pediatric orthopedic practices.
- ISO 13485 quality system convergence:Harmonized medical device quality management standards enable single-audit market access across multiple regulatory jurisdictions.
Industry Challenges
- Biomedical technician training gaps:Hospital maintenance departments lack specialized expertise for lithium-ion battery diagnostics and blade assembly calibration protocols.
- Legacy pneumatic infrastructure lock-in:Capital-intensive OR renovations required to eliminate compressed air lines slow cordless conversion at established surgical facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cast Saw Devices Market |
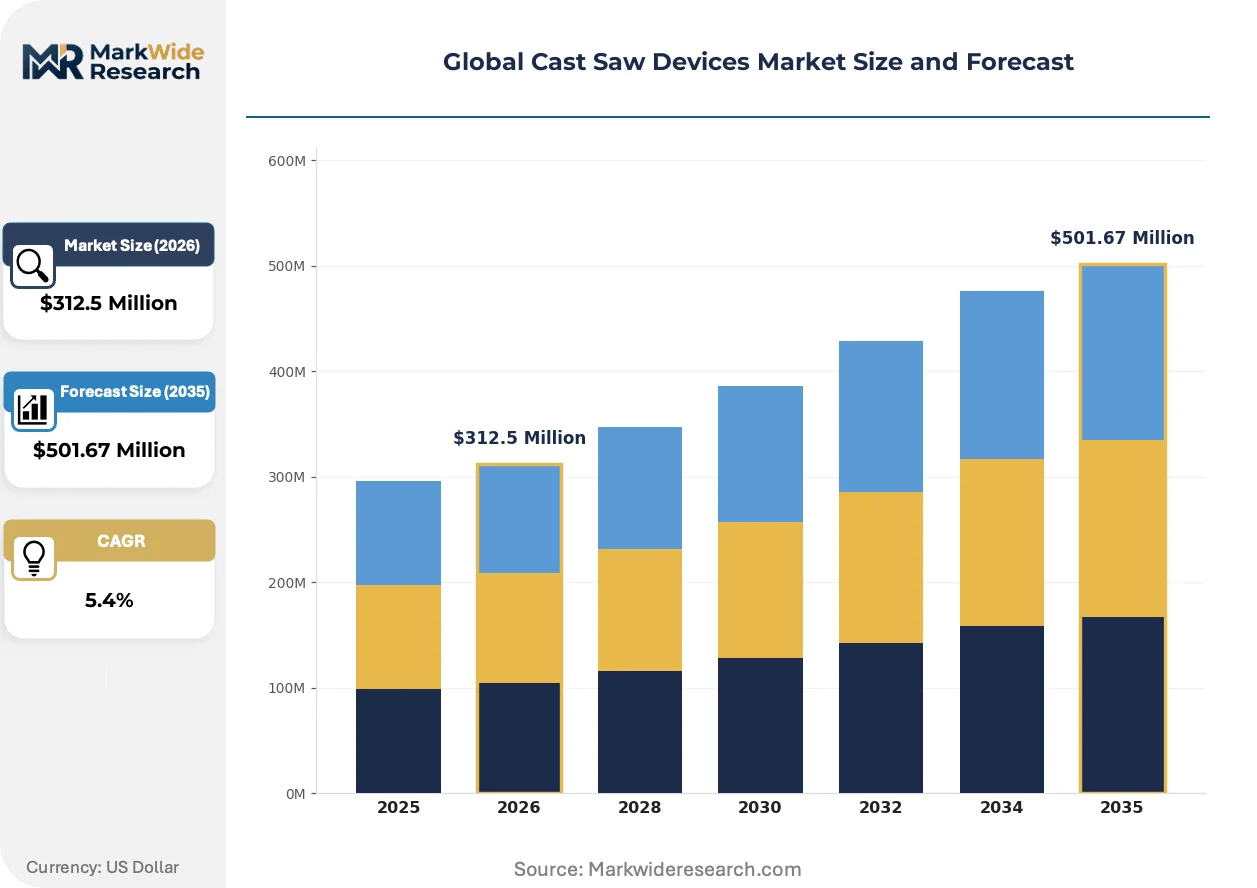
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corded Cast Saws, Cordless Cast Saws, Portable Cast Saws, Pneumatic Cast Saws Technology: Oscillating Blade, Reciprocating Blade, Rotary Blade, Ultrasonic Blade Application: Orthopedic Surgery, Emergency Care, Veterinary Use, Sports Medicine, Podiatry End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Veterinary Clinics |
| Companies Covered | Stryker Corporation, Smith & Nephew plc, De Soutter Medical, Essity Aktiebolag, HEBU medical GmbH, McArthur Medical Sales, Inc., Prime Medical, Inc., Shanghai Bojin Medical Instrument Co., Ltd., Hanshin Medical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cast Saw Devices Market Shifts & Advancements
Electrification of surgical power tools is compressing the technology refresh horizon. Three developments are actively restructuring competitive positioning and procurement patterns across cast saw device categories.
Brushless DC motor architecture paired with smart battery management systems is rewriting performance benchmarks for oscillating blade platforms. Ambulatory surgical centers in the United States are adopting these systems faster than academic medical centers due to lower infrastructure requirements. The shift is enabling same-day discharge protocols and reducing anesthesia recovery times in outpatient orthopedic settings.
EU MDR Article 10 clinical evaluation requirements are forcing manufacturers to generate post-market surveillance data for surgical power tool reclassification. European orthopedic clinics face temporary supply constraints as legacy devices undergo conformity reassessment. German and French distributors are prioritizing inventory positions for MDR-compliant units ahead of notified body bottlenecks.
Hospital procurement committees are unbundling cast saw blade assemblies from multi-year service contracts to achieve cost predictability. Group purchasing organizations in the United States negotiate blade supply separately from device capital expenditure, compressing vendor margin stacking. This pattern is most visible in integrated delivery networks consolidating orthopedic service lines under centralized supply chain governance.
Global Cast Saw Devices Market Segmentation
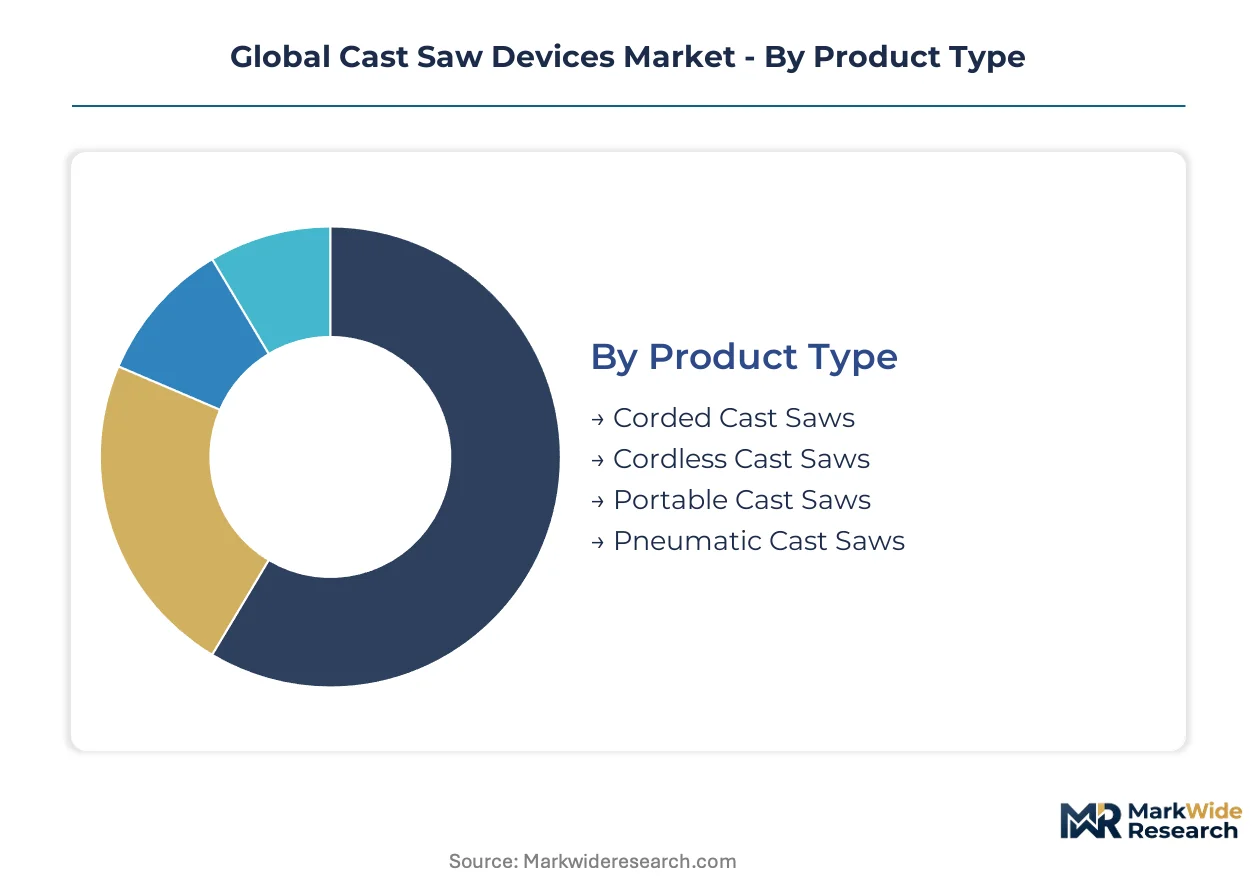
Cast saw device procurement patterns diverge sharply between high-volume hospital networks and specialized outpatient settings. Understanding these segment boundaries reveals where cordless electrification is displacing legacy pneumatic systems and where manual alternatives retain cost-driven footholds.
Product Type:
Cordless units command premium positioning while corded platforms still move volume in budget-constrained procurement cycles.
- Corded Cast Saws:Tethered electric units deliver consistent power output for high-throughput cast removal in fixed installation settings. Demand concentrates in United States academic medical centers where infrastructure retrofit costs delay cordless conversion despite OR trip hazard concerns.
- Cordless Cast Saws:Lithium-ion battery platforms eliminate compressed air dependency and enable point-of-care mobility. German orthopedic clinics are expanding procurement fastest as battery standardization across surgical power tool fleets reduces spare inventory complexity.
- Portable Cast Saws:Compact battery-powered units prioritize field deployability over cutting speed. China's county-level hospitals adopt these for emergency department overflow capacity.
- Pneumatic Cast Saws:Compressed air-driven systems persist where capital equipment replacement faces multi-year budget cycles. Legacy infrastructure lock-in sustains demand at established surgical facilities in France and Italy.
Mature deployment sits with corded and pneumatic systems. Newer deployment is concentrated in cordless platforms.
Technology:
Blade mechanism selection directly determines safety profile, material compatibility, and maintenance burden across end-use environments.
- Oscillating Blade:Rapid side-to-side motion at 15,000-25,000 cycles per minute sections fiberglass and plaster without skin contact. United States hospital networks specify these as standard of care for pediatric and geriatric populations where thermal injury risk must be minimized.
- Reciprocating Blade:Linear cutting stroke suits dense synthetic casting materials and veterinary applications with thicker limb circumferences. Demand clusters in large animal veterinary practices across Australia and New Zealand.
- Rotary Blade:Continuous circular cutting action delivers speed for trauma emergency settings. Sports medicine clinics in Brazil deploy these for rapid cast removal in high-volume athletic injury practices.
- Ultrasonic Blade:High-frequency vibration cutting generates minimal thermal load and dust. Japanese orthopedic centers evaluate these for specialized hand surgery applications requiring precision.
Oscillating mechanisms dominate installed base. Ultrasonic systems are climbing the fastest among emerging technologies.
Application:
Clinical setting dictates throughput requirements, patient population sensitivity, and reimbursement dynamics.
- Orthopedic Surgery:Primary cast removal following fracture fixation and joint procedures. Demand sustains replacement cycles at German trauma centers managing aging population fracture volumes.
- Emergency Care:Rapid cast and splint removal in trauma reception areas. United States emergency departments prioritize cordless units for space-constrained resuscitation bays.
- Veterinary Use:Equine and small animal orthopedic applications requiring modified blade guards. Australian veterinary teaching hospitals drive specialized product development.
- Sports Medicine:Outpatient athletic injury management with emphasis on rapid turnaround. Ambulatory surgical centers in China's tier-1 cities are expanding dedicated sports medicine cast removal capacity.
- Podiatry:Lower extremity cast applications with specialized limb positioning requirements. French podiatric clinics represent a concentrated margin segment for compact cordless units.
Orthopedic surgery maintains the largest installed base. Sports medicine is gaining share fastest among application segments.
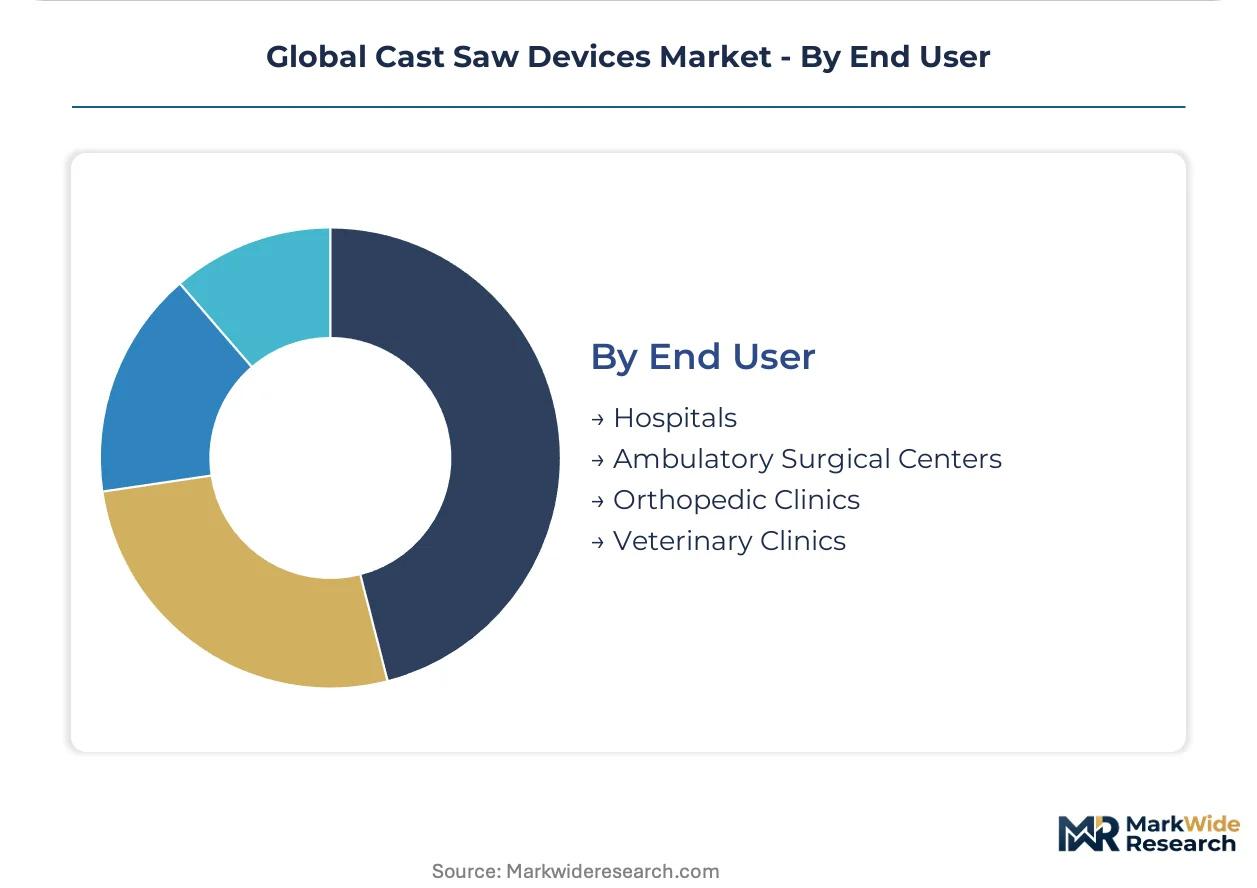
End User:
Procurement authority and capital budget scale separate centralized hospital purchasing from distributed clinic decision-making.
- Hospitals:Centralized supply chain governance with multi-year service contract structures. United States integrated delivery networks unbundle blade procurement from device capital expenditure to compress vendor margins.
- Ambulatory Surgical Centers:Same-day discharge protocols drive demand for compact, battery-standardized equipment. German outpatient orthopedic surgery centers lead cordless adoption in Europe.
- Orthopedic Clinics:Specialized cast application and removal services with high patient throughput requirements. China's private clinic chains are consolidating procurement across multi-site networks.
- Veterinary Clinics:Species-specific equipment modifications with lower price sensitivity than human medical counterparts. Large animal practices in rural United States markets sustain pneumatic system demand.
Hospital networks anchor current revenue concentration. Ambulatory surgical centers represent the steepest expansion trajectory for cordless platform vendors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium-ion battery cell manufacturing clusters in South Korea and Japan anchor the supply chain for cordless cast saw platforms across major hospital networks.
United States
Academic medical centers in Boston and the Mayo Clinic system sustain replacement demand for oscillating blade systems as trauma caseloads rise among patients over 65. The FDA's 510(k) clearance pathway governs premarket notification for powered surgical instruments, compressing product iteration timelines. Texas Medical Center in Houston concentrates procurement authority for integrated delivery networks unbundling blade supply from device contracts.
Germany
Aging demographics in Bavaria and North Rhine-Westphalia sustain orthopedic clinic expansion for fracture management and joint procedures. The EU Medical Device Regulation imposes enhanced clinical evidence requirements for surgical power tool reclassification, extending registration timelines for notified body assessment. The medical technology cluster around Tübingen and Stuttgart anchors specialized surgical power tool manufacturing for European distribution.
China
County-level hospitals in Jiangsu and Zhejiang provinces deploy portable battery-powered units for emergency department overflow capacity. The National Medical Products Administration implements GB standards for electromagnetic compatibility and electrical safety that foreign manufacturers must address for market access. Shanghai's private clinic chains consolidate procurement across multi-site networks in tier-1 cities.
Japan
Orthopedic centers in Tokyo and Osaka evaluate ultrasonic blade systems for specialized hand surgery applications requiring precision cutting with minimal thermal load. The Pharmaceuticals and Medical Devices Agency oversees device registration under harmonized standards aligned with international quality management protocols. The Nagoya medical device manufacturing corridor supplies precision motor components for brushless DC platforms.
India
Government hospital modernization programs in Maharashtra and Karnataka create first-mover opportunity for battery-powered cast saw vendors addressing tier-2 and tier-3 city networks. The Central Drugs Standard Control Organization regulates medical device imports and domestic manufacturing under phased notification requirements. Delhi-NCR's orthopedic infrastructure buildout concentrates demand for cost-compact cordless units in public sector procurement.
Global Cast Saw Devices Market Competitive Landscape
Portfolio diversification dominates the current landscape as vendors unbundle blade assemblies from multi-year service contracts to compress margin stacking. The vendor base organizes around three strategic archetypes: integrated orthopedic ecosystem players, specialized surgical power tool manufacturers, and regional medical device distributors. Consolidation pressure concentrates among mid-scale European manufacturers facing EU MDR compliance costs. Geographic expansion and technology licensing represent the dominant competitive moves for accessing price-sensitive procurement committees.
Among diversified orthopedic platform vendors, Stryker Corporation and Smith & Nephew plc occupy positions anchored by brand strength in trauma and extremities segments. De Soutter Medical exemplifies the specialized surgical power tool archetype with European manufacturing heritage. These three entities represent distinct strategic postures without overlapping core competency claims.
| Leading Market Players |
|---|
| Stryker Corporation |
| Smith & Nephew plc |
| De Soutter Medical |
| Essity Aktiebolag |
| HEBU medical GmbH |
| McArthur Medical Sales, Inc. |
| Prime Medical, Inc. |
| Shanghai Bojin Medical Instrument Co., Ltd. |
| Hanshin Medical Co., Ltd. |
| Others |
Supply & Pricing Matrix
Integrated delivery networks in the United States concentrate procurement authority for cast saw devices, forcing vendors toward unbundled blade pricing models that separate consumable costs from capital equipment contracts. This buyer consolidation reshapes margin capture across the value chain as group purchasing organizations negotiate component supply independently from multi-year service agreements.
Pricing Analysis
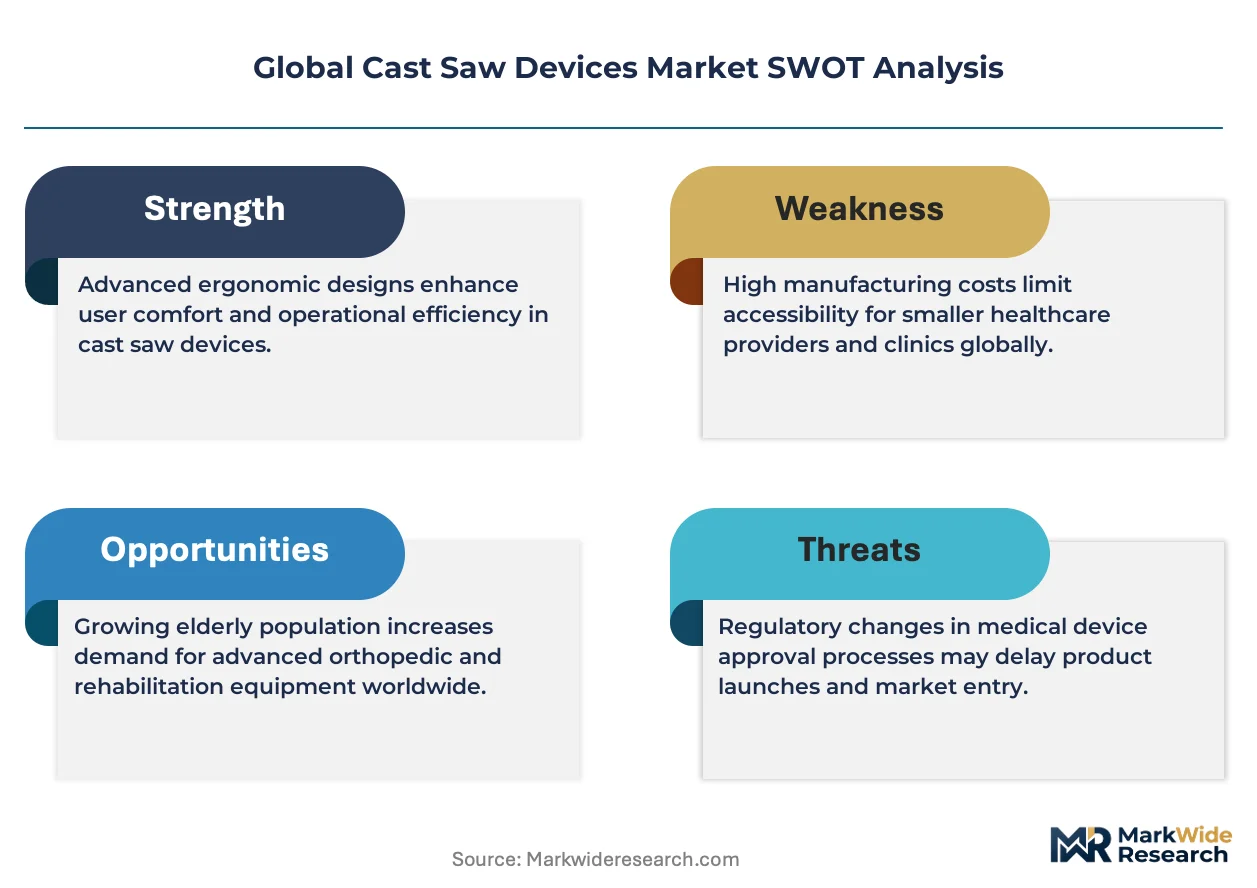
Warranty and preventive maintenance bundling varies sharply between vendor archetypes, with specialized surgical power tool manufacturers offering comprehensive service contracts while diversified orthopedic platforms push transactional blade-only pricing. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier, battery platform generation, and geographic delivery infrastructure. Pricing pressure stems from lithium-ion cell cost volatility as cobalt and nickel spot markets fluctuate. Ambulatory surgical centers exhibit highest price sensitivity due to constrained capital budgets, whereas academic medical centers prioritize safety certification and service reliability over unit economics.
Supply Chain Analysis
Lithium-ion battery cell production rests on South Korean and Japanese chemical conglomerates, with precision motor components sourced from Nagoya manufacturing corridors and blade assemblies fabricated in German and Chinese metalworking centers. Brushless DC motor controllers, cobalt-nickel-manganese cathode formulations, and surgical-grade stainless steel strip constitute critical input dependencies. Single-source vulnerability concentrates in specialty battery management system semiconductors. Distribution runs through regional medical device distributors serving hospital networks, with direct OEM relationships penetrating integrated delivery network procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cast saw device market is becoming a vertical-integration race as vendors pursue captive control over lithium-ion battery pack assembly to secure margin and supply continuity against raw material volatility.
For Market Incumbents: Deploy battery platform standardization across surgical power tool portfolios to lock hospital networks into proprietary ecosystems and raise switching costs. Consolidate blade manufacturing in-house to capture consumable revenue streams that procurement committees are unbundling from device contracts. Counter emerging entrants from Chinese domestic manufacturers by accelerating MDR-compliant product registrations ahead of notified body bottlenecks. For New Entrants and Emerging Players: Launch via tier-2 and tier-3 hospital networks in India where government modernization programs create first-mover windows before incumbent distribution relationships solidify. Target pediatric orthopedic practices with reduced-noise, reduced-vibration blade designs that incumbents have neglected. Pursue white-label manufacturing partnerships with established surgical power tool OEMs to bypass FDA 510(k) timeline disadvantages. For Investors and Strategic Acquirers: The window for entry favors specialized surgical power tool manufacturers with ISO 13485 quality systems and established European notified body relationships. Long-term viability hinges on lithium-ion battery chemistry expertise and brushless motor control IP. Watch MDR compliance completion rates as an inflection signal for European market access timing and competitive clearance velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Stryker's integrated orthopedic ecosystem secures captive demand across network procurement committees. |
| CE Marking Pathway | EU MDR Article 10 clinical evidence requirements extend registration timelines for surgical power tool reclassification. |
| Backward Integration into Battery Assembly | Captive lithium-ion pack production insulates margins from cobalt and nickel spot market volatility. |
| Software Companion Development | Smart battery management systems differentiate cordless platforms in ambulatory surgical center procurement. |
| Reimbursement Strategy | Outpatient cast removal coding alignment accelerates same-day discharge protocol adoption in United States ASCs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with hospital purchasing committee directors, biomedical engineering managers, orthopedic clinic administrators, and surgical power tool procurement specialists at group purchasing organizations. FDA 510(k) premarket notification databases, EU MDR notified body assessment records, NMPA registration filings, and hospital procurement contract repositories provided demand-side validation. Bottom-up unit shipment estimates triangulated against top-down revenue segmentation across product type, technology, application, and end-user dimensions.
Data-stream reconciliation across volume and value outputs employed a structured analytical framework spanning the projection horizon. Segmentation dimensions modeled include power source architecture, blade mechanism type, clinical setting, and geographic regulatory cluster. CAGRs derived from fitted growth curves incorporating trauma caseload demographics, replacement cycle compression from cordless platform adoption, and infrastructure buildout rates in emerging markets. Forecast inputs incorporated lithium-ion battery cost trajectories, MDR compliance velocity, and ambulatory surgical center expansion patterns.
The model assumes a particular technology adoption path; alternative pathways for ultrasonic blade commercialization would alter the outlook if Japanese orthopedic centers accelerate precision cutting platform evaluation. Forecasts reflect assumptions regarding regulatory clearance timelines, raw material cost stabilization, and hospital capital expenditure recovery. A small set of named triggers warrants ongoing watch: EU MDR notified body capacity constraints, cobalt supply chain disruptions from Central African sourcing regions, and CMS reimbursement coding changes for outpatient orthopedic procedures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Wearable Medical Devices Market
Medical Devices
Indwelling Catheter Market
Medical Devices
Tumour Ablation Devices Market
Medical Devices
South Korea Artificial Organs and Bionics Market
Medical Devices
3D and 4D Ultrasound Devices Market
Medical Devices
Gamma Knife Market
Medical Devices
Smart Bassinet Market
Medical Devices
Handheld Red Light Therapy Device Market
Medical Devices
Submucosal Injections Market
Medical Devices
Global Tympanostomy Products Market
Medical Devices
Physiotherapy Laser Wrist Watch Market
Medical Devices
Bone Growth Stimulators Market
Medical Devices
Asia-Pacific Viscosupplementation Market
Medical Devices
Sleeve Gastrectomy Devices Market
Medical Devices
Global Live Cell Encapsulation Market
Medical Devices
Prescription Goggles Market