
 Canada Contraceptive Devices Market | 2026-2036
Canada Contraceptive Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Contraceptive Devices Market Outlook
Canadian pharmaceutical manufacturing capacity is realigning toward hormone-eluting device production. Bayer AG anchors its North American contraceptive portfolio through established intrauterine device supply chains serving Ontario and British Columbia. Pfizer Inc. competes in hormonal delivery segments with sustained investment in implant formulation R&D. Johnson & Johnson leverages its consumer health division to control pharmacy shelf presence for over-the-counter barrier methods across Canadian provinces.
Contraceptive devices comprise regulated medical products designed to prevent pregnancy through hormonal suppression, physical barrier, or copper-ion mechanisms, with specifications varying by active pharmaceutical ingredient load, dwell time, and insertion methodology. Their primary commercial purpose centers on reversible fertility management within outpatient clinical and retail pharmacy settings. Intrauterine devices lead product type revenue pools due to extended duration of action and higher reimbursement rates under provincial drug plans. Condoms occupy mature over-the-counter channels with thin-margin, high-volume economics. Implants represent the fastest-expanding prescriptive category as healthcare providers shift toward long-acting reversible contraception counseling protocols.
Health Canada regulates device licensing under the Medical Devices Regulations, while provincial formularies determine public reimbursement eligibility and patient cost-sharing levels. Health Canada's alignment with International Medical Device Regulators Forum standards accelerates approval timelines for copper and hormone-eluting intrauterine devices. Stakeholders must monitor Ontario's formulary expansion negotiations and Health Canada's anticipated medical device classification updates to anticipate reimbursement-driven demand shifts.
Market Dynamics
Provincial formulary expansion is the dominant structural force reshaping contraceptive device access across Canada, with Ontario and Quebec systematically adding long-acting reversible contraceptives to public reimbursement schedules while Health Canada accelerates medical device licensing timelines.
Growth Catalysts
- Health Canada Medical Devices Regulations:Streamlined licensing pathways for hormone-eluting intrauterine devices reduce time-to-market for manufacturers serving Canadian healthcare systems.
- Long-acting reversible contraception counseling protocols:Family health teams in Ontario and British Columbia are systematically integrating implant and intrauterine device counseling into standard primary care workflows.
- Copper-ion mechanism devices:Non-hormonal alternatives are capturing patient segments with contraindications to progestin-based methods, expanding total addressable demand within fertility management clinics.
Market Restraints
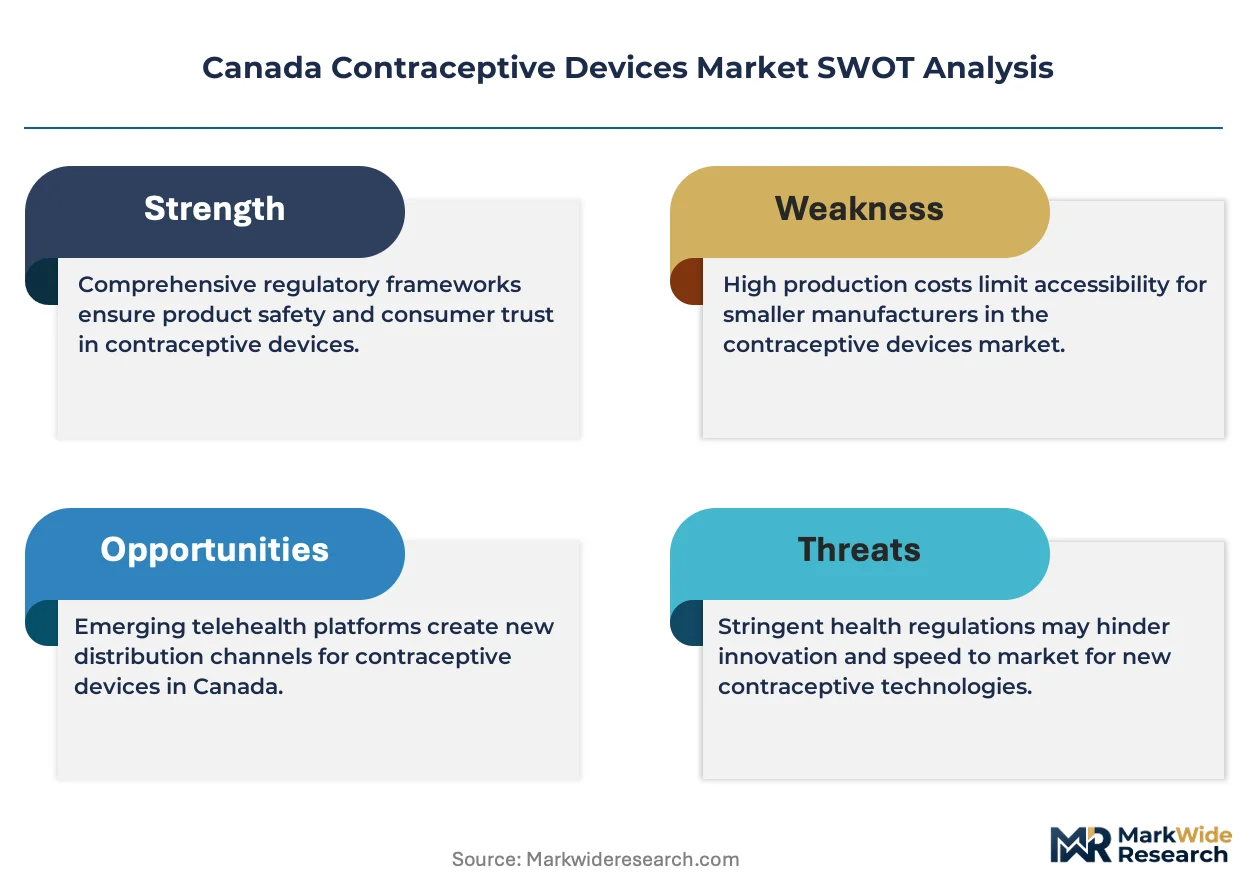
- Provincial reimbursement fragmentation:Atlantic Canada maintains inconsistent formulary coverage for intrauterine devices, creating geographic access inequities that suppress volume in New Brunswick and Nova Scotia.
- Specialized insertion training requirements:Rural healthcare provider shortages limit implant and intrauterine device placement capacity outside major urban centers in Manitoba and Saskatchewan.
- Barrier method substitution:Over-the-counter condom availability through pharmacy and retail channels captures price-sensitive demand that might otherwise convert to prescription devices.
Strategic Opportunities
- Telehealth-enabled prescription pathways:Virtual consultation platforms in Alberta and British Columbia are opening direct-to-patient channels for contraceptive counseling and device referral.
- Extended-duration hormone formulations:Next-generation implants with six-to-eight year efficacy profiles address patient preference for reduced replacement frequency.
- Indigenous community health center partnerships:Federally funded nursing stations and health centers in remote First Nations territories represent underpenetrated distribution nodes for subsidized device programs.
Industry Challenges
- Health Canada medical device classification updates:Anticipated reclassification of certain hormone-eluting devices to higher-risk categories threatens extended compliance timelines and additional clinical evidence requirements.
- Legacy electronic medical record integration:Provincial health information systems in Quebec and Ontario lack standardized contraceptive device tracking modules, complicating outcome monitoring and recall management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Contraceptive Devices Market |
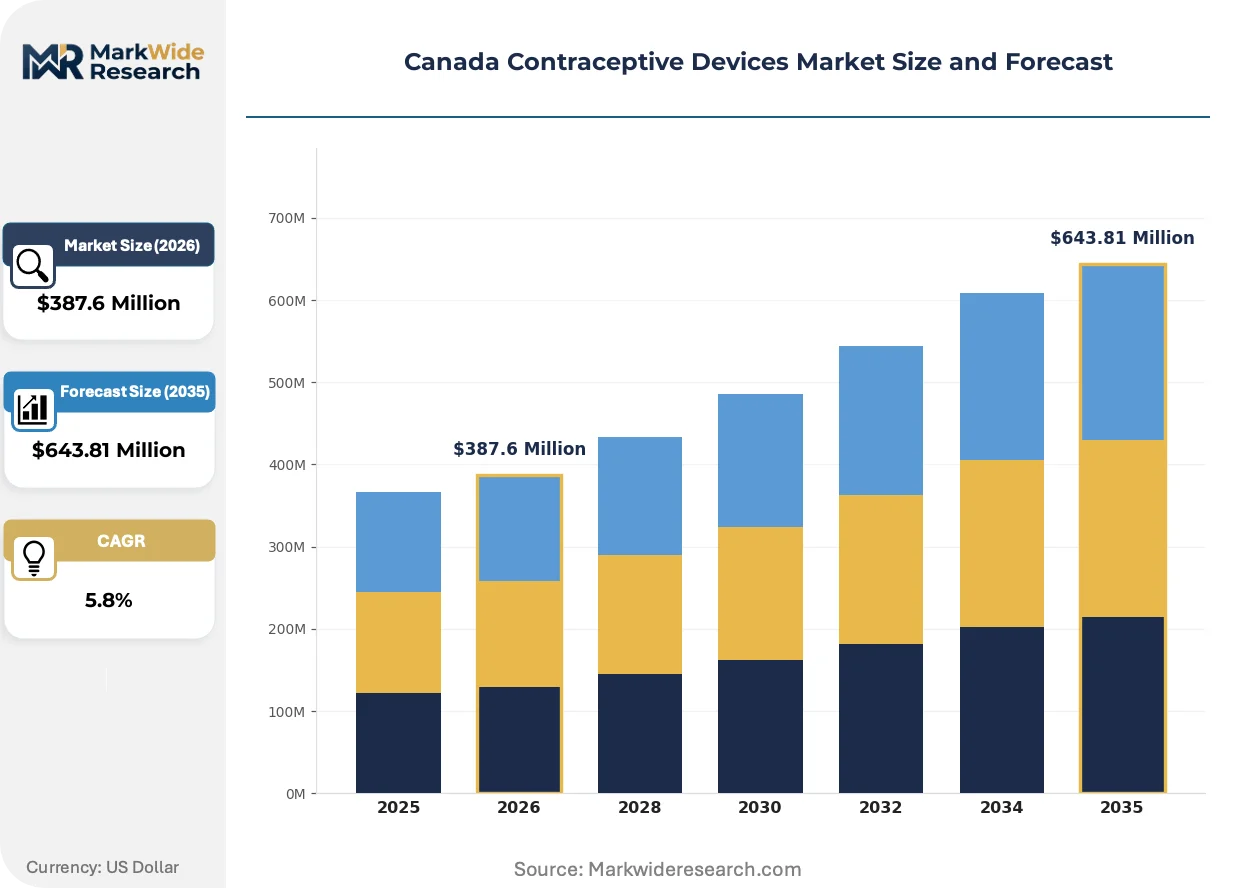
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intrauterine Devices, Condoms, Birth Control Pills, Implants End User: Healthcare Providers, Pharmacies, Clinics, Hospitals Material: Silicone, Latex, Polyurethane, Metal Usage Mode: Prescriptive, Over-the-Counter, Surgical, Non-Surgical |
| Companies Covered | CooperSurgical Inc., AbbVie Inc., Bayer AG, Pfizer Inc., Reckitt Benckiser, Teva Pharmaceutical Industries Ltd., Mylan N.V., Johnson & Johnson, Merck & Co., Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Contraceptive Devices Market Strategic Shifts
Biodegradable polymer technology and digital health integration are converging to transform how contraceptive devices are manufactured, prescribed, and monitored across Canadian healthcare networks.
Biodegradable implant matrices are rewriting the surgical removal requirement that has historically limited implant acceptance among Canadian patients. Family health clinics in urban Ontario are piloting these absorbable formulations at accelerated rates compared to rural counterparts. The technology is compressing the total cost of ownership for provincial drug plans by eliminating explantation procedure reimbursements.
Health Canada's alignment with International Medical Device Regulators Forum standards is synchronizing approval pathways for copper and hormone-eluting intrauterine devices with European and Australian regulators. Device manufacturers are consolidating clinical trial designs to satisfy multiple jurisdictions simultaneously. Intrauterine device submissions are experiencing the most pronounced timeline compression under this harmonized framework.
Patient-managed fertility tracking applications are disrupting traditional pharmacy-based contraceptive purchasing patterns among younger demographics in British Columbia and Alberta. Subscription-based digital health platforms are capturing counseling and prescription renewal functions previously performed in clinical settings. This behavioral shift is most concentrated among university-educated women aged 18-29 in Vancouver and Calgary metropolitan areas.
Canada Contraceptive Devices Market Segmentation
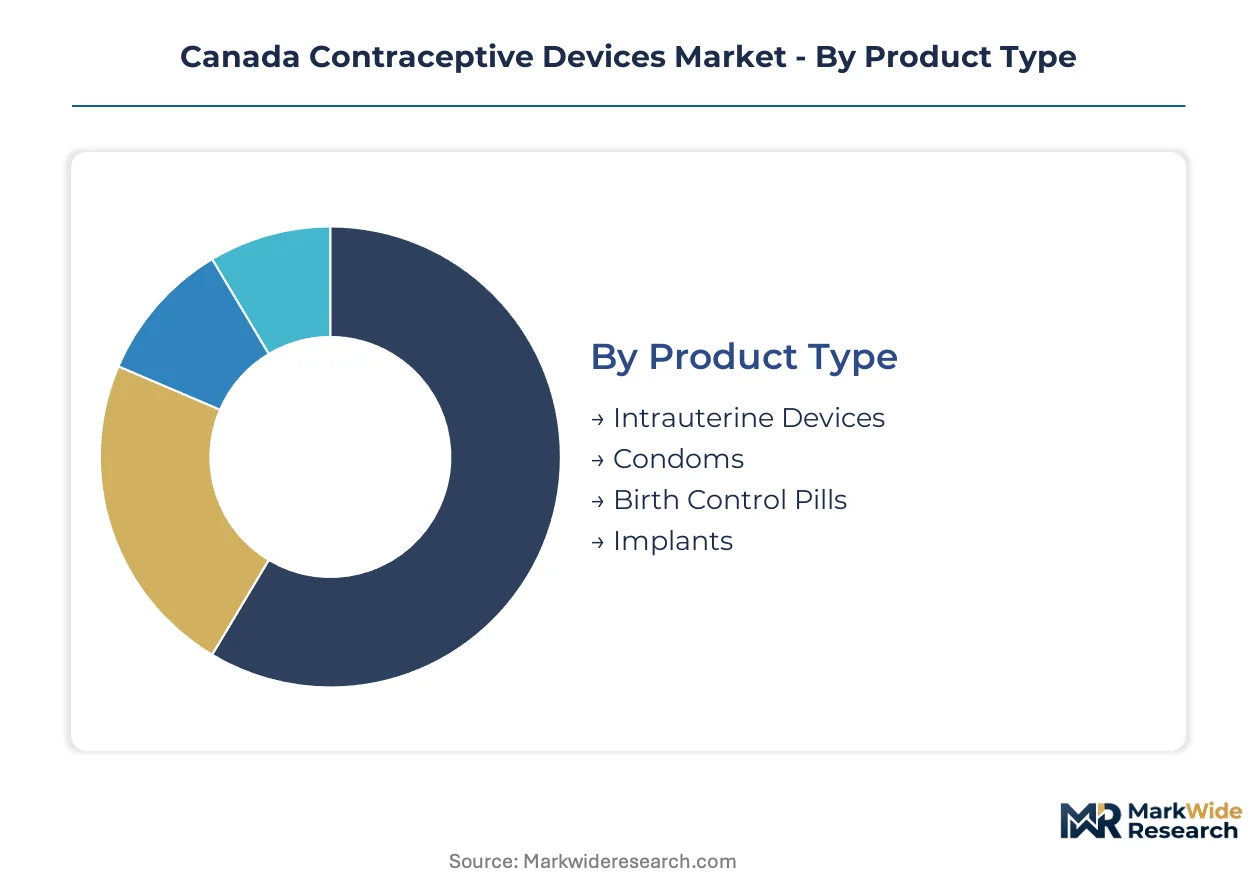
Device specification and procurement pathway segmentation determines reimbursement eligibility and margin structure across Canadian provincial health systems. Each dimension carries distinct regulatory implications under Health Canada frameworks and provincial formulary negotiations.
Product Type:
Supply concentration in hormone-eluting device manufacturing anchors the competitive landscape, with intrauterine systems commanding premium positioning through extended duration profiles.
- Intrauterine Devices:T-shaped frames deliver copper ions or progestin directly to the endometrial cavity, achieving efficacy through localized spermicidal or ovulation-suppression mechanisms. Ontario and Quebec health authorities prioritize these devices in formulary expansion negotiations due to cost-per-protected-year economics that outperform oral alternatives.
- Condoms:Latex and synthetic polymer barriers provide dual protection against pregnancy and sexually transmitted infections through physical fluid isolation. Pharmacy chains in British Columbia and Alberta capture volume through high-frequency replenishment cycles, though thin margins limit manufacturer investment in formulation innovation.
- Birth Control Pills:Oral hormonal regimens require daily adherence, creating compliance gaps that provincial drug plans address through alternative device subsidies.
- Implants:Subdermal rods release progestin over multi-year intervals, gaining traction in Ontario family health teams implementing long-acting reversible contraception counseling protocols.
Today's leader: Intrauterine Devices. Tomorrow's challenger: Implants.
End User:
Procurement authority fragmentation across institutional tiers creates distinct contracting dynamics, with hospitals leveraging volume aggregation against pharmacy retail fragmentation.
- Healthcare Providers:Physician offices and nurse practitioner clinics in Ontario deliver prescriptive counseling and device insertion services, capturing professional fees alongside product dispensing revenue. Health Canada's streamlined licensing pathways accelerate product availability through these channels.
- Pharmacies:Community and retail pharmacy networks dominate over-the-counter barrier method distribution, with Shoppers Drug Mart and Rexall controlling shelf placement economics across Canadian provinces.
- Clinics:Sexual health and fertility management centers in Vancouver and Toronto metropolitan areas specialize in complex device selection for patients with contraindications to standard hormonal methods.
- Hospitals:Acute care institutions in Quebec and Ontario aggregate procurement volume for postpartum intrauterine device placement programs, achieving favorable pricing through group purchasing organizations.
Procurement authority concentrates in hospitals. Patient access expansion centers on clinics.
Material:
Biocompatibility certification requirements under Health Canada Medical Devices Regulations segment manufacturing capacity by polymer chemistry expertise and metal processing capabilities.
- Silicone:Medical-grade elastomers form implantable rods and diaphragm rims, with platinum-cured formulations meeting biocompatibility standards for extended dwell applications. Alberta-based compounding facilities supply domestic device manufacturers seeking reduced import dependency.
- Latex:Natural rubber dominates mass-market condom production, though protein allergen concerns drive substitution toward synthetic alternatives in Quebec's formulary procurement.
- Polyurethane:Thermoplastic elastomers enable thinner barrier constructions with equivalent burst strength, capturing premium positioning in British Columbia retail channels.
- Metal:Copper wire and nickel-titanium alloys construct non-hormonal intrauterine frames, with purity specifications governed by Health Canada biocompatibility testing protocols.
Silicone commands implant applications. Polyurethane is displacing latex in premium tiers.
Usage Mode:
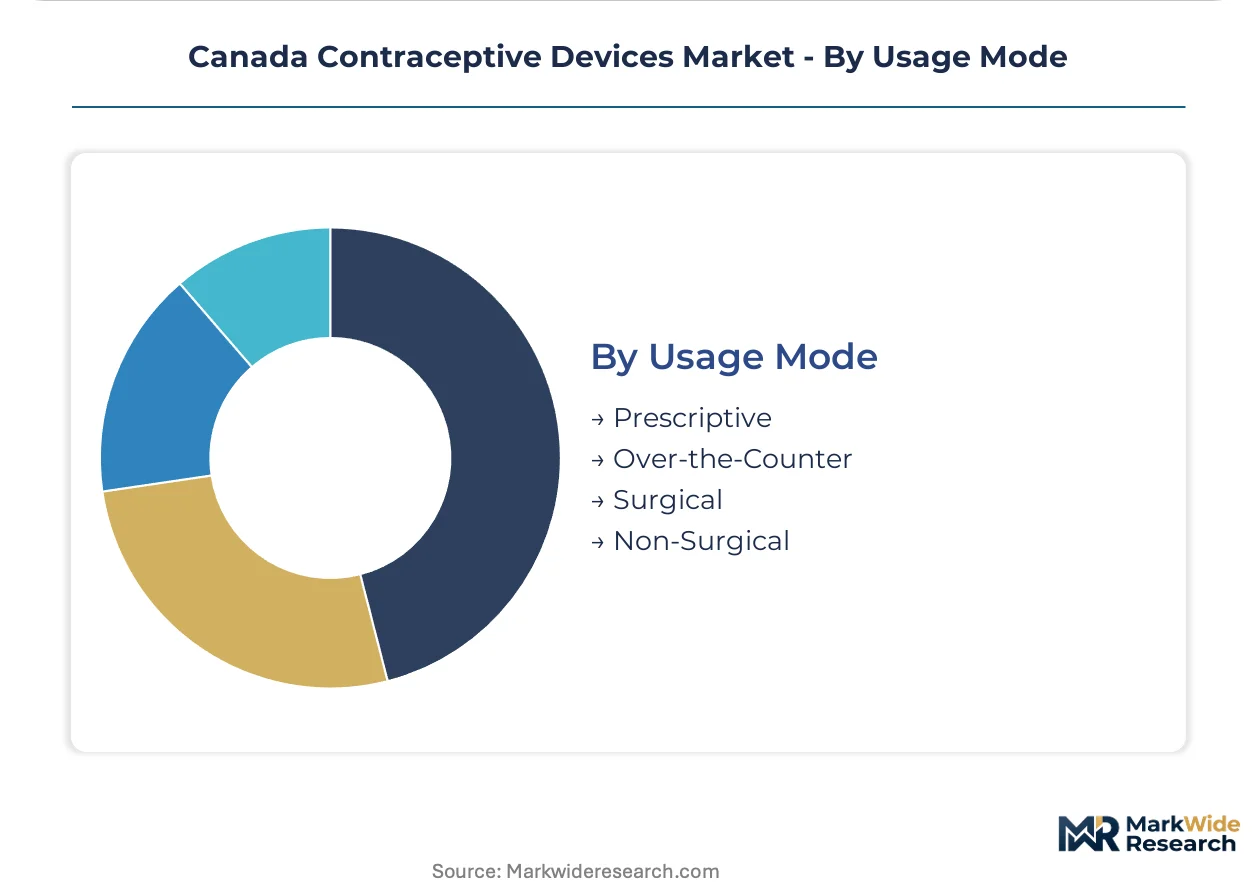
Regulatory classification under Health Canada Medical Devices Regulations stratifies distribution channels by risk tier, with prescriptive requirements protecting higher-risk hormonal delivery systems.
- Prescriptive:Hormone-eluting intrauterine devices and implants require physician or nurse practitioner authorization, creating clinical gatekeeping that influences patient access patterns across rural Manitoba and Saskatchewan.
- Over-the-Counter:Barrier methods bypass clinical authorization, enabling immediate access through pharmacy and retail channels that capture price-sensitive demand segments in Atlantic Canada.
- Surgical:Permanent sterilization procedures and complex implant removals occur in hospital settings, with fee schedules varying by provincial health insurance plans.
- Non-Surgical:Self-administered barrier methods and patient-inserted devices reduce healthcare system contact costs, appealing to telehealth-integrated care models in Alberta.
Prescriptive modes dominate value capture. Over-the-Counter modes dominate volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health Canada's streamlined Medical Devices Regulations create a compliance-cost advantage that attracts hormone-eluting device manufacturing investment toward Ontario and Quebec, while provincial formulary fragmentation generates arbitrage opportunities across sub-national markets.
Ontario
Toronto's family health teams drive implant counseling protocol adoption, with provincial formulary expansion adding long-acting reversible contraceptives to public reimbursement schedules. Health Canada's accelerated licensing pathways reduce time-to-market for manufacturers serving this population center. The Greater Toronto Area concentrates hospital procurement volume through group purchasing organizations managing postpartum intrauterine device placement programs.
Quebec
Montreal's sexual health clinics specialize in complex device selection for patients with hormonal contraindications, capturing demand from Atlantic Canada referral pathways. The province's formulary negotiations prioritize copper-ion intrauterine devices for cost-per-protected-year economics. Quebec City anchors provincial health information system development, though legacy electronic medical record platforms lack standardized contraceptive device tracking modules.
British Columbia
Vancouver's telehealth platforms pioneer direct-to-patient contraceptive counseling channels, with subscription-based digital health services capturing prescription renewal functions. The province's retail pharmacy chains control over-the-counter barrier method distribution across Pacific Northwest metropolitan corridors. Health Canada's alignment with International Medical Device Regulators Forum standards accelerates approval timelines for devices entering this market.
Alberta
Calgary's virtual consultation networks expand rural patient access to long-acting reversible contraception referrals, addressing healthcare provider shortages outside urban centers. The province's nursing stations in remote Indigenous territories represent underpenetrated distribution nodes for subsidized device programs. Edmonton-based compounding facilities supply medical-grade silicone for domestic implant manufacturing.
Atlantic Canada
Halifax and Moncton face inconsistent formulary coverage for intrauterine devices, creating geographic access inequities that suppress volume compared to central Canadian markets. New Brunswick's healthcare system relies on out-of-province referrals for specialized implant insertion services. Nova Scotia's sexual health centers concentrate limited prescriptive capacity within Halifax Regional Municipality.
Canada Contraceptive Devices Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue biodegradable polymer and digital health integration adjacent spaces. The market structures around three tiers: multinational pharmaceutical conglomerates with integrated device portfolios, specialized medical device manufacturers focused on intrauterine systems, and consumer health divisions controlling over-the-counter distribution. Strategic archetypes include hormone-eluting technology specialists, copper-ion mechanism fabricators, and barrier method mass-market suppliers. Dominant competitive moves encompass provincial formulary negotiation positioning and Health Canada licensing pathway optimization.
Within the multinational tier, Bayer AG and Pfizer Inc. exemplify divergent strategic positioning—Bayer anchoring North American intrauterine device supply chains through established distribution networks, Pfizer occupying hormonal delivery segments with sustained implant formulation development. Johnson & Johnson represents the consumer health archetype, leveraging pharmacy shelf presence for over-the-counter barrier methods across Canadian provinces. Among specialized device manufacturers, CooperSurgical Inc. occupies a position in fertility management clinic supply chains. These named entities illustrate how competitive positioning stratifies by regulatory navigation capability and provincial procurement relationship depth.
| Leading Market Players |
|---|
| CooperSurgical Inc. |
| AbbVie Inc. |
| Bayer AG |
| Pfizer Inc. |
| Reckitt Benckiser |
| Teva Pharmaceutical Industries Ltd. |
| Mylan N.V. |
| Johnson & Johnson |
| Merck & Co., Inc. |
| Others |
Value Chain & Pricing Dynamics
Biodegradable polymer manufacturing transitions are simultaneously compressing production costs for hormone-eluting devices and concentrating supply relationships among Health Canada-certified polymer compounders serving Ontario and Quebec health systems. This dual effect reshapes procurement economics for provincial drug plans while locking in tiered pricing structures across prescriptive and over-the-counter channels.
Pricing Analysis
Distributor margins for hormone-eluting intrauterine devices absorb the steepest compression as provincial group purchasing organizations consolidate procurement volume in Ontario and Quebec. Pricing stratifies across premium, standard, and economy tiers based on device dwell-time specifications and Health Canada biocompatibility certification levels. Cost compression in the standard tier intensifies because Atlantic Canada formulary fragmentation limits volume aggregation. Hospital systems demonstrate lowest price sensitivity due to postpartum placement program mandates, while independent pharmacies in Manitoba and Saskatchewan face highest sensitivity from thin-margin barrier method competition.
Supply Chain Analysis
Regional distribution centers in Toronto and Montreal anchor hub-and-spoke patterns reaching Atlantic Canada and Prairie provinces with 48-to-72-hour replenishment cycles. Manufacturing concentration rests on Germany, the United States, and Belgium for hormone-eluting polymer matrices, copper wire drawing, and medical-grade silicone compounding. Raw material dependencies include pharmaceutical-grade progestin APIs, nickel-titanium shape-memory alloys, and platinum-cured silicone elastomers. Single-source vulnerability for specialized polymer formulations threatens continuity under Health Canada reclassification timelines. Distribution runs through manufacturer-direct hospital contracting for prescriptive devices, with retail pharmacy networks controlling over-the-counter barrier method flow.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada contraceptive devices market represents a late-cycle quality story as provincial formulary expansion shifts procurement criteria toward extended-duration efficacy specifications and biodegradable removal profiles.
For Market Incumbents: Lock in formulary positioning through preemptive Health Canada licensing pathway optimization ahead of anticipated medical device classification updates. Secure backward integration into pharmaceutical-grade polymer compounding to defend margin structures against emerging biodegradable implant specialists. The threat of digital health platform substitution for counseling functions demands parallel investment in telehealth-integrated prescription renewal capabilities. For New Entrants and Emerging Players: Capture Indigenous community health center partnerships as the most penetrable distribution node, where federally funded nursing stations in remote First Nations territories remain underserved by established supply chains. Target Alberta's virtual consultation networks as the fastest-expanding prescriptive channel outside traditional clinic infrastructure. A go-to-market angle emphasizing six-to-eight year implant efficacy profiles addresses unmet patient preference for reduced replacement frequency. For Investors and Strategic Acquirers: Roll-up economics work for specialized intrauterine device manufacturers because provincial procurement consolidation rewards scale in Health Canada regulatory navigation and formulary negotiation capacity. Long-term viability hinges on portfolio exposure to hormone-eluting technology rather than commoditized barrier methods. The signal to watch is Ontario's electronic medical record standardization timeline, which will determine outcome-tracking infrastructure investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Licensing Pathway Optimization | Accelerated approval timelines for hormone-eluting devices compress competitive time-to-market gaps against European regulators. |
| Provincial Formulary Expansion Negotiation | Ontario and Quebec reimbursement schedule additions directly unlock public-sector volume for long-acting reversible contraceptives. |
| Biodegradable Polymer Manufacturing Scale-Up | Domestic compounding capacity in Alberta and Ontario reduces import dependency for implant matrix materials. |
| Telehealth Platform Integration | Virtual consultation networks in British Columbia and Alberta capture prescription renewal functions from traditional clinic workflows. |
| Indigenous Community Health Center Partnership | Federally funded nursing stations in remote First Nations territories represent subsidized device program expansion nodes. |
Study Parameters
Bottom-up provincial formulary modeling reconciled against top-down manufacturer supply tracking forms the analytical core of this study. Primary interviews with Health Canada regulatory affairs specialists, Ontario hospital procurement managers, Quebec formulary directors, and British Columbia telehealth platform operators combined with secondary validation from Health Canada Medical Devices Regulations filings, provincial drug plan reimbursement databases, and group purchasing organization contract disclosures. Triangulation across these sources ensures demand-side estimates align with supply-side capacity announcements.
Input-output matrices map device specification segments against end-user procurement authority tiers across the projection horizon. Segmentation dimensions modeled include product type, material composition, usage mode regulatory classification, and provincial reimbursement status. CAGRs derive from volume-weighted average of segment-level growth trajectories, with hormone-eluting intrauterine devices and biodegradable implants receiving distinct elasticity coefficients based on formulary expansion schedules. Forecast inputs incorporate Health Canada licensing timeline assumptions and provincial health information system integration readiness.
Health Canada classification updates, provincial formulary negotiation delays, and rural healthcare provider shortage persistence are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions about regulatory harmonization timelines and reimbursement expansion sequencing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Manometry System Market
Medical Devices
North America Ultrasound Devices Market
Medical Devices
Latin America Biomedical Sensors Market
Medical Devices
Russia Massage Equipment Market
Medical Devices
Australia and New Zealand Diabetes Devices Market
Medical Devices
Global Cochlear Implant Market
Medical Devices
United States Implantable Medical Devices Market
Medical Devices
Inhaled Nitric Oxide (NO) Delivery Systems Market
Medical Devices
Intelligent Prosthetics Market
Medical Devices
Cochlear Implant Systems Market
Medical Devices
Acoustic Puncture Assist Devices Market
Medical Devices
Incubator Devices Market
Medical Devices
Bone Allografts Market
Medical Devices
Erectile Dysfunction Shockwave Generators Market
Medical Devices
Electrosurgical Generators Market
Medical Devices
Hormonal Implants Market