
 Refurbished Dental Equipment and Maintenance Market | 2026-2036
Refurbished Dental Equipment and Maintenance Market Size, Share, and Industry Trends Forecast 2026-2036
Refurbished Dental Equipment and Maintenance Market Outlook
Multi-location dental service organizations is bifurcating procurement patterns away from solo practitioners who historically dominated new equipment purchases. Henry Schein leverages its distribution network to channel certified pre-owned units through formal dealer programs. Atlas Resell Management competes through technology-led inspection protocols that validate digital imaging component lifecycles. American Dental Refurbishment anchors its position in chair unit restoration, where cosmetic reconditioning and hydraulic system replacement sustain margin pools.
Refurbished dental equipment and maintenance encompasses the restoration, recertification, and ongoing servicing of previously deployed clinical apparatus to original manufacturer performance specifications, typically involving replacement of worn polymers, recalibration of sterilization cycles, and software updates for digital control modules. The primary purpose is to extend functional service life while meeting infection control and diagnostic accuracy standards at reduced capital outlay. Chair units and digital imaging systems command the largest volume flows, with autoclave refurbishment generating concentrated margin pools due to mandatory sterilization validation requirements. CAD/CAM technology segments within digital imaging are expanding fastest as laboratories and clinics seek affordable entry points into restorative workflow automation.
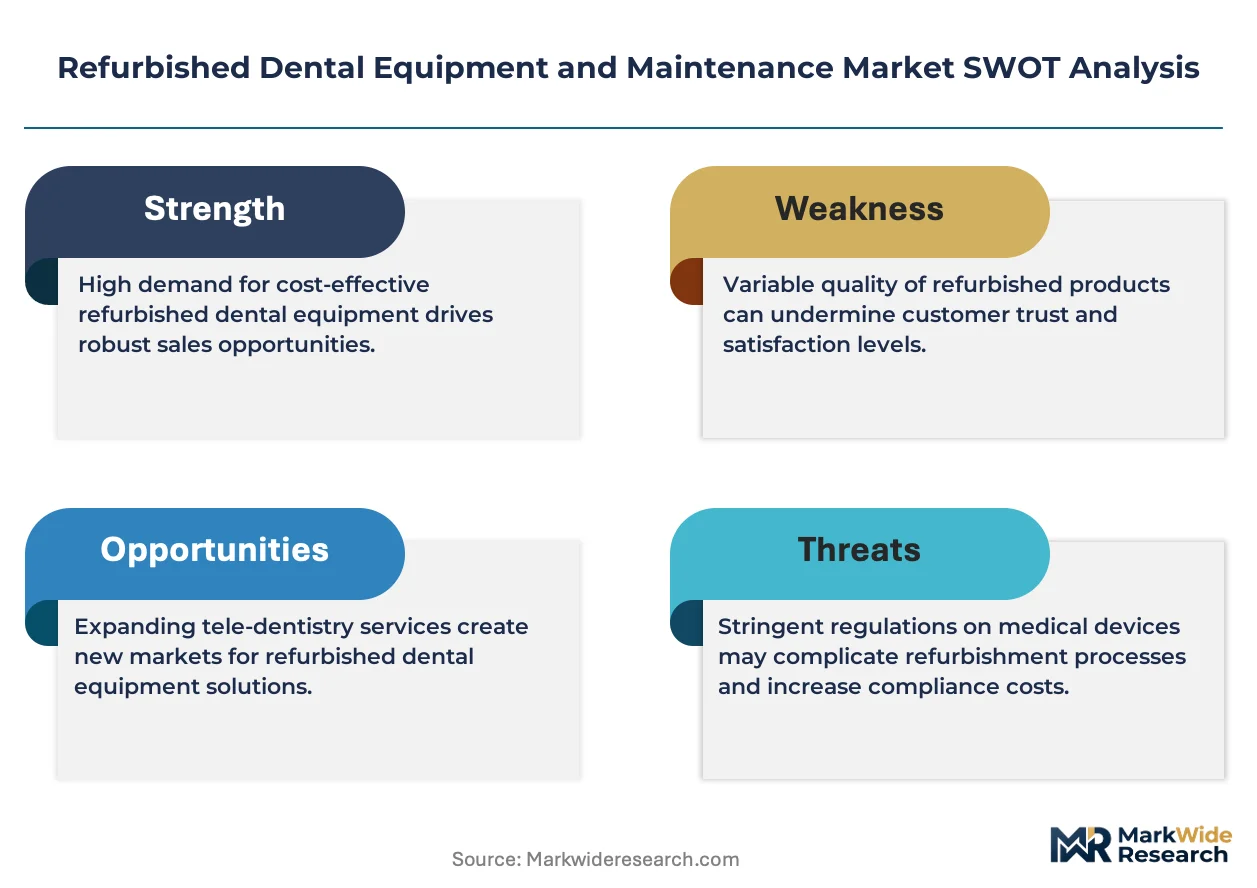
FDA 510(k) clearance requirements for refurbished medical devices shape market access by mandating predicate device equivalence documentation and quality system regulation compliance. The EU Medical Device Regulation and ISO 13485 certification frameworks enforce traceability protocols that filter low-capability refurbishers from formal supply chains. Stakeholders must monitor evolving notified body designation patterns and calibration standard updates to protect procurement flexibility and service revenue continuity.
Market Dynamics
Cost-sensitive dental service organizations are consolidating procurement volumes around certified pre-owned equipment, compressing traditional new-equipment sales cycles and forcing refurbishment networks to scale quality documentation infrastructure.
Growth Catalysts
- EU Medical Device Regulation:MDR traceability mandates are filtering out low-capability refurbishers, concentrating certified supply around ISO 13485-accredited facilities and expanding their addressable customer base.
- Digital imaging component lifecycle validation:Advanced inspection protocols for sensor arrays and control modules are extending functional service warranties, reducing buyer risk perception.
- Multi-location dental service organizations:DSOs are standardizing equipment fleets across acquired practices, creating bulk demand for matched-condition refurbished chair units.
Market Restraints
- Polymer and precision metal input costs:Replacement of worn chair upholstery and hydraulic components faces volatile commodity pricing, squeezing refurbishment margin pools.
- Notified body designation concentration:EU MDR implementation has reduced the number of active conformity assessment bodies, lengthening recertification timelines for smaller refurbishers.
- Single-use device substitution:Disposable handpiece and bur systems are displacing reprocessable alternatives in infection-control-sensitive procedures.
Strategic Opportunities
- India clinic expansion corridors:Tier-2 and tier-3 city dental chains lack established refurbishment infrastructure, creating first-mover positioning for quality-certified entrants.
- CAD/CAM workflow automation:Laboratories and restorative practices seek affordable entry points into chairside milling systems, expanding the addressable base beyond traditional imaging.
- Remote calibration and predictive maintenance:IoT-enabled condition monitoring is enabling subscription-based service revenue models that attach to refurbished equipment sales.
Industry Challenges
- Biomedical technician certification pipelines:FDA 510(k) documentation requirements and ISO 13485 quality system implementation demand specialized training that outpaces vocational program output.
- Legacy software integration:Digital control module updates must maintain backward compatibility with practice management systems, complicating refurbishment workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refurbished Dental Equipment and Maintenance Market |
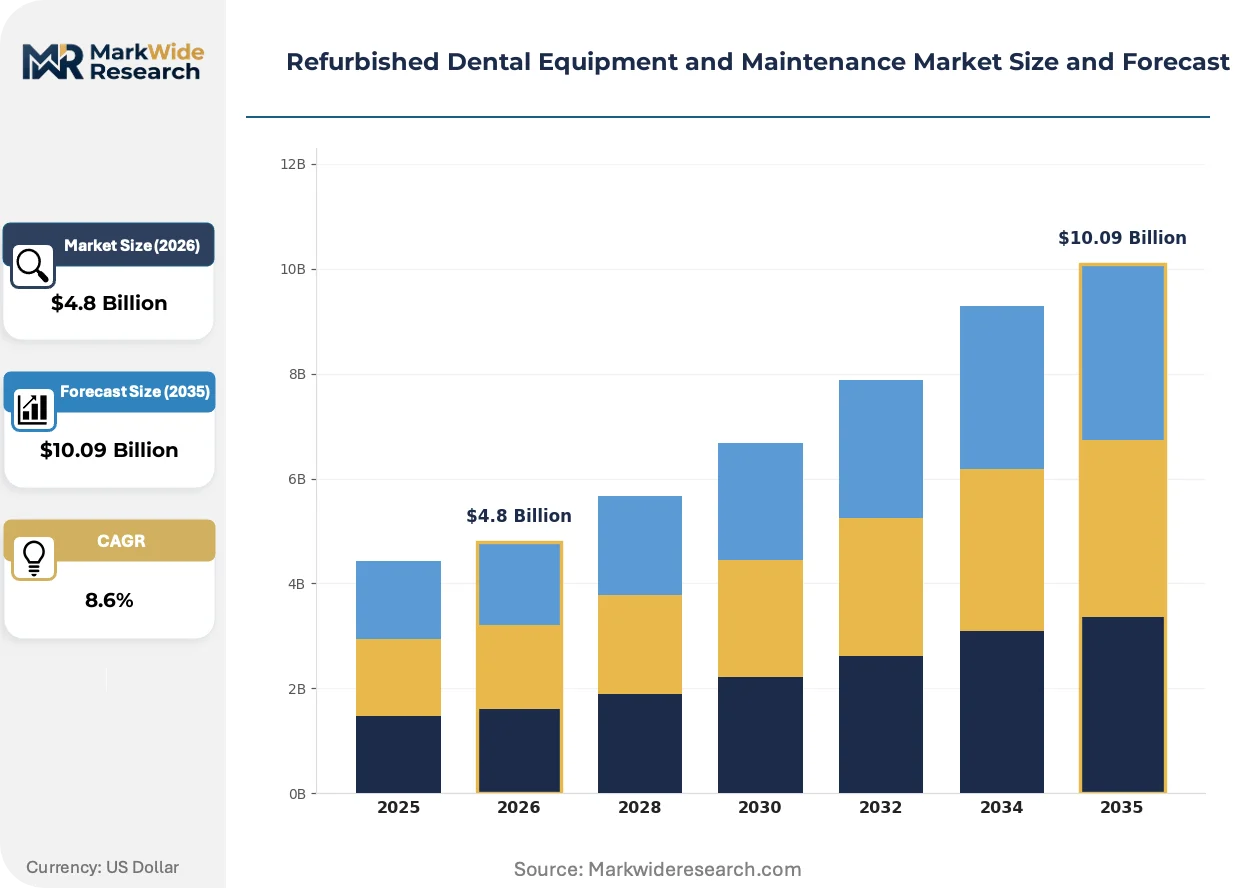
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chair Units, Autoclaves, X-Ray Systems, Handpieces Service Type: Repair, Calibration, Installation, Parts Replacement End User: Dental Clinics, Hospitals, Dental Laboratories, Dental Schools Technology: Digital Imaging, Laser Devices, CAD/CAM, 3D Printing |
| Companies Covered | American Dental Refurbishment, Capital Dental Equipment, Atlas Resell Management, A & K Dental Equipment, Henry Schein, Dental Equipment Liquidators Inc., Collins Dental Equipment Inc., Pre-Owned Dental Inc., Patterson Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refurbished Dental Equipment and Maintenance Market Strategic Shifts
Refurbishment value chains are digitizing inspection and documentation workflows, compressing buyer decision cycles while raising the technical bar for market participation.
AI-assisted component failure prediction is fragmenting traditional refurbishment scheduling. Machine learning models analyze sensor degradation patterns in digital imaging systems to flag preemptive replacement needs. Mid-sized dental laboratories are adopting these tools fastest, shifting from calendar-based maintenance to condition-triggered service intervals. The technology is fragmenting incumbent service revenue models built on fixed preventive maintenance contracts.
EU MDR Article 17 requirements for refurbished device traceability are tightening quality system documentation. Manufacturers must now maintain device history records equivalent to new production. German dental equipment refurbishers are investing in serialized component tracking systems. The regulation is compressing informal secondary markets while expanding formal dealer program volumes.
Subscription-based equipment access is displacing capital purchase models among emerging dental chains. Monthly per-chair fees bundle refurbished units with maintenance, calibration, and software updates. United States DSOs are piloting these arrangements to preserve cash flow for acquisition-driven expansion. The model is concentrating procurement authority at corporate headquarters rather than individual practice owners.
Refurbished Dental Equipment and Maintenance Market Segmentation
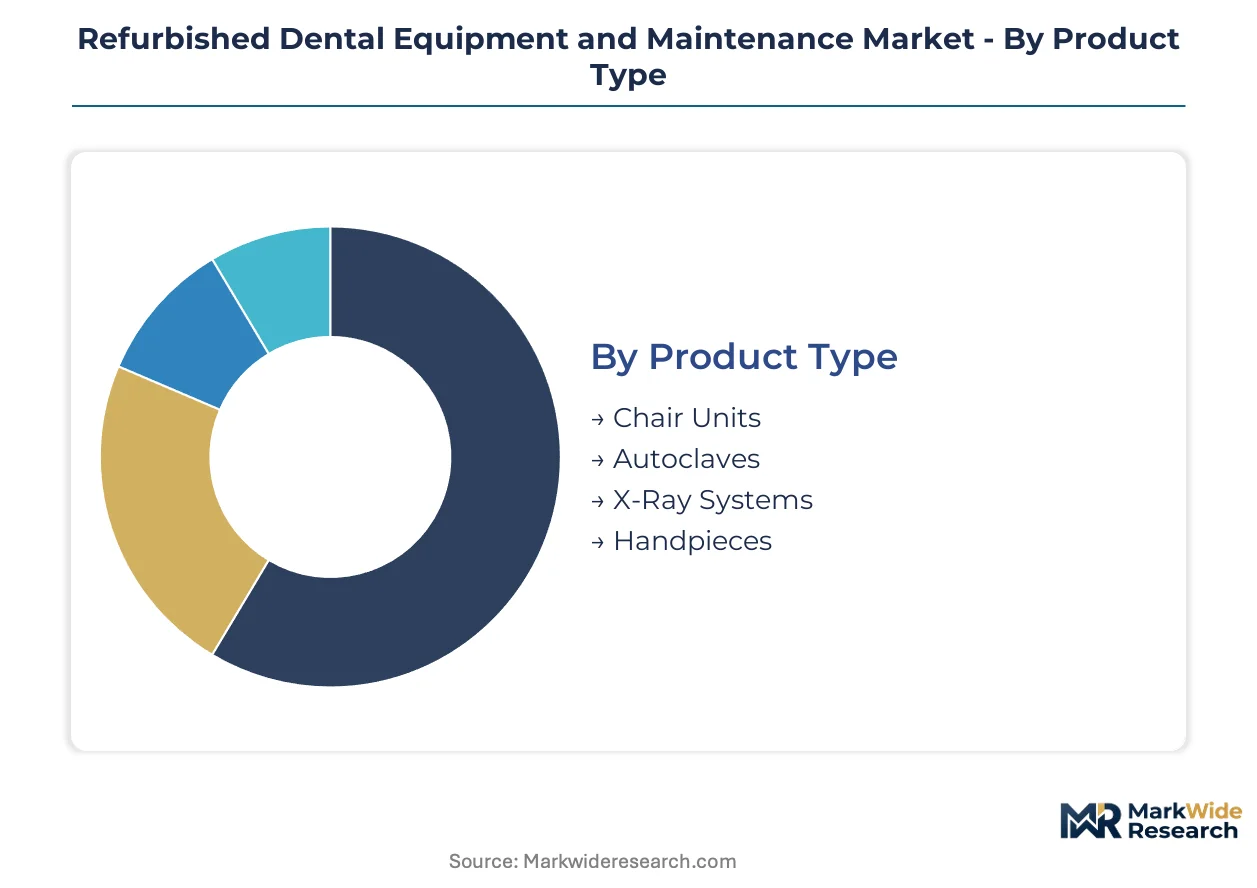
Equipment refurbishment economics vary sharply across product categories and service intensities. Channel access and margin capture depend on matching segment characteristics to buyer procurement maturity.
Product Type:
Channel flows split between dealer-network certified units and direct-to-practice refurbishment shops, with regulatory clearance requirements determining viable pathways.
- Chair Units:Hydraulic base restoration and polymer upholstery replacement consume the largest labor hours per unit. United States multi-location dental service organizations standardize fleet acquisitions around matched-condition chair lots, compressing vendor qualification timelines.
- Autoclaves:Sterilization cycle validation and chamber seal replacement demand ISO 13485-documented traceability. German dental chains prioritize autoclave refurbishment for infection control compliance, where notified body concentration lengthens recertification queues.
- X-Ray Systems:Sensor array calibration and control module software updates dominate restoration workflows.
- Handpieces:Turbine bearing replacement and chuck mechanism restoration serve high-volume, quick-turn refurbishment demand.
Chair units dominate installed base. Autoclaves are where expansion concentrates.
Service Type:
Cost tier stratification separates premium warranty-backed offerings from economy repair-only transactions, with calibration services commanding recurring revenue attachment.
- Repair:Component-level fault isolation and replacement restore functional performance without full recertification. India tier-2 clinic chains prioritize repair-only contracts to minimize capital outlay during expansion phases.
- Calibration:Measurement accuracy verification against manufacturer specifications requires traceable reference standards. United States FDA 510(k) predicate device documentation mandates calibration record retention for imaging systems.
- Installation:Site preparation and utility connection for refurbished equipment demands field technician deployment.
- Parts Replacement:Inventory-intensive polymer and precision metal sourcing faces commodity price volatility.
Repair commands transaction volume. Calibration is where margin expansion concentrates.
End User:
Customer procurement sophistication ranges from individual practice owner discretion to corporate fleet standardization, reshaping sales cycle length and contract structure.
- Dental Clinics:Solo and group practices drive chair unit and imaging system refurbishment demand. United States DSO consolidation shifts procurement authority to headquarters, favoring multi-unit service agreements over spot purchases.
- Hospitals:Centralized biomedical engineering departments impose stringent quality documentation requirements. German hospital procurement mandates EU MDR Article 17 traceability equivalent to new device production.
- Dental Laboratories:CAD/CAM milling system refurbishment demand climbs as restorative workflow automation spreads.
- Dental Schools:Training institution procurement prioritizes functional reliability over cosmetic condition for student practice equipment.
Dental clinics dominate transaction flow. Dental laboratories are where technology upgrade demand concentrates.
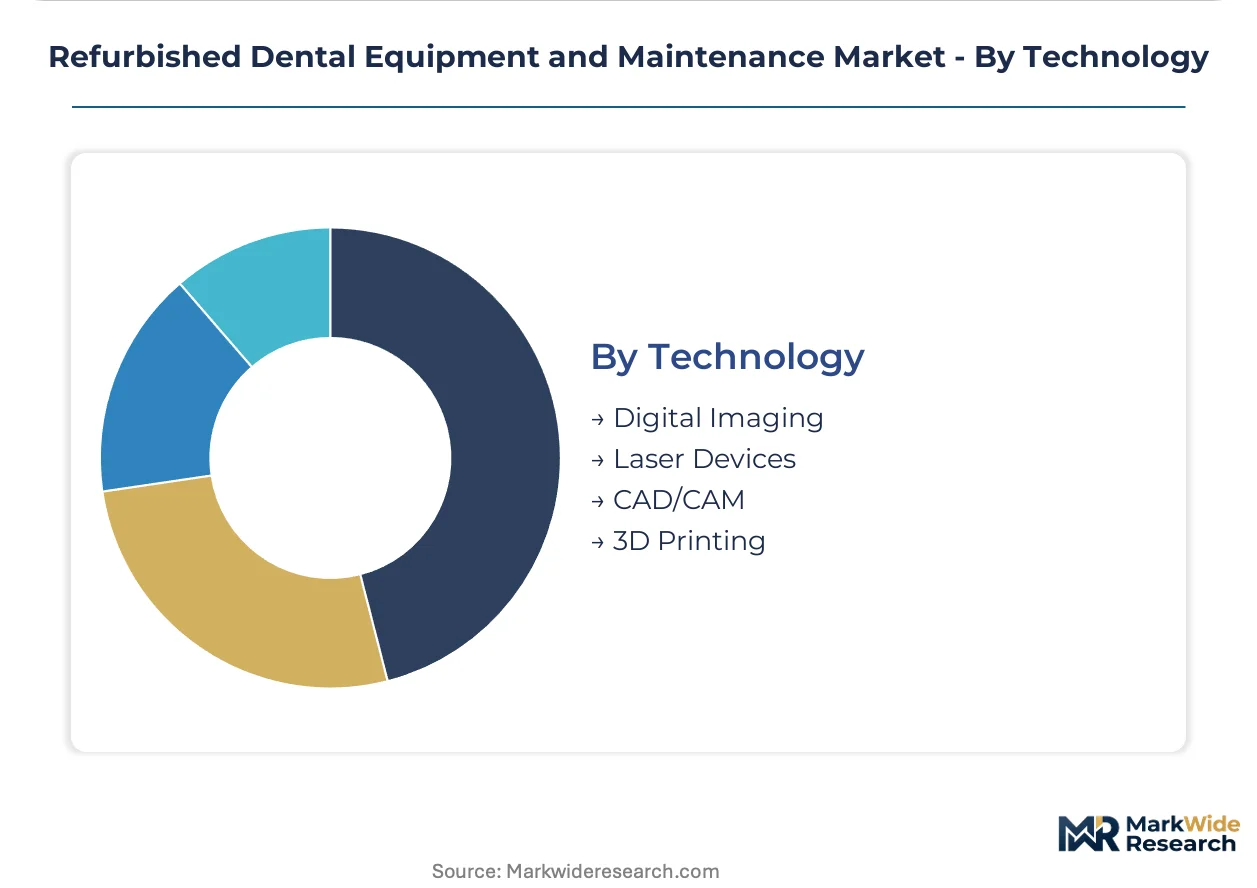
Technology:
Application-specific performance requirements determine refurbishment complexity, with digital modules demanding software backward compatibility that legacy analog equipment avoids.
- Digital Imaging:Sensor degradation pattern analysis and control module firmware updates extend functional service life. United States mid-sized laboratories adopt AI-assisted failure prediction fastest, shifting from calendar-based to condition-triggered maintenance intervals.
- Laser Devices:Optical component alignment and power output calibration restore therapeutic specifications. German refurbishment specialists concentrate laser device recertification due to precision optics expertise concentration.
- CAD/CAM:Milling spindle replacement and CAM software license transfer enable affordable entry into chairside restoration automation.
- 3D Printing:Resin vat replacement and print head refurbishment serve emerging dental laboratory demand.
Digital imaging dominates refurbishment volume. CAD/CAM is where steepest expansion trajectory concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified refurbishment capacity clusters in three national markets where dental clinic expansion intersects with established quality infrastructure. United States multi-location dental service organizations, German hospital procurement systems, and India's tier-2 city chains each present distinct regulatory and commercial entry conditions.
United States
DSO consolidation drives bulk procurement of matched-condition chair unit fleets. FDA 510(k) predicate device documentation requirements filter informal refurbishers from hospital supply chains. Dallas-Fort Worth and Phoenix metropolitan clusters host ISO 13485-accredited facilities serving southwestern state dental chains.
Germany
Hospital biomedical engineering departments mandate EU MDR Article 17 traceability equivalent to new device production. Notified body concentration around TÜV Süd and BSI lengthens recertification queues for smaller operators. Stuttgart and Munich industrial corridors concentrate precision optics expertise for laser device refurbishment.
India
Tier-2 and tier-3 city dental chains lack established refurbishment infrastructure, creating first-mover positioning for quality-certified entrants. CDSCO medical device rules require import license documentation for refurbished imaging systems. Bengaluru and Hyderabad technology corridors attract CAD/CAM milling system refurbishment demand from laboratory clusters.
United Kingdom
NHS procurement frameworks prioritize total cost of ownership calculations that favor certified pre-owned equipment. MHRA vigilance reporting requirements extend to refurbished device adverse events. London and Manchester dental school networks generate training equipment demand prioritizing functional reliability over cosmetic condition.
Japan
PMDA quality management system ordinances require refurbishment facilities to maintain manufacturing-equivalent documentation. Aging dental practitioner demographics slow clinic expansion but sustain replacement demand for digital imaging upgrades. Osaka-Kobe industrial zone hosts specialized handpiece turbine restoration workshops serving domestic and export markets.
Refurbished Dental Equipment and Maintenance Market Competitive Environment
Concentration sits with distribution-integrated refurbishers who channel certified pre-owned units through formal dealer programs. Market structure divides between national distributors with service network scale, regional specialists with component-level expertise, and direct-to-practice refurbishment shops competing on transaction speed. Equipment restoration specialists and technology-validated resellers represent the dominant strategic archetypes. Competitive moves center on quality documentation infrastructure expansion and subscription-based equipment access models that displace capital purchase transactions.
Among distribution-integrated operators, Henry Schein and Patterson Companies occupy positions anchoring formal dealer program volumes. Atlas Resell Management exemplifies the technology-validation archetype through inspection protocol specialization. American Dental Refurbishment represents equipment restoration specialists concentrated in chair unit reconditioning. These three patterns illustrate how market participants align capability investment with buyer procurement maturity segments.
| Leading Market Players |
|---|
| American Dental Refurbishment |
| Capital Dental Equipment |
| Atlas Resell Management |
| A & K Dental Equipment |
| Henry Schein |
| Dental Equipment Liquidators Inc. |
| Collins Dental Equipment Inc. |
| Pre-Owned Dental Inc. |
| Patterson Companies |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) clearance pathways and ISO 13485 certification frameworks gate both supplier qualification and price differentiation in refurbished dental equipment markets, concentrating premium pricing power among accredited facilities while filtering informal operators into economy tiers. This regulatory architecture simultaneously constrains supply base expansion and stratifies buyer access across dental service organizations, solo practitioners, and hospital procurement systems.
Pricing Analysis
FDA 510(k) predicate device documentation dictates the pricing tier structure across refurbished dental equipment markets. Three-tier pricing stratifies across premium warranty-backed offerings, standard certified pre-owned units, and economy repair-only transactions. Price differentiation hinges on certification level and after-sales service bundling, with calibration-inclusive contracts commanding recurring revenue premiums. Pricing pressure stems from volatile polymer and precision metal input costs compressing refurbishment margins. Multi-location dental service organizations exhibit lowest price sensitivity due to standardized fleet procurement, while India tier-2 clinic chains prioritize capital minimization.
Supply Chain Analysis
Container availability fluctuations on trans-Pacific and Asia-Europe trade lanes intermittently disrupt precision component inbound logistics for North American and European refurbishment facilities. Component sourcing concentrates in the United States, Germany, and China, with sensor arrays and control modules drawing from German optics corridors and Chinese electronics manufacturing. Hydraulic systems and polymer upholstery materials rest on petrochemical supply chains vulnerable to commodity volatility. Single-source vulnerability characterizes FDA-registered component suppliers for imaging system recalibration. Distribution runs through formal dealer programs anchored by national distributors alongside direct-to-practice refurbishment shops competing on transaction velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refurbished dental equipment markets sit in early-cycle expansion as subscription-based equipment access models displace capital purchase transactions among acquisition-driven dental service organizations. This structural shift in procurement architecture creates first-mover advantages for quality-certified refurbishment networks.
For Market Incumbents: Compound market position through ISO 13485 accreditation expansion into India tier-2 corridors and backward integration into polymer upholstery manufacturing to capture margin compression from commodity volatility. Channel control through exclusive dealer program agreements defends against technology-validated resellers encroaching on digital imaging segments. Invest in serialized component tracking systems to meet EU MDR Article 17 traceability mandates before notified body queues lengthen further. For New Entrants and Emerging Players: Lead with AI-assisted component failure prediction capabilities to differentiate in digital imaging refurbishment, targeting mid-sized dental laboratories adopting condition-triggered maintenance intervals. India's tier-2 and tier-3 city dental chains present the most penetrable geography given absent established refurbishment infrastructure. Pursue CDSCO import license partnerships with established German or American refurbishment facilities to bypass capital-intensive quality system buildout. For Investors and Strategic Acquirers: EU MDR notified body designation concentration reshapes the acquisition landscape toward ISO 13485-accredited facilities with existing Article 17 compliance infrastructure. Long-term viability centers on refurbishment networks capable of serving hospital procurement systems with manufacturing-equivalent documentation standards. Watch for calibration standard updates from national metrology institutes as inflection indicators for service revenue model disruption.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Accreditation Expansion | EU MDR Article 17 compliance filters low-capability refurbishers from hospital supply chains. |
| Subscription-Based Equipment Access | United States DSOs pilot monthly per-chair fees bundling refurbished units with maintenance services. |
| AI-Assisted Failure Prediction Integration | Machine learning models analyzing sensor degradation patterns fragment fixed preventive maintenance contracts. |
| Serialized Component Tracking Implementation | German refurbishers invest in traceability systems equivalent to new device production records. |
| India Market Entry Partnership | CDSCO import license documentation requirements favor quality-certified foreign facility alliances. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with biomedical engineering directors, dental service organization procurement heads, refurbishment facility quality managers, and notified body auditors; alongside secondary validation through FDA 510(k) device listings, EU MDR Article 17 guidance documents, CDSCO medical device import records, and ISO 13485 accreditation registries. Bottom-up equipment unit flow estimates triangulated against top-down dental clinic expansion projections across the United States, Germany, and India.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning equipment type, service intensity tier, end-user procurement sophistication, and technology generation. CAGRs derived from installed base retirement curves, replacement demand elasticity, and regulatory compliance cost trajectories. Forecast inputs incorporated DSO consolidation pace, CAD/CAM laboratory automation adoption, and polymer commodity price volatility assumptions.
Forecasts assume regulatory continuity in FDA 510(k) predicate device requirements and EU MDR notified body designation patterns; material policy shifts would require re-modeling. Specific risks include biomedical technician certification pipeline constraints, legacy software backward compatibility failures, and single-use device substitution accelerating beyond baseline assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
Dental Imaging Equipment Market
Dental Equipment
Dental 3D Printing Scanner Market
Dental Equipment
Dental CAM Milling Machine Market
Dental Equipment
Japan Dental Equipment Market
Dental Equipment
North America Dental Equipment Market
Dental Equipment
France Dental Equipment Market
Dental Equipment
Germany Dental Equipment Market
Dental Equipment
Dental Engine Market
Dental Equipment
Asia-Pacific Dental Equipment Market
Dental Equipment
Dental Simulator Market
Dental Equipment
Dental Lights Market
Dental Equipment
Dental Equipment and Maintenance Market
Dental Equipment
Refurbished Dental Lab Equipment Market
Dental Equipment
Global Dental Light Curing Equipment Market
Dental Equipment
Digital Dental Equipment Market
Dental Equipment
Brazil Dental Equipment Market