
 Dental Simulator Market | 2026-2036
Dental Simulator Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Simulator Market Intelligence
Market Dynamics
Buyer concentration among dental schools is consolidating as university systems centralize procurement across multiple campuses. Dentsply Sirona leverages its installed base of dental equipment to bundle simulator sales with service contracts. KaVo Dental anchors its position through long-standing relationships with European dental academies. 3Shape A/S differentiates via software integration that connects intraoral scanning hardware to simulation platforms.
Technology and Segmentation
Dental simulators are electromechanical training systems combining haptic feedback interfaces, three-dimensional patient models, and performance analytics software to replicate operative, endodontic, and prosthodontic procedures without biological risk. Phantom head systems retain volume leadership due to lower capital requirements, though virtual reality segments claim faster expansion as hardware costs decline and software fidelity improves. Haptic feedback technology captures premium margins because force-resolution specifications determine accreditation acceptance. Dental schools represent the dominant end-user channel, while research institutions generate concentrated demand for customizable simulation architectures.
Regulatory Environment
FDA oversight applies to software components classified as medical device training tools, while CE marking under the EU MDR governs European commercialization. The Commission on Dental Accreditation in the United States and comparable national bodies in Germany and Japan increasingly mandate documented simulator hours as prerequisites for clinical licensure. Stakeholders must track evolving competency frameworks that determine which technology tiers qualify for curriculum credit.
Market Dynamics
Haptic feedback systems are automating skill assessment protocols that previously required human examiner oversight, compressing accreditation timelines while raising hardware performance thresholds for vendor qualification.
Growth Catalysts
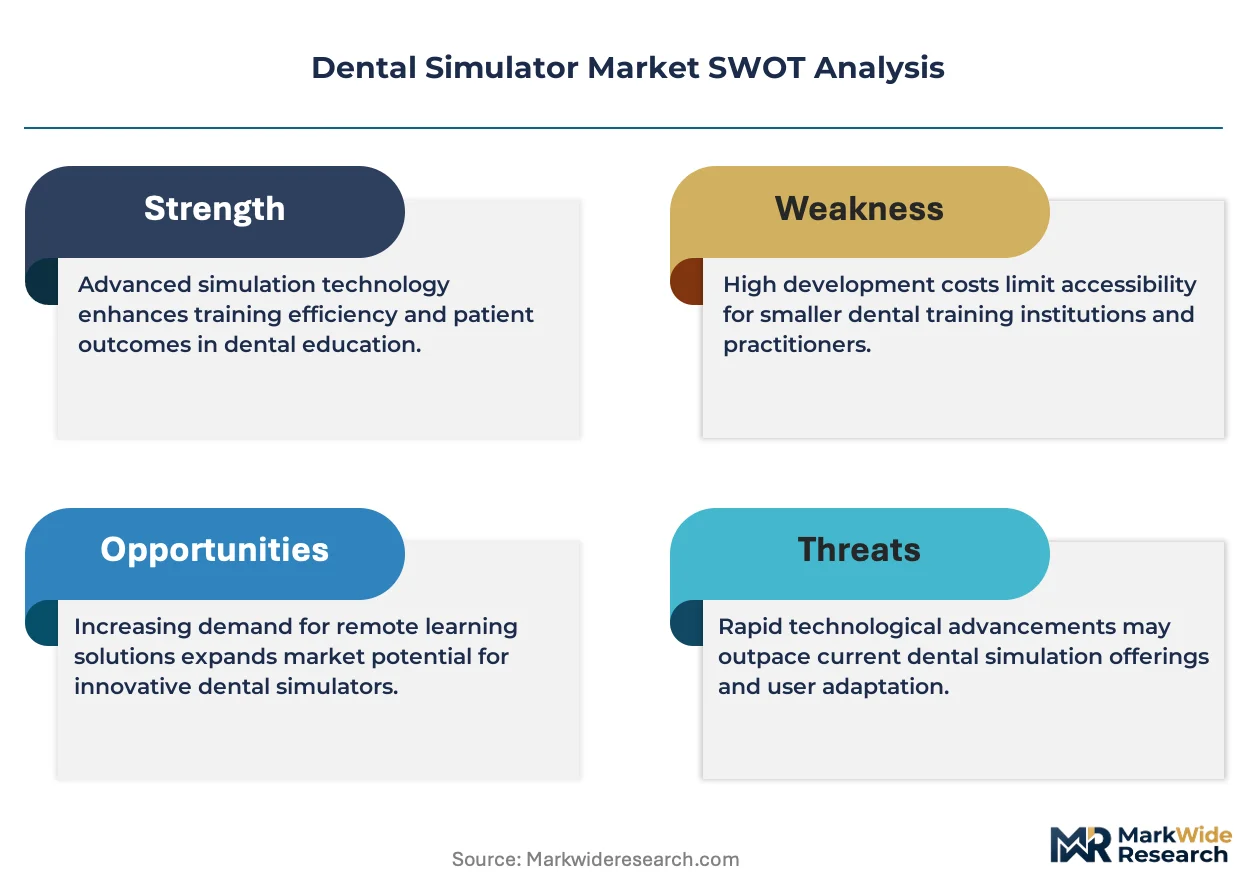
- Commission on Dental Accreditation mandates:Documented simulator hours now function as prerequisites for clinical licensure in the United States, forcing curriculum upgrades across accredited programs.
- Phantom-to-digital transition:Dental schools in Germany and Japan are retiring electromechanical phantom heads in favor of software-defined training architectures that reduce consumable costs.
- Public investment concentration:Sustained government funding for dental education infrastructure in the United States, Germany, and Japan creates predictable procurement cycles for capital equipment.
Market Restraints
- Force-resolution hardware costs:Haptic interfaces meeting accreditation specifications require precision electromechanical components whose input costs resist scale economies.
- CE marking friction under EU MDR:Reclassification of training software as medical device training tools extends regulatory timelines for European commercialization.
- Phantom head substitution:Lower-capital electromechanical simulators retain volume share in price-sensitive programs, constraining premium segment expansion.
Strategic Opportunities
- Research institution architectures:Customizable simulation platforms for endodontic and prosthodontic research command concentrated demand from university hospitals with dedicated funding streams.
- Intraoral scanning convergence:Integration between simulation software and chairside scanning hardware creates bundled value propositions for integrated dental systems.
- Service contract unbundling:After-sales support and performance analytics represent recurring revenue channels distinct from capital equipment sales.
Industry Challenges
- Haptic calibration expertise:Force-resolution specification maintenance requires specialized technical personnel scarce in dental school IT departments.
- Legacy phantom head integration:Hybrid curricula combining electromechanical and digital systems create operational complexity in program administration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Simulator Market |
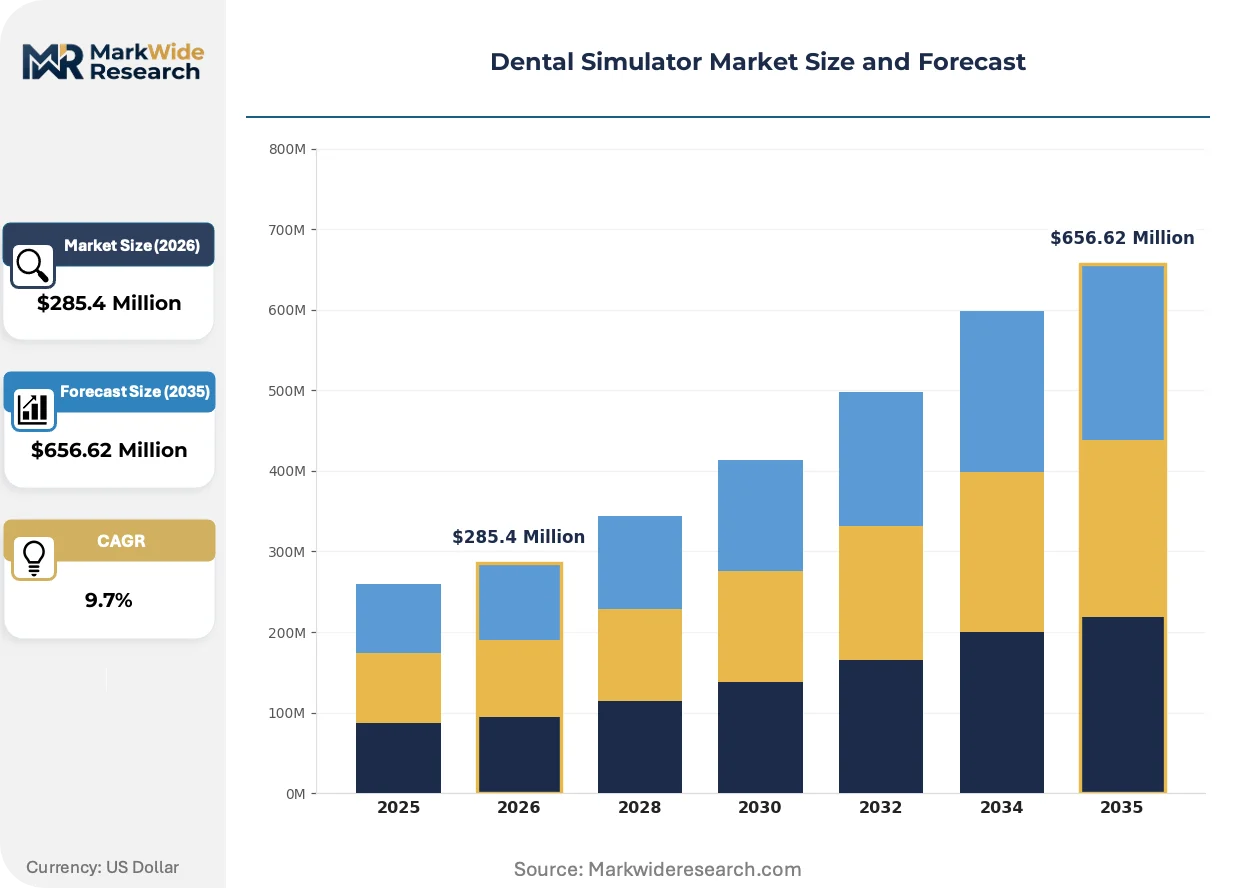
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $656.62 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virtual Reality, Augmented Reality, Phantom Head, Dental Chair Simulator End User: Dental Schools, Training Centers, Dental Clinics, Research Institutions Application: Skill Assessment, Procedure Simulation, Patient Interaction, Curriculum Development Technology: 3D Modeling, Haptic Feedback, Software Integration, Multimedia Interface |
| Companies Covered | Planmeca Oy, Navadha Enterprises, Dentsply Sirona, 3Shape A/S, VOXEL-MAN, KaVo Dental, HRV Simulation, Image Navigation, Nissin Dental Products Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Simulator Market Strategic Shifts & Innovations
Software-defined training architectures are compressing the hardware replacement cycle while elevating performance analytics to core curriculum components. Three forces are restructuring competitive positioning.
Force-feedback algorithms are automating real-time error detection during operative procedures, replacing delayed instructor review with immediate tactile correction. Advanced programs in Germany and Japan are adopting these systems at accelerated pace. This compression of feedback loops is automating competency documentation for accreditation bodies.
EU MDR CE marking requirements for medical device training tools are extending software validation timelines and elevating quality management system burdens. European dental academies now demand documented conformity assessment procedures from vendors. Phantom head manufacturers with legacy hardware portfolios face the steepest compliance reconfiguration.
University system procurement centralization is consolidating buyer power across multi-campus dental schools, displacing decentralized department-level purchasing. Bundled service contracts are replacing discrete equipment transactions in the United States. This concentration is most visible in public university systems with standardized curriculum mandates.
Dental Simulator Market Segmentation
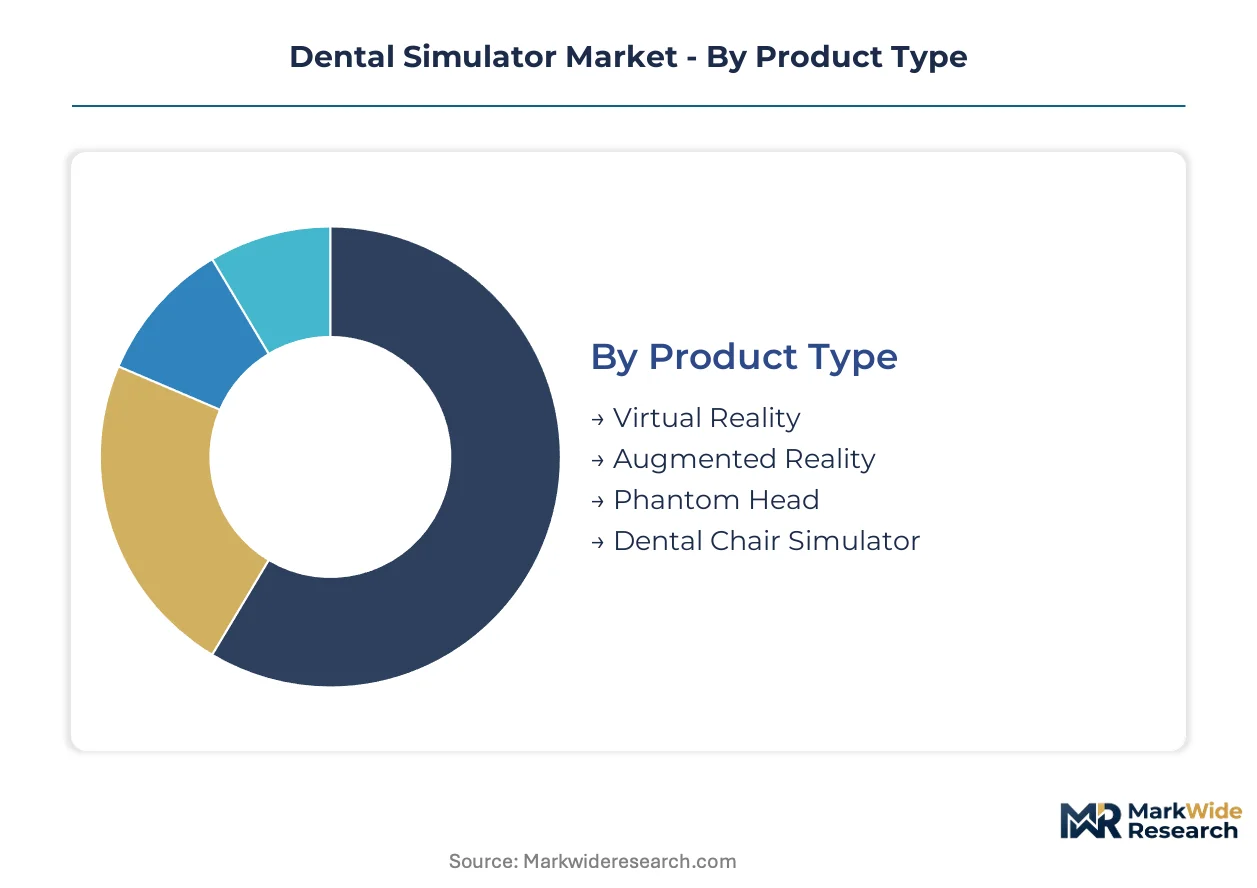
Segmentation in dental simulators reveals how procurement priorities diverge between cost-constrained institutions and premium-positioned academies. Understanding these splits clarifies which technology tiers capture curriculum mandates versus discretionary upgrades.
Product Type:
Replacement cycles vary sharply across simulator architectures, with phantom head systems facing accelerated retirement in favor of software-defined alternatives.
- Virtual Reality:Head-mounted displays with six-degrees-of-freedom tracking immerse trainees in anatomically accurate oral cavities. Demand clusters in German and Japanese dental academies where force-feedback gloves meet Commission on Dental Accreditation specifications for operative procedure documentation.
- Augmented Reality:Optical see-through headsets overlay digital tooth models onto physical manikins, blending tactile feedback with visual guidance. United States dental schools with hybrid curricula favor this intermediate tier as phantom head infrastructure ages out.
- Phantom Head:Electromechanical manikins with pneumatic jaw mechanisms and replaceable teeth remain the volume leader due to lower capital thresholds.
- Dental Chair Simulator:Integrated units replicating patient positioning, lighting, and instrument delivery occupy dedicated training bays in research-intensive institutions.
Volume placements concentrate in Phantom Head systems; the faster expansion belongs to Virtual Reality as hardware costs decline and software fidelity improves.
End User:
Buyer sophistication determines specification requirements, with research institutions demanding open-architecture customization unavailable to standard academic programs.
- Dental Schools:Accredited programs requiring documented simulator hours for licensure eligibility drive the core demand base. Procurement centralization across United States public university systems is consolidating vendor relationships.
- Training Centers:Commercial continuing education providers prioritize rapid patient throughput over deep skill assessment, favoring lower-cost multimedia interfaces.
- Dental Clinics:Private practices integrating chairside scanning hardware seek simulation modules for staff calibration on new equipment workflows.
- Research Institutions:University hospitals with dedicated National Institutes of Health or Japan Agency for Medical Research and Development funding command premium pricing for customizable endodontic and prosthodontic architectures.
Procurement scale favors Dental Schools; Research Institutions generate the highest margin per placement.
Application:
Curriculum integration depth varies by application, with skill assessment modules facing the steepest performance thresholds for accreditation acceptance.
- Skill Assessment:Automated scoring algorithms evaluating hand steadiness, tissue respect, and procedural sequence now satisfy Commission on Dental Accreditation documentation requirements in the United States.
- Procedure Simulation:Operative, endodontic, and prosthodontic modules replicate cavity preparation, root canal negotiation, and crown margin design without biological risk.
- Patient Interaction:Communication training scenarios address anxiety management, informed consent, and treatment plan explanation.
- Curriculum Development:Authoring tools allowing faculty to construct custom case libraries attract European dental academies adapting to EU MDR-aligned competency frameworks.
Deployment breadth centers on Procedure Simulation; Skill Assessment is climbing the fastest as automation replaces human examiner oversight.
Technology:
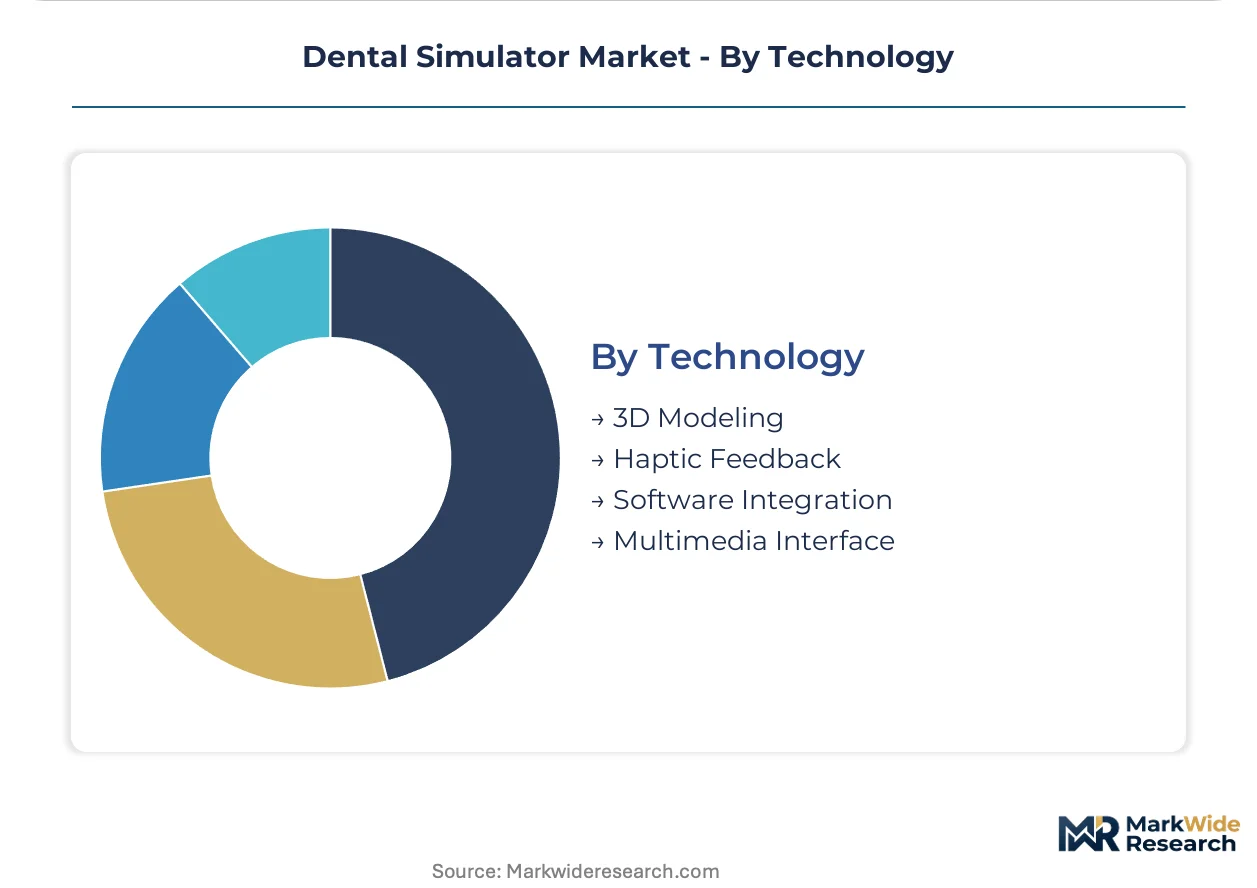
Force-resolution specifications create the widest margin dispersion, with haptic feedback components capturing premium positioning against commoditized multimedia layers.
- 3D Modeling:Volumetric patient reconstructions from cone-beam computed tomography datasets enable anatomically variant case libraries. Japanese programs lead adoption for implant planning simulation.
- Haptic Feedback:Electromechanical interfaces with sub-millimeter position sensing and force ranges replicating enamel, dentin, and periodontal ligament resistance claim the steepest price points. FDA classification as medical device training tools elevates validation burdens.
- Software Integration:Application programming interfaces connecting simulation platforms to intraoral scanners and practice management systems enable bundled value propositions.
- Multimedia Interface:Video-based instruction and two-dimensional case presentations occupy the entry tier with minimal hardware requirements.
Revenue concentration sits with Haptic Feedback; Software Integration is expanding most quickly as open-architecture demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration clusters in three national markets where public funding sustains predictable capital equipment cycles. Dental schools in the United States, Germany, and Japan account for the dominant share of simulator placements, driven by accreditation mandates and sustained government investment in clinical education infrastructure.
United States
The Commission on Dental Accreditation mandates documented simulator hours as prerequisites for clinical licensure, forcing curriculum upgrades across accredited programs. FDA oversight applies to software components classified as medical device training tools, elevating validation requirements for haptic feedback systems. University system procurement centralization across public campuses in California, Texas, and the Northeast Corridor is consolidating vendor relationships and displacing department-level purchasing.
Germany
Dental academies in Bavaria and North Rhine-Westphalia are retiring electromechanical phantom heads in favor of software-defined training architectures that reduce consumable costs. CE marking under the EU MDR governs commercialization, extending regulatory timelines for training software reclassified as medical device training tools. The KBA and national accreditation bodies increasingly specify force-resolution thresholds for curriculum credit eligibility.
Japan
The Japan Agency for Medical Research and Development funds university hospitals with dedicated streams for customizable endodontic and prosthodontic simulation architectures. METI standards and PMDA guidance shape hardware validation protocols for haptic interfaces used in implant planning simulation. Programs in the Kanto and Kansai regions lead adoption of volumetric patient reconstructions from cone-beam computed tomography datasets.
United Kingdom
Dental schools in London and the Southeast are expanding simulator-based curricula as the General Dental Council tightens clinical competency documentation requirements. MHRA oversight aligns with EU MDR transitional provisions for training software classification. Research-intensive institutions in Scotland and the Midlands generate concentrated demand for open-architecture platforms supporting custom case library development.
South Korea
The Seoul Capital Area anchors domestic demand as dental education infrastructure receives sustained investment from the Ministry of Health and Welfare. MFDS regulations govern software validation for haptic training systems used in operative procedure documentation. University hospitals in Busan-Ulsan are adopting force-feedback algorithms for real-time error detection during competency assessment.
Dental Simulator Market Key Industry Players
United States and German producers anchor the premium tier; Japanese and Korean specialists hold positions in hardware component supply. The vendor base organizes into three strategic archetypes: diversified dental equipment conglomerates bundling simulators with service ecosystems, pure-play simulation software developers integrating with chairside hardware, and precision electromechanical component suppliers capturing margin on force-resolution specifications. Competitive moves concentrate on intraoral scanning convergence and service contract unbundling as recurring revenue channels distinct from capital sales.
Within the diversified equipment tier, Dentsply Sirona and KaVo Dental exemplify archetypes leveraging installed base relationships and long-standing academy partnerships respectively. Among software-focused developers, 3Shape A/S occupies a position representing integration between simulation platforms and intraoral scanning hardware. These three companies illustrate how competitive positioning splits between hardware bundling strategies and open-architecture software differentiation.
| Leading Market Players |
|---|
| Planmeca Oy |
| Navadha Enterprises |
| Dentsply Sirona |
| 3Shape A/S |
| VOXEL-MAN |
| KaVo Dental |
| HRV Simulation |
| Image Navigation |
| Nissin Dental Products Inc. |
| Others |
Cost & Logistics Intelligence
Family-owned precision electromechanical component suppliers in Japan and Germany anchor haptic feedback manufacturing, creating pricing discipline through captive force-resolution expertise and limited vendor qualification slots for FDA-cleared medical device training tools.
Pricing Analysis
Phantom head systems capture volume placements at economy tiers while haptic feedback platforms command premium margins. Three-tier pricing structure across premium, standard, and economy levels stratifies by force-resolution specification and accreditation acceptance. Cost compression in the phantom head tier intensifies as German and Japanese dental schools accelerate digital transitions. Training centers exhibit the highest price sensitivity; research institutions with dedicated government funding streams show the least.
Supply Chain Analysis
CE marking and FDA 510(k) clearance requirements gate qualified suppliers, concentrating force-feedback actuator manufacturing in Japan, Germany, and the United States. Precision load cells, sub-millimeter position sensors, and medical-grade polymers constitute critical input dependencies. Single-source vulnerability runs through Japanese suppliers of high-fidelity haptic motors. Distribution runs through direct vendor relationships with dental school procurement offices and university system central purchasing authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental simulator market sits in a technology-transition phase as haptic feedback architectures displace electromechanical phantom heads across accredited curricula.
For Market Incumbents: Extend software integration capabilities to lock in intraoral scanning convergence before pure-play developers capture chairside hardware relationships. Deepen backward integration into force-resolution actuator supply to defend margin position against precision component cost inflation. Commission on Dental Accreditation documentation requirements create switching costs for installed-base customers. For New Entrants and Emerging Players: Begin with open-architecture simulation platforms for research institutions in the United Kingdom and South Korea where customizable endodontic and prosthodontic modules face limited incumbent specialization. Target university hospitals with dedicated national research agency funding as the most penetrable buyer segment. Pursue API-first development strategies that enable rapid integration with existing chairside scanning ecosystems. For Investors and Strategic Acquirers: Distressed-cycle entries favor simulation software specialists with established FDA or CE marking dossiers in Germany and Japan where regulatory reclassification under EU MDR has extended validation timelines and strained smaller vendor balance sheets. Long-term viability hinges on recurring service contract revenue streams decoupled from capital equipment cyclicality. Watch for Commission on Dental Accreditation expansion of documented simulator hour requirements as the signal indicating accelerated replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Haptic Feedback Hardware Certification | FDA 510(k) clearance for force-resolution interfaces opens Commission on Dental Accreditation-mandated curriculum placements. |
| Intraoral Scanning Platform Integration | API connectivity to 3Shape and Dentsply Sirona chairside systems creates bundled value propositions for dental schools. |
| Service Contract Unbundling | Recurring performance analytics and calibration support revenue reduces dependence on lumpy capital equipment cycles. |
| Research Institution Customization | Open-architecture platforms for NIH and Japan Agency-funded university hospitals capture premium-margin placements. |
| EU MDR Compliance Reconfiguration | CE marking pathway for software-defined training tools defends European market access against regulatory exclusion. |
Research Approach
Document review covered FDA 510(k) databases, EU MDR notified body guidance, and Commission on Dental Accreditation competency frameworks, complemented by interviews with dental school procurement directors, haptic hardware engineering leads, biomedical simulation researchers, and GPO contract managers. Secondary validation drew from hospital capital equipment expenditure records, dental academy curriculum disclosures, and regulatory filing repositories. Bottom-up placement data triangulated against top-down market sizing from public university system budget allocations.
Unit and value outputs across product type, technology tier, end-user channel, and geographic adoption pattern were modeled through the projection horizon. CAGRs were derived from segmented growth rate analysis incorporating accreditation mandate expansion timelines, hardware cost decline curves, and public funding commitment trajectories. Force-resolution specification evolution and phantom head retirement rates served as primary demand-side forecast inputs.
Accreditation body mandate reversals, haptic component supply disruptions, and EU MDR enforcement intensity shifts are the dominant revision risks to modeled outcomes. A model refresh is warranted upon material change in Commission on Dental Accreditation simulator hour requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
Dental Elevator and Luxator Market
Dental Equipment
Dental Equipment Market
Dental Equipment
Dental Dust Collector Market
Dental Equipment
Europe Dental Equipment Market
Dental Equipment
Brazil Dental Equipment Market
Dental Equipment
Dental Equipment and Maintenance Market
Dental Equipment
Ultrasonic Dental Scalers Market
Dental Equipment
Dental Radiology Equipment Market
Dental Equipment
North America Dental Equipment Market
Dental Equipment
Dental Diagnostic and Surgical Equipment Market
Dental Equipment
Asia-Pacific Dental Equipment Market
Dental Equipment
Global Dental Light Curing Equipment Market
Dental Equipment
Germany Dental Equipment Market
Dental Equipment
France Dental Equipment Market
Dental Equipment
Dental Lights Market
Dental Equipment
Global Dental Milling Machine Market