
 Germany Dental Equipment Market | 2026-2036
Germany Dental Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Dental Equipment Market Foresight
Aftermarket service revenue is reshaping profit dynamics across the Germany Dental Equipment Market. Dentsply Sirona leverages its extensive technician network to capture recurring maintenance contracts. KaVo Dental GmbH anchors its competitive stance through precision-engineered handpiece refurbishment programs. Straumann Group differentiates by controlling implant-related digital workflow services from scanning to final restoration.
Dental equipment encompasses electromechanical and digital systems engineered for oral diagnosis, treatment, and laboratory fabrication, typically operating at precision tolerances below 50 micrometers for implant components and requiring validated sterilization cycles at 134 degrees Celsius. These systems serve restorative, orthodontic, and surgical applications across clinical and laboratory environments. Imaging systems command established replacement cycles as practices transition from panoramic to cone beam computed tomography platforms. CAD/CAM systems represent the fastest-expanding technology segment as chairside milling and 3D printing compress traditional laboratory turnaround times. Dental implants sustain premium positioning through surface modification technologies and guided surgery integration.
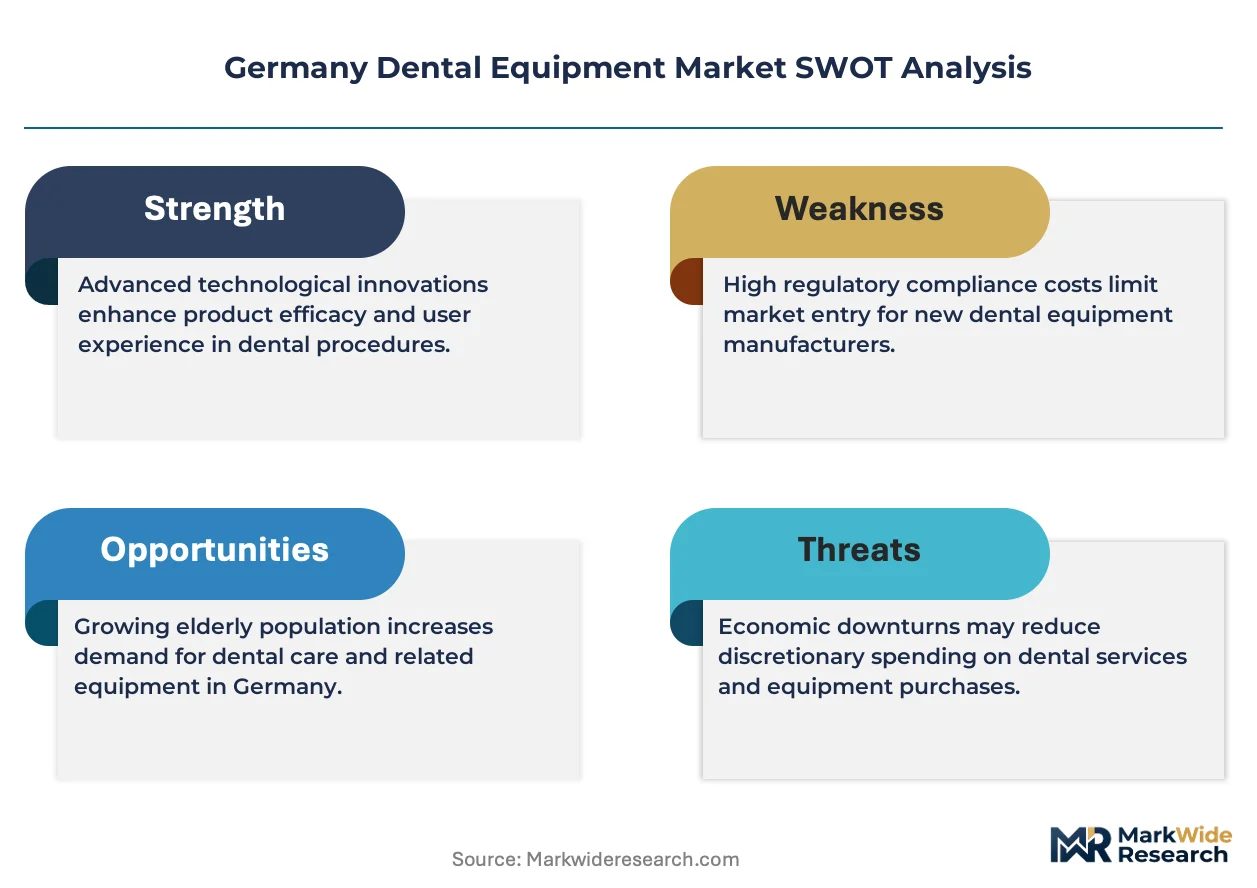
Germany's Federal Institute for Drugs and Medical Devices enforces Medical Device Regulation compliance, while the EU MDR framework mandates enhanced clinical evidence and post-market surveillance for active implantable devices. These standards elevate barriers for non-compliant manufacturers and steer procurement toward validated suppliers. Stakeholders must monitor reimbursement rate negotiations between statutory health insurers and dental associations, as these directly influence clinic capital expenditure cycles and technology refresh timelines.
Market Dynamics
Chairside CAD/CAM milling systems are compressing laboratory turnaround cycles from weeks to hours across Bavarian and Baden-Württemberg dental networks. This compression is forcing equipment suppliers to reconfigure service architectures around real-time digital workflow support rather than traditional hardware maintenance.
Growth Catalysts
- EU MDR implementation:Enhanced clinical evidence requirements for active implantable devices elevate procurement standards toward validated German suppliers with established quality management systems.
- Statutory health insurer reimbursement negotiations:Favorable rate settlements between KZBV and GKV-Spitzenverband accelerate capital expenditure cycles for digital imaging upgrades in university-affiliated hospitals.
- Bavaria private clinic concentration:Dense networks of independent practices in Munich and Nuremberg create localized demand clusters for cone beam computed tomography platforms.
Market Restraints
- Premium component import dependency:Precision optical sensors and ceramic milling burs originate from Swiss and Japanese suppliers, exposing German distributors to currency volatility and lead time extension.
- EU MDR compliance costs:Small and mid-sized equipment manufacturers face disproportionate burden from clinical evaluation requirements and notified body capacity constraints.
- Surface modification patent thickets:Implant manufacturers navigate complex licensing landscapes around hydroxyapatite coating technologies controlled by US and Swiss IP holders.
Strategic Opportunities
- East German dental network modernization:Saxony and Thuringia practices operate aging panoramic systems with replacement cycles compressed by EU MDR grandfathering deadlines.
- AI-enabled radiographic analysis:Machine learning algorithms for caries detection and periodontal assessment integrate with existing sensor infrastructure without full platform replacement.
- Subscription-based CAD/CAM service models:Per-procedure billing structures reduce upfront capital barriers for solo practitioners in rural North Rhine-Westphalia.
Industry Challenges
- Digital workflow technician scarcity:Laboratory fabrication specialists with simultaneous competence in conventional casting and chairside milling software command wage premiums exceeding 40% above regional medians.
- Legacy sterilizer integration:Autoclave validation protocols for 134-degree Celsius cycles require firmware modifications incompatible with pre-2018 control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Dental Equipment Market |
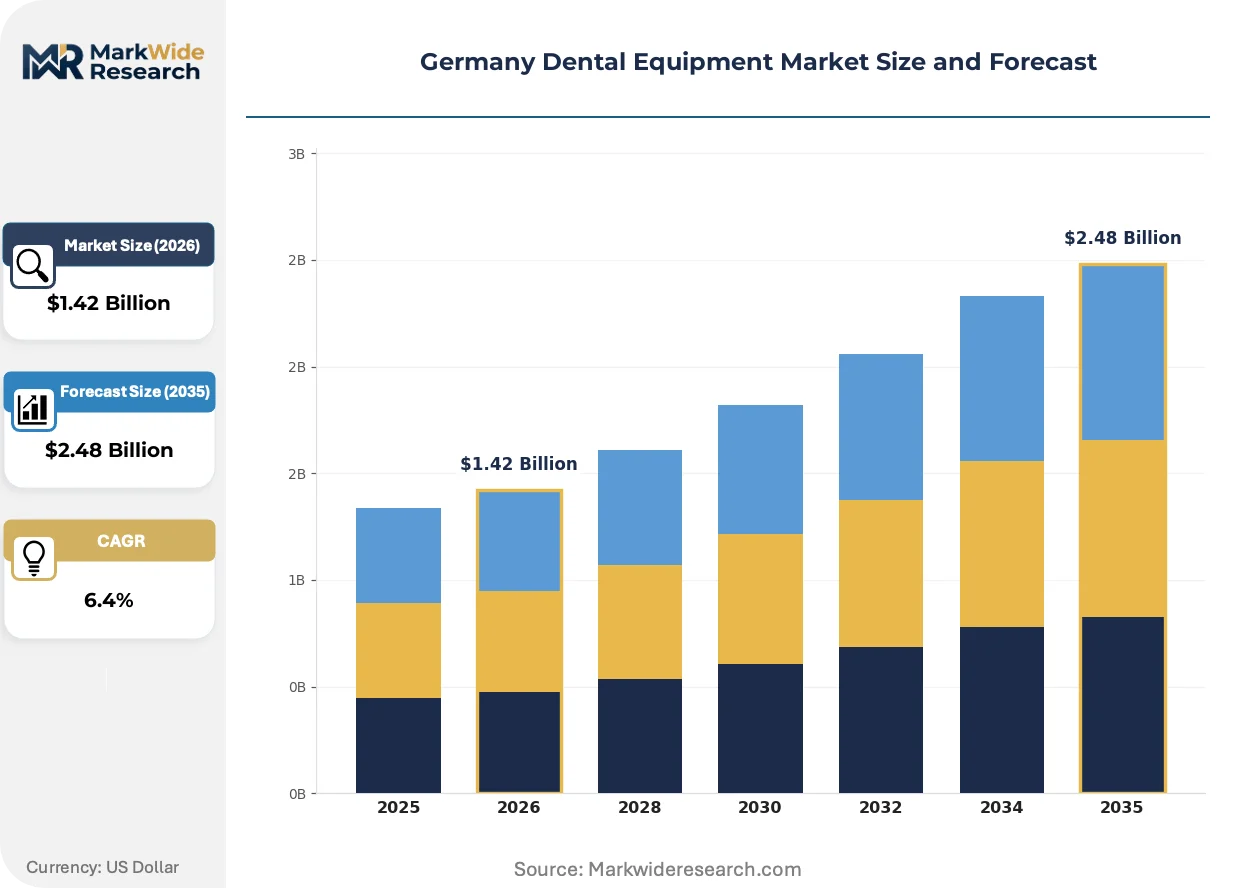
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dental Implants, Orthodontic Appliances, Dental Lasers, Imaging Systems, Sterilization Equipment Technology: CAD/CAM Systems, Digital Radiography, Cone Beam Computed Tomography, 3D Printing, Intraoral Scanners Application: Restorative Dentistry, Pediatric Orthodontics, Periodontal Therapy, Cosmetic Dentistry, Prosthodontics End User: Dental Clinics, Oral Surgery Centers, Specialty Dental Hospitals, Dental Laboratories, Academic Institutions |
| Companies Covered | Dürr Dental SE, Nobel Biocare Services, Dentsply Sirona, Carestream Dental Germany GmbH, Planmeca, KaVo Dental GmbH, 3M Deutschland GmbH, GC Corporation, Straumann Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Dental Equipment Market Shifts & Advancements
Workflow convergence between clinical diagnosis and laboratory fabrication is eliminating historical boundaries between chairside and off-site production. This integration demands equipment architectures that synchronize scanning, design, and manufacturing across distributed locations.
Intraoral scanning technology is hybridizing photogrammetric and confocal microscopy principles to capture sub-10-micrometer surface detail without powder application. Private clinics in Berlin and Hamburg adopt these systems at replacement cycles of 4-5 years versus 8-10 years for conventional impressions. The technology is hybridizing restorative and orthodontic workflows into unified digital patient records that traverse multiple treatment modalities.
Germany's Federal Institute for Drugs and Medical Devices enforces Medical Device Regulation post-market surveillance requirements that mandate systematic collection of implant performance data. This obligation compels manufacturers to embed connectivity modules in surgical motors and milling units for automated adverse event reporting. Implant component suppliers face the most acute compliance burden as they must demonstrate traceability from raw material batch to final restoration.
After-sales service unbundling is separating hardware maintenance from software support and consumable replenishment. Dental clinics in university hospital networks now contract independent technicians for handpiece refurbishment while retaining manufacturer relationships for digital workflow licenses. This fragmentation is most pronounced in North Rhine-Westphalia where dense supplier competition enables multi-vendor service architectures.
Germany Dental Equipment Market Segmentation
Segmentation in Germany's dental equipment landscape reveals divergent service intensity patterns across product categories. Aftermarket revenue potential varies dramatically between implant systems requiring lifelong traceability and sterilization equipment with predictable replacement cycles.
Product Type:
After-sales-service intensity peaks with implant platforms and imaging systems, where technical support contracts generate recurring revenue streams exceeding original equipment margins.
- Dental Implants:Titanium and zirconium oxide fixtures with surface-modified osseointegration layers demand surgical motor calibration and guided surgery software maintenance. University-affiliated hospitals in North Rhine-Westphalia concentrate procurement around platforms with embedded connectivity for EU MDR adverse event reporting.
- Imaging Systems:Panoramic and cone beam computed tomography platforms operate at precision tolerances requiring annual detector calibration and tube replacement cycles. Bavarian private clinics in Munich and Nuremberg drive demand for upgrade pathways from 2D panoramic to 3D volumetric imaging.
- Orthodontic Appliances:Clear aligner production systems and fixed appliance fabrication equipment serve Berlin and Hamburg orthodontic networks.
- Dental Lasers:Erbium and diode wavelength systems for soft and hard tissue applications require fiber optic replacement protocols.
- Sterilization Equipment:Autoclave units validated for 134-degree Celsius cycles with firmware-dependent pressure monitoring.
By volume, Sterilization Equipment leads. By growth pace, Dental Implants is ahead.
Technology:
Technology segmentation tracks capital intensity gradients, with chairside systems commanding premium pricing against centralized laboratory infrastructure.
- CAD/CAM Systems:Chairside milling units and design software compress laboratory turnaround from weeks to hours. Baden-Württemberg dental networks prioritize subscription-based service models reducing upfront capital barriers for solo practitioners.
- Intraoral Scanners:Photogrammetric and confocal microscopy-based devices capture sub-10-micrometer surface detail without powder application. Berlin and Hamburg clinics adopt these at compressed 4-5 year replacement cycles versus 8-10 years for conventional impressions.
- Cone Beam Computed Tomography:Volumetric imaging platforms with limited field-of-view options for endodontic and implant planning.
- Digital Radiography:Sensor-based intraoral and extraoral systems with AI-enabled caries detection integration.
- 3D Printing:Photopolymer and resin-based additive manufacturing for surgical guides and provisional restorations.
By installed base, Digital Radiography dominates. By expansion trajectory, CAD/CAM Systems is climbing the fastest.
Application:
Application segmentation aligns with reimbursement rate differentials between statutory health insurance and private payment pathways.
- Restorative Dentistry:Crown, bridge, and implant-supported prosthesis fabrication combining chairside and laboratory workflows. Demand concentrates in Bavaria and Baden-Württemberg where private clinic density supports digital investment.
- Cosmetic Dentistry:Veneer, whitening, and aesthetic alignment procedures with limited statutory coverage. North Rhine-Westphalia's affluent suburban practices drive premium equipment procurement.
- Pediatric Orthodontics:Early intervention appliances and growth modification systems.
- Periodontal Therapy:Surgical and non-surgical treatment platforms with regenerative component integration.
- Prosthodontics:Complex rehabilitation cases requiring multi-disciplinary coordination between clinics and laboratories.
By procedure volume, Restorative Dentistry leads. By margin per case, Cosmetic Dentistry is gaining share fastest.
End User:
End user segmentation reflects procurement authority concentration, with hospital networks leveraging volume aggregation against fragmented independent practice purchasing.
- Dental Clinics:Independent and group practices across Germany's 16 federal states with varying digital maturity. East German networks in Saxony and Thuringia operate aging panoramic systems with replacement cycles compressed by EU MDR grandfathering deadlines.
- Academic Institutions:University-affiliated dental hospitals in Berlin, North Rhine-Westphalia, and Bavaria with research-driven procurement prioritizing connectivity-enabled platforms for post-market surveillance data collection.
- Oral Surgery Centers:Specialized facilities with implant and orthognathic surgery focus.
- Specialty Dental Hospitals:Concentrated expertise centers for complex rehabilitation cases.
- Dental Laboratories:Independent and clinic-captive fabrication facilities navigating technician scarcity for simultaneous conventional casting and chairside milling competence.
By unit deployment, Dental Clinics lead. By technology sophistication, Academic Institutions is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across German dental networks. University-affiliated hospitals in North Rhine-Westphalia and Berlin prioritize connectivity-enabled platforms regardless of cost, while solo practitioners in rural Saxony and Thuringia delay replacement cycles until EU MDR grandfathering deadlines force action.
North Rhine-Westphalia
University hospitals in Cologne and Düsseldorf drive demand for implant platforms with embedded EU MDR adverse event reporting modules. The Federal Institute for Drugs and Medical Devices enforces post-market surveillance mandates that steer procurement toward validated suppliers. Dense supplier competition around the Ruhr Valley enables multi-vendor service architectures unbundling hardware maintenance from software licenses.
Bavaria
Private clinic networks in Munich and Nuremberg compress replacement cycles for intraoral scanners to 4-5 years versus 8-10 years nationally. KZBV reimbursement negotiations with statutory health insurers influence capital expenditure timing across independent practices. The concentration of affluent suburban practices supports premium cone beam computed tomography procurement.
Baden-Württemberg
Solo practitioners in Stuttgart and Karlsruhe adopt subscription-based CAD/CAM service models to reduce upfront capital barriers. The region's statutory health insurer rate settlements accelerate digital imaging upgrades relative to eastern federal states. Dental laboratories in the Neckar Valley navigate technician scarcity for simultaneous conventional casting and chairside milling competence.
Berlin-Brandenburg
Academic institutions prioritize research-driven procurement of connectivity-enabled platforms for systematic implant performance data collection. The EU MDR framework mandates enhanced clinical evidence for active implantable devices, elevating barriers for non-compliant manufacturers. Charité-affiliated dental hospitals anchor demand for AI-enabled radiographic analysis integration.
Saxony and Thuringia
East German practices operate aging panoramic systems with replacement cycles compressed by EU MDR grandfathering deadlines. The Federal Institute for Drugs and Medical Devices' validation protocols for 134-degree Celsius sterilization cycles expose pre-2018 control systems to firmware incompatibility. Leipzig and Dresden dental networks represent modernization opportunities as digital maturity lags western benchmarks.
Germany Dental Equipment Market Competitive Landscape
Capability concentration sits with specialized implant and imaging platform developers; scale advantage sits with diversified dental technology conglomerates. The market structures around three tiers: integrated workflow providers controlling end-to-end digital pathways, component specialists dominating precision-manufactured niches, and regional distributors capturing aftermarket service revenue. Dominant competitive moves include strategic partnerships compressing laboratory-clinic workflow boundaries and technology licensing agreements navigating surface modification patent thickets.
Among Germany-based fabricators, Dürr Dental SE and KaVo Dental GmbH occupy positions within the precision-engineered equipment tier, while Dentsply Sirona exemplifies the integrated workflow provider archetype. These entities represent distinct strategic postures: the German GmbH-structured manufacturers anchor regional service networks, while the broader group entity controls multi-point digital ecosystems spanning scanning through restoration.
| Leading Market Players |
|---|
| Dürr Dental SE |
| Nobel Biocare Services |
| Dentsply Sirona |
| Carestream Dental Germany GmbH |
| Planmeca |
| KaVo Dental GmbH |
| 3M Deutschland GmbH |
| GC Corporation |
| Straumann Group |
| Others |
Supply & Pricing Matrix
Bavarian precision manufacturing clusters around Munich anchor European dental component supply, with their capacity utilization rates directly transmitting into downstream pricing power for cone beam computed tomography platforms and chairside milling units. This geographic concentration enables incumbent suppliers to maintain premium positioning through controlled availability of validated replacement parts.
Pricing Analysis
Extended service contracts and per-procedure software licensing now generate lifetime value exceeding original equipment margins across German dental networks. Three-tier pricing structure across premium, standard, and economy levels stratifies by EU MDR certification grade and after-sales bundling intensity. Cost compression in entry-level imaging tiers is intensifying because statutory health insurer reimbursement rate negotiations compress capital expenditure cycles for independent practices. Solo practitioners in rural Saxony exhibit highest price sensitivity, while university-affiliated hospitals in North Rhine-Westphalia prioritize connectivity-enabled platforms regardless of cost premium.
Supply Chain Analysis
Precision optical sensors for intraoral scanners and ceramic milling burs for chairside systems draw from Swiss and Japanese manufacturing clusters. Titanium feedstock for implant fixtures rests on Ukrainian sponge and Chinese mill product availability. Single-source vulnerability concentrates around photopolymer resins for 3D printing surgical guides. Distribution runs through authorized dealer networks with embedded technician certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital workflow service layers now expand faster than hardware sales, transforming equipment vendors into recurring-revenue platforms through real-time remote support and automated EU MDR adverse event reporting modules.
For Market Incumbents: Entrench defensive moats by capturing independent technician networks for handpiece refurbishment while retaining proprietary control over implant-related digital workflow licenses. Deepen backward integration into precision-machined component manufacturing to offset Swiss and Japanese supplier currency volatility. Prioritize firmware architecture enabling seamless sterilizer validation protocol updates as EU MDR grandfathering deadlines approach.
For New Entrants and Emerging Players: East German dental networks in Saxony and Thuringia present modernization opportunities where aging panoramic systems face compressed replacement cycles. Subscription-based CAD/CAM service models reduce upfront capital barriers for solo practitioners in rural North Rhine-Westphalia. Lead with AI-enabled radiographic analysis modules that integrate with existing sensor infrastructure without requiring full platform replacement.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated workflow providers controlling end-to-end digital pathways from scanning through final restoration. Long-term viability hinges on embedded connectivity for post-market surveillance data collection mandated by Germany's Federal Institute for Drugs and Medical Devices. Monitor KZBV-GKV-Spitzenverband reimbursement negotiations as inflection signals for capital expenditure acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Charité-affiliated dental hospitals in Berlin prioritize connectivity-enabled platforms for research-driven procurement. |
| CE Marking Pathway | EU MDR compliance elevates barriers for non-validated manufacturers steering procurement toward established suppliers. |
| Software Companion Development | Chairside milling software licenses generate recurring revenue exceeding original hardware margins across Baden-Württemberg networks. |
| Reimbursement Strategy | Favorable rate settlements between statutory health insurers and dental associations accelerate digital imaging upgrade cycles. |
| Strategic Partnership | Multi-vendor service architectures in North Rhine-Westphalia unbundle hardware maintenance from digital workflow support. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with dental equipment procurement managers, biomedical engineers at university hospitals, GPO contracts specialists, and aftermarket service technicians; alongside secondary validation through EU MDR filing databases, statutory health insurer reimbursement rate publications, and hospital procurement records. Bottom-up equipment deployment counts triangulated against top-down manufacturer revenue estimates across product categories.
Forecast inputs span technology adoption curves, replacement cycle compression patterns, and reimbursement negotiation timelines across the projection horizon. Segmentation dimensions modeled include product type, technology platform, application specialty, and end-user procurement authority. CAGRs derived from equipment installation base growth rates and average selling price evolution assumptions. Industry-specific inputs incorporate EU MDR grandfathering deadline impacts and intraoral scanner replacement cycle acceleration observed in Berlin and Hamburg clinic networks.
Practitioners should monitor KZBV-GKV-Spitzenverband reimbursement negotiations and notified body capacity constraints for early signals requiring forecast revision. Cross-checking against Federal Institute for Drugs and Medical Devices adverse event reporting database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
Dental Imaging Equipment Market
Dental Equipment
Dental 3D Printing Scanner Market
Dental Equipment
Global Dental Light Curing Equipment Market
Dental Equipment
Refurbished Dental Equipment and Maintenance Market
Dental Equipment
France Dental Equipment Market
Dental Equipment
Digital Dental Equipment Market
Dental Equipment
Dental Lights Market
Dental Equipment
Europe Dental Equipment Market
Dental Equipment
Dental CAM Milling Machine Market
Dental Equipment
Dental Equipment Market
Dental Equipment
Veterinary Dental (Dentistry) Equipment Market
Dental Equipment
Global Dental Milling Machine Market
Dental Equipment
Asia-Pacific Dental Equipment Market
Dental Equipment
Dental Simulator Market
Dental Equipment
Dental Equipment and Maintenance Market
Dental Equipment
Ultrasonic Dental Scalers Market