
 North America Dental Equipment Market | 2026-2036
North America Dental Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dental Equipment Market Outlook
Dental equipment distribution through independent dealer networks is narrowing as manufacturers build direct-to-practice digital portals. Dentsply Sirona leverages its chairside ecosystem to sustain recurring revenue from consumables and software subscriptions. Danaher Corporation anchors its position through KaVo Kerr's integrated workflow platforms. Planmeca OY competes by dominating the Nordic-influenced design segment with open-architecture imaging systems.
North America dental equipment encompasses electromechanical devices, diagnostic imaging systems, and computer-aided manufacturing tools engineered to ISO 13485 quality standards for patient-contact medical applications. These systems perform tooth preparation, restoration fabrication, and oral structure imaging with precision tolerances measured in micrometers. Imaging devices lead product type revenue pools due to replacement cycles driven by detector upgrades and AI-enhanced diagnostic software. CAD/CAM technology within digital dentistry represents the fastest-expanding technology segment as same-day crown production reduces laboratory outsourcing. Preventive care applications mature slowly while prosthodontics generates premium pricing from implant-supported restoration complexity.
FDA 510(k) premarket notification requirements govern imaging device and laser system approvals, while Health Canada issues comparable medical device licenses affecting cross-border product harmonization. OSHA bloodborne pathogen standards and CDC infection control guidelines mandate autoclave-compatible instrument designs and barrier-protected touch surfaces. Stakeholders must monitor how state dental board telehealth rulings and provincial scope-of-practice expansions reshape equipment deployment models across the continent.
Market Dynamics
Practice consolidation across Sun Belt metropolitan corridors is compressing procurement cycles as dental service organizations negotiate enterprise-scale equipment contracts, forcing manufacturers to abandon traditional dealer networks for direct digital portals.
Growth Catalysts
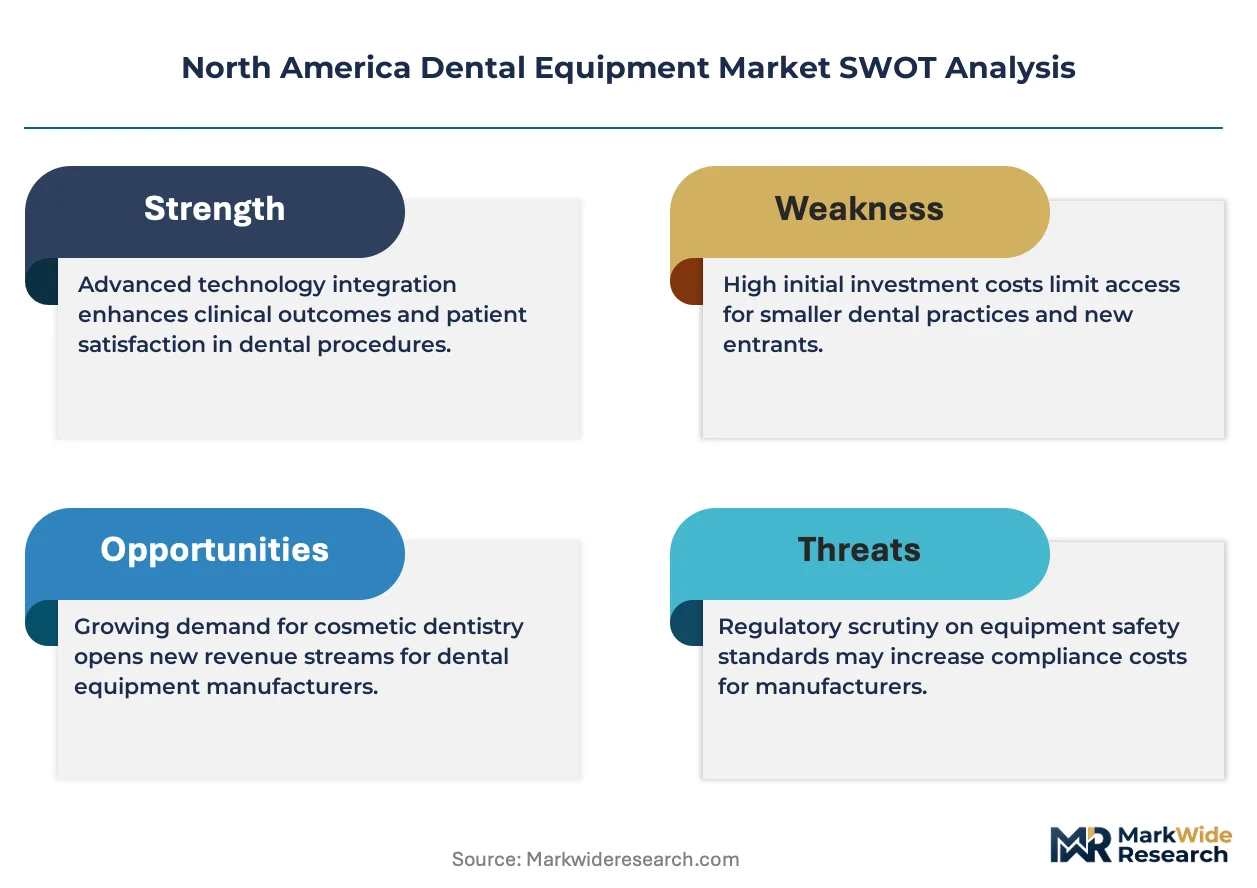
- OSHA Bloodborne Pathogen Standards:Mandates for autoclave-compatible instrument designs and barrier-protected touch surfaces accelerate replacement demand for infection-control-compliant equipment across US outpatient dental facilities.
- AI-Enhanced Diagnostic Software:Detector upgrade cycles in digital radiography systems shorten as machine learning algorithms improve caries detection accuracy, pulling forward capital expenditure timelines.
- Same-Day Crown Production:Chairside CAD/CAM milling systems eliminate laboratory outsourcing for single-unit restorations, capturing margin previously lost to external dental laboratories.
Market Restraints
- Concentrated Detector Supply:CMOS and scintillator component manufacturing concentrates in East Asian foundries, exposing imaging system assemblers to single-source disruption risk.
- FDA 510(k) Premarket Notification:Laser system and advanced imaging device approvals require substantial equivalence demonstrations that compress product differentiation windows and extend development timelines.
- Technical Limitation in Subgingival Imaging:Current intraoral scanner accuracy degrades below the gingival margin, restricting digital workflow adoption in complex implant cases requiring precise emergence profile capture.
Strategic Opportunities
- Provincial Scope-of-Practice Expansion:Canadian provincial dental board rulings permitting expanded hygiene services create equipment demand for preventive-care-focused practices in Ontario and British Columbia.
- Telehealth-Enabled Remote Consultation:State dental board telehealth rulings reshape equipment deployment models, requiring integrated intraoral cameras and cloud-based imaging platforms for asynchronous specialist referrals.
- Convergence of 3D Printing and Milling:Hybrid manufacturing workflows combining photopolymerization with subtractive finishing expand material options for surgical guides and provisional restorations.
Industry Challenges
- ISO 13485 Quality Management Certification:Medical device quality standard compliance requires documented risk management files and post-market surveillance systems that strain mid-size manufacturer administrative capacity.
- Integration Complexity with Legacy Practice Management Software:New digital imaging systems must maintain HL7 or DICOM interoperability with entrenched patient record platforms, extending implementation timelines and training burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dental Equipment Market |
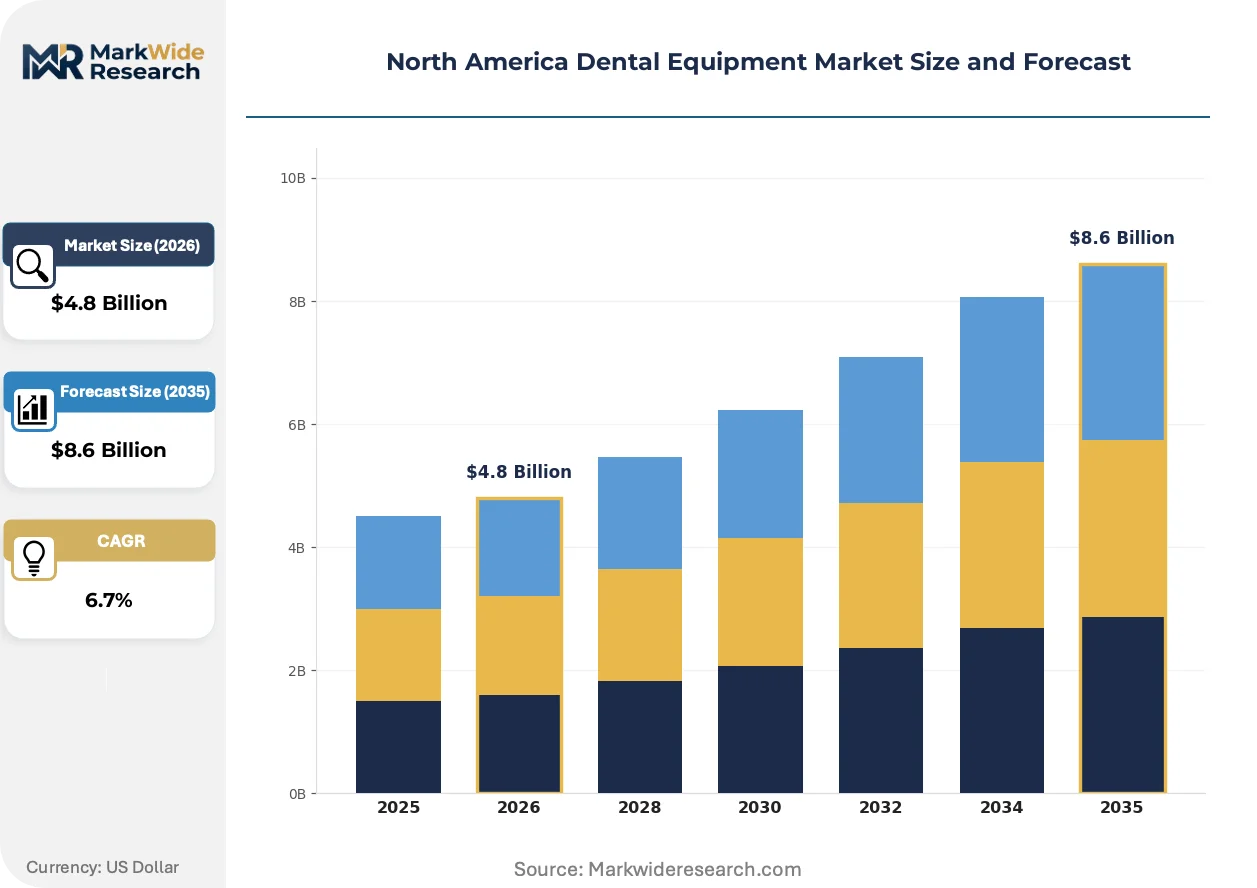
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instruments, Imaging Devices, Consumables, Equipment End User: Dental Clinics, Hospitals, Dental Schools, Research Institutions Technology: Digital Dentistry, CAD/CAM, Laser Dentistry, Traditional Methods Application: Orthodontics, Periodontics, Prosthodontics, Preventive Care |
| Companies Covered | Dentsply Sirona, Planmeca OY, Danaher Corporation, A-dec Inc., Carestream Health, Envista, Institut Straumann AG, Henry Schein, Patterson Companies, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dental Equipment Market Strategic Shifts
Digital dentistry workflows are compressing traditional laboratory relationships while regulatory pathways accelerate clearance timelines for integrated chairside systems. Three developments dominate current market evolution.
Intraoral scanning technology is digitizing impression capture across group dental practices and dental service organizations. These systems replace polyvinyl siloxane and alginate materials with optical triangulation or confocal microscopy, enabling immediate digital transmission to milling centers or printing facilities. The structural consequence is collapsing turnaround times for definitive restorations from two weeks to single-visit delivery.
FDA 510(k) premarket notification pathways for digital imaging and CAD/CAM workflows are compressing product launch timelines relative to traditional predicate device routes. Manufacturers now submit software-as-medical-device modules for iterative algorithm updates without full hardware re-clearance. Imaging device categories with established predicate libraries benefit most, accelerating detector upgrade cycles.
Equipment acquisition patterns among consolidated practice groups favor subscription-based service models over capital purchase. Dental service organizations negotiate all-inclusive per-procedure fees covering hardware, maintenance, consumables, and software updates. This shift concentrates most visibly across Texas, Florida, and Arizona metropolitan corridors where practice aggregation accelerates fastest.
North America Dental Equipment Market Segmentation
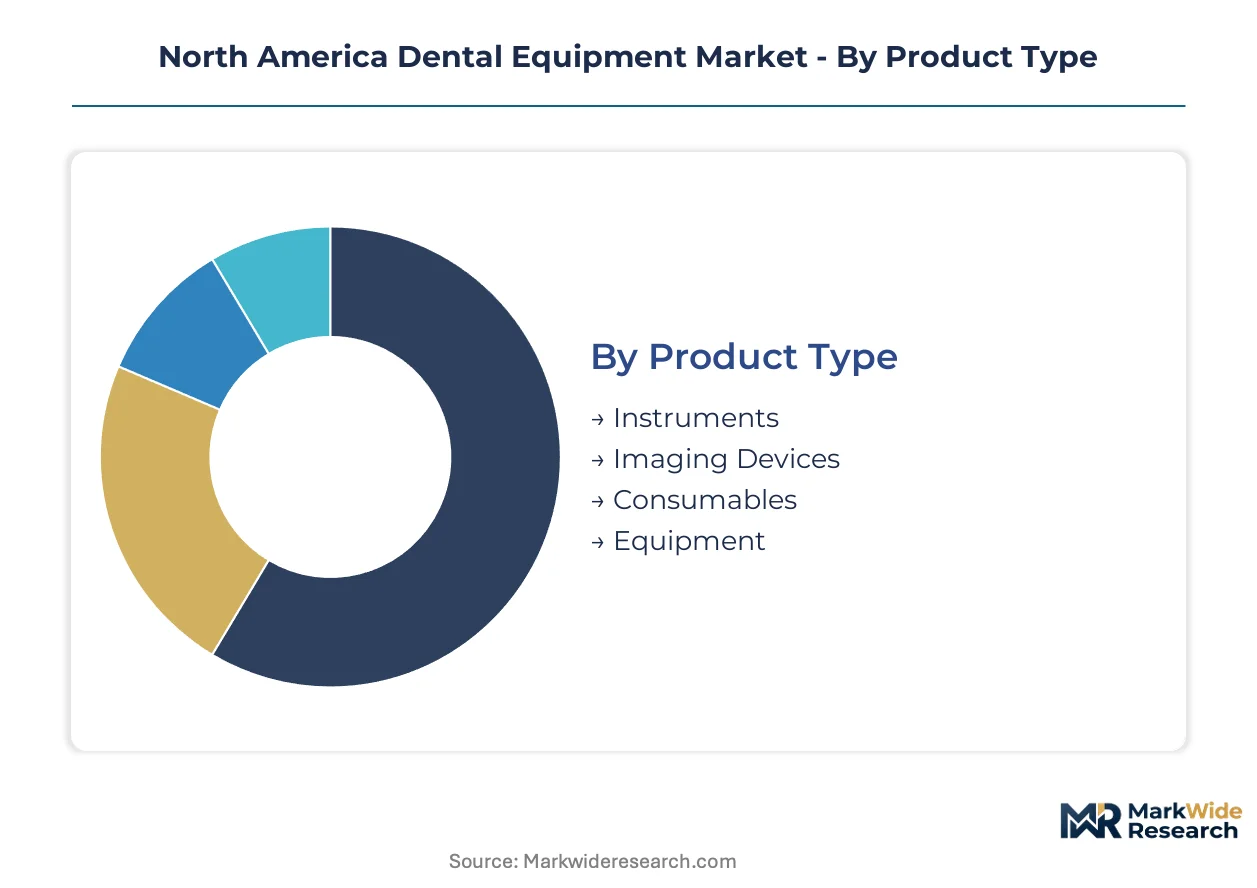
Equipment procurement patterns across North American dental practices diverge sharply by product lifecycle and technology intensity. Segment-level analysis reveals where capital budgets concentrate versus where replacement demand creates recurring revenue pools.
Product Type:
Imaging devices turn over fastest as detector technology advances, while durable equipment platforms persist across decade-long depreciation schedules.
- Imaging Devices:Digital radiography systems and cone-beam computed tomography units integrate CMOS sensors and scintillator arrays that require replacement every 5-7 years as resolution specifications advance. Demand clusters in Sun Belt metropolitan corridors where dental service organizations negotiate enterprise-scale upgrade contracts.
- Consumables:Barrier sleeves, sterilization pouches, and impression materials generate recurring revenue streams tied to procedure volume rather than capital cycles. OSHA bloodborne pathogen standards mandate single-use disposables that resist price compression.
- Instruments:Handpieces, scalers, and extraction forceps manufactured to ISO 13485 tolerances face replacement from wear rather than obsolescence.
- Equipment:Dental chairs, delivery systems, and cabinetry represent long-cycle infrastructure investments with 15-20 year service lives.
Equipment dominates installed base value. Imaging devices are where expansion concentrates fastest.
End User:
Procurement scale varies dramatically—solo practitioners purchase incrementally while consolidated networks negotiate system-wide deployments.
- Dental Clinics:Group practices and dental service organizations across Texas, Florida, and Arizona drive volume through standardized equipment specifications that reduce training complexity and spare parts inventory.
- Hospitals:Academic medical center dental departments require imaging systems with DICOM interoperability for electronic health record integration.
- Dental Schools:Training institutions prioritize durability and manufacturer support networks over cutting-edge specifications.
- Research Institutions:NIH-funded centers acquire specialized imaging for longitudinal oral health studies with stringent calibration protocols.
Dental clinics absorb the majority of unit shipments. Hospitals command premium pricing tiers.
Technology:
Digital workflows are displacing analog methods fastest in prosthodontics, while laser systems penetrate selectively due to capital intensity.
- Digital Dentistry:Intraoral scanners using optical triangulation or confocal microscopy eliminate polyvinyl siloxane impressions. FDA 510(k) pathways for software-as-medical-device updates accelerate feature deployment without hardware recertification.
- CAD/CAM:Chairside milling systems and 3D printing workflows compress restoration turnaround from weeks to single visits. Same-day crown production captures margin previously lost to external dental laboratories.
- Laser Dentistry:Erbium and diode laser systems for soft tissue procedures require substantial equivalence demonstrations that extend FDA clearance timelines.
- Traditional Methods:Analog impression materials and conventional casting techniques persist in cost-sensitive rural markets and certain complex implant cases.
Traditional methods retain installed base depth. CAD/CAM systems are climbing the fastest.
Application:
Procedure reimbursement rates and clinical complexity determine equipment specification intensity across specialties.
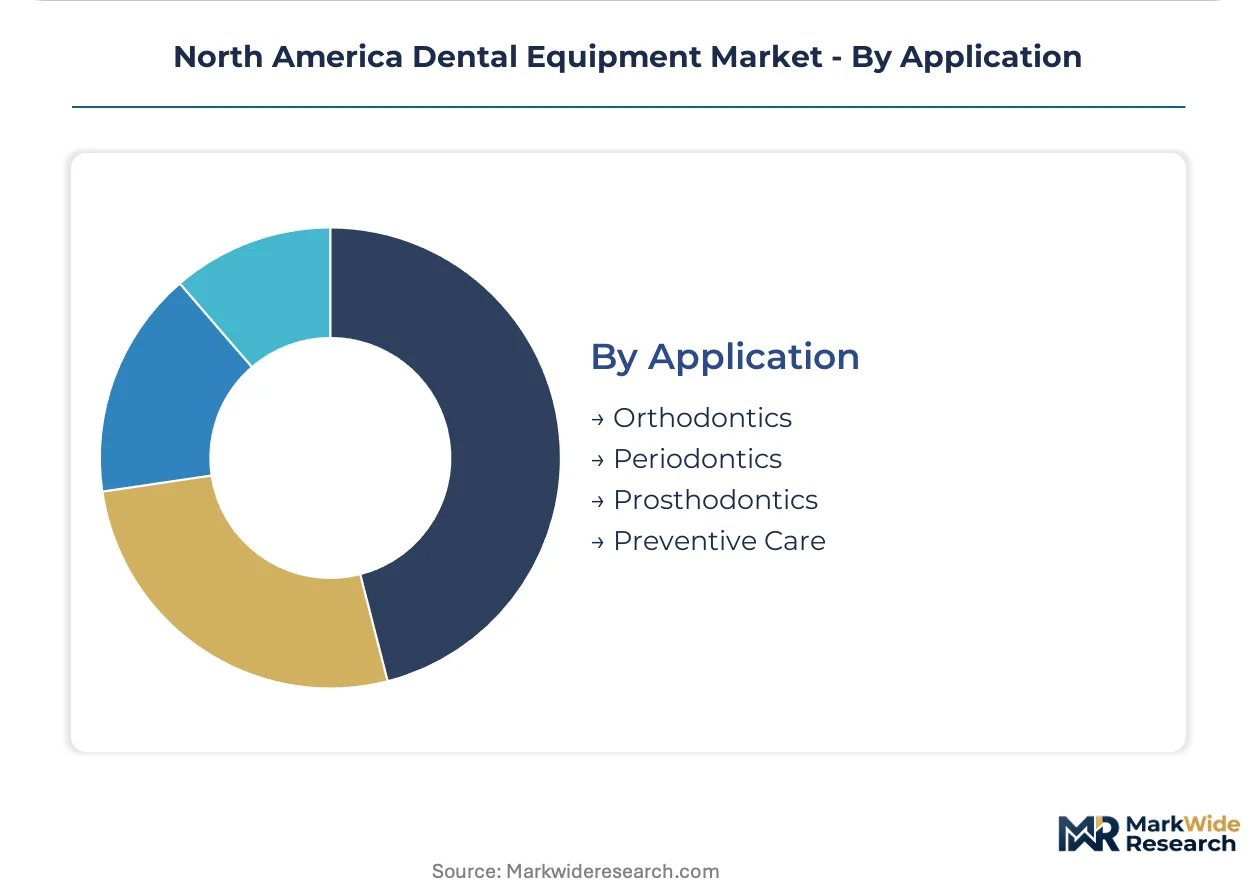
- Prosthodontics:Implant-supported restorations and full-arch reconstructions demand precision tolerances measured in micrometers. Intraoral scanner accuracy degrades below the gingival margin, restricting digital workflow adoption in complex emergence profile cases.
- Orthodontics:Clear aligner therapy and indirect bonding systems require high-throughput scanning and 3D printing infrastructure.
- Periodontics:Regenerative procedures and flap surgery utilize specialized ultrasonic and laser instrumentation.
- Preventive Care:Fluoride application systems and prophylaxis units face slower replacement cycles as hygiene service scope expands under provincial rulings in Ontario and British Columbia.
Preventive care holds the broadest installed base. Prosthodontics commands the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cross-border dental equipment trade corridor connecting Detroit-Windsor and the I-35 freight spine enables rapid distribution of chairside systems across the continent's consolidated practice networks.
United States
Texas, Florida, and Arizona metropolitan corridors drive procurement volume through dental service organization consolidation. FDA 510(k) premarket notification pathways compress clearance timelines for digital imaging and CAD/CAM workflows. Dallas-Fort Worth anchors enterprise-scale equipment contracts as DSOs negotiate system-wide deployments.
Canada
Ontario and British Columbia provincial dental board rulings expand hygiene service scope, creating equipment demand for preventive-care-focused practices. Health Canada medical device licensing requirements affect cross-border product harmonization with US FDA standards. Toronto's dental technology distribution hub serves consolidated practices across the Golden Horseshoe corridor.
Mexico
Border state maquiladora operations assemble components for US-market imaging systems under IMMEX program provisions. COFEPRIS medical device registration requirements govern product entry for domestic dental clinic sales. Tijuana-Baja California manufacturing clusters supply CMOS detector housings and precision-milled components.
North America Dental Equipment Market Competitive Environment
On the supply side, the industry is consolidating around integrated chairside ecosystems that capture recurring revenue from consumables and software subscriptions. Three strategic archetypes dominate: full-platform manufacturers bundling hardware with proprietary workflows, component specialists supplying open-architecture imaging systems, and distribution intermediaries pivoting toward direct digital portals. Competitive positioning hardens through M&A-driven platform consolidation and backward integration into detector manufacturing.
Among full-platform manufacturers, Dentsply Sirona and Danaher Corporation exemplify the integrated ecosystem archetype, while Planmeca OY occupies a position within the open-architecture design segment. These anchors represent contrasting approaches to workflow capture—proprietary closed systems versus interoperable imaging platforms.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Planmeca OY |
| Danaher Corporation |
| A-dec Inc. |
| Carestream Health |
| Envista |
| Institut Straumann AG |
| Henry Schein |
| Patterson Companies |
| Others |
Value Chain & Pricing Dynamics
The I-35 freight spine connecting Texas manufacturing clusters to Midwest distribution hubs imposes fuel-surcharge volatility that amplifies cost spreads between volume-consolidated dental service organizations and independent practices, compressing margins for mid-tier equipment assemblers while premium chairside ecosystems capture pricing power through captive consumable streams.
Pricing Analysis
Volume-discount tiering structures separate enterprise-scale dental service organization contracts from solo practitioner spot purchases by 15-30 percentage points on equivalent imaging platforms. Price differentiation rests on ISO 13485 certification grade and after-sales service bundling rather than hardware specifications alone. Cost compression in the standard-equipment tier is intensifying as Taiwanese CMOS detector foundries exercise supply control. Solo practitioners in rural markets exhibit highest price sensitivity, while Sun Belt DSOs prioritize total-cost-of-ownership metrics over upfront capital outlay.
Supply Chain Analysis
Contract-manufacturing concentration for CMOS sensors and scintillator arrays sits with Taiwanese and South Korean foundries, while precision-milled component fabrication localizes in Tijuana-Baja California maquiladora operations under IMMEX provisions. Raw material dependencies span rare-earth phosphors for scintillator layers, medical-grade aluminum alloys for housing structures, and photopolymer resins for 3D printing workflows. Single-source vulnerability in East Asian detector supply exposes assemblers to tariff exposure on cross-Pacific component flows. Distribution runs through direct-to-practice digital portals that bypass traditional independent dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America dental equipment market functions as a defensive-moat arena where regulatory entrenchment through FDA 510(k) predicate libraries creates substantial switching costs that protect incumbent positions.
For Market Incumbents: Insulate market position by deepening backward integration into CMOS detector manufacturing to neutralize East Asian supply chokepoints, while accelerating software-as-medical-device update cadences to tighten ecosystem lock-in against open-architecture challengers. Threat vectors include Planmeca OY's Nordic-influenced design segment gaining share among group practices prioritizing interoperability over proprietary workflows. For New Entrants and Emerging Players: Canadian provincial scope-of-practice expansions in Ontario and British Columbia represent underpenetrated white-space where preventive-care-focused equipment demand outpaces incumbent attention. Rural and small-market dental clinics in the US Mountain West exhibit lowest DSO consolidation penetration and highest price elasticity for open-architecture imaging alternatives. A direct digital portal go-to-market angle bypasses entrenched dealer relationships that favor established manufacturers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates holding dental equipment divisions as non-core assets, particularly those with dormant ISO 13485 certifications and established Health Canada licensing that could accelerate North American market entry. Long-term viability hinges on recurring revenue mix from consumables and software subscriptions rather than capital hardware cycles. The signal to watch is DSO procurement committee shifts toward subscription-based per-procedure pricing models as inflection indicator for valuation multiple expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software-as-Medical-Device Pathway | Accelerates algorithm update deployment without hardware recertification, compressing feature release cycles against predicate-dependent competitors. |
| Backward Integration into Detector Manufacturing | Captures CMOS sensor margin and neutralizes single-source supply risk from Taiwanese foundry concentration. |
| Direct-to-Practice Digital Portal Launch | Eliminates independent dealer margin stack while capturing procurement data for predictive consumable replenishment. |
| Subscription-Based Per-Procedure Pricing | Aligns revenue with DSO procedure volume and creates predictable recurring streams across Sun Belt consolidation corridors. |
| Health Canada Cross-Border Harmonization | Unlocks Ontario and British Columbia provincial expansion opportunities under unified North American quality standards. |
Study Parameters
Cross-validation between primary interviews with dental equipment procurement directors, biomedical engineers at academic medical centers, GPO contracts managers, and independent practice owners anchors the qualitative findings against secondary validation from FDA 510(k) premarket notification databases, Health Canada medical device licenses, hospital procurement contract disclosures, and dental service organization capital expenditure filings. Bottom-up equipment shipment modeling triangulates against top-down addressable market sizing across product type, end user, technology, and application dimensions.
Calibration against historical replacement cycle patterns and detector technology upgrade trajectories informs the analytical framework across the analysis window. Segmentation dimensions span imaging devices, consumables, instruments, and equipment by product type; dental clinics, hospitals, dental schools, and research institutions by end user; digital dentistry, CAD/CAM, laser dentistry, and traditional methods by technology; and prosthodontics, orthodontics, periodontics, and preventive care by application. CAGRs derive from procedure volume elasticity, DSO consolidation velocity, and regulatory clearance timeline compression.
The forecast holds incumbent behavior within observed patterns; aggressive moves by open-architecture specialists or unexpected FDA pathway reforms would shift outcomes. Quarterly review of DSO procurement committee composition changes, provincial dental board rulings, and CMOS foundry capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
Asia-Pacific Dental Equipment Market
Dental Equipment
Refurbished Dental Lab Equipment Market
Dental Equipment
Dental Radiology Equipment Market
Dental Equipment
Brazil Dental Equipment Market
Dental Equipment
Dental Lights Market
Dental Equipment
Europe Dental Equipment Market
Dental Equipment
Veterinary Dental (Dentistry) Equipment Market
Dental Equipment
Dental Diagnostic and Surgical Equipment Market
Dental Equipment
Dental Elevator and Luxator Market
Dental Equipment
Dental Simulator Market
Dental Equipment
Japan Dental Equipment Market
Dental Equipment
Dental Equipment and Maintenance Market
Dental Equipment
Global Dental Light Curing Equipment Market
Dental Equipment
Refurbished Dental Equipment and Maintenance Market
Dental Equipment
Digital Dental Equipment Market
Dental Equipment
Ultrasonic Dental Scalers Market