
 Global Dental Light Curing Equipment Market | 2026-2036
Global Dental Light Curing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Light Curing Equipment Market Foresight
High-intensity LED curing with calibrated irradiance above 1,000 mW/cm² is reorganizing procurement priorities across dental practices. Dentsply Sirona leverages its integrated CAD/CAM ecosystem to bundle curing units with chairside workflows. Kerr Corporation anchors North American distribution through its longstanding dealer relationships with group practices. Ivoclar Vivadent differentiates via proprietary polywave LED technology that addresses broader photoinitiator spectra.
Dental light curing equipment employs focused electromagnetic radiation, typically in the 400–500 nm blue-light range, to photopolymerize resin-based composite materials through free-radical initiation. LED curing lights dominate installed bases due to cooler operating temperatures, extended emitter lifespans exceeding 50,000 hours, and declining unit costs. Wireless technology commands premium positioning as practitioners prioritize ergonomic mobility and infection control protocols. Composite restoration applications generate the largest volume demand, though orthodontic bonding exhibits faster growth as clear aligner attachment procedures multiply. Dental clinics represent the core end-user channel, while dental laboratories sustain demand for high-throughput desktop units processing multiple restorations simultaneously.
FDA 510(k) premarket notification requirements govern optical output claims and biocompatibility testing for US market entry, while EU MDR technical documentation mandates clinical performance validation under the CE marking framework. ISO 10650 standards define measurement protocols for irradiance and exposure time, creating baseline interoperability expectations that manufacturers must satisfy across jurisdictions. Stakeholders should monitor evolving polymerization depth verification requirements as resin manufacturers formulate proprietary photoinitiator systems that challenge legacy curing parameters.
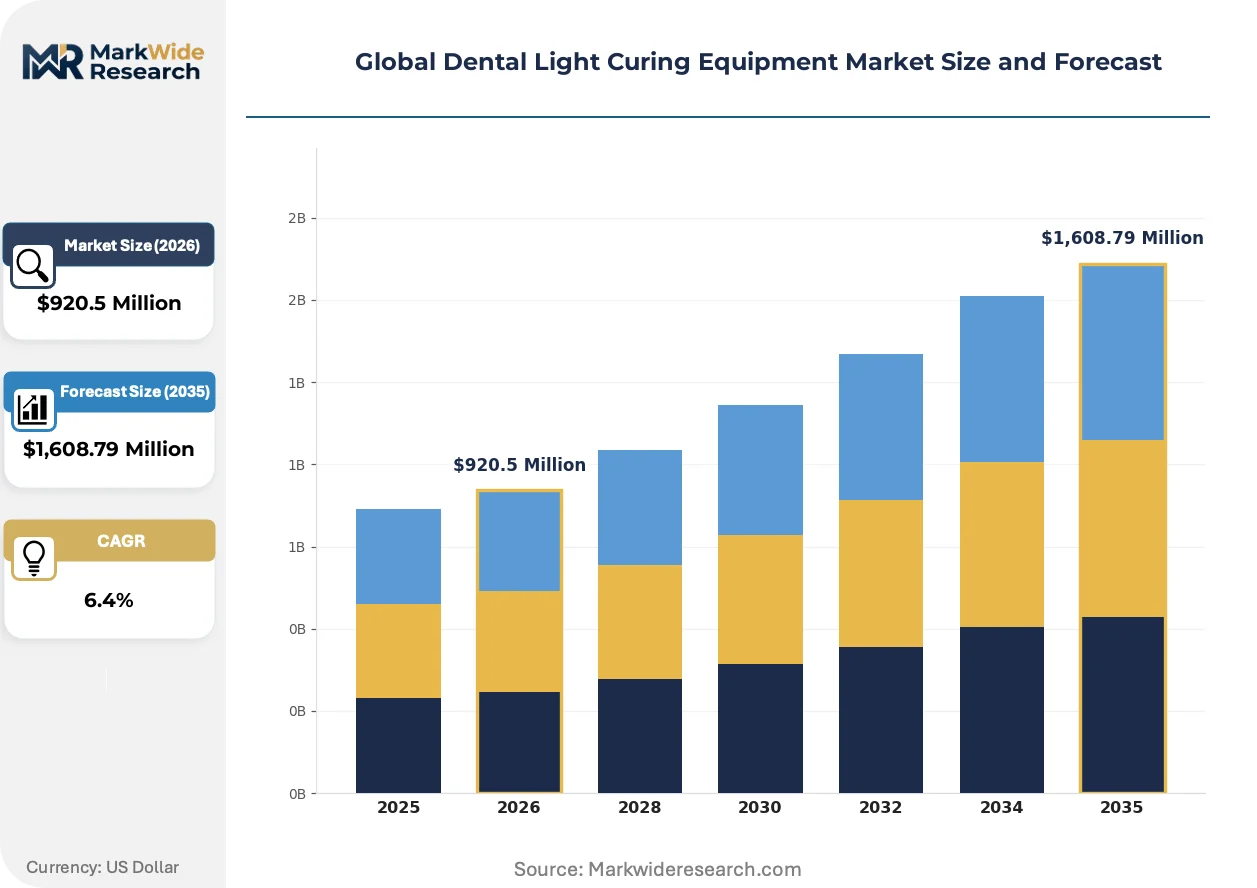
Market Dynamics
LED curing technology is decomposing the installed base of halogen units across dental practices worldwide, with calibrated irradiance specifications now dictating procurement decisions and reshaping competitive positioning between wireless and corded form factors.
Growth Catalysts
- EU MDR Conformity Requirements:Tightened clinical performance documentation for polymerization depth claims is forcing manufacturers to invest in validated optical output testing, raising barriers for low-quality entrants and benefiting established suppliers with in-house metrology capabilities.
- Composite Restoration Volume:Rising chairside restorative procedures in China's provincial hospital networks and India's metro-tier dental chains is generating bulk procurement demand for wireless LED units with ergonomic mobility features.
- Photoinitiator Spectrum Expansion:Proprietary polywave LED architectures capable of addressing broader photoinitiator spectra are enabling faster curing cycles for proprietary resin formulations, creating technology pull from dental clinics seeking workflow efficiency gains.
Market Restraints
- Emitter Supply Concentration:High-intensity blue LED chip manufacturing concentrates among East Asian semiconductor foundries, exposing curing equipment assemblers to input cost volatility and supply allocation risk during capacity constraints.
- FDA 510(k) Documentation Burden:Optical output claims and biocompatibility testing requirements for US market entry extend development timelines and increase regulatory compliance costs for smaller manufacturers lacking dedicated regulatory affairs functions.
- Halogen Unit Residual Stock:Extended operational lifespans of legacy halogen curing platforms in cost-sensitive dental practices create substitution drag, particularly in Latin American and Southeast Asian markets where equipment replacement cycles stretch beyond industry averages.
Strategic Opportunities
- Brazilian Dental Clinic Expansion:Chairside restorative capability investments across Brazil's growing dental clinic networks present white space for wireless LED unit penetration, with local distributors seeking exclusive territory arrangements for premium-tier equipment.
- Orthodontic Bonding Acceleration:Clear aligner attachment procedures are multiplying faster than composite restoration growth, creating demand for specialized curing accessories and shorter exposure protocols optimized for bracket adhesion workflows.
- ISO 10650 Harmonization:Emerging market regulators are adopting ISO irradiance measurement protocols as national standards, reducing technical barriers to entry for manufacturers with existing certification infrastructure and enabling faster multi-country product registrations.
Industry Challenges
- Calibration Technician Scarcity:Proper maintenance of irradiance calibration requires specialized optical metrology skills that dental equipment service networks struggle to recruit, leading to performance drift in fielded units and inconsistent polymerization outcomes.
- Legacy System Integration Complexity:Wireless LED units must interoperate with existing dental chair electrical systems and infection control protocols, creating installation friction in older clinic infrastructure that lacks dedicated USB charging ports or standardized mounting interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Light Curing Equipment Market |
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,608.79 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Curing Lights, Quartz Tungsten Halogen, Plasma Arc Curing Lights, Laser Curing Units, UV Curing Equipment Technology: Wireless, Corded, Battery-Operated, Portable, Desktop Application: Composite Restoration, Orthodontic Bonding, Sealant Curing, Endodontic Procedures, Preventive Treatment End User: Dental Laboratories, Dental Practitioners, Dental Clinics, Orthodontic Centers, Cosmetic Dentistry Facilities |
| Companies Covered | Coltene, Acteon Group, Dentsply Sirona, GEBDI Dentalproducts, DenMat Holdings, Ivoclar Vivadent, Woodpecker, Bredent Medical, Kerr Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Light Curing Equipment Market Shifts & Advancements
Photopolymerization technology is converging with digital dentistry workflows, with curing parameters becoming programmable variables within integrated restorative systems rather than standalone equipment specifications.
Polywave LED technology is decomposing the historical trade-off between curing speed and polymerization depth uniformity. Multi-peak emission spectra address proprietary photoinitiator systems developed by resin manufacturers seeking differentiation through faster chairside turnaround. Dental clinics in Germany and Japan are adopting these platforms at accelerated rates, compressing the replacement cycle for single-peak LED units purchased during the initial technology transition.
FDA 510(k) premarket notification pathways are tightening evidentiary requirements for optical output stability claims. Biocompatibility testing documentation must now demonstrate performance consistency across the full emitter lifespan, not just initial factory calibration. North American manufacturers are responding by integrating real-time irradiance monitoring sensors that provide usage-based maintenance alerts, shifting the compliance burden toward predictive validation rather than retrospective testing.
Group purchasing organizations are consolidating procurement authority across US dental practice networks. Traditional dealer relationships with individual clinics are yielding to centralized equipment specification and volume contracting, with Kerr Corporation and similar incumbents restructuring distribution agreements to maintain access. This concentration is most visible in the southeastern United States, where dental service organizations now control significant chair count and negotiate standardization across acquired practices.
Global Dental Light Curing Equipment Market Segmentation
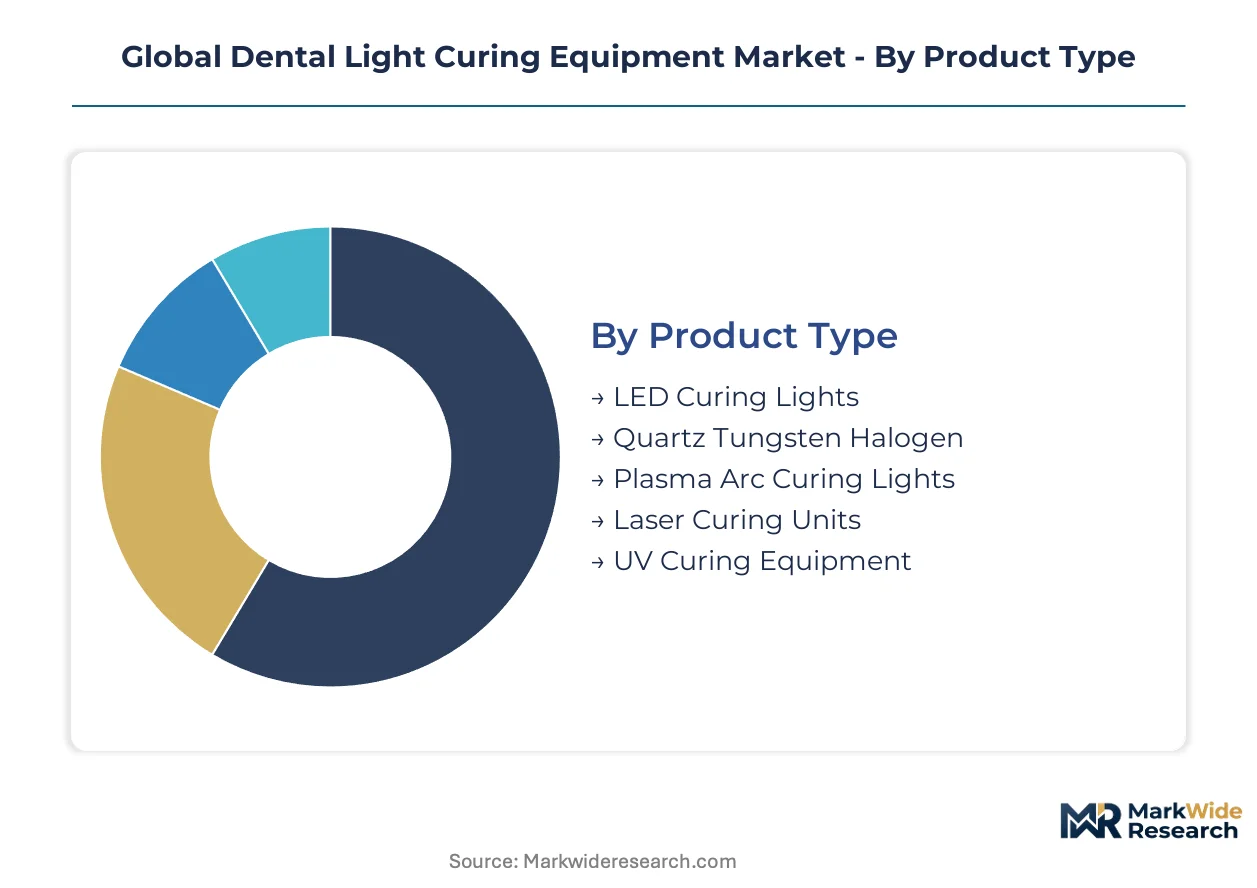
Segmentation in dental light curing equipment reveals how procurement priorities diverge between high-throughput laboratory environments and mobility-focused clinical settings. Technology choices cascade through application requirements, end-user workflows, and regulatory compliance obligations across distinct geographic markets.
Product Type:
LED curing lights dominate domestic manufacturing in Germany and Japan, while quartz tungsten halogen retains export relevance in cost-sensitive Southeast Asian markets. Plasma arc and laser platforms concentrate among North American specialty suppliers serving premium-tier orthodontic centers.
- LED Curing Lights:Solid-state blue-light emitters operating at 430-490 nm wavelengths deliver calibrated irradiance above 1,000 mW/cm² with thermal management below 40°C. Demand concentrates in China's provincial hospital networks where bulk procurement of polywave LED units accelerates replacement of legacy platforms.
- Quartz Tungsten Halogen:Broad-spectrum thermal emitters require filtered output to isolate the 400-500 nm range, consuming 60-80W continuous power with bulb lifespans of 50-100 hours. Residual stock persists in Brazil and Mexico where extended replacement cycles and distributor financing arrangements slow technology transition.
- Plasma Arc Curing Lights:High-intensity xenon plasma sources enable sub-3-second curing cycles for specialized orthodontic bonding workflows.
- Laser Curing Units:Argon ion and diode laser platforms address narrow photoinitiator absorption peaks in proprietary resin systems.
- UV Curing Equipment:Legacy 365 nm systems retain niche demand for specific industrial dental applications outside clinical restoration.
LED curing lights hold the largest share; momentum sits with polywave LED architectures addressing broader photoinitiator spectra.
Technology:
Cost tier stratification separates premium wireless units with ergonomic mobility features from economy corded platforms serving high-volume laboratory batch processing. Battery-operated variants occupy the mid-tier across India's metro-tier dental chains.
- Wireless:Lithium-polymer battery packs integrated into handpiece housings enable 60-120 minutes of continuous operation without tethering to dental chair electrical systems. Dental clinics in Germany and Japan adopt these platforms at accelerated rates, prioritizing infection control protocols and practitioner ergonomics.
- Corded:Direct AC power delivery eliminates battery weight and charging downtime, supporting sustained high-output operation. Dental laboratories in the United States and Switzerland specify corded desktop units for simultaneous processing of multiple restorations.
- Battery-Operated:Removable battery systems allow field replacement during extended clinical sessions.
- Portable:Lightweight housings under 200 grams target mobile dentistry and outreach programs.
- Desktop:Fixed-position units with articulated arms serve high-throughput laboratory curing stations.
Corded systems dominate laboratory volume; wireless configurations are climbing the fastest among clinical procurement specifications.
Application:
Application segmentation tracks procedure volume concentration versus growth trajectory divergence, with composite restoration generating absolute demand while orthodontic bonding multiplies attachment points per patient case.
- Composite Restoration:Layered photopolymerization of resin-based restorative materials requires calibrated exposure protocols ensuring polymerization depth exceeds 2 mm per increment. Chairside restorative capability investments across Brazil's expanding dental clinic networks drive specification of wireless LED units with real-time irradiance feedback.
- Orthodontic Bonding:Bracket adhesion and clear aligner attachment procedures demand precise spot curing with minimal thermal transfer to enamel surfaces. Clear aligner volume multiplication in South Korea and the United States creates demand for specialized curing accessories with shortened exposure protocols.
- Sealant Curing:Pit and fissure sealant applications prioritize rapid throughput in pediatric dentistry settings.
- Endodontic Procedures:Post cementation and core buildup curing within confined canal spaces requires specialized light guide configurations.
- Preventive Treatment:Fluoride varnish activation and desensitizing resin protocols represent emerging low-intensity applications.
Composite restoration commands the largest procedure volume; orthodontic bonding exhibits the steepest expansion trajectory driven by clear aligner adoption.
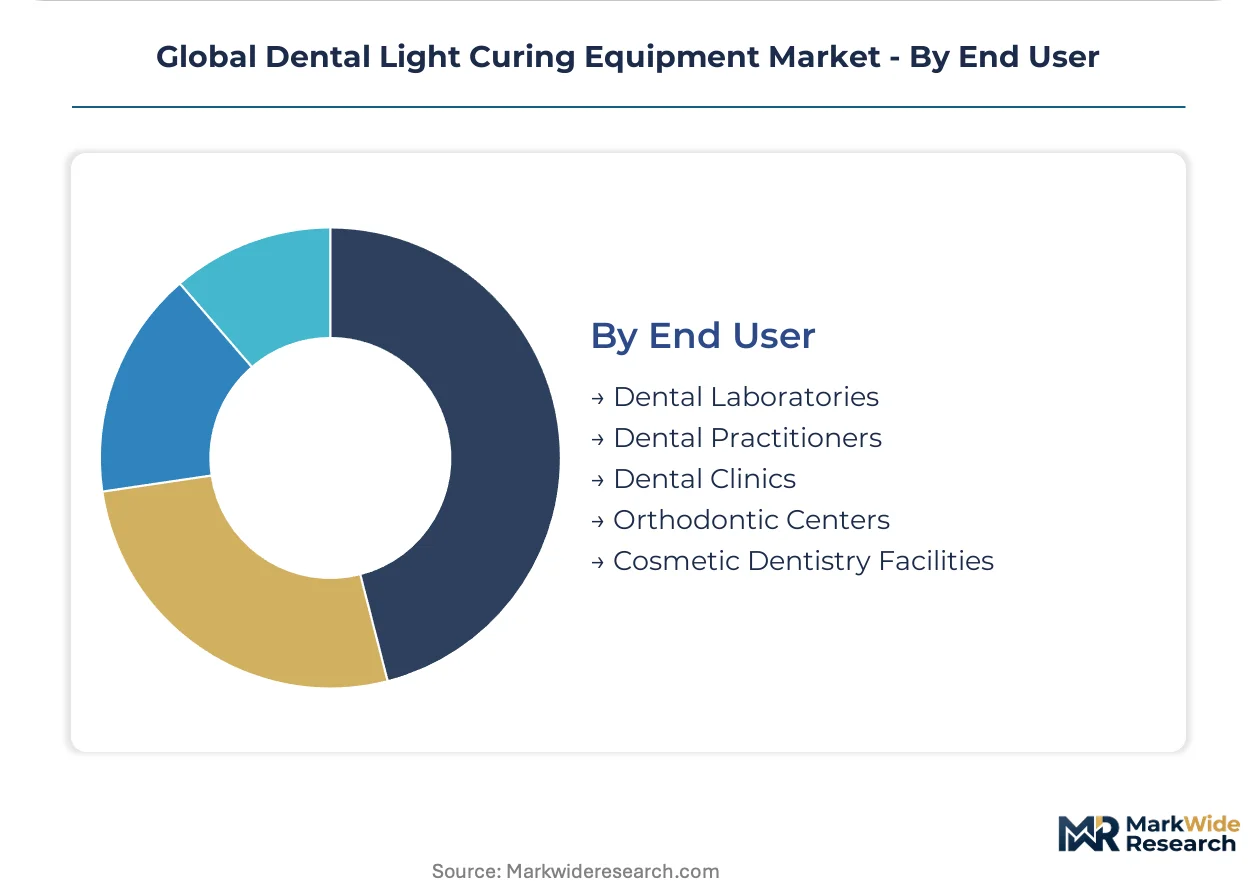
End User:
Customer type segmentation separates high-volume standardized procurement by dental service organizations from fragmented individual practitioner purchases, with orthodontic centers representing a concentrated specification channel.
- Dental Laboratories:Commercial restoration processing facilities operate multiple curing stations with batch workflow optimization, prioritizing corded desktop units with programmable exposure sequences. Group purchasing organizations across the southeastern United States consolidate procurement authority for laboratory equipment specifications.
- Dental Clinics:General practice restorative environments balance mobility requirements against capital equipment budgets, driving wireless LED penetration in China's provincial networks and India's metro-tier chains.
- Dental Practitioners:Solo and small-group practices exhibit fragmented purchasing patterns through traditional dealer relationships.
- Orthodontic Centers:Specialized facilities standardize on high-intensity platforms for bracket bonding efficiency.
- Cosmetic Dentistry Facilities:Premium-tier practices prioritize aesthetic outcome consistency and patient experience features.
Dental clinics represent the largest installed base; dental laboratories sustain the most concentrated procurement volume per location.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor established manufacturing hubs in Germany and Japan while China's provincial hospital networks drive import substitution through domestic LED assembly. Brazil and India represent net import markets where distributor financing structures shape equipment penetration rates.
United States
FDA 510(k) premarket notification pathways govern optical output stability claims for polymerization depth verification. Group purchasing organizations across the southeastern United States consolidate procurement authority for dental service organization networks. Kerr Corporation leverages longstanding dealer relationships to maintain distribution access amid this consolidation.
Germany
EU MDR technical documentation mandates clinical performance validation for CE marking of high-intensity LED platforms. Dental clinics in Bavaria and North Rhine-Westphalia adopt polywave LED architectures at accelerated replacement rates. The country's metrology infrastructure supports in-house optical output testing capabilities that raise barriers for low-quality entrants.
China
NMPA registration requirements and GB standards for medical device optical performance shape domestic manufacturing compliance. Provincial hospital networks in Sichuan and Guangdong execute bulk procurement of wireless LED units with ergonomic mobility specifications. Woodpecker anchors domestic supply through integrated production of emitter modules and finished handpiece assemblies.
India
CDSCO medical device rules and BIS certification requirements govern import clearance for LED curing equipment. Metro-tier dental chains in Maharashtra and Karnataka prioritize wireless configurations with infection control protocols. Local distributors seek exclusive territory arrangements as chairside restorative volumes expand in tier-2 cities.
Brazil
ANVISA registration pathways extend timelines for optical output documentation and biocompatibility testing. Dental clinic networks in São Paulo and Minas Gerais invest in chairside restorative capabilities as LED technology displaces legacy halogen platforms. Extended replacement cycles in cost-sensitive practices create substitution drag despite technology advantages.
Global Dental Light Curing Equipment Market Competitive Landscape
Listed leaders compete with private specialists across regulatory compliance capabilities and distribution infrastructure. The vendor base stratifies between integrated dental equipment conglomerates, regional fabrication specialists, and component-focused technology suppliers. Three archetypes dominate: full-platform integrators bundling curing units with CAD/CAM workflows; standalone equipment specialists optimizing wireless ergonomics; and emitter technology suppliers controlling upstream semiconductor supply. Competitive moves concentrate on strategic partnerships with resin manufacturers and geographic expansion through exclusive distributor arrangements.
Within the full-platform integrator tier, Dentsply Sirona and Ivoclar Vivadent exemplify divergent technology anchoring strategies. Dentsply Sirona occupies a position tied to chairside workflow integration, while Ivoclar Vivadent represents proprietary polywave LED specialization. Among standalone equipment specialists, Kerr Corporation sits within the North American distribution-focused archetype, leveraging scale in group practice procurement channels. Woodpecker anchors the domestic Chinese manufacturing archetype, exemplifying vertical control from semiconductor assembly through finished device production.
| Leading Market Players |
|---|
| Coltene |
| Acteon Group |
| Dentsply Sirona |
| GEBDI Dentalproducts |
| DenMat Holdings |
| Ivoclar Vivadent |
| Woodpecker |
| Bredent Medical |
| Kerr Corporation |
| Others |
Supply & Pricing Matrix
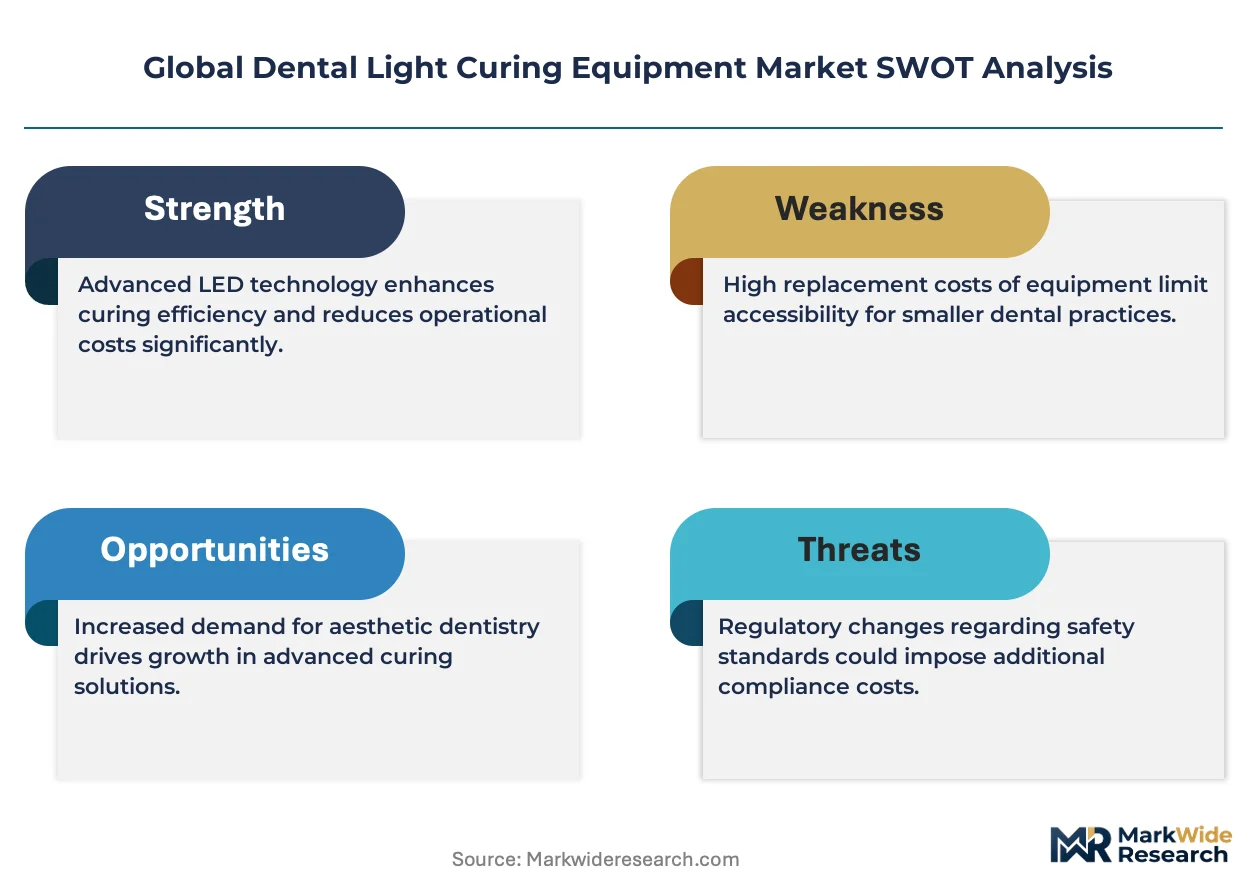
FDA 510(k) premarket notification requirements gate both supplier qualification and price differentiation across the dental light curing equipment market, as optical output documentation burdens favor established manufacturers with dedicated regulatory affairs functions while compressing margins for smaller entrants lacking in-house metrology capabilities.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with wireless LED units commanding premium positioning based on ergonomic mobility features and infection control protocols while corded laboratory platforms compete on throughput volume. Price differentiation rests on certification grade — FDA-cleared versus CE-marked versus non-certified units — and after-sales service bundling including calibration maintenance programs. Cost compression in the economy tier is intensifying because Chinese domestic manufacturers are scaling emitter module production. Dental service organizations exhibit the lowest price sensitivity due to centralized procurement authority, while solo practitioners in Southeast Asia remain most price-constrained.
Supply Chain Analysis
Inventory lead times for high-intensity blue LED chips stretch during semiconductor foundry capacity constraints, exposing curing equipment assemblers to allocation risk. Manufacturing concentrates in China, Japan, and South Korea, with East Asian foundries controlling blue LED emitter supply. Raw material dependencies include gallium nitride substrates, optical-grade silicone for light guides, and lithium-polymer cells for wireless handpieces. Single-source vulnerability concentrates in advanced emitter architectures, as polywave LED designs require specialized phosphor formulations from limited qualified suppliers. Distribution runs through dental equipment dealers and group purchasing organizations, with direct manufacturer relationships penetrating larger dental clinic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental light curing equipment market sits in early-cycle expansion as LED technology displaces legacy halogen platforms across Brazil, India, and China's provincial networks, with wireless form factor adoption accelerating replacement demand beyond historical equipment lifecycles.
For Market Incumbents: Shield installed base relationships by embedding real-time irradiance monitoring sensors that shift compliance toward predictive validation, and secure backward integration into emitter module production to buffer East Asian foundry allocation risk. The FDA's tightening evidentiary requirements for optical output stability claims threaten smaller competitors lacking dedicated regulatory infrastructure, while vertical control over semiconductor supply anchors margin defense. For New Entrants and Emerging Players: Differentiate on polywave LED specialization addressing proprietary photoinitiator spectra developed by resin manufacturers, targeting Brazil's expanding dental clinic networks where local distributors seek exclusive territory arrangements for premium-tier wireless units. The orthodontic bonding segment offers the most penetrable white space as clear aligner attachment procedures multiply faster than composite restoration growth, with shortened exposure protocols creating demand for specialized curing accessories. For Investors and Strategic Acquirers: EU MDR technical documentation mandates reshape the acquisition landscape by raising barriers for low-quality entrants and rewarding targets with validated in-house optical metrology capabilities. Long-term viability centers on manufacturers capable of clinical performance validation across evolving polymerization depth requirements. The signal to monitor is NMPA registration acceleration among Chinese domestic producers, which would indicate import substitution pressure on multinational market share.| Strategic Initiative | Industry Significance |
|---|---|
| Polywave LED Architecture Development | Ivoclar Vivadent's proprietary multi-peak emission addresses broader photoinitiator spectra for faster curing cycles. |
| Wireless Battery Integration | Ergonomic lithium-polymer handpieces penetrate Germany and Japan clinics prioritizing infection control protocols. |
| Real-Time Irradiance Monitoring | Sensor-embedded units shift FDA compliance burden from retrospective testing toward predictive validation. |
| Exclusive Distributor Arrangements | Territory-lock agreements in Brazil and India secure channel access amid clinic network expansion. |
| Emitter Module Backward Integration | Woodpecker's captive supply from semiconductor assembly through finished device production buffers input cost volatility. |
Research Methodology
The analysis maps LED curing lights, quartz tungsten halogen units, and plasma arc platforms, each validated through procurement managers at dental service organizations, biomedical engineers at hospital networks, regulatory affairs specialists at manufacturers, and aftermarket service technicians. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, NMPA registration records, and ISO 10650 certification registries. Bottom-up equipment shipment data triangulated against top-down dental clinic census estimates across Germany, China, India, Brazil, and the United States.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for emitter module imports, dental equipment distributor shipment reports, and group purchasing organization contract disclosures. The analytical framework segments by product type, technology configuration, application workflow, and end-user procurement channel across the projection horizon. CAGRs derived from procedure volume growth trajectories in composite restoration and orthodontic bonding, cross-referenced with equipment replacement cycle compression rates in wireless LED adoption.
Material uncertainties — regulatory timeline delays for optical output documentation, semiconductor foundry capacity allocation shocks, and resin manufacturer photoinitiator formulation shifts — sit outside the modeled envelope. Forecasts reflect assumptions about LED technology displacement velocity and bulk procurement concentration in emerging market clinic networks. Revision becomes warranted when polywave LED certification thresholds or emitter supply concentration metrics cross stability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
Europe Dental Equipment Market
Dental Equipment
Dental Equipment and Maintenance Market
Dental Equipment
North America Dental Equipment Market
Dental Equipment
Refurbished Dental Equipment and Maintenance Market
Dental Equipment
Japan Dental Equipment Market
Dental Equipment
Dental Radiology Equipment Market
Dental Equipment
Dental Equipment and Consumables Market
Dental Equipment
Germany Dental Equipment Market
Dental Equipment
Dental Equipment Market
Dental Equipment
Dental Elevator and Luxator Market
Dental Equipment
Dental Imaging Equipment Market
Dental Equipment
Dental Engine Market
Dental Equipment
Dental Dust Collector Market
Dental Equipment
Ultrasonic Dental Scalers Market
Dental Equipment
Dental Diagnostic and Surgical Equipment Market
Dental Equipment
France Dental Equipment Market