
 France Dental Equipment Market | 2026-2036
France Dental Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
France Dental Equipment Market Foresight
Equipment leasing and pay-per-use financing models are reshaping competitive access for mid-sized French dental practices that previously deferred capital purchases. Straumann Holding AG leverages its implantology specialization to anchor premium positioning across French university hospitals and private clinic chains. Ivoclar Vivadent AG sustains its ceramics and materials leadership through direct technical training programs with French dental technicians. Dentsply Sirona Inc competes by bundling chairside CAD/CAM workflows with service contracts that reduce upfront ownership barriers.
Dental equipment encompasses electromechanical devices, diagnostic imaging systems, and computer-aided manufacturing tools engineered to ISO 13485 quality standards for patient-contact medical applications, with precision tolerances often below 50 micrometers for prosthetic milling operations. These systems enable diagnosis, treatment planning, and restorative fabrication within oral healthcare delivery. Intraoral scanners and CAD/CAM systems capture the fastest expansion as French practitioners replace conventional impression workflows with digital chairside production. Dental lasers occupy mature positions in soft-tissue applications but face margin pressure from LED curing and ultrasonic alternatives in routine procedures. Imaging systems, particularly cone beam CT configurations, concentrate value in specialty centers and academic institutions where complex surgical planning justifies higher capital outlays.
ANSM enforces Medical Device Regulation conformity for dental equipment placed on the French market, while CE marking under the EU MDR mandates updated clinical evaluation and post-market surveillance protocols that extend manufacturer compliance timelines. The French national health insurance system (Assurance Maladie) influences demand through its reimbursement schedules for prosthetic and orthodontic procedures, directing clinic investment toward qualifying device categories. Stakeholders must monitor how the EU AI Act classification criteria will affect software-enabled diagnostic tools and automated treatment planning modules entering French regulatory pathways.
Market Dynamics
Digital chairside workflows are compressing treatment timelines across French dental practices, forcing equipment vendors to bundle hardware with continuous software subscriptions rather than discrete capital sales.
Growth Catalysts
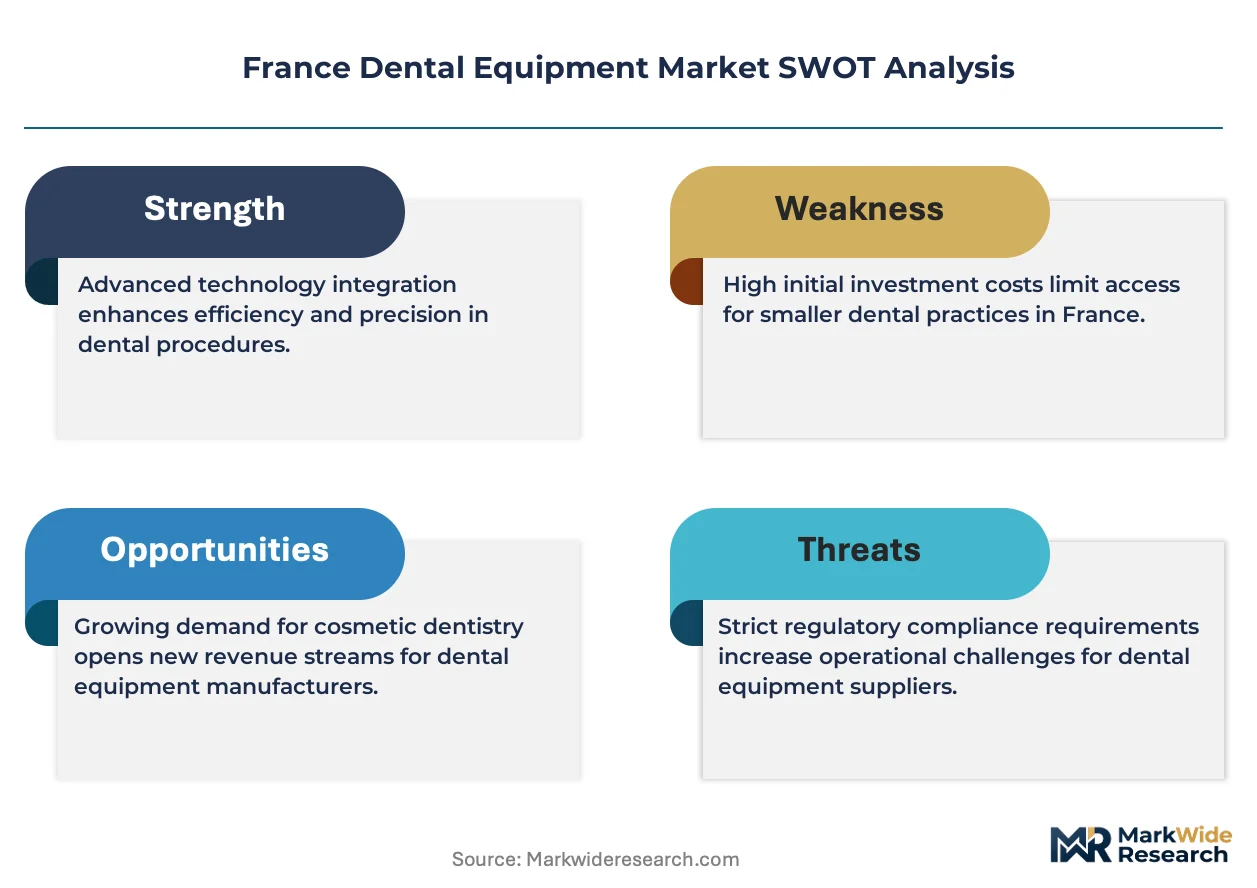
- EU Medical Device Regulation (MDR):Updated conformity assessment protocols for dental imaging systems are accelerating replacement cycles among French clinics seeking compliant device portfolios.
- Assurance Maladie reimbursement schedules:Prosthetic procedure coverage expansions in urban centers like Paris and Lyon are directing clinic investment toward qualifying CAD/CAM and milling equipment categories.
- Aging urban demographics:Concentrated demand from patients over 65 in Marseille and Nice is elevating prosthodontics and implantology service volumes requiring precision manufacturing tools.
Market Restraints
- Capital intensity barriers:Cone beam CT systems and chairside milling units require six-figure euro outlays that strain independent practitioners in secondary French cities.
- Supply concentration in German-speaking markets:Critical ceramic blanks and precision spindles for CAD/CAM workflows originate from concentrated Central European supplier networks vulnerable to logistics disruption.
- Technical workforce limitations:French dental technician training programs graduate insufficient numbers certified in digital design software, constraining chairside production throughput.
Strategic Opportunities
- Equipment-as-a-service models:Pay-per-scan and subscription-based intraoral scanner access are opening mid-sized Provence-Alpes-Côte d'Azur clinics previously excluded from digital workflows.
- AI-enabled diagnostic modules:Automated caries detection and treatment planning software integrated into imaging platforms are creating differentiated positioning ahead of EU AI Act classification implementation.
- Cosmetic dentistry expansion:Aesthetic procedure demand among younger demographics in Bordeaux and Toulouse is driving interest in advanced ceramic characterization ovens and digital smile design systems.
Industry Challenges
- MDR transition timelines:Extended clinical evaluation documentation requirements are delaying new product introductions and straining manufacturer regulatory affairs capacity.
- Legacy system integration:Practices with installed analog radiography and conventional impression workflows face workflow disruption and staff retraining costs when adopting digital platforms.
- Post-market surveillance obligations:Vigilance reporting mandates for software-enabled devices are imposing ongoing compliance costs that compress margins on entry-level equipment tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Dental Equipment Market |
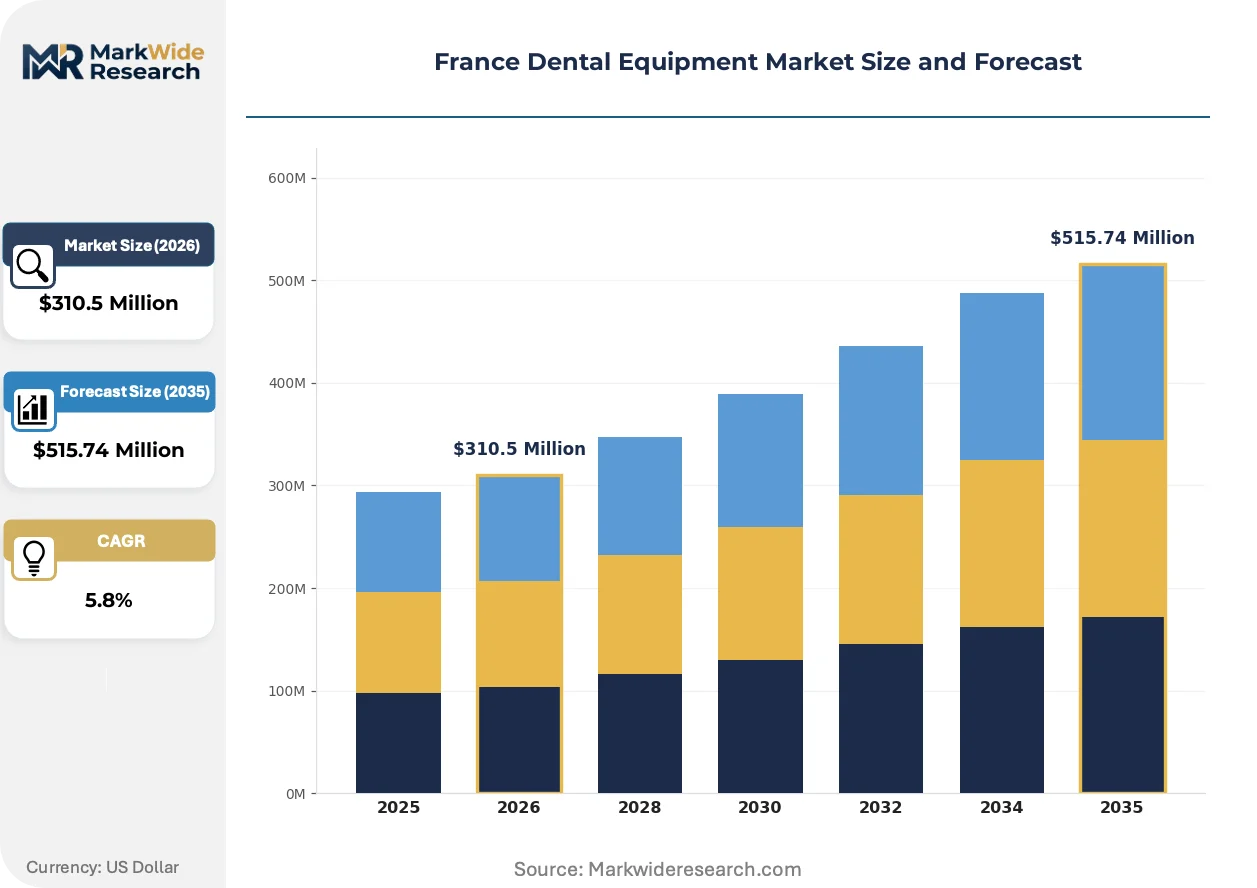
| Market Size in 2026 | $310.5 Million |
| Market Size in 2035 | $515.74 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraoral Scanners, Dental Lasers, CAD/CAM Systems, Autoclaves, Dental Chairs, Imaging Systems Technology: Digital Radiography, Cone Beam CT, 3D Printing, Ultrasonic, Optical Sensors, LED Curing Application: Orthodontics, Endodontics, Prosthodontics, Periodontics, Oral Surgery, Cosmetic Dentistry End User: Dental Clinics, Academic Institutions, Specialty Centers, Mobile Dentistry Units |
| Companies Covered | Straumann Holding AG, Ivoclar Vivadent AG, 3M Company, Septodont Holding, A-Dec, Carestream Dental Ltd, Dentsply Sirona Inc, Miglionico s.r.l., Planmeca Oy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Dental Equipment Market Shifts & Advancements
Convergence between diagnostic imaging and manufacturing execution is eliminating procedural handoffs that previously segmented French dental care delivery into discrete clinical and laboratory phases.
Intraoral scanning technology is virtualizing conventional physical impression workflows across Île-de-France private clinics. Single-visit crown fabrication is displacing two-appointment protocols with interim temporaries. Straumann and Dentsply Sirona service contracts are embedding these scanners into monthly operational budgets rather than capital expenditure cycles.
ANSM enforcement of EU MDR clinical evaluation requirements is extending manufacturer compliance timelines for new dental device introductions. Updated post-market surveillance protocols mandate systematic vigilance reporting for software-enabled diagnostic tools. French university hospitals and large clinic chains are prioritizing vendors with established notified body relationships and documented clinical evidence portfolios.
Mid-sized practices in Lyon and Marseille are unbundling after-sales service from equipment purchase contracts. Third-party technical support networks and independent software maintenance providers are capturing service revenue previously retained by original manufacturers. This fragmentation is compressing vendor service margins while expanding buyer negotiating leverage on multi-year agreements.
France Dental Equipment Market Segmentation
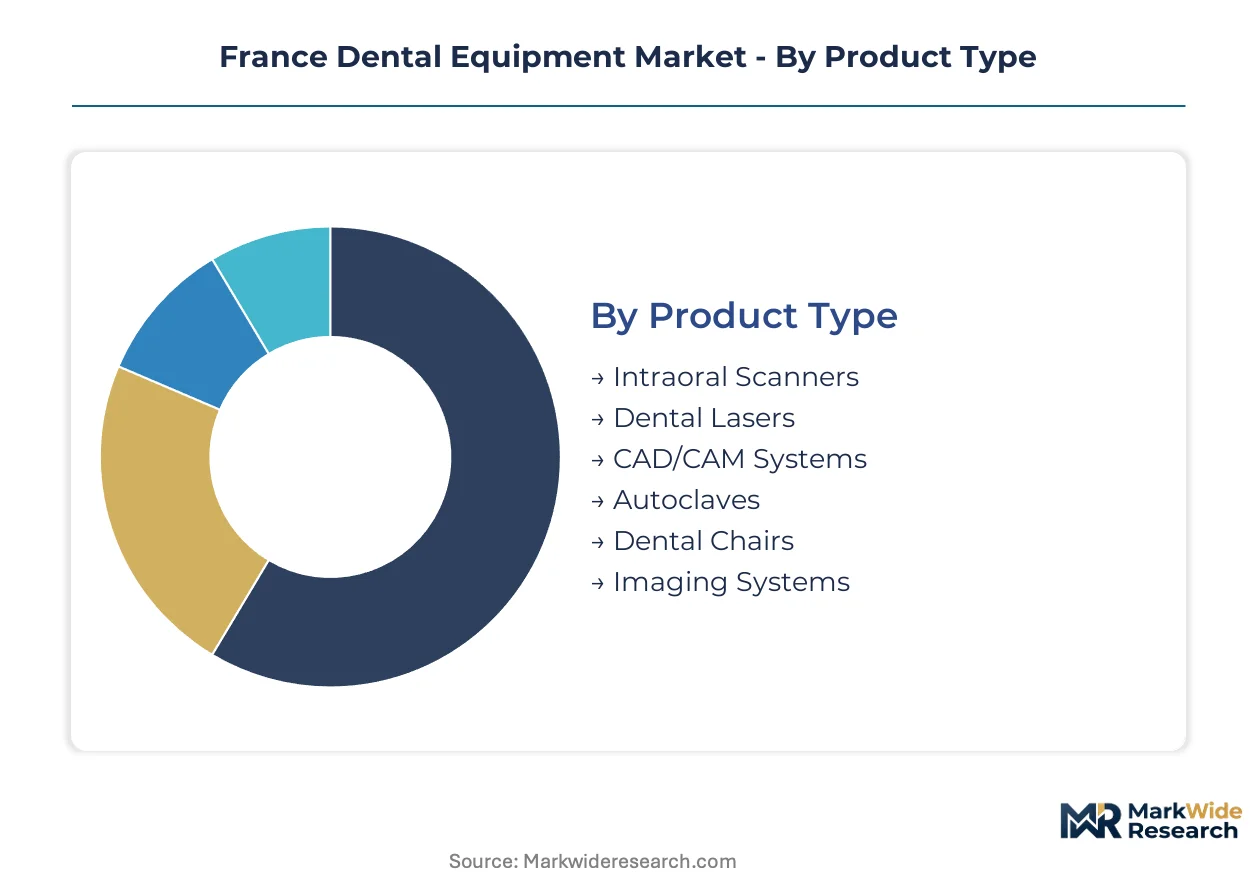
Equipment replacement cycles vary dramatically across French dental practices. Digital imaging platforms turn over every five to seven years while capital-intensive milling infrastructure remains installed for a decade. Understanding these differential rhythms helps vendors align financing, service contracts, and upgrade pathways to specific segment economics.
Product Type:
Replacement velocity separates high-turnover diagnostic peripherals from long-lived structural installations. Intraoral scanners and imaging systems refresh fastest as software capabilities obsolete hardware within five-year windows. Dental chairs and autoclaves demonstrate extended depreciation schedules stretching past twelve years in cost-conscious provincial practices.
- Intraoral Scanners:Handheld optical capture devices utilizing structured light or confocal microscopy to generate digital impressions with 10-micron accuracy. Demand concentrates among private Île-de-France clinics replacing polyether workflows, pressured by patient expectations for single-visit restorations. Software subscription bundling accelerates hardware refresh cycles beyond traditional capital planning horizons.
- CAD/CAM Systems:Chairside milling units and design stations executing subtractive manufacturing of zirconia, lithium disilicate, and hybrid ceramic restorations. Academic hospitals in Paris and Lyon anchor installed base concentration, though mid-sized Marseille practices increasingly adopt compact mill-only configurations to bypass laboratory outsourcing delays.
- Dental Lasers:Erbium and diode wavelength systems for soft-tissue incision and hard-tissue ablation occupy mature market positions with extended replacement timelines.
- Autoclaves:Steam sterilization chambers represent non-discretionary regulatory compliance equipment with fifteen-year operational lifespans in secondary city practices.
- Dental Chairs:Electromechanical patient positioning systems constitute the longest-lived installed base, refreshed only during complete clinic renovation cycles.
- Imaging Systems:Panoramic and cephalometric radiography units bridge diagnostic and treatment planning functions across mixed general-specialty practices.
Dental chairs dominate installed base by unit count. Intraoral scanners represent where expansion concentrates most rapidly.
Technology:
Capital intensity stratifies technology adoption across French practice tiers. Premium cone beam CT and metal-capable 3D printing concentrate in university-affiliated centers. Ultrasonic and LED curing technologies penetrate deepest into independent provincial clinics seeking functional capability without six-figure outlays.
- Digital Radiography:CMOS and CCD sensor-based intraoral imaging replacing analog film with immediate image acquisition and reduced radiation exposure. Provence-Alpes-Côte d'Azur specialty centers drive sensor replacement demand, motivated by ANSM vigilance reporting requirements for legacy device obsolescence.
- Cone Beam CT:Volumetric maxillofacial imaging systems generating sub-millimeter isotropic datasets for implant planning and orthodontic analysis. Paris and Lyon academic hospitals concentrate value, justifying capital expenditure through complex surgical case volumes and research protocols.
- 3D Printing:Photopolymerization and powder-bed fusion systems for surgical guide, model, and provisional fabrication.
- Ultrasonic:Piezoelectric scaling and cavity preparation devices with established reimbursement pathways through Assurance Maladie.
- Optical Sensors:Caries detection and transillumination technologies gaining traction in preventive-focused practices.
- LED Curing:Polymerization light sources with near-complete market penetration, now competing on irradiance consistency and battery longevity.
Digital radiography dominates installed base. Cone beam CT is where expansion concentrates.
Application:
Procedure reimbursement schedules from Assurance Maladie reshape equipment allocation across French dental disciplines. Prosthodontics and orthodontics command premium technology investment due to qualifying laboratory and appliance coverage. Periodontics and endodontics operate with tighter capital constraints, prioritizing durability over technological sophistication.
- Prosthodontics:Crown, bridge, and implant restoration workflows demanding precision manufacturing tolerances below 50 micrometers. Bordeaux and Toulouse private clinics concentrate demand for advanced ceramic characterization ovens, responding to younger patient aesthetic expectations and expanded ceramic coverage schedules.
- Cosmetic Dentistry:Veneer, whitening, and smile design procedures requiring digital planning software and shade-matching instrumentation. Urban centers with elevated discretionary income demonstrate strongest equipment procurement intensity.
- Orthodontics:Clear aligner and fixed appliance therapies with expanding digital workflow integration.
- Endodontics:Root canal treatment workflows utilizing apex locators, rotary instrumentation, and obturation systems.
- Periodontics:Soft-tissue management and regenerative procedures with mature equipment requirements.
- Oral Surgery:Extraction and implant placement procedures requiring specialized handpieces and physiologic monitoring.
Prosthodontics dominates installed base. Cosmetic dentistry is where expansion concentrates.
End User:
Purchasing authority and financing capacity diverge sharply across French dental delivery settings. Dental clinics operate with owner-operator decision velocity and equipment leasing access. Academic institutions navigate centralized procurement with extended vendor qualification timelines. Mobile dentistry units confront unique spatial and power constraints.
- Dental Clinics:Independent and small-group private practices constituting the volume foundation of French equipment demand. Mid-sized Provence-Alpes-Côte d'Azur clinics increasingly access digital workflows through pay-per-scan intraoral scanner subscriptions, circumventing capital barriers that previously excluded them from chairside manufacturing.
- Academic Institutions:University hospitals and dental schools with multi-year capital planning cycles and mandatory EU MDR documentation requirements. Paris, Lyon, and Marseille facilities prioritize vendors with established notified body relationships and published clinical evidence portfolios.
- Specialty Centers:Concentrated implantology and orthodontic practices with elevated case complexity justifying premium equipment configurations.
- Mobile Dentistry Units:Transportable delivery platforms serving rural and institutional populations with compact, ruggedized equipment specifications.
Dental clinics dominate installed base. Specialty centers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France dental equipment trade flows reflect a structural import dependency on German and Swiss precision manufacturing, with domestic production concentrated in medical device clusters around Lyon and Paris serving regional export markets into Belgium and Spain.
Île-de-France
Paris and its surrounding departments concentrate France's highest dental clinic density, driving demand for premium intraoral scanners and chairside CAD/CAM systems. ANSM enforcement of EU MDR clinical evaluation requirements accelerates replacement cycles among private practices seeking compliant device portfolios. The Paris-Saclay medical technology cluster anchors domestic distribution and technical service capabilities for imported equipment.
Auvergne-Rhône-Alpes
Lyon's position as France's second-largest metropolitan area supports elevated prosthodontics and implantology service volumes requiring precision manufacturing tools. The region's university hospital network prioritizes vendors with established notified body relationships and documented clinical evidence portfolios. Saint-Étienne's historical precision engineering base supplies specialized components for dental imaging systems.
Provence-Alpes-Côte d'Azur
Marseille and Nice serve aging demographics over 65, elevating demand for restorative and prosthetic procedures. Mid-sized clinics in this region increasingly access digital workflows through pay-per-scan intraoral scanner subscriptions, circumventing capital barriers that previously excluded them from chairside manufacturing. The Aix-Marseille University dental school anchors academic procurement for complex surgical planning equipment.
Nouvelle-Aquitaine
Bordeaux's younger demographic profile drives cosmetic dentistry expansion, with private clinics investing in advanced ceramic characterization ovens and digital smile design systems. Assurance Maladie reimbursement schedule expansions for aesthetic procedures in urban centers direct capital toward qualifying equipment categories. The region's lower clinic density per capita creates price sensitivity favoring equipment-as-a-service financing models.
Occitanie
Toulouse demonstrates similar cosmetic procedure demand patterns, with independent practitioners seeking mid-tier imaging and manufacturing platforms. Technical workforce limitations in digital design software constrain chairside production throughput across smaller practices in secondary cities. Regional equipment distributors emphasize training partnerships to address capability gaps.
France Dental Equipment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision subassemblies to finished device manufacturers. The France dental equipment market exhibits tiered concentration with Swiss and German multinationals anchoring premium positioning while Italian and regional specialists occupy mid-market segments. Two strategic archetypes dominate: full-workflow platform vendors bundling hardware with software subscriptions, and precision component suppliers capturing recurring revenue through consumable ceramic blanks and milling tools. Competitive moves center on service contract unbundling by third-party technical networks and pay-per-use financing partnerships expanding access to capital-constrained practices.
Among Swiss-based platform specialists, Straumann Holding AG and Ivoclar Vivadent AG exemplify divergent archetypes within the premium tier. Straumann represents the integrated implantology-to-restoration workflow model, while Ivoclar Vivadent occupies the materials and technical training specialization vector. Dentsply Sirona Inc, identifiable by its incorporated structure, anchors the American platform integrator position competing through bundled chairside CAD/CAM service contracts. These three entities collectively represent the geographic and strategic diversity pressuring mid-market positioning.
| Leading Market Players |
|---|
| Straumann Holding AG |
| Ivoclar Vivadent AG |
| 3M Company |
| Septodont Holding |
| A-Dec |
| Carestream Dental Ltd |
| Dentsply Sirona Inc |
| Miglionico s.r.l. |
| Planmeca Oy |
| Others |
Supply & Pricing Matrix
Undercapacity in precision spindle manufacturing across Baden-Württemberg is compressing lead times for French CAD/CAM vendors while simultaneously elevating input costs, forcing equipment manufacturers to choose between margin sacrifice and price pass-through to clinic buyers already strained by MDR compliance investments.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the France dental equipment market. Price differentiation hinges on ISO 13485 certification grade and bundled after-sales service intensity, with Assurance Maladie reimbursement eligibility serving as a secondary tiering mechanism. Cost compression in economy-tier imaging peripherals is intensifying because third-party technical support networks are unbundling service contracts from hardware sales. Independent practitioners in secondary French cities demonstrate highest price sensitivity, while university hospitals in Paris and Lyon show lowest sensitivity due to multi-year capital planning cycles and mandatory EU MDR documentation requirements.
Supply Chain Analysis
Contract manufacturing for dental imaging sensors concentrates in German and Swiss electronics foundries with ISO 13485-qualified cleanroom capacity. Geographic supply concentration centers on Germany, Switzerland, and Liechtenstein for precision mechanical components, with ceramic blanks sourcing extending into Austria. Raw material dependencies include rare-earth phosphors for digital radiography sensors, zirconia powders for milling substrates, and specialized optical glass for intraoral scanner lenses. Single-source vulnerability in ceramic spindle bearings creates exposure to logistics disruption through Alpine transit corridors. Distribution runs through Lyon-based medical device distributors serving clinic networks across southern France and into Belgium and Spain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France dental equipment market is emerging from a cyclical trough driven by EU MDR transition-related procurement freezes, with replacement cycle normalization now releasing pent-up demand for compliant imaging and manufacturing platforms.
For Market Incumbents: Build regulatory moats through notified body relationship depth and clinical evidence portfolio scale. Dentsply Sirona and Straumann should accelerate CE marking pathway investments for AI-enabled diagnostic modules ahead of EU AI Act classification implementation. Backward integration into ceramic blank manufacturing would reduce exposure to Central European supply concentration while capturing consumable recurring revenue from mid-sized French clinics.
For New Entrants and Emerging Players: Establish a beachhead in pay-per-scan equipment-as-a-service models targeting Provence-Alpes-Côte d'Azur mid-sized practices previously excluded from digital workflows. White-space opportunities concentrate in third-party technical support networks unbundling service from manufacturer contracts, and in compact mill-only configurations for Marseille clinics seeking laboratory bypass capability. A direct training partnership with French dental technician programs would differentiate against established vendors while addressing workforce certification gaps.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across subscription-based intraoral scanner segments, improving cash conversion and reducing customer concentration risk. Long-term viability favors platform integrators with software subscription attach rates above hardware financing penetration. Acquisition targets should demonstrate established ANSM regulatory affairs capacity and documented clinical evaluation portfolios. The signal to watch is Assurance Maladie reimbursement schedule expansion for aesthetic procedures, which would inflect capital allocation toward cosmetic dentistry equipment categories.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR clinical evaluation requirements are extending compliance timelines for new dental device introductions. |
| Equipment-as-a-Service Launch | Pay-per-scan models open mid-sized Provence-Alpes-Côte d'Azur clinics previously excluded from digital workflows. |
| Technical Training Partnership | Direct programs with French dental technician programs address workforce certification gaps constraining chairside throughput. |
| Backward Integration into Ceramics | In-house ceramic blank production reduces exposure to concentrated Central European supplier networks. |
| AI Diagnostic Module Development | Automated caries detection software creates differentiated positioning ahead of EU AI Act classification implementation. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with dental equipment procurement decision-makers and secondary validation against regulatory and reimbursement databases. Stakeholder interviews encompassed private clinic owners in Île-de-France and Provence-Alpes-Côte d'Azur, biomedical engineers at Lyon and Marseille university hospitals, GPO contracts managers serving French dental group practices, and regulatory affairs leads at notified bodies with dental device specialization. Secondary sources included ANSM vigilance reporting databases, Assurance Maladie reimbursement schedule documentation, EU MDR implementing act texts, and customs trade data for dental equipment imports. Bottom-up equipment unit economics were triangulated against top-down market sizing derived from national dental practice census data and capital expenditure surveys.
Forecast inputs incorporated replacement cycle dynamics across digital imaging platforms and long-lived structural installations, with segmentation modeling across product type, technology tier, application discipline, and end-user category. CAGRs were derived from regression analysis of historical procurement patterns against demographic and reimbursement drivers, validated through scenario testing of MDR transition timeline variations and AI Act implementation pathways. Industry-specific forecast inputs included dental technician graduation rates from French vocational programs and ANSM enforcement intensity metrics for post-market surveillance compliance.
Stress conditions across EU MDR transition delays, ceramic supply logistics disruption, and Assurance Maladie reimbursement schedule revisions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and demographic projection accuracy. Specific risks that could revise outlooks include accelerated EU AI Act classification for diagnostic software and unanticipated ANSM vigilance reporting mandate expansion. Quarterly review of notified body capacity utilization and ceramic blank spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
Dental Engine Market
Dental Equipment
Brazil Dental Equipment Market
Dental Equipment
Asia-Pacific Dental Equipment Market
Dental Equipment
Refurbished Dental Lab Equipment Market
Dental Equipment
Ultrasonic Dental Scalers Market
Dental Equipment
Dental 3D Printing Scanner Market
Dental Equipment
Europe Dental Equipment Market
Dental Equipment
Japan Dental Equipment Market
Dental Equipment
Digital Dental Equipment Market
Dental Equipment
Global Dental Milling Machine Market
Dental Equipment
Veterinary Dental (Dentistry) Equipment Market
Dental Equipment
Dental CAM Milling Machine Market
Dental Equipment
Dental Equipment and Maintenance Market
Dental Equipment
Dental Equipment and Consumables Market
Dental Equipment
Dental Lights Market
Dental Equipment
Dental Radiology Equipment Market