
 Asia-Pacific Dental Equipment Market | 2026-2036
Asia-Pacific Dental Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Dental Equipment Market Outlook
Ceramic-reinforced polymer is hardening its position against traditional metal alloys in dental handpiece construction, cutting unit weight and improving heat dissipation. Dentsply Sirona leverages its integrated manufacturing footprint to control supply timelines across Japan and Australia. Planmeca anchors its competitiveness through proprietary imaging software bundled with chairside CAD/CAM hardware.
Asia-Pacific dental equipment encompasses electromechanical instruments, diagnostic imaging systems, computer-aided design and manufacturing platforms, and patient seating infrastructure engineered for clinical ergonomics and infection control, typically operating at 20,000 to 400,000 RPM for rotary instruments and requiring autoclave sterilization compatibility. Dental imaging equipment commands the largest revenue pool given the capital intensity of cone-beam computed tomography systems, while 3D printing technology within the technology dimension is expanding fastest as chairside production of surgical guides and provisional restorations reduces laboratory turnaround. CAD/CAM technology spans both product type and technology segments, creating a margin concentration point where software licensing and consumable workflows generate recurring revenue streams.
Japan's PMDA and Australia's TGA enforce biocompatibility testing protocols under harmonized ISO 13485 quality management standards, raising compliance costs for new entrants but protecting incumbent manufacturers with established regulatory dossiers. China's NMPA requires in-country clinical evidence for imported Class III dental implants, favoring domestic producers and joint-venture structures. Stakeholders must monitor how India's proposed medical device rules alignment with ASEAN harmonization frameworks reshapes import pathways and local manufacturing incentives.
Market Dynamics
Chairside CAD/CAM integration is compressing laboratory turnaround times across Southeast Asian dental chains, forcing equipment vendors to bundle hardware with recurring software workflows rather than standalone device sales.
Growth Catalysts
- China's NMPA Class II fast-track:Registration timelines for imported dental imaging systems have shortened, accelerating market entry for CBCT manufacturers targeting tier-two city chains.
- Ceramic-reinforced polymer adoption:Private clinics in Thailand and Vietnam are specifying lightweight handpiece materials that improve clinician ergonomics during extended procedures.
- India's CDSCO medical device rules:Harmonization with ASEAN quality frameworks is streamlining import documentation for European and Japanese equipment suppliers.
Market Restraints
- Autoclave-grade alloy dependency:Stainless steel and titanium sourcing concentrates in Chinese and Japanese foundries, exposing handpiece manufacturers to input cost volatility.
- PMDA biocompatibility testing:Japan's premarket validation protocols add eighteen to twenty-four months to product launch timelines for polymer-based restorative materials.
- Laboratory outsourcing persistence:Milled zirconia crowns from centralized production facilities in Shenzhen and Bangkok undercut chairside unit economics for smaller clinic operators.
Strategic Opportunities
- Indonesia's archipelago distribution gap:Mobile dental units equipped with portable imaging and sterilization systems can capture demand in secondary cities beyond Java.
- 3D printing convergence with AI nesting:Surgical guide production workflows that optimize material usage per print job are reducing per-unit consumable costs for implantology practices.
- Australia's TGA tele-dentistry framework:Remote consultation regulations are creating demand for intraoral scanners that integrate with cloud-based treatment planning platforms.
Industry Challenges
- CAD/CAM technician scarcity:Dental schools in the Philippines and Malaysia are graduating insufficient operators proficient in both clinical dentistry and digital design software.
- Legacy chair integration:Electromechanical patient seating infrastructure from the 2010-2015 installation wave lacks data connectivity protocols required for modern imaging networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Dental Equipment Market |
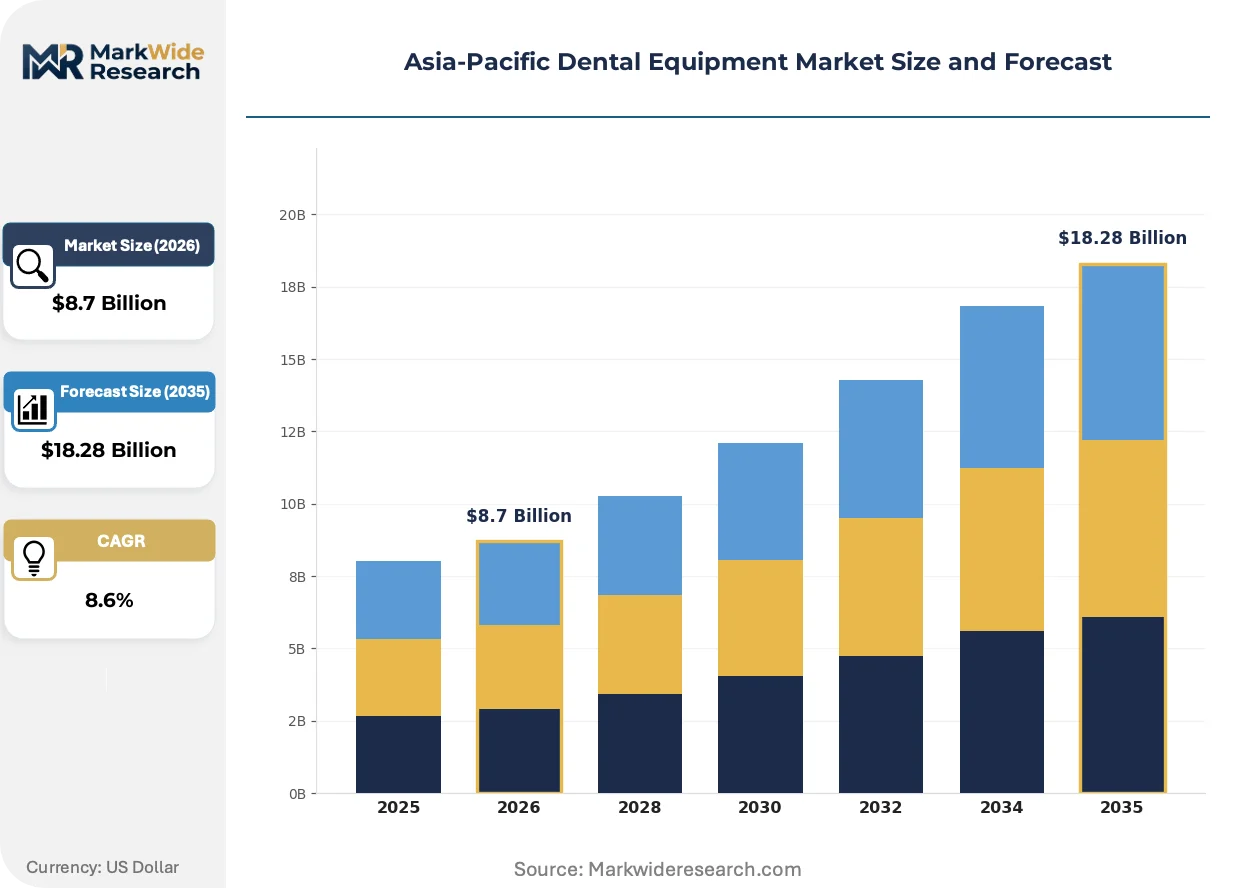
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $18.28 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dental Handpieces, Imaging Equipment, CAD/CAM, Dental Chairs Technology: Laser Dentistry, Digital X-Ray, CAD/CAM Technology, 3D Printing End User: Dental Clinics, Hospitals, Academic Institutions, Research Laboratories Service Type: Maintenance, Installation, Consulting, Training |
| Companies Covered | Dentsply Sirona, Straumann Holding AG, Planmeca, Align Technology Inc., GC Corporation, Carestream Health, 3M, Envista Holdings Corporation, A-dec Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Dental Equipment Market Strategic Shifts
Digital workflow unification is replacing modular equipment purchasing across Asia-Pacific dental chains, compressing vendor relationships toward single-source platform contracts.
Intraoral scanning hardware is converging with cloud-based treatment planning software to enable same-visit restorative workflows. Multi-location dental groups in South Korea and Australia are deploying these integrated systems to eliminate physical impression shipping. The technology is converging with chairside milling units, collapsing the traditional laboratory intermediary role into a software subscription layer.
China's NMPA is tightening clinical evidence requirements for Class III dental implants, mandating in-country patient data for imported devices. Domestic manufacturers in Jiangsu and Zhejiang provinces are accelerating biomaterial R&D to capture share previously held by European and US suppliers. Joint-venture structures between foreign brands and local distributors are proliferating to satisfy the regulatory pathway.
Consolidated procurement by dental service organizations is displacing individual clinic purchasing autonomy across China's tier-two cities. Chain operators in Chengdu, Xi'an, and Wuhan are negotiating enterprise-wide equipment leases that bundle maintenance, software updates, and consumable replenishment. This shift is most visible in diagnostic imaging, where CBCT deployment decisions now centralize at regional headquarters rather than practice level.
Asia-Pacific Dental Equipment Market Segmentation
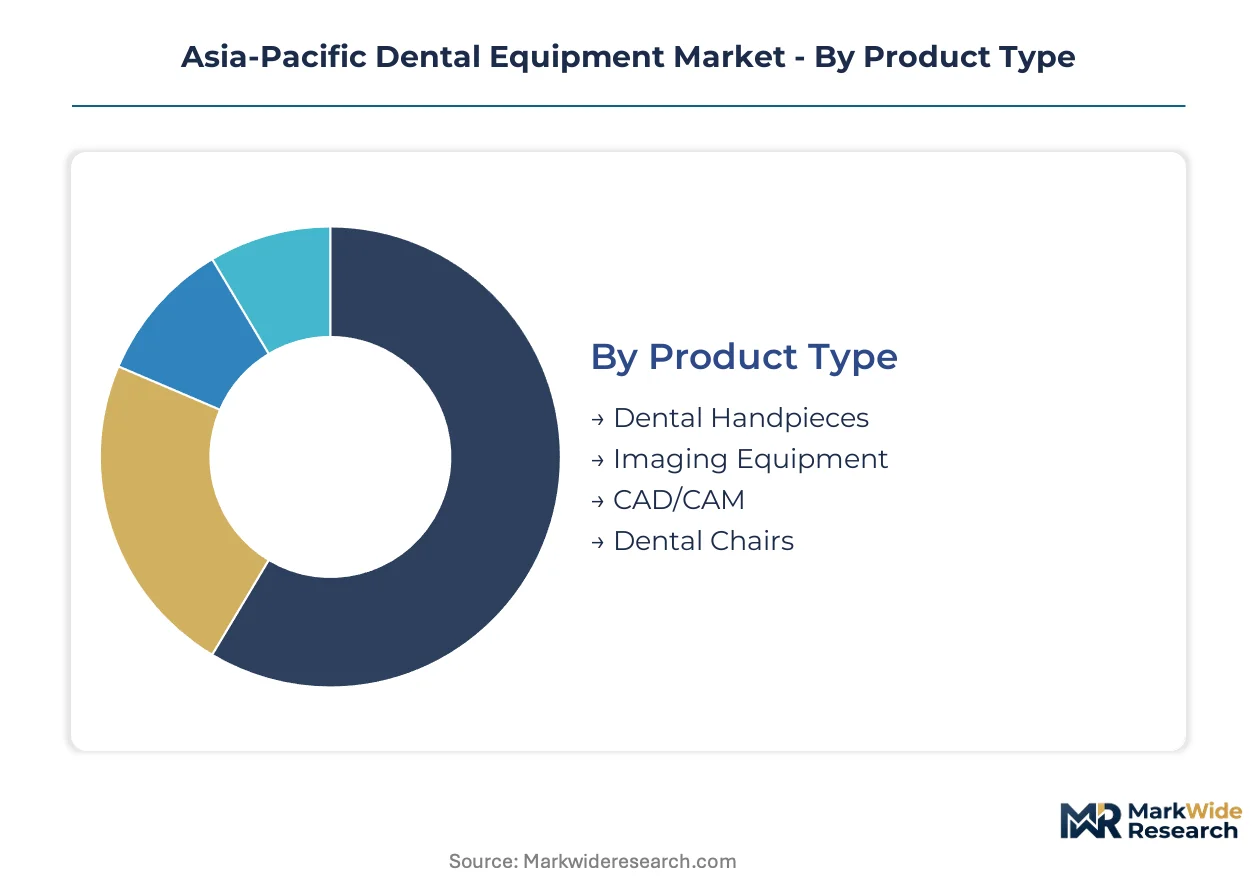
Dental equipment purchasing in Asia-Pacific fragments across clinical settings and technology generations, with replacement cycles varying dramatically between high-rotation handpieces and decade-scale imaging infrastructure. Understanding these segment boundaries clarifies where procurement budgets concentrate and which technologies are displacing legacy systems.
Product Type:
Replacement cycles drive divergent purchasing rhythms across product categories, with high-wear instruments demanding frequent refresh against capital-intensive platforms that anchor decade-long investment decisions.
- Dental Handpieces:Rotary instruments operating at 20,000 to 400,000 RPM incorporate ceramic-reinforced polymers to reduce unit weight and improve heat dissipation during extended procedures. Demand clusters in Thailand and Vietnam where private clinics specify lightweight materials for clinician ergonomics, though autoclave-grade alloy sourcing from Chinese and Japanese foundries exposes manufacturers to input cost volatility.
- Imaging Equipment:Cone-beam computed tomography systems command the largest revenue pool given capital intensity and software integration requirements. China's tier-two city dental chains are consolidating CBCT procurement decisions at regional headquarters in Chengdu, Xi'an, and Wuhan, compressing vendor negotiations toward enterprise-wide equipment leases.
- CAD/CAM:Chairside production platforms bundle hardware with recurring software workflows, collapsing the traditional laboratory intermediary into a subscription layer.
- Dental Chairs:Electromechanical patient seating from the 2010-2015 installation wave lacks data connectivity protocols required for modern imaging networks, forcing replacement decisions.
Volume placements concentrate in Dental Chairs; the faster expansion belongs to CAD/CAM.
Technology:
Technology adoption curves in Asia-Pacific dental practices stratify by clinical application maturity and regulatory clearance pathways, with some modalities already standard-of-care while others remain specialty-limited.
- Laser Dentistry:Soft and hard tissue lasers enable minimally invasive procedures with reduced bleeding and faster healing profiles. Adoption concentrates in South Korean and Australian multi-location dental groups where outcome-based procurement favors technologies that compress chair time and reduce postoperative complications.
- Digital X-Ray:Sensor-based radiography has displaced film across most urban clinics, with NMPA Class II fast-track registration accelerating deployment in China's secondary cities.
- CAD/CAM Technology:Digital design and milling workflows span both product type and technology segments, creating margin concentration through software licensing and consumable recurring revenue.
- 3D Printing:Surgical guide production with AI-optimized nesting algorithms is reducing per-unit consumable costs for implantology practices across the region.
Digital X-Ray holds the installed base majority; 3D Printing is climbing the fastest as chairside production eliminates laboratory turnaround.
End User:
End-user purchasing power and decision autonomy vary sharply across institutional settings, from centralized hospital procurement to independent clinic owner-operators.
- Dental Clinics:Private practice settings dominate equipment consumption, with Southeast Asian chains expanding chair counts and imaging capabilities. Indonesia's archipelago geography creates distribution gaps that mobile dental units with portable imaging and sterilization systems can capture beyond Java.
- Hospitals:Institutional procurement follows capital budget cycles with extended validation timelines, particularly under Japan's PMDA biocompatibility protocols.
- Academic Institutions:Training programs drive demand for equipment platforms that mirror commercial practice settings, though technician scarcity in Philippine and Malaysian dental schools constrains digital workflow proficiency.
- Research Laboratories:Specialized biomaterial and imaging research requires platforms with open architecture for protocol customization.
Procurement volume tilts toward Dental Clinics; Academic Institutions are gaining share fastest as curriculum modernization accelerates.
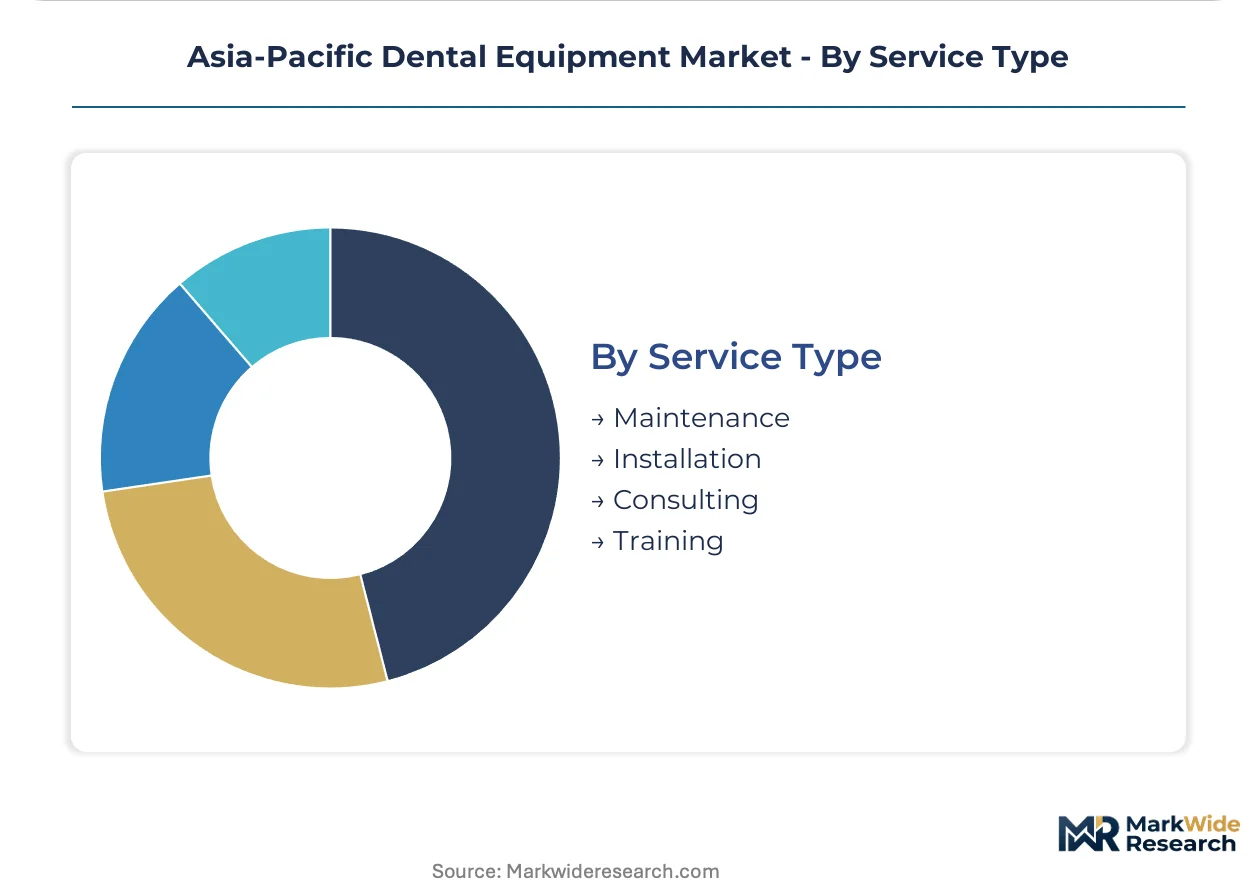
Service Type:
Service attach rates and contract structures increasingly determine lifetime customer value, with vendors competing on response time guarantees and predictive maintenance capabilities.
- Maintenance:Preventive service contracts covering calibration, sterilization validation, and component replacement secure recurring revenue streams. Australia's TGA tele-dentistry framework is creating demand for remote diagnostic capabilities that integrate with cloud-based treatment planning platforms.
- Installation:Physical deployment and network integration services carry premium pricing for imaging systems requiring specialized electrical and data infrastructure.
- Consulting:Workflow optimization and digital transformation advisory services attach most frequently to CAD/CAM and 3D printing platform sales.
- Training:Operator certification programs address the technician scarcity constraining chairside production adoption in the Philippines and Malaysia.
Maintenance contracts represent the revenue anchor; Training services are expanding most quickly as digital workflow complexity outpaces clinical education pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tier-two city dental chains concentrate procurement authority, while Southeast Asian private clinics expand chair counts and imaging capabilities. Regulatory acceleration through CDSCO harmonization and NMPA fast-tracks reshapes competitive entry timelines. Domestic manufacturers in Jiangsu and Zhejiang provinces capture implant market share previously held by European suppliers.
China
Dental service organizations in Chengdu, Xi'an, and Wuhan centralize CBCT deployment decisions at regional headquarters, compressing vendor negotiations toward enterprise-wide equipment leases. NMPA Class II fast-track registration shortens timelines for imported imaging systems. Domestic manufacturers in Jiangsu province accelerate biomaterial R&D to satisfy tightened clinical evidence requirements for Class III implants.
Japan
PMDA biocompatibility testing protocols add eighteen to twenty-four months to polymer-based restorative material launches, protecting incumbents with established dossiers. METI quality management standards under ISO 13485 raise compliance costs for new entrants. Tokyo and Osaka dental groups favor outcome-based procurement that compresses chair time and reduces postoperative complications.
India
CDSCO medical device rules harmonization with ASEAN quality frameworks streamlines import documentation for European and Japanese equipment suppliers. Private clinic expansion across Maharashtra and Karnataka drives demand for lightweight handpiece materials. Domestic distributors in Delhi-NCR and Mumbai negotiate service attach rates covering calibration and sterilization validation.
Australia
TGA tele-dentistry regulations create demand for intraoral scanners integrating with cloud-based treatment planning platforms. Multi-location dental groups in Sydney and Melbourne deploy integrated systems to eliminate physical impression shipping. Preventive maintenance contracts secure recurring revenue through remote diagnostic capabilities.
South Korea
MFDS regulatory pathways align with international standards for digital workflow platforms. Seoul-based dental chains adopt chairside CAD/CAM systems to collapse laboratory turnaround times. Busan-Ulsan manufacturing clusters supply ceramic-reinforced polymers for regional handpiece assembly.
Asia-Pacific Dental Equipment Market Competitive Environment
Strategic partnerships dominate the current landscape as vendors bundle hardware with recurring software workflows rather than standalone device sales. The vendor base stratifies across integrated platform providers, specialized imaging manufacturers, and regional equipment assemblers. Three archetypes anchor positioning: full-workflow integrators controlling supply timelines across multiple geographies; imaging-software bundlers leveraging proprietary CAD/CAM platforms; and lightweight-material specialists capturing ergonomic specification demand. Geographic expansion and technology licensing represent the dominant competitive vectors, with joint-venture structures proliferating to satisfy in-country clinical evidence requirements.
Among Switzerland-based holding companies, Straumann Holding AG exemplifies the premium-tier implant and digital workflow archetype. Finnish-origin Planmeca occupies a position within the imaging-software integration tier, while Dentsply Sirona represents the integrated manufacturing footprint archetype controlling supply timelines across Japan and Australia. These three anchors demonstrate how regulatory dossier depth and manufacturing geography determine competitive positioning in a market where procurement centralization favors vendors with comprehensive service architectures.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Straumann Holding AG |
| Planmeca |
| Align Technology Inc. |
| GC Corporation |
| Carestream Health |
| 3M |
| Envista Holdings Corporation |
| A-dec Inc. |
| Others |
Value Chain & Pricing Dynamics
China's tier-two city dental chains consolidating procurement authority at regional headquarters in Chengdu, Xi'an, and Wuhan forces supply responses toward enterprise-wide equipment leasing structures that compress unit margins while securing long-term service attach revenue.
Pricing Analysis
High-volume placements of dental chairs and handpieces operate on thin per-unit margins, while imaging equipment and CAD/CAM platforms command premium pricing through software licensing and consumable recurring revenue. Three-tier pricing structure across premium, standard, and economy levels separates NMPA-registered imported systems from domestic alternatives and refurbished units. Cost compression in the standard tier intensifies as Jiangsu and Zhejiang manufacturers scale biomaterial production. Smaller clinic operators in Indonesia and the Philippines exhibit highest price sensitivity, whereas Australian multi-location groups prioritize outcome-based procurement over upfront cost.
Supply Chain Analysis
Freight costs for CBCT systems and electromechanical chairs from German and Finnish manufacturing hubs concentrate margin pressure on landed equipment pricing. Autoclave-grade stainless steel and titanium feedstock draws from Chinese and Japanese foundries, while ceramic-reinforced polymers for lightweight handpieces source from Busan-Ulsan clusters. Single-source vulnerability in alloy sourcing exposes manufacturers to input cost volatility. Distribution runs through domestic distributors in Delhi-NCR and Mumbai who negotiate service attach rates covering calibration and sterilization validation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement centralization by dental service organizations across China's tier-two cities functions as a consolidation mechanism, squeezing standalone device vendors without integrated software workflows or comprehensive service architectures.
For Market Incumbents: Deploy proprietary imaging software bundling as the anchor lever to lock in multi-year enterprise contracts with Chengdu, Xi'an, and Wuhan dental chains. Deepen backward integration into ceramic-reinforced polymer production to secure handpiece margin control against Busan-Ulsan supply competition. Accelerate NMPA dossier maintenance to defend against Jiangsu and Zhejiang domestic manufacturers capturing Class III implant share through tightened clinical evidence requirements. For New Entrants and Emerging Players: Indonesia's archipelago geography creates an underserved mobile dental unit buyer archetype requiring portable imaging and sterilization systems beyond Java. Capture secondary city demand in Vietnam and Thailand through lightweight handpiece specifications that improve clinician ergonomics during extended procedures. Partner with established distributors in Delhi-NCR and Mumbai to leverage CDSCO harmonization with ASEAN quality frameworks for streamlined import documentation. For Investors and Strategic Acquirers: The window for entry favors imaging-software bundlers with established NMPA Class II fast-track pathways and recurring revenue architectures. Long-term viability hinges on regulatory dossier depth rather than hardware manufacturing scale alone. Monitor PMDA biocompatibility testing timeline extensions as an inflection indicator for polymer-based restorative material market access barriers protecting incumbent positions.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class II Fast-Track Registration | Shortens market entry timelines for CBCT manufacturers targeting tier-two city chains. |
| CAD/CAM Software Companion Development | Collapses laboratory intermediary role into subscription revenue layer for dental chains. |
| Joint Venture with Jiangsu Manufacturers | Satisfies in-country clinical evidence requirements for Class III dental implants. |
| Tele-dentistry Platform Integration | Aligns with Australia's TGA framework for remote consultation and cloud-based treatment planning. |
| Ceramic-Reinforced Polymer Manufacturing Scale-Up | Secures supply control for lightweight handpiece production serving Thai and Vietnamese clinics. |
Study Parameters
Trade customs records, NMPA registration databases, and CDSCO medical device filings formed the secondary backbone, supplemented by primary interviews with dental equipment procurement managers at Chinese dental service organizations, biomedical engineers at Australian multi-location groups, and regulatory affairs leads navigating PMDA biocompatibility protocols. Bottom-up equipment placement data from tier-two city chains triangulated against top-down market sizing from capital expenditure disclosures.
Historical trendline analysis of replacement cycles across handpiece, imaging, and CAD/CAM categories informed projection frameworks across the analysis window. Segmentation modeling incorporated product type, technology generation, end-user setting, and regulatory pathway complexity. CAGRs derived from equipment lease penetration rates, software attach coefficients, and biomaterial R&D investment trajectories specific to Jiangsu and Zhejiang manufacturing clusters.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA Class III evidence requirement tightening, PMDA testing timeline extensions, and CDSCO-ASEAN harmonization implementation pace. Forecasts reflect documented assumptions regarding procurement centralization velocity and ceramic-reinforced polymer adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
France Dental Equipment Market
Dental Equipment
Digital Dental Equipment Market
Dental Equipment
Europe Dental Equipment Market
Dental Equipment
Dental Equipment and Maintenance Market
Dental Equipment
Dental CAM Milling Machine Market
Dental Equipment
Veterinary Dental (Dentistry) Equipment Market
Dental Equipment
Dental Compressors Market
Dental Equipment
Brazil Dental Equipment Market
Dental Equipment
Global Dental Light Curing Equipment Market
Dental Equipment
Dental Simulator Market
Dental Equipment
Dental 3D Printing Scanner Market
Dental Equipment
Refurbished Dental Lab Equipment Market
Dental Equipment
Ultrasonic Dental Scalers Market
Dental Equipment
Dental Dust Collector Market
Dental Equipment
Japan Dental Equipment Market
Dental Equipment
Germany Dental Equipment Market