
 Red Orange Anthocyanin Extract Ingredients Market | 2026-2036
Red Orange Anthocyanin Extract Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Red Orange Anthocyanin Extract Ingredients Market Insights
Consolidation among functional food manufacturers is realigning procurement volumes toward fewer, larger contract buyers with stringent traceability requirements. Bionap S.r.l. anchors its position through Sicilian cultivation partnerships and controlled supply chains. Kalsec competes on extraction technology leadership for heat-sensitive anthocyanin preservation. Sensient Technologies extends its reach through global colorant distribution networks serving multinational food brands.
Red orange anthocyanin extract comprises water-soluble flavonoid pigments, primarily cyanidin-3-glucoside and delphinidin-3-glucoside, obtained through solvent extraction or supercritical CO2 processing at temperatures below 40°C to preserve chromophoric integrity. Powdered extract dominates current volume due to extended shelf stability and standardized color intensity for industrial batching. Liquid extract represents the fastest-growing product form as beverage manufacturers seek direct-pump dispensing systems. Food and beverage applications command the largest margin pool, though dietary supplements are gaining share as clinical validation of antioxidant bioavailability expands.
EU REACH and the F-Gas Regulation constrain solvent selection and extraction facility emissions across European production sites. EFSA colorant approval frameworks determine market access for novel extract formulations in food applications. Stakeholders must monitor evolving clean-label certification thresholds and solvent residue limits to maintain formulation eligibility across regulated jurisdictions.
Market Dynamics
Clean-label certification thresholds are compressing formulation windows for red orange anthocyanin extract suppliers, forcing simultaneous compliance with EU REACH solvent residue limits and EFSA colorant purity benchmarks while meeting beverage manufacturer demand for heat-stable natural colorants.
Growth Catalysts
- EFSA Colorant Framework Expansion:Novel food approval pathways for anthocyanin-rich extracts in fortified beverages are accelerating market access across EU member states. Manufacturers reformulate synthetic dye portfolios to capture clean-label positioning.
- Sicily Cultivation Cluster Density:Blood orange groves concentrated in the Catania and Enna provinces provide raw material proximity to extraction facilities. This geographic concentration reduces post-harvest degradation and stabilizes pigment yield consistency.
- Supercritical CO2 Processing:Low-temperature extraction technology preserves cyanidin-3-glucoside chromophoric integrity below 40°C. Food technologists specify this method for heat-sensitive applications in premium juice blends.
Market Restraints
- EU F-Gas Regulation Compliance:Solvent recovery system upgrades at extraction facilities require capital deployment to meet emissions thresholds. Smaller processors face facility consolidation or contract manufacturing dependence.
- Input Cost Volatility:Blood orange crop yields fluctuate with Mediterranean climate patterns, concentrating supply risk in Sicilian agricultural zones. Harvest shortfalls transmit directly to extract pricing volatility.
- Synthetic Colorant Substitution:Petroleum-derived alternatives maintain cost advantages in mass-market confectionery applications. Price-sensitive buyers delay natural extract adoption despite clean-label consumer preferences.
Strategic Opportunities
- Dietary Supplement Bioavailability Validation:Clinical trials demonstrating antioxidant absorption rates create formulation pull from nutraceutical brands. Capsule and tablet manufacturers seek standardized anthocyanin content for label claims.
- Liquid Extract Direct-Pump Systems:Beverage production lines integrate concentrated liquid formats for automated dosing. This format eliminates powder reconstitution steps and reduces batch-to-batch color variation.
- EU Green Deal Agricultural Incentives:Organic blood orange cultivation subsidies expand certified raw material supply. Extract processors secure premium positioning through organic supply chain documentation.
Industry Challenges
- Analytical Chemist Talent Scarcity:Specialized expertise in anthocyanin stability testing and HPLC quantification methods remains concentrated in Italian research institutions. Recruitment competition intensifies among Sicilian processors.
- Multi-Jurisdiction Certification Timelines:Parallel EFSA novel food dossiers and US FDA color additive petitions extend market entry cycles. Regulatory affairs teams manage divergent documentation requirements.
- Legacy Dye System Integration:Beverage manufacturers retrofit production lines designed for synthetic colorant handling. Equipment modification costs and cleaning validation protocols delay natural extract switching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Red Orange Anthocyanin Extract Ingredients Market |
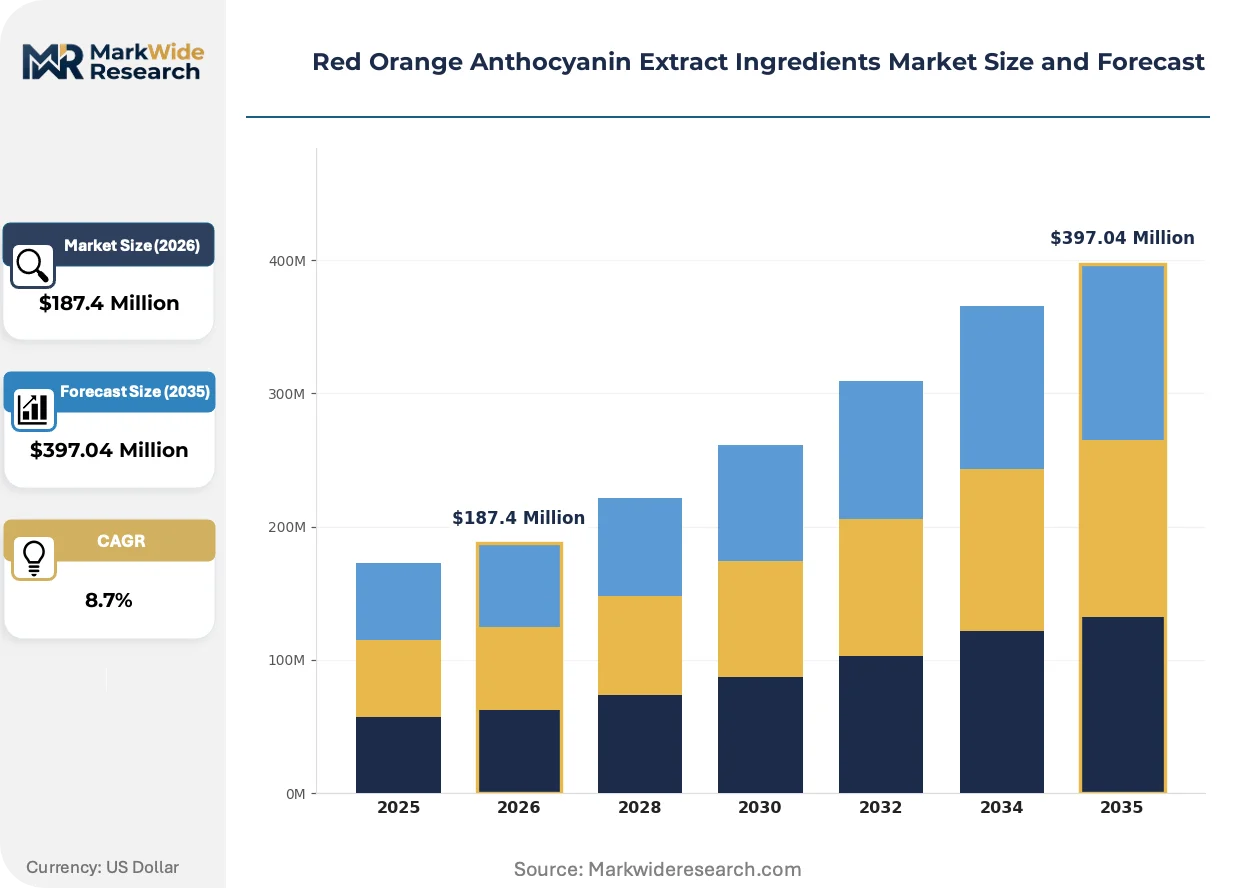
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Form: Liquid Extract, Powdered Extract, Concentrated Juice, Freeze-dried Powder, Granules Source Type: Red Orange Peel, Red Orange Pulp, Whole Fruit, Seeds, By-products Application: Food & Beverage, Dietary Supplements, Cosmetics, Pharmaceuticals, Animal Nutrition End User Industry: Functional Food Manufacturers, Nutraceutical Companies, Personal Care Brands, Pharmaceutical Firms, Pet Food Producers |
| Companies Covered | Bionap S.r.l., Branded Ingredients LLC, Native Extracts Pty Ltd, Natherm Group Sdn Bhd, Bioway (Xi'an Bioway Organic Ingredients Co., Ltd.), Sensient Technologies, Kalsec, GNT Group, California Natural Color, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Red Orange Anthocyanin Extract Ingredients Market Trends and Innovations
Extraction technology convergence with beverage manufacturing automation is compressing supply chain layers and redefining value capture points between Sicilian processors and multinational brand owners.
Supercritical CO2 extraction systems with integrated inline spectrophotometric monitoring are unifying quality control with production throughput. Mid-size beverage cooperatives in northern Italy adopt these units to bypass toll processing arrangements. Real-time pigment concentration measurement is compressing batch release timelines from days to hours.
EU REACH Annex XVII updates restricting residual solvent thresholds in food-contact extracts are forcing facility retrofits across Italian processing sites. ECHA compliance audits now mandate closed-loop solvent recovery exceeding 98% efficiency. Powder extract manufacturers serving confectionery applications face the steepest reformulation costs to meet tightened purity specifications.
Direct-procurement contracts between beverage brand technical teams and Sicilian extraction cooperatives are displacing traditional colorant distributor intermediaries. Multinational manufacturers establish annual volume commitments with named cultivation partnerships. This channel compression is most visible in German and French premium juice markets where traceability documentation carries shelf-price premiums.
Red Orange Anthocyanin Extract Ingredients Market Segmentation
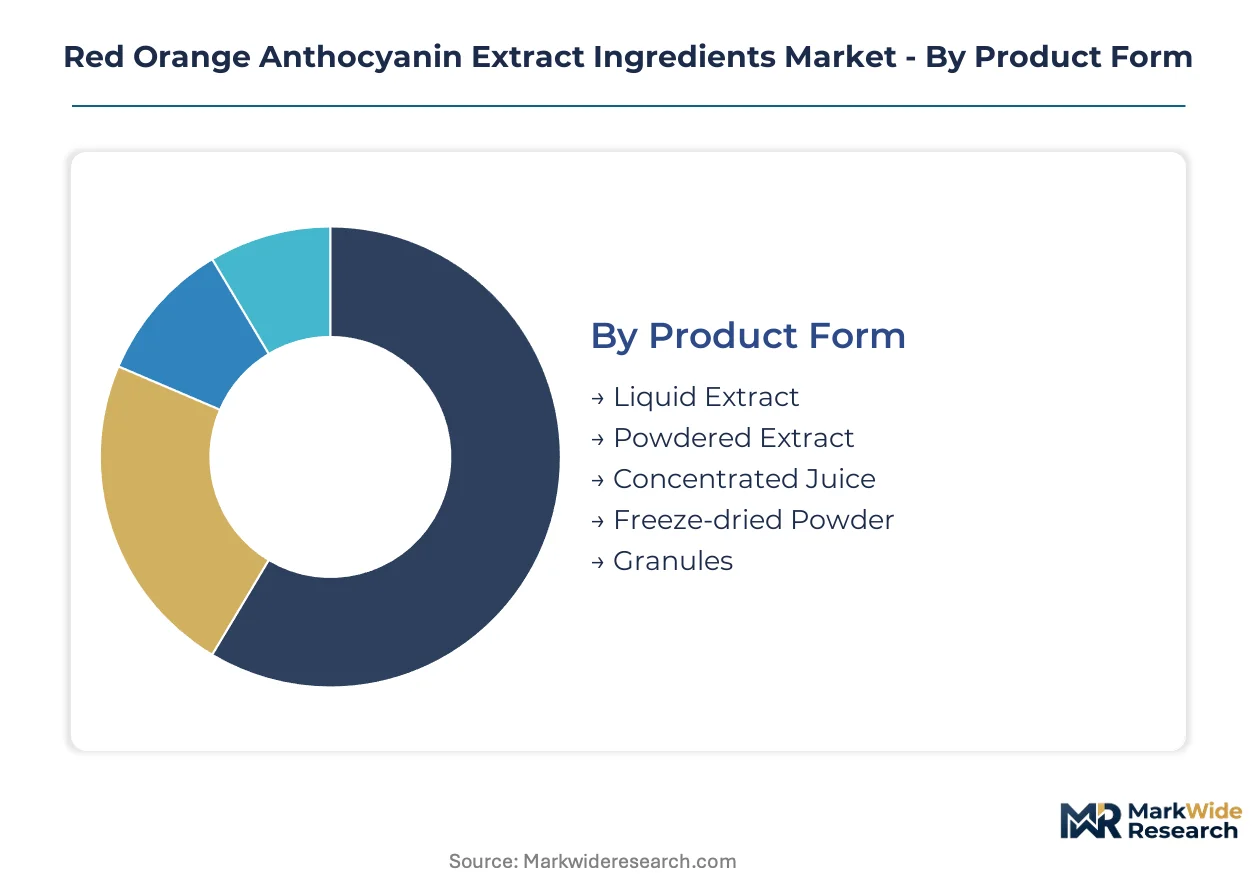
Procurement patterns across red orange anthocyanin extract diverge sharply by product stability requirements and clean-label certification thresholds. Formulators select formats based on heat sensitivity, shelf-life demands, and integration complexity with existing production lines.
Product Form:
Cost tier determines adoption sequencing, with premium extraction methods commanding technical specification from beverage and supplement manufacturers.
- Powdered Extract:Standardized cyanidin-3-glucoside content delivers consistent color intensity for industrial batching. Functional food manufacturers in Germany and France specify this format for confectionery and dry-mix applications where extended shelf stability outweighs reconstitution labor.
- Liquid Extract:Concentrated aqueous solutions enable direct-pump dispensing without powder hydration steps. Beverage cooperatives across northern Italy integrate these systems to compress batch release timelines and reduce color variation between production runs.
- Concentrated Juice:Minimal processing preserves volatile aromatic compounds alongside anthocyanin pigments. Premium juice blenders in Sicily source this format for single-origin positioning.
- Freeze-dried Powder:Lyophilization captures labile flavonoid structures at sub-zero temperatures. Dietary supplement capsule manufacturers specify this grade for bioavailability claims.
- Granules:Agglomerated particles improve flow properties for high-speed tableting operations. Nutraceutical contract manufacturers adopt this format to reduce capping and lamination defects.
Volume sits with Powdered Extract; growth tilts toward Liquid Extract.
Source Type:
Supply concentration in Sicily's Catania and Enna provinces shapes raw material access and post-harvest degradation risk.
- Red Orange Peel:Flavedo tissue concentrates the highest anthocyanin density per kilogram of input material. Extraction facilities adjacent to blood orange processing plants capture this stream to minimize pigment oxidation.
- Red Orange Pulp:Vesicle tissue delivers lower pigment concentration but carries food-grade status without additional purification. Juice manufacturers specify pulp-derived extracts for label simplicity.
- Whole Fruit:Homogenized processing maximizes yield per harvested ton. Integrated processors with captive orchard operations favor this approach to absorb crop quality variation.
- Seeds:Limonoid and flavonoid co-extraction creates dual-active ingredient potential. Cosmetic formulators in France explore this source for multifunctional antioxidant claims.
- By-products:Post-pressing pomace and wash-water streams offer lowest-cost raw material access. Smaller extraction cooperatives secure supply contracts with juice processors to offset Sicilian blood orange price volatility.
Procurement weight falls on Red Orange Peel; innovation attention clusters on By-products.
Application:
Margin structure varies by regulatory burden and clinical validation requirements across end-use categories.
- Food & Beverage:EFSA colorant approval frameworks govern formulation eligibility across EU member states. Clean-label positioning in German and French premium juice segments commands shelf-price premiums that absorb higher natural extract costs.
- Dietary Supplements:Clinical trials demonstrating antioxidant absorption rates create formulation pull from capsule and tablet manufacturers. Nutraceutical brands seek standardized anthocyanin content for compliant label claims.
- Cosmetics:Topical stability testing and skin penetration studies extend development timelines. Personal care brands specify microencapsulated formats to protect chromophoric integrity in emulsion systems.
- Pharmaceuticals:Drug-grade purity specifications and GMP documentation requirements constrain supplier qualification. Italian extraction facilities with pharmaceutical ingredient certifications capture this highest-margin tier.
- Animal Nutrition:Feed additive regulations under EU 1831/2003 determine market access for antioxidant claims in pet food applications. Premium pet food producers in Italy and Germany trial natural colorants for clean-label differentiation.
Revenue concentration favors Food & Beverage; expansion trajectory steepest in Dietary Supplements.
End User Industry:
Customer scale and technical capability determine contract structure, with multinational brands demanding named-cultivation traceability.
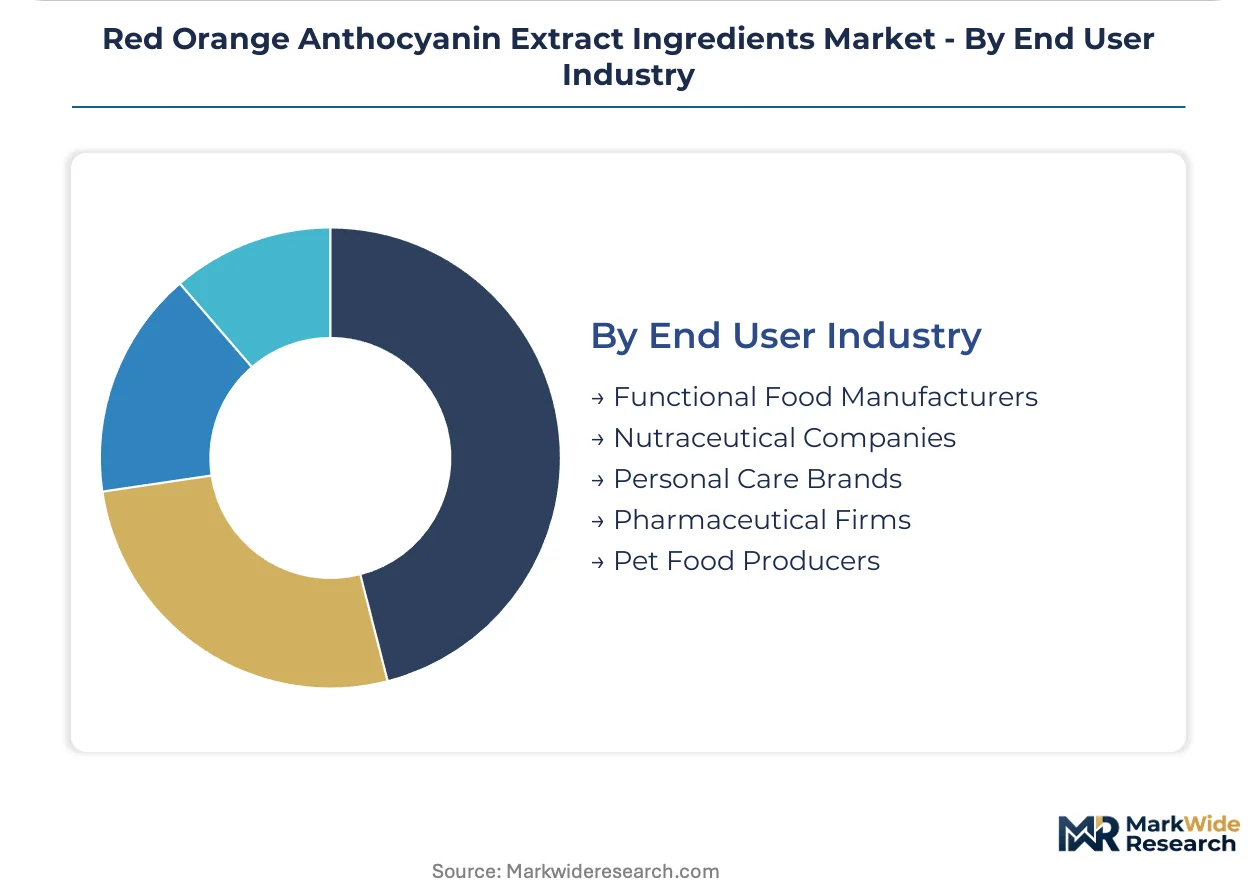
- Functional Food Manufacturers:Reformulation of synthetic dye portfolios accelerates procurement of heat-stable natural alternatives. Annual volume commitments with Sicilian extraction cooperatives displace traditional distributor relationships.
- Nutraceutical Companies:Standardized anthocyanin content specifications dominate technical requirements. HPLC quantification methods and certificate of analysis documentation are mandatory for batch release.
- Personal Care Brands:Microbiological stability and heavy metal testing extend supplier qualification cycles. French and Italian cosmetic houses specify organic supply chain documentation for premium positioning.
- Pharmaceutical Firms:Active pharmaceutical ingredient status requires complete supply chain audit trails. Only Italian processors with pharmaceutical-grade certifications qualify for this end user tier.
- Pet Food Producers:Palatability masking and oxidation protection drive formulation requirements. Premium segment producers in Germany test natural colorants against synthetic benchmarks for cost-performance tradeoffs.
Contract value concentrates with Functional Food Manufacturers; technical specification intensity peaks with Pharmaceutical Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration for red orange anthocyanin extract tilts toward European food and beverage manufacturers, with Italian cultivation clusters supplying the dominant share of raw material inputs. Clean-label reformulation pressures in Germany and France are accelerating contract volumes with Sicilian processors. Regulatory compliance timelines vary across jurisdictions, shaping market entry sequencing for extract suppliers.
Italy
Premium juice blenders in Milan and Bologna drive liquid extract procurement for automated production lines. EFSA colorant approval frameworks govern formulation eligibility for fortified beverage applications. Blood orange groves concentrated in Catania and Enna provinces anchor extraction facility proximity, minimizing post-harvest pigment degradation.
Germany
Functional food manufacturers in Bavaria and Baden-Württemberg reformulate synthetic dye portfolios to capture clean-label positioning. EU REACH Annex XVII solvent residue limits constrain supplier qualification cycles. Munich-based beverage cooperatives establish direct-procurement contracts with Sicilian extraction cooperatives, displacing traditional distributor relationships.
France
Cosmetic formulators in Grasse and Paris explore seed-derived extracts for multifunctional antioxidant claims. ANSM stability testing requirements extend development timelines for topical applications. Personal care brands specify organic supply chain documentation, leveraging EU Green Deal agricultural incentives for certified raw material sourcing.
United States
Dietary supplement manufacturers in California and Utah seek standardized anthocyanin content for compliant label claims. FDA color additive petition timelines run parallel to EFSA dossiers, extending market entry cycles. West Coast nutraceutical brands trial freeze-dried powder formats for bioavailability positioning in capsule applications.
Australia
Native Extracts Pty Ltd anchors regional supply through botanical extraction specialization. TGA therapeutic goods regulations determine market access for antioxidant claims in complementary medicines. Sydney and Melbourne-based natural health product manufacturers specify HPLC quantification methods for batch release documentation.
Red Orange Anthocyanin Extract Ingredients Market Competitive Landscape
Italian producers anchor the premium extraction tier; North American and Asian specialists hold complementary positions in distribution and scale processing. Market structure consolidates around cultivation-proximate processors with captive orchard relationships and toll manufacturers serving multinational brand technical specifications. Three archetypes dominate: Sicilian integrated cultivator-processors, global colorant distributors with extraction technology licensing, and regional botanical extract specialists serving nutraceutical contract manufacturers. Competitive intensity centers on backward integration into blood orange cultivation and supercritical CO2 processing capacity expansion.
Within the integrated cultivation tier, Bionap S.r.l. exemplifies geographic concentration through Sicilian partnership structures. Sensient Technologies and Kalsec occupy positions bridging extraction technology leadership with multinational distribution reach. GNT Group represents the botanical specialist archetype with European colorant portfolio diversification. California Natural Color anchors West Coast supply proximity for US dietary supplement manufacturers. These company patterns reflect procurement consolidation toward fewer contract buyers demanding named-cultivation traceability documentation.
| Leading Market Players |
|---|
| Bionap S.r.l. |
| Branded Ingredients LLC |
| Native Extracts Pty Ltd |
| Natherm Group Sdn Bhd |
| Bioway (Xi'an Bioway Organic Ingredients Co., Ltd.) |
| Sensient Technologies |
| Kalsec |
| GNT Group |
| California Natural Color |
| Others |
Pricing and Supply Chain Analysis
Family-owned Sicilian extraction cooperatives anchor supply-side ownership structures, transmitting blood orange crop volatility directly into contract pricing discipline through captive orchard relationships and limited external financing buffers.
Pricing Analysis
Volume concentration in powdered extract formats competes with margin expansion in liquid and freeze-dried grades serving premium beverage and nutraceutical applications. Price differentiation rests on EFSA colorant certification tier and supercritical CO2 processing method, with pharmaceutical-grade specifications commanding substantial premiums over food-grade alternatives. Cost compression in standard powdered extracts is intensifying because synthetic colorant substitution pressure from mass-market confectionery buyers limits pass-through of Sicilian harvest shortfalls. Beverage manufacturers demonstrate lowest price sensitivity due to clean-label shelf-price premiums, while commodity confectionery processors resist natural extract adoption at current price points.
Supply Chain Analysis
EU REACH Annex XVII compliance and EFSA novel food qualification gates filter supplier participation, concentrating viable extraction capacity among Italian processors with documented closed-loop solvent recovery systems. Geographic supply concentrates in Italy, with secondary processing nodes in Germany and France serving formulation and distribution functions. Raw material dependencies center on Sicilian blood orange peel, supercritical CO2 supply, and pharmaceutical-grade packaging materials. Single-source vulnerability runs through Catania-Enna cultivation clusters exposed to Mediterranean climate disruption. Distribution runs through direct-procurement contracts displacing traditional colorant distributor intermediaries, particularly in German and French premium juice markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EU F-Gas Regulation compliance costs and EFSA certification timelines force sub-scale processors into contract manufacturing dependence or exit.
For Market Incumbents: Deepen backward integration into certified organic blood orange cultivation to lock in raw material access ahead of EU Green Deal subsidy expiration. Expand supercritical CO2 capacity in Sicily to capture toll processing demand from smaller competitors unable to fund facility retrofits. Secure multi-year offtake agreements with German beverage cooperatives before distributor relationships fully dissolve.
For New Entrants and Emerging Players: Direct-procurement platform routes targeting mid-size Italian beverage cooperatives bypass established distributor gatekeepers. White-space opportunities concentrate in freeze-dried powder formats for US dietary supplement manufacturers seeking bioavailability positioning, and in by-product pomace extraction serving cost-sensitive cosmetic formulators. A technical sales team with HPLC quantification expertise accelerates supplier qualification timelines.
For Investors and Strategic Acquirers: Distressed-cycle entries favor Sicilian processors with EFSA colorant approvals and pharmaceutical-grade certifications facing working capital constraints from harvest volatility. Long-term viability hinges on five-to-ten year clean-label trend persistence in European premium food segments. The signal to watch is EFSA novel food dossier approval velocity for anthocyanin-rich extract formulations, which would expand addressable application scope.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Captures EU Green Deal subsidies and secures premium supply chain documentation for multinational buyers. |
| Supercritical CO2 Capacity Expansion | Preserves cyanidin-3-glucoside integrity below 40°C for heat-sensitive beverage applications. |
| Direct-Procurement Platform Launch | Displaces traditional colorant distributors in German and French premium juice markets. |
| Pharmaceutical-Grade Certification Investment | Unlocks highest-margin tier serving Italian drug manufacturers with GMP documentation requirements. |
| By-Product Pomace Processing Scale-Up | Absorbs Sicilian blood orange price volatility through lowest-cost raw material stream capture. |
Research Methodology
EFSA colorant approval databases, EU REACH Annex XVII regulatory filings, and Italian agricultural statistics formed the secondary backbone, cross-referenced against primary interviews with extraction facility technical directors, beverage cooperative procurement managers, and nutraceutical contract manufacturing executives. Bottom-up volume estimates derived from Sicilian blood orange cultivation data and extraction yield ratios were reconciled with top-down spending patterns from functional food manufacturer reformulation budgets.
Bottom-up modeling tracked product form, source type, and application segment demand across the projection horizon, while top-down validation assessed clean-label reformulation penetration in European premium food categories. CAGRs were derived from segment-level volume trajectories and price evolution assumptions. Forecast inputs incorporated EFSA novel food approval timelines, supercritical CO2 processing capacity expansion schedules, and synthetic colorant substitution elasticity in mass-market segments.
The model holds under stable EU regulatory frameworks; deviation in EFSA colorant purity benchmark revisions or F-Gas Regulation enforcement intensity would shift supply-side participation and pricing trajectories. Forecasts reflect documented assumptions regarding Sicilian cultivation yields and beverage manufacturer clean-label commitment persistence. A model refresh is warranted upon material change in EFSA novel food dossier approval velocity or Mediterranean climate pattern disruption severity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cocoa Maker Market
Ingredients
Global Malt Extracts and Ingredients Market
Ingredients
Home Baking Ingredients Market
Ingredients
Chickpea Protein Ingredients Market
Ingredients
Sugared Egg Yolk Market
Ingredients
Pulses Ingredients Market
Ingredients
Yeast Derivatives Market
Ingredients
Honey Powder Market
Ingredients
Vital Wheat Gluten Market
Ingredients
United Kingdom Protein Market
Ingredients
Europe Dairy Protein Market
Ingredients
Organic Starch Market
Ingredients
Europe Alcohol Ingredients Market
Ingredients
Soy Peptones Market
Ingredients
North America and Europe Coconut Derivatives Market
Ingredients
Hemp Seed Peptide Market