
 Cocoa Maker Market | 2026-2036
Cocoa Maker Market Size, Share, and Industry Trends Forecast 2026-2036
Cocoa Maker Market Outlook
Ivory Coast is reshaping upstream cocoa processing capacity with new government-backed industrial zones. Barry Callebaut AG leverages integrated grinding and conching operations across Abidjan and San Pedro to sustain supply chain control. Cargill Incorporated anchors West African sourcing through licensed buying operations and quality certification programs. Nestlé S.A. competes with proprietary tempering protocols that extend into artisanal equipment partnerships.
A cocoa maker is an electromechanical processing unit designed to roast, grind, conch, and temper cocoa beans into liquid chocolate or cocoa mass, typically operating at temperatures between 45°C and 80°C with precision particle-size reduction below 20 microns for smooth mouthfeel. The machine serves commercial confectionery production by transforming raw fermented beans into standardized inputs for chocolate bars, couverture, and industrial coatings. Bean-to-bar machines attract craft producers seeking origin-traceable output, while continuous cocoa makers dominate large-scale manufacturers prioritizing throughput over flexibility. Conching technology leads in premium positioning because extended aeration develops flavor complexity that commands higher finished-product pricing.
FDA food-contact substance regulations and EU Green Deal energy-efficiency directives constrain equipment design choices on both sides of the Atlantic. BIS certification requirements in India add compliance layers for imported machinery, while CE marking remains mandatory for European market access. Stakeholders must weigh regional certification burdens against localized assembly strategies when allocating capital across manufacturing footprints.
Market Dynamics
Bean-to-bar craft chocolate is fragmenting demand toward small-batch equipment, while EU Green Deal energy mandates force redesigns of thermal processing systems across all manufacturer tiers.
Growth Catalysts
- EU Green Deal energy-efficiency mandates:Tightening standards for food-processing machinery are accelerating replacement cycles in European confectionery operations.
- Artisan chocolate craft movement:Origin-traceable production is pulling demand toward compact, flexible processing units with batch-level control.
- Germany:Precision-engineered cocoa processing equipment commands premium positioning as confectionery manufacturers prioritize particle-size consistency below 20 microns.
Market Restraints
- Cocoa butter price volatility:Input cost swings compress margins for equipment buyers dependent on commodity-linked financing.
- West African supply concentration:Licensed buying operations cluster in Ivory Coast and Ghana, creating single-source exposure for grinding capacity expansion.
- CE marking complexity:Extended certification timelines for thermal systems delay European market entry by 8-14 months.
Strategic Opportunities
- India BIS certification pathway:Localized assembly strategies can bypass import duty layers while serving subcontinent confectionery growth.
- Conching-temper integration:Combined aeration and crystallization units reduce footprint for urban artisan producers.
- Renewable thermal systems:Heat pump retrofits for roasting drums align with EU Green Deal incentives and carbon border adjustments.
Industry Challenges
- Conching specialist scarcity:Flavor development expertise requires 5-7 year apprenticeship pipelines that equipment vendors cannot replicate.
- Legacy tempering protocol incompatibility:Proprietary chocolate crystallization methods resist standardization across bean-to-bar and industrial systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cocoa Maker Market |
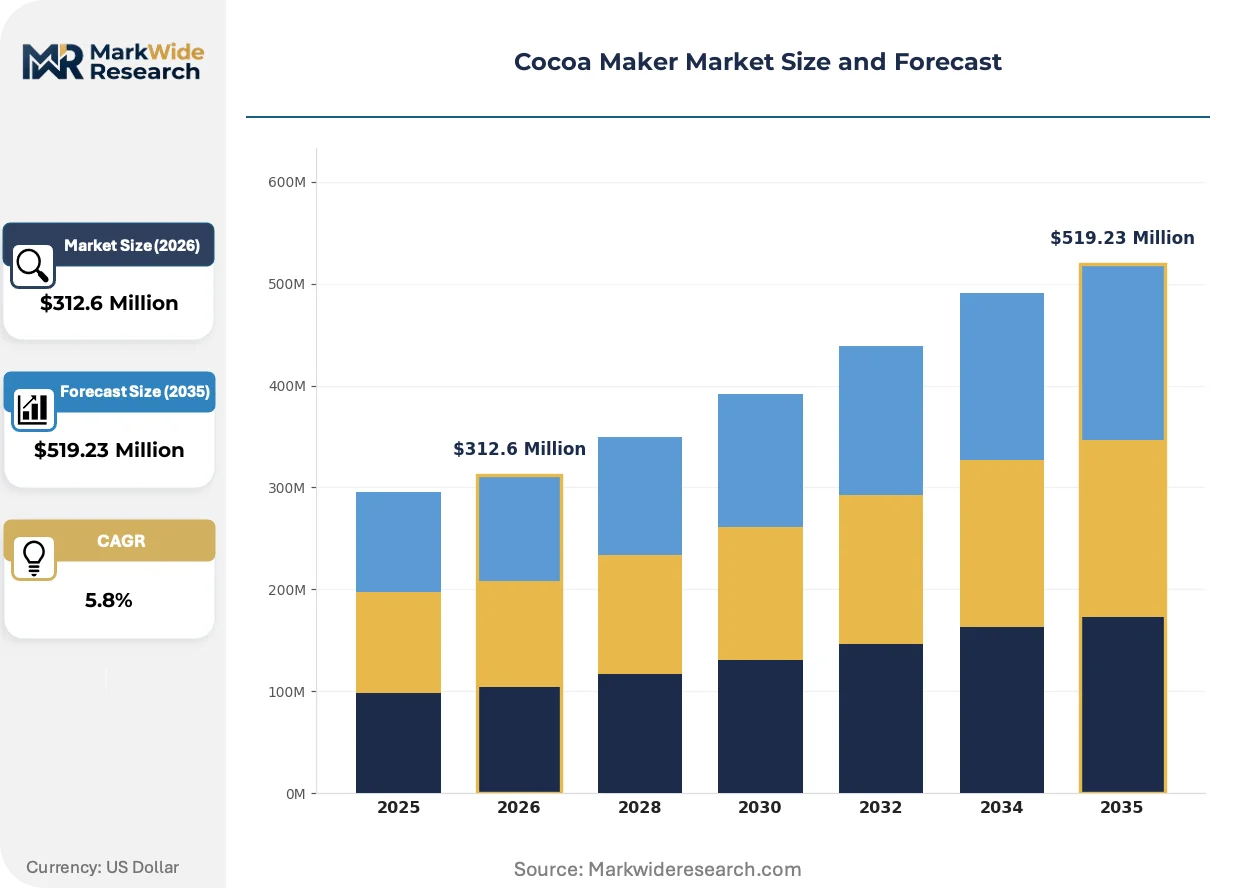
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $519.23 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Cocoa Maker, Continuous Cocoa Maker, Bean-to-Bar Machine, Melanger Technology: Conching, Roasting, Grinding, Tempering End User: Artisan Chocolate Makers, Large Scale Manufacturers, Confectionery Companies, Food Service Application: Chocolate Production, Beverage Manufacturing, Bakery Products, Snack Foods |
| Companies Covered | Barry Callebaut AG, Cargill Incorporated, Nestlé S.A., Mondelez International, Mars Incorporated, Olam International, Ferrero Group, Hershey Company, Guan Chong Berhad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cocoa Maker Market Strategic Shifts
Digital control layers are penetrating thermal processing equipment, compressing the expertise gap between artisan and industrial production while regulatory pressure reshapes energy architecture.
Sensor-integrated roasting control is virtualizing operator judgment through real-time bean-moisture feedback and automated airflow modulation. Small-batch manufacturers in Belgium and Switzerland are adopting these systems fastest. This capability is virtualizing the traditional roastmaster role, enabling consistent flavor profiles without decade-long training investments.
EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in chocolate tempering systems, forcing heat pump and CO2-based cooling retrofits. Equipment manufacturers must redesign thermal exchange architectures to maintain precision within 0.5°C setpoints. Confectionery multinationals with centralized European production are absorbing compliance costs fastest, while distributed artisan operators face equipment obsolescence risk.
Direct-to-maker equipment financing is displacing traditional distributor credit arrangements as craft producers seek asset-light entry. Specialty lending platforms in the Netherlands and California are underwriting small-batch machinery against projected couverture output rather than balance sheet strength. This channel innovation is most visible among origin-traceable chocolate startups prioritizing bean provenance over brand heritage.
Cocoa Maker Market Segmentation
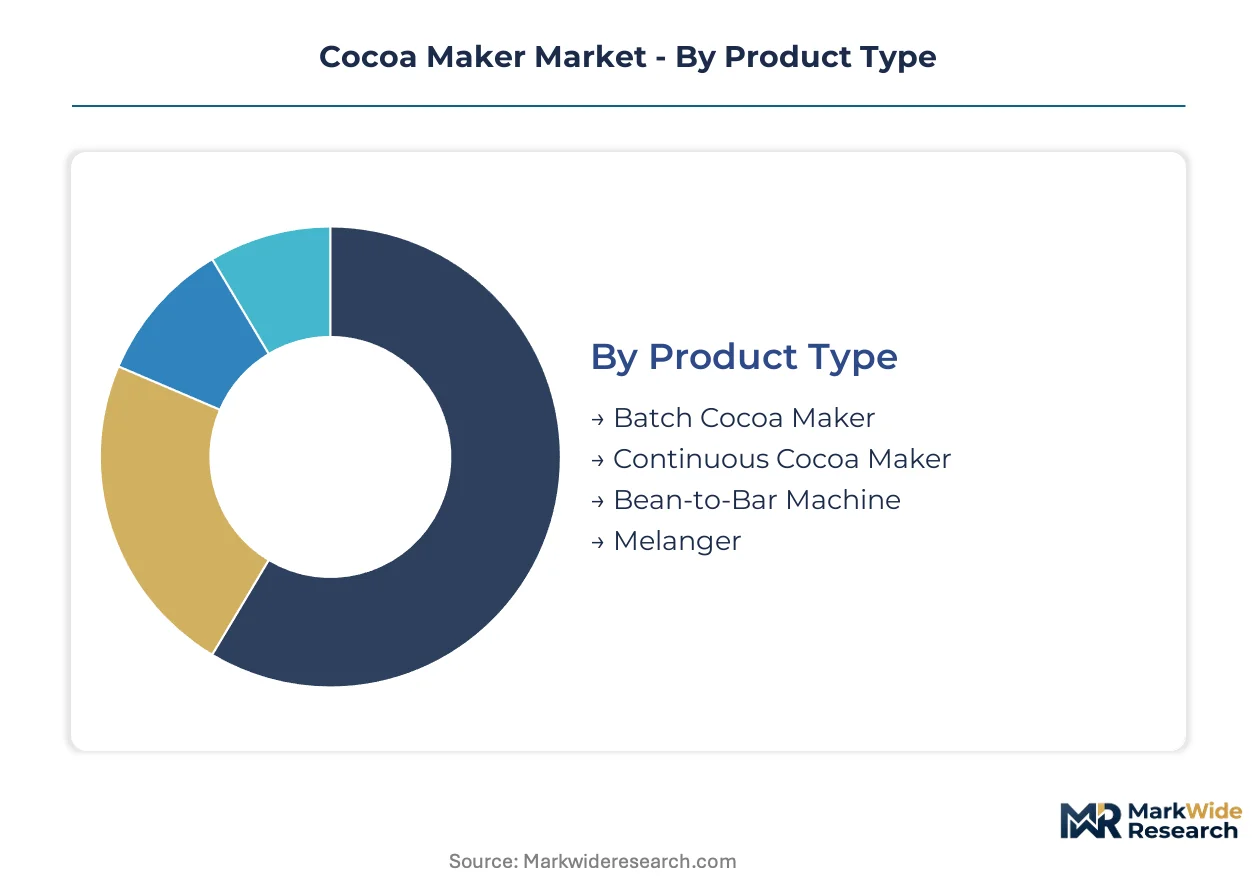
Cocoa maker segmentation reflects divergent processing philosophies between craft precision and industrial throughput. Equipment categories map directly to capital intensity thresholds and flavor-development priorities across the confectionery value chain.
Product Type:
Mature industrial formats coexist with emerging craft configurations as production scale fragments across the market.
- Batch Cocoa Maker:Discontinuous processing units operate on timed roasting and grinding cycles with manual transfer between stages. Artisan chocolate makers in Belgium and Switzerland concentrate demand here for origin-specific recipe development.
- Continuous Cocoa Maker:Integrated flow systems maintain uninterrupted bean-to-mass processing at sustained thermal profiles. Large scale manufacturers prioritize these units for couverture standardization and throughput maximization.
- Bean-to-Bar Machine:Compact all-in-one systems combine cracking, winnowing, grinding, and conching in footprint-optimized configurations. Equipment financing platforms in California and the Netherlands underwrite these units against projected output rather than balance sheet strength.
- Melanger:Stone-wheel grinding vessels reduce particle size through shear friction at controlled temperatures. Food service operators and micro-batch producers adopt these for small-volume cocoa mass production.
Continuous cocoa makers retain volume leadership; bean-to-bar machines hold the steepest expansion curve.
Technology:
Cost tier differentiation separates premium flavor-development systems from commodity processing infrastructure.
- Conching:Extended aeration and shear processing develops flavor complexity through volatile acid removal and lipid coating of solids. Conching commands premium positioning because finished chocolate pricing correlates directly with conching duration and precision.
- Roasting:Thermal treatment of fermented beans develops precursor compounds for chocolate flavor through Maillard reactions. Sensor-integrated roasting control is virtualizing operator judgment through real-time bean-moisture feedback.
- Grinding:Particle-size reduction below 20 microns achieves smooth mouthfeel through roller mills or ball mills. Germany's precision-engineered grinding equipment dominates demand for particle-size consistency.
- Tempering:Controlled crystallization of cocoa butter establishes stable polymorph forms for snap and gloss. EU F-Gas Regulation is forcing heat pump and CO2-based cooling retrofits in tempering system architectures.
Grinding retains volume leadership; conching holds the steepest expansion curve.
End User:
Application requirements dictate equipment specification across divergent production environments.
- Artisan Chocolate Makers:Small-batch producers prioritize origin traceability and batch-level control over throughput metrics. Direct-to-maker equipment financing is displacing traditional distributor credit arrangements for this segment.
- Large Scale Manufacturers:Industrial confectionery operations prioritize throughput, energy efficiency, and standardization. EU Green Deal energy-efficiency mandates are accelerating replacement cycles in European large-scale facilities.
- Confectionery Companies:Mid-tier producers balance flexibility with volume across multiple product lines. These buyers concentrate procurement decisions on conching-temper integration to reduce footprint.
- Food Service:Hotels, restaurants, and catering operations require compact, low-skill operation for fresh chocolate applications. Melanger configurations dominate this segment for on-site cocoa mass production.
Large scale manufacturers retain volume leadership; artisan chocolate makers hold the steepest expansion curve.
Application:
Customer type concentration shapes equipment specification across downstream processing requirements.
- Chocolate Production:Primary processing of cocoa beans into chocolate liquor, couverture, and finished confectionery. Barry Callebaut AG leverages integrated grinding and conching operations across Abidjan and San Pedro for chocolate production supply chain control.
- Beverage Manufacturing:Cocoa mass and powder inputs for chocolate drinks and functional beverages. Beverage multinationals prioritize continuous processing for consistent alkalization and flavor profiles.
- Bakery Products:Cocoa powder and chocolate inclusions for bread, pastry, and dessert applications. Bakery manufacturers favor batch flexibility for seasonal product variation.
- Snack Foods:Chocolate coatings and inclusions for bars, clusters, and coated products. Snack food producers demand high-throughput tempering for coating line integration.
Chocolate production retains volume leadership; beverage manufacturing holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal energy-efficiency directives are reshaping equipment procurement patterns across European confectionery operations. Germany's precision-engineered cocoa processing sector commands premium positioning through particle-size consistency below 20 microns. Artisan chocolate clusters in Belgium and Switzerland accelerate sensor-integrated roasting adoption.
Germany
Precision grinding equipment manufacturers in Baden-Württemberg serve industrial confectionery demand for sub-20-micron particle consistency. EU F-Gas Regulation forces heat pump retrofits in tempering system architectures. Cologne-Düsseldorf industrial corridor concentrates conching-temper integration R&D for urban artisan producers.
United States
FDA food-contact substance regulations constrain thermal processing equipment design choices for domestic and export-bound machinery. California and New York Metro clusters drive direct-to-maker equipment financing innovation against projected couverture output. Specialty lending platforms in these coastal markets underwrite bean-to-bar machinery for origin-traceable startups.
India
BIS certification requirements add compliance layers for imported cocoa processing machinery, incentivizing localized assembly strategies. Maharashtra and Gujarat confectionery growth pulls demand for compact batch processing units. Mumbai-Pune industrial belt hosts emerging equipment fabrication partnerships serving subcontinent mid-tier producers.
Switzerland
Swissmedic-aligned food safety protocols elevate certification burdens for precision tempering equipment exports. Geneva-Zurich corridor anchors sensor-integrated roasting control development for small-batch manufacturers. Basel chemical engineering expertise migrates into CO2-based cooling system architectures for EU F-Gas compliance.
Ivory Coast
Government-backed industrial zones in Abidjan and San Pedro reshape upstream cocoa processing capacity for West African supply chain control. Licensed buying operations concentrate grinding capacity expansion under national quality certification programs. Abidjan port logistics infrastructure supports integrated grinding and conching operations for chocolate liquor export.
Cocoa Maker Market Competitive Environment
Integrated confectionery multinationals and specialized cocoa processing operators split the market between captive supply chains and third-party equipment supply. Tiered competitive positioning separates precision-engineered European fabricators from scale-driven Asian manufacturers. Strategic archetypes include: integrated grinders controlling bean-to-mass operations; precision equipment specialists serving artisan craft movement; and diversified food conglomerates with proprietary tempering protocols. Dominant competitive moves encompass conching-temper integration for footprint reduction and renewable thermal system retrofits aligned with EU Green Deal incentives.
Among integrated cocoa processors, Barry Callebaut AG and Cargill Incorporated exemplify archetypes of supply chain control through licensed buying operations and quality certification programs. Nestlé S.A. occupies a position bridging proprietary tempering protocols with artisanal equipment partnerships. These three anchors illustrate divergent strategic postures: grinding-conching integration versus sourcing-network dominance versus technology-licensing approaches.
| Leading Market Players |
|---|
| Barry Callebaut AG |
| Cargill Incorporated |
| Nestlé S.A. |
| Mondelez International |
| Mars Incorporated |
| Olam International |
| Ferrero Group |
| Hershey Company |
| Guan Chong Berhad |
| Others |
Value Chain & Pricing Dynamics
Abidjan and San Pedro anchor West African grinding capacity expansion, concentrating upstream processing power that filters into downstream equipment pricing leverage for European and Asian fabricators. This geographic clustering of bean-to-mass operations creates asymmetric bargaining positions across the cocoa maker procurement chain.
Pricing Analysis
German precision-engineered equipment commands 40-60% premiums over Asian alternatives, with price differentiation driven by CE certification tier and particle-size consistency guarantees below 20 microns. Three-tier pricing structure across premium, standard, and economy levels stratifies by automation depth and thermal control precision. Cost compression in mid-tier batch equipment is intensifying because California and Dutch financing platforms underwrite bean-to-bar machinery against projected output rather than buyer balance sheets. Artisan chocolate makers exhibit highest price sensitivity due to asset-light financing constraints, while large-scale manufacturers prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Tariff exposure between Ivory Coast and EU destination markets dominates supply chain risk planning for grinding equipment imports. Manufacturing concentration centers on Germany, China, and India for fabricated components, with raw material dependencies spanning precision steel alloys, ceramic grinding media, and sensor-integrated control modules. Single-source vulnerability persists in conching aeration systems where Swiss and Belgian specialty fabricators retain process knowledge advantages. Distribution runs through licensed buying operations co-located with Abidjan and San Pedro port infrastructure, linking equipment procurement to national quality certification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities proliferate as bean-to-bar craft production fragments demand toward compact, origin-traceable equipment configurations. This demand-side shift creates defendable niches for specialized fabricators against integrated multinational supply chains.
For Market Incumbents: Entrench conching-temper integration capabilities as artisan producers prioritize footprint reduction in urban production environments. Deepen backward integration into precision grinding component supply through Baden-Württemberg supplier network consolidation. CE marking complexity and EU F-Gas Regulation compliance burdens create defensive moats against Asian cost competitors. Prioritize renewable thermal system R&D to capture EU Green Deal incentive flows. For New Entrants and Emerging Players: Establish a beachhead in India's Maharashtra and Gujarat confectionery growth corridor through localized assembly partnerships that bypass BIS certification import duty layers. Target food service melanger configurations where operational simplicity requirements lower technical barriers to entry. Leverage direct-to-maker financing channels pioneered in California and Dutch markets to reduce customer acquisition friction against established distributor networks. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with underutilized precision tempering capabilities and stranded artisan equipment partnerships. Long-term viability hinges on exposure to origin-traceable production growth rather than commodity chocolate volume exposure. Watch for inflection signals in BIS certification pathway completion rates for India-assembly strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Conching-Temper Integration | Combined aeration-crystallization units reduce urban artisan footprint by 30-40% versus separate systems. |
| Renewable Thermal Retrofit | Heat pump roasting drum upgrades align with EU Green Deal carbon border adjustment incentives. |
| Localized India Assembly | Maharashtra-Gujarat fabrication partnerships bypass BIS import duties while serving subcontinent demand growth. |
| Direct-to-Maker Financing | California and Dutch specialty lenders underwrite equipment against projected couverture output rather than balance sheet strength. |
| Sensor-Integrated Roasting Control | Real-time bean-moisture feedback virtualizes traditional roastmaster expertise for Belgian and Swiss small-batch producers. |
Study Parameters
Initial hypotheses were tested against primary input from artisan chocolate makers, large-scale confectionery procurement directors, precision equipment fabricators in Baden-Württemberg, and thermal systems R&D engineers, then refined through secondary validation. Primary interviews combined with customs trade data, EU F-Gas Regulation implementation filings, BIS certification pathway documentation, and SEC equipment manufacturer disclosures. Bottom-up segment sizing triangulated against top-down cocoa processing capacity estimates across the analysis window.
Demand-supply-balance framing anchored the quantitative model, with segmentation across product type, technology tier, end-user scale, and application requirements modeled throughout the forecast period. CAGRs derived from equipment replacement cycle analysis, EU Green Deal mandate acceleration effects, and craft confectionery growth trajectories. Industry-specific inputs incorporated conching duration premium correlation, bean-to-bar financing platform expansion rates, and thermal system retrofit incentive capture assumptions.
Macroeconomic conditions sit as an overlay; deviation in cocoa butter price volatility, West African political stability, or EU carbon border adjustment implementation pace would shift the trajectory. Forecasts reflect documented assumptions about licensed buying operation concentration and artisan craft movement persistence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
North America Alcohol Ingredients Market
Ingredients
Africa Plant Protein Ingredients Market
Ingredients
Global Starch Derivatives Market
Ingredients
Cocoa Powder Market
Ingredients
Rose Hips Extract Market
Ingredients
Global Vitamin Ingredients Market
Ingredients
PHO Oils Market
Ingredients
Jojoba Oil Market
Ingredients
Elecampane Root Market
Ingredients
Yeast Flakes Market
Ingredients
Europe Sodium Reduction Ingredient Market
Ingredients
Edible Fiber Market
Ingredients
Plant Sterols and Esters Market
Ingredients
Shortening Fats Market
Ingredients
Lentils Flour Market
Ingredients
Liquid Feed Market