
 Chickpea Protein Ingredients Market | 2026-2036
Chickpea Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Chickpea Protein Ingredients Market Analysis
North American pulse processing capacity is fragmenting as multiple extraction facilities come online across Saskatchewan and the northern Great Plains. AGT Food and Ingredients Inc. anchors this expansion through its integrated supply chain from farm gate to ingredient. Ingredion Inc. competes via its specialty protein R&D pipeline and toll manufacturing relationships. ChickP Protein Ltd. differentiates through its patented zero-waste extraction technology that preserves functional properties.
Chickpea protein ingredients comprise protein fractions extracted from Cicer arietinum seeds through wet or dry milling, typically yielding isolates exceeding 80% protein content with balanced essential amino acid profiles. These ingredients function as emulsifiers, gelling agents, and nutritional fortifiers in formulated foods where allergen-free positioning commands premium positioning. Isolate and concentrate categories lead current volume, though textured formats are gaining traction in meat alternative formulations where fibrous mouthfeel determines repeat purchase. Bakery applications represent a mature demand pocket, while dairy alternatives offer faster growth trajectories as barista-grade foaming properties improve.
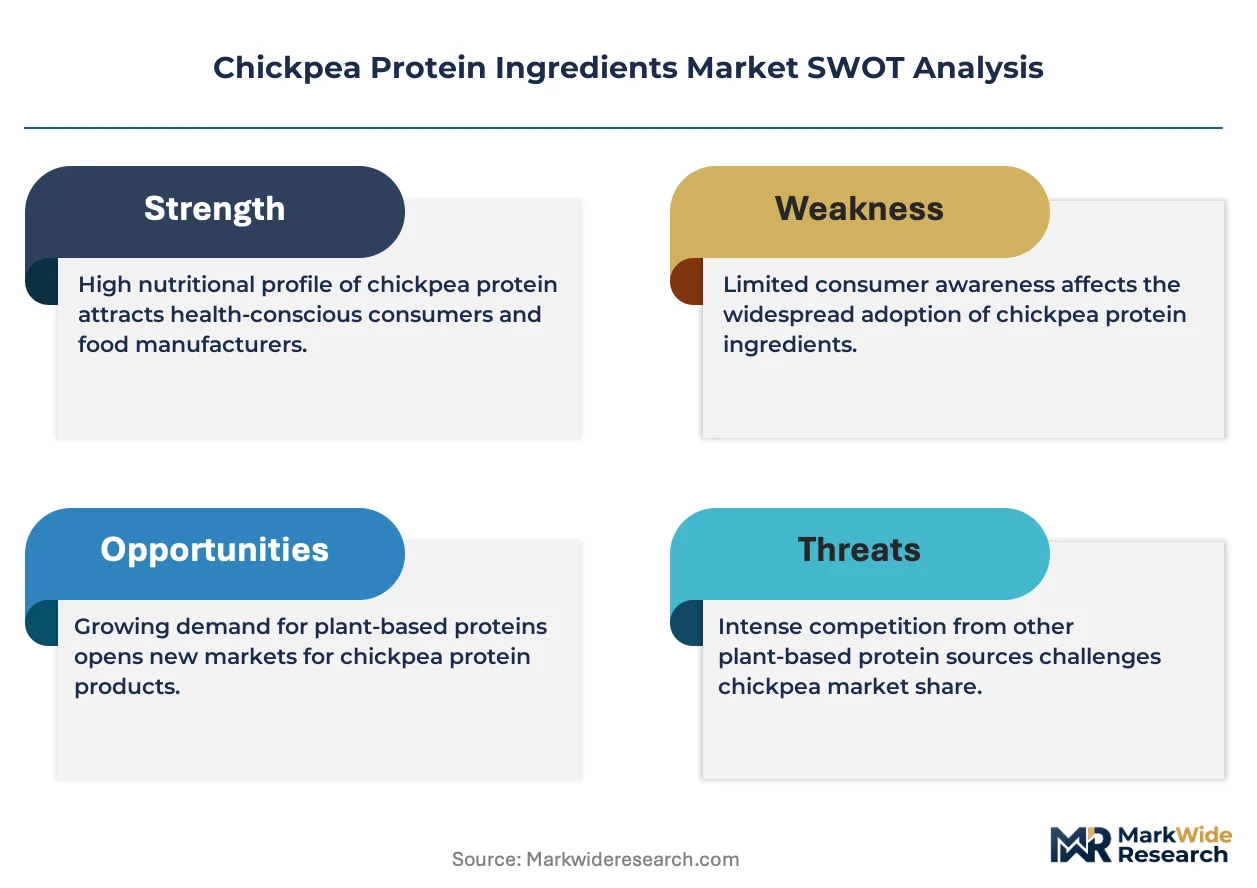
Health Canada and the FDA both scrutinize protein content claims and allergen labeling for novel pulse ingredients, creating compliance costs that favor scaled producers with regulatory affairs capacity. The EU Green Deal's protein strategy and REACH-aligned sustainability disclosures are redirecting procurement toward verified low-carbon chickpea supply chains. Stakeholders must monitor how EFSA's evolving stance on protein quality scoring affects formulation decisions across European branded food portfolios.
Market Dynamics
Plant-based meat manufacturers are accelerating chickpea protein adoption as extraction yields improve and functional property preservation becomes commercially viable. The FDA's updated guidance on novel protein labeling is reshaping product development requirements across formulated food categories.
Growth Catalysts
- EU Green Deal protein strategy:The EU's protein strategy and REACH-aligned sustainability disclosures redirect procurement toward verified low-carbon chickpea supply chains. Food manufacturers reformulate portfolios to meet disclosure thresholds.
- Barista-grade foaming properties:Dairy alternative formulators adopt chickpea isolates as emulsion stability and foam structure match performance requirements. Specialty coffee chains drive specification standards.
- Germany:Food technologists in Germany concentrate demand by reformulating bakery applications with higher-protein chickpea isolates. Local milling infrastructure supports rapid formulation iteration.
Market Restraints
- Pulse crop price volatility:Chickpea input costs fluctuate with Canadian Prairie weather patterns and Indian export policy shifts. Margin compression hits toll-dependent processors hardest.
- Regulatory friction:Health Canada and FDA scrutiny of protein content claims and allergen labeling for novel pulse ingredients creates compliance cost burdens. Smaller producers lack regulatory affairs capacity.
- Soy protein isolate substitution:Established soy processing infrastructure and lower unit economics displace chickpea protein in cost-sensitive applications. Functional parity gaps persist in high-shear extrusion.
Strategic Opportunities
- EFSA protein quality scoring evolution:EFSA's evolving stance on protein quality scoring creates formulation decision windows across European branded food portfolios. Early adopters secure shelf-space advantages.
- Textured protein formats:Meat alternative manufacturers seek fibrous mouthfeel solutions where repeat purchase depends on texture fidelity. Extrusion technology advances enable new product architectures.
- Saskatchewan processing cluster:Multiple extraction facilities coming online across Saskatchewan and the northern Great Plains fragment North American pulse processing capacity. Regional supply security attracts anchor customers.
Industry Challenges
- Zero-waste extraction scale-up:Patented extraction technologies preserving functional properties require capital-intensive equipment replication. Engineering talent scarcity constrains deployment timelines.
- Cross-jurisdictional claim substantiation:Protein content validation protocols differ between FDA, Health Canada, and EFSA requirements. Multi-market launches face extended certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chickpea Protein Ingredients Market |
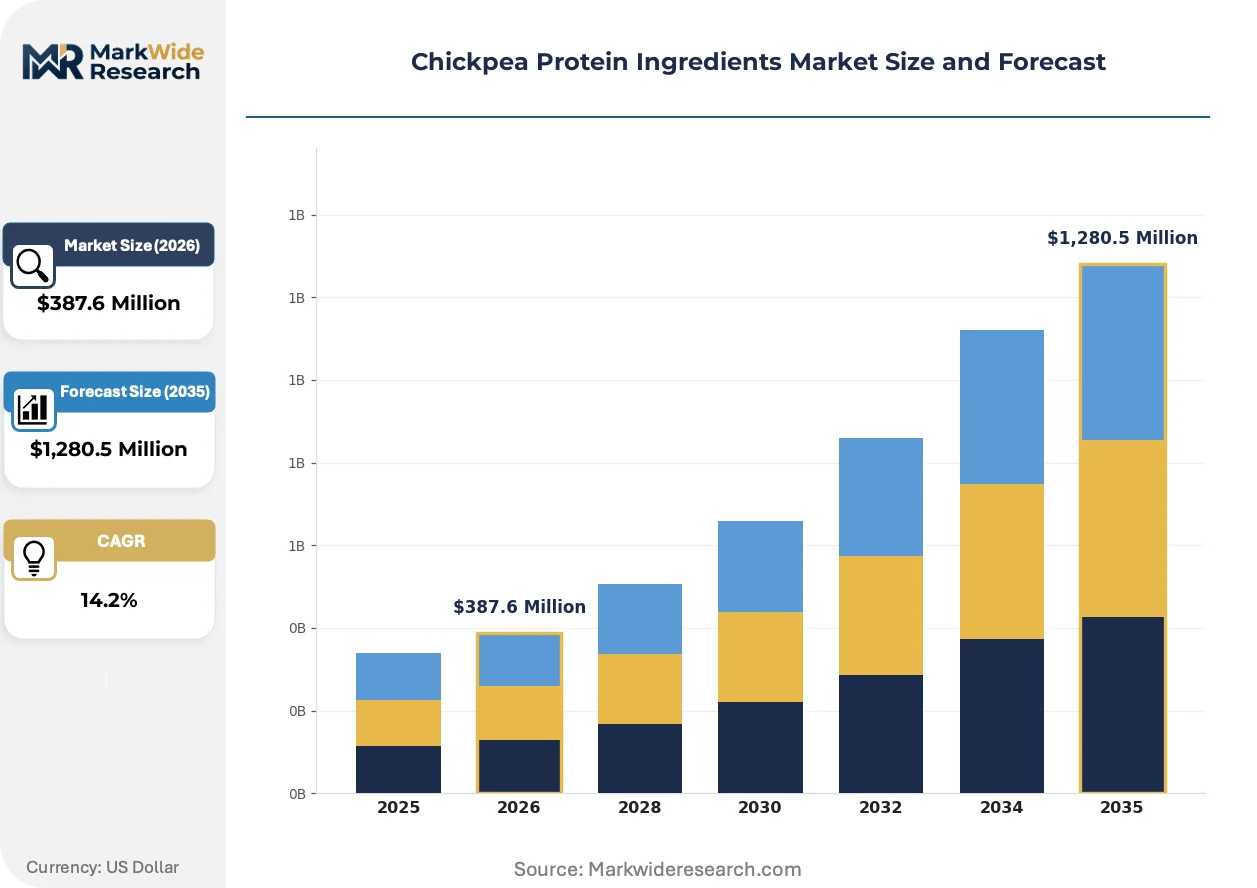
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Flour, Textured Application: Meat Alternatives, Dairy Alternatives, Snacks, Bakery End User: Food Industry, Nutraceuticals, Animal Feed, Personal Care Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | AGT Food and Ingredients Inc., STDM FOOD and Beverages Pvt. Ltd, Ingredion Inc., Batory Foods, VW-Ingredients, Archer Daniels Midland Company, ChickP Protein Ltd., Cambridge Commodities Limited, Roquette Frères, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chickpea Protein Ingredients Market Emerging Trajectories
Extraction technology convergence with sustainability mandates is compressing development cycles and redefining competitive moats. Functional property preservation now determines ingredient premiumization potential.
Wet milling protocols is hybridizing with membrane filtration advances to isolate protein fractions above 80% purity while retaining solubility curves. Plant-based meat R&D teams adopt these hybrid processes within 18-month formulation windows. The technology is compressing the performance gap between chickpea and animal-derived emulsifiers.
REACH-aligned sustainability disclosures under the EU Green Deal are mandating verified carbon intensity reporting for protein ingredient procurement. Food manufacturers reconfigure supplier scorecards to weight lifecycle emissions alongside functional specifications. European branded portfolios face the steepest compliance cost curves.
Buyer concentration among contract manufacturers is shortening switching cycles as barista-grade performance specifications tighten. Specialty coffee chains now specify foam stability duration and collapse rates, displacing generic dairy alternative procurement. Germany's bakery sector exhibits the most aggressive reformulation pace as protein fortification claims multiply.
Chickpea Protein Ingredients Market Segmentation
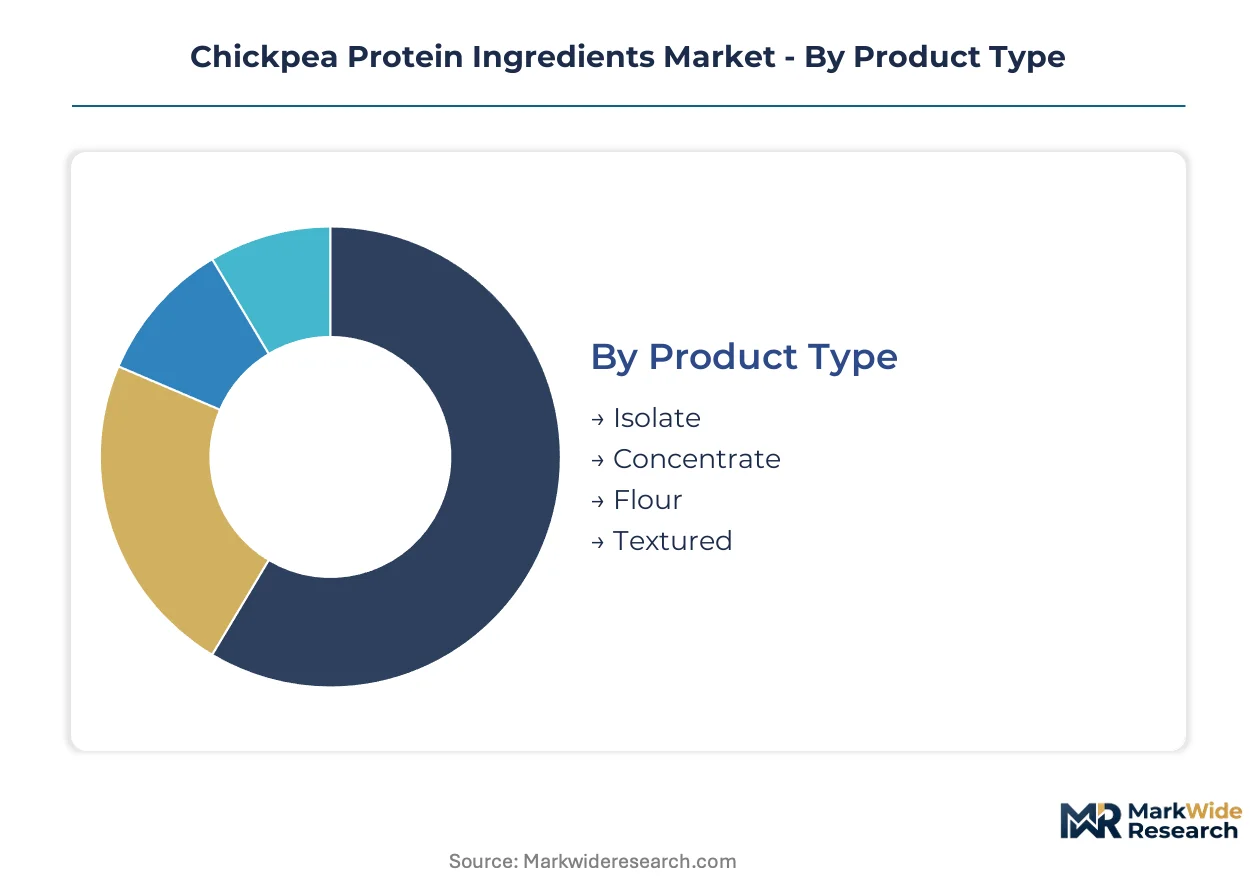
Chickpea protein ingredient buyers segment procurement by functional performance tiers and formulation complexity. Product purity levels and application-specific processing requirements create distinct value bands that determine supplier selection criteria and pricing negotiation leverage.
Product Type:
Cost tier stratification separates commodity-grade inputs from premium functional isolates commanding formulation premiums.
- Isolate:Protein fractions exceeding 80% purity with balanced essential amino acid profiles function as emulsifiers and gelling agents. Meat alternative manufacturers in Germany concentrate procurement here as fibrous mouthfeel specifications tighten.
- Concentrate:Intermediate purity grades (60-80% protein) balance cost and nutritional density for bakery fortification. Food technologists reformulate European bread applications where protein content claims multiply.
- Flour:Whole-seed milled products retain fiber and starch fractions for cost-sensitive applications.
- Textured:Extruded formats with fibrous architecture target meat analog applications.
Isolate commands the established base. The steepest expansion runs through Textured.
Application:
Customer type determines performance specifications and certification requirements across formulated food categories.
- Meat Alternatives:High-shear extrusion applications demand preserved functional properties and fibrous texture fidelity. Plant-based meat R&D teams adopt hybrid wet-milling protocols within compressed formulation windows.
- Dairy Alternatives:Barista-grade foaming properties and emulsion stability specifications drive isolate adoption. Specialty coffee chains now specify foam collapse rates, displacing generic procurement.
- Snacks:Protein fortification in extruded and baked formats leverages concentrate cost positions.
- Bakery:Mature demand pocket with established formulation protocols across European milling infrastructure.
Dairy Alternatives capture the fastest volume gains. Meat Alternatives present the highest technical barriers.
End User:
Volume concentration varies sharply between commodity-scale food manufacturing and specialized nutraceutical applications.
- Food Industry:Contract manufacturers and branded food companies drive bulk procurement with tight functional specifications. REACH-aligned sustainability disclosures are reconfiguring supplier scorecards toward verified low-carbon supply chains.
- Nutraceuticals:Sports nutrition and clinical nutrition formulators prioritize amino acid completeness and digestibility scoring. EFSA protein quality evaluation protocols shape European formulation decisions.
- Animal Feed:Cost-driven segment accepting lower purity grades for protein supplementation.
- Personal Care:Emerging applications in hair and skin formulations leveraging emulsification properties.
Food Industry anchors procurement volume. Nutraceuticals deliver the strongest margin expansion.
Distribution Channel:
Supply concentration dictates channel selection between direct procurement relationships and fragmented retail access.
- Online Retail:E-commerce platforms serve small-scale formulators and ingredient traders with flexible order quantities. Digital procurement shortens switching cycles as performance specifications tighten.
- Supermarkets:Limited to consumer-packaged finished goods rather than bulk ingredients.
- Specialty Stores:Health food and organic retailers stock finished products containing chickpea protein.
- Direct Sales:Anchor customers secure supply security through long-term contracts with Saskatchewan and northern Great Plains extraction facilities.
Direct Sales lock in the largest accounts. Online Retail is gaining share fastest among emerging formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA protein quality evaluation protocols are redirecting European procurement toward verified low-carbon chickpea supply chains. Procurement concentration is fragmenting across extraction facilities in Saskatchewan and the northern Great Plains. Formulation teams in Germany are compressing development cycles for bakery applications.
Germany
Food technologists reformulate bakery applications with higher-protein chickpea isolates as protein fortification claims multiply. The EU Green Deal protein strategy mandates REACH-aligned sustainability disclosures for ingredient procurement. Local milling infrastructure in Bavaria and North Rhine-Westphalia supports rapid formulation iteration for bread and pastry applications.
United States
Plant-based meat manufacturers accelerate chickpea protein adoption as extraction yields improve and functional property preservation becomes viable. The FDA's updated guidance on novel protein labeling reshapes product development requirements across formulated food categories. Multiple extraction facilities across North Dakota and Montana fragment North American pulse processing capacity.
Canada
Saskatchewan's integrated supply chain from farm gate to ingredient anchors regional expansion as AGT Food and Ingredients Inc. scales processing infrastructure. Health Canada scrutiny of protein content claims and allergen labeling creates compliance cost burdens favoring scaled producers. The Prairie Provinces cluster attracts anchor customers seeking supply security through long-term contracts.
India
Domestic chickpea production supports cost-competitive concentrate grades for regional bakery fortification. FSSAI labeling requirements for novel pulse ingredients extend certification cycles for multi-market launches. Processing activity concentrates in Gujarat and Maharashtra where traditional milling infrastructure adapts to isolate production protocols.
United Kingdom
Specialty coffee chains drive barista-grade foaming property specifications that displace generic dairy alternative procurement. EFSA's evolving stance on protein quality scoring creates formulation decision windows for European branded food portfolios. London-based contract manufacturers reconfigure supplier scorecards to weight lifecycle emissions alongside functional specifications.
Chickpea Protein Ingredients Market Vendor Landscape
Capability concentration sits with patented extraction technology specialists; scale advantage sits with integrated agribusiness conglomerates. The vendor base stratifies across three tiers: diversified ingredient conglomerates with toll manufacturing relationships, pulse-specific processors with captive supply chains, and technology licensors with zero-waste extraction patents. Dominant competitive moves include capacity expansion across Saskatchewan and the northern Great Plains and strategic partnerships between extraction technology developers and contract manufacturers.
Within the technology-specialist tier, ChickP Protein Ltd. exemplifies patented zero-waste extraction approaches that preserve functional properties. AGT Food and Ingredients Inc. anchors the integrated-processor archetype with farm-to-ingredient supply chain control. Ingredion Inc. occupies a position representing diversified ingredient conglomerates competing via specialty protein R&D pipelines. These three entities collectively illustrate the competitive tension between functional performance premiumization and commodity-scale cost positioning.
| Leading Market Players |
|---|
| AGT Food and Ingredients Inc. |
| STDM FOOD and Beverages Pvt. Ltd |
| Ingredion Inc. |
| Batory Foods |
| VW-Ingredients |
| Archer Daniels Midland Company |
| ChickP Protein Ltd. |
| Cambridge Commodities Limited |
| Roquette Frères |
| Others |
Supply Flow & Price Mechanics
Pulse crop price volatility from Canadian Prairie weather patterns and Indian export policy shifts determines both pricing tier spreads and supply chain shape. Margin compression cascades through toll-dependent processors while integrated farm-to-ingredient operators capture stability premiums.
Pricing Analysis
Saskatchewan-origin isolates trade at substantial premiums over Indian concentrate grades due to functional property preservation and REACH-aligned carbon verification. Three-tier pricing structure across premium, standard, and economy levels separates patented zero-waste extraction outputs from commodity wet-milled concentrates and whole-seed flour grades. Pricing pressure stems from soy protein isolate substitution in cost-sensitive meat alternative applications where functional parity gaps are narrowing. Contract manufacturers exhibit the highest price sensitivity; nutraceutical formulators absorb premiums for amino acid scoring advantages.
Supply Chain Analysis
Toll manufacturing relationships with AGT Food and Ingredients Inc., Ingredion Inc., and regional Saskatchewan processors concentrate North American extraction capacity. Supply draws from Canadian Prairie chickpea production, Indian desi and kabuli varietal exports, and emerging Australian winter crop development. Raw material dependencies center on seed protein content variability, hexane solvent availability for conventional extraction, and membrane filtration equipment lead times. Single-source vulnerability runs through Saskatchewan's integrated processing cluster where winterkill events disrupt farm-gate supply. Distribution runs through direct long-term offtake contracts for anchor customers, supplemented by ingredient trader networks for emerging formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across extraction technology tiers creates entry niches as barista-grade and textured format specifications multiply faster than incumbent capacity expansion. Each performance tier now supports specialist positioning.
For Market Incumbents: Build regulatory affairs capacity as a moat against Health Canada and FDA compliance cost burdens that disadvantage smaller competitors. Anchor backward integration into Saskatchewan farm-gate supply through long-term acreage contracts. Add membrane filtration capacity in North Dakota to capture textured protein format demand from meat alternative R&D teams. Defend against ChickP Protein Ltd.-style patent encroachment by accelerating zero-waste extraction licensing programs. For New Entrants and Emerging Players: Mid-tier concentrate grades for European bakery fortification represent the most penetrable entry point as German milling infrastructure demands rapid formulation iteration partners. Specialty coffee chain direct supply relationships offer bypass routes around established dairy alternative ingredient distributors. Target EFSA protein quality scoring advisory work to embed early in European branded food portfolio decisions. Lead with sustainability disclosure compliance as procurement teams reconfigure supplier scorecards. For Investors and Strategic Acquirers: Patent-holding extraction technology developers with demonstrated functional property preservation offer the strongest 5-10 year viability as premiumization depends on performance differentiation. Integrated processors with captive Canadian supply chains provide inflation hedge characteristics absent from toll-dependent operators. Watch FDA novel protein labeling guidance enforcement intensity as inflection indicator for compliance cost burden distribution.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Waste Extraction Scale-Up | Patented membrane filtration deployment preserves solubility curves that command formulation premiums. |
| Saskatchewan Processing Cluster Expansion | Farm-gate integration secures supply security for anchor customers facing Indian export policy volatility. |
| EFSA Protein Quality Advisory Engagement | Early scoring protocol influence embeds suppliers in European branded food reformulation decisions. |
| Barista-Grade Performance Certification | Foam stability specifications from specialty coffee chains displace generic dairy alternative procurement. |
| REACH-Aligned Carbon Verification | Lifecycle emissions documentation satisfies EU Green Deal procurement reconfiguration requirements. |
Methodological Framework
A standing panel of pulse processing plant managers, food technologists at German bakery reformulation labs, procurement leads at contract manufacturers, and regulatory affairs specialists at Health Canada and FDA provided ongoing calibration. Primary interviews with ingredient R&D directors and sustainability officers at branded food companies combined with secondary validation from EFSA guidance documents, FDA labeling updates, EU Green Deal protein strategy filings, and Saskatchewan agricultural statistics. Trade flow analysis from Canadian and Indian customs records, SEC 10-K disclosures from diversified ingredient conglomerates, and REACH registration databases anchored supply-side assessment. Bottom-up capacity buildout tracking and top-down procurement survey data were triangulated.
Scenario-bracketing across Canadian drought frequency, Indian export tariff regimes, and EFSA protein quality scoring timeline uncertainty framed projection ranges. Segmentation modeling spanned product purity tiers, application performance requirements, end-user certification needs, and regional regulatory clusters. CAGRs were derived from elasticity-adjusted adoption curves and capacity expansion pipelines. Forecast inputs included wet milling yield improvement trajectories, extrusion technology advancement rates, and specialty coffee chain specification diffusion patterns across the analysis window.
Stress conditions across Prairie precipitation variance, hexane price spikes, and FDA enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about extraction yield convergence and functional property preservation scalability. Quarterly review of EFSA advisory committee proceedings, Saskatchewan planting intention reports, and specialty coffee chain procurement specification releases is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Pine Pollen Powder Market
Ingredients
PHO Oils Market
Ingredients
Malted Wheat Flour Market
Ingredients
Asia-Pacific Prebiotic Ingredients Market
Ingredients
Mustard Flour Market
Ingredients
Psyllium Products Market
Ingredients
Cocoa Derivatives Market
Ingredients
France Sodium Reduction Ingredients Market
Ingredients
Cosmetic Bioactive Ingredients Market
Ingredients
Food Minerals Market
Ingredients
Grape Seed Extracts Market
Ingredients
Canola Oil Market
Ingredients
Meat Starter Culture Market
Ingredients
Notoginseng Root Extract Market
Ingredients
Europe Soy Protein Market
Ingredients
Vitamin and Mineral Premixes Market