
 Vital Wheat Gluten Market | 2026-2036
Vital Wheat Gluten Market Size, Share, and Industry Trends Forecast 2026-2036
Vital Wheat Gluten Market Analysis
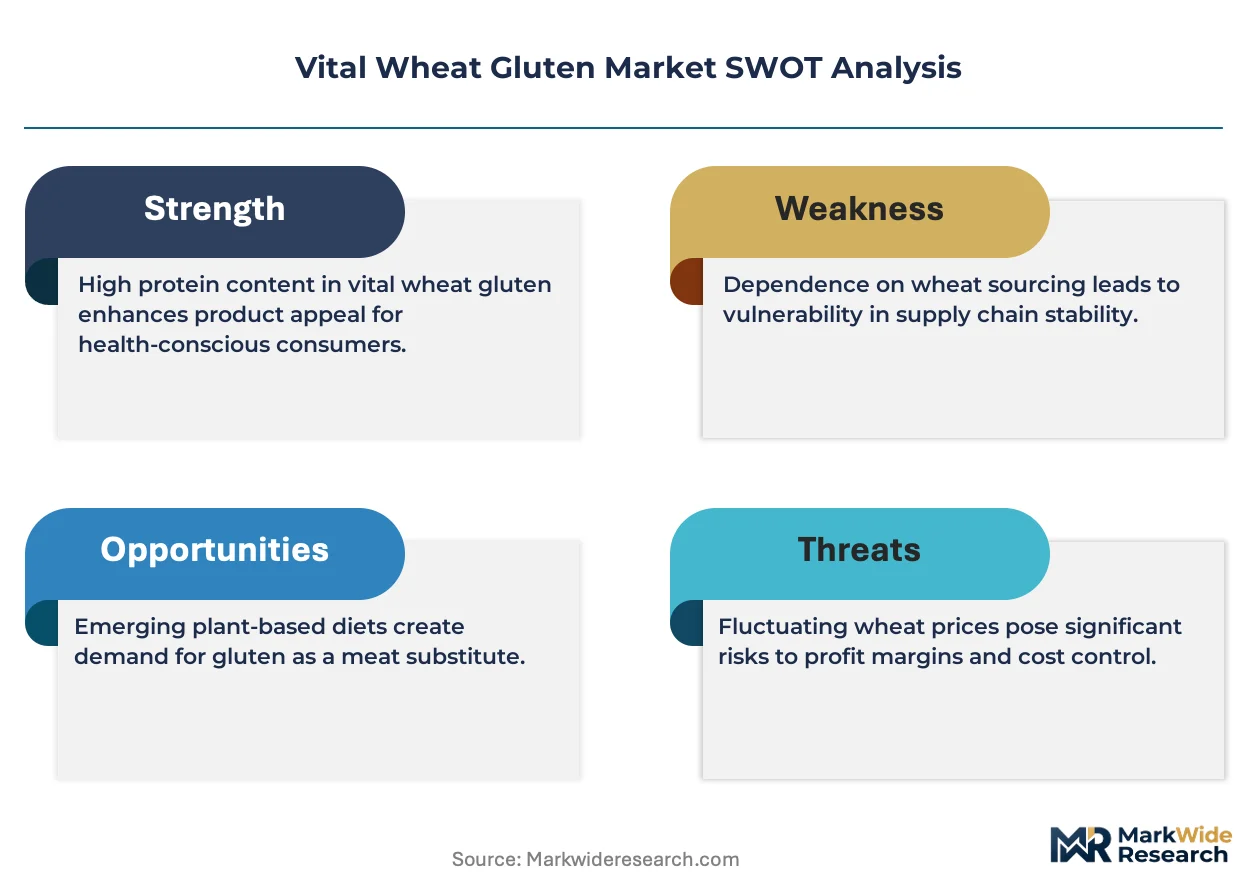
Pea protein is rebalancing vital wheat gluten economics across food formulation labs as cost parity and functional equivalence converge in meat-alternative recipes. Cargill leverages its North American grain origination network to sustain captive wheat supply for gluten extraction. Manildra Group anchors Australasian supply through integrated milling and fractionation assets. MGP Ingredients differentiates via specialty wheat protein isolates for beverage and nutritional applications.
Vital wheat gluten comprises the insoluble protein complex recovered from wheat flour through dough washing and centrifugal separation, typically yielding 75-85% protein content on a dry basis with viscoelastic properties that trap gases during fermentation. Its primary industrial purpose centers on imparting chewiness and structural integrity to baked goods, restructured meats, and extruded snacks. The organic product type commands premium positioning as clean-label bakery chains in Western Europe and North America shift procurement specifications. Meat alternatives represent the fastest-growing application channel, with textured wheat gluten displacing soy concentrates in European plant-based sausage formulations. Supermarkets and specialty stores together occupy the dominant distribution share, though direct sales to industrial food manufacturers capture the deepest margin pools through volume contracting.
FDA food additive regulations and USDA organic certification standards govern product safety and label claims in the United States, while EFSA novel food assessments shape market access for innovative wheat protein fractions in Europe. The EU Green Deal's farm-to-fork targets indirectly tighten wheat sourcing protocols by pressuring nitrogen fertilizer intensity in grain production. China's GB standards and SAMR food safety oversight impose compositional thresholds on imported vital wheat gluten for domestic processing. Stakeholders must monitor how carbon border adjustment mechanisms and evolving protein content specifications in buyer contracts reshape supplier qualification criteria.
Market Dynamics
Plant-based meat manufacturers are accelerating wheat gluten procurement as soy isolate prices fluctuate and EU energy regulations force dryer technology upgrades across European processing facilities.
Growth Catalysts
- EU F-Gas Regulation:Mandates for lower-global-warming-potential refrigerants push processors toward mechanical vapor recompression dryers that cut energy intensity by half while maintaining protein functionality.
- Textured protein extrusion:High-moisture extrusion systems now enable wheat gluten to mimic muscle fiber structures in plant-based sausages and deli slices, opening formulation doors previously locked to soy.
- German industrial bakery clustering:Hamburg and Cologne host dense concentrations of automated bread production lines that specify vital wheat gluten for dough strength and volume consistency.
Market Restraints
- Wheat price volatility:Drought cycles in Black Sea growing regions transmit directly to gluten extraction economics, compressing processor margins when flour input costs spike.
- Protein content specification creep:Buyers now contract for 80-85% protein minimums versus historical 75% thresholds, forcing processors to reject lower-grade wheat streams.
- Pea protein convergence:Cost parity in meat-alternative formulations lets food technologists substitute legume isolates without sacrificing texture or nutrition claims.
Strategic Opportunities
- Beverage protein fortification:Wheat protein isolates with enhanced dispersibility target sports nutrition and meal-replacement drinks where solubility barriers previously excluded gluten.
- EU Green Deal farm-to-fork:Nitrogen fertilizer reduction mandates create incentive structures for low-input wheat sourcing that processors can certify for premium bakery contracts.
- Direct-to-manufacturer contracting:Bypassing ingredient distributors lets gluten producers capture margin pools currently absorbed by foodservice intermediaries in alt-meat supply chains.
Industry Challenges
- Novel food authorization timelines:EFSA assessments for innovative wheat protein fractions stretch 18-24 months, freezing product launch schedules for European innovators.
- Extrusion technician scarcity:High-moisture extrusion operation demands hybrid skill sets combining thermal processing and protein chemistry that vocational programs have not yet standardized.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vital Wheat Gluten Market |
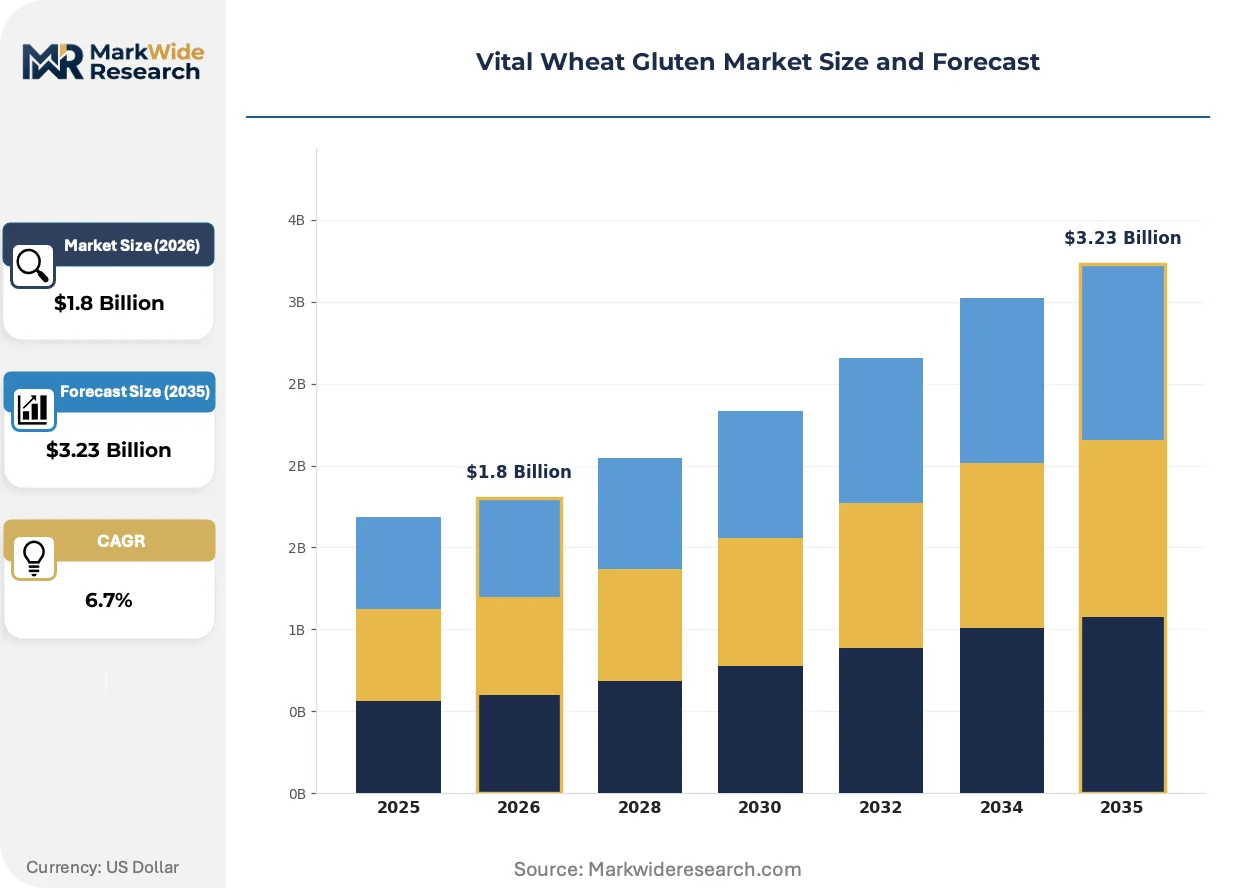
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Non-Organic, High-Protein, Low-Gluten Application: Baking, Meat Alternatives, Snacks, Beverage Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales End User: Food Manufacturers, Bakeries, Restaurants, Nutritional Supplements |
| Companies Covered | Ardent Mills, Cargill, Manildra Group, Tereos, Roquette Frères, Pioneer Industries, Anhui Ante Food, MGP Ingredients, Archer Daniels Midland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vital Wheat Gluten Market Emerging Trajectories
Processing technology and procurement specifications are rewriting competitive boundaries as energy costs and protein performance standards tighten simultaneously across wheat gluten value chains.
Membrane filtration is rewriting protein fractionation economics by enabling continuous separation of gluten from starch without the water-intensive dough-washing batch processes that dominated twentieth-century extraction. European processors near the Rhine corridor have piloted ceramic microfiltration systems that recover 12% more protein per ton of flour while slashing wastewater volumes. The technology is compressing capital requirements for mid-scale entrants who previously faced insurmountable dryer investments.
REACH chemical safety registrations now cover processing aids used in gluten extraction, forcing suppliers to disclose full substance portfolios or face import restrictions into the European Economic Area. Industrial bakeries in France and the Netherlands have begun auditing supplier REACH compliance as a procurement gate, rejecting non-registered hydrochloric acid and enzyme treatments. The regulation is fragmenting supplier bases into REACH-compliant tier-one processors and excluded secondary traders.
Clean-label bakery chains now specify organic-certified vital wheat gluten even where conventional product suffices functionally, creating a two-tier specification environment that conventional processors struggle to bridge. German retail discounters and French artisan bakery cooperatives have both tightened procurement codes to exclude pesticide-residue detectable wheat streams. The specification divergence is most visible in Western European markets where label claims command shelf price premiums of 15-40% without corresponding production cost differences.
Vital Wheat Gluten Market Segmentation
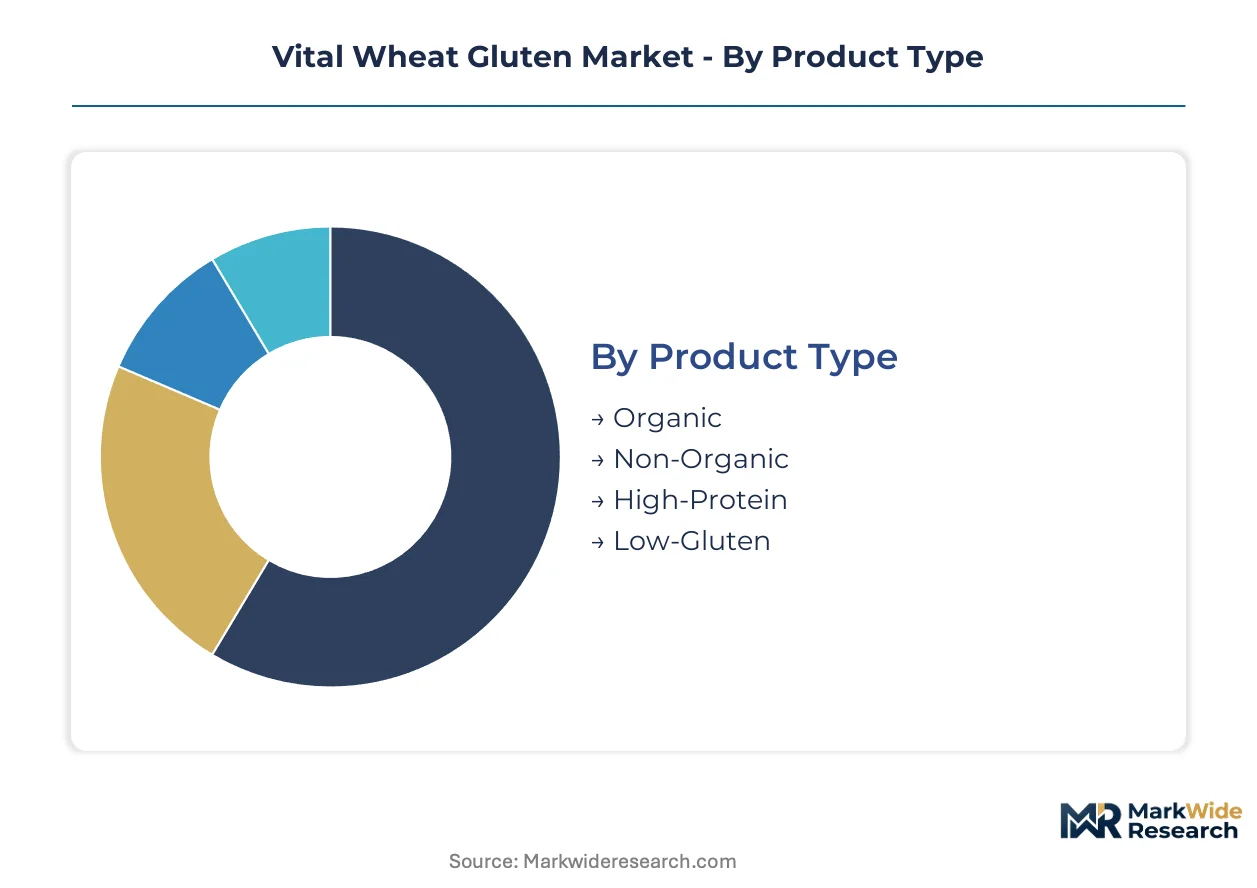
Segmentation in vital wheat gluten reveals how procurement specifications diverge between industrial-scale food manufacturing and premium-positioned clean-label channels. Protein content thresholds, certification requirements, and end-use functional demands create distinct margin pools that processors must target with tailored product grades.
Product Type:
Volume production concentrates in commodity grades serving industrial bakeries, while premium positioning accrues to certified organic streams commanding 15-40% shelf price premiums in Western European retail.
- Organic:Certified wheat streams exclude pesticide-residue detectable grain, meeting procurement codes from German retail discounters and French artisan bakery cooperatives. Clean-label bakery chains in Western Europe and North America now specify organic even where conventional product suffices functionally.
- Non-Organic:Standard extraction from conventional wheat flour supplies automated bread production lines in Hamburg and Cologne industrial bakery clusters where cost sensitivity dominates procurement decisions.
- High-Protein:Specifications now contract for 80-85% protein minimums versus historical 75% thresholds, forcing processors to reject lower-grade wheat streams during drought cycles in Black Sea growing regions.
- Low-Gluten:Modified protein fractions target beverage fortification applications where solubility barriers previously excluded wheat gluten from sports nutrition formulations.
Mature deployment sits with Non-Organic. Newer deployment is concentrated in Organic.
Application:
Functional requirements range from gas-trapping viscoelasticity in fermented doughs to muscle-fiber mimicry in extruded meat analogues, with each application channel imposing distinct protein performance standards.
- Baking:Imparts chewiness and structural integrity to bread, trapping gases during fermentation through viscoelastic protein networks. German industrial bakeries specify vital wheat gluten for dough strength and volume consistency in automated production lines.
- Meat Alternatives:High-moisture extrusion systems enable wheat gluten to mimic muscle fiber structures in plant-based sausages and deli slices, displacing soy concentrates in European formulations as pea protein achieves cost parity.
- Snacks:Extruded snack applications leverage gluten's film-forming and binding properties in restructured products, though this segment faces margin compression from wheat price volatility transmitted from Black Sea supply regions.
- Beverage:Wheat protein isolates with enhanced dispersibility target sports nutrition and meal-replacement drinks, representing an emerging channel where solubility engineering opens formulation doors previously locked to gluten.
Volume concentration remains in Baking. Steepest expansion trajectory is occurring in Meat Alternatives.
Distribution Channel:
Channel selection determines margin capture, with direct industrial contracting bypassing distributor markups versus retail-facing channels absorbing foodservice intermediary costs.
- Online Retail:E-commerce platforms serve small-scale bakeries and specialty food producers with smaller lot sizes, though logistics costs erode margins on low-density protein powders.
- Supermarkets:Mass retail channels dominate consumer-facing gluten sales for home baking applications, particularly in North American markets where domestic bread-making maintains cultural prevalence.
- Specialty Stores:Gourmet and health-food retailers capture premium positioning for organic-certified products, aligning with clean-label procurement trends in Western European urban centers.
- Direct Sales:Volume contracting with industrial food manufacturers captures the deepest margin pools, letting gluten producers bypass ingredient distributors currently absorbing margin in alt-meat supply chains.
Established volume flows through Direct Sales. Emerging channel development centers on Online Retail.
End User:
End-user differentiation reflects scale economies and formulation sophistication, from commodity-grade industrial procurement to precision-specified nutritional applications.
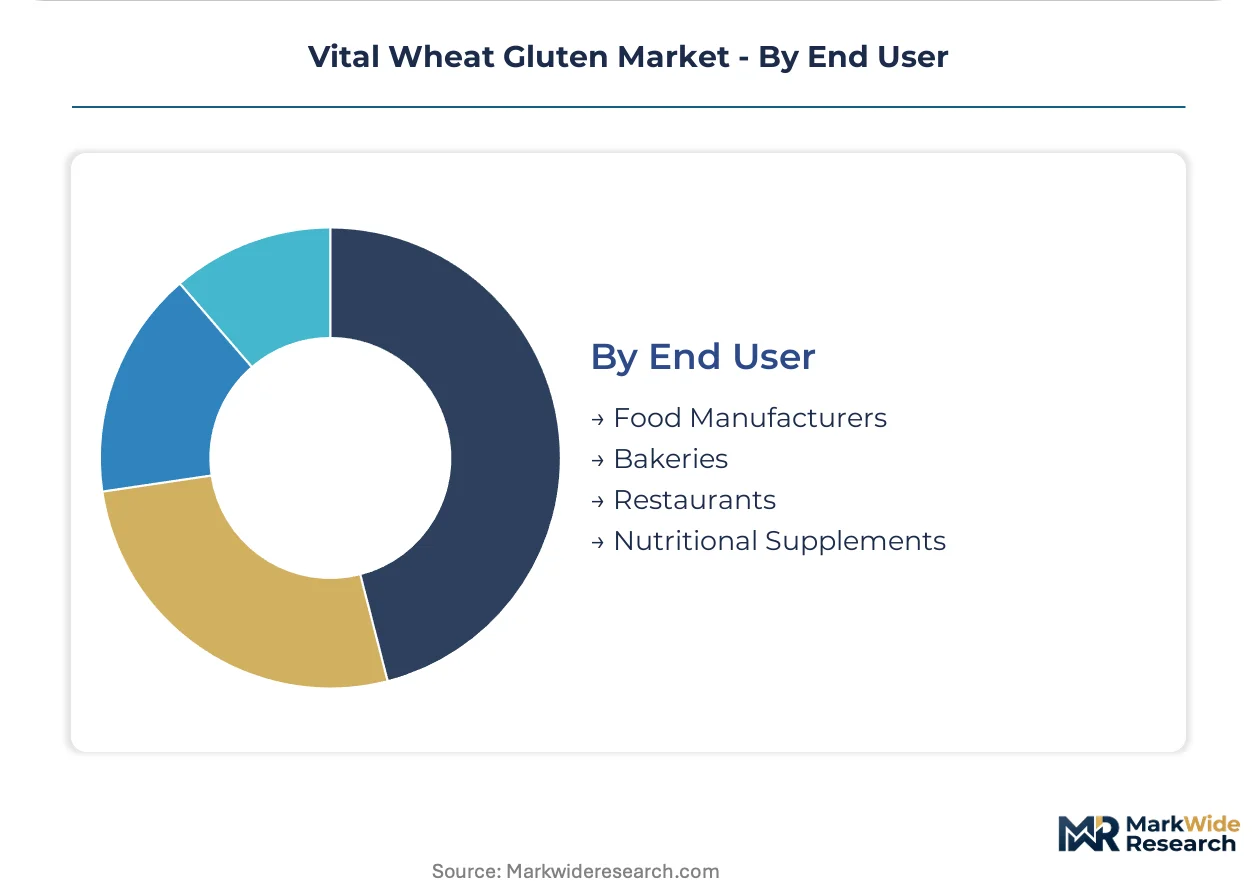
- Food Manufacturers:Large-scale processors of plant-based meats, baked goods, and extruded snacks drive bulk procurement with strict protein content and functionality specifications.
- Bakeries:Automated industrial operations in German clusters specify gluten for dough consistency, while artisan cooperatives in France demand organic certification regardless of functional necessity.
- Restaurants:Foodservice accounts represent fragmented, lower-volume demand primarily for specialty pizza and artisan bread operations seeking texture enhancement.
- Nutritional Supplements:Sports nutrition and meal-replacement formulators represent a nascent channel where dispersibility-engineered isolates command premium positioning.
Procurement scale concentrates with Food Manufacturers. Nutritional Supplements represents the most rapidly developing end-user segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Hamburg and Cologne concentrate European vital wheat gluten demand through industrial bakery clusters and alt-meat startup ecosystems that benefit from targeted tax incentives and infrastructure subsidies.
Germany
Industrial bakeries in Hamburg and Cologne specify vital wheat gluten for automated dough strength and volume consistency in high-throughput bread lines. EU F-Gas Regulation mandates push Rhine corridor processors toward mechanical vapor recompression dryers that halve energy intensity. The North Rhine-Westphalia cluster hosts dense concentrations of plant-based meat manufacturers displacing soy isolates with textured wheat gluten.
United States
North American grain origination networks sustain captive wheat supply chains for gluten extraction serving restructured meat and beverage fortification channels. FDA food additive regulations and USDA organic certification standards govern product safety and label claims across state boundaries. Kansas and Minnesota milling corridors anchor domestic production capacity for industrial bakery and snack applications.
France
Artisan bakery cooperatives in Île-de-France and Auvergne-Rhône-Alpes tightened procurement codes to exclude pesticide-residue detectable wheat streams regardless of functional necessity. REACH chemical safety registrations now cover processing aids used in gluten extraction, forcing full substance portfolio disclosure. Industrial bakeries in the Paris Basin audit supplier REACH compliance as a procurement gate.
China
GB standards and SAMR food safety oversight impose compositional thresholds on imported vital wheat gluten for domestic processing in sports nutrition and extruded snack applications. Yangtze River Delta processors pilot ceramic microfiltration systems that recover additional protein per ton of flour while slashing wastewater volumes. Shandong Peninsula wheat belts supply raw material streams for fractionation assets.
Australia
Integrated milling and fractionation assets in New South Wales and Victoria anchor Australasian supply through the Manildra Group production network. TGA oversight shapes import protocols for nutritional supplement applications where wheat protein isolates target dispersibility-engineered formulations. Sydney and Melbourne metropolitan clusters concentrate clean-label bakery demand for organic-certified grades.
Vital Wheat Gluten Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated origination networks controlling upstream wheat supply while mid-scale fractionators compete on protein content specifications. The structure tiers into three archetypes: grain-trading conglomerates with captive milling assets, integrated regional processors with drying technology advantages, and specialty isolates producers targeting beverage and nutritional channels. Dominant competitive moves include backward integration into grain origination and technology licensing for membrane filtration systems that compress capital requirements.
Within the grain-trading conglomerate tier, Cargill and Archer Daniels Midland represent North American origination networks that sustain captive wheat supply chains. Manildra Group exemplifies integrated Australasian processors with combined milling and fractionation assets. MGP Ingredients occupies a position among specialty isolates producers differentiating via dispersibility-engineered wheat protein for beverage applications. These three anchors illustrate how competitive positioning depends on upstream control over raw material streams versus downstream formulation partnerships.
| Leading Market Players |
|---|
| Ardent Mills |
| Cargill |
| Manildra Group |
| Tereos |
| Roquette Frères |
| Pioneer Industries |
| Anhui Ante Food |
| MGP Ingredients |
| Archer Daniels Midland |
| Others |
Supply Flow & Price Mechanics
Chicago wheat futures and Black Sea export quotations cascade directly into processor margin structures, compressing or expanding pricing tiers as drought cycles and trade disruptions transmit from field to fractionation facility. Contract structures now bifurcate between long-term offtake agreements favored by German industrial bakeries and spot purchasing by Asian extrusion snack manufacturers absorbing volatility.
Pricing Analysis
Short lead-time premiums now command 15-25% markups over quarterly contract rates as Hamburg and Cologne industrial bakeries prioritize supply security over procurement cost. Three-tier pricing structure across organic-certified, high-protein specification, and commodity-grade segments separates premium bakery chains from cost-sensitive snack processors. Pricing pressure stems from protein content specification creep forcing rejection of lower-grade wheat streams during Black Sea drought cycles. Automated bread production lines exhibit highest price sensitivity, while plant-based meat startups prioritize functional performance over per-kilogram procurement cost.
Supply Chain Analysis
Direct-to-manufacturer channels handle hyperscale demand from Cargill and Archer Daniels Midland captive supply networks serving North American restructured meat processors. Raw material concentration centers on Kansas and Minnesota milling corridors in the United States, Shandong Peninsula wheat belts in China, and New South Wales grain production zones in Australia. Critical dependencies include nitrogen fertilizer inputs for wheat cultivation, natural gas for mechanical vapor recompression drying, and ceramic membrane filtration systems for protein fractionation. Single-source vulnerability concentrates in EU F-Gas Regulation-compliant dryer technology suppliers where Rhine corridor processors face 18-24 month equipment lead times.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-moisture extrusion technician scarcity and REACH-registered processing aid bottlenecks prop pricing premiums for qualified suppliers across European and North American markets.
For Market Incumbents: Cement origination control through backward integration into Black Sea and North American grain supply chains before drought cycles tighten wheat availability. Invest in mechanical vapor recompression dryer fleets to capture EU F-Gas Regulation compliance premiums while competitors face retrofitting delays. Pea protein cost parity represents the priority threat requiring formulation partnership defenses. For New Entrants and Emerging Players: Ceramic microfiltration technology offers entry pathway for mid-scale processors avoiding capital-intensive traditional dryer investments. Target beverage protein fortification applications where dispersibility-engineered isolates command premium positioning absent incumbent concentration. Pursue direct contracting relationships with alt-meat startups bypassing distributor markups. For Investors and Strategic Acquirers: The window for entry favors integrated processors with combined milling and fractionation assets in low-input wheat sourcing regions. Long-term viability hinges on certification capabilities for organic and EU Green Deal farm-to-fork compliance. Monitor EFSA novel food authorization timelines as inflection indicator for innovative wheat protein fraction commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Cargill and ADM networks demonstrate how captive wheat supply secures margin capture against Black Sea volatility. |
| Mechanical Vapor Recompression Dryer Deployment | Rhine corridor processors halve energy intensity while meeting EU F-Gas Regulation refrigerant mandates. |
| Ceramic Microfiltration Technology Licensing | Yangtze River Delta pilots recover additional protein per ton while compressing capital requirements for entrants. |
| Direct-to-Manufacturer Contracting Expansion | Bypassing ingredient distributors captures margin pools currently absorbed in alt-meat supply chains. |
| REACH-Compliant Processing Aid Registration | Full substance portfolio disclosure becomes procurement gate for French and Dutch industrial bakery audits. |
Methodological Framework
Independent corroboration across plant-based meat R&D directors, industrial bakery procurement leads, wheat fractionation plant managers, and membrane filtration technology suppliers underwrites the qualitative findings. Primary interviews with EU regulatory affairs specialists and REACH compliance officers combined with secondary validation from EFSA novel food assessment databases, FDA food additive regulation filings, and USDA organic certification records. Bottom-up demand modeling across application segments triangulates against top-down wheat supply and gluten extraction capacity estimates.
Rate-of-change decomposition separates volume growth from price realization across the projection horizon. Segmentation dimensions include product grade tier, end-use application channel, certification status, and regional regulatory cluster. CAGRs derive from protein content specification trajectory analysis, extrusion technology adoption curves, and bakery automation penetration rates. Wheat price volatility indices and nitrogen fertilizer cost inputs feed scenario-weighted forecast distributions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Black Sea supply disruption and EFSA authorization timeline extension scenarios. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cocoa Solids Market
Ingredients
Canada Soy Protein Market
Ingredients
Functional Flours Market
Ingredients
Glucosylglycerol Market
Ingredients
Pea Hull Fiber Market
Ingredients
Bone and Joint Health Ingredients Market
Ingredients
Global Gelatin Market
Ingredients
Canola Meal Market
Ingredients
Diastatic Malt Market
Ingredients
Almond Flour Market
Ingredients
Cultured Non-Fat Dairy Ingredients Market
Ingredients
Europe Algae Omega-3 Ingredients Market
Ingredients
Icing Shortening Market
Ingredients
Rice Bran Fatty Alcohols Market
Ingredients
Microbial Food Ingredients Market
Ingredients
Sea Buckthorn Berry Extract Market