
 Europe Dairy Protein Market | 2026-2036
Europe Dairy Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dairy Protein Market Analysis
Sports nutrition is hardening as the dominant demand vertical for Europe dairy protein, displacing traditional bakery applications. Arla Foods amba leverages its Danish cooperative structure to anchor organic whey supply chains across Scandinavia. Glanbia plc sustains R&D intensity in hydrolyzed protein isolates for endurance athletes. Lactalis Ingredients dominates French manufacturing scale, converting regional milk surpluses into specialized concentrates for export.
Europe dairy protein encompasses milk-derived fractions—whey, casein, and their concentrates or isolates—separated through ultrafiltration, microfiltration, or ion exchange to achieve protein contents ranging from 34% to over 90% by dry weight. These ingredients function as emulsifiers, gelling agents, and complete amino acid sources in formulated foods and clinical nutrition. Whey protein leads value generation due to its rapid digestibility and leucine density, while casein protein occupies slower-release applications in overnight recovery and medical foods. Milk protein concentrate competes on cost-efficiency in processed dairy and infant formula, where margin pools remain deepest for suppliers meeting EFSA compositional standards.
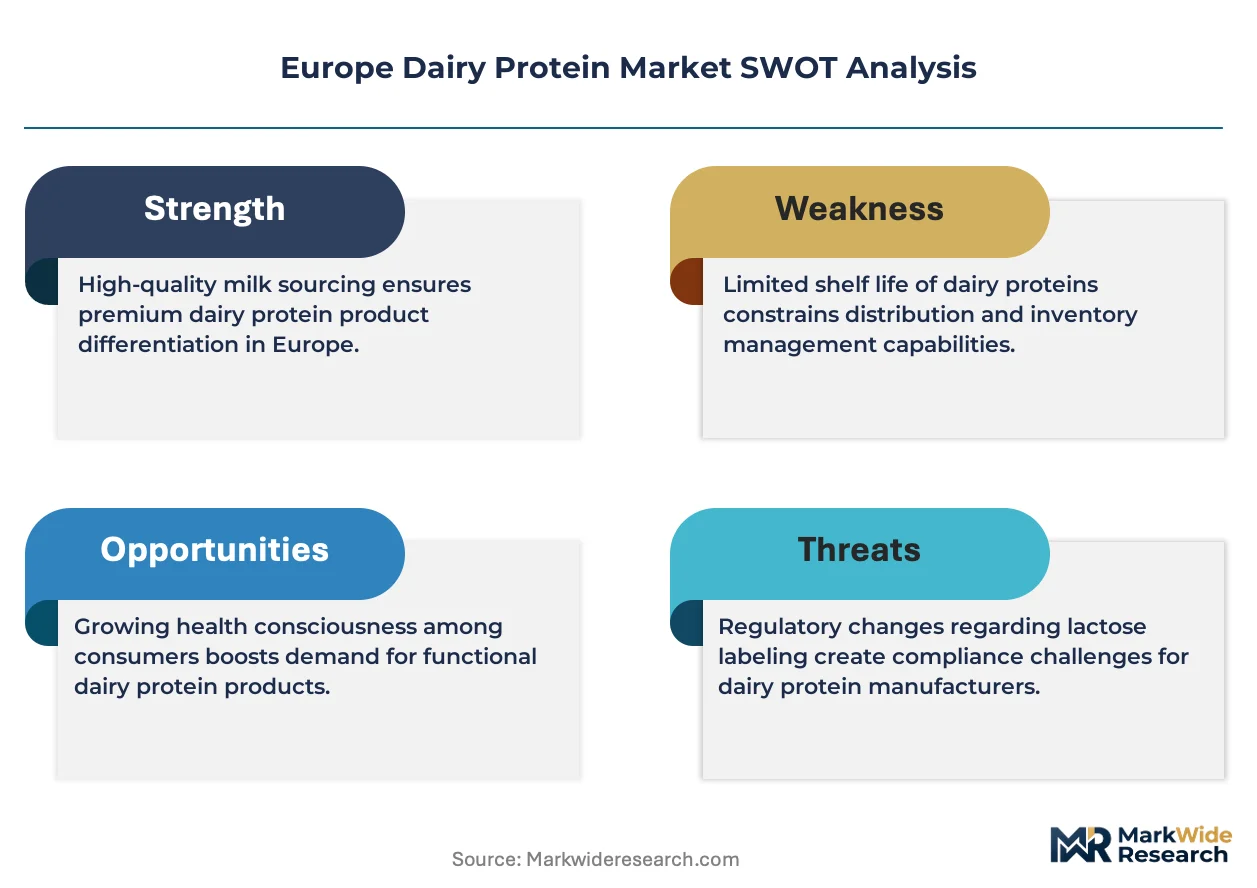
EFSA evaluates all health claims on protein products before market authorization, while EU Green Deal targets pressure processors to reduce methane intensity in milk sourcing. REACH and CE marking requirements govern equipment and additive inputs, shaping capital expenditure timelines for fractionation facilities. Stakeholders must monitor pending F-Gas Regulation amendments affecting cold-chain refrigeration across dairy processing networks.
Market Dynamics
EFSA health claim authorization timelines and EU Green Deal methane reduction mandates are compressing capital deployment cycles for dairy protein fractionation facilities across the continent. These regulatory pressures intersect with sports nutrition demand concentration in Germany's functional food corridor, creating a bifurcated supply landscape where certified organic whey commands sourcing priority.
Growth Catalysts
- EFSA Article 13.1 Health Claims:Authorized protein-specific claims for muscle maintenance and satiety are enabling sports nutrition brands to differentiate finished products in Germany and France. This regulatory clarity accelerates new product development pipelines for whey isolate applications.
- EU Green Deal Farm-to-Fork Strategy:Methane intensity reduction targets for dairy operations are redirecting capital toward grass-fed protein sourcing. Scandinavian cooperatives are consolidating organic milk supply bases to capture sustainability premiums.
- Sports Nutrition Formulation:Endurance and strength athlete segments are specifying hydrolyzed whey isolates with leucine density above 10% by dry weight. This performance specification is pulling investment toward ion exchange capacity expansion.
Market Restraints
- Input Cost Volatility:Regional milk powder prices fluctuate with feed grain costs and energy inputs for refrigeration. F-Gas Regulation compliance costs for cold-chain retrofits are amplifying working capital requirements for fractionation operators.
- Supply Concentration Risk:French milk surplus conversion capacity dominates specialized concentrate production. Disruption at Lactalis Ingredients facilities would cascade through export-dependent infant formula customers in Southern Europe.
- Plant Protein Substitution:Pea and fava protein isolates are achieving amino acid completeness through blending. Bakery and meat analog applications are tolerating sensory trade-offs that sports nutrition segments currently reject.
Strategic Opportunities
- Eastern European Production Expansion:Poland and Romania offer untapped milk collection density with lower land and labor costs for grass-fed certification. Greenfield fractionation sites can anchor EU-wide organic supply without Nordic cost structures.
- Medical Foods Channel Development:Sarcopenia-targeted clinical nutrition represents underdeveloped demand. Casein micelle concentrates for overnight amino acid release require different formulation partnerships than sports nutrition.
- Precision Fermentation Convergence:Dairy-identical whey protein from microbial hosts is approaching cost parity. Hybrid sourcing strategies combining traditional fractionation with fermentation output can de-risk supply and extend EFSA claim eligibility to novel production methods.
Industry Challenges
- Fractionation Engineering Talent Scarcity:Membrane process optimization and chromatography scale-up expertise concentrates in Danish and Dutch technical universities. Recruitment pipelines for facility commissioning and troubleshooting remain underdeveloped in emerging production geographies.
- REACH Compliance Timeline Compression:Novel processing aids and enzyme inputs for hydrolyzed protein production require extended safety dossier preparation. Registration delays can freeze product line extensions for 18-24 months.
- Legacy Dairy Integration Complexity:Traditional cheese manufacturers retrofitting whey recovery face yield optimization conflicts with existing curd production schedules. Capital allocation between core operations and protein fractionation creates internal competition for technical resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dairy Protein Market |
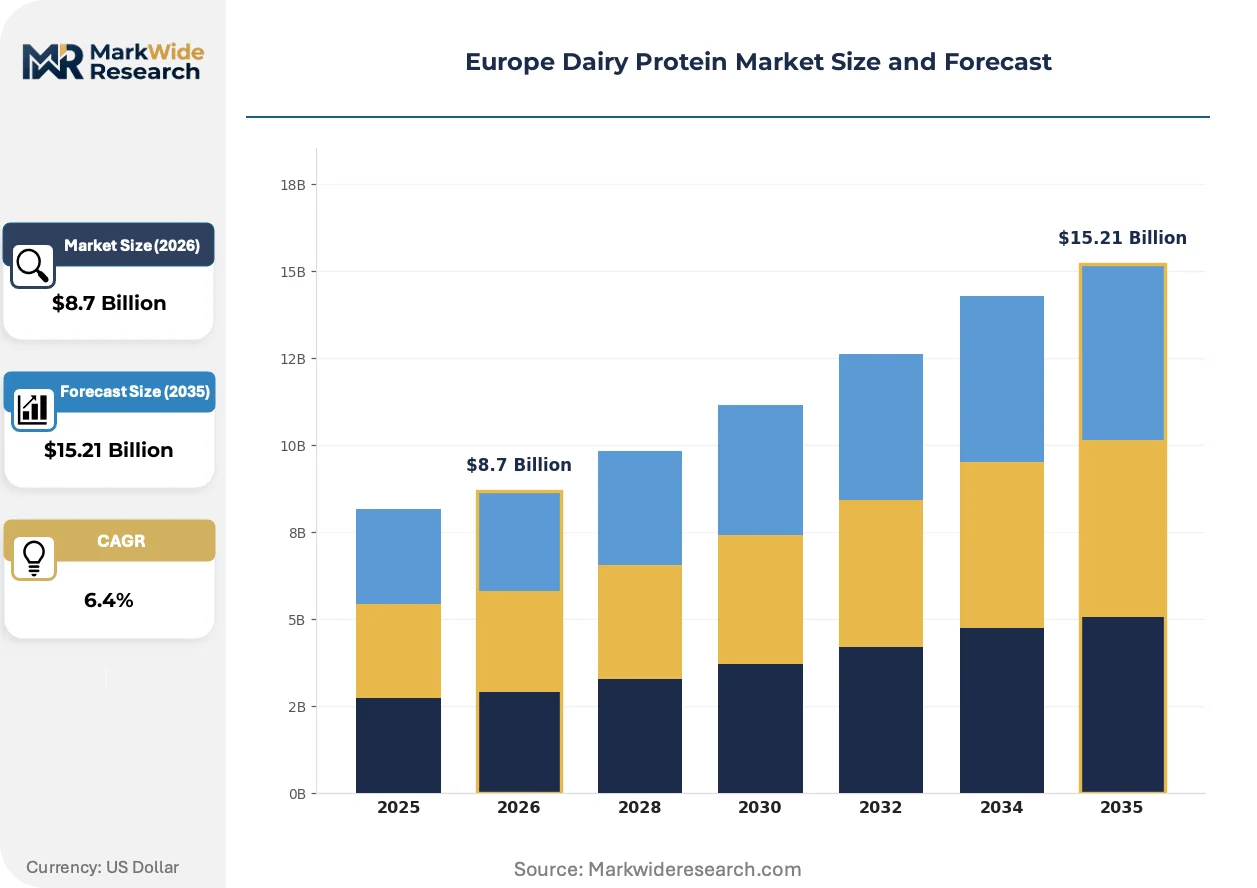
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein Protein, Milk Protein Concentrate, Milk Protein Isolate End User: Dairy Manufacturers, Sports Nutrition, Functional Foods, Infant Formula Form: Dry Powder, Liquid, Cream, Concentrate Application: Food & Beverage, Dietary Supplements, Bakery & Confectionery, Snacks |
| Companies Covered | Kerry Group Plc, Saputo Inc., Arla Foods amba, LAITA Group, Fonterra Co-operative Group, Glanbia plc, Lactalis Ingredients, Carbery Group, FrieslandCampina Ingredients, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dairy Protein Market Emerging Trajectories
Membrane filtration technology advancement and regulatory sustainability mandates are restructuring competitive advantage around energy efficiency and carbon-accounted sourcing. These forces are compressing the viable technology set for new capacity investment.
Microfiltration and ultrafiltration membrane systems with ceramic configurations are achieving 40% energy reduction versus polymeric alternatives in whey protein concentration. Arla Foods amba and FrieslandCampina are retrofitting Danish and Dutch facilities with these systems to meet EU Green Deal operational targets. This technology is absorbing capital that would otherwise deploy toward greenfield expansion, concentrating margin improvement within existing asset bases rather than geographic extension.
REACH and pending F-Gas Regulation amendments are mandating refrigerant transitions and process chemical disclosures for dairy protein facilities. These rules are extending commissioning timelines for new fractionation plants by 8-14 months as operators validate alternative cooling chemistries. German and French regulators are enforcing disclosure requirements most stringently, pushing suppliers to consolidate certification documentation across multi-site operations.
Athlete and clinical nutrition buyers are consolidating procurement around suppliers with third-party carbon accounting and grass-fed certification. This preference compression is disintermediating traders and spot-market intermediaries who cannot document chain-of-custody. Direct contracting between Scandinavian cooperatives and German sports nutrition brands now dominates whey isolate volume, marginalizing traditional ingredient distributors in premium segments.
Europe Dairy Protein Market Segmentation
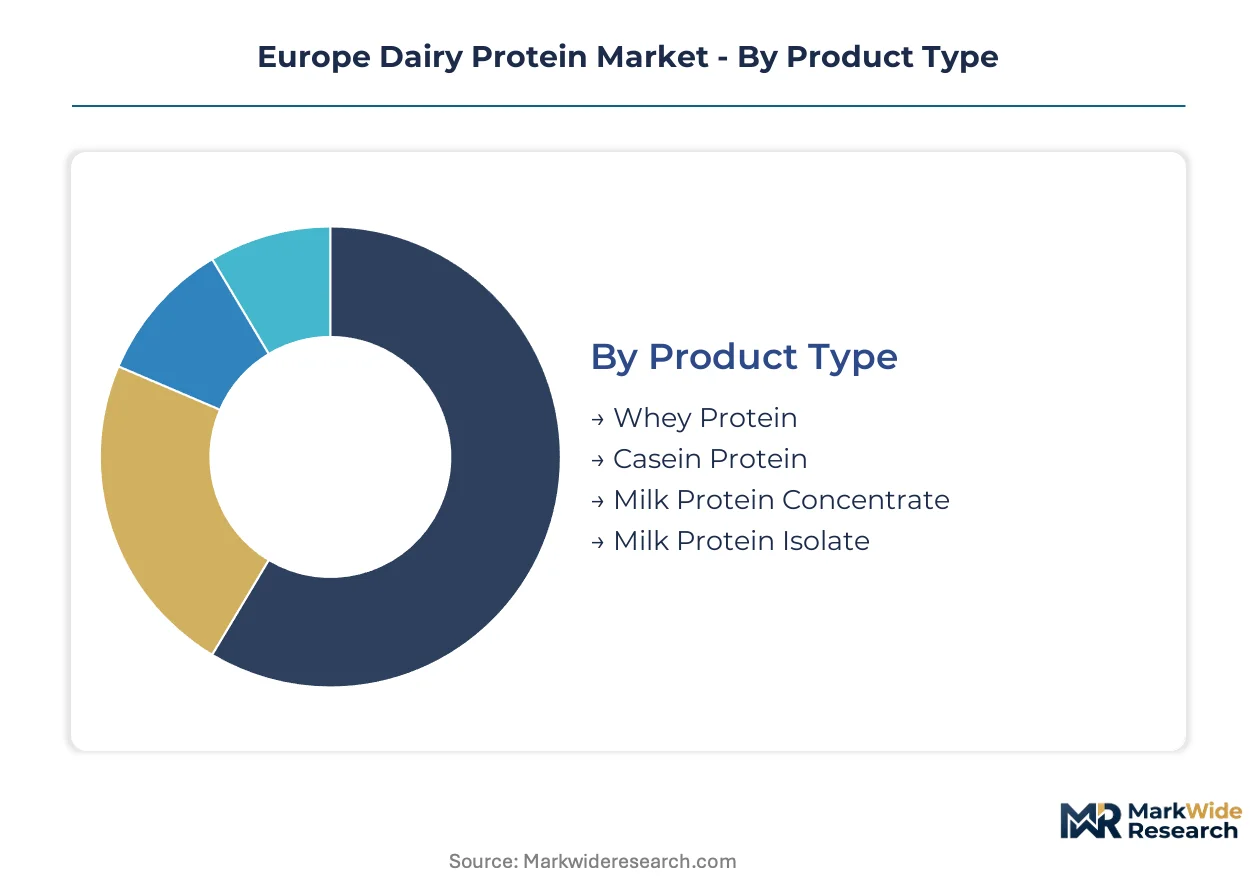
Europe dairy protein segmentation reveals divergent margin architectures across product types and end-use channels. Sports nutrition and infant formula buyers command premium specifications that reshape supplier investment priorities across fractionation capacity.
Product Type:
Whey protein concentrates dominate volume throughput, while isolates and micellar caseins extract disproportionate value from performance nutrition segments.
- Whey Protein:Rapidly digestible fractions with leucine density exceeding 10% by dry weight anchor sports nutrition formulations. German functional food brands specify ion-exchange isolates for endurance athlete products, compressing supplier margins on standard concentrates.
- Casein Protein:Slow-release micellar structures enable overnight recovery applications and medical food positioning. Scandinavian cooperatives control micelle concentrate supply for sarcopenia-targeted clinical nutrition, locking in multi-year procurement contracts.
- Milk Protein Concentrate:Cost-efficient 34-85% protein fractions compete in processed dairy and infant formula where EFSA compositional standards govern margin eligibility.
- Milk Protein Isolate:90%+ protein purity commands formulation premiums in specialized medical foods and premium sports recovery products.
Today's leader: Whey Protein. Tomorrow's challenger: Casein Protein.
End User:
Channel concentration in Germany's sports nutrition corridor contrasts with dispersed dairy manufacturing demand across French and Dutch processing clusters.
- Sports Nutrition:Hydrolyzed whey isolates with specified leucine thresholds dominate procurement. Endurance and strength athlete segments pull investment toward ion exchange capacity expansion at FrieslandCampina and Arla facilities.
- Infant Formula:EFSA compositional standards and Chinese export registration requirements concentrate supply qualification among Lactalis Ingredients and Danone Nutricia. Milk protein concentrate specifications here tolerate lower purity thresholds than sports applications.
- Dairy Manufacturers:Processed cheese and yogurt applications absorb volume at compressed margins, with procurement prioritizing cost stability over functional differentiation.
- Functional Foods:Satiety and muscle maintenance claims enabled by EFSA Article 13.1 authorizations are redirecting bakery and beverage formulation toward protein fortification.
Sports Nutrition captures premium pricing. Functional Foods expand addressable volume fastest.
Form:
Dry powder formats absorb capital investment in membrane filtration and spray-drying capacity, while liquid and cream segments leverage existing dairy processing infrastructure.
- Dry Powder:Spray-dried isolates and concentrates enable shelf-stable distribution and precise dosing in supplement manufacturing. Energy intensity of drying operations subjects this segment to EU Green Deal operational pressure.
- Liquid:Ready-to-drink protein beverages concentrate demand in German and UK convenience retail, requiring aseptic filling partnerships that extend supplier value chains.
- Cream:Protein-enriched dairy creams serve premium dessert and coffee applications with limited scale relative to powder formats.
- Concentrate:Intermediate liquid concentrates reduce drying costs for captive dairy manufacturing but constrain geographic reach due to cold-chain requirements.
Dry Powder commands capacity expansion. Liquid gains share in convenience channels.
Application:
Dietary supplements and food fortification applications diverge in regulatory pathway and formulation complexity, with supplements facing stricter EFSA health claim scrutiny.
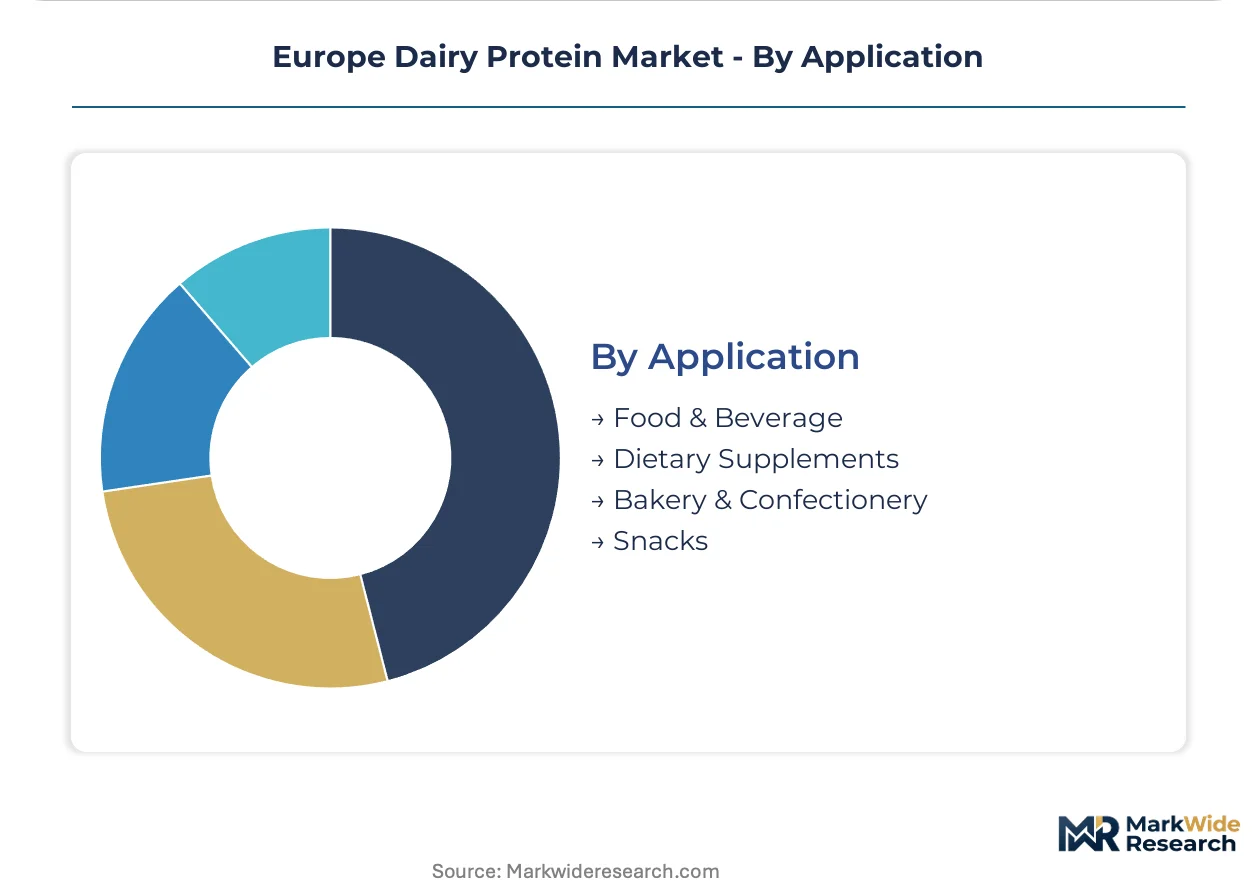
- Dietary Supplements:Powder and capsule formats targeting athlete and active aging segments require EFSA-substantiated claims for muscle maintenance and satiety. This application absorbs hydrolyzed whey premium.
- Food & Beverage:Fortified dairy drinks and protein waters concentrate in German and French retail, with taste-masked formulations tolerating lower protein purity than supplement applications.
- Bakery & Confectionery:Emulsification and water-binding functions compete with plant protein alternatives on cost, with sensory trade-offs limiting dairy protein penetration in mass-market baked goods.
- Snacks:Protein bars and extruded products specify texturized concentrates, with Arla Foods amba and Glanbia plc supplying fractionated ingredients for European co-manufacturers.
Dietary Supplements extract premium value. Food & Beverage expands volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting dairy protein fractionation investment toward Eastern European member states where EU Green Deal compliance costs run lower than in Nordic production zones. Capital deployment patterns now favor Poland and Romania for grass-fed certification capacity without Danish or Dutch overhead structures.
Germany
Sports nutrition brands in Cologne and Munich drive hydrolyzed whey isolate procurement with leucine density specifications above 10%. EFSA Article 13.1 health claim enforcement here is the strictest in Europe, compressing new product authorization timelines. The country's functional food corridor concentrates demand from endurance athlete segments and clinical nutrition formulators.
France
Lactalis Ingredients converts regional milk surpluses into specialized concentrates for export-dependent customers. ANSM and DGCCRF enforcement of REACH process chemical disclosures extends fractionation plant commissioning. The Brittany and Normandy dairy belts anchor specialized micellar casein production for medical food applications.
Netherlands
FrieslandCampina retrofits existing facilities with ceramic membrane systems to meet EU Green Deal energy reduction targets. ECHA registration requirements for novel processing aids freeze some hydrolyzed protein line extensions. The Wageningen food technology cluster supplies membrane process optimization expertise to domestic operators.
Denmark
Arla Foods amba leverages cooperative structure to consolidate organic milk supply bases across Scandinavia. Danish regulators enforce F-Gas Regulation refrigerant transitions most stringently, amplifying cold-chain retrofit costs. Aarhus and Copenhagen host the continent's densest concentration of chromatography scale-up technical talent.
Poland
Untapped milk collection density and lower land costs attract greenfield fractionation investment for EU-wide organic supply. The country's national dairy regulator applies EFSA standards with shorter authorization timelines than Western European counterparts. Greater Poland and Mazovia regions emerge as alternative grass-fed certification hubs without Nordic cost structures.
Europe Dairy Protein Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with cooperative structures dominating premium organic whey and publicly traded entities controlling hydrolyzed isolate capacity. The supplier base concentrates around three strategic archetypes: Scandinavian cooperatives with captive milk supply, Irish and French dairy conglomerates with surplus conversion scale, and Dutch-German ingredient houses with membrane technology leadership. Competitive moves center on M&A for organic certification capacity and ion exchange technology licensing rather than greenfield expansion.
Among cooperative-structured suppliers, Arla Foods amba and Fonterra Co-operative Group exemplify the captive milk supply archetype, while Lactalis Ingredients occupies a position representing surplus conversion scale at the French production cluster. These three entities anchor the competitive structure without exhaustive claims about their specific strategic actions or market positions.
| Leading Market Players |
|---|
| Kerry Group Plc |
| Saputo Inc. |
| Arla Foods amba |
| LAITA Group |
| Fonterra Co-operative Group |
| Glanbia plc |
| Lactalis Ingredients |
| Carbery Group |
| FrieslandCampina Ingredients |
| Others |
Supply Flow & Price Mechanics
EU milk powder price benchmarks cascade through fractionation economics into three distinct procurement tiers. Organic grass-fed whey isolates command sourcing premiums that widen spreads against standard concentrates, while EFSA certification costs embed at the contract layer for German sports nutrition brands.
Pricing Analysis
Distributor margins absorb 12-18 percentage points before product reaches German functional food manufacturers. Three-tier pricing structure across premium organic, standard dairy, and commodity-grade concentrates stratifies by certification level and leucine density specifications. Cost compression in standard whey concentrates intensifies because Polish greenfield capacity adds volume without Nordic overhead structures. Infant formula manufacturers exhibit lowest price sensitivity due to Chinese export registration requirements, while bakery applications tolerate substitution to plant proteins at higher price elasticity.
Supply Chain Analysis
Chromatography scale-up expertise concentrates in Danish and Dutch technical universities, constraining workforce availability for new facility commissioning. Supply draws from France, Denmark, and Poland, with French surplus conversion dominating specialized micellar casein output. Raw material dependencies rest on regional milk collection density, feed grain inputs, and ceramic membrane filtration equipment. Single-source vulnerability runs through Lactalis Ingredients' Brittany production cluster for medical-grade concentrates. Distribution runs through direct contracting between Scandinavian cooperatives and German sports nutrition brands, bypassing traditional ingredient traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe dairy protein operates as a late-cycle quality story where sports nutrition brands now specify leucine thresholds above 10% by dry weight. This demand-shift toward premium performance specifications compresses margin pools for undifferentiated concentrate suppliers.
For Market Incumbents: Hedge organic certification exposure by consolidating grass-fed milk supply bases across Poland and Romania before Eastern European land costs adjust upward. Capture ion exchange capacity licensing from Dutch membrane technology houses to defend against precision fermentation substitution threats. Prioritize EFSA Article 13.1 claim maintenance as the regulatory lever that locks out commodity competitors from sports nutrition procurement. For New Entrants and Emerging Players: Capture sarcopenia-targeted clinical nutrition as the most penetrable segment, where casein micelle concentrates for overnight amino acid release face limited incumbent specialization. Target Eastern European greenfield sites with lower EU Green Deal compliance costs than Nordic equivalents. Pursue co-manufacturing partnerships with German functional food brands as the go-to-market angle that bypasses distributor margin extraction. For Investors and Strategic Acquirers: Consolidation pressure builds where fractionation engineering talent scarcity intersects with REACH compliance timeline compression for novel processing aids. The 5-10 year viability window favors suppliers with captive organic milk supply and EFSA-substantiated health claim portfolios. Acquisition target archetype: Eastern European fractionation operators with grass-fed certification infrastructure and underutilized ion exchange capacity. Watch precision fermentation cost parity announcements as the inflection signal that would trigger hybrid sourcing strategy adoption across German sports nutrition procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Grass-Fed Certification Buildout | Polish and Romanian sites capture EU Green Deal premiums without Danish overhead structures. |
| Ion Exchange Capacity Expansion | FrieslandCampina and Arla facilities meet German leucine density specifications for endurance athletes. |
| EFSA Health Claim Maintenance | Authorized muscle maintenance claims lock commodity competitors out of premium sports nutrition. |
| Precision Fermentation Partnership | Hybrid sourcing with microbial whey producers de-risks supply and extends claim eligibility. |
| Eastern European Greenfield Investment | Untapped milk collection density offers organic supply without Nordic F-Gas retrofit costs. |
Methodological Framework
Bottom-up sports nutrition and infant formula modeling reconciled against top-down milk surplus conversion tracking forms the analytical core of this study. Primary interviews with fractionation plant managers, procurement leads at German functional food brands, EFSA regulatory affairs specialists, and Scandinavian cooperative supply directors combined with secondary validation from EFSA health claim registers, EU dairy trade statistics, and REACH process chemical disclosure filings. This approach triangulates volume estimates against capacity utilization data from ceramic membrane system deployments.
Input-output matrices map milk collection density through fractionation yields to end-use demand across the projection horizon. Segmentation dimensions include protein type, end-user channel, dry versus liquid format, and application category. CAGRs derive from slope analysis of EFSA authorization timelines and EU Green Deal methane reduction compliance trajectories. Forecast inputs incorporate F-Gas Regulation amendment schedules and precision fermentation cost curves.
Underlying measurement precision varies by segment; sports nutrition procurement data carries tighter precision than dispersed bakery applications. Forecasts reflect documented assumptions about EFSA claim authorization rates and organic certification adoption curves. Material deviation in EU Green Deal enforcement intensity or precision fermentation cost parity achievement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Bay Leaf Oil Market
Ingredients
Hydrolyzed Oat Protein Market
Ingredients
PDO/PGI-Linked Mediterranean Ingredient Collections Market
Ingredients
Konjac Root Fiber Market
Ingredients
Plant Based Thickener Market
Ingredients
Plant-Based API Market
Ingredients
Dry Brewing Ingredients Market
Ingredients
Europe Algae Omega-3 Ingredients Market
Ingredients
Vitex Agnus Castus Extract Market
Ingredients
Europe Amino Acid Market
Ingredients
Campesterol Market
Ingredients
Salt Market
Ingredients
Rye Bran Beta-Glucan Market
Ingredients
Mastic Gum Market
Ingredients
Bertholletia Excelsa Seed Oil Market
Ingredients
Zea Mays Starch Market