
 Global Malt Extracts and Ingredients Market | 2026-2036
Global Malt Extracts and Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Global Malt Extracts and Ingredients Market Outlook
Australian grain processors is hardening their positions in global malt supply chains. GrainCorp leverages its integrated grain handling and malting infrastructure across eastern Australia. Malteurop sustains one of the world's largest malting footprints with operations spanning five continents. Rahr Corporation anchors North American supply through its specialty malt and brewing ingredient divisions.
Malt extracts and ingredients comprise concentrated soluble solids derived from germinated cereal grains, typically standardized at 80% solids for syrups and 95% for dried powders through controlled kilning and enzymatic conversion. These products function as fermentable substrates, colorants, and flavor precursors across brewing, baking, and nutritional applications. Malt extract dominates value capture in beverage applications where brewers prize enzymatic activity and fermentability. Malt powder occupies expanding niches in baking and confectionery where dry handling and shelf stability matter. The pharmaceutical application segment is attracting R&D investment as malt-derived carriers gain traction in oral dosage formulations.
The FDA governs malt ingredient labeling and GRAS status in the United States, while EFSA and the EU Green Deal shape sustainable sourcing mandates across European supply chains. REACH compliance adds chemical safety verification burdens for imported malt derivatives. Stakeholders must monitor evolving carbon accounting rules for agricultural inputs and their cascading effects on malt procurement strategies.
Market Dynamics
The EU Green Deal is rewriting agricultural sourcing standards for malted barley inputs, forcing processors to reconfigure procurement networks and carbon accounting systems across European supply chains. This regulatory pressure cascades through pricing structures and supplier qualification protocols worldwide.
Growth Catalysts
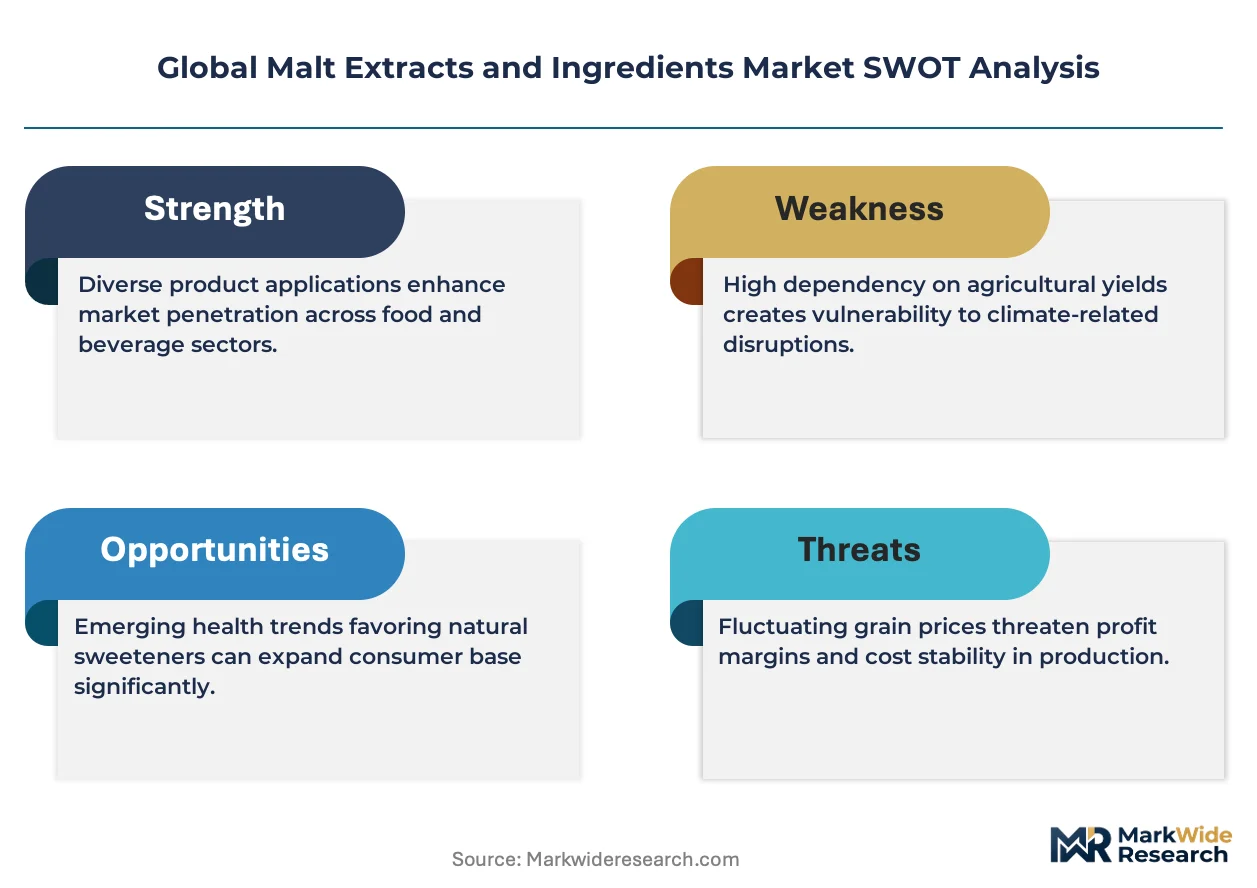
- Craft brewery expansion:Specialty malt extracts enable flavor consistency across small-batch production runs in North American and European brewing operations.
- REACH compliance maturation:Chemical safety verification systems for imported malt derivatives now provide competitive differentiation for compliant suppliers.
- Pharmaceutical formulation R&D:Malt-derived carriers gain traction in oral dosage applications as excipient innovation accelerates.
Market Restraints
- Barley input volatility:Weather-driven harvest fluctuations in Australia and Canada create raw material cost instability for malting operations.
- Malting capacity concentration:Five-continent processing footprints limit geographic redundancy and amplify regional supply disruption risks.
- Enzymatic activity degradation:Temperature-sensitive malt extract shelf life constrains distribution radius for liquid syrup formats.
Strategic Opportunities
- Indian functional foods penetration:Malt powder applications in nutritional beverages remain underdeveloped relative to established baking markets.
- Carbon border adjustment mechanisms:Early compliance with EU Green Deal sourcing standards positions suppliers for preferential market access.
- E-commerce ingredient channels:Direct-to-brewery malt extract distribution bypasses traditional wholesale tiers for mid-size craft producers.
Industry Challenges
- Kilning specialist scarcity:Controlled germination and roasting expertise requires multi-year apprenticeship pipelines that regional education systems underproduce.
- GRAS dossier preparation:FDA substantiation timelines for novel malt-derived ingredients extend commercialization cycles by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Malt Extracts and Ingredients Market |
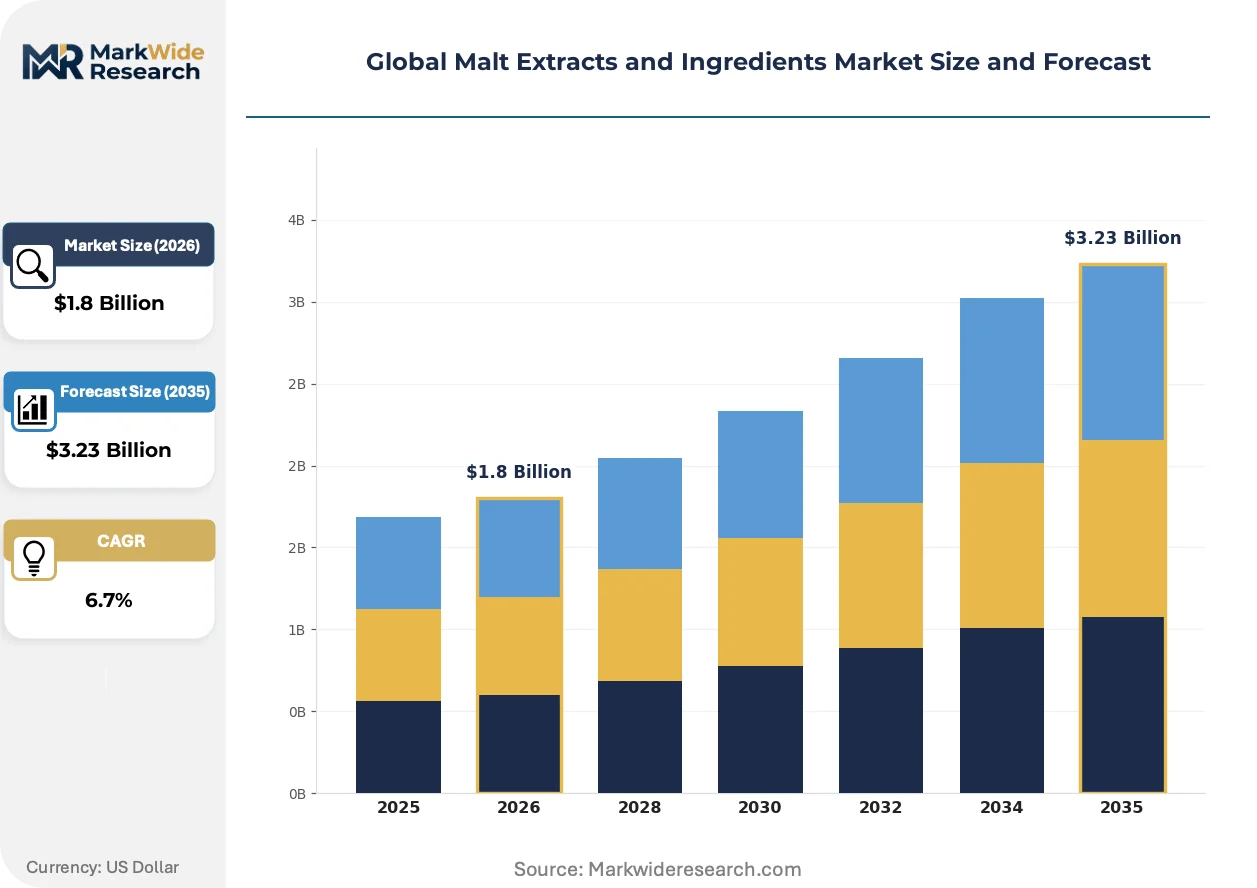
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Malt Extract, Malt Powder, Malt Syrup, Liquid Malt Application: Beverage, Baking, Confectionery, Pharmaceuticals End User: Food Industry, Beverage Industry, Dietary Supplements, Animal Feed Form: Dry, Liquid, Granulated, Syrupy |
| Companies Covered | GrainCorp, Malteurop, Rahr Corporation, Boortmalt, Groupe Soufflet, Muntons PLC, Viking Malt, Holland Malt, Maltproducts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Malt Extracts and Ingredients Market Strategic Shifts
Precision malting technologies and sustainability-linked procurement are converging to transform how malt extracts and ingredients move from grain to formulation. These shifts compress traditional processing timelines while elevating traceability requirements.
Continuous germination monitoring using IoT-enabled moisture and temperature sensors is rewriting quality control protocols in industrial malting. Large-scale brewers in Germany and the Czech Republic deploy these systems to reduce batch-to-batch variability. The technology compresses quality assurance labor costs while enabling real-time process adjustments.
REACH chemical safety verification for imported malt derivatives now mandates full substance inventory disclosure across European supply chains. Malting operations sourcing from non-EU origins face expanded documentation burdens and third-party testing costs. Specialty extract importers are responding by qualifying captive EU-based malting capacity.
Buyer concentration among contract brewers and private-label beverage producers is consolidating procurement leverage. These mid-tier brewers bypass traditional distributor networks to source directly from malting groups with integrated logistics. The shift is most visible in North American craft brewing clusters where scale thresholds favor volume-committed supply agreements.
Global Malt Extracts and Ingredients Market Segmentation
Malt extract and ingredient buyers diverge sharply by technical specification needs, shelf-life constraints, and regulatory exposure. Understanding these fault lines reveals where procurement leverage concentrates and where premium positioning opens.
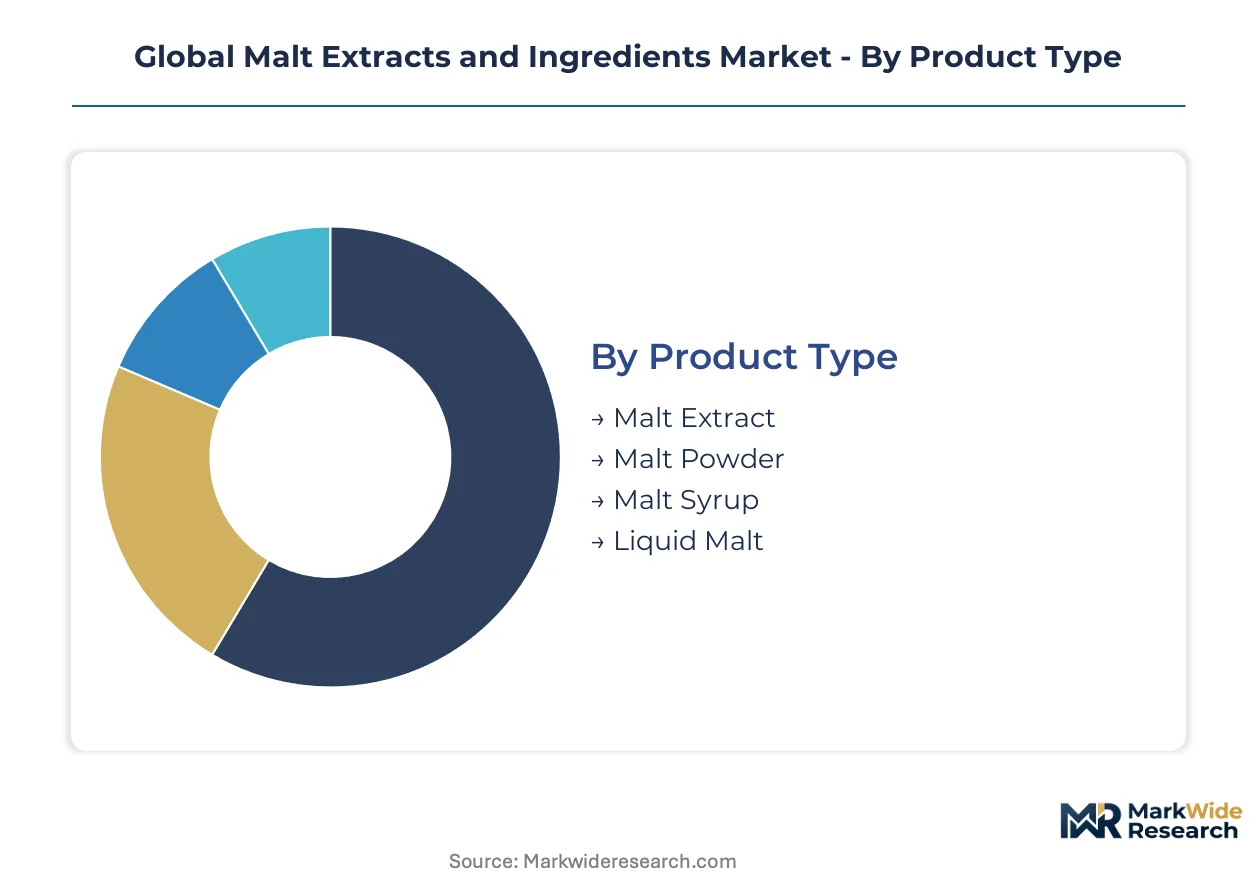
Product Type:
Cost tier separates commodity buyers from specialty purchasers across malt derivatives.
- Malt Extract:Concentrated soluble solids standardized at 80% for syrups deliver enzymatic activity prized by craft brewers in Germany and the Czech Republic. Beverage applications dominate value capture where fermentability consistency commands contract premiums.
- Malt Powder:Dried to 95% solids through controlled kilning, this format enables dry handling and extended shelf stability. Baking and confectionery operations in France and Italy concentrate procurement here, driven by clean-label ingredient mandates under EFSA guidance.
- Malt Syrup:Intermediate viscosity liquid used where moderate sweetness and browning reactions matter.
- Liquid Malt:Unconcentrated format for large-scale brewing operations with dedicated storage infrastructure.
Volume sits with Malt Extract; growth tilts toward Malt Powder.
Application:
Margin structure varies dramatically by end-use regulatory burden and formulation complexity.
- Beverage:Brewing applications anchor absolute volume through enzymatic conversion requirements and color development specifications. German industrial brewers deploy precision malting technologies to compress batch-to-batch variability.
- Pharmaceuticals:Malt-derived carriers gain traction in oral dosage formulations where excipient innovation accelerates under FDA GRAS pathways. R&D investment concentrates here as drug delivery applications expand.
- Baking:Bread and pastry applications leverage malt powder for crust color and fermentation acceleration.
- Confectionery:Chocolate and candy producers use malt derivatives for flavor depth and texture modification.
Revenue concentrates in Beverage; margin expansion is climbing the fastest in Pharmaceuticals.
End User:
Customer scale determines whether procurement runs through distributor tiers or direct malting relationships.
- Beverage Industry:Contract brewers and private-label producers in the United States and Canada are consolidating procurement leverage through volume-committed supply agreements that bypass traditional wholesale networks.
- Food Industry:Mid-size baking operations across Spain and Poland source through regional distributors with limited direct malting penetration.
- Dietary Supplements:Nutritional beverage formulators in India remain underdeveloped relative to established baking markets.
- Animal Feed:Livestock nutrition applications use lower-grade malt derivatives for palatability enhancement.
Procurement scale sits with Beverage Industry; channel disruption potential tilts toward Dietary Supplements.
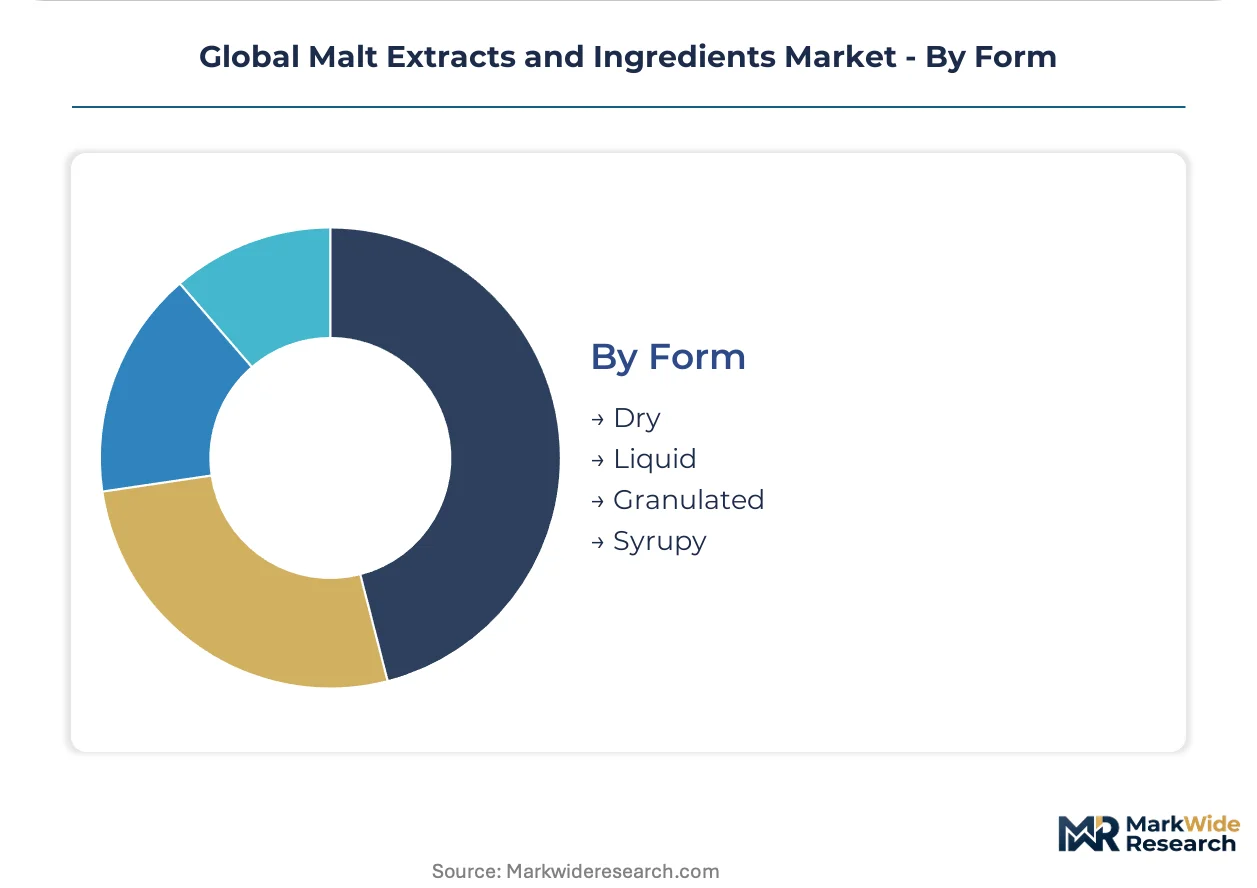
Form:
Supply chain configuration determines feasible distribution radius and storage capital requirements.
- Dry:Powder and granulated formats dominate intercontinental trade where moisture stability eliminates cold-chain dependency. Australian grain processors leverage this format for Asian market penetration.
- Liquid:Syrupy and unconcentrated liquids constrain distribution radius due to temperature-sensitive enzymatic degradation. North American craft brewing clusters favor this format for flavor freshness.
- Granulated:Intermediate flow properties for automated handling systems in industrial baking.
- Syrupy:High-viscosity liquid for specialized brewing and confectionery applications requiring precise dosing.
Trade volume sits with Dry; freshness premium capture tilts toward Liquid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barley cultivation belts in southern Australia and the Canadian prairies anchor raw material flows for malting operations worldwide. These agricultural localities feed processing clusters in Germany, the United States, and China where demand concentrates.
Germany
Industrial brewers in Bavaria and North Rhine-Westphalia drive specialty malt extract procurement for flavor consistency across craft and mass-market production. The EU Green Deal mandates carbon accounting for agricultural inputs, forcing malting groups to reconfigure barley sourcing networks. Munich and Hamburg host precision malting technology deployments that compress batch-to-batch variability through IoT-enabled germination monitoring.
United States
Contract brewers and private-label producers across the Pacific Northwest and Colorado brewing clusters consolidate procurement leverage through direct malting relationships. FDA GRAS pathways govern novel malt-derived ingredient commercialization, extending substantiation timelines for pharmaceutical excipient applications. Chicago and Milwaukee anchor North American specialty malt distribution where mid-tier craft producers bypass traditional wholesale tiers.
China
Beverage manufacturers in the Yangtze River Delta and Shandong Peninsula absorb expanding malt powder volumes for baking and confectionery applications. SAMR food safety standards and GB labeling requirements shape import compliance for Australian and Canadian barley derivatives. Qingdao and Jinan concentrate domestic malting capacity where state-backed grain processors integrate handling infrastructure with industrial-scale production.
India
Nutritional beverage formulators in Maharashtra and Karnataka represent underdeveloped demand relative to established baking markets for malt powder applications. FSSAI clean-label mandates accelerate ingredient substitution trends in commercial bread and biscuit production. Mumbai and Bangalore host emerging R&D activity for malt-derived functional food formulations targeting dietary supplement channels.
Australia
Grain handlers in New South Wales and Victoria leverage integrated malting infrastructure for Asian market penetration through dry powder exports. TGA pharmaceutical excipient guidelines and parallel carbon border preparedness efforts position processors for EU Green Deal alignment. Sydney and Melbourne anchor quality verification laboratories that service REACH compliance documentation for European specialty extract importers.
Global Malt Extracts and Ingredients Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical excipient specialization and carbon-certified sourcing credentials. The vendor base stratifies across five-continent processing footprints, Australian grain-handling integrators, and regional craft-focused suppliers. Three archetypes dominate: integrated agribusiness conglomerates with captive malting capacity, standalone malting specialists with multi-continental operations, and niche extract processors serving pharmaceutical and premium brewing segments. Competitive moves concentrate on backward integration into barley origination and qualification of EU-compliant low-carbon supply chains.
Within the integrated agribusiness tier, GrainCorp exemplifies the model of combining grain handling infrastructure with captive malting operations across eastern Australia. Malteurop occupies a position among standalone specialists with processing footprints spanning multiple continents. Rahr Corporation anchors North American supply representation through specialty malt and brewing ingredient divisions. These three entities collectively illustrate how scale, geographic scope, and end-market focus differentiate competitive positioning across the standard and premium tiers.
| Leading Market Players |
|---|
| GrainCorp |
| Malteurop |
| Rahr Corporation |
| Boortmalt |
| Groupe Soufflet |
| Muntons PLC |
| Viking Malt |
| Holland Malt |
| Maltproducts |
| Others |
Value Chain & Pricing Dynamics
Barley futures volatility on the Intercontinental Exchange cascades through malting operations into three-tier pricing structure across premium, standard, and economy levels. German and Australian processors translate agricultural input swings into contract premiums for enzymatic-grade extracts while commodity malt powders absorb cost compression.
Pricing Analysis
Technical service bundling separates premium malt extract contracts from unbundled commodity powder transactions. Pricing stratifies across premium, standard, and economy tiers based on enzymatic activity certification and volume-commitment scale. Cost compression in standard-grade powders is intensifying because Australian grain handlers are consolidating origination leverage. Contract brewers in North America exhibit the lowest price sensitivity due to flavor-consistency requirements, while industrial baking operations in Southern Europe drive hard volume discounts.
Supply Chain Analysis
Ocean freight rate fluctuations between Australian east coast ports and Hamburg or Shanghai determine viable export windows for bulk malt powder. Supply concentrates in Australia, Germany, and China where integrated grain handlers and standalone malting specialists anchor global capacity. The chain draws from malting barley varieties, enzymatic conversion equipment, and kilning energy inputs. Single-source vulnerability runs through concentrated germination expertise pools in Bavaria and Bohemia. Distribution runs through direct malting relationships for large beverage producers and regional distributor tiers for mid-size food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained through kilning specialist scarcity, with apprenticeship pipeline gaps in Germany and the Czech Republic propping contract premiums for precision-malted extracts.
For Market Incumbents: Anchor carbon-accounting compliance investments in EU Green Deal-aligned sourcing networks before border adjustment mechanisms activate. Defensive consolidation should target captive barley origination in Australian drought corridors and certification laboratory capacity in Hamburg or Melbourne to preempt REACH documentation bottlenecks. For New Entrants and Emerging Players: Contract brewers in the US Pacific Northwest represent the most penetrable channel partner type for direct malt extract distribution bypassing wholesale tiers. White-space targets include pharmaceutical excipient qualification under FDA GRAS pathways and carbon-certified specialty extracts for German industrial brewers. A technical service bundling go-to-market angle compresses procurement friction for mid-tier craft producers. For Investors and Strategic Acquirers: Distressed-cycle entries favor Australian grain-handling integrators with malting capacity and REACH-ready documentation infrastructure. Long-term viability across the analysis window rests on backward integration into drought-resilient barley varieties and low-carbon kilning technology. The signal to watch is EU Green Deal enforcement timing on agricultural input carbon accounting.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barley Origination | GrainCorp's eastern Australian infrastructure demonstrates captive supply resilience against harvest volatility. |
| EU Green Deal Compliance Certification | Malteurop's five-continent footprint positions for preferential access under emerging carbon border mechanisms. |
| Pharmaceutical Excipient GRAS Dossier Investment | Rahr Corporation's specialty malt divisions target FDA oral dosage carrier applications with extended substantiation timelines. |
| Precision Malting Technology Deployment | IoT-enabled germination monitoring in Bavaria compresses batch-to-batch variability for industrial brewers. |
| Direct-to-Brewery E-Commerce Channel | Mid-size craft producers in Colorado and Oregon bypass traditional wholesale tiers for freshness-premium liquid extracts. |
Study Parameters
Independent corroboration across malting operations executives, craft brewery procurement leads, and pharmaceutical formulation scientists underwrites the qualitative findings. Primary fieldwork combined structured interviews with plant managers at integrated grain handlers, technical R&D directors at standalone malting specialists, and category buyers at contract brewing groups. Secondary validation drew from customs trade data on malt extract flows, EFSA guidance documents on clean-label ingredient standards, and SEC filings from listed agribusiness conglomerates. Bottom-up volume builds across product type and application segments triangulate against top-down macroeconomic demand drivers.
Rate-of-change decomposition separates volume trajectory from value capture across the modeling period. Segmentation dimensions include product format, application end-use, and customer scale tier alongside geographic regulatory cluster. CAGRs derive from historical shipment data and forward-looking capacity expansion announcements. Forecast inputs incorporate barley yield projections from Australian Bureau of Agricultural and Resource Economics assessments and EU Green Deal implementation pacing.
Caveats apply where barley harvest failures in Australian or Canadian cultivation belts, abrupt REACH substance inventory expansions, or pharmaceutical excipient approval delays could materially shift the outlook. Forecasts reflect documented assumptions about regulatory enforcement timing and agricultural productivity trends. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Mussel Oil and Powder Market
Ingredients
Sodium Caseinate Market
Ingredients
Brazil Corn Syrup Market
Ingredients
Europe BBQ Charcoal Market
Ingredients
Pig Protein Concentrate Market
Ingredients
Non-GMO Soya Market
Ingredients
Instant Starches Market
Ingredients
Ximenia Oil Market
Ingredients
Textural Food Ingredients Market
Ingredients
Asia-Pacific Brewing Enzymes Market
Ingredients
Europe Vanilla Beans and Extract Market
Ingredients
Fish Peptones Market
Ingredients
Global Vitamin Ingredients Market
Ingredients
Asia-Pacific Potato Protein Market
Ingredients
Coconut Oil Based Products Market
Ingredients
Corn Oil Cake Market